
 Tissue Transglutaminase Test Market | 2026-2036
Tissue Transglutaminase Test Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Transglutaminase Test Market Analytics
Automated chemiluminescence immunoassay integration is tilting the technology stack away from manual ELISA workflows toward high-throughput, random-access analyzers. Thermo Fisher Scientific leverages its installed base of clinical chemistry systems to bundle tTG-IgA assays with routine metabolic panels. Quest Diagnostics anchors the reference laboratory channel through its national specimen logistics network and direct-to-consumer ordering portals. Bio-Rad Laboratories specializes in quality control materials and external run controls that laboratories require for assay standardization across multiple instrument platforms.
Tissue transglutaminase tests detect autoantibodies against the tTG enzyme, typically tTG-IgA, using recombinant human antigen coated on solid-phase matrices with cutoff calibrators traceable to WHO standards; these assays serve as first-line serological screening for celiac disease before confirmatory duodenal biopsy. Enzyme-Linked Immunosorbent Assay formats retain the largest volume share due to their low per-test cost and compatibility with existing open-system pipetting stations, though rapid test kits are gaining traction in point-of-care settings where turnaround time governs clinical decision-making. Diagnostic laboratories capture the dominant end-user share as centralized testing achieves economies of scale that physician office laboratories cannot replicate.
The FDA's pending LDT rulemaking and CLIA proficiency testing requirements shape validation burdens for laboratory-developed tTG assays, while the EU In Vitro Diagnostic Regulation forces manufacturers to renew technical documentation and performance studies under stricter notified body oversight. Health Canada and Australia's TGA maintain parallel convergence with IMDRF guidance on serological test performance thresholds, creating a fragmented but harmonizing compliance landscape for multinational kit suppliers. Stakeholders must monitor how decentralized point-of-care expansion alters the balance between centralized laboratory reimbursement and capitated primary care budgets.
Market Dynamics
Automated chemiluminescence platforms are compressing turnaround times for celiac disease screening while CLIA proficiency requirements and FDA LDT oversight reshape validation economics for diagnostic laboratories.
Growth Catalysts
- CLIA Proficiency Testing Mandates:Laboratory accreditation requirements under CLIA drive standardization investments that expand assay menus and consolidate testing volumes into accredited reference laboratories.
- Point-of-Care Expansion:Rapid tTG-IgA test kits enable same-visit celiac screening in primary care settings, extending serological testing beyond centralized laboratory infrastructure.
- Recombinant Antigen Advances:Human tTG antigen production using mammalian expression systems improves assay specificity and reduces lot-to-lot variability in commercial kit manufacturing.
Market Restraints
- Duodenal Biopsy Dependency:Serological screening remains a gateway to tissue diagnosis rather than definitive confirmation, limiting standalone test reimbursement and clinical utility.
- IgA Deficiency Prevalence:Selective IgA deficiency in 2-3% of celiac patients necessitates parallel IgG-based testing, adding cost complexity and interpretation burden.
- Reimbursement Compression:CMS and commercial payers have narrowed fee schedules for automated immunoassays, squeezing margin contribution per reportable result.
Strategic Opportunities
- At-Home Collection Models:Dried blood spot sampling paired with mail-in laboratory processing extends screening access to rural and underserved populations without local endoscopy capacity.
- Pediatric Screening Protocols:Early childhood celiac detection programs in school-based health settings create demand for fingerstick-compatible rapid assays with visual result interpretation.
- AI-Assisted Result Triage:Machine learning algorithms applied to antibody titer patterns and clinical metadata stratify biopsy urgency, optimizing gastroenterology referral queues.
Industry Challenges
- Multiplex Assay Development:Combining tTG-IgA, deamidated gliadin peptide, and endomysial antibody detection on single platforms requires extensive cross-reactivity validation and harmonization with WHO reference materials.
- Laboratory Information System Integration:Automated result flagging for celiac panels demands customized middleware connectivity between immunoanalyzers and electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Transglutaminase Test Market |
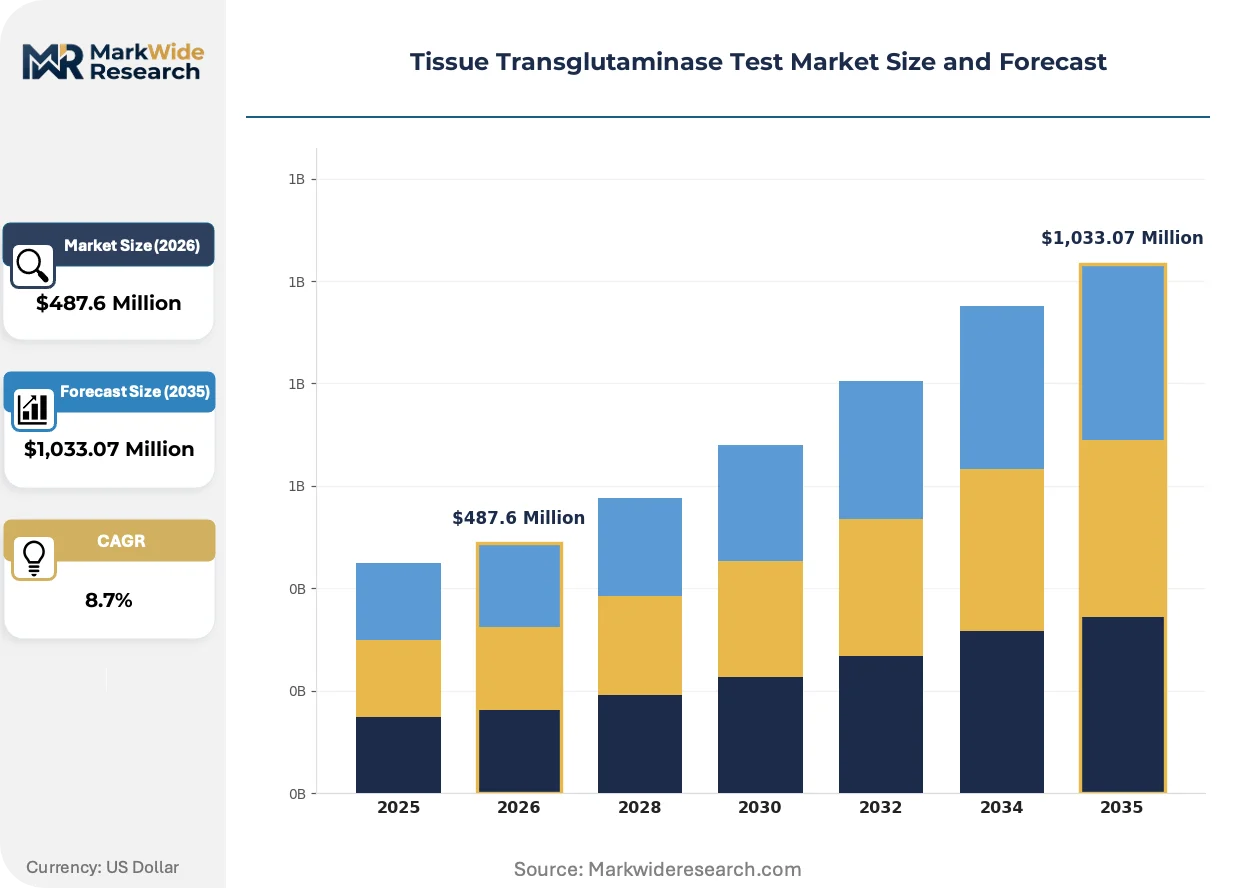
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Latex Agglutination Test, Western Blot Analysis, Rapid Test Kits End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Immunoassay, Molecular Diagnostics, Flow Cytometry, Microarray Application: Autoimmune Disorders, Celiac Disease, Allergy Testing, Gastrointestinal Disorders |
| Companies Covered | Trinity Biotech, ZEDIRA GmbH, Quest Diagnostics Incorporated, ARUP Laboratories, Demeditec Diagnostics GmbH, Thermo Fisher Scientific Inc., SQI Diagnostics, Cell Science Systems, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Transglutaminase Test Market Evolving Landscape
Digital pathology workflows and decentralized diagnostic models are restructuring how celiac serology results reach clinicians, compressing the interval between specimen collection and therapeutic intervention.
Multiplex bead-based immunoassays are virtualizing traditional single-analyte testing by enabling simultaneous quantification of tTG-IgA, tTG-IgG, and DGP antibodies on Luminex and MagPix platforms. Large reference laboratories in the United States are deploying these systems to consolidate autoimmune panels and reduce reagent inventory complexity. This technology is virtualizing the economics of high-volume screening by collapsing per-test costs and enabling random-access batching across disease indications.
The FDA's pending LDT oversight rulemaking is forcing clinical laboratories to document analytical validity for in-house tTG assay modifications previously exempt from premarket review. Manufacturers of open-system reagents face expanded labeling obligations and post-market surveillance requirements. Academic medical centers with established celiac research programs are most affected, as they must now compile performance studies or transition to FDA-cleared kits.
Direct-to-consumer test ordering through patient-initiated portals is bypassing traditional physician gatekeeping for celiac screening. Quest Diagnostics and regional laboratory networks have launched online result dashboards that trigger automated gastroenterology referrals for positive findings. This channel shift is most visible in the United States, where high-deductible health plans and consumer health literacy campaigns accelerate self-directed diagnostic behavior.
Tissue Transglutaminase Test Market Segmentation
Segmentation of the tissue transglutaminase test market reveals how testing workflows fragment across technical platforms, care settings, and disease indications. Each dimension carries distinct margin profiles, regulatory burdens, and service intensity requirements that shape supplier strategy.
Product Type:
After-sales service intensity varies sharply across product formats, with automated systems demanding multi-year maintenance contracts and consumable re-supply agreements while rapid formats minimize ongoing vendor contact.
- Enzyme-Linked Immunosorbent Assay:Solid-phase microplate formats using horseradish peroxidase or alkaline phosphatase conjugates with spectrophotometric endpoint detection. Diagnostic laboratories in the United States concentrate procurement here due to open-system flexibility and CLIA-waived protocol adaptations that reduce regulatory overhead.
- Rapid Test Kits:Lateral flow immunochromatographic strips delivering qualitative tTG-IgA results within 15 minutes at point-of-care. Primary care clinics and school-based health programs drive uptake where immediate clinical decision-making outweighs quantitative precision requirements.
- Latex Agglutination Test:Visual agglutination assays for semi-quantitative antibody detection requiring minimal equipment infrastructure.
- Western Blot Analysis:Confirmatory protein electrophoresis reserved for equivocal serological results and research applications.
Enzyme-Linked Immunosorbent Assay holds the largest share; momentum sits with Rapid Test Kits.
End User:
Customer concentration patterns split between high-volume centralized laboratories achieving reagent economies and distributed sites prioritizing turnaround speed over per-test cost.
- Diagnostic Laboratories:High-throughput reference facilities processing thousands of celiac panels monthly on random-access chemiluminescence analyzers. National networks like Quest Diagnostics anchor volume leadership through integrated specimen logistics and direct-to-consumer ordering portals that bypass traditional physician gatekeeping.
- Hospitals:Acute care settings requiring STAT turnaround for inpatient gastrointestinal consultations and pre-endoscopy screening protocols. Tertiary medical centers with embedded gastroenterology departments drive demand for multiplex autoimmune panels that consolidate tTG testing with related serological markers.
- Clinics:Outpatient and community health settings where point-of-capillary testing reduces referral leakage.
- Research Institutions:Academic medical centers validating novel biomarkers and participating in FDA-mandated post-market surveillance studies.
Diagnostic Laboratories capture dominant volume; Clinics are expanding most quickly.
Technology:
Platform selection determines capital commitment cycles, with immunoassay infrastructure representing sunk costs that constrain rapid technology transitions.
- Immunoassay:Chemiluminescence and enzyme-linked detection systems using recombinant human tTG antigen with WHO-traceable calibrators. Automated platforms from Thermo Fisher Scientific and similar suppliers dominate installed bases in US reference laboratories.
- Molecular Diagnostics:PCR-based HLA-DQ2/DQ8 genotyping as adjunctive testing for celiac disease risk stratification.
- Flow Cytometry:Research-phase applications for lymphocyte population analysis in refractory celiac cases.
- Microarray:Multiplex protein profiling enabling simultaneous autoantibody detection across gastrointestinal and systemic autoimmune indications.
Immunoassay commands installed base leadership; Microarray shows steepest expansion trajectory.
Application:
Disease indication targeting shapes reimbursement pathways and clinical utility claims, with celiac screening representing the anchor indication that subsidizes broader autoimmune menu development.
- Celiac Disease:First-line serological screening using tTG-IgA with reflex to deamidated gliadin peptide and endomysial antibody confirmation. US commercial payers and Medicare maintain established CPT codes that sustain predictable reimbursement for high-risk population screening.
- Autoimmune Disorders:Expanded panels incorporating tTG as a component of systemic autoimmune differential diagnosis.
- Gastrointestinal Disorders:Non-celiac gluten sensitivity and inflammatory bowel disease workups where tTG testing rules out competing diagnoses.
- Allergy Testing:Distinct immunoglobulin-mediated pathways requiring separate assay interpretation frameworks.
Celiac Disease holds the largest share; momentum sits with Autoimmune Disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories and hospital networks concentrate procurement power in markets with established celiac disease screening protocols and favorable reimbursement frameworks. National reference laboratory chains and integrated health systems drive volume aggregation, while point-of-care expansion reshapes geographic access patterns.
United States
Quest Diagnostics and ARUP Laboratories anchor national specimen logistics networks that process high-throughput tTG-IgA panels. The FDA's pending LDT oversight rulemaking forces clinical laboratories to document analytical validity for in-house assay modifications. Major metropolitan clusters in Boston, San Francisco, and Minneapolis host academic medical centers validating novel biomarkers and participating in post-market surveillance studies.
Germany
ZEDIRA GmbH and Demeditec Diagnostics GmbH supply recombinant antigen and kit manufacturing to European diagnostic networks. The EU In Vitro Diagnostic Regulation mandates renewed technical documentation and performance studies under stricter notified body oversight. The Rhine-Main region around Frankfurt concentrates reference laboratory capacity serving centralized German healthcare procurement.
United Kingdom
NHS England's celiac screening guidelines drive standardized serological testing protocols across regional pathology networks. MHRA convergence with IMDRF guidance shapes performance threshold requirements for commercial kit suppliers. London and Manchester host tertiary gastroenterology centers that validate multiplex autoimmune panels and coordinate national quality assurance programs.
Canada
Health Canada maintains parallel regulatory convergence with IMDRF guidance on serological test performance thresholds. Provincial laboratory services in Ontario and Quebec consolidate tTG testing volumes into centralized facilities achieving reagent economies. Toronto and Vancouver anchor research collaborations between academic medical centers and multinational kit suppliers.
Australia
The TGA's oversight of in vitro diagnostics creates a harmonizing compliance pathway for multinational suppliers entering Asia-Pacific markets. State-based pathology services in New South Wales and Victoria deploy automated chemiluminescence platforms for population-level celiac screening. Sydney and Melbourne host clinical research networks validating point-of-care rapid test formats for rural deployment.
Tissue Transglutaminase Test Market Competitive Landscape
Channel-controlling players compete with product-specialist players across overlapping territory. The market structure tilts toward consolidation around national reference laboratory networks and diversified life sciences conglomerates with installed instrument bases. Three archetypes dominate: integrated diagnostic platforms bundling assays with chemistry systems, standalone kit manufacturers supplying open-system reagents, and quality control specialists standardizing assay performance across multiple platforms. Competitive moves center on automated platform integration and direct-to-consumer channel development.
Among diversified laboratory service providers, Quest Diagnostics Incorporated exemplifies the channel-control archetype through national specimen logistics and patient-directed ordering portals. Thermo Fisher Scientific Inc. occupies a position as integrated platform supplier leveraging clinical chemistry installed bases. Bio-Rad Laboratories, Inc. anchors the quality control tier, supplying external run controls that laboratories require for assay standardization. Trinity Biotech represents the specialized kit manufacturing segment with focused celiac and autoimmune portfolios.
| Leading Market Players |
|---|
| Trinity Biotech |
| ZEDIRA GmbH |
| Quest Diagnostics Incorporated |
| ARUP Laboratories |
| Demeditec Diagnostics GmbH |
| Thermo Fisher Scientific Inc. |
| SQI Diagnostics |
| Cell Science Systems |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Network & Pricing Analysis
The Rhine-Main region around Frankfurt anchors recombinant antigen production capacity that feeds diagnostic kit manufacturers across Europe, concentrating upstream supply leverage among a handful of specialized biotechnology suppliers. This geographic clustering of mammalian expression systems and protein purification infrastructure creates asymmetric pricing power for critical raw material inputs, compressing margins for downstream assay assemblers while sustaining premium capture for antigen specialists.
Pricing Analysis
Cost-plus contracts with quarterly indexation to recombinant protein spot markets dominate procurement between antigen suppliers and kit manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by CLIA certification tier and annual test volume commitments. Pricing pressure stems from CMS reimbursement compression for automated immunoassays, squeezing reference laboratory margins and forcing backward pressure on reagent suppliers. Physician office laboratories exhibit highest price sensitivity due to capitated budget constraints, while national reference networks leverage multi-year volume commitments to secure preferential tier placement.
Supply Chain Analysis
Upstream recombinant human tissue transglutaminase production draws from Germany, the United States, and Switzerland, where specialized contract manufacturing organizations operate GMP-certified mammalian cell culture facilities. Critical inputs include HEK293 expression vectors, protein A chromatography resins, and WHO-traceable calibrator sera. Single-source vulnerability concentrates in affinity purification resin supply, where two manufacturers control global production. Distribution runs through cold-chain logistics networks serving diagnostic laboratory hubs, with regional distribution centers in Boston, Frankfurt, and Singapore managing inventory pooling for just-in-time reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from multiplex microarray platforms that collapse multiple celiac serology markers into single-test workflows, threatening standalone tTG-IgA assay volumes. Defense requires strategic repositioning around integrated platform ecosystems rather than discrete kit sales.
For Market Incumbents: Harden installed base retention by bundling tTG assays with random-access chemistry analyzers through multi-year reagent rental contracts that raise switching costs. Deepen backward integration into recombinant antigen production through acquisition of specialized biotechnology suppliers or captive manufacturing investments in the Rhine-Main region. This counters margin erosion from upstream concentration while securing supply continuity for high-volume reference laboratory contracts.
For New Entrants and Emerging Players: Point-of-care rapid test formats in rural and underserved US markets represent the most penetrable entry point, where centralized laboratory infrastructure gaps create demand for fingerstick-compatible screening tools. School-based pediatric health programs in Canada and Australia offer parallel white-space opportunity given national screening guideline expansions. Go-to-market execution should prioritize direct-to-consumer channel partnerships with regional laboratory networks that operate patient-initiated ordering portals.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because reference laboratory channel control and antigen manufacturing specialization are concentrating competitive returns among scaled platform operators. Acquisition targets should emphasize quality control material suppliers with cross-platform standardization capabilities or point-of-care rapid test developers with FDA 510(k) clearance pathways. The signal to watch is FDA LDT oversight rulemaking finalization, which would accelerate laboratory transition to FDA-cleared kits and expand addressable market for commercial assay manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Integration | Thermo Fisher Scientific bundles tTG-IgA assays with clinical chemistry systems to lock in reference laboratory volumes. |
| Direct-to-Consumer Channel Development | Quest Diagnostics bypasses physician gatekeeping through patient-initiated ordering portals that trigger automated referrals. |
| Recombinant Antigen Manufacturing Scale-Up | ZEDIRA GmbH expands mammalian expression capacity to reduce lot-to-lot variability for kit manufacturer customers. |
| Quality Control Material Standardization | Bio-Rad Laboratories supplies external run controls that enable assay harmonization across multiple instrument platforms. |
| Point-of-Care Rapid Test Regulatory Pathway | SQI Diagnostics pursues CLIA-waived designation for fingerstick-compatible tTG-IgA screening formats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notifications, EU MDR technical documentation, and CMS Medicare reimbursement schedules. Primary interviews engaged diagnostic laboratory directors, biomedical engineers at reference facilities, GPO contracts managers, and regulatory affairs leads at kit manufacturers. Secondary validation drew from hospital procurement databases, CLIA proficiency testing records, and WHO reference material certifications. Bottom-up test volume estimates triangulate against top-down market size calculations across product type, end user, technology, and application segmentation dimensions.
Forecast inputs incorporate instrument placement trends, reimbursement trajectory assumptions, and regulatory implementation timelines across the analysis window. Segmentation modeling spans product format, care setting, detection technology, and disease indication with regional regulatory cluster overlays. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and adjusted for platform transition dynamics. Industry-specific inputs include CLIA-waived test expansion rates and direct-to-consumer channel penetration assumptions.
Practitioners should monitor FDA LDT oversight rulemaking implementation, EU MDR notified body capacity constraints, and point-of-care test accuracy validation studies for early signals of forecast deviation. Material shifts in CMS fee schedule determination or WHO reference standard revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Vision Screeners Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Global Molecular Diagnostics Services Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Home Diagnostics Market
Diagnostics
Global Rubella Diagnostic Testing Market