
 Global Chlamydia Infection Diagnostics Market | 2026-2036
Global Chlamydia Infection Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlamydia Infection Diagnostics Market Foresight
The WHO Global Health Sector Strategy on STIs is rebalancing procurement priorities toward molecular diagnostics in low-resource settings. Hologic Inc. leverages its Panther system automation to sustain installed-base loyalty across high-throughput laboratories. Danaher Corporation anchors its position through integrated sample-to-answer workflows that reduce operator dependency. Abbott Laboratories differentiates with portable nucleic acid platforms designed for decentralized sexual health clinics.
Chlamydia infection diagnostics encompass laboratory and point-of-care systems that detect Chlamydia trachomatis nucleic acids or antigens in urogenital, rectal, and oropharyngeal specimens, with polymerase chain reaction achieving analytical sensitivity below 10 copies per reaction. These technologies serve public health screening, clinical diagnosis, and partner notification programs where asymptomatic carriage drives transmission chains. Nucleic Acid Amplification Tests command the dominant revenue share due to superior sensitivity and FDA-cleared multiplex capabilities, while Rapid Diagnostic Tests represent the fastest-expanding segment as immunochromatography strips enable same-visit treatment decisions in resource-limited settings. Enzyme Immunoassays occupy a mature, cost-sensitive niche in high-volume reference laboratories where batch processing optimizes per-test economics.
The FDA's CLIA complexity categorization shapes market access by determining which platforms qualify for waived settings versus moderate-complexity laboratories. EMA's In Vitro Diagnostic Regulation enforces post-market surveillance and performance documentation requirements that elevate compliance costs for CE-marked entrants. India's CDSCO and the country's national pharmaceutical regulator coordinate import licensing for molecular diagnostic reagents under the Drugs and Cosmetics Act. Stakeholders must monitor evolving WHO prequalification criteria and national Essential Diagnostics List adoptions to anticipate procurement channel shifts.
Market Dynamics
The nucleic acid amplification test standardization push from WHO guidelines revision is compressing test complexity tiers and forcing platform consolidation across public procurement channels worldwide.
Growth Catalysts
- India National Health Mission scaling:Government screening programs under this mission are expanding molecular diagnostics capacity in district hospitals and urban health centers.
- CLIA-waived platform expansion:FDA complexity reclassification enables same-visit testing protocols in decentralized sexual health clinics previously restricted to moderate-complexity laboratories.
- Multiplex assay development:Simultaneous Chlamydia trachomatis and Neisseria gonorrhoeae detection is reducing per-sample processing costs in high-throughput reference laboratories.
Market Restraints
- Reagent cold-chain dependency:Nucleic acid amplification chemistries require continuous 2-8°C storage, elevating logistics costs in tropical climates and remote clinic networks.
- EMA post-market surveillance burden:In Vitro Diagnostic Regulation performance documentation requirements impose recurring compliance expenditures on CE-marked assay manufacturers.
- Enzyme immunoassay price floor:Mature batch-processing technologies in centralized laboratories cap pricing power for newer molecular entrants in cost-sensitive screening contracts.
Strategic Opportunities
- Rectal and oropharyngeal specimen expansion:Extragenital site testing protocols open addressable volume in men who have sex with men outreach programs and correctional health settings.
- WHO prequalification pathway:Alignment with evolving prequalification criteria unlocks pooled procurement through Global Fund and PEPFAR supply mechanisms in low-resource settings.
- Connectivity-enabled result reporting:Cloud-integrated point-of-care devices support real-time surveillance data transmission to national health information systems.
Industry Challenges
- Molecular diagnostics technician scarcity:Moderate-complexity laboratory certification requirements limit workforce availability for nucleic acid amplification test operation in rural health facilities.
- Sample-to-answer workflow integration:Automated platform installation demands HVAC and electrical infrastructure upgrades incompatible with legacy clinic footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlamydia Infection Diagnostics Market |
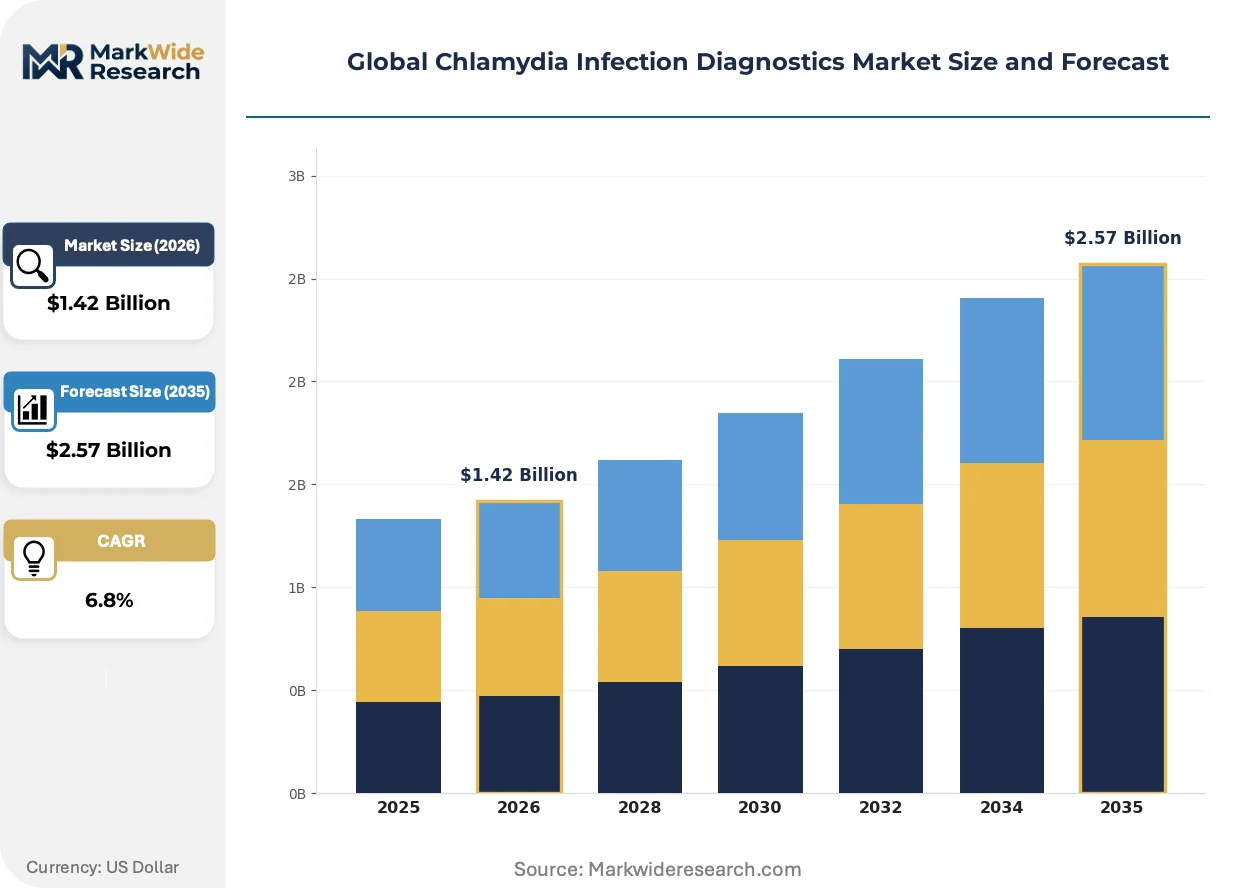
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleic Acid Amplification Tests, Rapid Diagnostic Tests, Enzyme Immunoassays, Direct Fluorescent Antibody Tests, Culture Techniques Application: Genital Testing, Neonatal Screening, Male Urethritis Detection, Female Pelvic Infections, Asymptomatic Carrier Identification End User: Diagnostic Laboratories, Sexual Health Clinics, Gynecology Centers, Pediatric Clinics, Public Health Agencies Technology: Polymerase Chain Reaction, Immunochromatography, Enzyme-Linked Immunosorbent Assay, Direct Immunofluorescence, Microbial Culture Methods |
| Companies Covered | Hologic Inc., Danaher Corporation, Abbott Laboratories, F. Hoffmann-La Roche Ltd., Becton Dickinson and Company, Roche Diagnostics, Thermo Fisher Scientific Inc., Siemens Healthineers, Qiagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlamydia Infection Diagnostics Market Shifts & Advancements
Portable nucleic acid platforms are collapsing the distance between laboratory-grade sensitivity and point-of-care accessibility, redrawing competitive boundaries between centralized and decentralized testing architectures.
Isothermal amplification chemistries are absorbing market share from traditional thermal-cycler polymerase chain reaction in near-patient settings. Sexual health clinics in Australia and the United Kingdom are adopting these room-temperature-stable formats for same-visit result delivery. The technology is absorbing capital previously allocated to laboratory automation by eliminating complex instrumentation requirements.
EMA's In Vitro Diagnostic Regulation transition timeline is compressing certificate validity periods and mandating annual performance reviews for CE-marked assays. Manufacturers face accelerated clinical evidence generation obligations for legacy product portfolios. High-throughput laboratory segments in Germany and France are prioritizing suppliers with established notified body relationships to mitigate transition risk.
Partner notification program integration is reshaping procurement specifications toward dual-result capability. Public health departments in the United States and Canada now require Chlamydia-gonorrhea combination assays for contact tracing efficiency. This specification compression favors molecular multiplex platforms over single-target rapid diagnostic tests in government tender processes.
Global Chlamydia Infection Diagnostics Market Segmentation
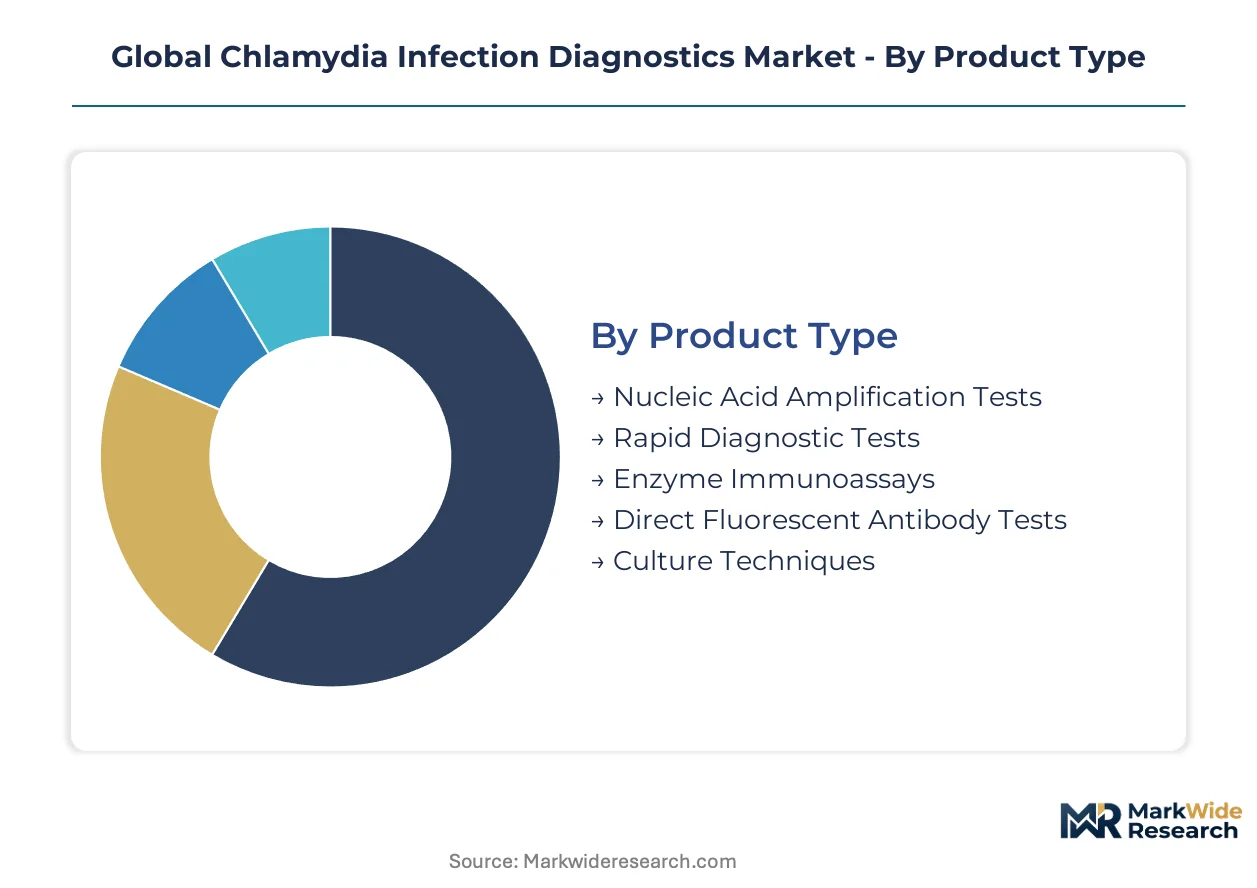
Segmentation in Chlamydia diagnostics reveals how test complexity tiers map to distinct procurement channels and infrastructure requirements. Laboratory-grade molecular platforms compete against waived-complexity point-of-care devices for overlapping patient populations, while specimen source diversity drives specialized assay development.
Product Type:
Customization intensity varies sharply across this category, from standardized high-throughput molecular platforms to configurable rapid test formats adapted for tropical storage conditions.
- Nucleic Acid Amplification Tests:These platforms detect Chlamydia trachomatis nucleic acids with analytical sensitivity below 10 copies per reaction, typically requiring thermal cyclers or isothermal amplification instrumentation. Demand concentrates in India's district hospitals under National Health Mission scaling, where government tenders prioritize FDA-cleared multiplex capabilities for combined Chlamydia-gonorrhea screening.
- Rapid Diagnostic Tests:Immunochromatography strips deliver qualitative results within 15-20 minutes without cold-chain-dependent reagents. Sexual health clinics in Australia and the United Kingdom are absorbing capital previously allocated to laboratory infrastructure by adopting these room-temperature-stable formats for same-visit treatment decisions.
- Enzyme Immunoassays:Batch-processing technologies occupy mature, cost-sensitive niches in centralized reference laboratories where per-test economics dominate procurement decisions.
- Direct Fluorescent Antibody Tests:Microscopy-dependent methods retain utility in resource-constrained settings lacking molecular infrastructure.
- Culture Techniques:Gold-standard specificity supports legal evidence requirements and antimicrobial resistance surveillance in select jurisdictions.
Most installed capacity flows through Nucleic Acid Amplification Tests. Expansion is steepest in Rapid Diagnostic Tests.
Application:
Volume distribution across applications reflects asymptomatic carriage patterns and public health screening priorities rather than symptomatic presentation rates.
- Genital Testing:Urogenital specimen collection dominates laboratory submission volumes, with nucleic acid amplification platforms processing cervical and urethral swabs in high-throughput reference laboratories across Germany and France.
- Asymptomatic Carrier Identification:Population screening programs in correctional health settings and men who have sex with men outreach programs drive demand for extragenital site capability, with rectal and oropharyngeal protocols expanding addressable test volumes.
- Neonatal Screening:Conjunctival specimen testing prevents ophthalmia neonatorum in maternity wards, particularly where prenatal screening coverage remains incomplete.
- Male Urethritis Detection:Syndromic management protocols in decentralized clinics favor rapid diagnostic formats over laboratory referral.
- Female Pelvic Infections:Pelvic inflammatory disease diagnosis requires differential detection against other ascending pathogens, favoring multiplex molecular panels.
Genital Testing captures the highest absolute volumes. Asymptomatic Carrier Identification is climbing the fastest as contact tracing programs expand extragenital site protocols.
End User:
Customer type determines regulatory complexity tier, with CLIA-waived eligibility restricting platform selection in decentralized settings.
- Diagnostic Laboratories:Moderate-complexity certification enables nucleic acid amplification test operation, with high-throughput facilities in urban India and metropolitan United States prioritizing automated sample-to-answer workflows.
- Sexual Health Clinics:Point-of-care testing protocols are expanding fastest in this channel, with FDA complexity reclassification enabling same-visit result delivery previously restricted to referral laboratories.
- Public Health Agencies:Tender specifications increasingly mandate dual-result Chlamydia-gonorrhea capability for partner notification program efficiency.
- Gynecology Centers:Cervical cancer screening integration creates opportunities for co-located STI testing during routine examinations.
- Pediatric Clinics:Neonatal conjunctivitis protocols and adolescent confidentiality requirements shape test format preferences.
Diagnostic Laboratories retain the largest installed instrument base. Sexual Health Clinics are gaining share fastest as waived-complexity platforms proliferate.
Technology:
Technical maturity spans decades, from established enzyme-linked formats to emerging isothermal chemistries eliminating thermal cycler dependency.
- Polymerase Chain Reaction:Thermal-cycler-dependent amplification achieves superior analytical sensitivity for low-burden infections, dominating reference laboratory segments in Germany and France where EMA In Vitro Diagnostic Regulation compliance elevates supplier selection criteria.
- Immunochromatography:Lateral flow strip formats enable visual result interpretation without instrumentation, absorbing investment in tropical clinic networks where cold-chain logistics prove prohibitive.
- Enzyme-Linked Immunosorbent Assay:Batch-processing microplate systems optimize per-test costs in high-volume centralized facilities.
- Direct Immunofluorescence:Microscopy-based detection retains niche applications in resource-limited settings.
- Microbial Culture Methods:Cell-based isolation supports antimicrobial susceptibility testing and medicolegal evidence standards.
Polymerase Chain Reaction dominates installed capacity. Immunochromatography is expanding most quickly as room-temperature-stable formats penetrate near-patient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's molecular diagnostics technician pipeline anchors the strongest workforce concentration in low-resource settings. Germany's reference laboratory density sustains Europe's highest nucleic acid amplification test throughput. Australia's sexual health clinic network drives point-of-care protocol innovation.
United States
FDA's CLIA complexity reclassification unlocks same-visit testing in 2,800+ sexual health clinics previously restricted to laboratory referral. The agency's waived-complexity pathway accelerates point-of-care platform deployment in correctional health settings. California's Los Angeles County health department mandates dual-result Chlamydia-gonorrhea capability for all municipal tender awards.
Germany
EMA's In Vitro Diagnostic Regulation elevates supplier selection criteria through annual performance review mandates. The country's notified body relationships concentrate in Bavaria and Baden-Württemberg laboratory clusters. Berlin-Brandenburg's high-throughput reference facilities prioritize automated sample-to-answer workflows from established CE-marked manufacturers.
India
National Health Mission screening programs expand molecular diagnostics capacity across 700+ district hospitals under CDSCO import licensing coordination. The Drugs and Cosmetics Act governs reagent procurement for government tenders prioritizing FDA-cleared multiplex platforms. Maharashtra's Mumbai-Pune corridor concentrates private diagnostic laboratory automation investments.
Australia
TGA registration pathways enable rapid adoption of room-temperature-stable isothermal amplification formats. New South Wales and Victoria sexual health clinics absorb capital previously allocated to laboratory infrastructure through same-visit result delivery protocols. Sydney's St Vincent's Hospital network pilots cloud-integrated point-of-care surveillance data transmission.
United Kingdom
NHS England's procurement specifications compress toward dual-result capability for partner notification program efficiency. The country's devolved health authorities in Scotland and Wales adopt WHO prequalification-aligned tender criteria for Global Fund eligibility. London's Chelsea and Westminster Hospital NHS Foundation Trust anchors extragenital site testing protocol development for men who have sex with men outreach programs.
Global Chlamydia Infection Diagnostics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across platform automation versus reagent chemistry specialization. The vendor base concentrates around three strategic tiers: multinational conglomerates with integrated sample-to-answer workflows, mid-scale molecular specialists with region-specific regulatory approvals, and point-of-care innovators with waived-complexity platform portfolios. Market consolidation proceeds through automated platform installation base expansion and multiplex assay development partnerships rather than horizontal acquisition.
Within the multinational conglomerate tier, Hologic Inc. and Danaher Corporation exemplify divergent automation strategies, while Abbott Laboratories occupies a position bridging laboratory-grade sensitivity with point-of-care accessibility. These three anchors represent the dominant competitive archetypes: installed-base loyalty through high-throughput automation, integrated workflow reduction of operator dependency, and portable nucleic acid platform development for decentralized settings.
| Leading Market Players |
|---|
| Hologic Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson and Company |
| Roche Diagnostics |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers |
| Qiagen |
| Others |
Supply & Pricing Matrix
WHO prequalification criteria for molecular diagnostics gate both qualified supply and premium-tier pricing access, compressing vendor eligibility to manufacturers with established cold-chain logistics and performance documentation. This certification filter concentrates procurement power among FDA-cleared and CE-marked platform holders while relegating uncertified entrants to price-competitive rapid diagnostic segments.
Pricing Analysis
Bundled reagent-rental agreements dominate high-throughput laboratory contracts while unbundled per-test pricing prevails in decentralized sexual health clinics. Price differentiation hinges on multiplex assay capability and CLIA complexity tier, with waived platforms commanding modest premiums over moderate-complexity alternatives. Pricing pressure stems from India's National Health Mission tender aggregation, which consolidates district hospital demand into volume-discounted procurement. Public health agencies exhibit highest price sensitivity due to budget-constrained screening programs, whereas private reference laboratories prioritize automation reliability over per-test economics.
Supply Chain Analysis
Freight costs for temperature-controlled reagent shipments absorb disproportionate margin in tropical clinic networks, elevating landed costs for nucleic acid amplification chemistries in India's southern states and Australia's northern territories. Manufacturing concentration centers on the United States, Germany, and India for thermal cycler production, with isothermal amplification reagents sourcing primarily from Japan and South Korea. Single-source vulnerability for polymerase enzyme supply creates exposure to fermentation capacity constraints. Distribution runs through specialized medical device distributors with cold-chain certification rather than general pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Chlamydia diagnostics rests on isothermal chemistry cost-down trajectories that eliminate thermal cycler capital requirements while preserving laboratory-grade sensitivity thresholds.
For Market Incumbents: Lock in installed-base loyalty through automated sample-to-answer workflow upgrades that reduce technician training burdens. Defend against portable nucleic acid platform entrants by embedding connectivity-enabled surveillance reporting into high-throughput contracts. Prioritize CE marking pathway acceleration under EMA's In Vitro Diagnostic Regulation to capture tender specifications in Germany and France. For New Entrants and Emerging Players: FDA CLIA-waived complexity reclassification in the United States opens a window for room-temperature-stable rapid diagnostic formats in correctional health and sexual health clinic channels. Target Australia's TGA-registered isothermal amplification segment where same-visit result protocols absorb capital previously allocated to laboratory infrastructure. Pursue WHO prequalification alignment to unlock Global Fund procurement in low-resource settings. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale molecular specialists with region-specific regulatory approvals because platform consolidation accelerates under WHO standardization pressure. Five-to-ten year viability favors vendors with dual-result Chlamydia-gonorrhea multiplex portfolios over single-target rapid test manufacturers. Watch India's CDSCO import licensing coordination under the Drugs and Cosmetics Act as inflection indicator for government tender access.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA-Waived Platform Submission | Unlocks same-visit testing in 2,800+ U.S. sexual health clinics previously restricted to laboratory referral. |
| CE Marking Pathway Acceleration | Mitigates EMA In Vitro Diagnostic Regulation transition risk for high-throughput laboratory segments in Germany. |
| Hospital System Partnership | Secures automated sample-to-answer workflow placement in India's National Health Mission district hospitals. |
| Software Companion Development | Enables cloud-integrated surveillance data transmission to Australia's national health information systems. |
| Reimbursement Strategy | Aligns assay pricing with NHS England's dual-result capability specifications for partner notification efficiency. |
Research Methodology
Multiple input streams — primary interviews with diagnostic laboratory directors, sexual health clinic procurement officers, and biomedical engineers; secondary validation against FDA 510(k) filings, EMA CE marking databases, and WHO prequalification lists; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates. Field intelligence from India's CDSCO coordination meetings and Australia's TGA registration pathways supplemented quantitative tender analysis.
Historical volume trajectories were cross-referenced against expert panel input across the projection horizon. The analytical framework modeled segmentation by product type, application, end user, and technology tier, with CAGRs derived from installed base expansion rates and assay consumption per instrument. Forecast inputs incorporated CLIA complexity reclassification timelines and National Health Mission scaling commitments.
Revisions become necessary when WHO diagnostic guideline revisions, EMA regulatory transition delays, or cold-chain logistics disruptions materialize. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Global Exocrine Pancreatic Insufficiency (EPI) Therapeutics and Diagnostics Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Chile in Vitro Diagnostics Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
Global Veterinary POC Diagnostic Market