
 Global Creatinine Measurement Market | 2026-2036
Global Creatinine Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Creatinine Measurement Market Foresight
A wide capital-intensity divergence between platform developers and reagent specialists is reorganizing competitive tiers in creatinine diagnostics. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to dominate high-throughput laboratory workflows. Randox Laboratories anchors its position through specialized quality control materials and external quality assessment programs. Siemens Healthineers competes via extensive installed bases of automated chemistry analyzers with embedded creatinine protocols.
Creatinine measurement quantifies serum or urine creatinine concentration, typically expressed in milligrams per deciliter or micromoles per liter, to estimate glomerular filtration rate and assess renal clearance function. The Jaffe alkaline picrate method remains widely deployed for its cost efficiency, though enzymatic creatinine assays are displacing it in laboratories seeking specificity against interfering substances. Automated analyzers occupy the largest value pool due to bundled consumables and service contracts, while point of care devices represent the fastest-expanding segment driven by emergency department and perioperative monitoring needs. Immunoassay kits command premium positioning in specialized reference laboratories requiring traceability to isotope dilution mass spectrometry standards.
The FDA regulates creatinine assays as Class II medical devices under 510(k) premarket notification pathways, while the EU AI Act and In Vitro Diagnostic Regulation impose stricter clinical evidence and post-market surveillance obligations. ISO 15189 accreditation requirements for medical laboratories shape procurement criteria and vendor qualification processes across multiple jurisdictions. Stakeholders must monitor evolving harmonization between IDMS-traceable reference methods and routine assay standardization initiatives to anticipate reimbursement and competitive dynamics.
Market Dynamics
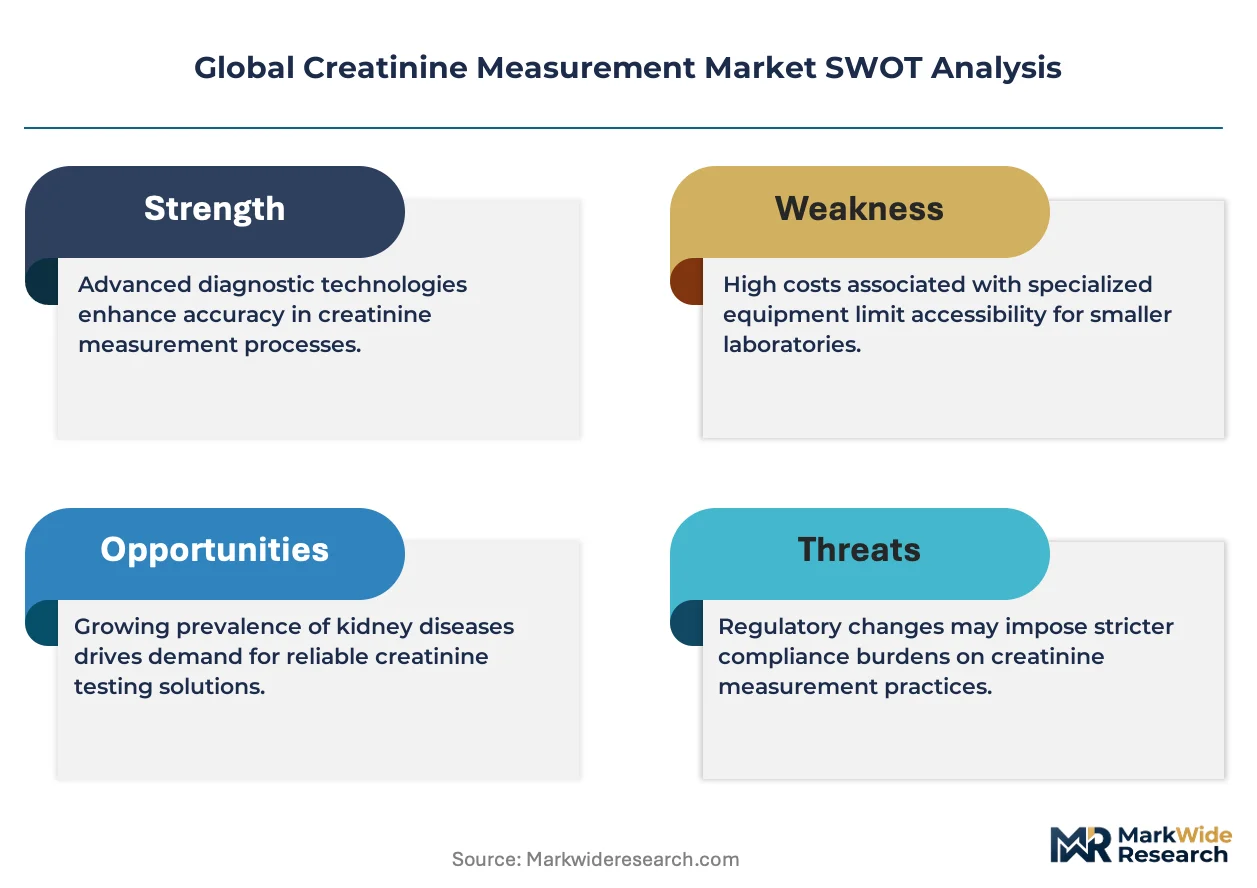
The enzymatic creatinine assay is decomposing the Jaffe method's dominance as laboratories prioritize specificity against bilirubin and hemoglobin interference, while the EU's In Vitro Diagnostic Regulation and FDA's CLIA tighten accuracy thresholds that favor method standardization.
Growth Catalysts
- Point-of-care expansion:Emergency departments and perioperative units in the United States are deploying handheld creatinine analyzers to reduce central lab turnaround times for acute kidney injury triage.
- IDMS traceability mandates:The EU's In Vitro Diagnostic Regulation requires isotope dilution mass spectrometry alignment for creatinine assays, forcing assay recalibration that improves diagnostic confidence.
- Chronic kidney disease screening programs:Japan's Ministry of Health has institutionalized population-wide creatinine testing protocols, expanding reagent volume demand through preventive care infrastructure.
Market Restraints
- Reagent cost volatility:Enzymatic creatinine reagents depend on purified creatininase enzymes whose fermentation production concentrates in South Korean and Chinese bioprocessing facilities.
- Reference laboratory consolidation:Independent reference labs in Germany face reimbursement compression from statutory health insurance consolidation, limiting capital for analyzer upgrades.
- Interference limitations:The Jaffe alkaline picrate method retains systematic bias from cephalosporin and dopamine interference, locking laboratories into dual-method workflows for complex patient populations.
Strategic Opportunities
- Home dialysis monitoring:Peritoneal dialysis patients in Australia require frequent creatinine self-monitoring, creating demand for connected point-of-care devices with telemedicine integration.
- Biomarker multiplexing:Cystatin C-creatinine ratio panels are converging with AI-assisted glomerular filtration rate algorithms to displace single-analyte testing in nephrology clinics.
- Indian diagnostic expansion:The country's PLI scheme for medical devices is attracting contract manufacturers to localize enzymatic reagent production for price-sensitive hospital chains.
Industry Challenges
- ISO 15189 accreditation timelines:Medical laboratories in France face 12-18 month certification queues from ANSM backlog, delaying analyzer procurement decisions.
- Legacy analyzer protocol fragmentation:Siemens, Roche, and Beckman Coulter chemistry platforms use incompatible creatinine calibration curves, forcing laboratories to maintain parallel quality control material inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Creatinine Measurement Market |
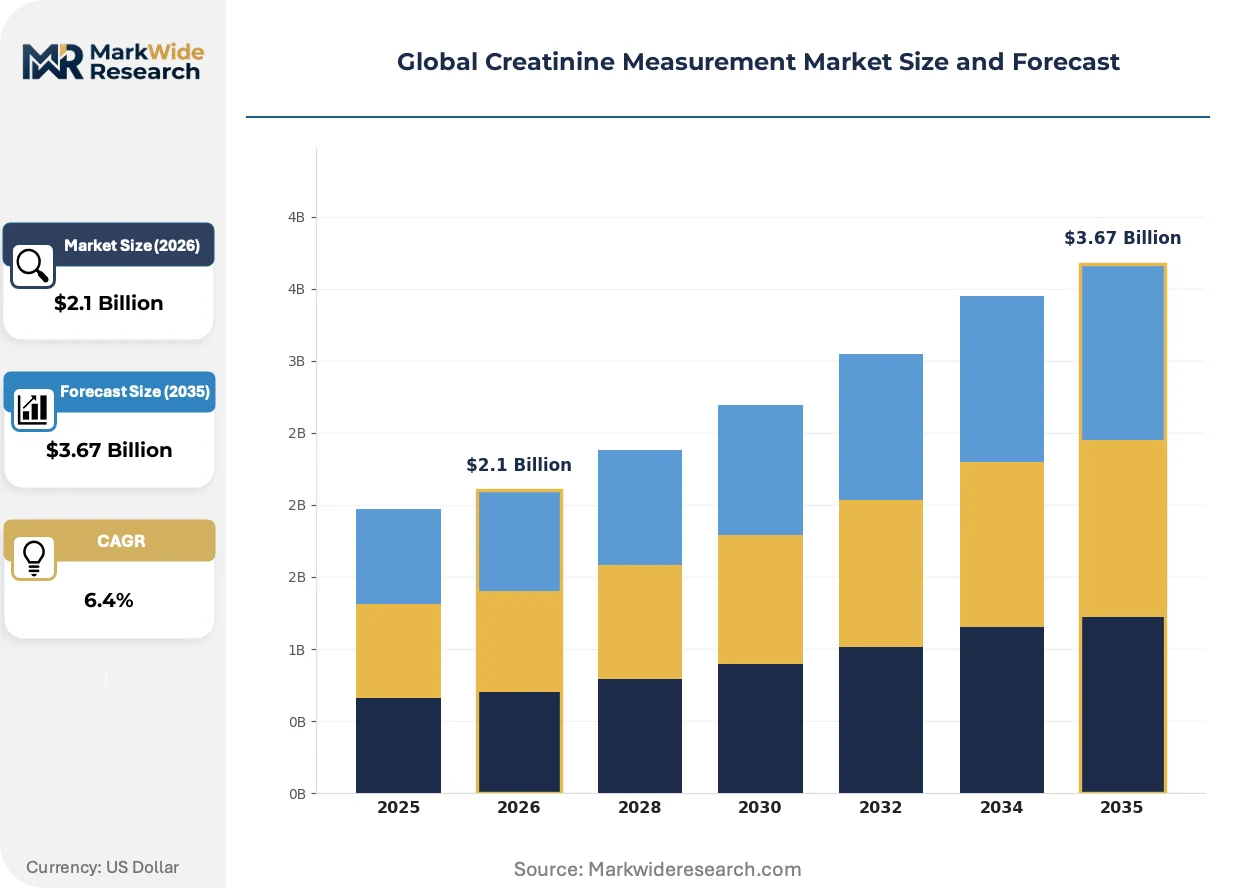
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Point of Care Devices, Immunoassay Kits, Colorimetric Assays, Biosensors Application: Renal Function Testing, Drug Monitoring, Clinical Research, Sports Medicine, Veterinary Diagnostics End User: Diagnostic Laboratories, Clinical Research Centers, Sports Clinics, Veterinary Hospitals, Pharmaceutical Companies Technology: Enzymatic, Jaffe Method, Electrochemical, Spectrophotometric, Fluorometric |
| Companies Covered | Thermo Fisher Scientific, Abbott, Hoffmann-La Roche, Siemens Healthineers, Danaher Corporation, Randox Laboratories, Nova Biomedical, Merck KGaA, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Creatinine Measurement Market Shifts & Advancements
Creatinine diagnostics is bifurcating between high-throughput laboratory automation and decentralized point-of-care deployment, with regulatory harmonization efforts compressing method diversity while AI-assisted interpretation layers add software-defined value.
Enzymatic creatinine assays are decomposing the Jaffe method's installed base. Nephrology reference laboratories in Switzerland and the Netherlands are adopting creatininase-based protocols to eliminate bilirubin interference in icteric samples. This specificity premium is compressing Jaffe reagent volumes to cost-optimized screening applications while enzymatic methods capture revenue-intensive confirmatory testing.
REACH substance restrictions are reshaping reagent formulation supply chains. The European Chemicals Agency's candidate list scrutiny of picric acid derivatives is forcing Jaffe reagent manufacturers to reformulate alkaline picrate stabilizers. German and French IVD suppliers are accelerating enzymatic pipeline investments to preempt regulatory discontinuation risk.
Renal function testing procurement is consolidating through integrated instrument-reagent-service bundles. Hospital laboratory directors in Japan and the United States are compressing vendor rosters to single-source agreements that lock in creatinine assay standardization across health system networks. This preference shift is most visible in United States academic medical centers where procurement committees prioritize total cost of ownership over per-test reagent pricing.
Global Creatinine Measurement Market Segmentation
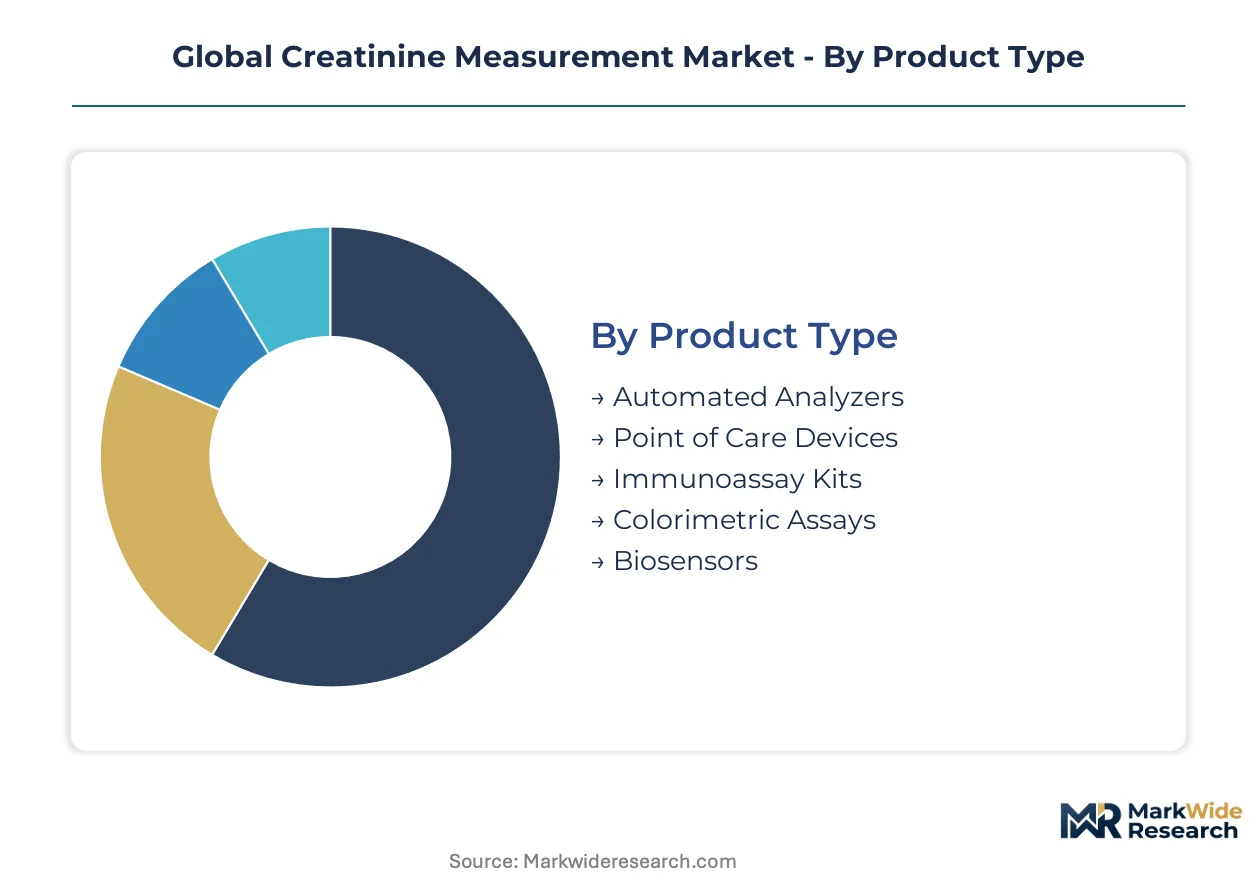
Creatinine measurement markets fragment across technology generations, with legacy methods facing substitution pressure from enzymatic and point-of-care alternatives. Segmentation reveals where capital flows concentrate and which product categories capture margin expansion from regulatory tightening.
Product Type:
Substitution pressure concentrates in reagent-based segments as laboratories abandon consumable-heavy workflows for integrated platform ecosystems.
- Automated Analyzers:High-throughput chemistry systems bundle creatinine protocols with electrolyte and metabolic panels. Hospital laboratories in the United States and Japan prioritize these platforms for health system standardization, locking in multi-year service contracts that displace standalone analyzers.
- Point of Care Devices:Handheld and cartridge-based systems deliver serum creatinine results within minutes. Emergency departments in Germany deploy these for acute kidney injury triage, bypassing central lab queues during critical care episodes.
- Immunoassay Kits:Reference laboratories seeking IDMS traceability specify these for confirmatory testing of borderline renal function cases.
- Colorimetric Assays:Cost-optimized Jaffe-based reagents retain volume in resource-constrained screening programs.
- Biosensors:Emerging electrochemical strips target home dialysis monitoring applications in Australia and the United Kingdom.
Automated analyzers anchor the volume base while point of care devices gain share at the steepest rate.
Application:
Renal function testing dominates revenue concentration, though adjacent applications diverge in margin structure and regulatory pathway complexity.
- Renal Function Testing:Serum and urine creatinine quantification for glomerular filtration rate estimation. Population screening programs in Japan and chronic disease management protocols in Germany sustain reagent demand through preventive care infrastructure.
- Drug Monitoring:Therapeutic drug monitoring for nephrotoxic agents requires precise creatinine clearance calculations. Oncology and transplant units in the United States specify enzymatic methods to eliminate bilirubin interference in hepatically compromised patients.
- Clinical Research:Phase III renal trials demand standardized creatinine assays across multi-site protocols.
- Sports Medicine:Athlete hydration and muscle mass assessment drives portable analyzer adoption.
- Veterinary Diagnostics:Companion animal renal panels replicate human assay architectures at reduced regulatory burden.
Renal function testing commands the installed base while drug monitoring applications expand most quickly on precision medicine tailwinds.
End User:
Procurement authority centralization favors vendors with integrated quality control and accreditation support capabilities.
- Diagnostic Laboratories:Hospital-based and independent reference labs process high-volume creatinine panels. ISO 15189 accreditation requirements in France and the United Kingdom shape vendor selection toward suppliers with external quality assessment programs.
- Clinical Research Centers:Contract research organizations standardize on IDMS-traceable assays for regulatory submission consistency.
- Sports Clinics:Performance medicine facilities in Australia adopt point-of-care systems for immediate athlete assessment.
- Veterinary Hospitals:Companion animal practices in the United States deploy chemistry analyzers with species-specific creatinine reference ranges.
- Pharmaceutical Companies:In-house bioanalytical labs support drug development pharmacokinetics studies.
Diagnostic laboratories concentrate purchasing volume while clinical research centers show the steepest spending trajectory on specialized assay standardization.
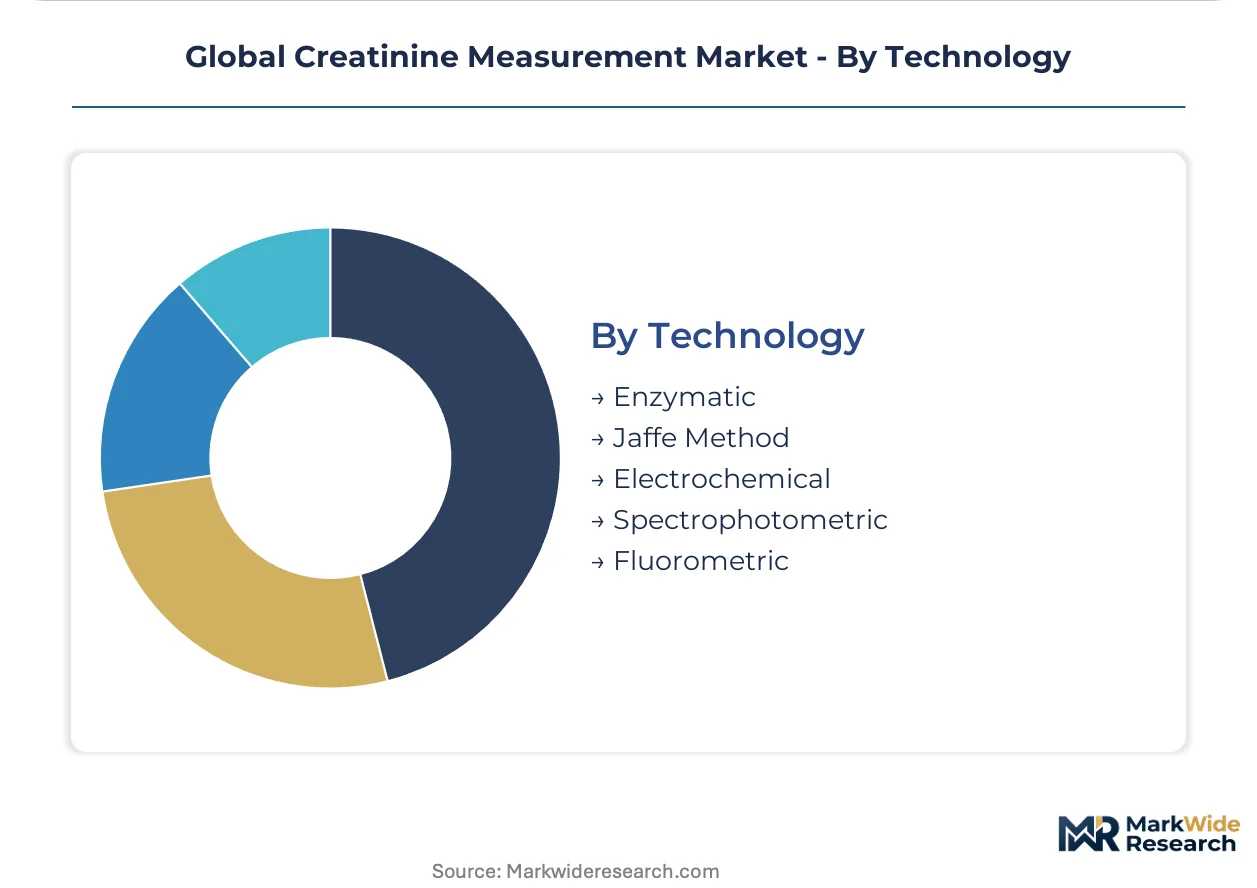
Technology:
Method diversity compresses as regulatory harmonization eliminates non-specific interference-prone protocols from premium applications.
- Enzymatic:Creatininase-based assays eliminate systematic bias from bilirubin, hemoglobin, and cephalosporin interference. Swiss and Dutch reference laboratories specify these for icteric and hemolyzed samples, commanding price premiums over Jaffe alternatives.
- Jaffe Method:Alkaline picrate chemistry retains cost advantage in high-volume screening despite known interference limitations. REACH substance restrictions on picric acid derivatives in Europe threaten long-term formulation continuity.
- Electrochemical:Amperometric biosensors enable miniaturization for point-of-care and wearable applications.
- Spectrophotometric:UV detection methods support specialized research applications requiring high sensitivity.
- Fluorometric:Fluorescence-based protocols serve niche high-throughput screening in drug discovery settings.
Enzymatic technology anchors the revenue base while electrochemical methods climb the fastest on decentralized testing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in creatinine diagnostics diverges sharply: hospital laboratories in Germany and Japan absorb premium enzymatic reagent costs for accuracy compliance, while screening programs in India and Brazil prioritize cost-optimized Jaffe methods for volume coverage.
United States
Emergency departments in Cleveland Clinic and Mayo Clinic networks deploy handheld creatinine analyzers for acute kidney injury triage. FDA's CLIA amendments tighten accuracy thresholds for waived testing sites. Boston's Longwood Medical Area anchors point-of-care device validation studies for perioperative monitoring protocols.
Germany
Statutory health insurance consolidation compresses reimbursement rates for independent reference laboratories in North Rhine-Westphalia. ECHA's REACH scrutiny of picric acid derivatives forces Jaffe reagent reformulation. Mannheim's Rhine-Neckar biotechnology cluster hosts enzymatic creatininase fermentation facilities serving European IVD manufacturers.
Japan
Ministry of Health population-wide chronic kidney disease screening institutionalizes serum creatinine testing protocols. PMDA alignment with IDMS-traceable standards mandates assay recalibration for domestic manufacturers. Tokyo's Koto biomedical district concentrates automated analyzer production for health system standardization contracts.
India
Hospital chains in Maharashtra and Karnataka expand nephrology departments for diabetes-related renal complications. CDSCO's medical device rules tighten import licensing for diagnostic reagents. Hyderabad's Genome Valley attracts PLI scheme contract manufacturers for localized enzymatic reagent production.
Australia
Peritoneal dialysis patients in New South Wales and Victoria drive demand for connected home monitoring devices. TGA's IVD regulatory framework accelerates point-of-care device approvals for telemedicine integration. Melbourne's Parkville biomedical precinct validates biosensor platforms for remote renal function tracking.
Global Creatinine Measurement Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in creatinine diagnostics. Full-platform vendors bundle instruments, reagents, and service contracts to lock hospital laboratories into multi-year agreements. Reagent specialists compete on external quality assessment programs and IDMS-traceable calibration materials. Strategic moves concentrate on assay standardization partnerships and point-of-care miniaturization licensing.
Within the integrated-platform tier, Thermo Fisher Scientific and Siemens Healthineers occupy positions defined by installed-base scale and chemistry analyzer ecosystem control. Randox Laboratories exemplifies the specialist archetype through quality control material dominance. Danaher Corporation anchors the life sciences conglomerate model with diagnostic platform diversification. These three company types represent how competitive positioning splits between comprehensive workflow ownership and targeted reagent excellence.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott |
| Hoffmann-La Roche |
| Siemens Healthineers |
| Danaher Corporation |
| Randox Laboratories |
| Nova Biomedical |
| Merck KGaA |
| Sysmex Corporation |
| Others |
Supply & Pricing Matrix
ISO 15189 accreditation requirements gate both vendor qualification timelines and price differentiation across enzymatic and Jaffe reagent tiers, compressing procurement decisions toward bundled platform contracts that embed after-sales service premiums.
Pricing Analysis
Service contracts and multi-year maintenance agreements anchor lifetime value for automated analyzer vendors. Three-tier pricing structure across premium enzymatic, standard Jaffe, and economy colorimetric levels segments buyers by accuracy requirements. Price differentiation hinges on IDMS traceability certification and health system volume scale. Cost compression in Jaffe reagents intensifies as REACH restrictions on picric acid derivatives force reformulation investments. Hospital laboratories in Germany exhibit lowest price sensitivity due to statutory reimbursement floors, while screening programs in India prioritize per-test economy.
Supply Chain Analysis
Extended lead times for purified creatininase enzymes concentrate inventory risk at South Korean and Chinese fermentation facilities. Enzymatic reagent production draws from bioprocessing capacity in Mannheim's Rhine-Neckar cluster and Seoul's Songdo biotech district. Raw material dependencies include creatininase enzymes, alkaline picrate stabilizers, and electrochemical sensor substrates. Single-source vulnerability in creatininase supply threatens assay continuity for European IVD manufacturers. Distribution runs through hospital GPO contracts in the United States and statutory health insurance tender processes in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and health network standardization mandates, with procurement committees in Japan and the United States compressing vendor rosters to single-source agreements.
For Market Incumbents: Compound installed-base advantage through integrated instrument-reagent-service bundles that lock laboratories into multi-year standardization contracts. Deepen quality control material offerings to capture external quality assessment program mandates from ISO 15189-accredited labs. Counter enzymatic substitution pressure by accelerating Jaffe reformulation ahead of REACH substance restrictions. For New Entrants and Emerging Players: Lead with point-of-care miniaturization for home dialysis monitoring in Australia and perioperative triage in United States emergency departments. Target telemedicine-integrated biosensor platforms as the most penetrable white space. Pursue PLI scheme contract manufacturing partnerships in India to localize enzymatic reagent production for price-sensitive hospital chains. For Investors and Strategic Acquirers: The EU's In Vitro Diagnostic Regulation reshapes the acquisition landscape by elevating clinical evidence requirements and post-market surveillance capabilities as valuation differentiators. Long-term viability favors targets with IDMS-traceable assay portfolios and established quality control material franchises. Monitor PMDA alignment timelines in Japan as the signal for regional assay recalibration investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| IDMS Traceability Certification | PMDA and EMA alignment mandates recalibration investments that filter non-compliant vendors from premium tenders. |
| Point-of-Care Miniaturization | Handheld analyzer development captures emergency department bypass demand in Cleveland Clinic and Mayo networks. |
| Enzymatic Reagent Localization | PLI scheme manufacturing in Genome Valley reduces import dependency for Indian hospital chain procurement. |
| Quality Control Material Expansion | External quality assessment program dominance locks reference laboratories into recurring reagent purchases. |
| Telemedicine Integration | Connected biosensor platforms for Australian peritoneal dialysis patients enable remote monitoring revenue streams. |
Research Methodology
Operator-level perspectives from hospital laboratory directors, nephrology clinic administrators, IVD procurement managers, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, PMDA approval databases, EMA In Vitro Diagnostic Regulation guidance documents, hospital procurement contract records, and ISO 15189 accreditation registries. Bottom-up reagent volume estimates and top-down analyzer installed-base calculations converged through iterative validation.
Sensitivity analysis tested forecast robustness across enzymatic substitution rates, REACH substance restriction timelines, and health system consolidation scenarios. The analytical framework segmented by technology generation, application specificity, end-user procurement authority, and regional regulatory cluster across the projection horizon. CAGRs derived from instrument replacement cycles, screening program expansion rates, and reagent consumption per test trends. Model inputs included creatininase fermentation capacity utilization and point-of-care device validation study completion rates.
The analysis sits within stated boundaries; outcomes outside IDMS standardization harmonization or enzymatic cost parity timelines would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and health system capital allocation priorities. Specific risk factors include REACH substance restriction acceleration, reference laboratory reimbursement compression, and creatininase supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Liver Disease Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market