
 Self-Administered HPV Test Market | 2026-2036
Self-Administered HPV Test Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Administered HPV Test Market Analytics
Home-based screening is restructuring demand patterns across the Self-Administered HPV Test Market, with women bypassing traditional clinic visits for private sample collection. Roche Diagnostics leverages its molecular diagnostics infrastructure to sustain channel dominance in laboratory-validated self-collection workflows. Everlywell competes through direct-to-consumer platform integration, while Teal Health, Inc specializes in purpose-built self-sampling devices designed for unsupervised use.
A self-administered HPV test enables individuals to collect their own cervical or vaginal specimens using a brush or swab device, with samples subsequently analyzed via PCR, nucleic acid hybridization, or sequencing methods detecting high-risk HPV DNA or RNA subtypes; the primary purpose is expanding cervical cancer screening reach among populations with limited healthcare access or privacy concerns. DNA Test products anchor current revenue streams due to established reimbursement and clinical validation, while Point-of-Care Test formats represent the fastest-growing segment as biosensor miniaturization reduces dependency on centralized laboratory infrastructure. Online Sales channels capture expanding margin pools through subscription models and telehealth integration, though Pharmacies retain volume leadership in markets with established over-the-counter diagnostic pathways.
FDA oversight of self-collection devices through the de novo and 510(k) pathways shapes product development timelines and clinical evidence requirements, while WHO prequalification standards influence procurement decisions in low- and middle-income country programs. The EU Medical Device Regulation and CE marking requirements for in vitro diagnostics create additional compliance layers for manufacturers seeking European market access. Stakeholders must monitor evolving payer coverage decisions for self-collected specimens versus clinician-collected alternatives, as reimbursement parity will determine whether home-based screening achieves sustained volume growth or remains confined to cash-pay consumer segments.
Market Dynamics
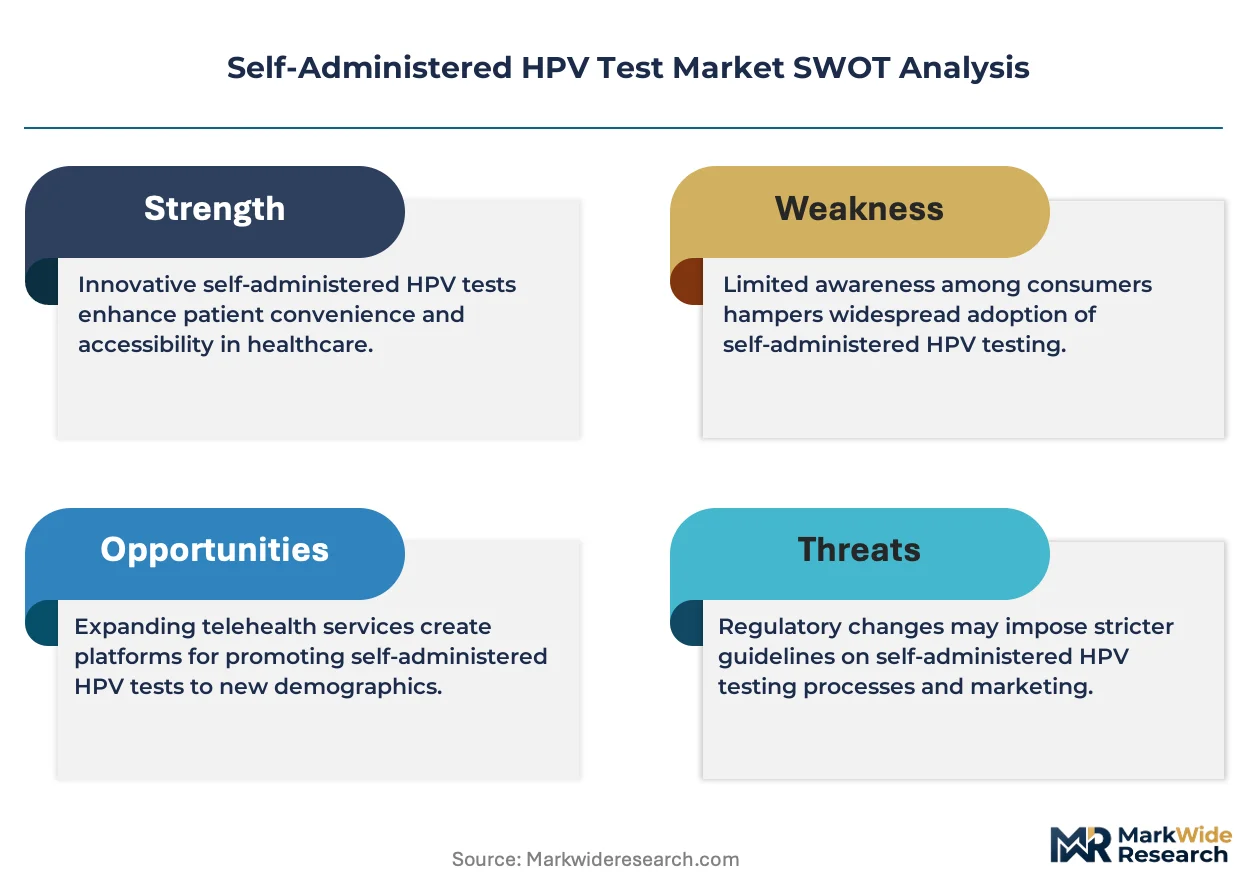
Self-administered HPV testing is restructuring around laboratory-to-consumer channel compression, as diagnostic manufacturers bypass traditional clinic networks and direct-to-consumer platforms capture specimen flow previously controlled by gynecology practices.
Growth Catalysts
- FDA de novo pathway expansion:The FDA's streamlined review for novel self-collection devices accelerates market entry timelines for manufacturers with robust clinical validation packages.
- Telehealth platform integration:Virtual care networks in the United States embed self-collection kits into asynchronous consultation workflows, extending screening access to rural counties with OB-GYN shortages.
- HPV DNA amplification miniaturization:Isothermal amplification chemistries reduce thermal cycler dependency, enabling decentralized specimen processing at lower capital thresholds.
Market Restraints
- Laboratory infrastructure concentration:PCR validation capacity clusters in metropolitan hubs, creating logistics bottlenecks for rural specimen transport and result turnaround.
- Reimbursement parity gaps:CMS and commercial payers in the United States maintain coverage differentials between clinician-collected and self-collected specimens, suppressing volume migration.
- Specimen quality variability:Unsupervised collection produces higher inadequate sample rates versus provider-guided sampling, requiring repeat testing and eroding cost efficiency.
Strategic Opportunities
- Medicaid expansion states:States with expanded eligibility present concentrated demand for low-cost screening alternatives to clinic-based Pap smears.
- Subscription preventive health bundles:Direct-to-consumer platforms bundle HPV testing with STI panels and contraception consultations, capturing recurring revenue streams.
- WHO prequalification procurement:Prequalified self-collection devices gain preferential access to national cervical cancer elimination programs in low- and middle-income countries.
Industry Challenges
- Clinical laboratory personnel shortages:Molecular diagnostics technicians are scarce in secondary markets, constraining processing capacity expansion.
- Cross-platform data integration:Self-collection results must reconcile with electronic health record systems designed around provider-ordered workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Administered HPV Test Market |
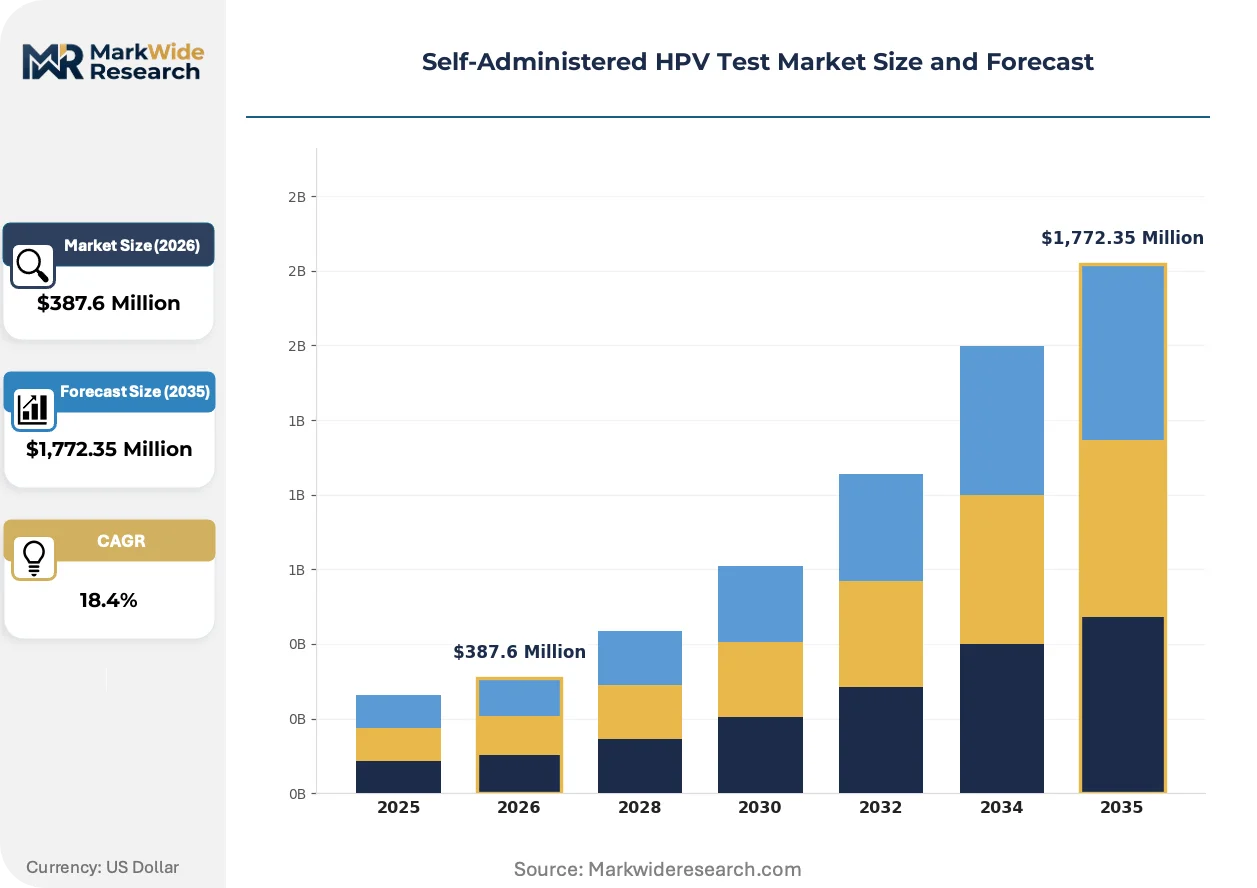
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Test, RNA Test, Combination Test, Point-of-Care Test End User: Home Users, Clinics, Laboratories, Healthcare Providers Technology: Polymerase Chain Reaction, Nucleic Acid Hybridization, Sequencing, Biosensors Distribution Channel: Online Sales, Pharmacies, Hospitals, Direct-to-Consumer |
| Companies Covered | Roche Diagnostics, Becton, Dickinson and Company, Hologic, Inc., QIAGEN, Quest Diagnostics, Everlywell, Teal Health, Inc, LifeCell International, Trinity Medical Centre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Administered HPV Test Market Evolving Landscape
Specimen-to-answer miniaturization is collapsing the traditional laboratory intermediary, while regulatory pathways and consumer channel preferences reshape how screening reaches end users.
CRISPR-based HPV detection is converging with lateral flow cartridge formats, enabling nucleic acid amplification without thermal cycling equipment. Community health centers in underserved regions pilot these platforms to eliminate cold-chain specimen transport. The technology is converging with smartphone-based result interpretation, compressing infrastructure requirements to near-zero in decentralized settings.
The FDA's 510(k) pathway for over-the-counter diagnostic devices is tightening clinical evidence standards for unsupervised use claims. Manufacturers must now submit usability studies with layperson cohorts, extending development timelines by 12-18 months. DNA Test formats face the steepest compliance burden, while Point-of-Care Test categories benefit from predicate device precedents.
Pharmacy retail networks are capturing specimen collection volume through in-store kiosk models that bridge self-administration with professional oversight. CVS and Walgreens deploy these hybrid stations in states with independent practice authority for pharmacists. This channel shift concentrates in the southeastern United States, where provider density lags national averages and consumers demonstrate higher pharmacy-based health service utilization.
Self-Administered HPV Test Market Segmentation
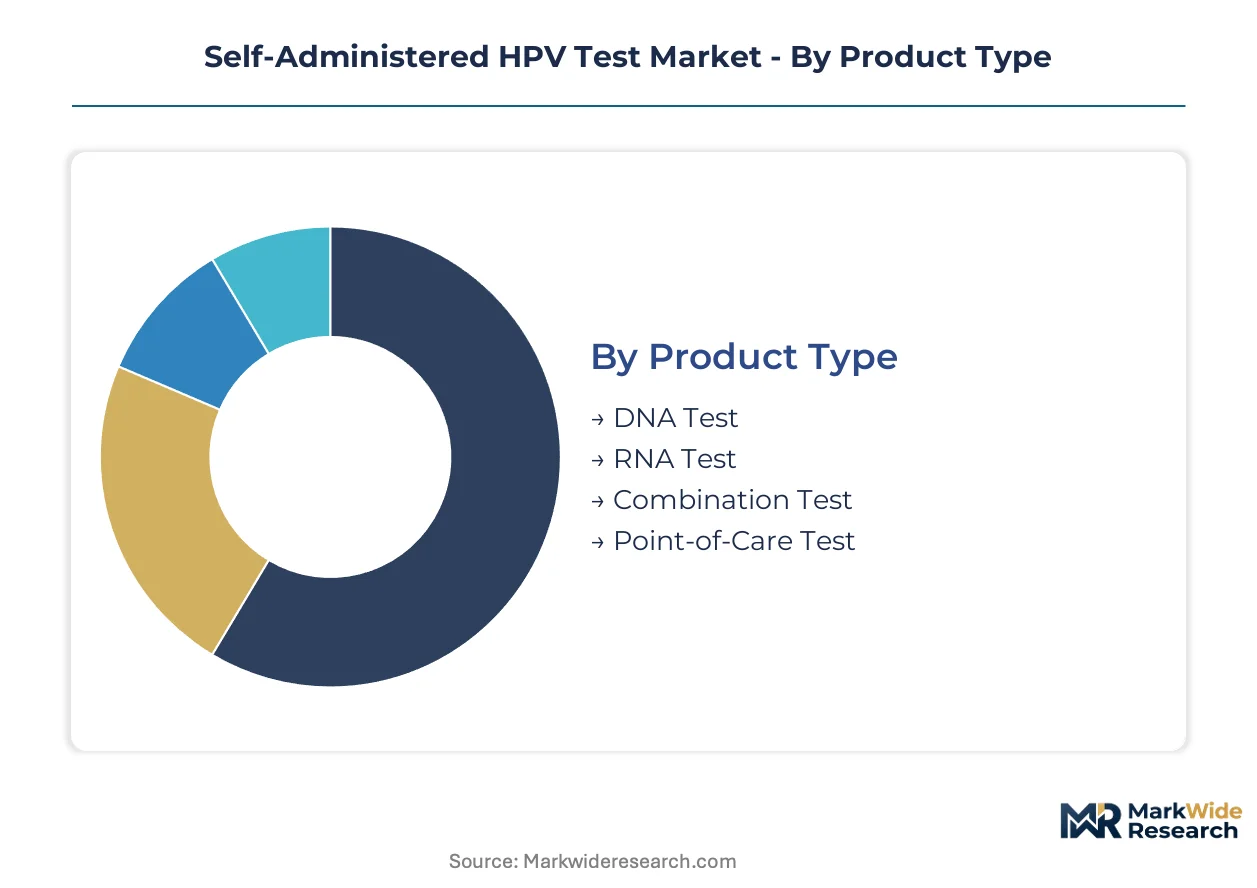
Segmentation in the Self-Administered HPV Test Market reveals how technology choices and channel strategies determine reimbursement pathways and clinical adoption curves. Manufacturers must align product configurations with specific end-user workflows to capture volume in this fragmented diagnostic landscape.
Product Type:
Supply concentration in molecular diagnostics infrastructure favors formats that leverage existing PCR and nucleic acid testing platforms already deployed across reference laboratories and health systems.
- DNA Test:Detects high-risk HPV DNA subtypes through amplification-based methods with extensive clinical validation and established CPT coding for reimbursement. Demand concentrates in the United States where commercial payers and CMS maintain coverage parity for DNA-based screening, though self-collection modifiers still create payment friction.
- Point-of-Care Test:Integrates specimen collection with on-device nucleic acid amplification, eliminating cold-chain transport and laboratory turnaround delays. Biosensor miniaturization is accelerating development, with pilot programs in Federally Qualified Health Centers targeting same-result consultation workflows.
- RNA Test:Targets E6/E7 oncogene mRNA expression as a marker of active viral transcription and malignant progression.
- Combination Test:Simultaneously detects HPV DNA and triage biomarkers such as p16 or Ki-67 to reduce unnecessary colposcopy referrals.
Today's leader: DNA Test. Tomorrow's challenger: Point-of-Care Test.
End User:
Cost tier stratification separates premium clinical workflows from mass-market consumer segments, with reimbursement eligibility and supervision requirements driving pricing architecture.
- Home Users:Unsupervised consumers purchasing through direct-to-consumer platforms or retail pharmacies, bearing full out-of-pocket costs or limited HSA/FSA eligibility. Privacy preferences and OB-GYN access barriers in rural Texas, Mississippi, and Alabama counties concentrate demand.
- Laboratories:CLIA-certified facilities processing self-collected specimens with validated PCR workflows, capturing professional fee revenue and managing result reporting to ordering clinicians.
- Clinics:Community health centers and family planning sites distributing self-collection kits as an alternative to speculum examination.
- Healthcare Providers:Individual clinicians prescribing self-collection for patients with physical disabilities, trauma histories, or scheduling constraints.
Volume concentrates with Home Users. Margin concentrates with Laboratories.
Technology:
Application-specific performance requirements favor amplification sensitivity in screening programs versus speed and portability in decentralized settings.
- Polymerase Chain Reaction:Gold-standard nucleic acid amplification with analytical sensitivity detecting fewer than 10 copies of viral DNA per reaction. Thermal cycler infrastructure and trained molecular diagnostics personnel requirements limit deployment to centralized laboratories.
- Biosensors:Electrochemical or optical transducers detecting nucleic acid hybridization without thermal cycling, enabling instrument-free operation at point-of-collection sites.
- Nucleic Acid Hybridization:Probe-based detection methods including hybrid capture and line probe assays for HPV genotyping.
- Sequencing:Next-generation and nanopore platforms for full viral genome characterization and novel subtype discovery.
PCR anchors current validation standards. Biosensors are climbing the fastest.
Distribution Channel:
Customer type segmentation distinguishes subscription-driven digital health platforms from transaction-based retail and institutional procurement.
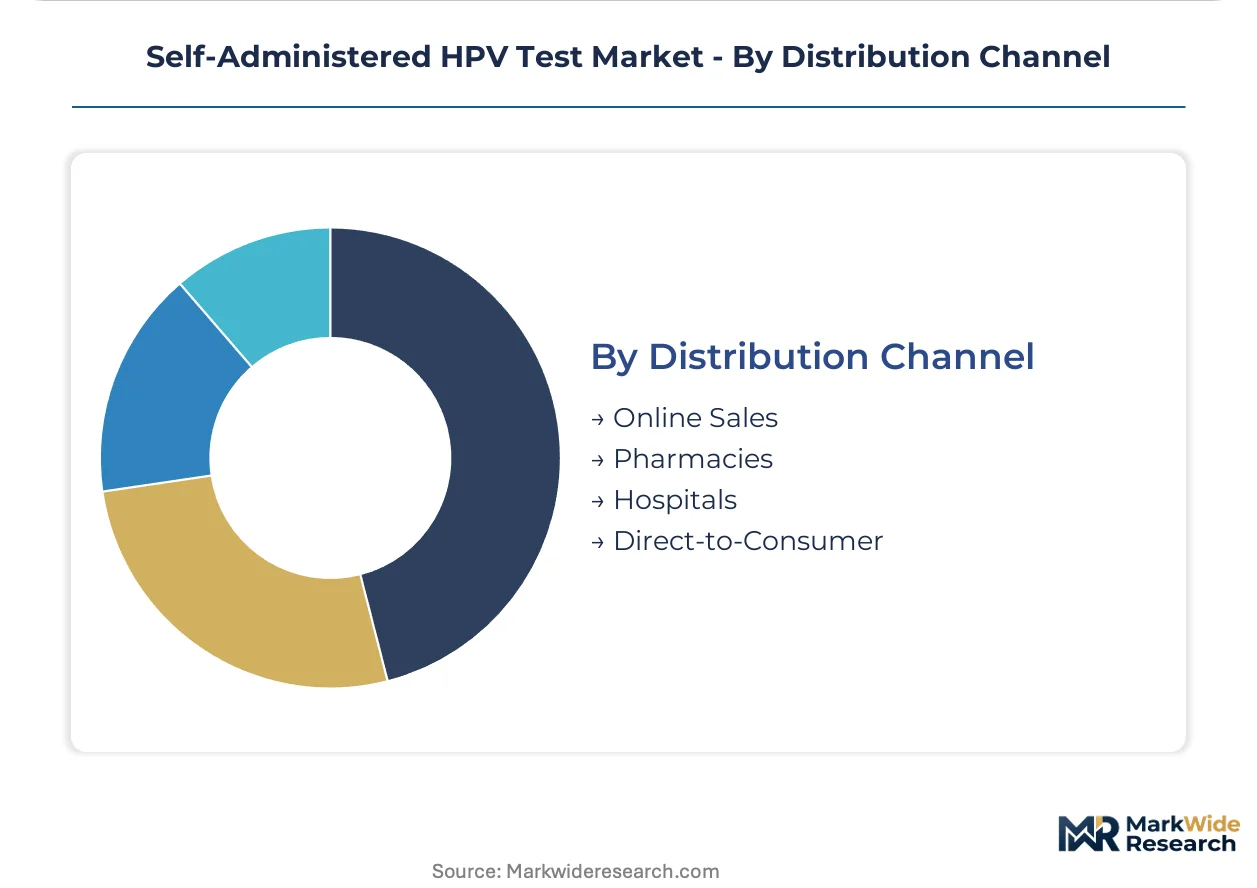
- Online Sales:Direct-to-consumer platforms and telehealth-integrated services offering subscription screening programs with automated result delivery and care navigation. Asynchronous consultation integration in the United States reduces patient leakage from positive result to follow-up colposcopy.
- Pharmacies:Retail chains with established over-the-counter diagnostic sections and pharmacist consultation services, particularly CVS and Walgreens locations in states with independent prescribing authority.
- Hospitals:Health system outpatient networks embedding self-collection into primary care and women's health clinics as a workflow efficiency tool.
- Direct-to-Consumer:Manufacturer-owned channels bypassing retail markups and capturing first-party data for product development.
Pharmacies hold volume leadership. Online Sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roche Diagnostics' molecular diagnostics infrastructure in Basel anchors European supply chains for laboratory-validated self-collection workflows. Distribution networks concentrate where FDA and WHO prequalification pathways intersect with direct-to-consumer platform maturity.
United States
Telehealth-integrated screening platforms in California and Texas drive consumer adoption among rural counties with OB-GYN shortages. FDA de novo pathway approvals for self-collection devices accelerate product launches from manufacturers with robust clinical validation packages. Boston's biotechnology corridor hosts CLIA-certified laboratories processing specimens from nationwide direct-to-consumer shipments.
Germany
EU Medical Device Regulation compliance requirements shape product development timelines for manufacturers seeking CE marking for in vitro diagnostics. The country's statutory health insurance system maintains reimbursement parity discussions for self-collected versus clinician-collected specimens. Munich's medical technology cluster concentrates biosensor miniaturization research for point-of-care test formats.
United Kingdom
NHS England's cervical cancer elimination targets create procurement demand for self-sampling devices in underserved regions. MHRA oversight of post-Brexit medical device regulations adds compliance layers distinct from EU MDR pathways. London's digital health startups partner with pharmacy retail networks to deploy hybrid collection kiosk models.
India
CDSCO regulatory frameworks for in vitro diagnostics influence domestic manufacturing priorities for low-cost self-collection devices. WHO prequalification standards determine access to national cervical cancer screening programs in partnership with state health missions. Hyderabad's pharmaceutical and diagnostics corridor houses contract manufacturers serving Southeast Asian export markets.
Australia
TGA approval pathways for self-collection devices align with national cervical screening program modernization efforts. Medicare reimbursement decisions for self-collected specimens determine volume migration from traditional Pap smear workflows. Melbourne's biomedical research institutes pilot CRISPR-based detection platforms for decentralized community health settings.
Self-Administered HPV Test Market Competitive Landscape
Strategic partnerships dominate the current landscape as diagnostic manufacturers align with direct-to-consumer platforms and telehealth networks to bypass traditional clinic channels. The vendor base concentrates around three tiers: multinational molecular diagnostics conglomerates with established laboratory infrastructure, digital health platforms integrating screening into subscription preventive care bundles, and purpose-built device specialists focused on unsupervised collection usability. Tiered competitive moves include technology licensing agreements for isothermal amplification chemistries and geographic expansion through WHO prequalification procurement in low- and middle-income country programs.
Among Swiss-German molecular diagnostics conglomerates, Roche Diagnostics and QIAGEN occupy positions anchoring laboratory-validated workflows, while Everlywell represents the direct-to-consumer platform archetype integrating asynchronous telehealth consultation. These three exemplify the structural division between infrastructure-heavy centralized processing and channel-compressed consumer-facing delivery, with each archetype capturing distinct margin pools across the specimen-to-result value chain.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Becton, Dickinson and Company |
| Hologic, Inc. |
| QIAGEN |
| Quest Diagnostics |
| Everlywell |
| Teal Health, Inc |
| LifeCell International |
| Trinity Medical Centre |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up laboratory networks concentrate processing capacity in metropolitan hubs, compressing margins for rural specimen logistics while enabling premium pricing for same-result turnaround in urban corridors. This ownership pattern ties pricing discipline directly to cold-chain infrastructure investments and CLIA-certified facility density.
Pricing Analysis
Direct-to-consumer platform margins capture value previously absorbed by clinic networks, with subscription models anchoring customer lifetime value against transactional pharmacy purchases. Three-tier pricing structure across laboratory-validated, point-of-care, and over-the-counter formats reflects FDA clearance tier and clinical validation depth. Cost compression in the home-user segment intensifies as telehealth platforms bundle HPV screening with broader preventive care panels. Medicaid expansion states exhibit highest price sensitivity, while cash-pay consumers in OB-GYN shortage counties demonstrate lower elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of isothermal amplification reagents and Taiwanese producers of biosensor microelectronics. Molecular diagnostics supply chains draw from Germany for precision optics, the United States for PCR thermal cyclers, and India for plastic consumables. Tariff exposure on Chinese-manufactured collection devices threatens cost structures for price-sensitive home-user segments. Distribution runs through CLIA-certified reference laboratories that validate self-collected specimens before result release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Self-Administered HPV Test Market compounds steadily as cervical cancer elimination targets in the United States and WHO prequalification pathways in low-income countries sustain procurement demand across economic cycles.
For Market Incumbents: Anchor laboratory infrastructure dominance by acquiring CLIA-certified processing capacity in secondary markets where molecular diagnostics technician shortages constrain competitor expansion. Deepen backward integration into biosensor manufacturing to offset reagent cost volatility and defend margin position against point-of-care test miniaturization. For New Entrants and Emerging Players: Telehealth-integrated asynchronous consultation platforms offer the most penetrable route for bypassing established clinic networks and capturing positive-result care navigation revenue. Target pharmacy kiosk deployments in southeastern United States states with independent pharmacist prescribing authority and below-average OB-GYN density. For Investors and Strategic Acquirers: Diagnostic platform conglomerates with existing FDA 510(k) predicate libraries are the most active acquirers in this space, seeking point-of-care test capabilities to complement centralized laboratory workflows. Watch WHO prequalification award velocity as the signal indicating which device manufacturers will secure national program procurement in low- and middle-income country elimination initiatives.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Pathway Navigation | First-mover clearance for unsupervised use claims creates 12-18 month regulatory moats against followers. |
| CLIA Laboratory Network Partnership | Validated processing agreements with Quest or LabCorp unlock reimbursement parity for self-collected specimens. |
| Isothermal Amplification Licensing | CRISPR and LAMP chemistry access eliminates thermal cycler dependency for decentralized deployment. |
| Telehealth Platform Integration | Asynchronous consultation embedding with Hims & Hers or Ro captures care navigation revenue from positive screens. |
| WHO Prequalification Submission | Prequalified status unlocks national cervical cancer program procurement in India, Nigeria, and Indonesia. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs specialists at FDA-cleared manufacturers, CLIA laboratory operations directors, telehealth platform product managers, and pharmacy retail health services executives. Secondary validation drew from FDA 510(k) and de novo submission databases, CMS reimbursement coding decisions, WHO prequalification listings, and GPO contract archives. Bottom-up specimen volume modeling and top-down market sizing triangulated across these sources.
Segment-weighted forecasting anchored projections to DNA test, point-of-care test, and RNA test format trajectories, crossed with home-user, laboratory, and clinic end-user penetration curves across the analysis window. CAGRs derived from logistic adoption curves fitted to telehealth integration rates and Medicaid expansion state screening program rollouts. Biosensor miniaturization timelines and FDA review duration assumptions shaped point-of-care test growth contours.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based lateral flow detection would alter the outlook if regulatory validation accelerates beyond PCR predicate timelines. Forecasts reflect assumptions about reimbursement parity evolution and laboratory personnel supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Prenatal Diagnostics Market
Diagnostics
At-Home Cancer Testing Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Netherlands in-Vitro Diagnostics Market
Diagnostics
Precision Diagnostics Market
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Inflammatory Markers Market
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Global Chemiluminescence Immunoassay (CLIA) Market
Diagnostics
IVD Antibody Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market