
 Thoracic Surgery Market | 2026-2036
Thoracic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Thoracic Surgery Market Intelligence
Software-defined capabilities enabled through subscription services for robotic platforms is hardening the division between capital equipment sales and recurring revenue streams. This model shifts the focus from one-time hardware purchases to long-term service relationships. Intuitive Surgical leverages its established position in robotic-assisted systems with its da Vinci platform. Medtronic competes across a wider spectrum, offering both robotic solutions and a comprehensive portfolio of surgical staplers and energy devices for open and minimally invasive procedures.
Thoracic surgery encompasses surgical procedures performed on organs within the chest cavity, including the lungs, esophagus, and mediastinum. These interventions often require specialized instrumentation, such as thoracoscopes with high-definition imaging or surgical staplers designed for specific tissue thicknesses. The primary purpose is to diagnose and treat diseases like lung cancer, esophageal disorders, and chest trauma. Robotic-assisted technology is accelerating in adoption and commands premium pricing. Procedures like lobectomy and video-assisted thoracic surgery (VATS) see high volume in academic hospitals and specialized clinics.
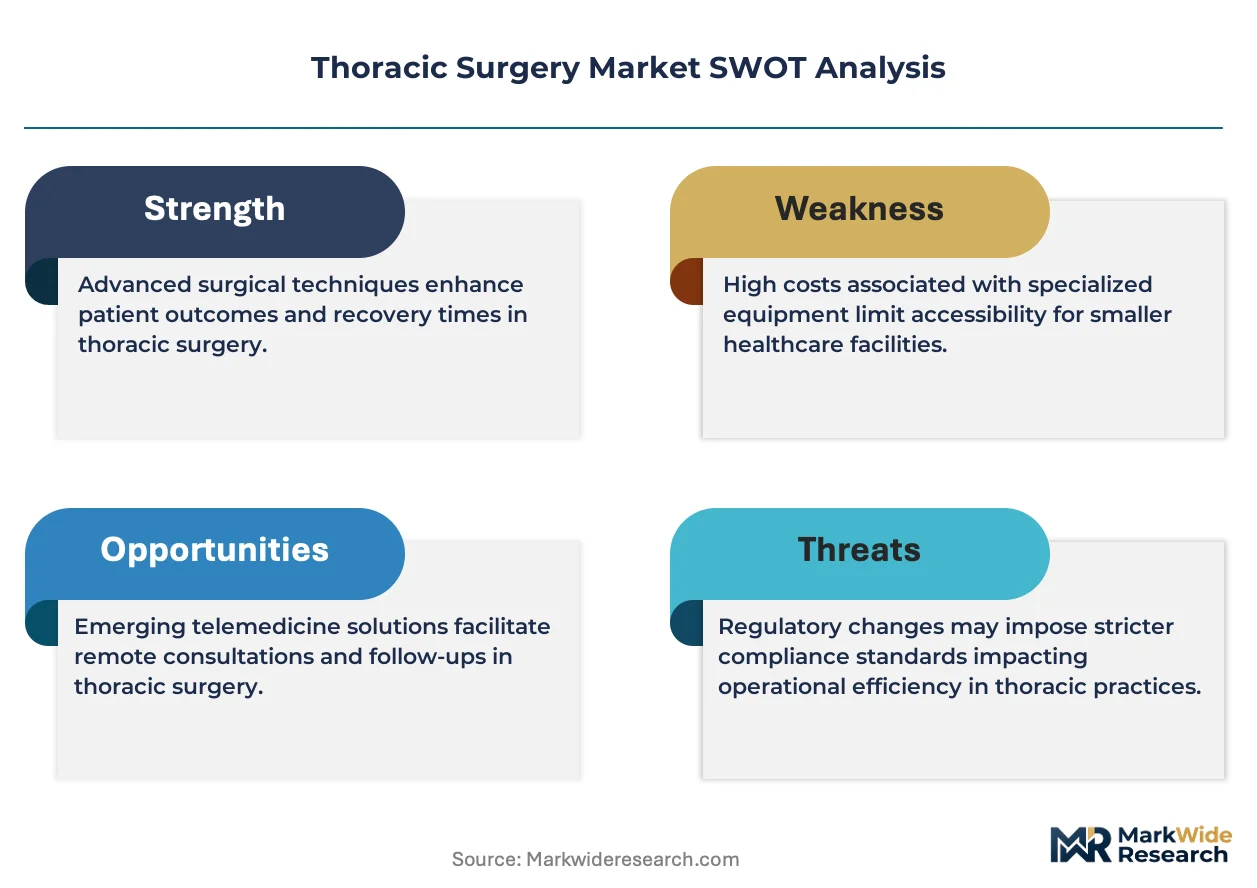
Regulatory frameworks, including the US FDA's 510(k) clearance process and the EU's Medical Device Regulation (MDR), dictate market access for new surgical devices. These regulations establish stringent requirements for clinical data, device safety, and post-market surveillance. In parallel, China's NMPA has its own distinct approval pathways, impacting global product launch sequencing. The critical decision for device manufacturers revolves around balancing investment in novel robotic platforms against expanding the capabilities of existing endoscopic instrument portfolios.
Market Dynamics
The central structural force shaping the thoracic surgery market is the bifurcation of revenue models between capital equipment and recurring services. This dynamic, driven by the adoption of robotic platforms, is compelling hospitals to evaluate long-term service relationships over one-time hardware purchases.
Growth Catalysts
- Aging Demographics:Countries with rapidly aging populations, such as Japan and China, exhibit a higher incidence of thoracic diseases like lung cancer, directly increasing the volume of surgical procedures and demand for specialized instruments.
- Value-Based Healthcare:Reimbursement frameworks in the US and parts of Europe that reward improved patient outcomes are accelerating the shift to minimally invasive VATS and robotic procedures, which are associated with shorter recovery times.
- Academic Hospital Adoption:The concentration of robotic-assisted systems within academic medical centers and specialized cancer clinics creates a strong pull-through demand for compatible instrumentation, software subscriptions, and advanced training programs.
Market Restraints
- High Capital Costs:The substantial initial investment for robotic surgical platforms and their dedicated operating suites remains a significant barrier to adoption for community hospitals and healthcare systems in emerging economies.
- Surgeon Training Bottleneck:Proficiency in robotic-assisted thoracic surgery requires a long and intensive learning curve, creating a scarcity of qualified surgeons that limits the capacity to perform these advanced procedures.
- EU Regulatory Hurdles:The European Union's Medical Device Regulation (MDR) imposes stringent requirements for clinical data and post-market surveillance, increasing the cost and time-to-market for new surgical technologies.
Strategic Opportunities
- Geographic Expansion:There is significant potential for market entry and expansion in large, underpenetrated countries like India and Brazil, where healthcare infrastructure is modernizing and demand for advanced surgical care is rising.
- AI-Powered Surgical Planning:The convergence of artificial intelligence with preoperative CT imaging allows for the development of software tools that can aid in precise surgical planning and automated lesion detection, creating a new value stream.
- Single-Port Instrumentation:Developing next-generation robotic platforms and instruments specifically for single-port thoracic surgery represents a key opportunity to offer even less invasive procedures and capture a premium segment.
Industry Challenges
- Data Interoperability:Achieving seamless integration between disparate surgical robots, imaging modalities, and hospital electronic health record systems is a persistent technical challenge that complicates workflow efficiency and data analysis. *Instrument Reprocessing Complexity: The intricate design of advanced thoracoscopes and robotic instruments poses significant challenges for hospital central sterile services departments, affecting instrument availability and operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thoracic Surgery Market |
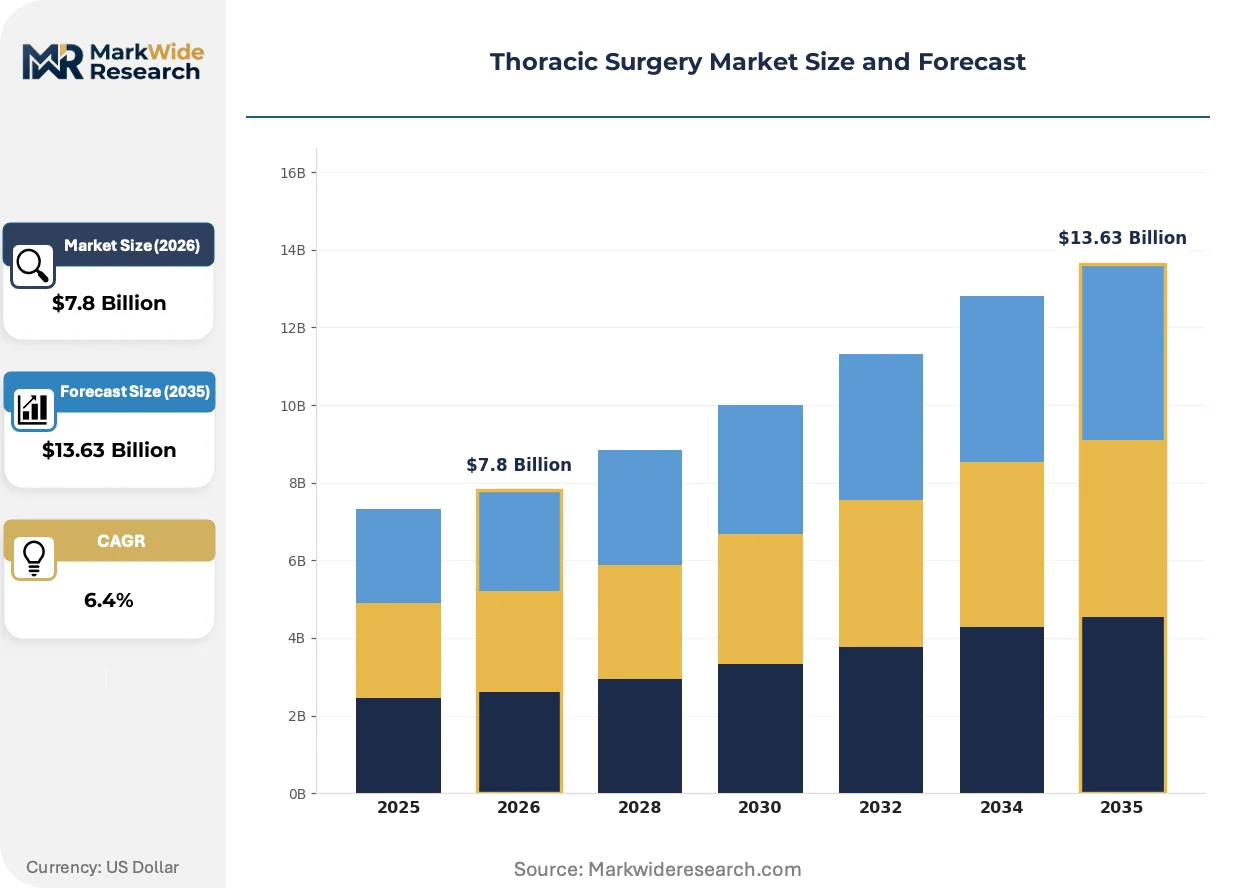
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Lobectomy, Pneumonectomy, Thoracoscopy, Bronchoscopy, Mediastinoscopy, Decortication Technology: Robotic-Assisted, Video-Assisted Thoracic Surgery, Laser Surgery, Cryotherapy, Electrocautery, Ultrasonic End User: Specialized Clinics, Academic Hospitals, Community Hospitals, Outpatient Surgical Centers, Trauma Centers Device Type: Surgical Staplers, Thoracoscopes, Electrosurgical Devices, Endoscopic Instruments, Energy Devices, Retractors |
| Companies Covered | Medtronic, Johnson & Johnson, Intuitive Surgical, Stryker, Olympus Corporation, Karl Storz, GE Healthcare, Boston Scientific, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thoracic Surgery Market Strategic Shifts & Innovations
The evolution of surgical practice is defined by the fusion of digital technologies with mechanical instrumentation. This integration creates new service-based revenue models and establishes higher benchmarks for device efficacy, data management, and procedural consistency.
AI-powered image guidance systems are being integrated directly into modern thoracoscopes, overlaying anatomical maps and tumor margins onto the surgeon's real-time view. High-volume cancer centers and academic hospitals are leading the adoption of this technology. This fusion of software and hardware is consolidating the value proposition around complete surgical platforms, making standalone imaging devices less competitive.
China's NMPA has established accelerated approval pathways for innovative medical devices deemed to have significant clinical advantages. This policy incentivizes manufacturers to prioritize the Chinese market for launching novel robotic systems and advanced energy devices. Consequently, global device firms are adapting their clinical trial strategies and product launch sequencing to align with NMPA requirements, sometimes preceding FDA or EU submissions.
Hospital purchasing committees are progressively moving from single-vendor capital equipment contracts to multi-vendor, interoperable ecosystems. This shift disrupts the traditional lock-in model where one robotic platform dictated the choice of all associated instruments and software. This trend is most visible in large hospital networks across the United States and Germany, where operational flexibility and cost control are primary objectives.
Thoracic Surgery Market Segmentation
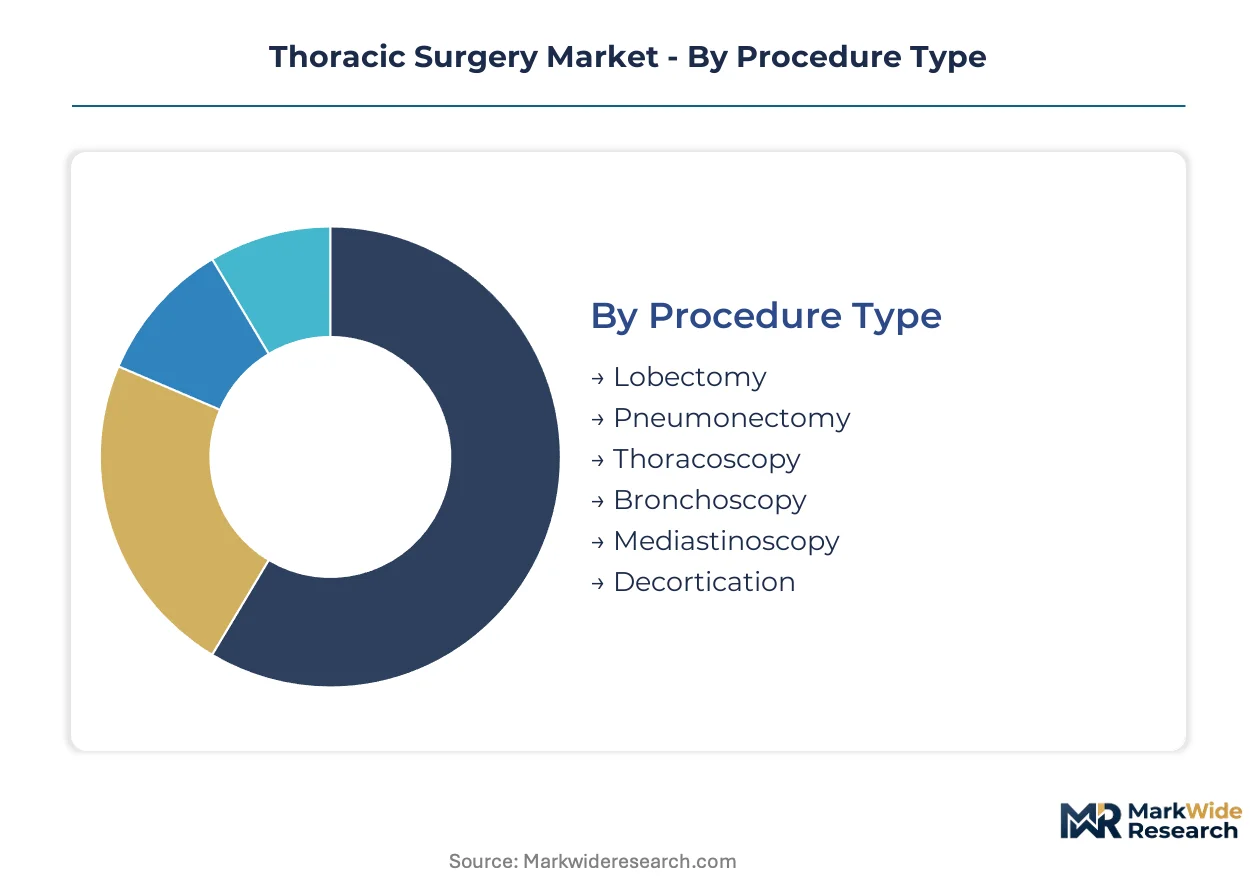
Understanding the varied segments within the thoracic surgery market is crucial for device manufacturers to align product development with clinical needs and for healthcare providers to optimize resource allocation. This segmentation highlights the diverse approaches, technologies, and institutional settings driving surgical interventions in the chest cavity.
Procedure Type:
Hospitals and surgical centers prioritize specific procedure types based on disease prevalence and patient outcomes.
- Lobectomy:This procedure involves the surgical removal of an entire lobe of the lung, primarily performed for lung cancer treatment or severe infections. Demand concentrates in specialized cancer centers in countries like the United States due to high lung cancer incidence.
- Thoracoscopy:A minimally invasive surgical technique utilizing a thoracoscope to visualize and operate within the chest cavity, often preferred for diagnostic biopsies and early-stage lung resections. Adoption is accelerating in academic hospitals across Germany, driven by value-based healthcare models.
- Pneumonectomy:The surgical removal of an entire lung, typically reserved for advanced lung cancer or extensive lung disease where other treatments are not viable.
- Bronchoscopy:An endoscopic procedure used to examine the airways within the lungs, frequently employed for diagnosis of lung conditions and removal of foreign bodies.
- Mediastinoscopy:An invasive diagnostic procedure to examine the mediastinum, the space between the lungs, often used for staging lung cancer or diagnosing other mediastinal masses.
- Decortication:A surgical procedure to remove a restrictive layer of fibrous tissue from the surface of the lung, commonly performed to treat empyema or chronic pleural effusions.
Lobectomy leads on scale; Thoracoscopy leads on momentum.
Technology:
The choice of technology in thoracic surgery directly influences surgical precision and recovery times.
- Robotic-Assisted:These systems provide surgeons with enhanced dexterity, 3D visualization, and tremor filtration, enabling complex minimally invasive procedures with greater precision. Demand is concentrating in academic medical centers and specialized clinics in Japan due to an aging population and high disease burden.
- Video-Assisted Thoracic Surgery:VATS involves small incisions and a video camera to guide surgical instruments, offering a less invasive alternative to open surgery with reduced pain and shorter hospital stays. This technology sees widespread adoption in European hospitals aiming for improved patient outcomes and cost efficiencies.
- Laser Surgery:Utilizes focused laser beams for precise tissue cutting and ablation, often employed in specific lung resections or for treating tracheal stenosis.
- Cryotherapy:Involves the use of extreme cold to destroy abnormal tissue, finding application in treating certain lung tumors or managing airway obstructions.
- Electrocautery:Uses heat generated by an electric current to cut tissue or control bleeding, a fundamental tool in most surgical procedures.
- Ultrasonic:Employs high-frequency sound waves for tissue dissection and coagulation, offering precision and minimizing thermal spread in delicate structures.
Robotic-Assisted systems command premium investment; Video-Assisted Thoracic Surgery offers widespread accessibility.
End User:
End-user decisions for thoracic surgery solutions are shaped by patient volume and specialized care requirements.
- Academic Hospitals:These institutions serve as major referral centers, conducting complex procedures, engaging in research, and training future surgeons. Academic hospitals in the United States drive demand for advanced robotic platforms and specialized instrumentation.
- Specialized Clinics:Focused on specific conditions or patient populations, these clinics often adopt cutting-edge technologies to offer highly specialized care. Demand for advanced thoracoscopes is high in specialized cancer clinics across China.
- Community Hospitals:Providing general surgical services to local populations, these hospitals often balance capital costs with the need for effective, widely applicable surgical tools.
- Outpatient Surgical Centers:Facilities performing less complex procedures that do not require overnight stays, focusing on efficiency and patient throughput.
- Trauma Centers:Equipped to handle severe injuries, these centers require robust and versatile surgical instruments for emergency thoracic interventions.
Academic Hospitals represent centers of advanced training; Specialized Clinics drive innovation in niche procedures.
Device Type:
The selection of device types often depends on the specific surgical approach and tissue manipulation needs.
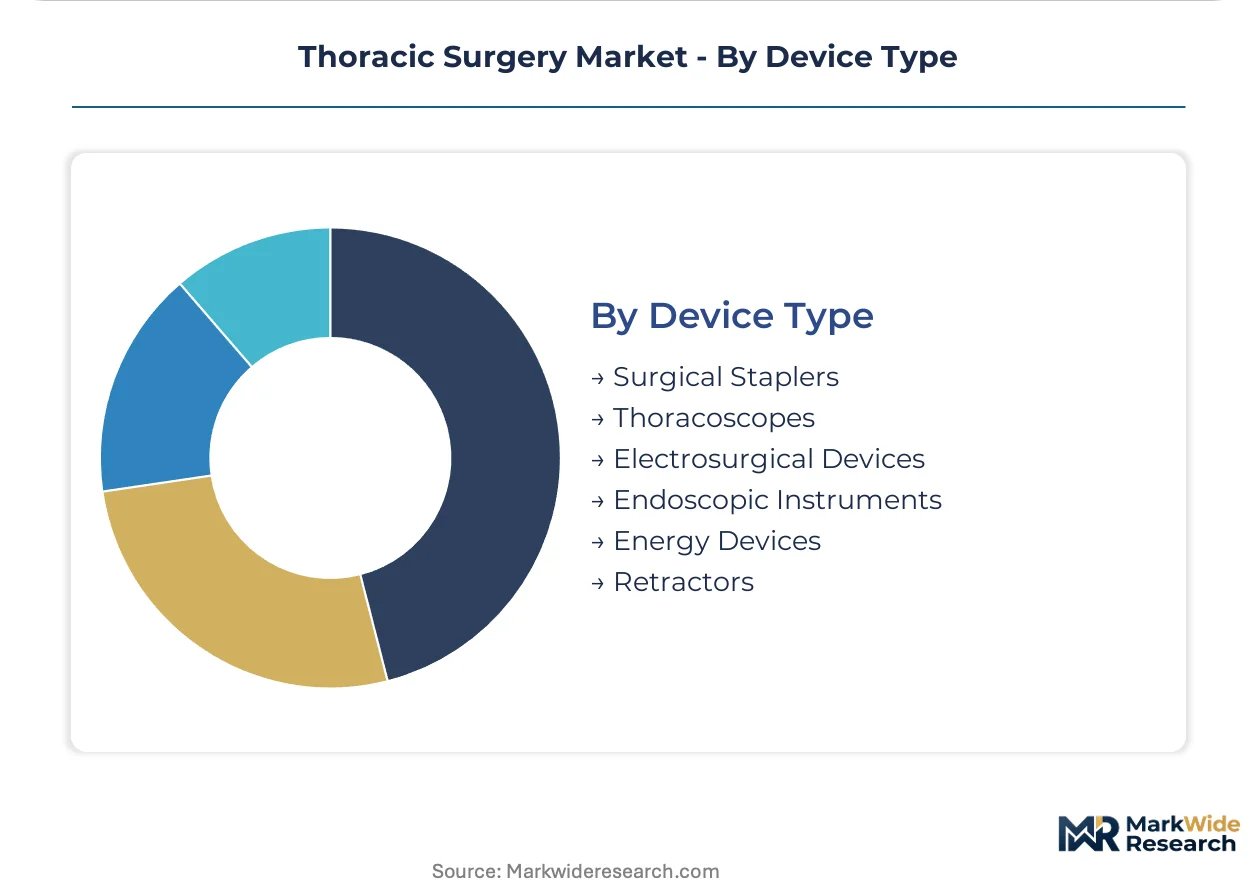
- Thoracoscopes:These specialized endoscopes provide high-definition imaging and illumination within the chest cavity, essential for minimally invasive thoracic procedures. Demand is concentrating in high-volume cancer centers in South Korea due to emphasis on early diagnosis.
- Surgical Staplers:Devices used to simultaneously cut and seal tissue, critical for lung resections and other procedures requiring precise tissue approximation and hemostasis. These are widely used across hospitals in India for both open and minimally invasive surgeries.
- Electrosurgical Devices:Instruments that use high-frequency electrical current to cut, coagulate, desiccate, or fulgurate tissue during surgery.
- Endoscopic Instruments:A broad category including graspers, scissors, dissectors, and other tools designed for use through small incisions in minimally invasive surgery.
- Energy Devices:Instruments that use various forms of energy (e.g., ultrasonic, radiofrequency) for tissue dissection and vessel sealing, enhancing surgical efficiency.
- Retractors:Surgical instruments used to hold back tissue or organs, providing access to the surgical site during open thoracic procedures.
Surgical Staplers maintain high procedural volume; Thoracoscopes enable advanced visualization capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global thoracic surgery market exhibits distinct regional dynamics driven by varying regulatory landscapes. Device manufacturers often sequence product launches to leverage accelerated approval pathways, influencing market entry strategies. This regulatory arbitrage affects investment in novel platforms versus existing instrument portfolios across major geographies.
United States
High lung cancer incidence drives demand for lobectomy procedures in the United States. The US FDA's 510(k) clearance process dictates market access for new surgical devices. Academic hospitals in major medical centers like Boston and Houston concentrate demand for advanced robotic platforms. These institutions also drive specialized instrumentation and advanced training programs.
China
China's aging population and expanding advanced healthcare infrastructure fuel demand for specialized thoracic care. The NMPA's accelerated approval pathways incentivize manufacturers to prioritize this market for novel robotic systems. Specialized cancer clinics in Shanghai and Beijing show high demand for advanced thoracoscopes. These clinics are leading the adoption of cutting-edge technologies.
Germany
Value-based healthcare models in Germany accelerate the shift towards minimally invasive VATS procedures. The EU's Medical Device Regulation (MDR) imposes stringent requirements for clinical data and post-market surveillance. Academic hospitals across cities like Berlin and Munich are adopting thoracoscopy for improved patient outcomes. These centers prioritize cost efficiencies in surgical interventions.
Japan
Japan's rapidly aging population contributes to a high incidence of thoracic diseases, increasing surgical procedure volumes. The PMDA ensures device safety and efficacy through its regulatory approval processes. Academic medical centers in Tokyo and Osaka concentrate demand for robotic-assisted systems. These institutions benefit from enhanced dexterity and 3D visualization for complex procedures.
India
India's modernizing healthcare infrastructure and rising demand for advanced surgical care create significant market potential. The PLI scheme for medical devices supports domestic manufacturing and innovation. Hospitals in metropolitan areas like Mumbai and Bangalore widely use surgical staplers. These cities are also seeing increased adoption of minimally invasive techniques.
Thoracic Surgery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the thoracic surgery market. The market exhibits a tiered structure, with established medical device giants dominating premium robotic platforms and comprehensive surgical solutions. Niche innovators focus on specialized instrumentation, advanced imaging, and AI-powered software solutions. Competitive moves primarily involve strategic partnerships to expand technology ecosystems and continuous portfolio diversification into less invasive techniques.
Among companies offering comprehensive surgical platforms, Intuitive Surgical exemplifies a focused approach to robotic-assisted systems, particularly with its da Vinci platform. Medtronic, a diversified medical technology company, occupies a position across both robotic solutions and a broader portfolio of surgical staplers and energy devices. Johnson & Johnson, another large medical device corporation, sits within the segment providing a wide array of surgical instruments and solutions for various thoracic procedures. These firms anchor the market by influencing technological benchmarks and driving innovation in advanced surgical tools.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Intuitive Surgical |
| Stryker |
| Olympus Corporation |
| Karl Storz |
| GE Healthcare |
| Boston Scientific |
| Getinge AB |
Cost & Logistics Intelligence
Hospitals' progressive shift to multi-vendor, interoperable ecosystems compels device manufacturers to offer flexible pricing models. This buyer consolidation influences both hardware and recurring service revenue streams.
Pricing Analysis
Distributor margins for advanced surgical devices reflect the specialized training and logistical support required. The dominant pricing structure is a hybrid of capital equipment sales and subscription-based recurring revenue for software and services. Brand premium and the level of after-sales service differentiate pricing significantly. Pricing softness stems from increasing competition in the minimally invasive segment, with academic hospitals less price-sensitive for advanced robotic platforms compared to community hospitals.
Supply Chain Analysis
Specialized instrument manufacturing relies heavily on precision components sourced from Germany and Japan. Key inputs include high-definition optics, micro-electronics, and medical-grade polymers. Single-source vulnerability for these specialized components poses a structural risk to device availability. Distribution runs through a network of direct sales forces and specialized medical distributors, particularly for complex robotic systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thoracic surgery market functions as a stable compounder, driven by persistent demographic shifts like aging populations and the continuous evolution of surgical technologies. These forces ensure sustained demand for advanced medical devices and procedures.
For Market Incumbents: Acquire AI-powered surgical planning software firms to integrate automated lesion detection and precise preoperative mapping. This move counters the threat from niche innovators specializing in digital tools. Deepen channel control by investing in specialized training centers for robotic-assisted surgery, reinforcing brand loyalty against emerging competitors. Expand capabilities of existing endoscopic instrument portfolios to offer cost-effective alternatives to premium robotic platforms.
For New Entrants and Emerging Players: Enter via single-port instrumentation development for robotic platforms, targeting the less invasive procedure segment. Focus on markets like India and Brazil, where healthcare infrastructure is modernizing and demand for advanced surgical care is rising. Develop AI-powered image guidance systems for existing thoracoscopes, offering a cost-effective upgrade path for community hospitals. Prioritize NMPA approval pathways in China for novel devices to gain early market access.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software developers and instrument manufacturers focusing on single-port or AI-integrated solutions for the long term. These firms represent attractive acquisition targets for incumbents seeking to expand their technology ecosystems. Focus on companies with strong intellectual property in surgical robotics or advanced visualization. A critical signal to watch is the adoption rate of AI-powered diagnostic and planning tools in high-volume cancer centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Next-Gen Robotic Platforms | Advances surgical precision and expands procedural capabilities in academic hospitals. |
| Expand Subscription Services for Software | Creates predictable recurring revenue streams and deepens long-term hospital partnerships. |
| Pursue NMPA Accelerated Approvals | Secures early market entry and competitive advantage in China's growing healthcare sector. |
| Invest in Surgeon Training Programs | Addresses the training bottleneck and accelerates adoption of advanced robotic procedures. |
| Integrate AI for Surgical Planning | Enhances diagnostic accuracy and optimizes procedural workflow for thoracic surgeons. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. The analysis involved discussions with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary data sources included FDA filings, NMPA submissions, hospital procurement databases, and medical device company SEC 10-K filings. This approach ensured robust bottom-up and top-down triangulation of market data.
The forecast window was anchored to historical reference periods, ensuring consistency in trend identification across the modeling period. The analytical framework incorporated segmentation dimensions including procedure type, technology, end user, and device type. It also considered regional regulatory clusters. CAGRs were derived from a detailed analysis of market drivers and restraints, with specific forecast inputs including disease incidence rates and healthcare infrastructure investment levels.
Inputs from device manufacturers and hospital procurement databases were available through the study window; gaps in real-time surgical procedure volume data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancements. A small set of named triggers, including new reimbursement policies and major robotic platform launches, warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Pneumoperitoneum Market
Surgical Instruments
Endoscopic Closure Systems Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Asia Pacific Surgical Equipment Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market