
 Breast Retractors Market | 2026-2036
Breast Retractors Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Retractors Market Analytics
German surgical instrument manufacturers is repositioning toward premium reusable breast retractors as hospitals prioritize total cost of ownership over disposable alternatives. B. Braun Melsungen leverages its sterilization infrastructure to dominate European hospital procurement cycles. Integra LifeSciences anchors its competitive stance through deep specialization in reconstructive surgery workflows. Medtronic competes by extending its integrated operating room ecosystem into breast-specific retraction systems.
Breast retractors are mechanical devices designed to separate and hold breast tissue during surgical procedures, typically manufactured from stainless steel or medical-grade polymers with blade widths ranging from 20mm to 80mm to accommodate varying patient anatomies and procedural depths. Their primary commercial purpose centers on maintaining operative visibility while minimizing tissue trauma during oncological, cosmetic, and reconstructive breast interventions. Electric retractors command premium positioning due to integrated lighting and suction capabilities that reduce auxiliary staff demands during lengthy procedures. Disposable retractors capture volume in ambulatory surgical centers where reprocessing logistics constrain reusable instrument adoption. Stainless steel variants sustain margin pools through multi-year depreciation schedules that appeal to capital-constrained hospital systems.
FDA 510(k) clearance pathways and EU MDR Class I/IIa certification requirements govern breast retractor commercialization, with the latter imposing enhanced clinical evidence standards that extend time-to-market for novel designs. The EPA regulates sterilization effluent from reusable instrument reprocessing facilities, influencing material selection toward corrosion-resistant alloys. Stakeholders must monitor evolving CMS reimbursement thresholds for outpatient breast surgery, as site-of-service payment differentials directly determine whether hospitals or ambulatory centers drive procurement volume.
Market Dynamics
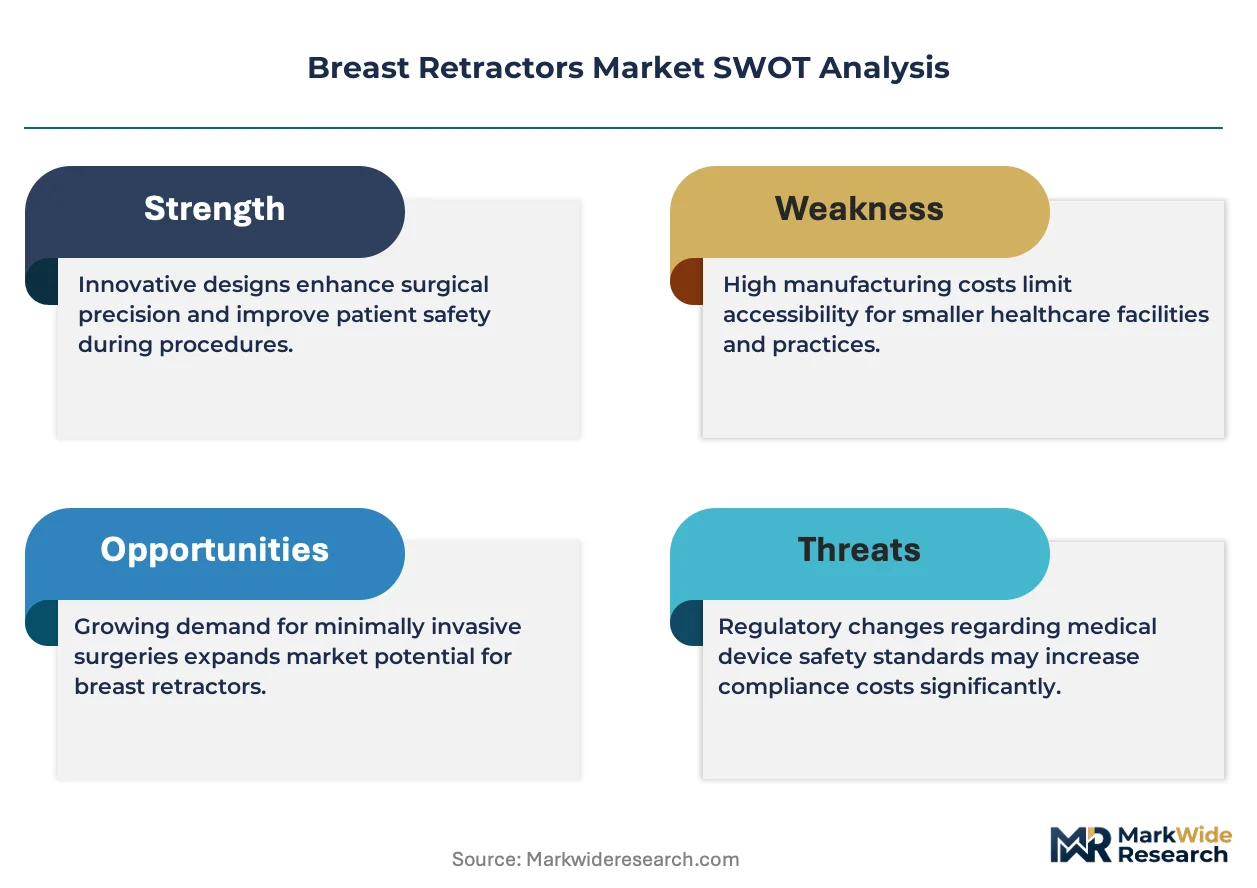
EU MDR Class I/IIa certification timelines are compressing competitive windows as sterilization infrastructure investments become the decisive barrier to market entry for reusable breast retractor portfolios.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS reimbursement thresholds for outpatient breast procedures are pulling procedure volume away from inpatient settings, creating dedicated demand for disposable retractor formats.
- EU MDR Compliance:Enhanced clinical evidence requirements for reusable instruments are advantaging manufacturers with established sterilization validation infrastructure.
- Stainless Steel Alloy Advances:Corrosion-resistant formulations meeting EPA sterilization effluent standards are extending instrument depreciation schedules and defending capital equipment margins.
Market Restraints
- Reprocessing Cost Escalation:EPA-regulated sterilization effluent treatment and labor-intensive validation protocols are inflating total cost of ownership for reusable retractor systems.
- Supply Concentration:German and Japanese precision instrument clusters control high-grade stainless steel forging capacity, creating geographic dependency for premium retractor sourcing.
- Polymer Performance Ceiling:Medical-grade polymers lack the thermal resilience for repeated autoclave cycles, limiting their penetration beyond single-use applications.
Strategic Opportunities
- Japan's Aging Surgical Workforce:Electric retractors with integrated lighting and suction are capturing preference as auxiliary staff constraints intensify in Tokyo and Osaka metropolitan surgical networks.
- Reconstructive Surgery Workflow Integration:Convergence of retractor systems with intraoperative imaging and navigation platforms is creating premium positioning for ecosystem-anchored suppliers.
- US Outpatient Migration:Site-of-service payment differentials under evolving CMS frameworks are accelerating ambulatory center procurement of procedure-matched disposable retractor kits.
Industry Challenges
- EU MDR Technical Documentation:Extended clinical evaluation report preparation and notified body queue times are delaying novel retractor design commercialization by 18-24 months.
- Sterilization Validation Talent:Scarce expertise in ethylene oxide and vaporized hydrogen peroxide cycle validation is constraining reprocessing facility expansion for reusable instrument portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Retractors Market |
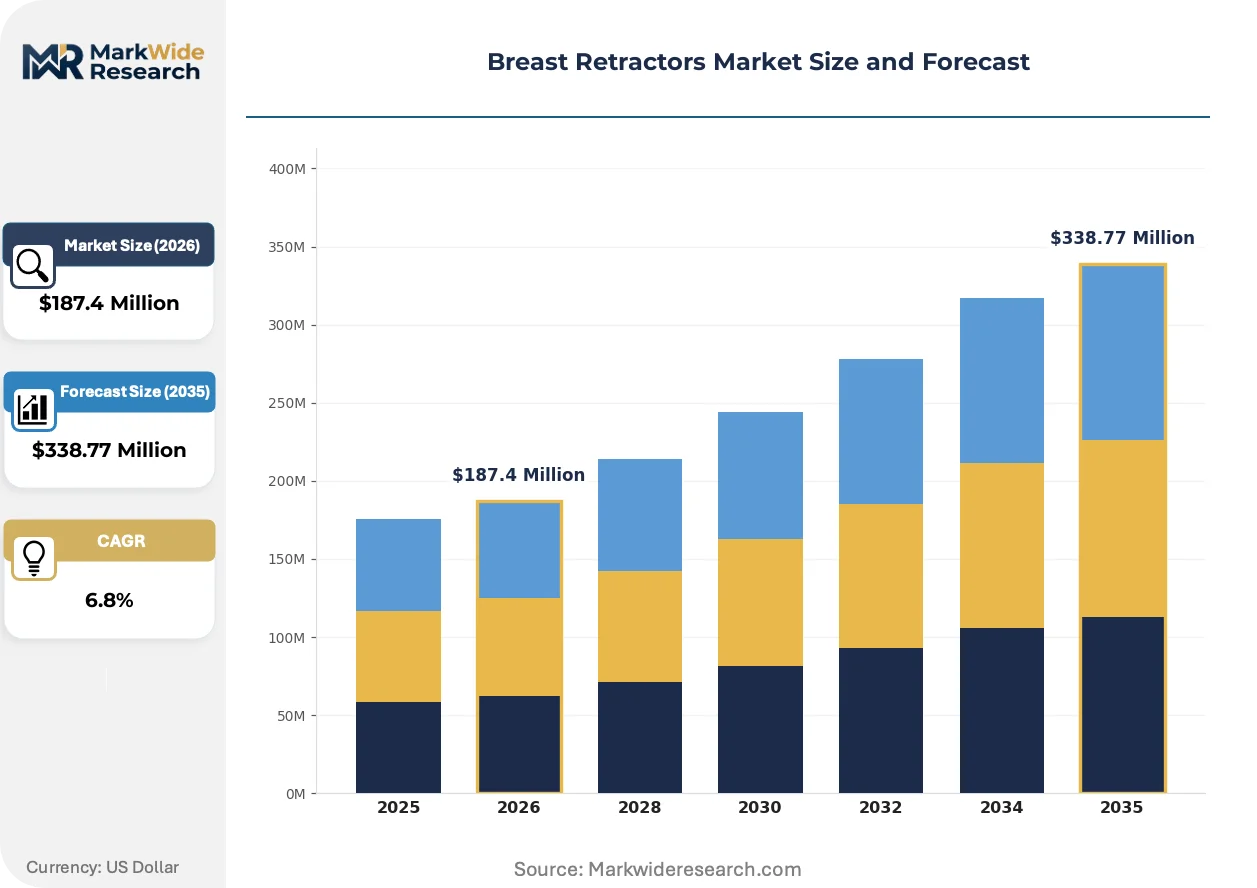
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Retractors, Electric Retractors, Disposable Retractors, Self-retaining Retractors End User: Hospitals, Outpatient Clinics, Surgical Centers, Ambulatory Surgical Centers Material: Stainless Steel, Plastic, Silicone, Aluminium Application: Oncology Surgery, Cosmetic Surgery, Reconstructive Surgery, General Surgery |
| Companies Covered | B. Braun Melsungen, Integra LifeSciences, Medtronic, CooperSurgical, Thompson Surgical, Accurate Surgical & Scientific Instruments, Hayden Medical, Mediflex, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Retractors Market Evolving Landscape
Active illumination and suction integration is redefining retractor value propositions as surgical teams prioritize operative field autonomy over auxiliary staff dependency. Material science advances and regulatory compliance automation are simultaneously reshaping product development roadmaps.
LED-integrated electric breast retractors are integrating photonic modules directly into blade assemblies, eliminating the need for external light sources and reducing shadow interference during deep tissue dissection. Academic medical centers in Germany and the United States are standardizing these systems for oncological breast procedures exceeding 90 minutes. The technology is integrating suction evacuation channels that maintain hemostasis without instrument exchange, compressing operative time and staff resource allocation.
EU MDR clinical evidence requirements are mandating biocompatibility testing and post-market surveillance documentation that exceeds prior Medical Device Directive standards. Manufacturers must now submit comprehensive clinical evaluation reports for reusable retractor modifications that previously qualified for self-certification. European hospital procurement committees are responding by consolidating supplier relationships toward established players with dedicated regulatory affairs infrastructure.
Hospital materials management departments are unbundling instrument reprocessing from capital acquisition decisions, treating sterilization as a discrete cost center with internal chargeback mechanisms. This accounting separation is elevating disposable retractor attractiveness in US ambulatory surgical centers where reprocessing infrastructure investment is prohibitive. The shift is most pronounced in Texas and Florida metropolitan markets where independent surgery center density exceeds national averages.
Breast Retractors Market Segmentation
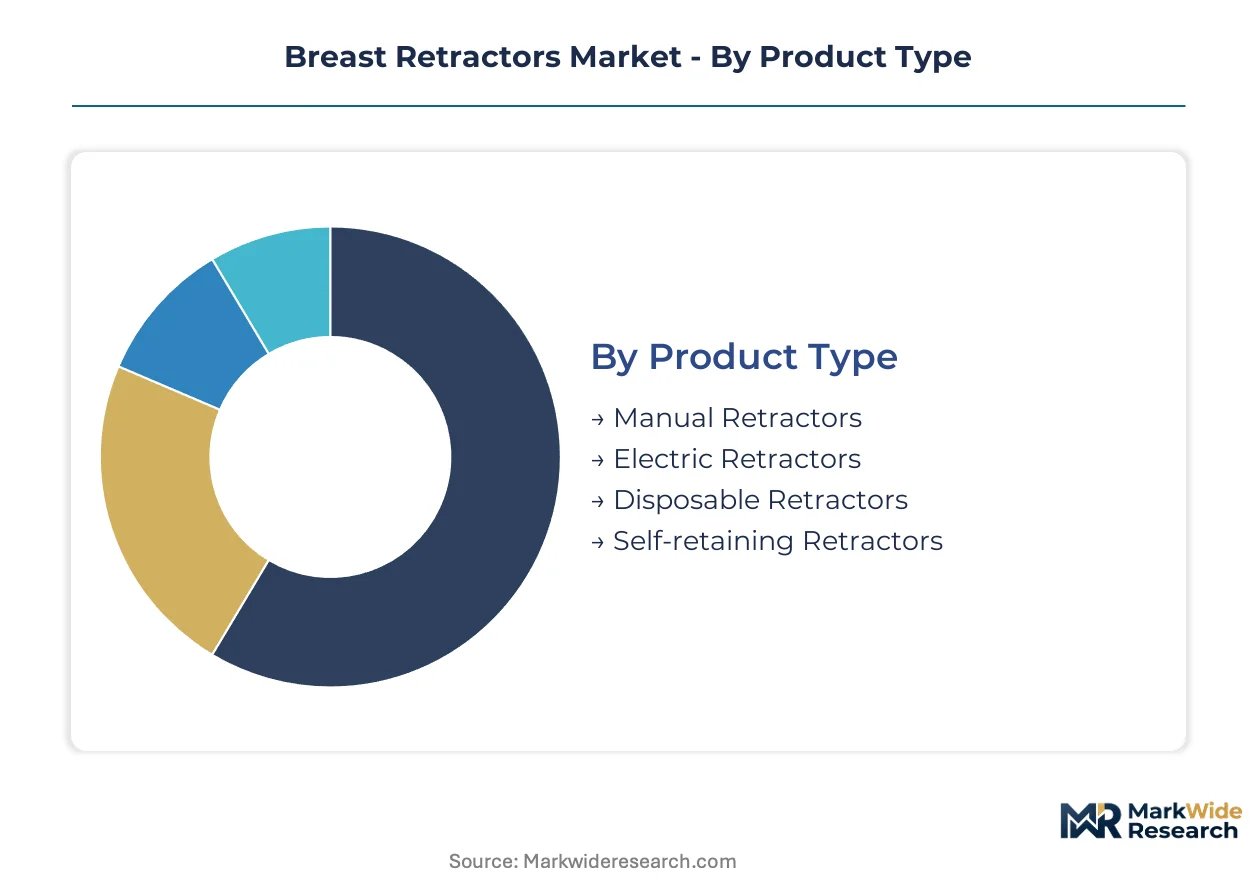
Segmentation in breast retractors reveals how procurement authority, sterilization economics, and procedural specialization fragment demand across customer types and material specifications. Manufacturers must align product portfolios with distinct capital cycles, regulatory burdens, and clinical workflows rather than pursuing uniform market penetration.
Product Type:
Supply concentration in German and Japanese precision forging clusters shapes competitive positioning across powered and mechanical retraction systems.
- Manual Retractors:Stainless steel instruments with fixed or adjustable blade angles dominate hospital capital equipment budgets through multi-year depreciation schedules. Demand concentrates in German university hospitals and Japanese metropolitan surgical networks where reprocessing infrastructure amortizes acquisition costs across high procedure volumes.
- Electric Retractors:Motorized systems integrate LED illumination and suction evacuation channels that reduce auxiliary staff dependency during extended oncological procedures. Tokyo and Osaka academic medical centers are standardizing these configurations as workforce constraints intensify.
- Disposable Retractors:Polymer-based single-use formats eliminate sterilization validation burdens for US ambulatory surgical centers in Texas and Florida where reprocessing infrastructure investment is prohibitive.
- Self-retaining Retractors:Ratchet-lock mechanisms maintain tissue separation without continuous manual holding, appealing to reconstructive surgery workflows requiring sustained exposure.
Manual retractors absorb the bulk of installed capacity; disposable retractors are expanding most quickly.
End User:
Site-of-service payment differentials under CMS frameworks are fragmenting procurement authority between capital-constrained hospitals and volume-focused outpatient facilities.
- Hospitals:Integrated delivery networks in Germany and the United States prioritize total cost of ownership, favoring reusable stainless steel systems with validated sterilization cycles. B. Braun Melsungen leverages hospital group purchasing organization relationships to defend installed base positions.
- Ambulatory Surgical Centers:Independent surgery centers in Texas and Florida metropolitan markets drive demand for procedure-matched disposable kits that eliminate reprocessing labor and EPA-regulated effluent compliance.
- Outpatient Clinics:Limited-procedure settings favor compact manual retractor sets with minimal storage and maintenance requirements.
- Surgical Centers:Multi-specialty facilities balance reusable and disposable inventories based on case mix and sterilization partner availability.
Hospitals retain the deepest retractor installed base; ambulatory surgical centers are climbing the fastest.
Material:
Corrosion-resistant alloy advances and polymer thermal limitations define the boundary between reusable capital equipment and single-use consumption models.
- Stainless Steel:Medical-grade 316L and 17-4 PH formulations withstand repeated autoclave cycles while meeting EPA sterilization effluent standards. German manufacturers command premium positioning through precision forging capabilities.
- Plastic:Medical-grade polymers including polycarbonate and polypropylene serve single-use applications where thermal resilience requirements are absent. Demand clusters in US outpatient migration markets.
- Silicone:Soft-tissue contact surfaces reduce trauma in cosmetic and reconstructive applications requiring gentle tissue manipulation.
- Aluminium:Lightweight alloys serve specialized pediatric and geriatric applications where instrument weight affects surgical ergonomics.
Stainless steel dominates capital procurement value; plastic formats are gaining share fastest.
Application:
Procedural complexity and duration determine whether electric integrated systems or manual instruments deliver superior economic returns.
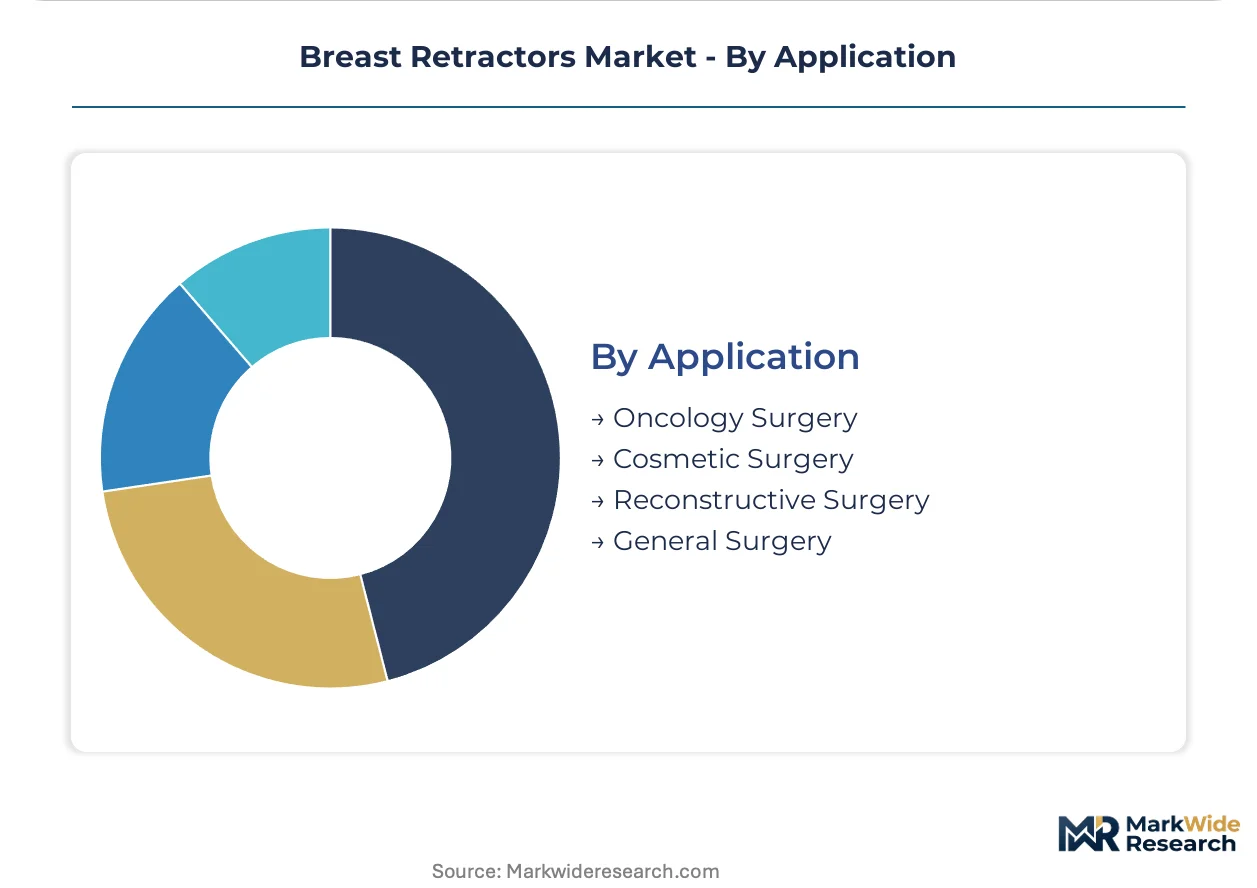
- Oncology Surgery:Extended tumor resection procedures exceeding 90 minutes favor electric retractors with integrated lighting and suction. German academic medical centers standardize these configurations for breast-conserving therapy workflows.
- Reconstructive Surgery:Microvascular anastomosis and flap inset procedures require sustained exposure without instrument exchange, driving preference for self-retaining and electric systems with stable positioning.
- Cosmetic Surgery:Shorter augmentation and reduction procedures accommodate manual retractor formats with lower capital intensity.
- General Surgery:Occasional breast procedures within broader surgical caseloads favor versatile manual instruments rather than specialized electric configurations.
Oncology surgery commands the highest equipment specification; reconstructive surgery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade stainless steel forging clusters in Solingen and Tuttlingen anchor European supply chains for precision surgical instruments. Japanese metropolitan surgical networks and German university hospitals sustain the deepest installed bases for reusable retractor systems. US ambulatory migration patterns are redrawing procurement geography toward Texas and Florida outpatient facilities.
United States
Site-of-service payment differentials under CMS frameworks are accelerating ambulatory surgical center expansion in Texas and Florida metropolitan markets. FDA 510(k) clearance pathways govern electric retractor commercialization with moderate clinical evidence requirements. Independent surgery centers in Dallas and Houston favor disposable polymer formats to bypass EPA-regulated sterilization infrastructure investment.
Germany
University hospitals in Berlin and Munich prioritize total cost of ownership calculations that favor reusable stainless steel systems with extended depreciation schedules. EU MDR Class I/IIa certification timelines are compressing competitive windows for novel retractor designs. The Tuttlingen precision instrument cluster dominates high-grade forging capacity for corrosion-resistant 316L and 17-4 PH alloy formulations.
Japan
Aging surgical workforces in Tokyo and Osaka academic medical centers are standardizing electric retractors with integrated LED illumination and suction evacuation. PMDA regulatory frameworks align with international standards while maintaining distinct documentation requirements for powered surgical instruments. The Nagoya medical device manufacturing corridor supplies precision-machined components for domestic and export markets.
United Kingdom
NHS procurement frameworks emphasize sterilization validation infrastructure as a decisive supplier qualification criterion. MHRA post-Brexit regulatory autonomy maintains EU MDR alignment while streamlining notified body interactions for established manufacturers. London teaching hospitals anchor reconstructive surgery volumes that sustain premium retractor specification demand.
India
CDSCO medical device regulations are tightening quality system requirements for imported and domestically manufactured surgical instruments. Maharashtra and Karnataka hospital networks are expanding breast surgery capacity through public-private partnership models. Mumbai-based distributors are building sterilization service partnerships to support reusable instrument adoption in tier-two cities.
Breast Retractors Market Competitive Landscape
Global majors compete with regional champions across sterilization infrastructure and regulatory compliance capabilities. The vendor base stratifies between integrated surgical instrument conglomerates and specialized retractor fabricators with deep category expertise. Three archetypes dominate: sterilization-anchored European hospital suppliers, electric-integrated system vendors targeting academic medical centers, and disposable-format specialists serving US outpatient migration. Competitive moves concentrate on M&A to acquire sterilization validation capabilities and strategic partnerships with ambulatory surgery center management companies.
Among diversified surgical instrument conglomerates, B. Braun Melsungen and Stryker occupy positions anchored by hospital group purchasing organization relationships and integrated sterilization service networks. Medtronic exemplifies the electric-integrated system archetype through its operating room ecosystem extension strategy. Integra LifeSciences represents specialization in reconstructive surgery workflows. CooperSurgical and Thompson Surgical sit within the premium manual instrument tier serving academic medical center preferences.
| Leading Market Players |
|---|
| B. Braun Melsungen |
| Integra LifeSciences |
| Medtronic |
| CooperSurgical |
| Thompson Surgical |
| Accurate Surgical & Scientific Instruments |
| Hayden Medical |
| Mediflex |
| Stryker |
| Others |
Value Network & Pricing Analysis
Electric-integrated versus manual-mechanical tier divergence manifests in divergent supply chain footprints and pricing power dynamics. Premium electric retractors bundle LED photonics and suction modules that anchor pricing through dedicated component sourcing from Nagoya and Tuttlingen precision clusters, while commodity manual instruments compete on corrosion-resistant alloy grades validated for EPA effluent compliance.
Pricing Analysis
Warranty and reprocessing service bundling separates premium stainless steel portfolios from unbundled disposable alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU MDR Class I/IIa versus self-certified manual instruments. Pricing pressure stems from ambulatory surgical center procurement committees demanding procedure-matched disposable kits with zero sterilization overhead. Hospital integrated delivery networks exhibit lowest price sensitivity due to total cost of ownership depreciation models, while independent Texas and Florida surgery centers drive commoditization of polymer formats.
Supply Chain Analysis
Regional distribution centers in Solingen, Tuttlingen, and Nagoya operate hub-and-spoke patterns serving hospital procurement cycles. High-grade stainless steel forging concentrates in Germany and Japan, with medical-grade 316L and 17-4 PH alloys drawing from specialized metallurgical suppliers. Single-source vulnerability runs through precision-machined LED photonic modules and suction evacuation channels. Distribution runs through sterilization service partnerships and GPO contract channels rather than direct-to-facility logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through sterilization validation talent scarcity, with ethylene oxide and vaporized hydrogen peroxide cycle expertise propping pricing for reusable instrument portfolios.
For Market Incumbents: Cement hospital GPO relationships through captive sterilization service networks that lock in multi-year depreciation schedules. Acquire sterilization validation capabilities in Tuttlingen and Nagoya corridors to defend against emerging electric-integrated system vendors. Prioritize EU MDR technical documentation infrastructure to compress notified body queue times for novel retractor designs. For New Entrants and Emerging Players: Begin with disposable polymer formats targeting Texas and Florida ambulatory surgical centers where reprocessing infrastructure investment is prohibitive. Capture white-space in reconstructive surgery workflow integration through partnerships with intraoperative imaging platform vendors. Pursue direct ASC management company contracts rather than hospital procurement committee channels. For Investors and Strategic Acquirers: Re-rating potential sits with sterilization-anchored European hospital suppliers given EU MDR compliance timelines compressing competitive windows. Long-term viability over the next decade hinges on regulatory affairs infrastructure depth rather than manufacturing scale alone. Monitor CMS site-of-service payment differential announcements as the decisive inflection signal for disposable versus reusable format mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Service Partnership | Captures hospital procurement cycles through bundled reprocessing validation under EPA effluent standards. |
| EU MDR Technical Documentation Investment | Compresses notified body queue times for novel retractor designs against competitor delays. |
| Electric System Workflow Integration | Aligns retractor platforms with intraoperative imaging vendors serving German academic medical centers. |
| ASC Management Company Contract | Bypasses hospital GPO concentration to access Texas and Florida outpatient volume directly. |
| Corrosion-Resistant Alloy R&D | Extends instrument depreciation schedules through 316L and 17-4 PH formulation advances meeting EPA standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this breast retractors analysis. Primary interviews with hospital purchasing committee directors, GPO contracts managers, biomedical engineers, and sterilization facility operators combined with FDA 510(k) clearance databases, EU MDR notified body documentation, and CMS reimbursement schedule records. Bottom-up procedure volume modeling and top-down manufacturer shipment triangulation validated segment-level outputs.
Data-stream reconciliation across electric retractor shipment records, stainless steel alloy import manifests, and ambulatory surgical center accreditation databases informed the analytical framework. Segmentation dimensions modeled include product type, end-user facility category, material specification, and procedural application across the projection horizon. CAGRs derived from installed base replacement cycles, outpatient migration patterns, and regulatory compliance cost trajectories. Forecast inputs incorporated PMDA powered surgical instrument documentation requirements and EPA sterilization effluent treatment cost escalations.
Underlying measurement precision varies by segment; electric retractor and disposable polymer categories carry tighter precision than manual stainless steel installed base estimates due to fragmented distributor reporting. Forecasts reflect documented assumptions regarding CMS reimbursement threshold evolution and EU MDR notified body capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
US Veterinary Surgical Instruments Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Japan General Surgical Devices Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Endometrial Ablation Market
Surgical Instruments
Surgical Hemostats Market