
 Endoscopic Closure Systems Market | 2026-2036
Endoscopic Closure Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscopic Closure Systems Market Foresight
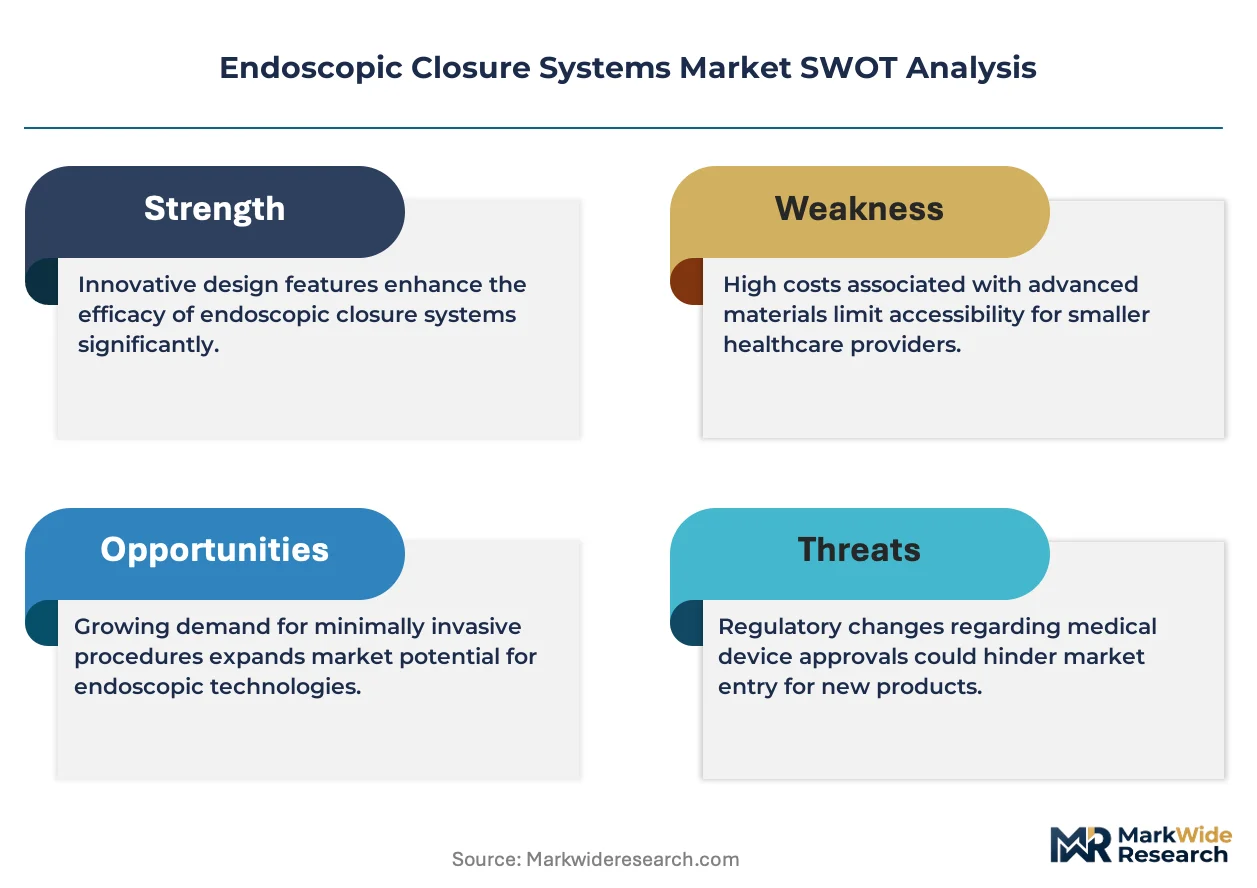
The FDA's 510(k) pathway revision for endoscopic surgical instruments is expanding documentation burdens for new entrants. Medtronic leverages its vertically integrated manufacturing network to sustain compliance cost advantages across multiple regulatory jurisdictions. Ovesco Endoscopy AG anchors its competitive position through specialized clip designs for complex luminal defects. Boston Scientific Corporation differentiates via broad portfolio breadth spanning suturing, clipping, and banding modalities.
Endoscopic closure systems comprise implantable and deployable devices designed to achieve hemostasis and tissue apposition during minimally invasive procedures, typically incorporating nitinol alloy construction with polyester or silicone coverings to ensure biocompatibility and mechanical stability at deployment diameters ranging from 8 mm to 16 mm. Their primary commercial purpose centers on reducing procedure time, minimizing patient recovery intervals, and avoiding conversion to open surgery following iatrogenic perforations or post-resection defects. Over-the-Scope Clips dominate current revenue pools due to established reimbursement codes and broad indication coverage across upper and lower GI applications. Endoscopic Suturing Devices represent the fastest-expanding category as bariatric revision procedures and endoscopic full-thickness resections gain clinical traction in academic medical centers.
The FDA enforces biocompatibility and sterilization validation standards under 21 CFR Part 820 quality system regulations, while the EU Medical Device Regulation mandates clinical evidence requirements and notified body oversight for Class IIa and above devices. Japan's PMDA imposes additional language-specific labeling and local clinical trial data expectations that shape market entry sequencing for Western manufacturers. Stakeholders must monitor evolving post-market surveillance requirements and health technology assessment methodologies as payers scrutinize cost-effectiveness relative to surgical alternatives.
Market Dynamics
The FDA's 510(k) pathway revision for endoscopic surgical instruments is compressing product launch timelines while simultaneously elevating documentation burdens for new entrants. This regulatory recalibration is forcing manufacturers to front-load clinical evidence generation and sterilization validation protocols before commercialization.
Growth Catalysts
- MDR Clinical Evidence Mandates:The EU Medical Device Regulation's tightened clinical data requirements for Class IIa and above devices is accelerating consolidation among notified bodies, favoring established manufacturers with robust post-market surveillance infrastructure.
- Bariatric Revision Procedures:Academic medical centers in Germany and the United States are expanding endoscopic suturing device utilization for post-surgical defect management, creating procedural volume anchors for advanced closure technologies.
- Nitinol Alloy Advancements:Enhanced shape-memory properties in nickel-titanium compositions are enabling larger deployment diameters with reduced tissue trauma, broadening indication coverage across complex luminal defects.
Market Restraints
- Notified Body Bottlenecks:EU MDR implementation has reduced the number of designated conformity assessment bodies by over half, extending certification timelines to 18-24 months for novel clip designs.
- Reimbursement Code Fragmentation:Inconsistent procedural coding between upper and lower gastrointestinal applications creates administrative friction for hospital billing departments, particularly in Japan where PMDA labeling requirements demand language-specific documentation.
- Silicone Supply Concentration:Biocompatible covering materials for clip construction depend on a limited supplier base concentrated in East Asian chemical manufacturing clusters, exposing producers to input volatility.
Strategic Opportunities
- India's Tertiary Care Expansion:Government-funded medical college hospital networks are installing advanced endoscopy suites, creating first-mover advantages for clip manufacturers establishing training partnerships with gastroenterology societies.
- Endoscopic Full-Thickness Resection:Hybrid procedures combining mucosal resection with immediate defect closure are generating demand for integrated suturing-clipping platforms in Japanese and German academic centers.
- Digital Health Integration:RFID-enabled clip tracking systems are converging with hospital inventory management platforms, enabling procedure-specific consumption analytics for value-based purchasing contracts.
Industry Challenges
- Interventional Gastroenterology Fellowship Gaps:Advanced endoscopic closure techniques require specialized training pathways that remain underdeveloped outside major metropolitan teaching hospitals, limiting addressable procedure volumes.
- Legacy Sterilization Infrastructure:Ethylene oxide sterilization capacity constraints following EPA emissions regulations are forcing manufacturers to validate alternative terminal sterilization methods, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscopic Closure Systems Market |
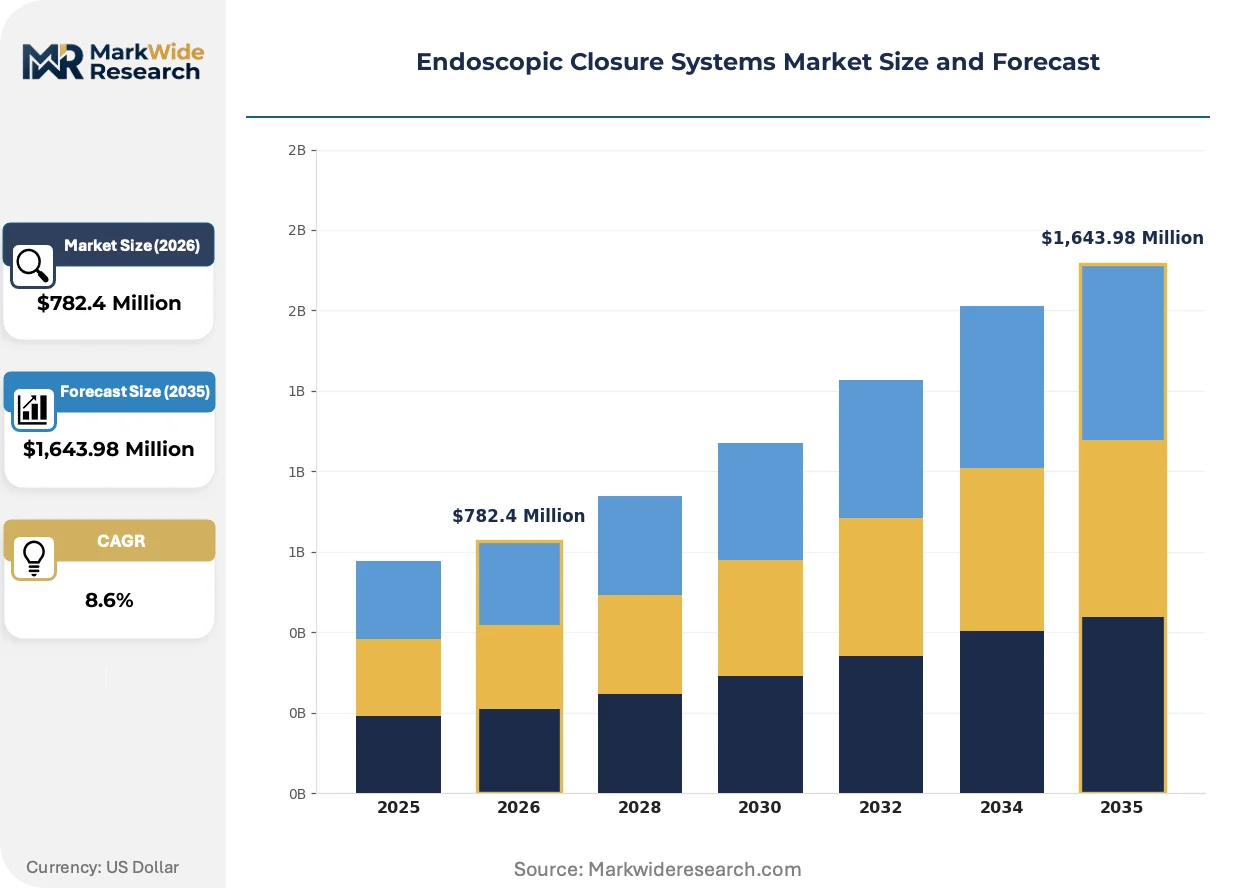
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,643.98 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
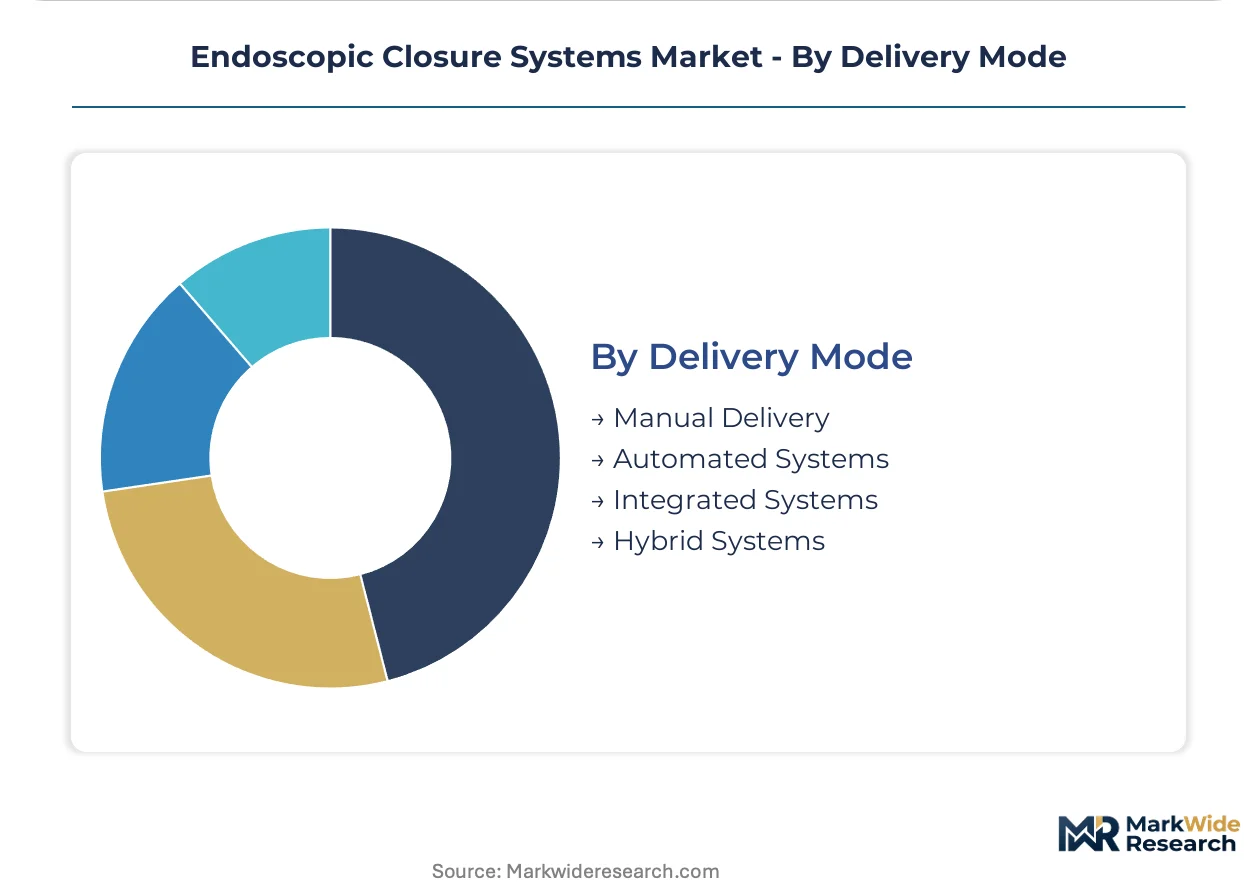
| Segmentation | Product Type: Over-the-Scope Clips, Endoscopic Suturing Devices, Banding Devices, Tacking Devices End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Gastrointestinal Procedures, Cardiovascular Procedures, Bariatric Surgery, Cancer Treatments Delivery Mode: Manual Delivery, Automated Systems, Integrated Systems, Hybrid Systems |
| Companies Covered | Medtronic, US Endoscopy, Ovesco Endoscopy AG, Apollo Endosurgery Inc., CooperSurgical Inc., Boston Scientific Corporation, Olympus Corporation, Steris, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscopic Closure Systems Market Shifts & Advancements
Active materials science and regulatory data requirements are reshaping competitive positioning in endoscopic closure. Manufacturers are pivoting from incremental clip design improvements toward integrated procedural ecosystems that capture value across the care continuum.
Shape-memory nitinol architectures with programmable deployment forces are expanding into complex anatomical locations previously requiring surgical intervention. Tertiary care centers in the United States and Germany are adopting these advanced configurations for duodenal and colonic defect management at accelerating rates. This technology expansion is compressing the addressable market for conventional surgical closures while elevating reimbursement scrutiny for endoscopic alternatives.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating systematic device performance tracking across implantable closure systems. Manufacturers must now maintain active registries documenting real-world outcomes, fundamentally altering cost structures for market participation. Smaller clip specialists without dedicated clinical affairs infrastructure face disproportionate compliance burdens relative to diversified portfolios.
Hospital procurement committees are consolidating vendor relationships around full-procedure contracts that bundle devices with technical training and outcome guarantees. This behavioral shift is displacing transactional purchasing through distributor networks, particularly in German hospital systems where procurement centralization has accelerated. The United States exhibits similar consolidation as integrated delivery networks standardize closure device formularies across multi-hospital systems.
Endoscopic Closure Systems Market Segmentation
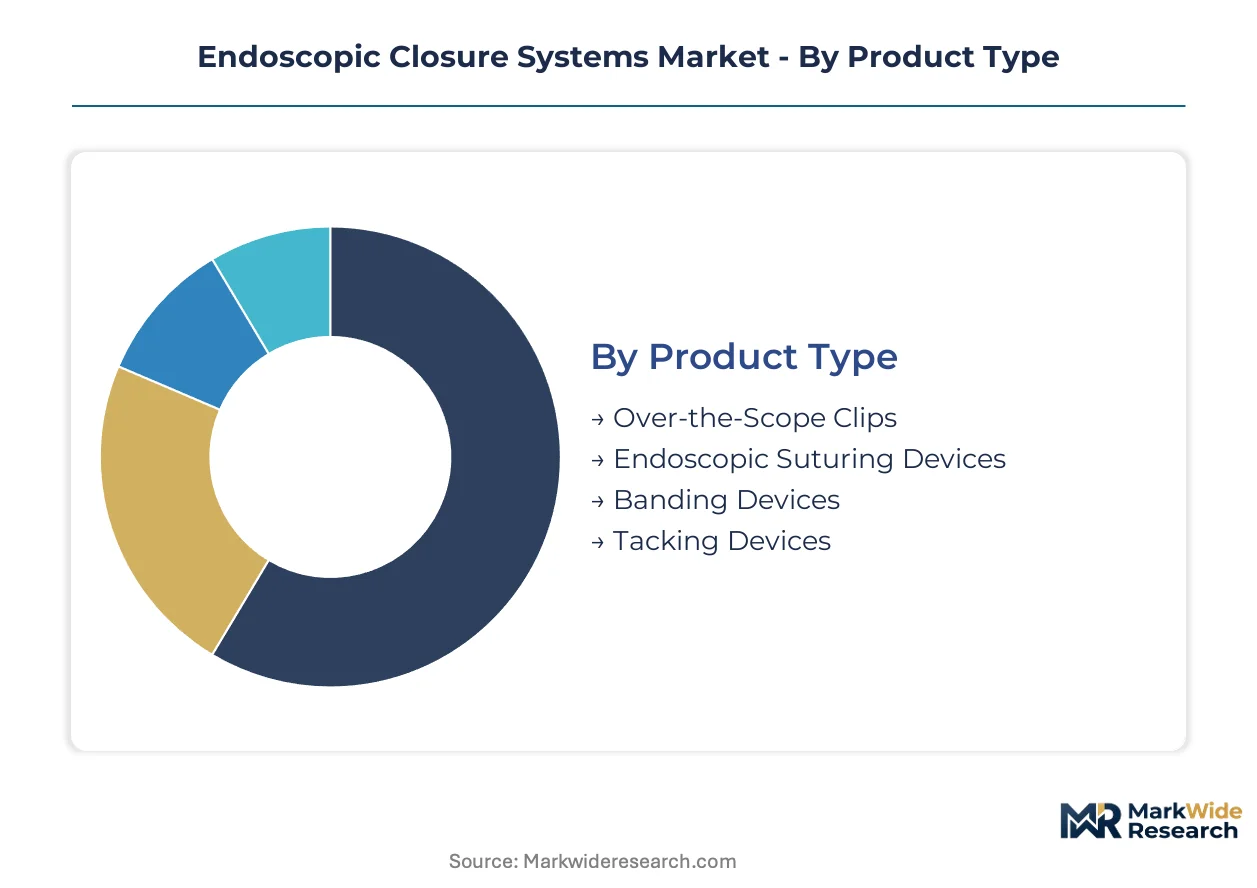
Endoscopic closure systems fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and technical training requirements. Product type concentration shapes manufacturing scale economies, while end-user configuration dictates sales force deployment and service bundling strategies.
Product Type:
Supply concentration in nitinol alloy processing and biocompatible covering materials favors manufacturers with captive metallurgy capabilities and long-term silicone supply agreements.
- Over-the-Scope Clips:Nitinol alloy construction with polyester or silicone coverings enables deployment diameters from 8 mm to 16 mm. Demand concentrates in United States tertiary care centers performing high volumes of upper and lower GI defect management, driven by established reimbursement codes and broad indication coverage.
- Endoscopic Suturing Devices:Mechanized needle drivers with braided suture delivery systems achieve full-thickness tissue apposition. German and United States academic medical centers anchor demand for bariatric revision procedures and endoscopic full-thickness resections, reflecting specialized training infrastructure availability.
- Banding Devices:Elastic ring applicators for variceal ligation and hemorrhoid management.
- Tacking Devices:Tissue anchors for mesh fixation and luminal wall stabilization.
Over-the-Scope Clips absorb the bulk of installed capacity; Endoscopic Suturing Devices are expanding most quickly.
End User:
Procurement centralization in hospital systems and integrated delivery networks is displacing transactional purchasing through distributor networks.
- Hospitals:Tertiary care centers with advanced endoscopy suites perform complex defect closures requiring immediate surgical backup. United States and German hospital systems drive volume through standardized formularies and value-based purchasing contracts.
- Ambulatory Surgical Centers:Lower-acuity GI procedures with same-day discharge protocols. United States freestanding ASC networks expand capacity for routine clip deployments as reimbursement shifts toward outpatient settings.
- Specialty Clinics:Gastroenterology-focused outpatient facilities with limited surgical backup.
- Research Institutions:Academic medical centers generating clinical evidence for novel indications and device iterations.
Hospitals command the dominant share of procedure volume; Ambulatory Surgical Centers are climbing the fastest as outpatient migration accelerates.
Application:
Procedure coding fragmentation between upper and lower gastrointestinal applications creates administrative friction that shapes product development priorities.
- Gastrointestinal Procedures:Iatrogenic perforation closure, post-resection defect management, and fistula sealing. Japanese and United States tertiary centers anchor demand for complex duodenal and colonic applications.
- Bariatric Surgery:Revision procedures addressing anastomotic leaks and staple line failures. German academic centers pioneer endoscopic suturing for post-surgical defect management.
- Cardiovascular Procedures:Vascular access site closure and cardiac structural defect management.
- Cancer Treatments:Defect closure following endoscopic mucosal resection and submucosal dissection.
Gastrointestinal Procedures capture the majority of device utilization; Bariatric Surgery is gaining share fastest as metabolic surgery volumes expand.
Delivery Mode:
Technology maturity gradients separate established manual platforms from emerging automated and integrated configurations requiring capital equipment investment.
- Manual Delivery:Hand-actuated deployment mechanisms with tactile feedback. Dominates current installed base due to lower capital requirements and broader physician familiarity.
- Automated Systems:Motorized deployment with programmable force modulation. Japanese and German academic centers pilot these platforms for complex anatomical locations.
- Integrated Systems:Device-endoscope coupling with imaging-guided deployment.
- Hybrid Systems:Combines manual control with automated force assistance.
Manual Delivery retains the largest installed base; Automated Systems are expanding most quickly as procedural complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Ireland and Puerto Rico concentrate endoscopic closure manufacturing through tax-advantaged structures. These zones attract nitinol alloy processing and sterile packaging operations from multinational producers seeking regulatory harmonization across FDA and EU jurisdictions.
United States
Tertiary care centers in Cleveland and Houston perform the highest volumes of complex GI defect closures requiring immediate surgical backup. FDA 510(k) pathway revisions are compressing product launch timelines while elevating documentation burdens for new clip designs. The Minneapolis-St. Paul corridor hosts concentrated manufacturing operations for nitinol-based deployment systems.
Germany
Academic medical centers in Berlin and Heidelberg anchor European demand for endoscopic suturing devices in bariatric revision procedures. EU MDR clinical evidence mandates are accelerating consolidation among notified bodies, favoring established manufacturers with post-market surveillance infrastructure. The Baden-Württemberg region specializes in precision metallurgy for shape-memory alloy components.
Japan
Tokyo and Osaka metropolitan areas concentrate advanced endoscopy suites performing duodenal and colonic defect management. PMDA imposes language-specific labeling and local clinical trial data expectations that shape market entry sequencing for Western manufacturers. The Kansai region hosts specialized training centers for interventional gastroenterology fellowship programs.
India
Government-funded medical college hospital networks in Maharashtra and Karnataka are installing advanced endoscopy suites with clip deployment capabilities. CDSCO regulatory pathways for Class IIa implantable devices require sterilization validation documentation aligned with ISO standards. Hyderabad's medical technology corridor is emerging as a hub for distributor training partnerships with gastroenterology societies.
Endoscopic Closure Systems Market Competitive Landscape
United States producers anchor the premium-tier segment through vertically integrated manufacturing networks; German specialists hold positions in precision metallurgy and clinical evidence generation. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with multi-modality portfolios, specialized clip designers focused on complex luminal defects, and endoscopic platform manufacturers bundling closure devices with imaging systems. Consolidation is accelerating through strategic partnerships between alloy processors and device assemblers, alongside geographic expansion into India's tertiary care networks.
Within the diversified conglomerate tier, Medtronic and Boston Scientific Corporation exemplify scale-driven positioning through captive supply chains and multi-jurisdictional compliance infrastructure. Ovesco Endoscopy AG occupies a specialized niche representing the focused-technology archetype, while Olympus Corporation anchors the integrated-platform approach combining endoscope manufacturing with closure device compatibility. These three patterns illustrate how competitive positioning fragments across manufacturing depth, clinical specialization, and system integration vectors.
| Leading Market Players |
|---|
| Medtronic |
| US Endoscopy |
| Ovesco Endoscopy AG |
| Apollo Endosurgery Inc. |
| CooperSurgical Inc. |
| Boston Scientific Corporation |
| Olympus Corporation |
| Steris |
| Abbott |
| Others |
Supply & Pricing Matrix
Nitinol alloy ingot costs cascade through three pricing tiers as the raw material moves from East Asian metallurgy processors to finished clip manufacturers serving hospital procurement committees. German precision forgers and United States medical device assemblers capture margin premiums through captive heat-treatment capabilities, while spot-market buyers of standard-grade alloys face compressed margins in economy-tier consumables.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to expedited orders from United States tertiary care centers facing urgent surgical backup requirements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, ISO 13485 certification tier, and bundled technical training offerings. Cost compression in economy-tier clips is intensifying because South Korean and Chinese producers are expanding nitinol wire-drawing capacity. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize performance specifications over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume demand from integrated delivery networks, while specialized distributors serve mid-tier ambulatory facilities with fragmented purchasing authority. Nitinol alloy supply concentrates in China, Germany, and the United States, with biocompatible silicone covering materials drawing from Japanese and South Korean chemical manufacturers. Single-source vulnerability in ethylene oxide sterilization capacity following EPA emissions regulations threatens terminal processing timelines. Distribution runs through GPO-negotiated contracts for United States hospital systems and centralized procurement consortia in German state hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's clinical evidence mandates and post-market surveillance requirements erect substantial compliance moats that favor incumbents with dedicated regulatory affairs infrastructure over capital-constrained challengers.
For Market Incumbents: Cement market position by acquiring notified body relationships and post-market registry capabilities before MDR consolidation eliminates accessible certification pathways. Backward integration into nitinol wire-drawing insulates against East Asian supply volatility while capturing margin from precision metallurgy. Threat from automated suturing platforms demands accelerated R&D in integrated device-endoscope coupling technologies. For New Entrants and Emerging Players: Distributor training partnerships with Indian gastroenterology societies offer de-risked market entry through government-funded medical college hospital networks. White-space targets include Hyderabad and Bangalore tertiary care corridors where procurement centralization remains incomplete. Go-to-market execution should emphasize disposable clip economics against reusable surgical alternatives in cost-sensitive settings. For Investors and Strategic Acquirers: Notified body designation withdrawals exceeding fifty percent under MDR implementation is the leading indicator that regulatory infrastructure scarcity will concentrate value in compliant manufacturing assets. Five-to-ten year viability favors specialized clip designers with proprietary deployment geometries over undifferentiated commodity producers. Signal to monitor: German academic center procurement committee consolidation around full-procedure outcome guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Secures certification pathway access as designation scarcity intensifies competitive exclusion. |
| Nitinol Metallurgy Backward Integration | Captures margin from shape-memory alloy processing while reducing East Asian supply exposure. |
| Indian Training Partnership Network | Establishes first-mover position in government-funded tertiary care expansion corridors. |
| Automated Deployment Platform Development | Addresses German and Japanese academic center demand for complex anatomical applications. |
| RFID-Enabled Inventory Integration | Aligns with United States hospital value-based purchasing contract analytics requirements. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, PMDA approval databases, and hospital procurement records, complemented by interviews with interventional gastroenterologists, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists at notified bodies. Secondary sources included CMS Medicare reimbursement data, German hospital procurement consortium disclosures, and nitinol alloy trade flow statistics. Bottom-up procedure volume estimates were triangulated against top-down manufacturer revenue assessments across product categories.
Cross-referencing historical adoption curves with expert panel input on bariatric revision procedure growth shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed product type, end-user configuration, application indication, and delivery mode complexity. CAGRs were derived from elasticity-adjusted price-volume relationships and reimbursement pathway evolution. Industry-specific inputs included fellowship training pipeline capacity and sterilization infrastructure regulatory constraints.
Caveats apply where FDA guidance revisions, notified body capacity crunches, or ethylene oxide sterilization alternatives validation could materially shift the outlook. Forecasts embed assumptions regarding MDR implementation pacing and outpatient migration acceleration that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Global Powered Surgical Instruments Market