
 Artificial Cartilage Implant Market | 2026-2036
Artificial Cartilage Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Cartilage Implant Market Outlook
Aftermarket service revenue is fragmenting across the artificial cartilage implant landscape as manufacturers diversify beyond hardware sales into patient monitoring and revision surgery protocols. Stryker Corporation anchors its position through integrated surgical navigation systems that lock in hospital purchasing cycles. Johnson & Johnson leverages its DePuy Synthes channel to sustain high-touch orthopedic service relationships. Anika Therapeutics specializes in hyaluronic acid-based interventions, occupying a distinct niche between pharmaceutical and device paradigms.
Artificial cartilage implants are biocompatible constructs engineered to restore load-bearing function in synovial joints, typically fabricated from hydrogel matrices, collagen scaffolds, or nanocomposite polymers with compressive moduli matching native tissue. These devices serve primarily to delay or avoid total joint arthroplasty in younger, active patients with focal chondral defects. Hydrogel formulations lead current commercial adoption due to established injection protocols and reversible clinical outcomes, while nanocomposite platforms represent the fastest-growing category as tribological performance improves. Surgical implants command premium pricing over intra-articular injection delivery modes, reflecting longer procedure times and specialized instrumentation requirements.
FDA breakthrough device pathways and EMA adaptive licensing frameworks compress development timelines for novel cartilage restoration technologies, though post-market surveillance obligations intensify. ISO 10993 biocompatibility standards and MDR clinical evidence requirements in Europe shape material selection and predicate device strategies for market entrants. Stakeholders must weigh regulatory capital requirements against the narrowing window for first-mover advantage in nanocomposite platforms.
Market Dynamics
Biomimetic scaffold technologies are compressing the clinical validation timeline for cartilage restoration, forcing manufacturers to front-load regulatory capital while reimbursement frameworks lag behind technical proof points.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated review pathway compresses time-to-market for novel hydrogel matrices, rewarding predicate device strategies with earlier revenue capture.
- Aging Demographics in Germany and Japan:Focal chondral defect prevalence among patients over 55 expands the addressable surgical population beyond traditional sports medicine indications.
- Nanocomposite Polymer Maturation:Improved tribological performance in load-bearing applications is opening knee repair protocols previously reserved for total arthroplasty.
Market Restraints
- Hyaluronic Acid Price Volatility:Pharmaceutical-grade polymer supply concentrates among three European chemical suppliers, exposing implant manufacturers to input cost squeezes.
- MDR Clinical Evidence Requirements:Europe's tightened post-market surveillance obligations extend recertification cycles and inflate regulatory maintenance budgets.
- Autologous Chondrocyte Implantation:Cell-based therapies retain strong clinician loyalty in academic medical centers, creating substitution pressure on synthetic scaffold adoption.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives reduce import duty exposure for multinational implant producers establishing local assembly.
- Remote Patient Monitoring Integration:Post-operative gait analysis via wearable sensors creates recurring revenue streams beyond hardware sale.
- EMA Adaptive Pathways:Conditional approval frameworks enable earlier commercialization in orphan indications, building real-world evidence for broader label expansion.
Industry Challenges
- Bioengineer Talent Scarcity:Tissue engineering PhD pipelines fail to match manufacturer hiring velocity, inflating R&D salary benchmarks.
- ISO 10993 Testing Backlogs:Biocompatibility certification queues at notified bodies delay product launches by 8-14 months.
- Legacy EMR Integration:Surgical navigation systems require costly interoperability workarounds with hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Cartilage Implant Market |
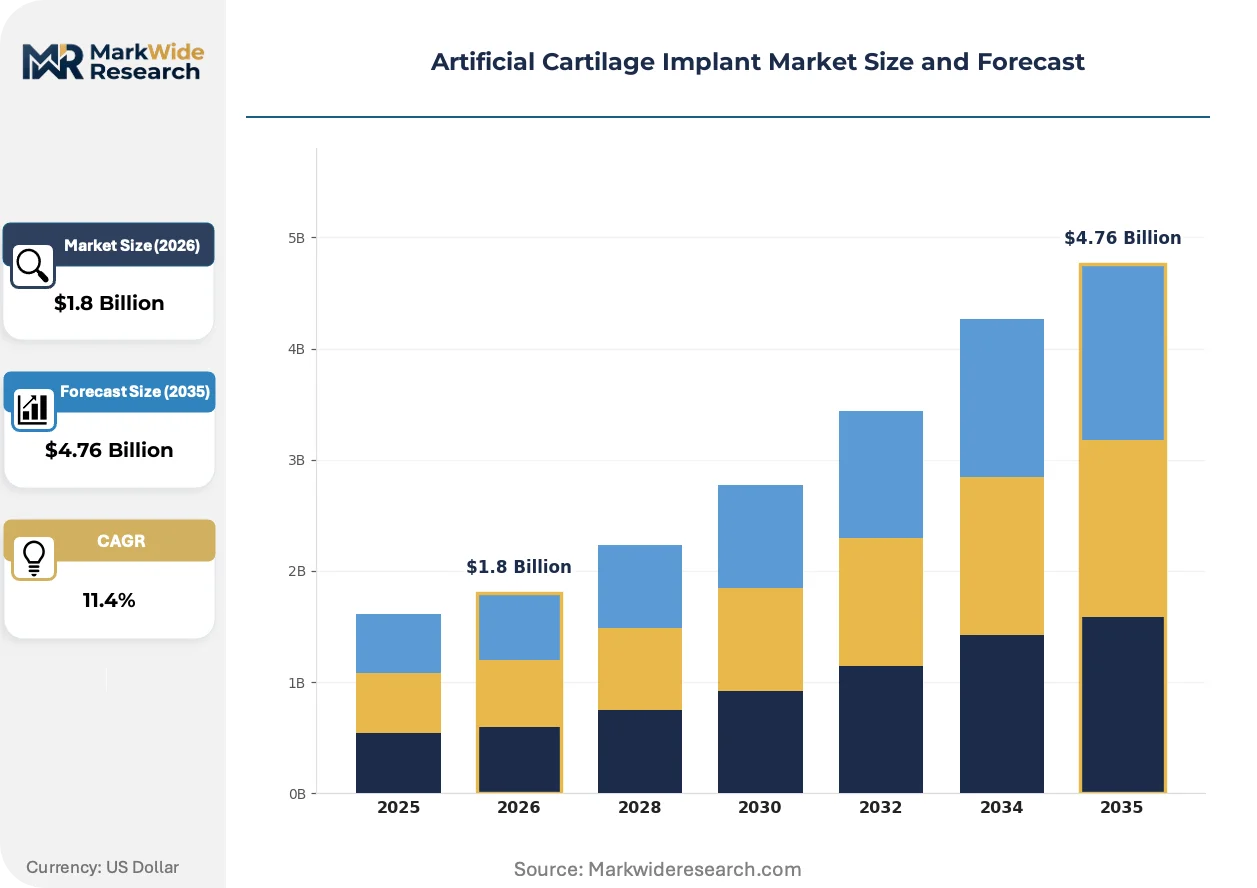
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogel, Biomimetic, Nanocomposite, Bioceramic End User: Surgery Centers, Orthopedic Clinics, Hospitals, Rehabilitation Centers Application: Knee Repair, Ankle Repair, Hip Replacement, Cartilage Regeneration Delivery Mode: Intra-articular Injection, Surgical Implants, Articular Surface Replacement, Augmentation |
| Companies Covered | Johnson & Johnson, Medtronic, Smith & Nephew, Stryker Corporation, Zimmer Biomet, Anika Therapeutics, Azellon Cell Therapeutics, Cartiva Inc., Vericel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Cartilage Implant Market Strategic Shifts
Cartilage restoration technologies are pivoting from reversible palliative interventions toward durable structural replacements, compressing the boundary between pharmaceutical and device regulatory paradigms.
Injectable hydrogel formulations are migrating from temporary viscosupplementation toward permanent load-bearing scaffolds. Academic medical centers in the United States are piloting intraoperative mixing protocols that customize crosslink density to defect geometry. This technology is migrating from outpatient clinic administration into operating room workflows, extending procedure reimbursement codes and capturing margin previously allocated to pharmaceutical distributors.
Europe's MDR implementation has intensified clinical evidence requirements for permanent implant classifications. Manufacturers now face mandatory post-market clinical follow-up studies that extend surveillance obligations to 15 years. Nanocomposite platforms with predicate device pathways in the United States confront de novo classification hurdles in Europe, fragmenting global launch sequencing.
Hospital purchasing committees are unbundling after-sales service from hardware procurement, forcing manufacturers to price navigation systems and revision protocols separately. Orthopedic service contracts now compete with independent surgical coaching networks for post-implant patient management. This shift is most visible in German university hospitals, where value analysis teams scrutinize total cost of ownership across 10-year implant lifecycles.
Artificial Cartilage Implant Market Segmentation
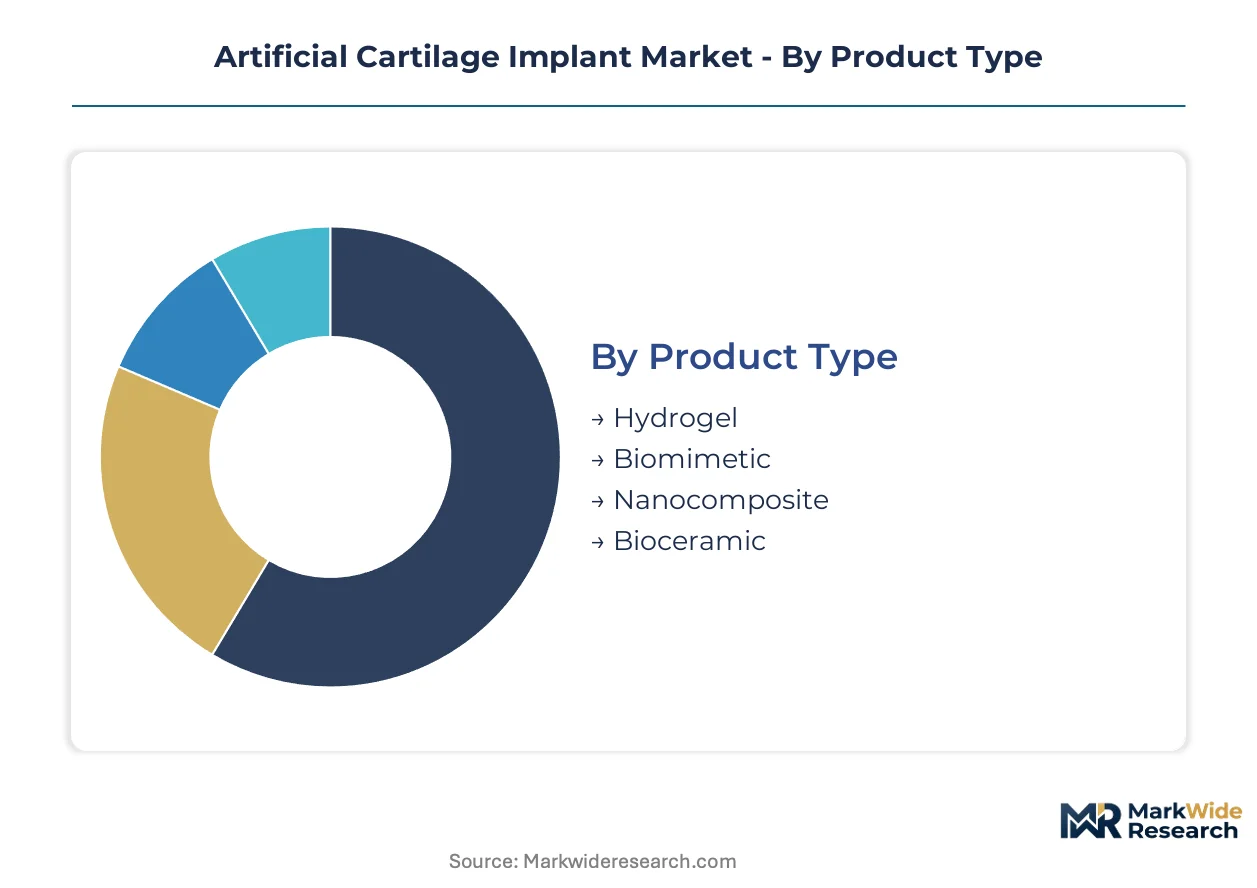
Segmentation in artificial cartilage implants reveals divergent commercial rhythms across material platforms and care settings. Product lifecycle velocity varies dramatically between reversible hydrogel injections and permanent nanocomposite reconstructions, forcing manufacturers to balance inventory turns against margin depth.
Product Type:
Hydrogel formulations turn inventory fastest through outpatient injection protocols, while nanocomposite platforms lock capital longest due to surgical scheduling and custom fabrication cycles.
- Hydrogel:Crosslinked polymer networks deliver reversible viscosupplementation through minimally invasive injection. United States outpatient clinics favor these for rapid patient throughput and established reimbursement codes. Cycle times compress to days between procurement and revenue recognition.
- Nanocomposite:Reinforced polymer matrices with tribological properties matching native cartilage enable permanent load-bearing function. German university hospitals drive adoption for younger patients seeking to defer total arthroplasty. Manufacturing lead times extend to weeks due to precision molding requirements.
- Biomimetic:Collagen-based scaffolds with hierarchical pore architecture guide host cell infiltration. Academic medical centers in Japan pilot these for focal defect repair.
- Bioceramic:Hydroxyapatite-reinforced constructs target osteochondral defects requiring subchondral bone integration. Limited adoption concentrates in revision surgery protocols.
Hydrogel dominates installed base. Nanocomposite is where expansion concentrates.
End User:
Procurement authority fragments across facility types, with hospitals commanding capital equipment budgets while surgery centers optimize per-procedure economics.
- Hospitals:Integrated health systems in the United States consolidate purchasing through value analysis committees, bundling implants with navigation systems and revision protocols. Capital allocation cycles span 18-24 months.
- Surgery Centers:Ambulatory facilities prioritize disposable delivery systems and rapid room turnover. German outpatient clinics drive demand for pre-mixed hydrogel syringes.
- Orthopedic Clinics:Specialist practices concentrate initial diagnostics and injection therapies, referring complex reconstructions to hospital partners.
- Rehabilitation Centers:Post-acute facilities influence implant selection through outcomes data collection and patient-reported outcome measures.
Hospitals anchor volume concentration. Surgery centers are climbing the fastest.
Application:
Anatomical site determines regulatory pathway complexity and predicate device availability, with knee applications offering the clearest clinical evidence base.
- Knee Repair:Focal chondral defect treatment in the medial femoral condyle represents the most validated indication. United States sports medicine practices drive volume through arthroscopic delivery techniques.
- Hip Replacement:Acetabular cartilage restoration faces anatomical access challenges and higher mechanical loading requirements. Japanese orthopedic surgeons pioneer modified surgical approaches.
- Ankle Repair:Talus lesions in younger patients create demand for durable small-joint solutions. Limited predicate devices slow regulatory timelines.
- Cartilage Regeneration:Broad indication category spanning multiple anatomical sites with variable clinical endpoints.
Knee repair dominates installed base. Hip replacement is where expansion concentrates.
Delivery Mode:
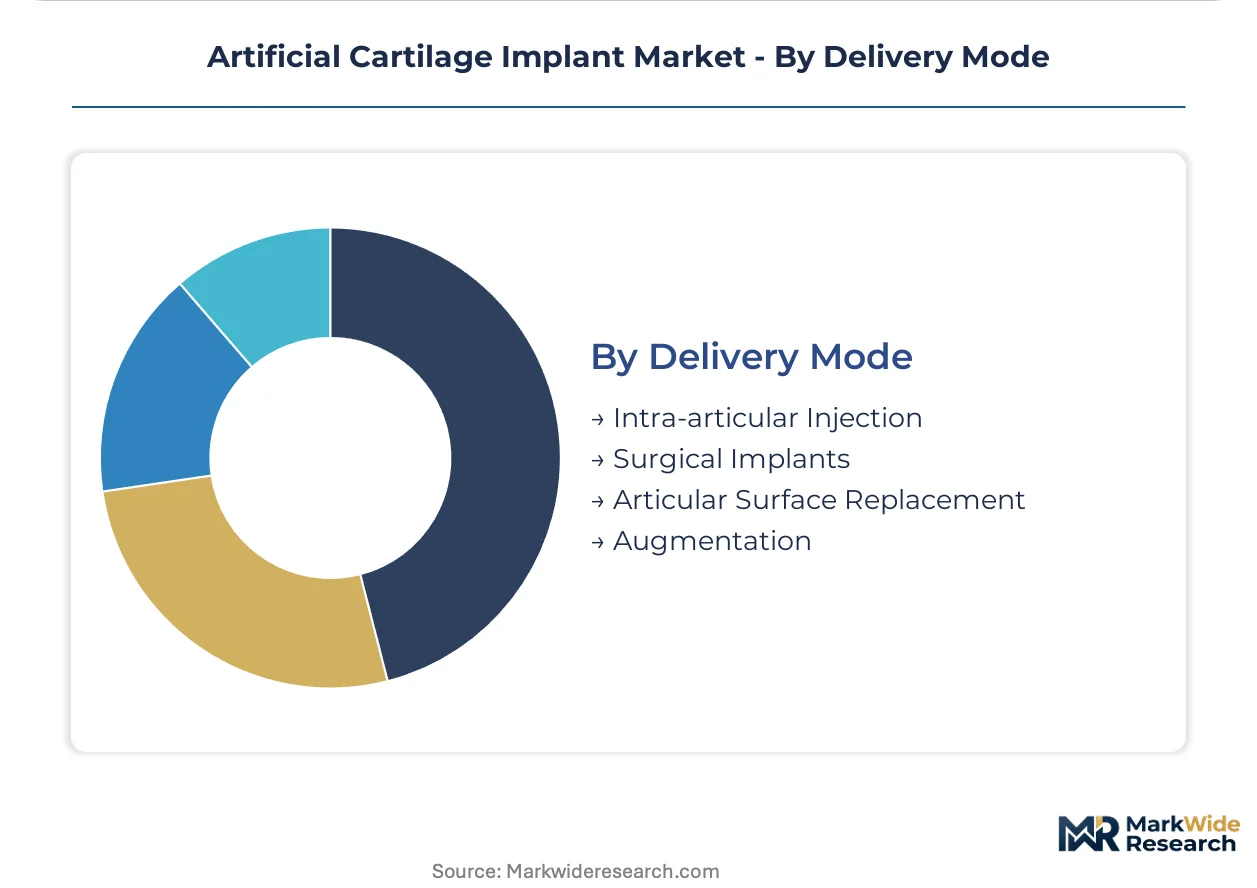
Revenue recognition timing splits between immediate pharmaceutical-style injection sales and deferred surgical implant billing with instrumentation attach rates.
- Surgical Implants:Permanent scaffold placement with specialized instrumentation commands premium pricing. German hospital purchasing committees evaluate total cost of ownership across implant lifecycle.
- Intra-articular Injection:Office-based administration with reversible outcomes aligns with pharmaceutical distribution models. United States clinics favor quarterly injection schedules.
- Articular Surface Replacement:Resurfacing procedures for large defects require custom-milled implants. Manufacturing lead times extend surgical scheduling.
- Augmentation:Adjunctive procedures combining multiple material platforms for complex defect geometries.
Intra-articular injection dominates installed base. Surgical implants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies, with German hospital purchasing committees demanding total-cost-of-ownership transparency while United States outpatient clinics prioritize rapid reimbursement capture over unit economics.
United States
FDA breakthrough device designations compress clinical trial timelines for hydrogel matrices, attracting venture capital into Boston and San Diego biotech clusters. Sports medicine practices in the Southeast drive injection volume through established CPT codes. The Mayo Clinic in Rochester anchors multicenter trials for nanocomposite platforms.
Germany
EMA adaptive pathways enable conditional approval for orphan cartilage indications, though MDR post-market surveillance extends obligations to 15 years. University hospitals in Bavaria and North Rhine-Westphalia unbundle service contracts from hardware procurement. The Berlin-Brandenburg region concentrates biomaterials R&D through Fraunhofer Institute partnerships.
Japan
PMDA Sakigake designation accelerates priority review for novel scaffolds, with METI funding regenerative medicine manufacturing infrastructure. Aging demographics in Kansai and Chubu expand the surgical population beyond traditional sports medicine. Osaka-based orthopedic surgeons pioneer modified approaches for hip restoration.
India
PLI scheme incentives for medical devices reduce import duty exposure for multinational producers establishing local assembly in Maharashtra and Gujarat. CDSCO streamlined pathways compress regulatory timelines for Class C implants. Hyderabad's medical device cluster attracts contract manufacturing for hydrogel formulations.
United Kingdom
NICE technology appraisals condition reimbursement on patient-reported outcome measures, favoring implants with demonstrated 10-year durability. London teaching hospitals concentrate revision surgery protocols for complex defect geometries. The Oxford-Cambridge arc anchors academic spinouts in biomimetic scaffold development.
Artificial Cartilage Implant Market Competitive Environment
Capability concentration sits with mid-cap specialists commanding tissue engineering expertise; scale advantage sits with diversified orthopedic conglomerates leveraging integrated surgical navigation ecosystems. The market structures around three tiers: diversified multinationals with hospital purchasing lock-in, mid-cap device specialists with predicate device strategies, and cell therapy platforms competing for academic medical center loyalty. Dominant competitive moves include backward integration into hyaluronic acid supply chains and technology licensing partnerships with academic research hospitals.
Within the diversified multinational tier, Johnson & Johnson and Stryker Corporation occupy positions defined by channel breadth and surgical system integration. Anika Therapeutics exemplifies the mid-cap specialist archetype, bridging pharmaceutical and device paradigms through hyaluronic acid-based interventions. Vericel Corporation anchors the cell therapy vector, representing autologous chondrocyte platforms that retain clinician loyalty in academic settings.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Smith & Nephew |
| Stryker Corporation |
| Zimmer Biomet |
| Anika Therapeutics |
| Azellon Cell Therapeutics |
| Cartiva Inc. |
| Vericel Corporation |
| Others |
Value Chain & Pricing Dynamics
European pharmaceutical-grade hyaluronic acid supply concentrates among three chemical suppliers in Germany and France, anchoring margin capture in downstream hydrogel formulations while exposing implant manufacturers to input cost squeezes that reshape procurement strategies across United States outpatient clinics and German university hospitals.
Pricing Analysis
After-sales service contracts for surgical navigation systems and revision protocols now drive lifetime value, displacing upfront hardware margins as hospital purchasing committees unbundle procurement. Three-tier pricing structure across premium nanocomposite platforms, standard hydrogel formulations, and economy injection therapies reflects ISO 10993 certification tiers and customization depth. Cost compression in hyaluronic acid feedstocks is intensifying because polymer supply bottlenecks, while ambulatory surgery centers exhibit highest price sensitivity and integrated United States health systems least.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for hydrogel precursor procurement, easing working capital strain for mid-cap specialists. Manufacturing concentrates in Germany for precision nanocomposite molding, the United States for hydrogel formulation, and India for contract assembly under PLI incentives. The chain draws from collagen isolates, synthetic polymer resins, and hydroxyapatite ceramics as core inputs. Single-source vulnerability in European hyaluronic acid supply creates structural exposure. Distribution runs through orthopedic GPOs in the United States and direct hospital contracting in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where surgical navigation ecosystems are locking in hospital purchasing cycles, with interoperability between implant hardware and post-operative monitoring software determining competitive viability across the next decade.
For Market Incumbents: Entrench hospital system relationships by deepening backward integration into hyaluronic acid supply chains and embedding FDA breakthrough pathway expertise into regulatory affairs teams. Cell therapy platforms threaten synthetic scaffold adoption in academic medical centers; defend through exclusive GPO contracts and integrated navigation system bundles that raise switching costs.
For New Entrants and Emerging Players: Build out remote patient monitoring capabilities for post-operative gait analysis, capturing recurring revenue streams beyond hardware sale. India's PLI scheme for medical devices offers the most penetrable geography, with CDSCO streamlined pathways compressing regulatory timelines. Target contract manufacturing partnerships with Hyderabad's medical device cluster as the go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap device specialists with predicate device strategies and established ISO 10993 certification, positioned for nanocomposite platform expansion. Long-term viability hinges on navigating the narrowing window for first-mover advantage before MDR post-market surveillance obligations mature. Watch EMA adaptive pathway approvals as the signal for inflection toward broader label expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review compresses time-to-market for novel hydrogel matrices in United States sports medicine. |
| CE Marking Pathway under MDR | European clinical evidence requirements extend surveillance obligations to 15 years for permanent implants. |
| Hospital System Partnership | Integrated purchasing committees bundle navigation systems with revision protocols across German university hospitals. |
| Software Companion Development | Wearable sensor integration for gait analysis creates recurring revenue beyond initial hardware sale. |
| Reimbursement Strategy | NICE technology appraisals in the United Kingdom condition coverage on 10-year durability data. |
Study Parameters
A spread of perspectives from orthopedic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions, validated against FDA 510(k) filings, EMA submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up segmentation modeling triangulated with top-down macroeconomic indicators anchored volume and value estimates.
Demand-supply balance framing across the analysis window integrated procedure volume forecasts, implant adoption curves, and material platform substitution dynamics. Segmentation dimensions modeled include material technology, delivery mode, end-user facility type, anatomical application, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical procedure data and reimbursement trajectory assumptions, with nanocomposite tribological performance improvements and MDR compliance cost inflation as key forecast inputs.
Stress conditions across hyaluronic acid price volatility, MDR recertification timeline extensions, and autologous chondrocyte therapy substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions and baseline projections. Macroeconomic contraction, regulatory pathway disruption, or step-change in cell therapy efficacy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Near Vision Devices Market
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Global Medical Grade Coating Market
Medical Devices
C-Arms Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Anti-Aging Devices Market
Medical Devices
Conduction Vaporizers Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Endodontic Files Market
Medical Devices
Next-Generation Neurofeedback Device Market