
 Minimally Invasive Thoracic Surgery Market | 2026-2036
Minimally Invasive Thoracic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Thoracic Surgery Market Intelligence
Project finance and equipment leasing for robotic surgical suites is tilting competitive dynamics toward capital-rich health systems and consolidated hospital networks. Intuitive Surgical leverages its installed base of da Vinci systems to sustain recurring instrument revenue. Medtronic competes through integrated surgical ecosystems that combine navigation with energy devices. Johnson & Johnson anchors its position via specialized suturing platforms and advanced stapling technologies.
Minimally invasive thoracic surgery encompasses procedures performed through small incisions using video-assisted or robotic platforms, typically employing 5-12 mm ports with high-definition imaging and articulated instruments to access the pleural cavity, mediastinum, and pulmonary structures without sternotomy or thoracotomy. Its primary purpose is to reduce perioperative trauma, shorten hospital stays, and enable faster recovery for lung resection, biopsy, and esophageal procedures. Robotic systems command premium positioning due to capital intensity and specialized training requirements, while video-assisted thoracoscopic surgery retains volume leadership across cost-sensitive hospital segments. Energy devices represent the fastest-expanding product category as bipolar and ultrasonic platforms displace conventional mechanical dissection in lobectomy and pleurodesis workflows.
FDA 510(k) and premarket approval pathways govern robotic system commercialization in the United States, while EU MDR and CE marking requirements impose strengthened clinical evidence standards for thoracoscopic instruments across European markets. Japan's PMDA oversees pharmaceutical and medical device agency clearances that shape market entry timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement coding for robotic-assisted procedures and anticipate how health technology assessment bodies will value long-term patient outcomes against upfront capital expenditures.
Market Dynamics
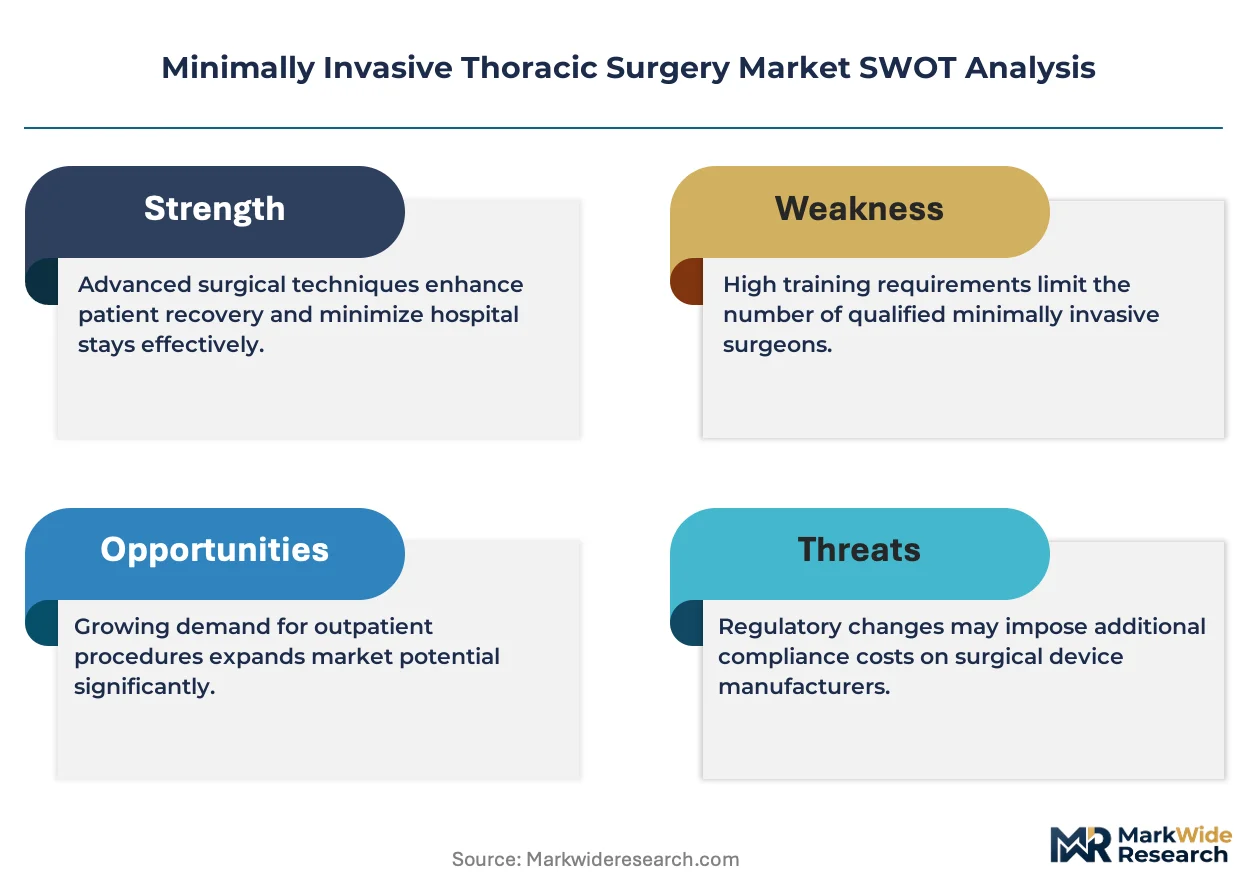
Hospital capital allocation committees are prioritizing robotic thoracic platforms over conventional video-assisted systems, creating a bifurcated procurement landscape where reimbursement adequacy determines technology tier selection across integrated delivery networks.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearances for surgical staplers and energy devices are compressing time-to-market for instrument manufacturers targeting US hospital systems.
- Japan's PMDA reimbursement expansion:National health insurance coverage for robotic-assisted lobectomy procedures is expanding addressable procedure volumes in tertiary medical centers.
- Single-port thoracoscopic platforms:Reduced intercostal trauma from uniportal approaches is driving adoption in early-stage lung cancer resections among academic medical centers.
Market Restraints
- Capital intensity barriers:Robotic system acquisition costs exceeding $2 million per suite restrict deployment to consolidated health systems with access to tax-exempt bond financing.
- EU MDR clinical evidence requirements:Strengthened post-market surveillance obligations for thoracoscopic instruments are extending certification timelines and compliance expenditures.
- Specialized surgeon training pipelines:Proctoring requirements and case volume thresholds for robotic credentialing create bottlenecks in expanding qualified operator pools.
Strategic Opportunities
- German outpatient thoracic surgery centers:Ambulatory surgical facility licensing reforms are enabling same-day discharge protocols for pleural biopsy and wedge resection procedures.
- Artificial intelligence-integrated imaging:Real-time nodule detection algorithms combined with 4K fluorescence visualization are creating differentiated platform positioning.
- India's Ayushman Bharat coverage expansion:Government-sponsored insurance schemes for cancer surgery are opening reimbursement pathways for video-assisted thoracoscopic procedures in tier-2 cities.
Industry Challenges
- Robotic system integration complexity:Operating room retrofit requirements for da Vinci Xi installations demand HVAC upgrades, structural reinforcements, and sterile supply workflow reconfiguration.
- Instrument sterilization standardization:Reprocessing protocol variations across hospital systems create compliance audit risks and potential FDA warning letter exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Thoracic Surgery Market |
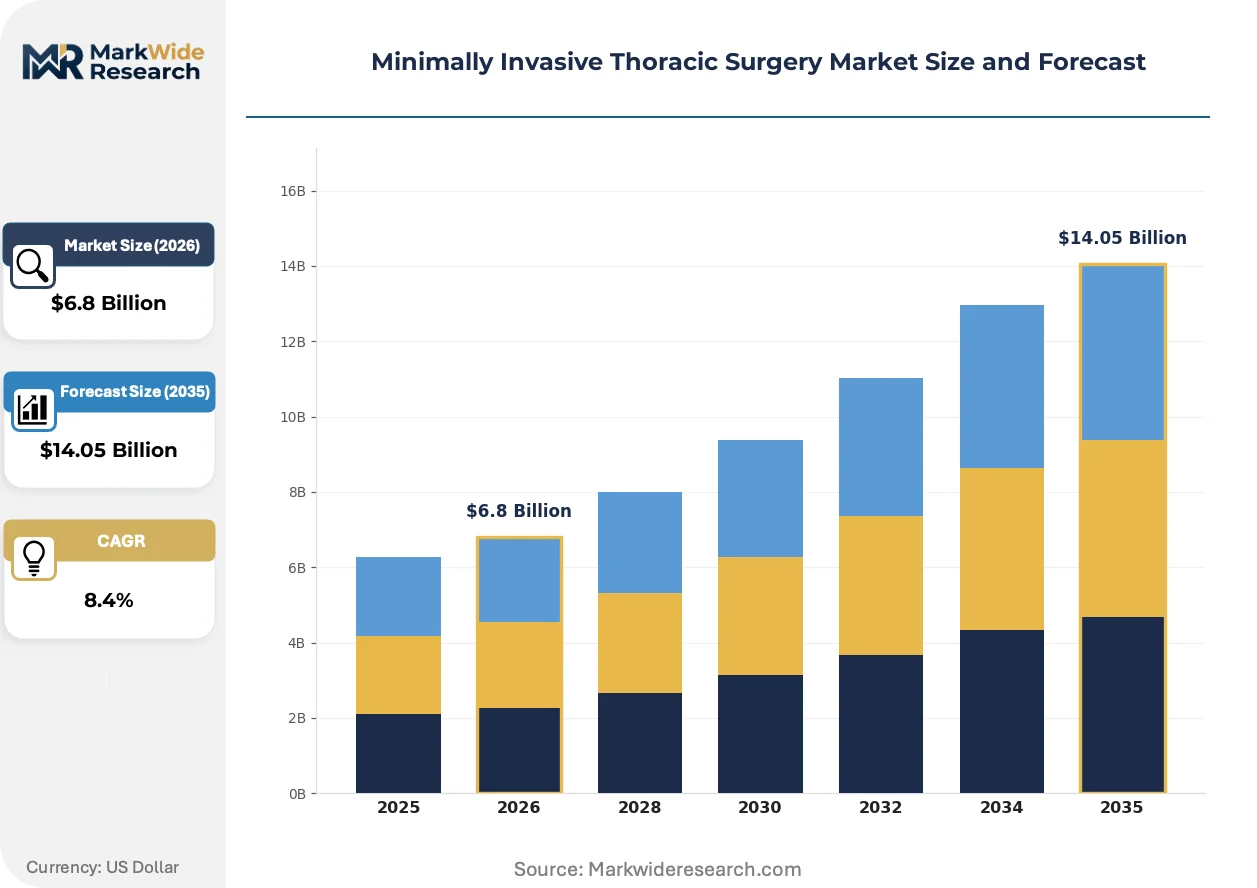
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thoracoscopic Instruments, Energy Devices, Robotic Systems, Suturing Devices End User: Hospitals, Surgical Centers, Academic Institutions, Specialty Clinics Technology: Video-Assisted Thoracoscopic Surgery, Robotic-Assisted Surgery, Minimally Invasive Techniques, Endoscopic Procedures Procedure Type: Lung Biopsy, Lobectomy, Pleurodesis, Esophagectomy |
| Companies Covered | Intuitive Surgical, Johnson & Johnson, Medtronic, Stryker, Olympus Corporation, Karl Storz, CONMED Corporation, Cook Group, Richard Wolf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Thoracic Surgery Market Strategic Shifts & Innovations
Digital twin technology is virtualizing preoperative planning workflows, enabling patient-specific anatomical modeling that reduces intraoperative conversion rates to open thoracotomy.
Haptic feedback systems are virtualizing the tactile sensation of tissue manipulation for robotic platforms, addressing the primary limitation cited by thoracic surgeons transitioning from open procedures. Academic medical centers in the United States are piloting these interfaces at a measured pace, with residency programs integrating force-feedback training modules. The technology is virtualizing the skill acquisition curve, compressing the learning plateau for complex mediastinal dissection.
EU MDR Article 10 clinical evaluation requirements are mandating systematic literature reviews and post-market clinical follow-up for thoracoscopic staplers, forcing manufacturers to rebuild technical documentation portfolios. The regulation is elevating barriers for mid-tier instrument suppliers lacking dedicated regulatory affairs infrastructure. German notified bodies are experiencing backlog-induced delays, pushing commercial launch timelines for novel energy devices into 2026-2027 windows.
Hospital procurement committees are consolidating vendor relationships through integrated sourcing agreements that bundle robotic systems, instruments, and service contracts. Independent community hospitals are losing negotiating leverage as group purchasing organizations centralize thoracic surgery capital expenditures. This concentration is most visible in the southeastern United States, where regional health systems are standardizing on single-platform deployments to achieve volume-based instrument pricing.
Minimally Invasive Thoracic Surgery Market Segmentation
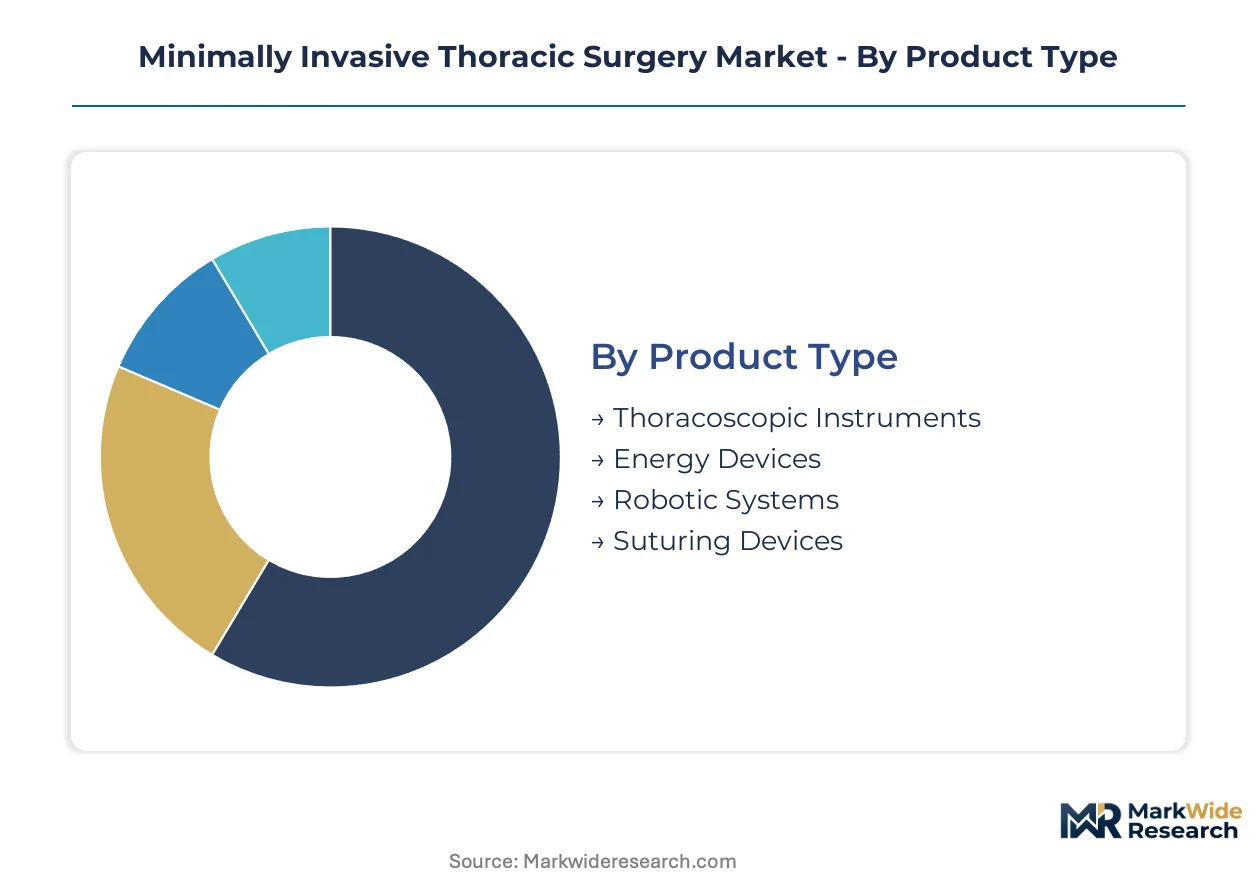
Segmentation in minimally invasive thoracic surgery reveals how capital allocation, clinical workflow complexity, and reimbursement economics fragment procurement decisions across health systems. Understanding these divides exposes where instrument manufacturers can command premium positioning versus competing on operational efficiency.
Product Type:
Cost tier stratification separates capital-intensive robotic platforms from disposable instrument categories with recurring revenue models.
- Robotic Systems:Integrated surgical platforms combining patient-side carts with surgeon consoles and vision stacks. Demand concentrates in consolidated US hospital networks where IRS tax-exempt bond financing enables $2 million suite acquisitions.
- Energy Devices:Bipolar and ultrasonic platforms for vessel sealing and tissue dissection. German academic medical centers are displacing mechanical staplers in lobectomy workflows, driving fastest category expansion.
- Thoracoscopic Instruments:Graspers, dissectors, and clip appliers for video-assisted procedures. Indian tier-2 hospitals under Ayushman Bharat procurement constraints favor reusable titanium instrumentation.
- Suturing Devices:Powered and manual stapling systems for parenchymal closure. Japanese PMDA reimbursement coding distinguishes between manual and powered variants in national health insurance claims.
Robotic Systems commands the established base. The steepest expansion runs through Energy Devices.
End User:
Customer type determines purchasing authority complexity, from centralized capital committees to individual surgeon preference cards.
- Hospitals:Integrated delivery networks with robotic credentialing programs and structured proctoring requirements. US southeastern health systems are standardizing on single-platform deployments through group purchasing organization consolidation.
- Surgical Centers:Ambulatory facilities licensed for same-day thoracic procedures. German outpatient center licensing reforms are expanding addressable volumes for pleural biopsy and wedge resection.
- Academic Institutions:Teaching hospitals with residency programs and research mandates. Pilot programs for haptic feedback training modules are concentrating at US academic medical centers with NIH funding access.
- Specialty Clinics:Focused thoracic practices with direct-to-employer contracting. These entities lack negotiating leverage for robotic system procurement and rely on hospital affiliate access.
Hospitals anchor volume concentration. Surgical Centers are gaining share fastest as ambulatory licensing expands.
Technology:
Maturity curves separate established video-assisted techniques from emerging robotic platforms with steeper learning gradients.
- Video-Assisted Thoracoscopic Surgery:Conventional multiport approaches with high-definition imaging and rigid instrumentation. Retains procedure volume leadership across cost-sensitive segments in India and Southeast Asia.
- Robotic-Assisted Surgery:Telemanipulation platforms with wristed instruments and 3D visualization. Japan's PMDA expanded national health insurance coverage for robotic lobectomy, accelerating tertiary center adoption.
- Minimally Invasive Techniques:Uniportal and needlescopic approaches reducing intercostal trauma. Single-port platforms are expanding in early-stage lung cancer resections at US academic centers.
- Endoscopic Procedures:Flexible bronchoscopic and mediastinoscopic interventions. Diagnostic applications dominate, with therapeutic expansion constrained by instrument diameter limitations.
Video-Assisted Thoracoscopic Surgery holds the installed base. Robotic-Assisted Surgery is climbing the fastest as reimbursement frameworks mature.
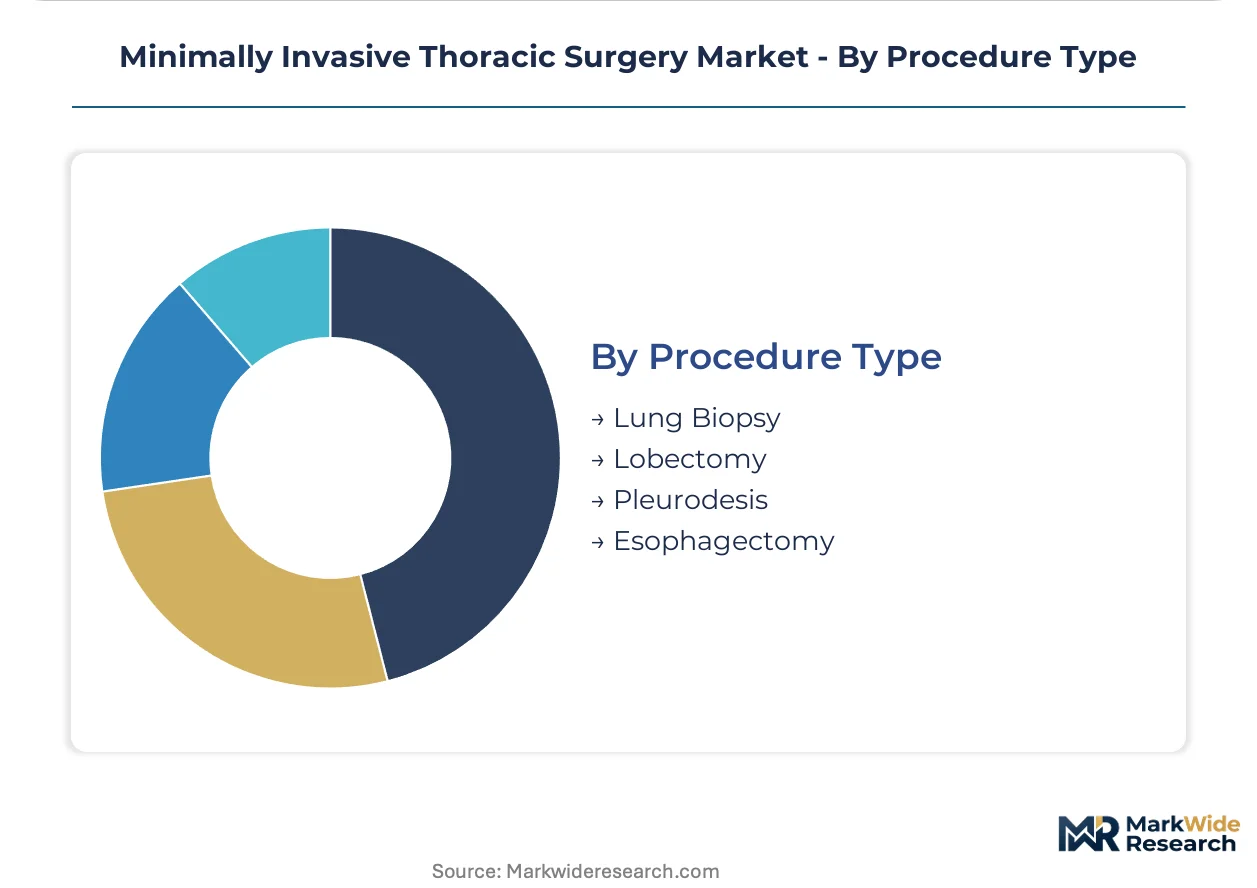
Procedure Type:
Application complexity ranges from diagnostic biopsies to multi-hour oncologic resections with divergent instrument consumption profiles.
- Lobectomy:Anatomic lung resection requiring hilar dissection and staple line reinforcement. Energy device utilization is displacing mechanical techniques in German and US academic workflows.
- Lung Biopsy:Tissue acquisition for histopathologic diagnosis. Outpatient migration is concentrating volume at ambulatory surgical centers with rapid on-site pathology evaluation.
- Pleurodesis:Pleural symphysis procedures for recurrent effusion or pneumothorax. Talc poudrage and mechanical abrasion techniques vary by surgeon training background.
- Esophagectomy:Complex foregut resection with intrathoracic anastomosis. Robotic platforms are reducing conversion rates to open thoracotomy at high-volume centers.
Lobectomy dominates procedural economics. Lung Biopsy is expanding most quickly with ambulatory site migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA reimbursement expansion for robotic-assisted lobectomy procedures is redirecting hospital capital toward integrated surgical platforms. Germany's EU MDR implementation timelines are compressing market entry windows for thoracoscopic instrument manufacturers. India's Ayushman Bharat coverage schemes are unlocking video-assisted procedure volumes in tier-2 urban centers.
United States
IRS tax-exempt bond financing enables consolidated health systems to acquire robotic suites exceeding $2 million per installation. FDA 510(k) pathway streamlining accelerates clearances for surgical staplers and energy devices targeting hospital procurement committees. Southeastern integrated delivery networks concentrate single-platform standardization efforts through group purchasing organization consolidation.
Germany
Ambulatory surgical facility licensing reforms enable same-day discharge protocols for pleural biopsy and wedge resection procedures. EU MDR Article 10 clinical evaluation requirements mandate systematic literature reviews for thoracoscopic staplers, extending certification timelines. Notified body backlogs push commercial launch windows for novel energy devices into 2026-2027 periods at academic medical centers in Bavaria and North Rhine-Westphalia.
Japan
National health insurance coverage expansion for robotic-assisted lobectomy procedures accelerates tertiary medical center adoption. PMDA oversight shapes market entry timelines for foreign thoracoscopic instrument manufacturers. Tokyo and Osaka academic hospitals concentrate proctoring programs and case volume thresholds for robotic credentialing pipelines.
India
Government-sponsored Ayushman Bharat insurance schemes for cancer surgery open reimbursement pathways for video-assisted thoracoscopic procedures. CDSCO regulatory frameworks govern medical device commercialization timelines for multinational manufacturers. Tier-2 cities in Maharashtra and Karnataka concentrate cost-sensitive hospital procurement favoring reusable titanium instrumentation.
United Kingdom
NHS England specialized commissioning frameworks determine robotic thoracic surgery program authorization thresholds. MHRA post-Brexit regulatory alignment with EU MDR standards imposes strengthened clinical evidence requirements on thoracoscopic instrument suppliers. London and Manchester academic medical centers pilot haptic feedback training modules with NIH-equivalent research funding access.
Minimally Invasive Thoracic Surgery Market Key Industry Players
Channel-controlling players compete with product-specialist players across capital-intensive robotic platforms and disposable instrument categories. Consolidated health system procurement committees favor integrated sourcing agreements that bundle systems, instruments, and service contracts. Three archetypes dominate: installed-base incumbents leveraging recurring instrument revenue, integrated ecosystem providers combining navigation with energy devices, and specialized suturing platform manufacturers. Dominant competitive moves include vendor relationship consolidation through group purchasing organization centralization and portfolio diversification into AI-integrated imaging capabilities.
Within the installed-base archetype, Intuitive Surgical occupies a position exemplifying recurring revenue models tied to console deployments. Medtronic and Johnson & Johnson represent integrated ecosystem and specialized platform positions respectively, anchoring competitive dynamics across German and US hospital procurement landscapes. These three entities exemplify how capital-rich health systems and consolidated networks tilt competitive dynamics through equipment leasing and project finance structures.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Johnson & Johnson |
| Medtronic |
| Stryker |
| Olympus Corporation |
| Karl Storz |
| CONMED Corporation |
| Cook Group |
| Richard Wolf |
| Others |
Cost & Logistics Intelligence
The Shanghai-Frankfurt air freight corridor carries precision surgical instruments and robotic console components at rates that fluctuate with fuel surcharges and capacity constraints, compressing margins for European distributors while amplifying price spreads between FDA-validated and CE-marked equipment tiers. Hospital procurement committees in consolidated US networks exploit this concentration to extract volume discounts, whereas independent German clinics absorb premium logistics costs that widen their procurement disadvantage.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE-MDR grade) creates the primary spread between robotic system tiers, with Japanese PMDA-cleared instruments commanding 15-25% premiums over standard CE-marked equivalents in Asian markets. Three-tier pricing structure across premium, standard, and economy levels segments procurement: academic medical centers absorb premium bundled service contracts, while Indian tier-2 hospitals under Ayushman Bharat constraints favor economy-tier reusable titanium instrumentation. Cost compression in the mid-tier is intensifying because EU MDR compliance expenditures are forcing smaller instrument suppliers to exit, consolidating pricing power among capital-rich incumbents. Community hospitals lacking GPO negotiating leverage exhibit highest price sensitivity; consolidated southeastern US health systems demonstrate lowest sensitivity due to tax-exempt bond financing access.
Supply Chain Analysis
Export control regimes under US EAR Category 0 and Japan's Foreign Exchange and Foreign Trade Act restrict telepresence software and haptic feedback hardware flows to certain end-users, fragmenting component sourcing for robotic console manufacturers. Supply concentrates in the United States for surgeon console assembly, Germany for precision optical components, and Japan for force-sensor microelectronics. Raw material dependencies span surgical-grade stainless steel from Sweden, rare-earth magnets for robotic arm actuators from China, and high-purity silicon for imaging sensors from Taiwan. Single-source vulnerability in haptic feedback chipsets creates bottleneck exposure. Distribution runs through hospital group purchasing organizations in North America, direct manufacturer-to-hospital contracts in Germany, and government tender processes in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open thoracotomy techniques retain 30-40% volume share in complex esophagectomy and redo lung resection cases, presenting a persistent substitution threat that robotic and video-assisted platforms must displace through outcome documentation and training pipeline expansion.
For Market Incumbents: Harden installed-base defenses by embedding AI-integrated imaging modules into existing console architectures, creating switching costs that lock hospital systems into proprietary instrument ecosystems. Deepen backward integration into energy device manufacturing to capture margin pools currently flowing to bipolar and ultrasonic platform specialists. The rising threat of open procedure volume retention in complex cases demands accelerated proctoring program deployment to compress surgeon learning curves. For New Entrants and Emerging Players: Mid-market surgical centers in India's tier-2 cities represent the most penetrable entry point, where Ayushman Bharat reimbursement expansion outpaces robotic system deployment and video-assisted thoracoscopic procedures dominate procurement specifications. German outpatient thoracic facilities licensing same-day discharge protocols offer secondary white-space, with instrument reprocessing service bundling as the viable go-to-market angle against capital-constrained incumbents. For Investors and Strategic Acquirers: Specialized energy device manufacturers with EU MDR technical documentation portfolios and established German notified body relationships present asymmetric upside capture potential. Long-term viability hinges on whether reimbursement frameworks mature to cover robotic-assisted procedures in outpatient settings before capital intensity barriers consolidate the field. The signal to watch is Japan PMDA expansion of national health insurance coverage to wedge resection and pleural biopsy procedures, which would validate ambulatory migration economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Technical Documentation Rebuild | EU notified body backlog delays compress commercial launch windows for novel thoracoscopic staplers. |
| Hospital System Partnership | Integrated delivery network standardization on single-platform deployments locks in instrument recurring revenue. |
| Reimbursement Strategy | PMDA national health insurance coding expansion determines addressable procedure volumes in Japanese tertiary centers. |
| Software Companion Development | AI-integrated nodule detection algorithms differentiate platform positioning in US academic medical center procurement. |
| Proctoring Program Scale-Up | Structured credentialing pipelines overcome surgeon training bottlenecks constraining qualified operator pool expansion. |
Research Approach
A spread of perspectives from thoracic surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions that shape this analysis. Primary interview data combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, PMDA reimbursement bulletins, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down health system capital expenditure disclosures.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation across product type, end user, technology, and procedure type dimensions. CAGRs derived from instrument shipment data, console installation records, and reimbursement code utilization trends. Forecast inputs incorporated surgeon training pipeline capacity, EU MDR certification timeline delays, and ambulatory surgical facility licensing reform trajectories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting hospital tax-exempt bond financing access would shift the trajectory. Forecasts reflect assumptions about reimbursement framework stability and regulatory clearance pathway efficiency. Material shifts in EU MDR notified body processing capacity or Japan PMDA coverage expansion scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Hemostatic Instruments Market
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Neovaginal Surgery Market
Surgical Instruments
India General Surgical Devices Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Special Purpose Needles Market