
 Thin Wall Glass Container Market | 2026-2036
Thin Wall Glass Container Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wall Glass Container Market Analytics
Subscription-based container fleet management is broadening what glass packaging suppliers sell beyond physical units. Ardagh Group leverages long-term supply agreements with beverage multinationals to sustain volume commitments across European production sites. Owens-Illinois anchors North American food packaging demand through its extensive furnace network. Verallia differentiates via lightweighting technology leadership, competing on gram-weight reduction for premium wine and spirits brands.
Thin wall glass containers are hollow vessels manufactured with wall thickness typically below 2.5 millimeters, formed through narrow-neck press-and-blow or blow-blow processes using soda-lime or borosilicate compositions, designed to reduce material weight while maintaining structural integrity for liquid and semi-solid contents. The bottles segment dominates volume due to beverage industry scale, while the vials category captures concentrated margin pools from pharmaceutical serialization and cold-chain requirements. Food & Beverage end users drive baseline demand, though Cosmetics applications are expanding fastest as brands switch from plastic to glass for premium positioning.
FDA cGMP standards and EU MDR requirements govern pharmaceutical glass contact surfaces, while REACH restricts heavy metal content in decorative coatings. The EPA and OSHA frameworks in the United States regulate furnace emissions and worker exposure limits at manufacturing facilities. Stakeholders must monitor how tightening EU ETS carbon costs and emerging state-level extended producer responsibility laws reshape the total cost of glass ownership against alternative materials.
Market Dynamics
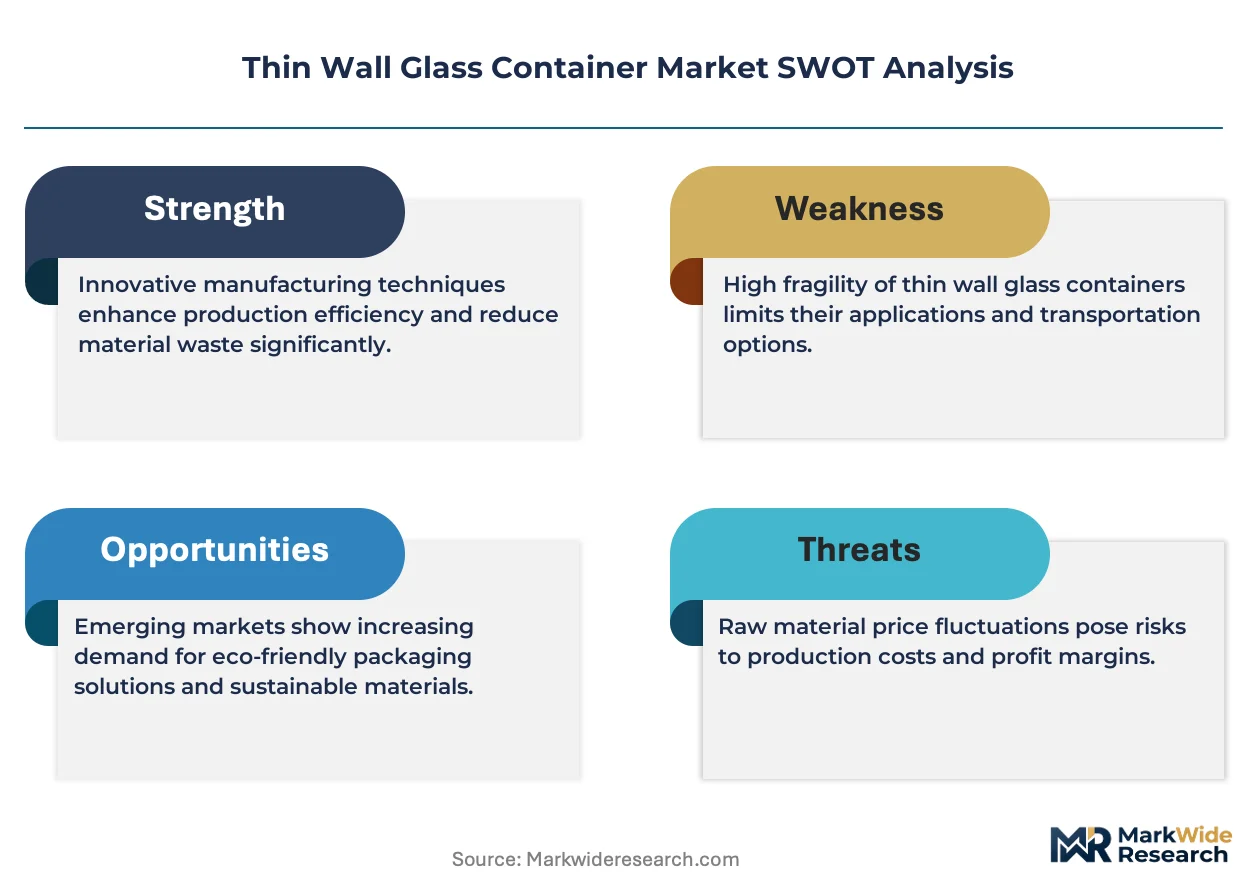
Pharmaceutical serialization mandates and EU ETS carbon pricing are compressing margins for conventional soda-lime glass while rewarding borosilicate thin wall investments in precision drug delivery applications.
Growth Catalysts
- EU F-Gas Regulation:Tighter fluorinated gas controls are accelerating furnace upgrades toward electric melting, reducing carbon intensity for German and French pharmaceutical glass clusters.
- Biologic cold-chain expansion:mRNA vaccine storage requirements are pulling borosilicate vial demand into oncology and gene therapy pipelines.
- Cosmetic plastic-to-glass switching:Premium skincare brands in South Korea and France are specifying thin wall bottles for shelf differentiation and regulatory compliance.
Market Restraints
- Natural gas price volatility:Float glass furnaces in Italy and Spain face input cost swings that compress operating margins during winter demand spikes.
- Quartz sand supply concentration:High-purity silica deposits in Belgium and northern France create geographic chokepoints for borosilicate production.
- Polymer barrier coatings:Advanced multilayer plastics are capturing single-use pharmaceutical applications where glass breakage risk dominates purchasing criteria.
Strategic Opportunities
- India CDSCO serialization mandates:Track-and-trace requirements for exported pharmaceuticals are creating demand for pre-etched glass vials with integrated data matrix codes.
- Direct-to-consumer wine channels:Lightweight thin wall bottles reduce shipping costs for California and Australian e-commerce vintners.
- EU Green Deal carbon border adjustments:Imported glass from carbon-intensive regions faces tariff exposure, protecting domestic European furnace investments.
Industry Challenges
- Specialized furnace engineering talent:Electric melting and oxy-fuel conversion projects require skills concentrated among retired German and Czech technical specialists.
- FDA cGMP validation timelines:Pharmaceutical container qualification cycles extend 18-24 months, locking capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wall Glass Container Market |
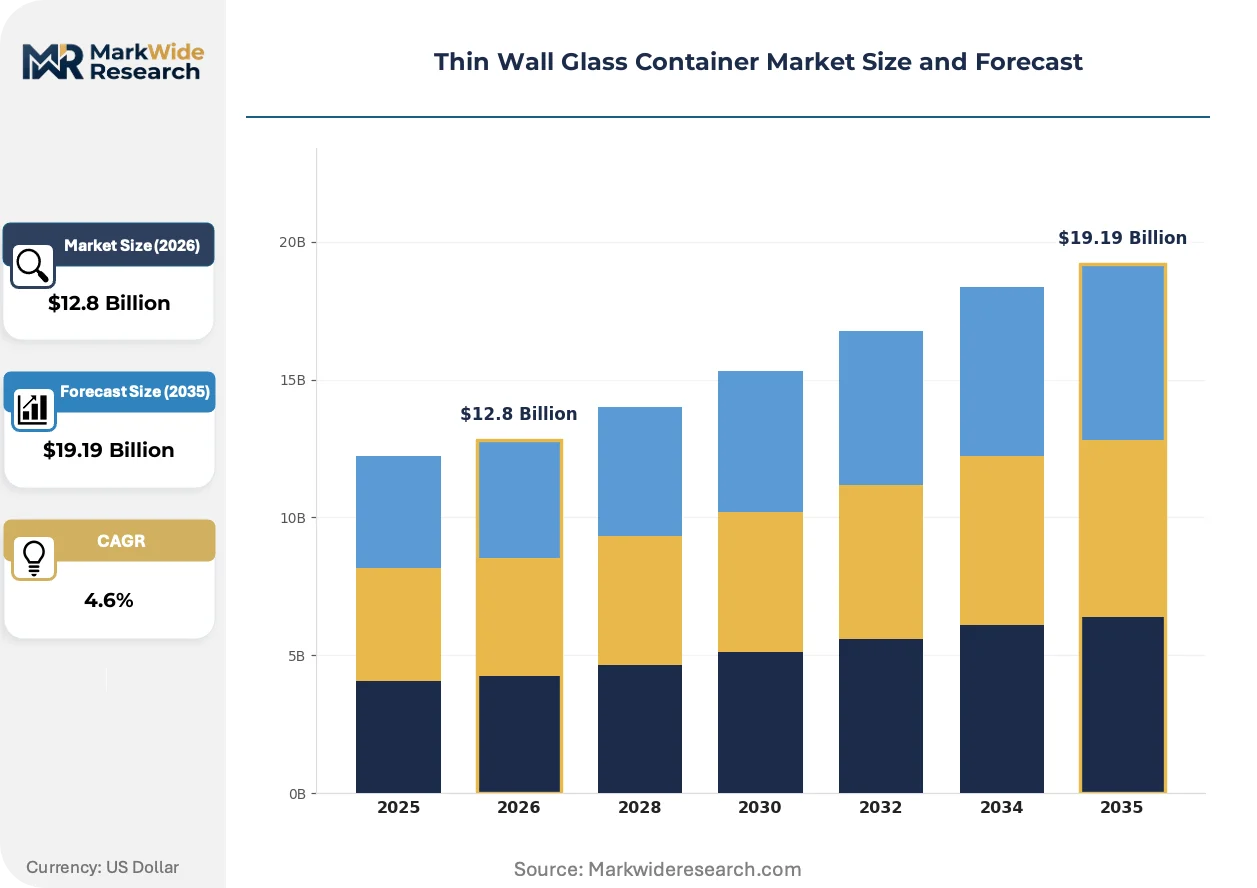
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tumblers, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Home Care Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales Application: Packaging, Storage, Shipping, Display |
| Companies Covered | Ardagh Group, Owens-Illinois, Verallia, Vetropack, Vidrala, Duran Group, Hilgenberg GmbH, Berlin Packaging, Stölzle Glass Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wall Glass Container Market Evolving Landscape
Active lightweighting programs and digital printing integration are redefining how glass packaging competes against aluminum and polymer alternatives in premium segments.
Plasma-enhanced chemical vapor deposition is expanding into thin wall pharmaceutical vials, depositing silicon oxide barrier layers that extend drug stability without adding measurable weight. Biologic manufacturers in Switzerland and Massachusetts are qualifying these coated containers for moisture-sensitive biologics. The technology is expanding into standard borosilicate pricing tiers, compressing differentiation windows for uncoated premium vials.
REACH Annex XVII restrictions on cadmium and lead in decorative coatings are forcing reformulation of colored glass enamels used in cosmetic and spirits packaging. German and Italian decorators are migrating to rare-earth-based colorants at 15-30% cost premiums. Wine and spirits brands with heritage color signatures face reformulation timelines that extend through 2027.
Brand procurement teams are consolidating supplier panels from 12-15 vendors to 3-4 strategic partners with integrated design-to-delivery capabilities. Beverage multinationals in Brazil and Mexico are awarding five-year thin wall bottle contracts with embedded volume flexibility clauses. This concentration is most visible in sparkling water and premium beer segments where SKU proliferation demands rapid mold changeover capabilities.
Thin Wall Glass Container Market Segmentation
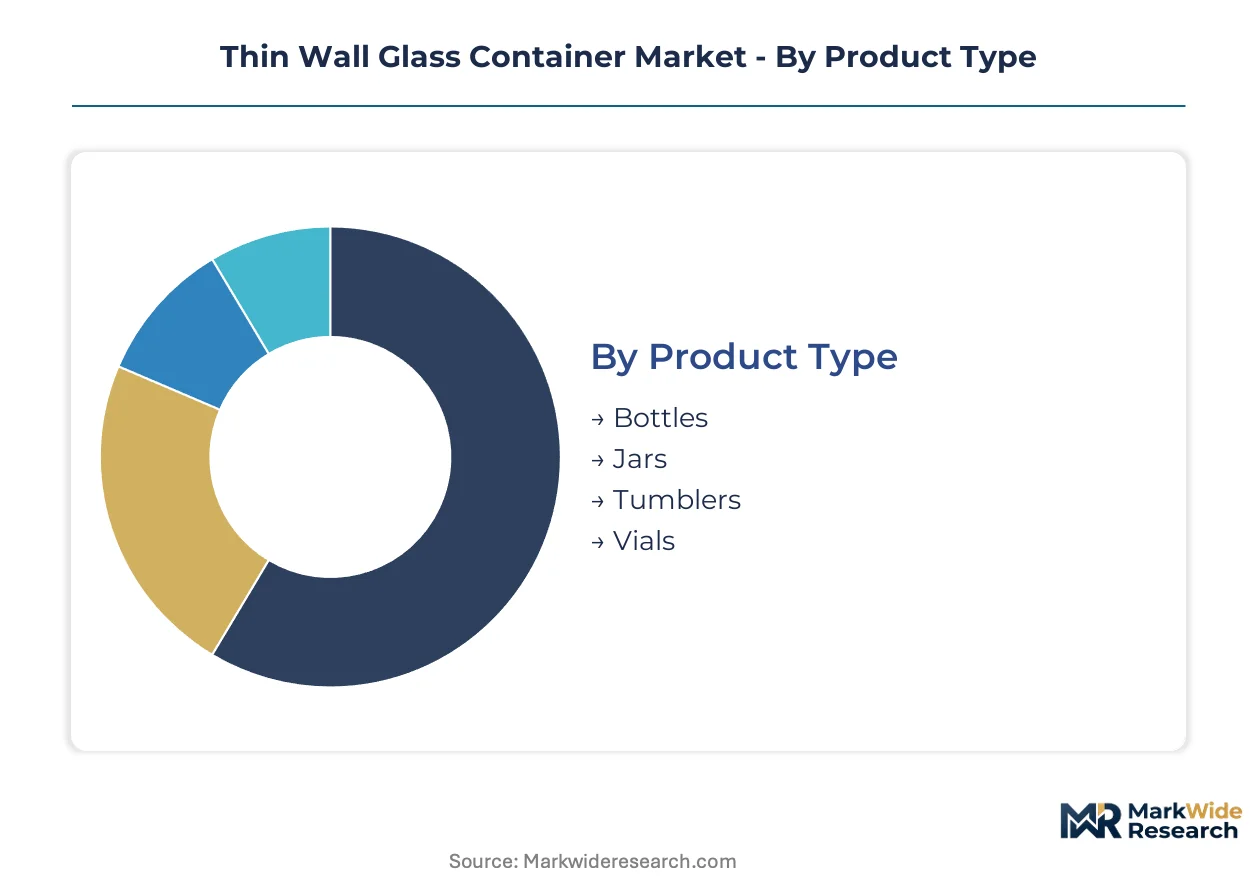
Thin wall glass container segmentation reveals how certification burdens, thermal performance requirements, and channel economics split manufacturing investments across incompatible specification tiers. Pharmaceutical and food-grade applications operate under divergent validation protocols that reshape supplier capabilities and margin structures.
Product Type:
FDA cGMP and EU MDR compliance requirements concentrate on vials and pharmaceutical-grade bottles, while food-contact FDA and EU FCM frameworks govern jars and tumblers for beverage and home care applications.
- Bottles:Narrow-neck press-and-blow formations in soda-lime and borosilicate compositions deliver sub-2.5mm walls for carbonated beverages and wine. Demand clusters in German sparkling water and California direct-to-consumer wine channels where lightweighting cuts freight costs. REACH-compliant decorative coatings for premium spirits brands are forcing rare-earth pigment migration at 15-30% cost premiums.
- Vials:Borosilicate thin wall constructions with wall thickness below 1.8mm serve biologic cold-chain requirements for mRNA vaccines and gene therapy pipelines. Swiss and Massachusetts manufacturers are qualifying plasma-enhanced CVD silicon oxide barriers for moisture-sensitive oncology drugs. FDA validation cycles extend 18-24 months, locking supplier capital before revenue recognition.
- Jars:Wide-mouth blow-blow containers for premium skincare and food preservation. South Korean cosmetic brands specify thin wall glass for shelf differentiation and plastic-to-glass switching mandates.
- Tumblers:Straight-sided drinking vessels for food service and home care. Italian and Spanish furnace operators face natural gas price volatility that compresses operating margins during winter demand spikes.
Leading the category by volume: Bottles. Growing fastest: Vials.
End User:
Margin concentration follows validation intensity, with pharmaceutical serialization requirements extracting premium pricing against commoditized food and beverage procurement.
- Food & Beverage:Baseline demand driver spanning carbonated drinks, wine, spirits, and packaged foods. Owens-Illinois anchors North American volume through extensive furnace networks. EU ETS carbon pricing and natural gas volatility in Italy and Spain are compressing margins for conventional soda-lime production.
- Pharmaceuticals:Serialization mandates and biologic cold-chain expansion pull borosilicate vial demand into oncology and gene therapy. India CDSCO track-and-trace requirements for exported drugs are creating demand for pre-etched glass vials with integrated data matrix codes.
- Cosmetics:Premium skincare brands in France and South Korea specify thin wall bottles for regulatory compliance and shelf differentiation. REACH Annex XVII cadmium and lead restrictions are forcing enamel reformulation through 2027.
- Home Care:Storage and dispensing applications for cleaning products and candles. Lightweighting programs compete against polymer alternatives in mass-market segments.
Widest margin pool: Pharmaceuticals. Most price-sensitive: Home Care.
Distribution Channel:
Channel selection determines mold changeover frequency and inventory carrying costs, with direct sales and wholesale rewarding integrated design-to-delivery capabilities.
- Direct Sales:Long-term supply agreements with beverage multinationals sustain volume commitments across European production sites. Five-year contracts with embedded flexibility clauses are consolidating supplier panels from 12-15 vendors to 3-4 strategic partners.
- Wholesale:Intermediate stocking for mid-tier food and cosmetics brands. Rapid SKU proliferation in sparkling water demands mold changeover capabilities that favor suppliers with digital printing integration.
- Supermarkets:Private-label thin wall containers for retail-brand beverages and condiments. Price pressure from polymer alternatives dominates purchasing criteria.
- Online Retail:Direct-to-consumer wine channels in California and Australia favor lightweight bottles that reduce last-mile shipping costs. E-commerce vintners are specifying gram-weight reductions for premium positioning.
Highest volume commitment: Direct Sales. Fastest channel expansion: Online Retail.
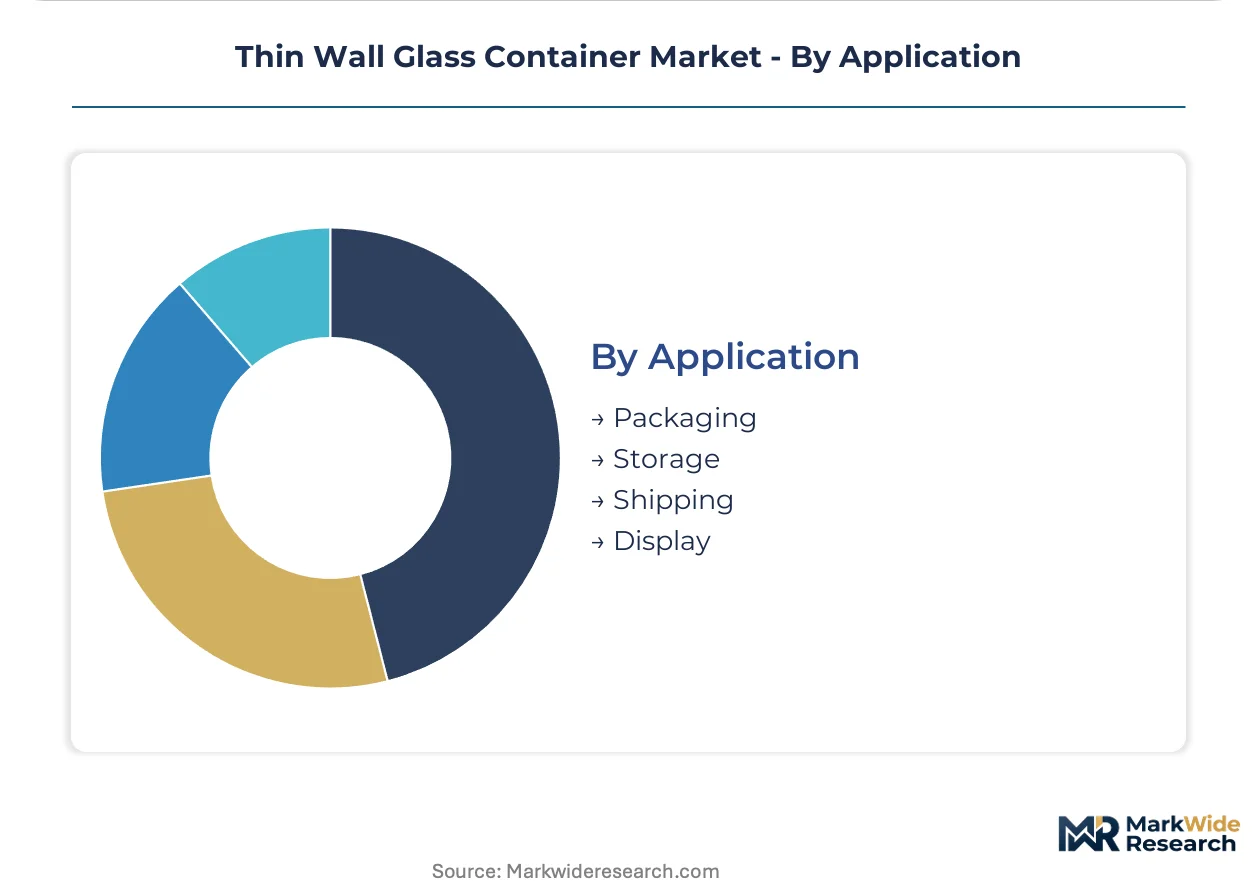
Application:
Functional requirements split between protective performance (packaging, shipping) and aesthetic presentation (storage, display), with divergent coating and decoration specifications.
- Packaging:Primary containment for liquids and semi-solids with barrier integrity requirements. Plasma-enhanced CVD coatings are expanding into standard borosilicate tiers, compressing differentiation windows for uncoated premium vials.
- Storage:Long-term preservation for wine, spirits, and pharmaceuticals. German and French glass clusters around Mainz and Jena supply precision containers with specialized annealing profiles.
- Shipping:Logistics-optimized lightweight designs for e-commerce and export. EU Green Deal carbon border adjustments expose imported glass from carbon-intensive regions to tariff protection for domestic furnace investments.
- Display:Shelf-facing cosmetic and spirits presentation with decorative coatings. Rare-earth-based colorants are replacing cadmium and lead enamels at 15-30% cost premiums.
Dominant application by unit volume: Packaging. Steepest technology investment: Shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mainz and Jena anchor German precision glass manufacturing, supplying pharmaceutical clusters with borosilicate thin wall vials for biologic drug delivery. Regulatory tightening across multiple jurisdictions is reshaping furnace economics and supplier geography.
Germany
Specialized glass clusters around Mainz and Jena supply precision pharmaceutical and cosmetic containers with sub-2.5mm wall specifications. EU F-Gas Regulation and REACH compliance frameworks tighten material specifications for glass packaging across production sites. Electric melting furnace upgrades accelerate in Rhineland-Palatinate to reduce carbon intensity under EU ETS pricing.
United States
FDA cGMP standards govern pharmaceutical glass contact surfaces while EPA and OSHA frameworks regulate furnace emissions and worker exposure limits at manufacturing facilities. California direct-to-consumer wine channels favor lightweight thin wall bottles that reduce last-mile shipping costs. Massachusetts biologic manufacturers qualify plasma-enhanced CVD coated containers for moisture-sensitive oncology drugs.
France
Verallia anchors lightweighting technology leadership, competing on gram-weight reduction for premium wine and spirits brands. EU Green Deal carbon border adjustments expose imported glass from carbon-intensive regions to tariff protection for domestic furnace investments. Rare-earth-based colorants replace cadmium and lead enamels in decorative coatings at 15-30% cost premiums through 2027.
India
CDSCO serialization mandates for exported pharmaceuticals create demand for pre-etched glass vials with integrated data matrix codes. Pharmaceutical manufacturers expand adoption of borosilicate thin wall vials for biologic drug delivery serving oncology and gene therapy pipelines. Track-and-trace requirements reshape supplier qualification protocols for container exports.
Italy
Float glass furnaces face natural gas price volatility that compresses operating margins during winter demand spikes. REACH Annex XVII restrictions force reformulation of colored glass enamels used in cosmetic and spirits packaging. Decorators migrate to rare-earth-based colorants as heritage color signature brands extend reformulation timelines.
Thin Wall Glass Container Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent specification tiers. Integrated furnace operators with captive sand deposits and electric melting capabilities command premium positioning in pharmaceutical serialization markets. Three archetypes dominate: multinational conglomerates with beverage anchor contracts, mid-cap specialists focused on borosilicate pharmaceutical vials, and regional decorators with rapid mold changeover capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement panels consolidate from 12-15 vendors to 3-4 strategic partners.
Among European-integrated multinationals, Ardagh Group, Verallia, and Owens-Illinois occupy positions across beverage and pharmaceutical specification tiers. Ardagh exemplifies long-term supply agreement structures with volume flexibility clauses. Verallia represents lightweighting technology leadership in premium wine and spirits positioning. Owens-Illinois anchors North American food packaging demand through extensive furnace network scale. These three exemplify how geographic production density and regulatory compliance capabilities determine strategic positioning.
| Leading Market Players |
|---|
| Ardagh Group |
| Owens-Illinois |
| Verallia |
| Vetropack |
| Vidrala |
| Duran Group |
| Hilgenberg GmbH |
| Berlin Packaging |
| Stölzle Glass Group |
| Others |
Value Network & Pricing Analysis
Natural gas price benchmarks in European trading hubs cascade through furnace economics into three distinct pricing tiers for thin wall glass containers. Soda-lime commodity grades absorb input volatility through volume scale, while borosilicate pharmaceutical vials command premium stability via long-term offtake structures with biologic manufacturers.
Pricing Analysis
Margin tightening in standard soda-lime containers reflects natural gas price volatility and EU ETS carbon cost pass-through pressures. Three-tier pricing structure across pharmaceutical-grade borosilicate, premium cosmetic glass, and commodity beverage containers differentiates by certification intensity and validation burden. Pricing pressure accelerates in Italian and Spanish furnace operations during winter demand spikes. Home care applications exhibit highest price sensitivity, while oncology drug packaging shows lowest elasticity due to FDA cGMP lock-in effects.
Supply Chain Analysis
High-purity silica sand supply rests on Belgian and northern French deposit concentration for borosilicate pharmaceutical production. Soda-lime glass feeds from German, Italian, and Spanish furnace networks with varying carbon intensity profiles. Raw material dependencies include natural gas for melting energy, rare-earth colorants for REACH-compliant decorative coatings, and boron compounds for thermal resistance. Single-source vulnerability concentrates in quartz sand geography. Distribution runs through direct sales agreements with beverage multinationals and wholesale channels for mid-tier cosmetics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin wall glass container manufacturing is transitioning from fossil-fuel furnaces to electric melting and oxy-fuel systems, with EU F-Gas Regulation compliance forcing capital reallocation across European production bases.
For Market Incumbents: Cement market position through captive quartz sand deposit control and electric furnace conversion in Rhineland-Palatinate. Deepen backward integration into rare-earth colorant supply chains before REACH Annex XVII reformulation deadlines. Polymer barrier coatings threaten pharmaceutical vial margins; respond with plasma-enhanced CVD coating qualification programs. For New Entrants and Emerging Players: Enter via India CDSCO serialization mandate compliance for pre-etched pharmaceutical vials with integrated data matrix codes. Target direct-to-consumer wine channels in California and Australia with lightweight bottle designs optimized for last-mile freight economics. Pursue rapid mold changeover capabilities as the primary go-to-market angle against consolidated supplier panels. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap borosilicate specialists with FDA validation track records in German precision glass clusters. Five-to-ten year viability hinges on electric melting technology deployment and carbon border adjustment positioning. Watch EU ETS price trajectory and natural gas forward curves as inflection indicators for furnace economics.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Furnace Conversion | Rhineland-Palatinate upgrades reduce carbon intensity under EU ETS pricing frameworks. |
| Plasma-Enhanced CVD Coating Qualification | Swiss and Massachusetts biologic manufacturers adopt silicon oxide barriers for moisture-sensitive drugs. |
| Pre-Etched Vial Serialization Capacity | India CDSCO track-and-trace mandates reshape supplier qualification for export markets. |
| Rare-Earth Colorant Supply Agreement | German and Italian decorators secure REACH-compliant pigment sources ahead of 2027 deadlines. |
| Lightweighting Technology Licensing | Verallia's gram-weight reduction programs transfer to California direct-to-consumer wine channels. |
Research Methodology
Multi-period observation of furnace utilization rates, natural gas input costs, and pharmaceutical serialization adoption anchored the trend analysis, supplemented by interviews with glass furnace operators, pharmaceutical packaging procurement managers, cosmetic brand supply chain directors, and REACH compliance consultants. Secondary validation drew from EU ETS carbon price data, FDA cGMP guidance documents, CDSCO export notifications, and trade flow statistics. Bottom-up capacity modeling and top-down demand segmentation were triangulated against primary fieldwork.
Segment-weighting across product type, end user, distribution channel, and application dimensions structured the analytical framework across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Forecast inputs incorporated electric melting adoption curves, biologic cold-chain expansion rates, and EU Green Deal carbon border adjustment implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price spike scenarios and accelerated polymer substitution in single-use pharmaceutical applications. Forecasts reflect documented assumptions about regulatory timelines and technology adoption curves. A small set of triggers—EU ETS price thresholds, FDA validation backlog duration, and rare-earth supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Spain Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Vietnam Container Glass Market