
 Latin America Glass Packaging Market | 2026-2036
Latin America Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Glass Packaging Market Foresight
Direct-to-brewer supply contracts is reconfiguring how container glass flows across Latin America. Verallia SA anchors its position through furnace-scale production in Brazil and Argentina. O-I Glass, Inc. leverages its cross-border logistics network to serve multinational beverage accounts. Vitro, S.A.B de C.V. dominates the premium spirits segment with decorative finishing capabilities.
Glass packaging denotes rigid containers formed from silica-based melts, typically comprising soda ash, limestone, and cullet, shaped through blow-and-blow or press-and-blow forming and annealed for thermal durability; these vessels provide inert, impermeable barriers for consumable and chemical products. Bottles lead volume within the product type dimension, though jars command margin premiums in artisan food and cosmetic applications. Food & Beverage end users drive baseline throughput, while Pharmaceuticals generates higher unit economics due to ANVISA compliance burdens and batch certification requirements.
Brazil's ANVISA and Mexico's COFEPRIS enforce material safety and traceability protocols that elevate entry costs for pharmaceutical-grade glass converters. The EU Green Deal's extraterritorial reach through supply chain audit requirements is pressing Latin American exporters toward lighter-weight bottle designs and post-consumer cullet integration. Stakeholders must weigh furnace reinvestment cycles against the pull from refillable bottle mandates circulating in several Mercosur capitals.
Market Dynamics
The Latin America glass packaging sector operates under furnace capacity constraints that collide with refillable bottle mandates spreading through Mercosur capitals, forcing converters to choose between asset reinvestment and format flexibility.
Growth Catalysts
- ANVISA pharmaceutical traceability rules:Brazil's updated packaging standards mandate batch-level material certification, elevating demand for compliant glass converters serving injectable and oral dosage formats.
- Returnable bottle system expansion:Beverage bottlers across Mexico and Brazil are scaling closed-loop collection infrastructure to meet corporate sustainability targets and reduce per-use material intensity.
- Tequila premiumization corridor:Jalisco's craft spirits producers command specialized decorative finishing and custom mold capabilities, pulling investment toward high-margin premium bottle production.
Market Restraints
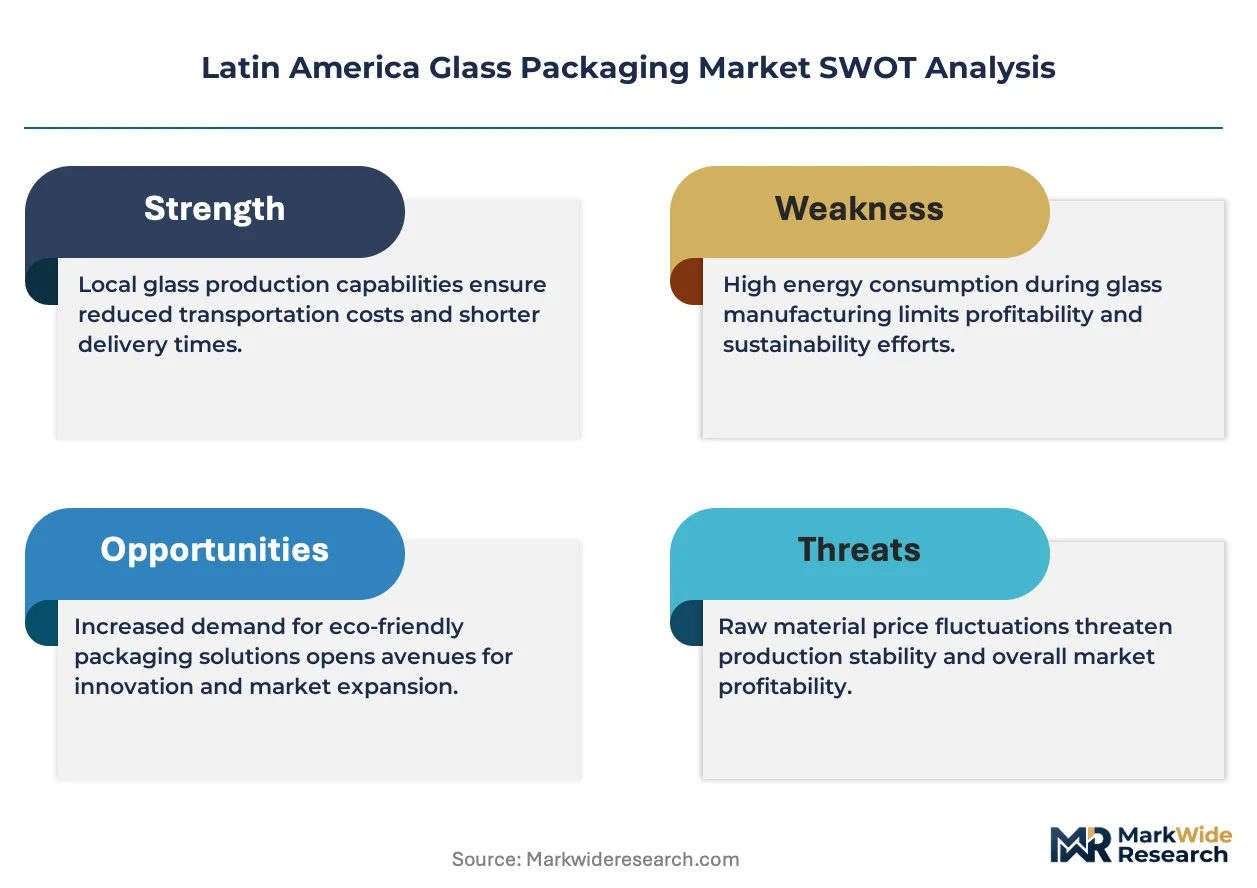
- Natural gas price volatility:Furnace operations depend on imported LNG pricing indexed to international benchmarks, compressing margins during energy cost spikes.
- Concentrated soda ash supply:Regional converters rely on limited domestic alkali production, exposing cost structures to import dependency from North American suppliers.
- Aluminum can substitution:Lightweight metal formats capture share in mass-market beer and carbonated soft drinks, particularly where cold-chain logistics favor single-use disposability.
Strategic Opportunities
- Colombia's underdeveloped spirits packaging base:Premium rum and aguardiente producers lack local decorative glass capacity, creating entry points for converters with mold-making expertise.
- EU Green Deal supply chain audits:Extraterritorial compliance requirements for Latin American exporters favor converters with verified post-consumer cullet integration and carbon accounting systems.
- Direct-to-brewer contracting models:Craft beverage producers are bypassing traditional distributor networks to secure dedicated furnace allocation and custom design services.
Industry Challenges
- Specialized mold engineering talent scarcity:Decorative bottle production requires skilled blow mold designers and CNC machinists, with training pipelines failing to match converter expansion timelines.
- Furnace rebuild capex cycles:Major refractory overhauls demand capital reserves that compete with lightweighting R&D investments, straining mid-scale producer balance sheets.
- COFEPRIS pharmaceutical certification timelines:Mexico's regulatory approval process for primary packaging materials extends 18-24 months, delaying new converter market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Glass Packaging Market |
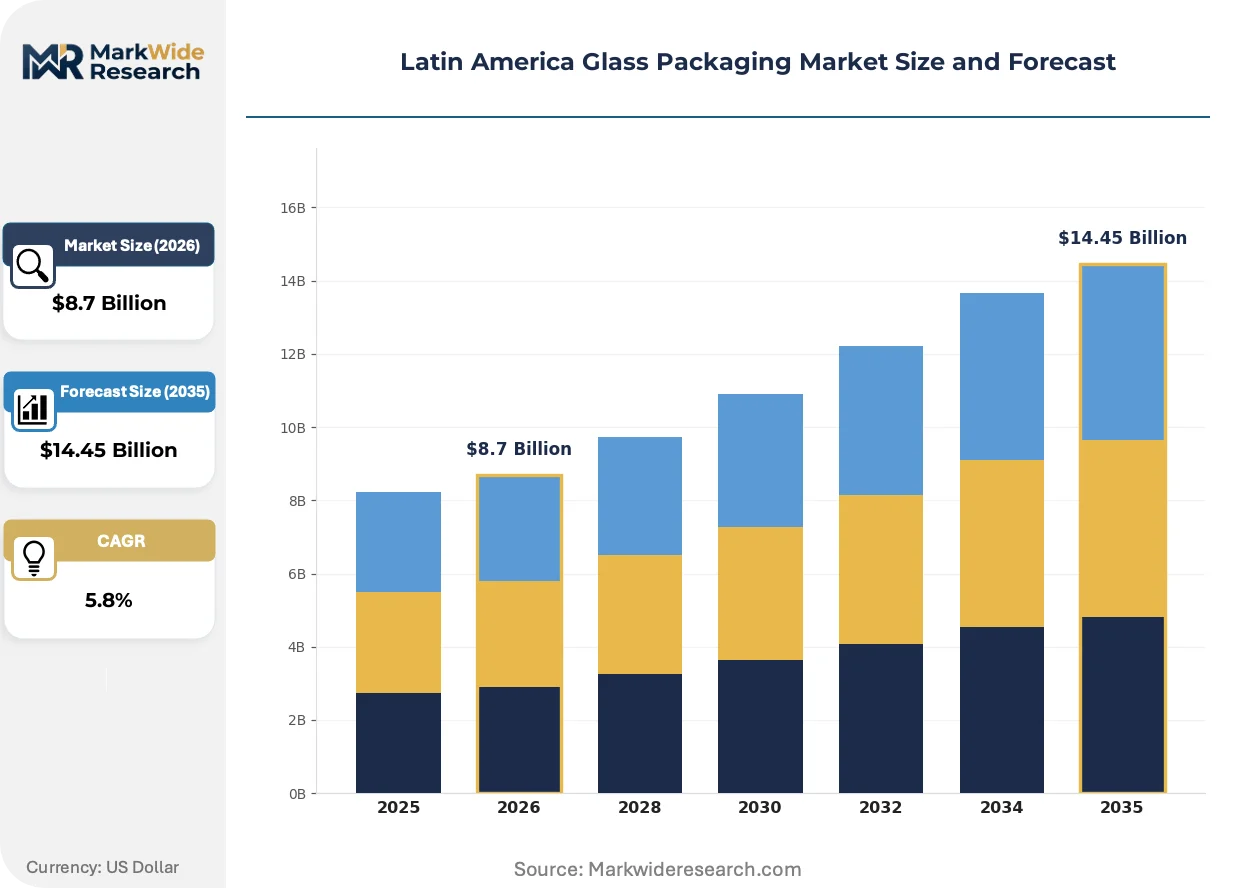
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Care Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Wheaton Brasil Group, Verallia SA, O-I Glass, Inc., Fevisa Industrial, S.A. de C.V., Fusión y Formas S.A. de C.V., Vitro, S.A.B de C.V., Saverglass SAS, Owens-Illinois do Brasil Industria e Comercio SA, Gerresheimer AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Glass Packaging Market Shifts & Advancements
Container lightweighting and digital traceability systems are redefining competitive capability across Latin American glass converters, separating furnace-scale specialists from artisan finishing shops.
Electrochemical batch monitoring is migrating from quality control laboratories onto furnace floor operations. Large-format beverage producers in São Paulo state are installing real-time melt analysis sensors to reduce seed and stone defects. This migration from offline sampling to continuous digital feedback is compressing reject rates and enabling thinner wall designs without structural compromise.
ANVISA's updated pharmaceutical packaging resolution tightens material traceability to the raw batch level. Converters must now maintain chain-of-custody documentation from silica sand sourcing through final annealing. Injectable glass and ampoule segments face the steepest compliance burdens, with Brazilian facilities accelerating ERP system upgrades to capture batch-level genealogy data.
Refillable bottle pooling systems are reshaping procurement relationships between beverage brands and converters. Mexican beer and soft drink bottlers are negotiating long-term returnable format contracts that embed collection logistics responsibility with glass suppliers. This shift concentrates volume commitments with converters owning reverse logistics infrastructure, visible in the Mexico City-Guadalajara corridor where deposit-return legislation is advancing.
Latin America Glass Packaging Market Segmentation
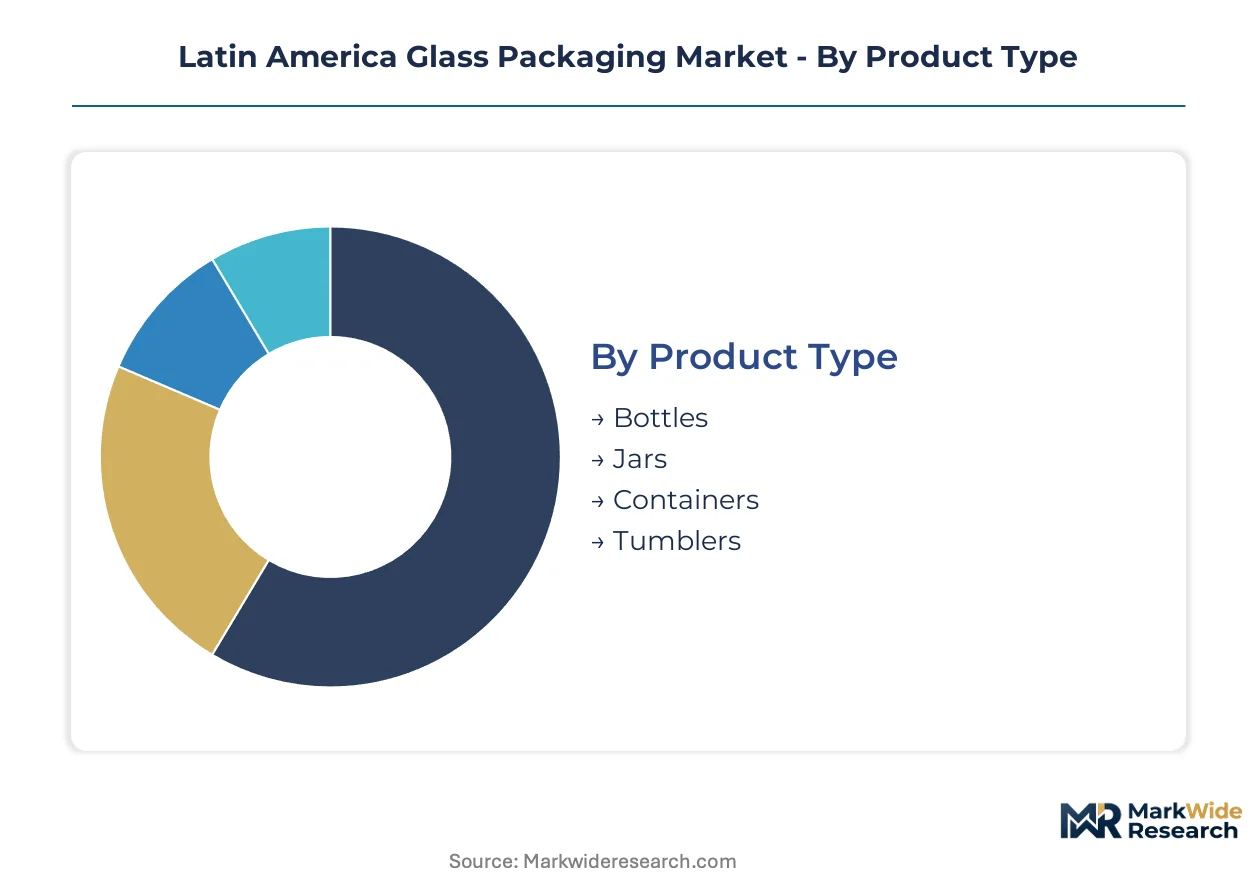
Glass packaging converters across Latin America align furnace output and mold investments against distinct performance requirements. Segmentation reveals where margin premiums concentrate versus where volume throughput drives asset utilization decisions.
Product Type:
Beverage bottlers in Mexico and Brazil source formats spanning single-serve disposability to multi-trip returnability, with decorative finishing capabilities separating premium spirits contracts from commodity beer supply.
- Bottles:Formed through blow-and-blow or press-and-blow processes, these vessels dominate beverage applications with neck finish precision critical for crown cork and screw cap compatibility. Tequila producers in Jalisco command specialized mold capabilities for embossed and applied ceramic decoration, pulling converter investment toward premium spirits corridors.
- Jars:Wide-mouth containers with lug or continuous thread finishes serve artisan food preservation and cosmetic cream applications. Brazilian fruit preserve exporters and Colombian coffee processors specify hermetic seal performance, generating margin premiums above standard beverage bottles through specialized closure interface engineering.
- Containers:Rectangular and square-section pressed glass formats accommodate bulk food service and institutional chemical packaging. ANVISA-registered pharmaceutical converters in São Paulo state mold amber and flint glass for tablet and powder storage.
- Tumblers:Straight-sided drinking vessels without handles target hospitality and retail tableware channels. Mexican hotel supply distributors consolidate procurement through direct converter relationships, bypassing traditional wholesale intermediaries.
Established volume favors bottles; emerging adoption favors jars.
End User:
Regulatory burden and thermal performance requirements segment converter capabilities across consumer-facing and compliance-intensive applications.
- Food & Beverage:Baseline throughput for regional furnace operations, spanning carbonated soft drinks, beer, wine, spirits, sauces, and preserves. Returnable bottle mandates in Mercosur capitals are embedding collection logistics responsibility with glass suppliers.
- Pharmaceuticals:Injectable and oral dosage formats demand Type I borosilicate or Type II treated soda-lime glass with documented batch genealogy. ANVISA's updated resolution mandates material traceability from silica sand sourcing through final annealing.
- Personal Care:Cosmetic jars and fragrance bottles require decorative finishing capabilities including silk screening, hot stamping, and metallization. Premium positioning in Brazilian and Mexican urban markets drives specification for heavier wall weights and custom color matching.
- Household Care:Abrasive-resistant formulations for cleaning chemical storage, typically amber glass for light-sensitive contents. Volume concentrates with multinational brand owners operating Latin American filling operations.
Food & Beverage anchors furnace throughput; Pharmaceuticals commands unit economics premiums.
Capacity:
Size tiering aligns with distribution economics and consumption occasion fragmentation across on-premise and retail channels.
- Small:Sub-250ml formats for single-serve spirits, pharmaceutical ampoules, and cosmetic sampler packaging. Jalisco's craft mezcal producers specify miniature bottles for tourism retail.
- Medium:250ml to 750ml range capturing standard wine, spirits, and sauce applications. Mexican beer returnable systems concentrate at 355ml and 500ml nominal capacities.
- Large:750ml to 1.5L family-size and food service formats. Brazilian orange juice exporters specify 1L rectangular containers for cold-chain efficiency.
- Extra Large:Above 1.5L bulk retail and institutional packaging. Water and edible oil distributors in Colombia negotiate direct converter contracts for 5L carboy formats.
Medium capacity dominates returnable system design; small formats gain share in premium spirits sampling.
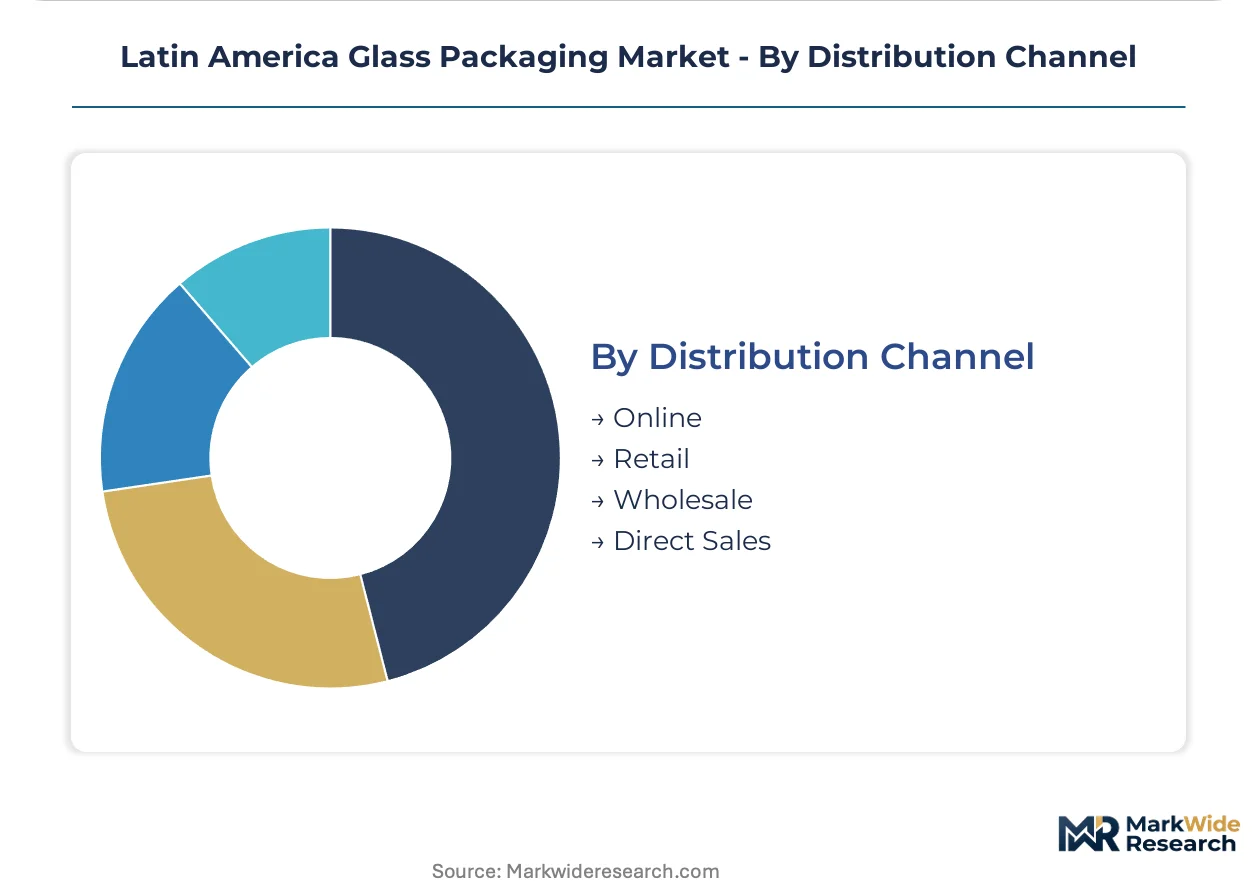
Distribution Channel:
Channel configuration determines logistics infrastructure requirements and order minimum thresholds for converter direct relationships.
- Online:E-commerce platforms serving craft beverage direct-to-consumer and specialty food subscription boxes. Fragile handling requirements favor corrugated partition designs over traditional bulk palletization.
- Retail:Supermarket and convenience store supply through distributor networks. Mexican modern trade consolidation is compressing SKU variety and favoring standardized bottle platforms.
- Wholesale:Traditional cash-and-carry and food service redistribution. Brazilian independent bar and restaurant supply remains fragmented across regional distributors.
- Direct Sales:Converter-to-bottler contracts bypassing intermediary inventory positions. Craft spirits producers in Mexico and Colombia negotiate dedicated furnace allocation through this channel.
Wholesale retains volume concentration; direct sales expands fastest among premium beverage accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico commands premium pricing power through tequila and craft spirits bottling contracts, while Brazilian converters absorb margin compression from ANVISA compliance burdens and natural gas import dependency.
Brazil
São Paulo state hosts the continent's densest furnace cluster, serving injectable pharmaceutical and returnable beer formats. ANVISA's batch-level traceability mandates force ERP upgrades that smaller converters cannot fund. The Campinas-Sorocaba corridor concentrates Type I borosilicate capacity for ampoule and vial production.
Mexico
Jalisco's tequila premiumization drives demand for embossed ceramic decoration and custom mold capabilities. COFEPRIS pharmaceutical certification timelines stretch 18-24 months, delaying new converter entry. The Mexico City-Guadalajara corridor anchors refillable bottle pooling systems with embedded reverse logistics.
Argentina
Mendoza's wine exporters specify lightweight Bordeaux and Burgundy formats for European market access. Mercosur capital debates over refillable mandates create regulatory uncertainty for furnace investment cycles. Buenos Aires province retains artisan pressed-glass capacity for institutional food service.
Colombia
Antioquia's aguardiente producers lack local decorative glass capacity, importing premium rum bottles from Mexican and Brazilian suppliers. The Bogotá savanna hosts multinational household care filling operations specifying amber glass for light-sensitive formulations. Pacific port access favors bulk raw material imports.
Chile
Central Valley wine exporters face EU Green Deal supply chain audit pressure for carbon accounting and post-consumer cullet verification. Valparaíso's port infrastructure supports furnace-scale soda ash imports from North American alkali producers. Santiago's cosmetic formulators drive specification for silk-screened fragrance bottles.
Latin America Glass Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mold-making and decorative finishing. The Latin America glass packaging sector organizes around furnace-scale volume players, mid-cap regional converters, and artisan finishing shops. Three archetypes dominate: multinational beverage supply networks, pharmaceutical-grade certified facilities, and premium spirits decorative specialists. Competitive moves concentrate on direct-to-brewer contracting and reverse logistics infrastructure deployment.
Among French-origin platform operators, Verallia SA and Saverglass SAS occupy positions spanning furnace-scale production and premium decorative capability. Mexican converters Vitro, S.A.B de C.V. and Fevisa Industrial, S.A. de C.V. exemplify the premium spirits archetype through Jalisco corridor relationships. These named entities anchor archetype tiers without implying specific strategic actions or market shares beyond their visible positioning in regional supply chains.
| Leading Market Players |
|---|
| Wheaton Brasil Group |
| Verallia SA |
| O-I Glass, Inc. |
| Fevisa Industrial, S.A. de C.V. |
| Fusión y Formas S.A. de C.V. |
| Vitro, S.A.B de C.V. |
| Saverglass SAS |
| Owens-Illinois do Brasil Industria e Comercio SA |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Natural gas price volatility indexed to international LNG benchmarks compresses margin structures across furnace operations while simultaneously widening spreads between commodity-grade and configured-to-order glass formats. This energy cost exposure dictates both the pricing tier architecture and the geographic clustering of production assets around pipeline-accessible zones in São Paulo state and Mexico City-Guadalajara corridor.
Pricing Analysis
The customization-premium spread separates standard returnable beer bottles from tequila producers' embossed ceramic-decorated formats in Jalisco. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation for ANVISA pharmaceutical compliance versus commodity beverage supply. Cost compression in standard formats is intensifying because aluminum can substitution captures mass-market beer share. Mass-market beverage bottlers exhibit highest price sensitivity; craft spirits producers and pharmaceutical accounts demonstrate lowest sensitivity due to regulatory compliance requirements and brand positioning needs.
Supply Chain Analysis
Export-control regimes on advanced furnace monitoring equipment from European and North American suppliers constrain technology transfer into regional converter operations. Geographic supply concentration centers on Brazil, Mexico, and Argentina for furnace-scale production, with decorative finishing capacity clustering in Jalisco and São Paulo. Raw material dependencies draw from imported soda ash from North American alkali producers, silica sand from domestic quarries, and natural gas from international LNG markets. Single-source vulnerability pervades specialized mold engineering talent pools. Distribution runs through direct-to-brewer contracting channels for premium accounts and traditional wholesale redistribution for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse logistics service layers for refillable bottle pooling systems are expanding faster than furnace capacity additions, converting asset-heavy glass production into recurring-revenue infrastructure relationships. This service-attach dynamic reconfigures converter economics toward collection-network ownership.
For Market Incumbents: Insulate furnace allocation commitments through long-term returnable format contracts that embed collection logistics responsibility with glass suppliers. Prioritize ERP system upgrades to capture ANVISA-mandated batch-level genealogy data before compliance deadlines tighten. Aluminum can substitution and emerging craft converter entrants in Colombia represent immediate threats; vertical integration into mold-making capabilities provides defensive moats. For New Entrants and Emerging Players: Establish a beachhead in Colombia's aguardiente and premium rum packaging segment where local decorative glass capacity remains underdeveloped. Target direct-to-brewer contracting models that bypass traditional distributor networks and secure dedicated furnace allocation. Leverage mold-making expertise as entry credential; partner with Jalisco craft mezcal producers for decorative finishing validation before scaling. For Investors and Strategic Acquirers: The market sits at a furnace reinvestment cycle phase that favors converters with verified post-consumer cullet integration and carbon accounting systems for EU Green Deal compliance. Long-term viability across the next decade hinges on reverse logistics infrastructure ownership rather than pure production scale. Acquisition targets should display embedded collection-network assets and ANVISA certification completion. The signal to watch is Mercosur capital legislation advancing refillable bottle mandates that would accelerate pooling system deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Logistics Infrastructure Buildout | Converters owning collection networks capture volume commitments from Mexican beer and soft drink bottlers. |
| ANVISA ERP System Upgrade | Batch-level genealogy documentation separates compliant pharmaceutical suppliers from excluded competitors. |
| Direct-to-Brewer Contracting Model | Craft spirits producers in Jalisco negotiate dedicated furnace allocation bypassing distributor intermediaries. |
| Post-Consumer Cullet Integration | Verified carbon accounting systems satisfy EU Green Deal supply chain audit requirements for export access. |
| Specialized Mold Engineering Capability | Decorative finishing expertise commands premium pricing from tequila premiumization corridor producers. |
Research Methodology
A standing panel of furnace operations directors, pharmaceutical packaging procurement managers, craft spirits brand owners, and ANVISA regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data for soda ash and cullet flows, ANVISA resolution filings and compliance bulletins, SEC 10-K disclosures from listed packaging converters, and beverage industry association production statistics. Bottom-up furnace capacity modeling triangulated against top-down end-use demand aggregation across the analysis window.
Scenario-bracketing around energy cost volatility and regulatory compliance timeline uncertainty framed the analytical approach. Segmentation dimensions modeled include product type, end-use industry, capacity tier, and distribution channel structure throughout the forecast period. CAGRs derived from production volume trends weighted by regional natural gas pricing differentials and ANVISA certification penetration rates. Industry-specific forecast inputs incorporated Mercosur legislative tracking for refillable mandate proposals and EU Green Deal audit implementation schedules.
Sensitivities concentrate around LNG benchmark price spikes, ANVISA resolution enforcement timing, and Mercosur capital legislative outcomes for refillable systems. Forecasts reflect documented assumptions regarding furnace rebuild cycles and craft spirits volume trajectories. Material shifts in natural gas import pricing regimes or accelerated EU supply chain audit requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Australia Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
France Container Glass Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Boston Round Glass Bottle Market