
 Europe Glass Bottles and Containers Market | 2026-2036
Europe Glass Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glass Bottles and Containers Market Foresight
Subscription-based container pooling and fleet management is pivoting how glass packaging gets sold across Europe, shifting capital burden from brand owners to logistics operators. Gerresheimer AG leverages its pharmaceutical-grade borosilicate expertise to dominate high-barrier drug delivery segments. Stölzle Glass Group sustains artisanal positioning across premium spirits while competing on furnace efficiency at its Austrian and Czech plants. Verallia Group anchors volume supply through its French and Italian production network, extending reuse-ready formats to major beverage clients.
Europe glass bottles and containers are rigid, chemically inert vessels formed from silica sand, soda ash, and limestone melted at approximately 1,500°C, primarily designed to preserve product integrity across food, beverage, pharmaceutical, and cosmetic supply chains. Wine bottles occupy the largest product-type position, reflecting entrenched Old World viticulture infrastructure and export-oriented bottling economics. Cosmetic bottles represent the fastest-growing structural segment, propelled by personal-care brands replacing plastic with amber and cobalt glass for shelf differentiation and regulatory compliance. Blow molding dominates manufacturing-stage output, though handcrafted methods retain margin concentration in limited-edition spirits and apothecary positioning.
EU Green Deal targets and the Packaging and Packaging Waste Regulation are mandating minimum recycled content thresholds and extended producer responsibility schemes, directly reshaping furnace feedstock sourcing and collection infrastructure investments across member states. ECHA REACH compliance governs chemical safety in decorative coatings and closures, while CE marking ensures mechanical performance standards for pharmaceutical and food-contact applications. Stakeholders must monitor how the EU AI Act and digital product passport requirements will reshape traceability obligations and quality verification workflows across multi-country supply networks.
Market Dynamics
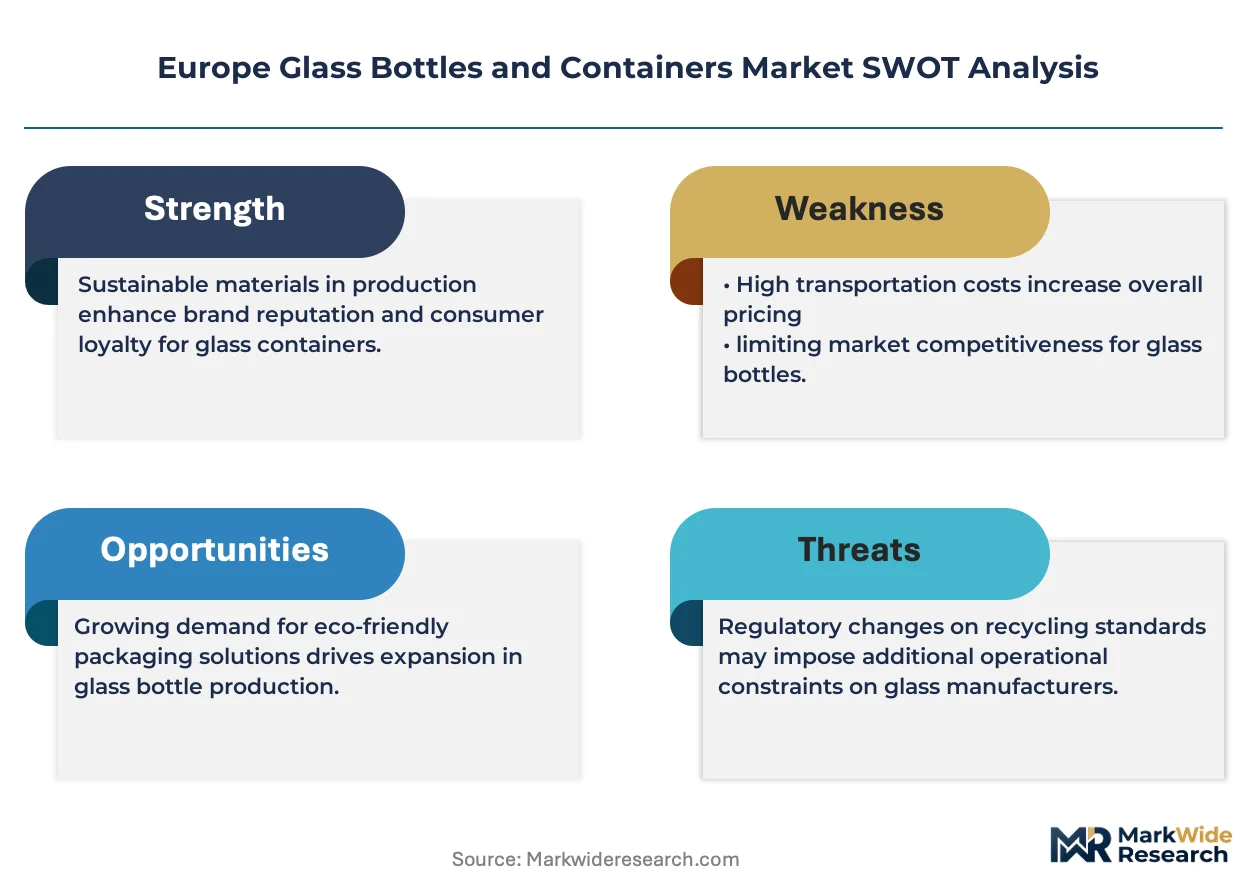
The EU Green Deal and revised Packaging and Packaging Waste Regulation are forcing furnace operators to reconfigure feedstock sourcing around minimum recycled content thresholds, compressing margins for plants unable to secure quality cullet streams at scale.
Growth Catalysts
- EU Green Deal mandates:Binding recycled content thresholds for glass packaging are pulling investment toward furnace upgrades and collection infrastructure across member states.
- Premium beverage commitments:Wine and spirits producers in France and Germany are expanding long-term glass supply contracts to secure circular, refillable formats.
- Pharmaceutical barrier demand:Borosilicate glass is capturing share in drug delivery systems requiring thermal shock resistance and chemical inertness.
Market Restraints
- Natural gas cost volatility:Furnace operations depend on natural gas feedstock, exposing margins to price spikes from Norwegian and Algerian supply disruptions.
- Cullet quality scarcity:High-purity recycled glass feedstock concentrates in Germany and France, leaving southern European plants dependent on virgin batch.
- Lightweighting limits:Mechanical performance standards for wine bottles and pharmaceutical vials impose floor thickness requirements that resist material reduction.
Strategic Opportunities
- Digital product passport integration:The EU AI Act and traceability mandates are creating first-mover advantage for suppliers embedding RFID and blockchain verification into container fleets.
- Cosmetic amber glass expansion:Personal-care brands in Italy and Spain are replacing plastic with cobalt and amber glass for shelf differentiation and REACH compliance.
- Subscription pooling models:Logistics operators are capturing capital burden from brand owners through container-as-a-service platforms managing refillable bottle fleets.
Industry Challenges
- Furnace engineer scarcity:Specialized glass-melting expertise concentrates among aging workforces in Bohemia and Murano, constraining plant expansion timelines.
- CE marking certification delays:Pharmaceutical and food-contact applications face extended approval cycles under EFSA and national competent authority review.
- Legacy system integration:Digital product passport requirements are forcing mid-sized producers to retrofit traceability onto decades-old batch control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glass Bottles and Containers Market |
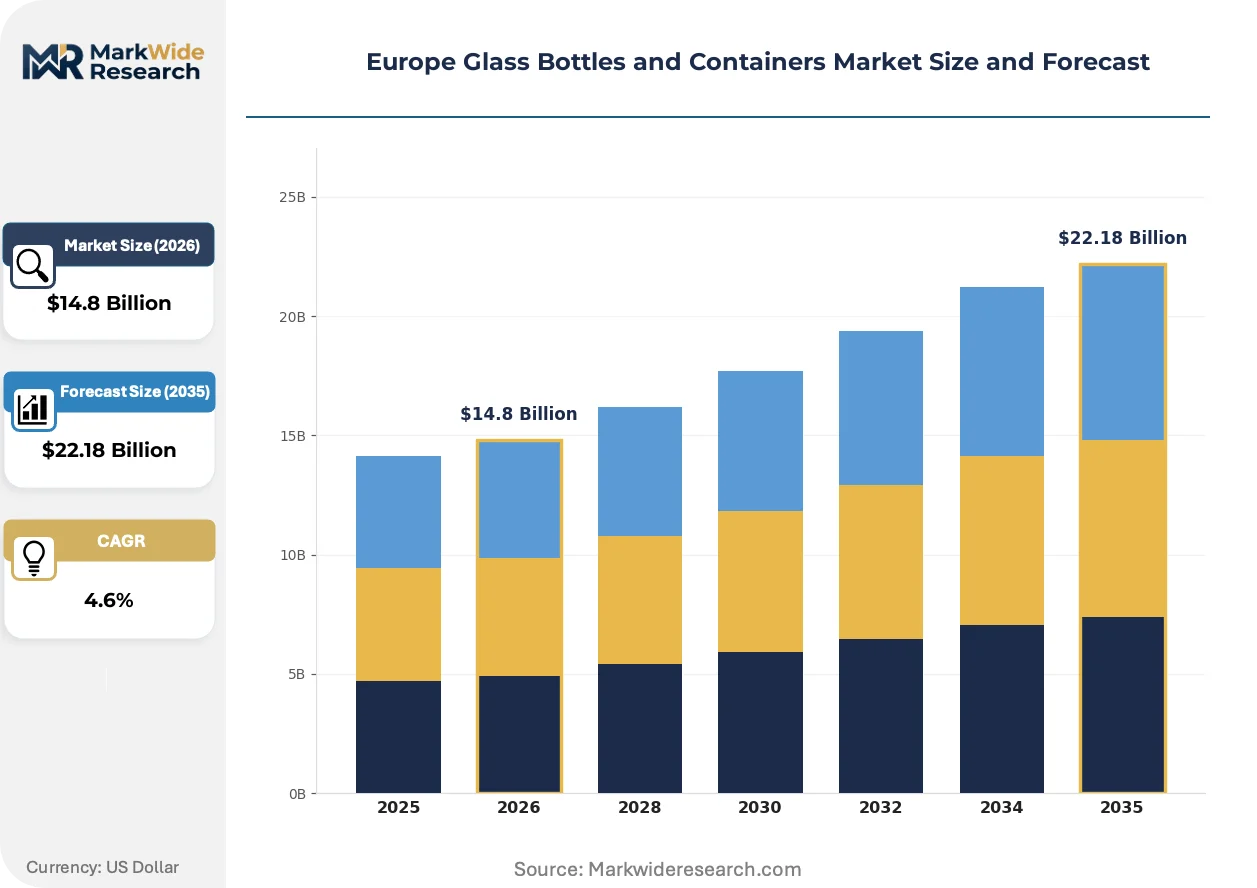
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wine Bottles, Beverage Containers, Food Jars, Cosmetic Bottles End Use: Food Industry, Beverage Industry, Personal Care, Pharmaceuticals Manufacturing Stage: Blow Molding, Pressing, Machine Forming, Handcrafted Capacity: 300ml, 500ml, 750ml, 1L |
| Companies Covered | Gerresheimer AG, Stölzle Glass Group, Verallia Group, Vetropack Group, Schott AG, O-I Glass, Vidrala, Berlin Packaging, Ardagh Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glass Bottles and Containers Market Shifts & Advancements
Electrification of melting technology, regulatory digitization of supply chains, and the rise of circular service models are compressing traditional ownership structures across European glass packaging.
Hybrid oxy-fuel electric melting is unifying thermal efficiency with grid-responsive operations. Furnace operators in Austria and the Czech Republic are retrofitting plants to enable demand-side electricity management. This technology is unifying decarbonization targets with operational cost control across premium spirits bottling corridors.
The EU Packaging and Packaging Waste Regulation is mandating extended producer responsibility schemes and deposit-return systems. Member states must implement harmonized collection infrastructure by statutory deadlines. Wine and spirits bottlers in France and Italy are restructuring supply contracts to internalize end-of-life costs.
Refillable container pooling is displacing single-use ownership in on-premise beverage service. German and Dutch hospitality operators are contracting with logistics platforms for fleet-managed glass return systems. This shift concentrates most visibly in urban beer and mineral water dispensing networks where transport density supports circular economics.
Europe Glass Bottles and Containers Market Segmentation
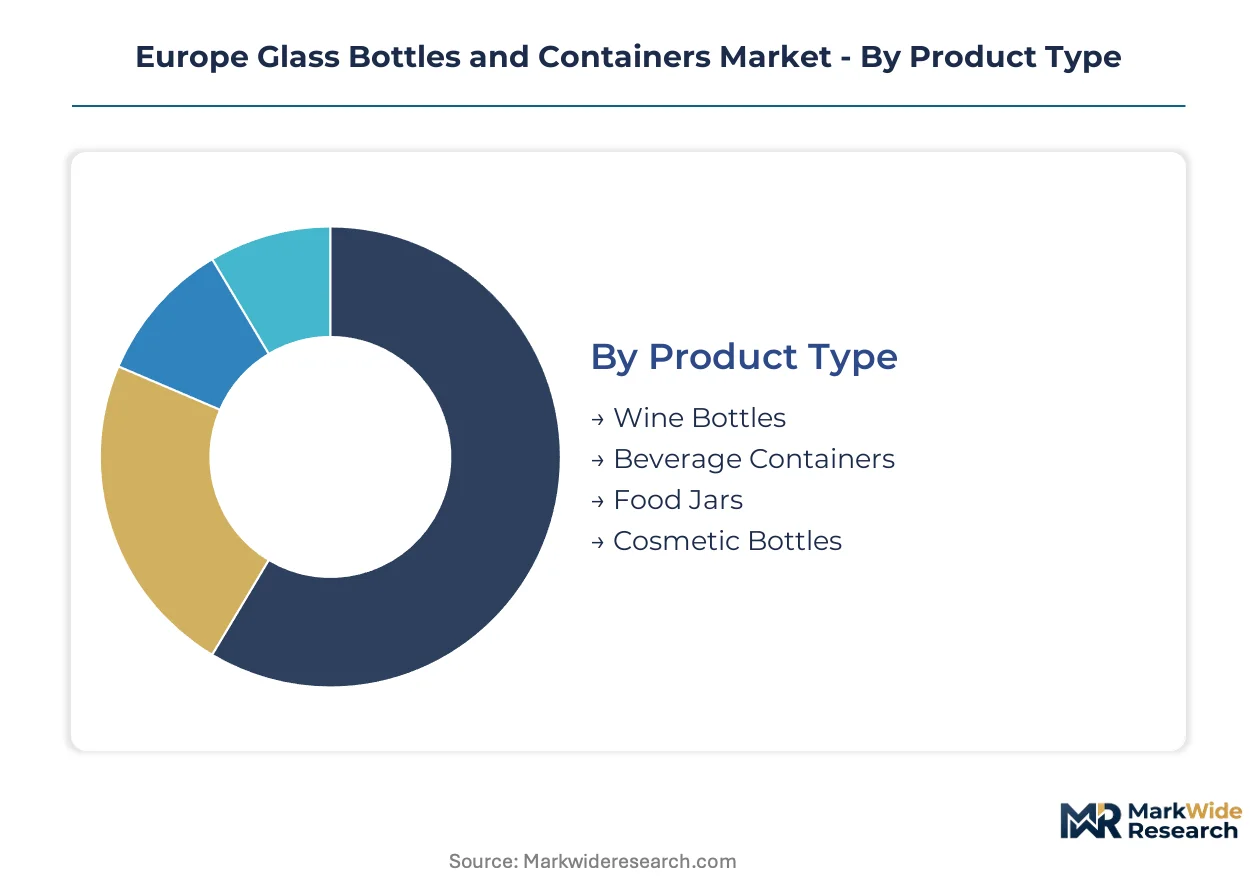
Glass packaging economics across Europe diverge sharply by product geometry and end-use performance requirements. Furnace operators configure batch chemistry and forming equipment around segment-specific thermal profiles and barrier specifications.
Product Type:
Wine bottles concentrate furnace capacity in France, Italy, and Spain, where Old World viticulture infrastructure anchors volume demand.
- Wine Bottles:Heavy-wall bordeaux and burgundy formats dominate export-oriented bottling corridors. French cooperatives and Italian consorzi negotiate multi-year supply contracts specifying minimum 85% recycled content under EU Green Deal thresholds.
- Cosmetic Bottles:Amber and cobalt glass variants are expanding fastest as Italian and Spanish personal-care brands replace plastic for shelf differentiation and REACH compliance. Smaller furnace batches and decorative coating capabilities command premium positioning.
- Beverage Containers:Standard beer and mineral water formats serve high-velocity filling lines across German and Dutch brewing networks.
- Food Jars:Wide-mouth preserving and sauce containers leverage thermal shock resistance for hot-fill pasteurization in Central European processing plants.
Today's leader: Wine Bottles. Tomorrow's challenger: Cosmetic Bottles.
End Use:
Cost tier stratification separates commodity beverage filling from pharmaceutical barrier applications requiring borosilicate expertise.
- Pharmaceuticals:Borosilicate glass vials and ampoules demand thermal shock resistance and chemical inertness for injectable drug delivery. Gerresheimer AG and Schott AG anchor supply through German and Swiss manufacturing sites.
- Beverage Industry:Wine, spirits, and mineral water bottlers in France, Germany, and Italy drive volume demand. Deposit-return systems in Germany and the Netherlands concentrate return logistics around refillable formats.
- Food Industry:Preserving jars and condiment containers serve thermal processing requirements across Spanish and Polish agri-food clusters.
- Personal Care:Premium fragrance and skincare brands in France and Italy specify decorative coatings and custom colors for shelf differentiation.
Pharmaceuticals command the highest unit margins. Personal Care is climbing the fastest on plastic substitution trends.
Manufacturing Stage:
Volume application dictates forming method selection, with blow molding capturing throughput and handcrafted retaining artisanal positioning.
- Blow Molding:Automated IS machine production dominates wine and beverage container output. Czech and Austrian plants compete on furnace efficiency and lightweighting precision.
- Handcrafted:Limited-edition spirits and apothecary positioning in Murano and Bohemia sustain margin concentration through decorative techniques and small-batch color formulas.
- Pressing:Wide-mouth jars and cosmetic compacts leverage mechanical strength for closure torque requirements.
- Machine Forming:Intermediate automation serves mid-volume pharmaceutical and food segments requiring dimensional consistency.
Blow Molding holds volume dominance. Handcrafted defends premium pricing through scarcity economics.
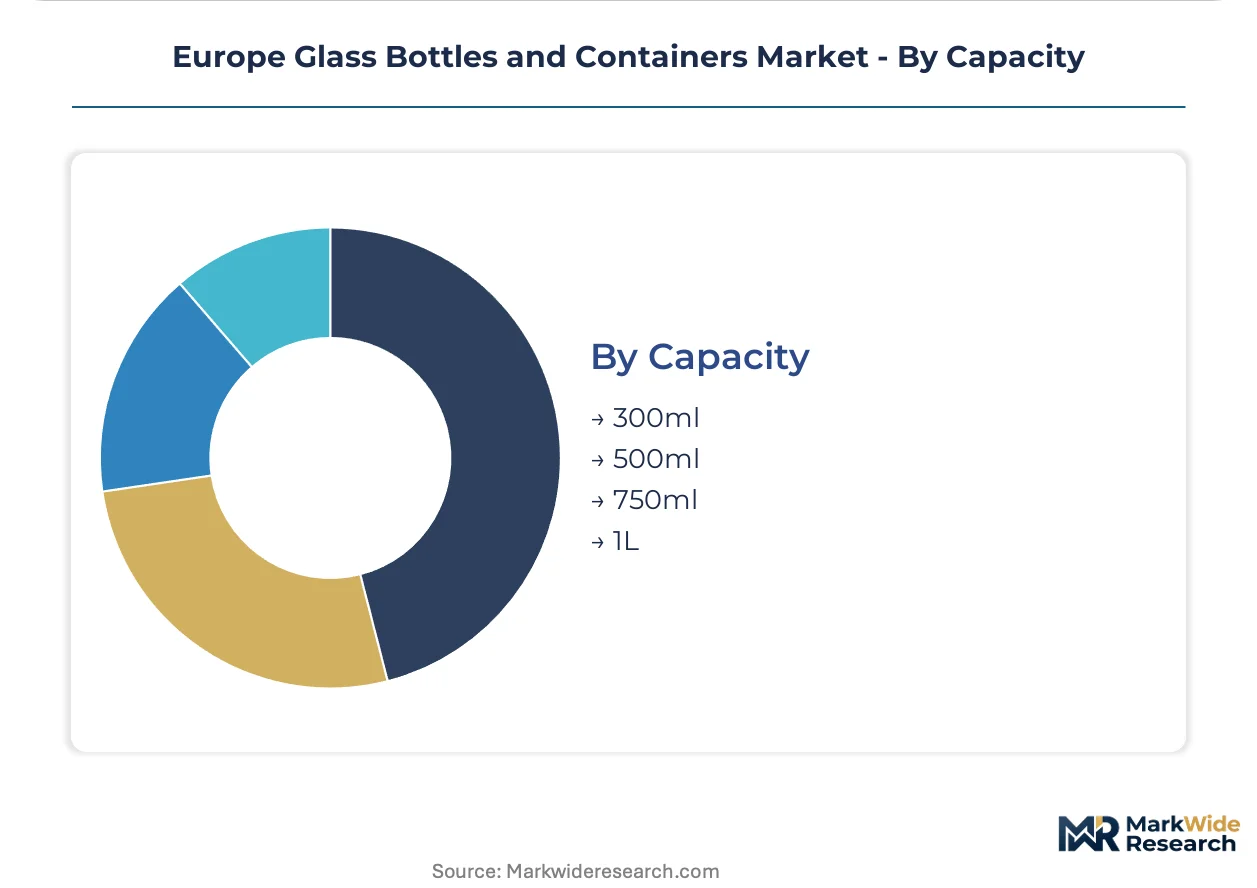
Capacity:
Customer type segmentation separates on-premise dispensing from retail shelf formats, with standard wine and spirits sizes anchoring procurement patterns.
- 750ml:The standard wine bottle format aligns with global trade conventions and ocean freight palletization. French and Italian exporters specify this capacity for transatlantic and Asian market access.
- 500ml:Beer and mineral water refillable formats dominate German and Dutch deposit-return systems. Logistics operators optimize fleet pooling around this transport-efficient geometry.
- 300ml:Single-serve beverage and cosmetic trial sizes serve hospitality and sampling channels.
- 1L:Family-size preserving jars and bulk spirits formats serve retail and food-service segments.
750ml commands procurement scale. 500ml is expanding most quickly on circular service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade borosilicate capacity while France anchors wine bottle export corridors, creating divergent furnace feedstock demands across Western Europe.
Germany
Beverage deposit-return systems and pharmaceutical barrier requirements drive dual demand streams. The EU Green Deal mandates 70% recycled content thresholds for glass packaging by 2030. North Rhine-Westphalia hosts furnace clusters retrofitting for hybrid oxy-fuel electric melting to manage grid-responsive operations.
France
Wine export bottling and luxury spirits positioning sustain premium format demand. Extended producer responsibility schemes under the revised Packaging and Packaging Waste Regulation reshape supply contract economics. The Champagne-Ardenne corridor concentrates cooperative bottling infrastructure serving transatlantic and Asian markets.
Italy
Cosmetic amber glass substitution and traditional viticulture create mixed furnace batch requirements. REACH compliance governs decorative coatings for personal-care applications. Murano and Tuscany maintain artisanal handcrafted capacity alongside industrial IS machine production in Emilia-Romagna.
Spain
Agri-food preserving jars and bulk wine bottling serve distinct thermal processing needs. National implementation of EU collection infrastructure targets lags northern neighbors, constraining cullet quality access. Catalonia and La Rioja anchor volume production for export-oriented cooperatives.
Netherlands
Refillable mineral water and beer logistics platforms pioneer container-as-a-service models. The EU AI Act traceability requirements intersect with digital product passport pilots in Rotterdam port corridors. Randstad logistics operators optimize fleet pooling around 500ml transport-efficient geometries.
Europe Glass Bottles and Containers Market Competitive Landscape
Top-tier vendors anchor pharmaceutical and premium beverage supply, while mid-scale specialists defend regional beverage and food jar positions. The market structures around furnace scale economies and batch chemistry expertise rather than brand recognition. Three archetypes dominate: pharmaceutical barrier specialists, premium spirits artisans, and volume beverage contractors. Competitive moves concentrate on furnace electrification partnerships and refillable fleet management alliances.
Among Germany-based AG-structured manufacturers, Gerresheimer AG and Schott AG exemplify pharmaceutical barrier specialization, while Verallia Group represents volume beverage contracting across French and Italian production networks. These three occupy positions defined by end-use certification requirements and furnace scale rather than geographic coverage alone.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Stölzle Glass Group |
| Verallia Group |
| Vetropack Group |
| Schott AG |
| O-I Glass |
| Vidrala |
| Berlin Packaging |
| Ardagh Group |
| Others |
Supply & Pricing Matrix
Natural gas feedstock costs cascade through furnace operations in Germany and the Czech Republic, compressing margins at virgin-batch plants while hybrid electric retrofits in Austria command premium pricing tiers for carbon-responsive buyers.
Pricing Analysis
Capacity additions in France and Italy are reshaping price floors for wine bottle contracts as Verallia and regional cooperatives expand furnace output. Three-tier pricing structure across premium borosilicate pharmaceutical grades, standard beverage formats, and economy food jars separates buyers by certification intensity and volume scale. Pricing pressure stems from cullet quality scarcity in southern Europe, forcing Spanish plants to absorb virgin batch premiums. Commodity beverage bottlers exhibit highest price sensitivity, while pharmaceutical barrier buyers accept sustained premiums for thermal shock certification.
Supply Chain Analysis
Silica sand supply rests on German and Belgian quarry operations, while soda ash concentrates in Bulgarian and Romanian chemical complexes. High-purity limestone feeds from French and Italian deposits anchor batch chemistry for premium spirits and pharmaceutical applications. Single-source vulnerability runs through Algerian natural gas corridors that fuel furnace operations across southern European plants. Distribution runs through cooperative bottling networks in Champagne-Ardenne and logistics pooling platforms in the Randstad corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Divergent recycled content mandates between Germany's 70% threshold and Spain's lagging implementation create arbitrage opportunities for cullet traders and furnace operators repositioning batch sourcing across borders.
For Market Incumbents: Extend hybrid oxy-fuel electric furnace partnerships in Austria and North Rhine-Westphalia to defend against natural gas price volatility and emerging lightweighting competitors from Asia. Deepen backward integration into cullet collection infrastructure in France and Germany to secure quality feedstock streams ahead of EU Green Deal threshold enforcement. Lock long-term supply contracts with premium wine cooperatives before deposit-return system expansion reshapes contract economics. For New Entrants and Emerging Players: Launch via container-as-a-service logistics platforms targeting Dutch and German hospitality refillable networks where transport density supports circular unit economics. Penetrate cosmetic amber glass segments in Italy and Spain where personal-care plastic substitution outpaces incumbent furnace batch flexibility. Pursue white-label pharmaceutical borosilicate supply agreements with mid-tier drug delivery device manufacturers seeking second-source security. For Investors and Strategic Acquirers: Consolidation pressure builds where furnace engineer scarcity in Bohemia and Murano constrains plant expansion timelines for independent operators. Five-to-ten-year viability favors acquiring mid-scale beverage contractors with unretrofitted natural gas exposure that can be converted to grid-responsive electric melting. Watch German implementation deadlines for digital product passport requirements as the inflection signal for traceability technology acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Partnership | Hybrid oxy-fuel retrofits in Austria and Czech plants align decarbonization with grid-responsive cost control. |
| Cullet Collection Infrastructure Investment | Backward integration into German and French recycling networks secures quality feedstock ahead of threshold mandates. |
| Digital Product Passport Integration | RFID and blockchain verification embedded in container fleets captures first-mover advantage under EU AI Act traceability rules. |
| Refillable Fleet Management Alliance | Logistics operators in Randstad and Rhine-Ruhr corridors capture capital burden from brand owners through subscription pooling. |
| Cosmetic Amber Glass Capacity Expansion | Smaller batch furnace output in Italy and Spain serves REACH-compliant personal-care brands replacing plastic packaging. |
Research Methodology
Bottom-up beverage and pharmaceutical modeling reconciled against top-down furnace capacity and cullet flow tracking forms the analytical core of this study. Primary fieldwork incorporated furnace operations managers at Austrian and Czech plants, procurement leads at French wine cooperatives, logistics directors at Dutch container pooling platforms, and regulatory affairs specialists navigating ECHA REACH compliance. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, Eurostat trade flow databases, ECHA substance registry filings, and national competent authority circular economy reports.
Historical production volume trendlines across French, Italian, and German furnace corridors established baseline growth patterns extended through the projection horizon. Segmentation modeling captured product type geometry, end-use barrier requirements, manufacturing stage automation levels, and capacity format specifications. CAGRs derived from weighted capacity utilization rates, recycled content threshold compliance timelines, and premium beverage contract renewal cycles. Forecast inputs incorporated natural gas price volatility scenarios and deposit-return system expansion schedules across member states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Algerian supply disruption or accelerated EU AI Act enforcement. Projections reflect documented assumptions regarding furnace retrofit adoption curves and cullet quality availability gradients. A small set of triggers—German digital product passport pilot results, French extended producer responsibility tariff levels, and Czech hybrid melting technology performance data—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Beveled Edge Jars Market