
 Belarus Container Glass Market | 2026-2036
Belarus Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Belarus Container Glass Market Insights
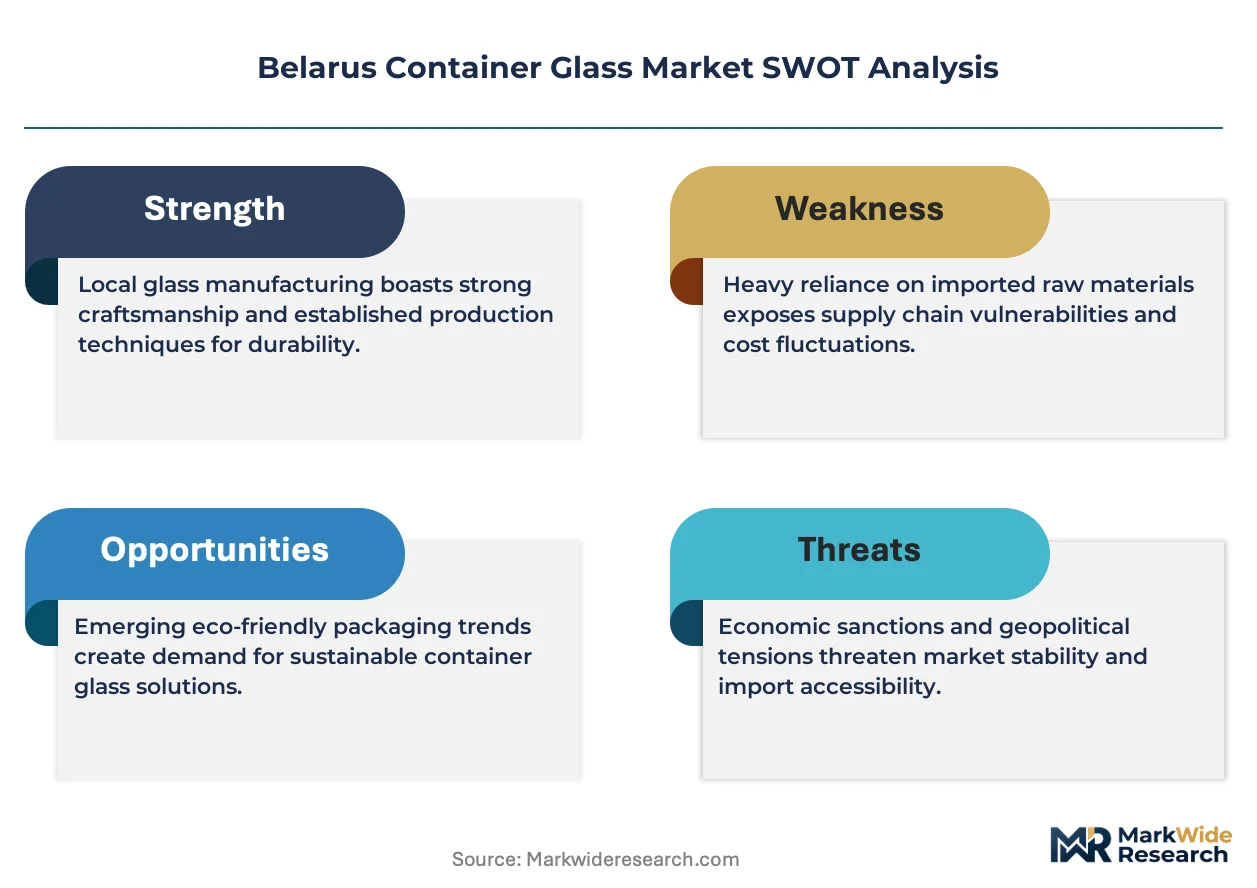
Aftermarket service revenue for mold refurbishment and furnace relining is fragmenting across Belarus as container glass producers seek to reduce capital intensity. Gomel Glass leverages its southeastern location to anchor supply for regional beverage distilleries. Belglass sustains furnace efficiency through proprietary batching recipes that lower energy draw per ton. Brestglass competes on specialty colored glass for premium cosmetic brands.
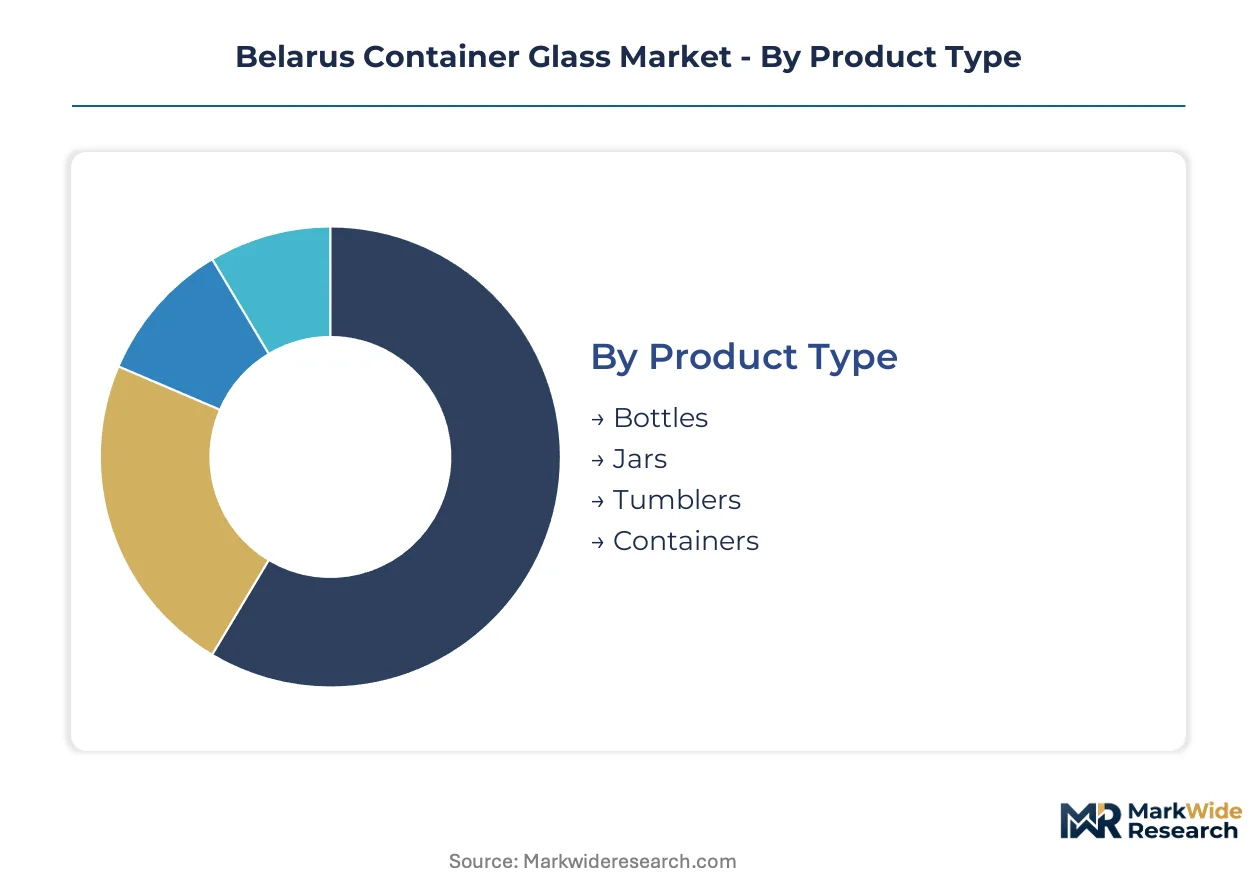
Container glass denotes soda-lime silica glassware formed by blow-and-blow or press-and-blow methods, typically containing 70% silica, 12% soda ash, and 10% lime, engineered to withstand internal pressures up to 20 bar for carbonated liquids. Bottles command the largest product type position due to entrenched demand from Belarusian vodka and beer exporters. Jars represent the fastest-growing category as domestic food preservation and pickling traditions sustain household and artisanal procurement. Surface treatment capabilities differentiate margin pools, with anti-abrasion coatings and organic lubricants commanding premium placement in pharmaceutical and cosmetic end-user segments.
The national standards body enforces GB-equivalent technical regulations for glass contact materials, while the country's pharmaceutical regulator mandates compliance with European Pharmacopoeia container standards for drug packaging. These frameworks elevate capital requirements for new entrants and push incumbent producers toward automated quality control systems. Stakeholders must monitor whether Eurasian Economic Union harmonization deepens technical barriers or opens cross-border certification reciprocity for Belarusian exporters.
Market Dynamics
Belarusian container glass producers face intensifying pressure from Eurasian Economic Union technical harmonization, which simultaneously opens export corridors and elevates compliance burdens for cross-border shipments. This regulatory convergence is compressing margins while forcing furnace upgrades and automated inspection investments across Minsk industrial clusters.
Growth Catalysts
- Pharmaceutical-grade mandates:The country's pharmaceutical regulator enforces European Pharmacopoeia container standards, compelling domestic drug packagers to source certified amber glass locally rather than import.
- Regional beverage export expansion:Belarusian vodka and beer bottlers in the Minsk metropolitan zone are scaling flint and amber glass orders to supply EAEU duty-free markets.
- Specialty surface treatments:Anti-abrasion coatings and organic lubricants for pharmaceutical and cosmetic segments command premium placement, differentiating margin pools for converters with treatment capabilities.
Market Restraints
- Natural gas cost volatility:Furnace operations depend on Russian pipeline supply, exposing producers to input energy price swings that erode per-ton economics.
- Batch material import concentration:High-purity silica sand and soda ash sourcing concentrates through limited cross-border suppliers, creating supply vulnerability.
- Substitution by PET and aluminum:Carbonated beverage packagers in cost-sensitive segments are pivoting to lighter-weight alternatives for logistics efficiency.
Strategic Opportunities
- Gomel regional anchoring:Southeastern production sites can capture distillery demand from regional beverage clusters underserved by Minsk-centric supply.
- Cosmetic premiumization:Specialty colored glass for premium cosmetic brands offers margin expansion as Brestglass and competitors develop custom hue capabilities.
- EAEU certification reciprocity:Harmonized technical regulations may enable Belarusian producers to displace Western suppliers in Russian and Kazakh pharmaceutical packaging tenders.
Industry Challenges
- Furnace refractory skill scarcity:Mold refurbishment and furnace relining expertise is fragmenting across aftermarket service providers, complicating maintenance scheduling.
- Automated quality control capex:Compliance with tightened national standards body protocols demands machine vision and laser inspection investments that strain mid-cap balance sheets.
- Legacy batching system integration:Proprietary energy-efficient recipes require retrofitting older furnace control architectures without disrupting continuous production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belarus Container Glass Market |
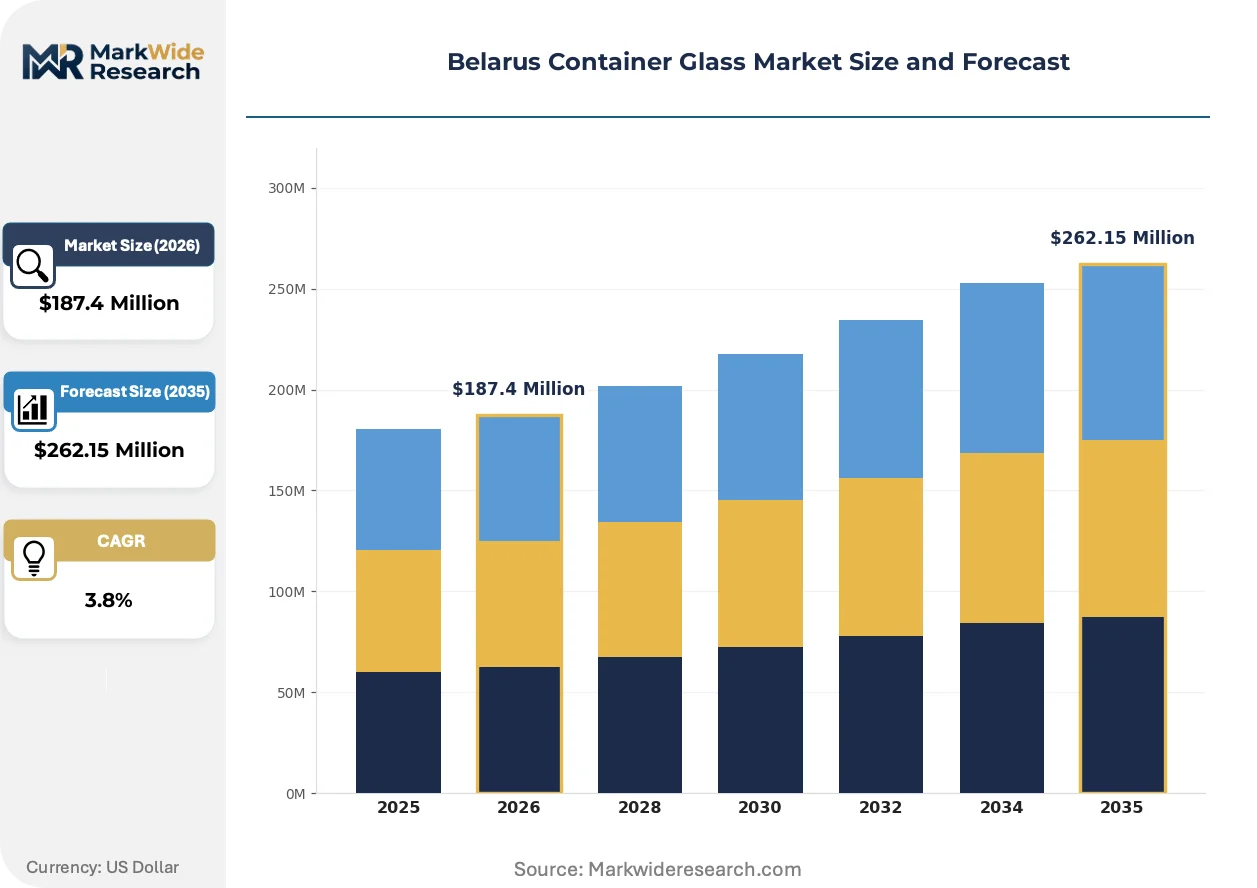
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Tumblers, Containers End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Capacity: Small, Medium, Large, Extra Large Manufacturing Stage: Fabrication, Annealing, Surface Treatment, Quality Control |
| Companies Covered | Gomel Glass, Belglass, Brestglass, Glass Factory Elizovo, Yelizovo Glass Plant, Minsk Crystal Group, Glass Factory Yelizovo, Borisov Glassworks, Polotsk Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belarus Container Glass Market Trends and Innovations
Digital instrumentation and regulatory convergence are compressing quality assurance timelines while reshaping how Belarusian converters compete for pharmaceutical and premium beverage contracts. These shifts favor producers with capital reserves for automation and certification depth.
Machine vision inspection systems is digitizing defect detection on Belarusian container glass lines. Pharmaceutical packagers in the Minsk industrial zone are adopting these systems at accelerated pace to satisfy European Pharmacopoeia batch documentation requirements. This compression of quality assurance cycles is eliminating manual sampling protocols and raising barriers for producers without automated infrastructure.
The Eurasian Economic Union's technical regulation harmonization is mandating unified container contact-material standards across member states. Belarusian producers must now certify products for multi-jurisdiction acceptance, elevating documentation burdens but enabling single-facility supply to Russian and Kazakh markets. Pharmaceutical-grade amber glass manufacturers are responding by consolidating certification workflows under unified quality management systems.
Aftermarket service unbundling is separating mold refurbishment from furnace maintenance contracts across Belarusian producers. Container glass converters in the Minsk metropolitan area are sourcing these services from independent specialists rather than captive shops, reducing capital intensity but fragmenting vendor accountability. This disaggregation is most visible among mid-cap producers seeking to preserve liquidity for core furnace investments.
Belarus Container Glass Market Segmentation
Segmentation in the Belarus container glass market reveals how furnace configurations, quality tiers, and end-use specifications determine converter profitability. Each dimension shapes capital allocation decisions across Minsk industrial clusters and regional production sites.
Product Type:
Cost tier differentiation separates commodity volume plays from specialty margin pools across Belarusian converter portfolios.
- Bottles:Soda-lime silica vessels engineered to withstand internal pressures up to 20 bar for carbonated liquids. Demand concentrates among Minsk metropolitan vodka and beer exporters sourcing flint and amber glass for EAEU duty-free markets.
- Jars:Wide-mouth containers with thicker heel sections for vacuum-sealed food preservation. Domestic pickling traditions and artisanal food processors in the Gomel region sustain procurement volumes.
- Tumblers:Straight-sided drinking vessels with reinforced rims for hospitality and retail channels. Belarusian household goods distributors stock standard capacities for mass-market placement.
- Containers:Multi-purpose rectangular and cylindrical forms for industrial and specialty chemical packaging. Pharmaceutical-grade variants require European Pharmacopoeia certification for drug contact applications.
Bottles commands the established base. The steepest expansion runs through Jars.
End User:
Application-specific quality mandates fragment production workflows and certification burdens across Belarusian glassworks.
- Food & Beverage:Carbonated and still liquid packaging dominates tonnage throughput. Regional distillery clusters in Gomel and Brest anchor demand for amber and flint glass with standard surface treatments.
- Pharmaceuticals:Amber glass for light-sensitive drug formulations demands European Pharmacopoeia compliance and automated batch documentation. The national pharmaceutical regulator mandates these standards, compelling local sourcing over imports.
- Cosmetics:Premium brands in the Minsk zone commission specialty colored glass from Brestglass and competitors. Custom hue capabilities and anti-abrasion coatings command placement premiums.
- Household:Standard ware for food preservation and table service. Price-sensitive procurement favors basic annealing without surface modification.
Food & Beverage captures the volume anchor. The fastest share gains are occurring in Pharmaceuticals.
Capacity:
Volume tier segmentation aligns furnace batch economics with end-use logistics requirements and filling line specifications.
- Small:Single-serve and sample formats for cosmetics and pharmaceutical trial packaging. Premium positioning offsets higher per-unit forming costs.
- Medium:Standard household and food service containers. This tier balances furnace efficiency with distribution palletization norms across Belarusian logistics corridors.
- Large:Family-size and food-service formats for regional beverage and pickle producers. Gomel Glass anchors supply for distillery demand in this range.
- Extra Large:Bulk industrial and institutional containers. Limited production runs require dedicated mold sets and extended annealing cycles.
Medium capacity holds the production center of gravity. The most rapid demand shift is toward Small formats.
Manufacturing Stage:
Process step segmentation determines where automation investments and quality control capex concentrate across Belarusian facilities.
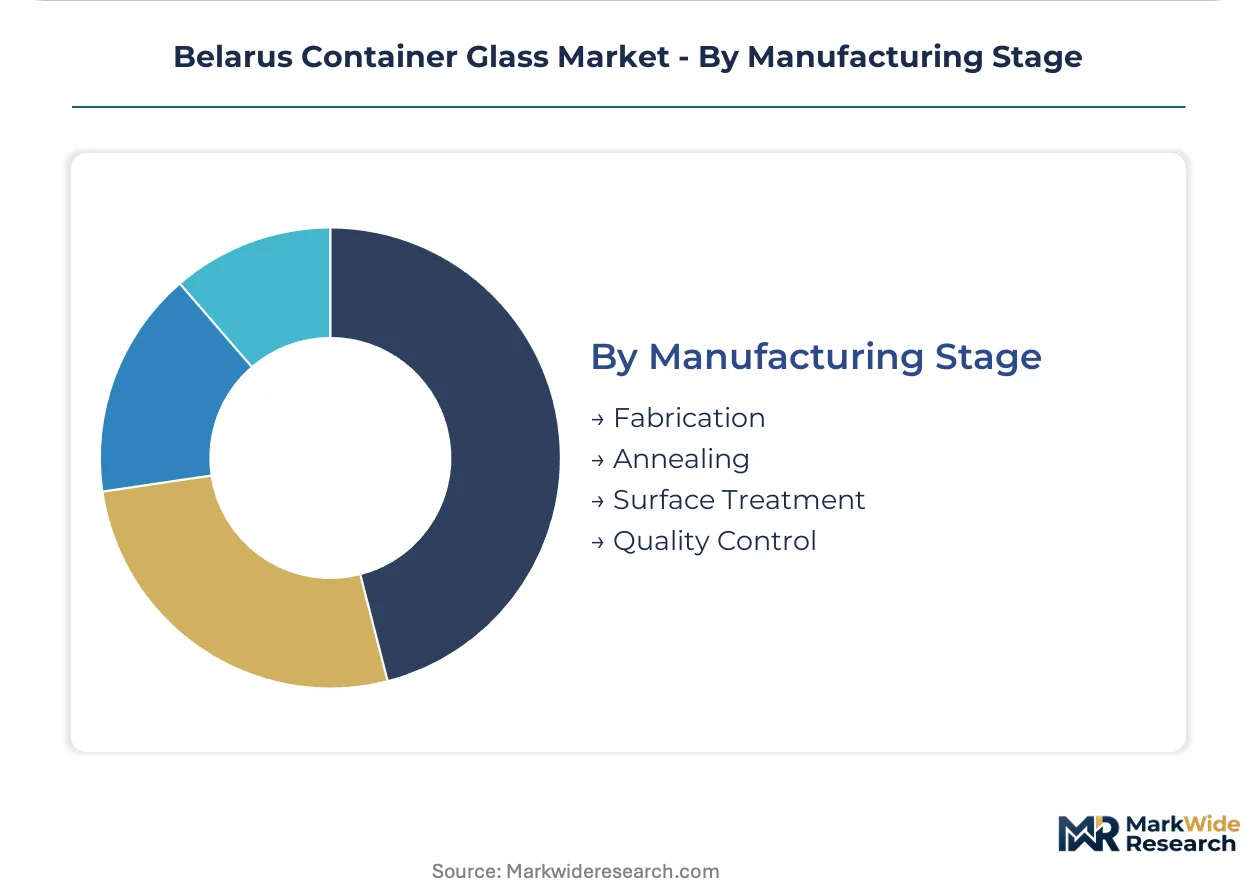
- Fabrication:Blow-and-blow or press-and-blow forming of molten glass into parisons and finished shapes. Proprietary batching recipes at Belglass lower energy draw per ton during this phase.
- Annealing:Controlled cooling through lehr tunnels to relieve thermal stress. Legacy furnace architectures require retrofitting to maintain continuous production cycles during upgrades.
- Surface Treatment:Anti-abrasion coatings and organic lubricant application for pharmaceutical and cosmetic segments. This stage commands premium placement and differentiates margin pools for converters with treatment capabilities.
- Quality Control:Machine vision and laser inspection systems for defect detection. Pharmaceutical packagers adopt these at accelerated pace to satisfy tightened national standards body protocols.
Fabrication absorbs the dominant capital share. The most intensive capability buildup is happening in Quality Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Belarus diverge sharply between the Minsk metropolitan industrial zone and southeastern distillery corridors, with pharmaceutical-grade amber glass concentrating in the capital region while food preservation jars dominate household procurement in provincial markets.
Minsk Region
Pharmaceutical packaging and premium beverage bottling anchor demand in this central industrial zone. The national standards body enforces tightened quality protocols for drug-contact containers, compelling local sourcing over imports. Machine vision inspection systems are proliferating across Minsk industrial clusters as packagers automate quality documentation.
Gomel Region
Regional beverage distilleries in this southeastern zone sustain procurement of amber and flint glass for vodka and beer exports. The Eurasian Economic Union's duty-free market access incentivizes capacity expansion near these production clusters. Gomel Glass leverages its location to anchor supply for underserved regional demand.
Brest Region
Specialty colored glass for premium cosmetic brands differentiates output from western Belarusian facilities. European Union proximity shapes compliance expectations for cross-border cosmetic shipments. Brestglass competes on custom hue capabilities and anti-abrasion surface treatments.
Vitebsk Region
Polotsk Glass anchors container supply for northern Belarusian food processors and household goods distributors. Domestic pickling traditions sustain jar procurement volumes across this agricultural zone. Legacy furnace architectures here face retrofitting pressure to meet national energy efficiency mandates.
Mogilev Region
Borisov Glassworks serves central-eastern demand for standard ware and industrial chemical containers. Batch material logistics concentrate through cross-border suppliers accessing this corridor. Furnace refractory skill scarcity complicates maintenance scheduling for mid-cap producers in this zone.
Belarus Container Glass Market Competitive Landscape
Capability concentration sits with specialty treatment providers; scale advantage sits with furnace operators serving commodity beverage segments. The Belarusian container glass sector structures around three tiers: integrated furnace operators with proprietary batching recipes, regional specialists anchoring geographic demand pockets, and surface treatment converters capturing pharmaceutical and cosmetic premiums. Competitive moves center on automated quality control capex for regulatory compliance and aftermarket service unbundling to preserve liquidity.
Among Belarus-based integrated producers, Gomel Glass, Belglass, and Brestglass occupy distinct positioning vectors. Gomel Glass exemplifies the regional anchoring archetype, securing southeastern distillery demand through proximity advantage. Belglass represents the efficiency-driven furnace operator tier, sustaining throughput through proprietary energy formulations. Brestglass sits within the specialty converter category, differentiating on colored glass capabilities for premium cosmetic clients.
| Leading Market Players |
|---|
| Gomel Glass |
| Belglass |
| Brestglass |
| Glass Factory Elizovo |
| Yelizovo Glass Plant |
| Minsk Crystal Group |
| Glass Factory Yelizovo |
| Borisov Glassworks |
| Polotsk Glass |
| Others |
Pricing and Supply Chain Analysis
Russian natural gas pipeline concentration into Belarusian furnace operations anchors margin volatility downstream, forcing converters to absorb input swings or renegotiate beverage sector contracts. Pharmaceutical-grade amber glass commands placement premiums that insulate certified producers from commodity pricing cycles.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical and premium beverage procurement, locking in volume commitments against raw material indexation clauses. Three-tier pricing structure across European Pharmacopoeia-certified, national standard, and economy grades reflects compliance depth and surface treatment capabilities. Cost compression in commodity flint glass is intensifying because PET substitution threatens carbonated beverage contracts. Food processors in the Gomel region exhibit highest price sensitivity, while cosmetic brands in Minsk accept premiums for custom hue development.
Supply Chain Analysis
Tariff exposure between Russia and Belarusian batch material importers complicates soda ash and high-purity silica sand procurement. Sourcing concentrates through Russian and Ukrainian mineral processors, with limited alternative suppliers meeting pharmaceutical-grade specifications. Furnace refractory maintenance draws from a fragmenting aftermarket service base, creating single-source vulnerability for specialized mold refurbishment. Distribution runs through Minsk metropolitan logistics corridors to EAEU duty-free markets, with regional distilleries in Gomel and Brest served by dedicated fleet arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furnace refractory expertise and automated quality control engineering are narrowing faster than capital can remedy, compressing operational runway for mid-cap producers without captive technical depth.
For Market Incumbents: Pre-empt PET substitution in carbonated beverage packaging by deepening European Pharmacopoeia certification coverage and anchoring long-term supply agreements with Minsk pharmaceutical packagers. Automated inspection capex is the critical lever for defending margin pools against quality-sensitive import competitors. For New Entrants and Emerging Players: Establish a beachhead in specialty cosmetic glass through partnerships with Brest-region premium brands seeking custom anti-abrasion coatings. Gomel regional distillery demand offers the most penetrable geographic white space, with direct sales relationships replacing Minsk-centric distribution as the viable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward furnace operators with proprietary batching recipes and existing pharmaceutical certification depth, where technical moats sustain returns across the analysis window. Watch EAEU harmonization implementation pace as the signal for cross-border certification reciprocity opening Russian and Kazakh tender participation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Certification Expansion | European Pharmacopoeia compliance unlocks Minsk drug packager procurement previously sourced from Western suppliers. |
| Furnace Energy Efficiency Retrofit | Proprietary batching recipe integration lowers per-ton gas consumption against Russian pipeline price volatility. |
| Regional Distillery Supply Anchoring | Gomel proximity captures southeastern beverage cluster demand underserved by capital-constrained Minsk competitors. |
| Surface Treatment Capability Buildup | Anti-abrasion coating installation commands cosmetic segment premiums and differentiates margin pools. |
| Aftermarket Service Unbundling | Independent mold refurbishment sourcing preserves liquidity for core furnace investments across mid-cap balance sheets. |
Research Methodology
A standing panel of furnace operations directors, pharmaceutical packaging procurement managers, beverage distillery supply chain leads, and aftermarket refractory service technicians provided ongoing calibration throughout primary fieldwork. Secondary validation drew from Eurasian Economic Union technical regulation filings, Belarusian national standards body protocols, customs trade data for soda ash and silica sand imports, and SEC disclosures from multinational packaging converters. Bottom-up volume modeling triangulated against top-down EAEU market sizing assessments.
Scenario-bracketing framed projections across regulatory harmonization acceleration, natural gas price regime shifts, and PET substitution penetration assumptions. Segmentation dimensions modeled encompassed product type, end-use industry, capacity tier, and manufacturing stage automation level. CAGRs derived from weighted average growth across these segments, with furnace throughput efficiency curves and pharmaceutical certification adoption rates as industry-specific demand drivers throughout the projection horizon.
Sensitivities concentrate around EAEU technical regulation implementation timing, Russian gas pricing volatility, and furnace refractory skill availability. Forecasts reflect documented assumptions regarding regulatory convergence pace and substitution elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market