
 Germany Container Glass Market | 2026-2036
Germany Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Container Glass Market Foresight
Market Context
The EU Green Deal is repositioning capital allocation across German container glass manufacturing. O-I Germany GmbH & Co. KG leverages its integrated furnace network to serve premium beverage accounts. Wiegand-Glas GmbH anchors supply for returnable bottle pools across central Germany. Verallia Deutschland AG competes on lightweighting technology for wine and spirits packaging.
Technical Definition and Structural Segments
Container glass refers to hollow glassware formed from silica sand, soda ash, and limestone melted at approximately 1,500°C, then shaped by blow or press-blow methods to store liquids, solids, or gases with chemical inertness and impermeability. Bottles dominate volume across German production lines, while amber glass commands premium positioning in pharmaceutical and craft beer segments where UV protection justifies higher unit economics. Blow and blow technology still occupies the majority of installed capacity, though narrow neck press and blow systems are displacing legacy equipment in lightweight wine bottle applications.
Regulatory Frame and Outlook
The EU F-Gas Regulation and Germany's national packaging ordinance under the KBA's extended producer responsibility framework shape furnace emissions targets and post-consumer collection quotas. REACH compliance adds raw material certification burdens that favor larger integrated producers over fragmented converters. Stakeholders must monitor how the EU CSRD's supply chain disclosure rules alter procurement criteria for brand owners sourcing decorated and labeled glass containers.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing German container glass producers to reconfigure furnace operations and recalibrate raw material sourcing strategies around post-consumer cullet recovery targets.
Growth Catalysts
- Returnable bottle pool expansion:Bavarian brewing cooperatives are scaling refillable glass infrastructure to meet retailer sustainability commitments.
- REACH raw material certification:Standardized chemical safety documentation is streamlining supplier qualification for pharmaceutical packaging accounts.
- Lightweighting technology adoption:Narrow neck press and blow systems are reducing per-unit silica consumption across wine and spirits production lines.
Market Restraints
- Natural gas price volatility:Furnace energy costs constitute the dominant share of production economics, exposing margins to commodity swings.
- Post-consumer cullet supply concentration:Collection infrastructure remains concentrated in North Rhine-Westphalia and Bavaria, creating regional imbalances.
- Aluminum can substitution:Beverage brand owners are diversifying packaging portfolios toward metal alternatives for single-serve formats.
Strategic Opportunities
- Pharmaceutical serialization integration:Track-and-trace mandates under the EU Falsified Medicines Directive are creating demand for decorated amber vials with embedded authentication.
- Carbon border adjustment positioning:Early alignment with the EU CBAM framework offers export competitiveness against non-European suppliers.
- Chemical packaging lightweighting:Industrial solvent and reagent producers are requesting thinner-walled containers to reduce logistics costs.
Industry Challenges
- Furnace rebuild cadence:Decarbonization targets require accelerated capital deployment for oxy-fuel and electric melting conversion.
- Decorative coating compliance:Heavy metal restrictions in surface treatments are forcing reformulation of organic and inorganic colorants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Container Glass Market |
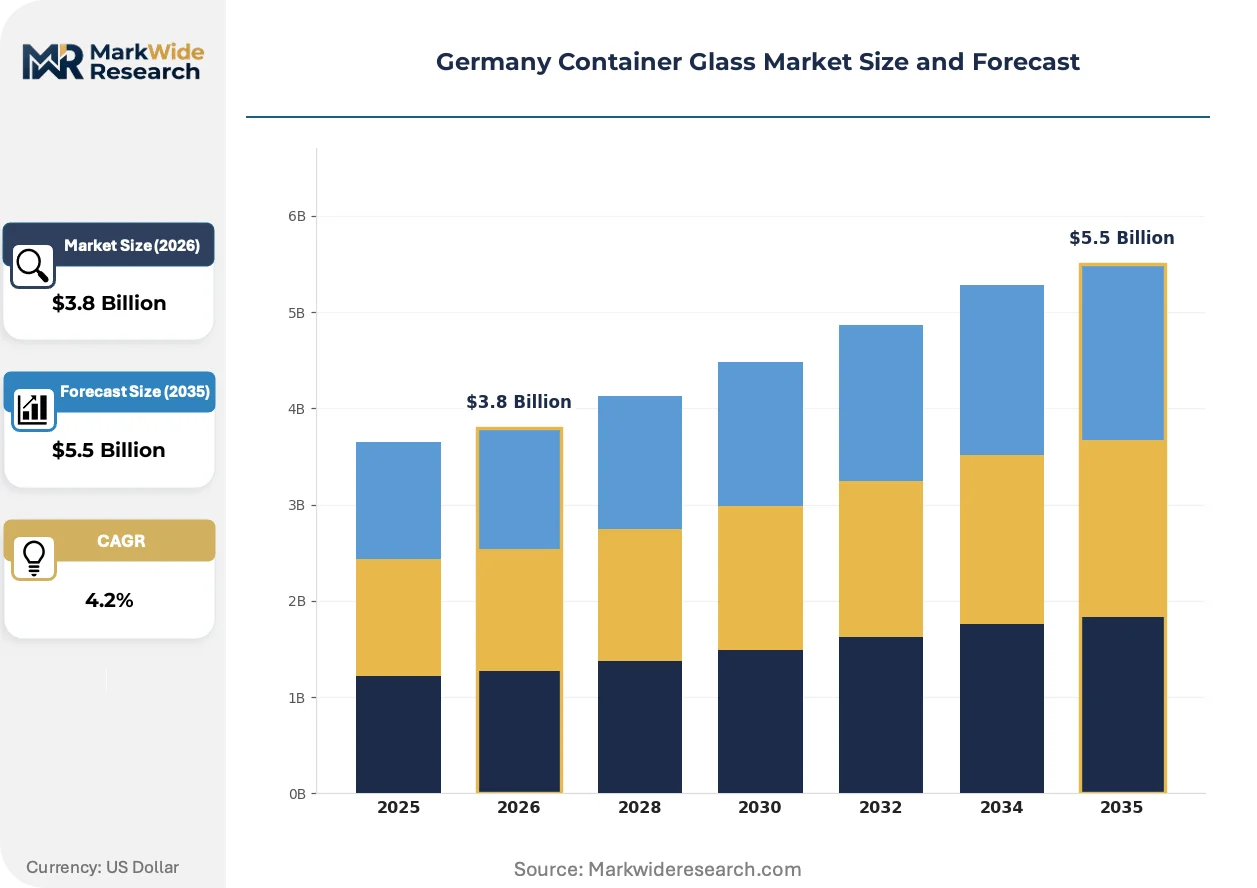
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Canisters, Tubs End Use Industry: Beverages, Cosmetics & Personal Care, Pharmaceuticals, Food Processing, Chemicals Packaging Type: Green Glass, Amber Glass, Flint Glass, Opal Glass, Frosted Glass Manufacturing Technology: Blow & Blow, Press & Blow, Narrow Neck Press & Blow, Injection Molded, Automated Forming |
| Companies Covered | O-I Germany GmbH & Co. KG, Schott AG, Ardagh Group, HEINZ-GLAS GmbH, Systempack Manufaktur GmbH, Verallia Deutschland AG, Wiegand-Glas GmbH, Saint-Gobain Oberland AG, Gerresheimer AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Container Glass Market Shifts & Advancements
Electrification of melting technology and digital furnace control systems are compressing energy intensity benchmarks while enabling real-time emissions compliance monitoring across German production sites.
Hybrid oxy-fuel furnace architecture is absorbing natural gas demand by substituting oxygen-enriched combustion in regenerative chamber designs. Premium spirits distillers in the Black Forest region are specifying these containers for carbon-neutral product lines. The technology is absorbing investment flows that previously targeted conventional air-fuel rebuilds.
The EU CSRD's supply chain disclosure rules are mandating Scope 3 emissions reporting from packaging suppliers. German brand owners are now requiring verified environmental product declarations from container glass vendors. Wine cooperatives in Rheinhessen face the steepest documentation burdens due to fragmented supplier bases.
Consolidated procurement through beverage pooling systems is displacing direct supplier relationships for standard bottle formats. Returnable bottle pool operators in central Germany are capturing volume previously managed by individual brand procurement teams. This concentration is most pronounced in mineral water and mainstream beer segments.
Germany Container Glass Market Segmentation
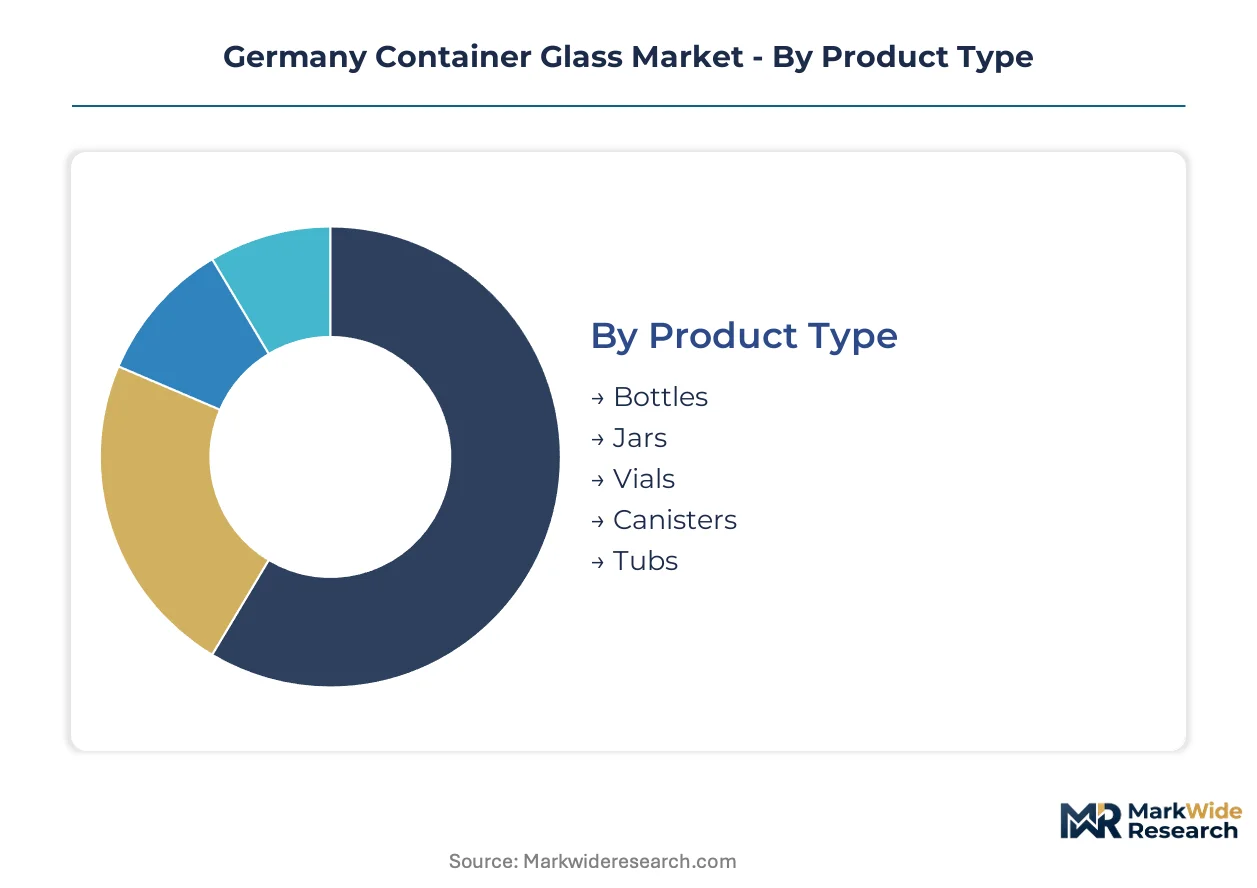
German container glass manufacturers configure production lines around distinct technical specifications and end-use requirements. Segmentation reveals where furnace capacity concentrates and which technology investments command priority capital allocation.
Product Type:
Supply concentration tilts toward formats serving Bavaria's beverage corridors and North Rhine-Westphalia's chemical packaging belt.
- Bottles:Hollow vessels formed through blow or press-blow methods dominate installed furnace capacity across German production sites. Bavarian brewing cooperatives and mineral water brands in the Rhön Mountains anchor demand for returnable bottle pools, with lightweighting programs reducing per-unit silica consumption.
- Jars:Wide-mouth containers with continuous thread or lug finishes preserve food products through hermetic sealing. Food processors in Lower Saxony's agricultural zones specify these for premium preserves and sauerkraut lines where thermal shock resistance matters.
- Vials:Small-volume pharmaceutical containers with precise neck finishes for rubber stoppers and aluminum crimp seals. Sterile manufacturing requirements under EU GMP Annex 1 drive specification rigor.
- Canisters:Large-format containers with handles and wide openings for industrial chemicals and solvents. Chemical producers along the Rhine corridor request thinner-walled variants to reduce logistics costs.
- Tubs:Short, wide containers for cosmetics and food spreads. Limited domestic capacity sees import substitution from Czech and Polish suppliers.
Today's leader: Bottles. Tomorrow's challenger: Vials.
End Use Industry:
Application-specific thermal and chemical resistance requirements fragment furnace scheduling across German manufacturing sites.
- Beverages:Beer, wine, spirits, and non-alcoholic drinks consume the majority of domestic cullet recovery streams. The returnable bottle pool system in central Germany creates concentrated procurement power among pool operators.
- Pharmaceuticals:Amber and flint glass vials and bottles for injectables, oral liquids, and solid dosages. Serialization mandates under the EU Falsified Medicines Directive push decoration and authentication integration.
- Cosmetics & Personal Care:Premium fragrance and skincare brands specify heavy-base bottles and opal glass for shelf differentiation. Smaller batch sizes complicate furnace economics.
- Food Processing:Jars and bottles for preserves, sauces, and dairy products. Rheinhessen wine cooperatives and Black Forest distillers drive regional demand clusters.
- Chemicals:Solvent, reagent, and laboratory chemical packaging. REACH compliance documentation favors integrated producers with certified raw material traceability.
Beverages command current volume. Pharmaceuticals claim the steepest expansion trajectory.
Packaging Type:
Color chemistry and light transmission properties segment furnace campaigns and raw material sourcing strategies.
- Flint Glass:Clear, colorless glass with high visible light transmission for premium spirits and cosmetics. The KBA's extended producer responsibility framework shapes post-consumer collection targets for this high-culter-recovery format.
- Amber Glass:Iron-sulfur chromophore chemistry blocks UV wavelengths below 450nm. Pharmaceutical and craft beer segments in Bavaria absorb capacity where UV protection justifies unit economics premiums.
- Green Glass:Chromium and iron oxide coloration for wine and certain beer categories. Rheinhessen cooperatives specify this for traditional Riesling presentation.
- Opal Glass:Fluorine-opacified or phosphate-based white glass for cosmetic and pharmaceutical applications requiring light blocking with premium aesthetics.
- Frosted Glass:Acid-etched or molded surface treatments for premium fragrance and gift packaging. Decorative coating compliance under heavy metal restrictions complicates supplier qualification.
Flint Glass holds installed capacity leadership. Amber Glass gains on regulatory and premiumization tailwinds.
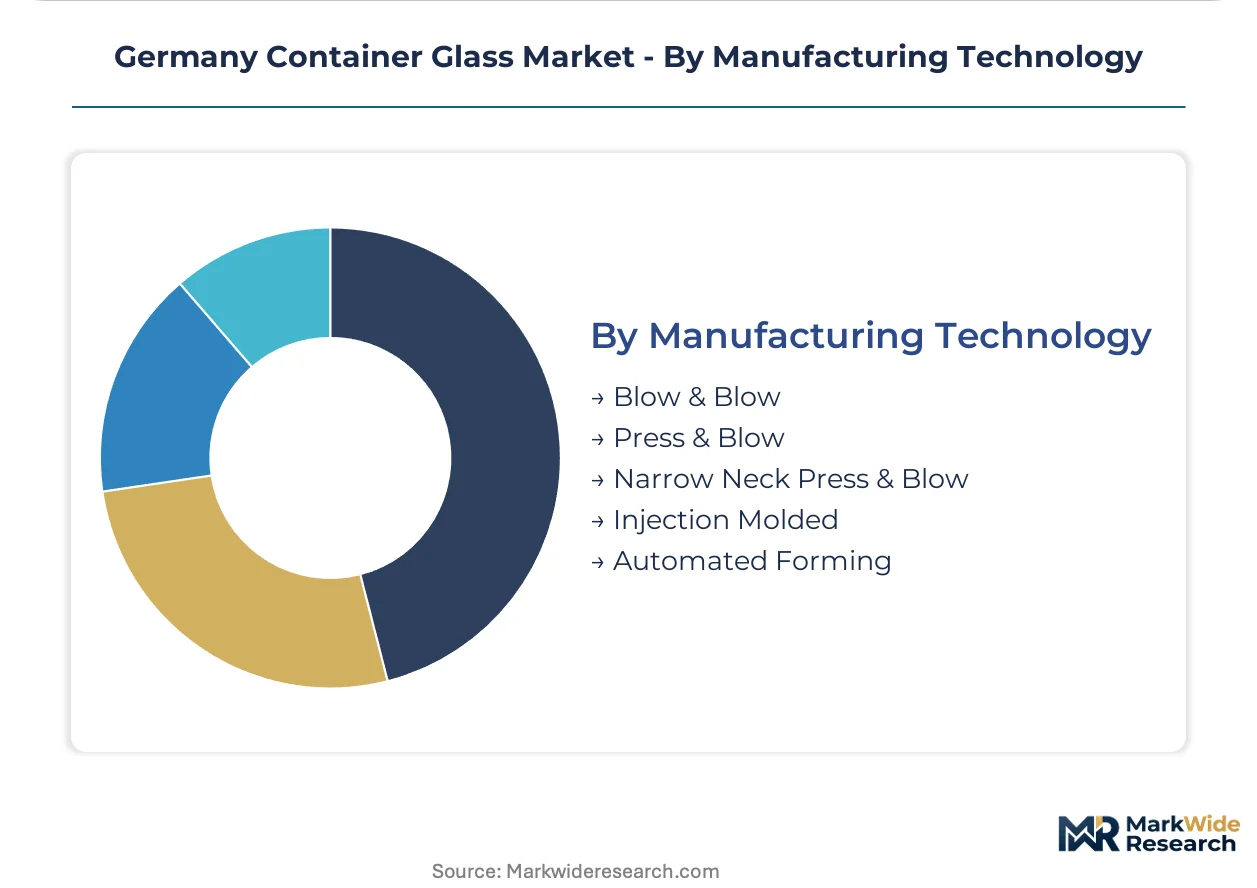
Manufacturing Technology:
Equipment vintage and energy intensity separate cost structures across German container glass production.
- Blow & Blow:Traditional parison formation and final blow in sequential molds. Legacy installations across central Germany face decarbonization-driven rebuild decisions.
- Narrow Neck Press & Blow:Plunger-formed parisons enable lighter wall weights in wine bottle production. Wiegand-Glas and Verallia deploy these systems for lightweighting mandates.
- Press & Blow:Wide-mouth jar and container production with mechanical pressing for parison definition. Food processing demand in northern Germany sustains this capacity.
- Injection Molded:Precision forming for pharmaceutical vials and technical glassware. Limited German presence; specialty applications dominate.
- Automated Forming:Integrated IS machine lines with robotic handling and inspection. New furnace investments pair this with digital control systems for emissions compliance monitoring.
Blow & Blow retains volume dominance. Narrow Neck Press & Blow captures rebuild investment flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled furnace operators and glass technologists cluster along the Rhine corridor and southern industrial belt, anchoring production capacity in proximity to Bavarian beverage brands and North Rhine-Westphalia chemical processors.
Bavaria
Bavarian brewing cooperatives and mineral water brands in the Rhön Mountains drive returnable bottle pool expansion. The KBA's extended producer responsibility framework mandates post-consumer cullet recovery quotas that concentrate collection infrastructure around Munich and Nuremberg. Wiegand-Glas operates integrated furnace networks serving these refillable glass systems.
North Rhine-Westphalia
Chemical packaging demand from industrial solvent and reagent producers along the Rhine corridor absorbs flint and amber glass capacity. REACH compliance documentation requirements favor integrated producers with certified raw material traceability. O-I Germany maintains furnace operations serving pharmaceutical and chemical accounts in the Cologne-Düsseldorf industrial zone.
Baden-Württemberg
Premium spirits distillers in the Black Forest region specify lightweight containers for carbon-neutral product lines. The EU Green Deal's circular economy mandates push these producers toward oxy-fuel furnace suppliers. Verallia Deutschland deploys narrow neck press and blow systems for wine bottle lightweighting programs serving Rheinhessen cooperatives.
Lower Saxony
Food processors in agricultural zones around Hanover and Brunswick specify jars for premium preserves and sauerkraut lines where thermal shock resistance matters. The EU F-Gas Regulation shapes furnace emissions targets for glass manufacturers supplying these accounts. Saint-Gobain Oberland anchors supply for wide-mouth container applications.
Hesse
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive create demand for decorated amber vials in the Frankfurt-Rhine-Main biotech corridor. Gerresheimer and Schott AG occupy positions serving sterile manufacturing requirements under EU GMP Annex 1. Track-and-trace integration pushes specification rigor for rubber stopper and aluminum crimp seal compatibility.
Germany Container Glass Market Competitive Landscape
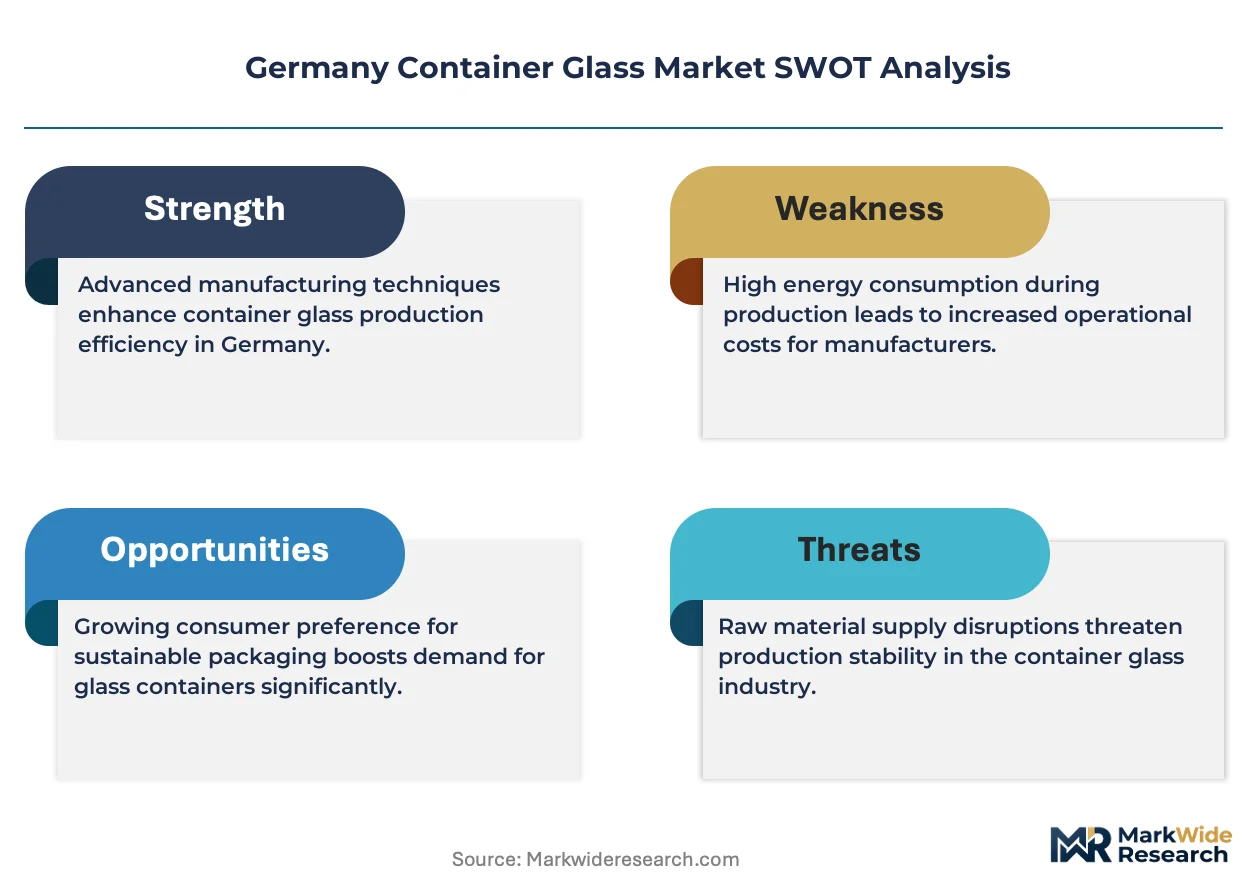
The competitive structure tilts toward integrated furnace operators with multi-site networks. German container glass manufacturing exhibits consolidated capacity around legacy industrial zones, with tiered competition separating volume-scale beverage suppliers from specialty pharmaceutical and cosmetic packaging specialists. Strategic archetypes include returnable pool system anchors, lightweighting technology leaders, and pharmaceutical serialization integrators. Capacity expansion and furnace electrification represent the dominant competitive moves as decarbonization targets accelerate capital deployment.
Among integrated multi-site operators, O-I Germany GmbH & Co. KG and Wiegand-Glas GmbH occupy positions exemplifying the returnable bottle pool anchor archetype. Verallia Deutschland AG represents the lightweighting technology vector through narrow neck press and blow system deployment. Gerresheimer AG and Schott AG sit within the pharmaceutical specialization tier, serving sterile manufacturing and serialization requirements. These five entities collectively span the strategic archetypes reshaping competitive positioning across German production geography.
| Leading Market Players |
|---|
| O-I Germany GmbH & Co. KG |
| Schott AG |
| Ardagh Group |
| HEINZ-GLAS GmbH |
| Systempack Manufaktur GmbH |
| Verallia Deutschland AG |
| Wiegand-Glas GmbH |
| Saint-Gobain Oberland AG |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Skilled furnace operators and glass technologists cluster along the Rhine corridor and southern industrial belt, and this labor concentration widens the spread between premium lightweighted containers and standard-format pricing tiers. The KBA's extended producer responsibility framework adds compliance-cost layering that separates certified returnable pool suppliers from spot-market converters.
Pricing Analysis
Bundled furnace services with integrated decoration and logistics command premiums against unbundled container-only supply. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade amber vials with serialization from mainstream beverage bottles and commodity food jars. Pricing pressure stems from natural gas cost volatility eroding margins at air-fuel furnace operators. Beverage brand owners in the returnable pool system exhibit highest price sensitivity, while pharmaceutical accounts accept premiums for EU GMP Annex 1 compliance.
Supply Chain Analysis
High-purity silica sand supply rests on deposits in Germany, Belgium, and the Netherlands, with specialty soda ash drawing from European and North American chemical producers. Raw material dependencies center on silica sand quality grades, soda ash purity tiers, and post-consumer cullet recovery streams. Single-source vulnerability concentrates in oxy-fuel combustion technology licensors and narrow neck press and blow equipment suppliers. Distribution runs through returnable bottle pool operators in Bavaria and direct procurement relationships for pharmaceutical and cosmetic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Container Glass Market functions as a stable compounder anchored by regulatory mandates under the EU Green Deal that lock in replacement demand for decarbonized furnace capacity.
For Market Incumbents: Lock in returnable bottle pool contracts with Bavarian brewing cooperatives before electrified furnace investments mature at competitors. Secure oxy-fuel technology partnerships to defend position against aluminum can substitution in single-serve formats. Prioritize backward integration into post-consumer cullet collection infrastructure in North Rhine-Westphalia to control input costs. For New Entrants and Emerging Players: Beverage pooling system operators represent the most accessible channel partners for volume entry without legacy furnace rebuild obligations. Target pharmaceutical serialization integration in the Frankfurt-Rhine-Main corridor where EU Falsified Medicines Directive mandates create specification gaps. Pursue lightweighting technology licensing as the go-to-market angle to bypass capital-intensive furnace construction. For Investors and Strategic Acquirers: Packaging conglomerates with circular economy mandates are the most active acquirer in this space, seeking furnace assets with verified environmental product declarations. Five-to-ten-year viability hinges on electric melting conversion timelines and carbon border adjustment alignment. Target acquisition archetype: mid-cap operators with oxy-fuel installations and established pharmaceutical certifications. Watch EU CBAM implementation pace as the inflection signal for export-competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Conversion | Decarbonization targets under the EU Green Deal mandate oxy-fuel and electric melting technology deployment. |
| Returnable Pool System Expansion | Bavarian brewing cooperatives scale refillable infrastructure to meet retailer sustainability commitments. |
| Pharmaceutical Serialization Integration | EU Falsified Medicines Directive drives demand for decorated amber vials with embedded authentication. |
| Post-Consumer Cullet Recovery Investment | KBA extended producer responsibility quotas concentrate collection infrastructure around Munich and Nuremberg. |
| Lightweighting Technology Licensing | Narrow neck press and blow systems reduce per-unit silica consumption for wine and spirits producers. |
Research Methodology
Bottom-up beverage and pharmaceutical modeling reconciled against top-down furnace capacity tracking forms the analytical core of this study. Primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors combined with secondary validation from KBA filings, EU ETS emissions data, SEC disclosures by listed packaging groups, and customs trade records. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped silica sand, soda ash, and cullet flows against furnace output by product format and end-use segment across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, packaging color chemistry, and manufacturing technology vintage. CAGRs derived from capacity utilization trends, replacement demand cycles, and regulatory compliance timelines. Forecast inputs incorporated natural gas price scenarios and electric grid decarbonization curves affecting furnace economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU CBAM implementation pace and electric melting technology cost curves. Forecasts reflect assumptions about regulatory enforcement consistency and raw material supply continuity. A small set of triggers—furnace electrification subsidies, aluminum can penetration rates, and pharmaceutical serialization mandate delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Logistics Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Russia Glass Packaging Market