
 Glass Growlers Market | 2026-2036
Glass Growlers Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Growlers Market Foresight
Aftermarket refill programs is reconfiguring margin pools away from one-time bottle sales toward recurring revenue from cap replacements and branded sleeve accessories. Owens-Illinois Inc. anchors North American production capacity through its extensive furnace network. Berlin Packaging LLC differentiates via private-label decoration services and custom mold capabilities for regional brewers. Ardagh Group S.A. leverages European glassmaking heritage to supply premium cobalt and amber variants for export markets.
Glass growlers are refillable beverage containers typically manufactured from soda-lime silica glass in capacities ranging from 32 oz to 64 oz, featuring screw-cap or swing-top closures designed to maintain carbonation pressure during transport and storage. Amber glass commands structural preference among craft breweries because its iron-sulfur composition blocks ultraviolet wavelengths that degrade hop compounds in India pale ales and hazy styles. The 64 oz capacity segment dominates taproom-to-consumer flows, while swing-top closure demand accelerates among home brewers seeking reusable sealing mechanisms without tool-dependent opening.
FDA food-contact substance regulations govern interior surface coatings and leachate thresholds for all glass growlers distributed in the United States. The EU Packaging and Packaging Waste Directive shapes extended producer responsibility obligations for refillable bottle pools across member states. California's rigid plastic packaging regulations indirectly elevate glass alternatives through recycled-content mandates that PET competitors struggle to satisfy. Stakeholders must monitor how deposit-return scheme expansions in Oregon, Germany, and Australia alter collection infrastructure economics and refill-loop viability.
Market Dynamics
Refillable beverage container economics are compressing unit margins while extending customer lifetime value through recurring cap and accessory purchases. Deposit-return scheme expansions across Oregon, Germany, and Australia are restructuring collection infrastructure investment priorities for glass manufacturers.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Extended producer responsibility mandates for refillable bottle pools create compliance-driven demand for durable glass formats across member states.
- Amber glass chemistry:Iron-sulfur composition blocking UV degradation of hop compounds drives brewer preference for India pale ales and hazy styles.
- Swing-top closure engineering:Tool-independent sealing mechanisms accelerate adoption among home brewers seeking reusable transport solutions.
Market Restraints
- Natural gas price volatility:Soda-lime silica furnace operations face input cost swings that compress foundry margins during energy price spikes.
- Single-use aluminum can substitution:Lightweight metal formats capture on-premise consumption occasions that glass growlers cannot economically serve.
- FDA leachate thresholds:Interior surface coating compliance adds testing overhead that slows new product introduction timelines for US-bound shipments.
Strategic Opportunities
- Branded sleeve accessories:Custom decoration services unlock recurring revenue streams beyond one-time bottle sales for regional craft breweries.
- California recycled-content mandates:Rigid plastic packaging regulations indirectly elevate glass alternatives as PET competitors struggle to satisfy threshold requirements.
- Taproom direct-to-consumer channels:64 oz capacity formats bypass traditional distribution markups for brewery-owned retail operations.
Industry Challenges
- Mold fabrication lead times:Custom glass mold production cycles extend 16-24 weeks, constraining speed-to-market for seasonal beer releases.
- Carbonation pressure engineering:Screw-cap and swing-top seal integrity must maintain dissolved CO2 levels across temperature fluctuations during transport.
- Cross-border deposit harmonization:Incompatible state-level return schemes fragment refill-loop economics for multi-state distributing breweries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Growlers Market |
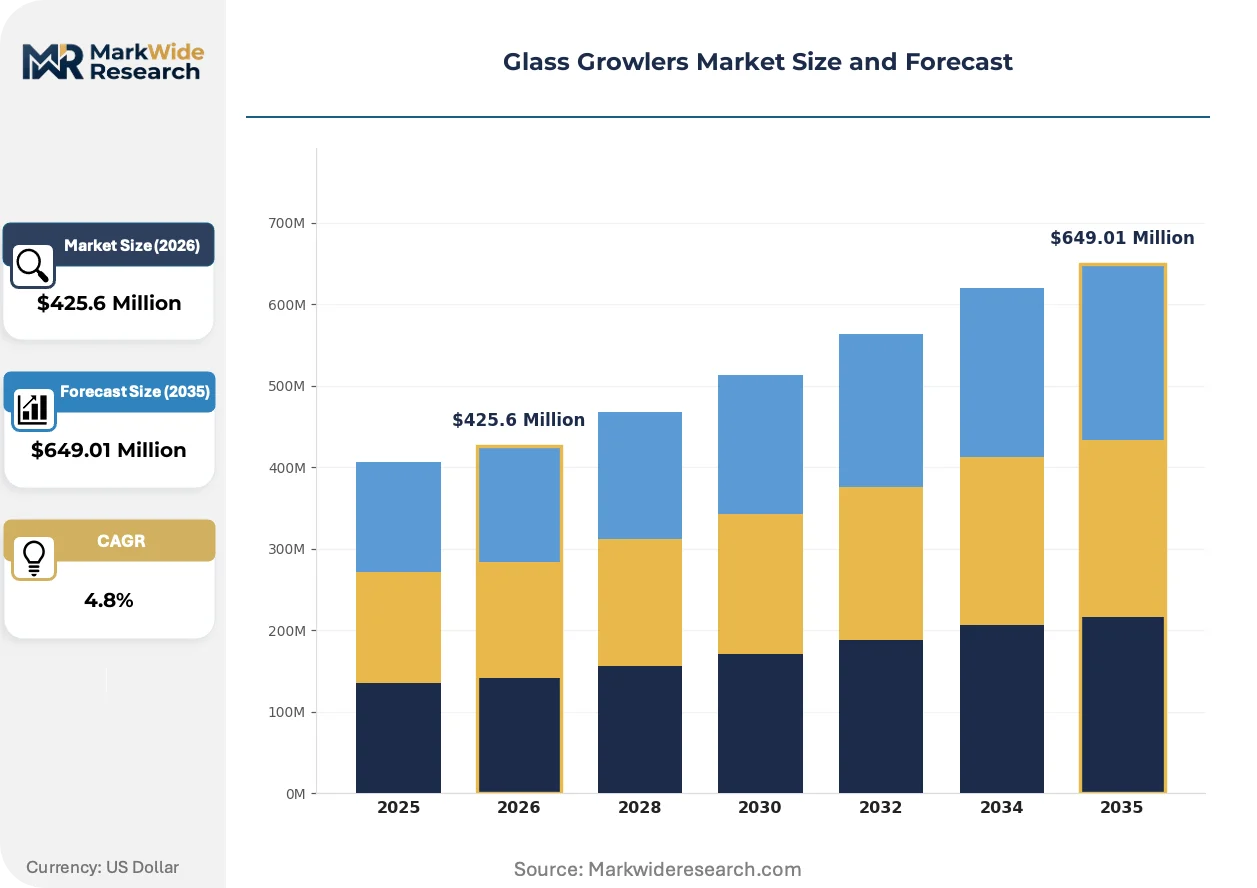
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $649.01 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Glass, Amber Glass, Flint Glass, Cobalt Blue Glass, Green Glass Capacity: 32 oz, 64 oz, 12 oz, 22 oz, 48 oz Closure Type: Screw Cap, Flip Top, Cork Stopper, Swing Top, Cap with Seal End User: Craft Breweries, Taprooms, Beverage Distributors, Specialty Stores, Home Brewers |
| Companies Covered | Ardagh Group S.A., Owens-Illinois Inc., Berlin Packaging LLC, Alpha Packaging, GrowlerWerks, Inc., Global Glass Solutions, William Croxsons & Sons Limited, Zenan Glass, Boelter Companies, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Growlers Market Shifts & Advancements
Active migration toward UV-protective glass chemistry and closure innovation is reconfiguring product specifications across craft beverage packaging. Regulatory pressure on single-use alternatives accelerates investment in durable container formats.
Advanced amber glass formulations with enhanced iron oxide loading are migrating from premium export portfolios toward standard domestic SKUs. Mid-sized craft breweries in the Pacific Northwest and New England are specifying these variants for year-round hop-forward releases. The shift is compressing price premiums between protective and clear glass grades.
Germany's national packaging ordinance implementing EU extended producer responsibility frameworks is mandating refillable quota thresholds for beverage containers. Glass foundries serving Central European markets are retooling furnace campaigns toward heavier-walled formats engineered for 50+ reuse cycles. Premium cobalt and amber variants face compliance-driven specification reviews.
Direct taproom procurement of 64 oz formats is displacing traditional three-tier distribution for brewery-owned retail channels. Smaller craft producers in Australia and the United States are bypassing wholesale markups through on-premise refill programs. The model concentrates volume with foundries offering private-label decoration and short-run mold capabilities.
Glass Growlers Market Segmentation
Glass growler specifications diverge sharply across beverage categories, with UV protection chemistry and carbonation retention engineering driving fundamentally different procurement priorities for hop-forward brewers versus wine or kombucha producers.
Product Type:
Iron oxide loading and sulfur content differentiate protective performance across the ultraviolet spectrum, with brewers matching glass chemistry to hop compound sensitivity and shelf-life requirements.
- Amber Glass:Iron-sulfur composition blocks ultraviolet wavelengths below 450 nanometers that degrade iso-alpha acids in India pale ales and hazy styles. Pacific Northwest craft breweries specify this variant for year-round distributed releases requiring extended retail shelf stability.
- Clear Glass:Soda-lime silica without colorant additives offers lowest unit cost for immediate-consumption formats where UV exposure is minimal. Taprooms serving same-day consumption prioritize this grade for price-sensitive refill programs.
- Flint Glass:Highly transparent lead-free crystal variant commands premium positioning for specialty gift sets and commemorative brewery releases.
- Cobalt Blue Glass:Cobalt oxide colorant provides moderate UV filtration with distinctive visual branding for export-oriented premium portfolios.
- Green Glass:Chromium-iron chemistry offers intermediate protection at price points between amber and clear grades, finding niche adoption among European lager producers.
The dominant share belongs to Amber Glass, while Clear Glass is closing the gap fastest as same-day taproom consumption displaces distributed retail channels.
Capacity:
Volume specifications track consumption occasion fragmentation, with direct-to-consumer refill economics favoring larger formats while sampling and mixed-flights drive small-container demand.
- 64 oz:Standard half-gallon format dominates brewery-owned retail channels, capturing the economics of bypassing three-tier distribution markups through direct taproom sales.
- 32 oz:Quart-size specification accelerates among urban taprooms where portability constraints and single-visit consumption patterns limit larger format viability.
- 12 oz:Single-serving equivalent supports flight-sampling programs and mixed-pack offerings for specialty retail.
- 22 oz:Bomber-format legacy specification persists among established craft breweries with existing mold investments.
- 48 oz:Intermediate capacity targets crowler-alternative positioning for limited-release small-batch offerings.
Sixty-four ounce formats anchor procurement volumes, though thirty-two ounce variants are expanding most quickly in metropolitan taproom networks.
Closure Type:
Sealing mechanism selection balances carbonation pressure retention against user convenience, with tool-dependency and resealability driving divergent adoption curves across consumer segments.
- Swing Top:Wire-bail ceramic stopper enables tool-independent opening and reliable resealing across multiple use cycles. Home brewers and refill-program participants prioritize this mechanism for reusable transport without dedicated equipment.
- Screw Cap:Threaded aluminum or phenolic closure offers lowest per-unit cost and consistent torque specifications for high-speed filling lines. Production breweries favor this format for volume efficiency.
- Flip Top:Hinged plastic or metal lever mechanism provides one-handed operation for on-premise consumption occasions.
- Cork Stopper:Natural or synthetic tapered seal targets wine and mead producers seeking traditional aesthetic positioning.
- Cap with Seal:Crown-cap derivative with integrated gasket supports single-use export formats requiring tamper-evidence.
Screw Cap specifications hold the volume lead, yet Swing Top configurations are gaining share fastest as refill-loop infrastructure matures.
End User:
Procurement authority concentrates with beverage producers and their direct retail channels, though distributor and specialty retail intermediaries maintain specification influence in fragmented markets.
- Craft Breweries:Production-scale facilities with taproom operations specify growler formats as brand extension vehicles and margin-recapture instruments. These buyers prioritize mold customization and decoration services for portfolio differentiation.
- Taprooms:Brewery-owned retail channels bypass wholesale markups through direct refill programs, concentrating volume with foundries offering short-run flexibility and rapid mold turnaround.
- Beverage Distributors:Three-tier intermediaries specify standardized formats for multi-brand portfolios, favoring screw-cap compatibility across filling equipment.
- Specialty Stores:Curated retail channels drive gift-set and commemorative specifications with premium decoration requirements.
- Home Brewers:Small-volume consumers prioritize swing-top reusability and individual-unit availability through homebrew supply channels.
Craft Breweries command the largest procurement share, though Taproom direct channels are climbing the fastest as vertical retail integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass foundry capacity clusters heavily in Germany and the United States, where integrated furnace networks serve craft beverage producers across multiple continents. Regulatory frameworks in Oregon, Bavaria, and Victoria are accelerating refill-loop infrastructure investment.
United States
Craft brewery taprooms in Portland, Oregon and Denver, Colorado drive 64 oz format procurement for direct-to-consumer refill programs. FDA food-contact substance regulations govern interior coating compliance for all domestic distribution. Owens-Illinois anchors North American supply through its multi-furnace production network serving regional brewers.
Germany
The national packaging ordinance implementing EU extended producer responsibility mandates refillable quota thresholds for beverage containers. ECHA chemical safety standards shape glass composition requirements for export-bound formats. Bavarian foundries around Nuremberg retool toward heavier-walled variants engineered for 50-plus reuse cycles.
Australia
Deposit-return scheme expansions in Victoria and New South Wales restructure collection infrastructure economics for refillable bottle pools. TGA packaging guidelines intersect with state-level environmental regulations for food-contact materials. Melbourne-area craft producers bypass wholesale markups through vertical taproom integration.
United Kingdom
London and Manchester craft brewery clusters specify amber glass variants for hop-forward distributed releases requiring extended retail stability. REACH chemical registration requirements govern colorant additive compliance for EU export shipments. William Croxsons & Sons Limited represents traditional British glassmaking heritage serving specialty commemorative formats.
China
Zenan Glass and domestic foundries supply cost-competitive clear glass formats for immediate-consumption taproom channels. SAMR market supervision and GB standards regulate food-contact surface specifications. Yangtze River Delta manufacturing bases serve export demand for private-label decoration and custom mold capabilities.
Glass Growlers Market Competitive Landscape
Integrated multinational foundries and specialized decoration service providers split the market between scale-driven commodity supply and flexible short-run customization. The structure concentrates volume among three furnace-operating conglomerates while fragmented regional decorators capture brewery-specific branding demand. Two strategic archetypes dominate: capital-intensive glass manufacturers with captive raw material sourcing, and mold-flexible packaging specialists offering rapid turnaround private-label programs. Competitive moves center on furnace capacity expansion in natural gas-advantaged geographies and strategic partnerships with craft brewery consortiums for dedicated refill-loop supply.
Among North American furnace operators, Owens-Illinois Inc. exemplifies scale-driven vertical integration into raw material sourcing and multi-plant distribution logistics. Berlin Packaging LLC occupies a position within the flexible-service archetype, anchoring private-label decoration and custom mold capabilities for regional craft brewers requiring rapid seasonal turnaround. Ardagh Group S.A. represents European heritage glassmaking with premium cobalt and amber variant supply for export-oriented brewery portfolios.
| Leading Market Players |
|---|
| Ardagh Group S.A. |
| Owens-Illinois Inc. |
| Berlin Packaging LLC |
| Alpha Packaging |
| GrowlerWerks, Inc. |
| Global Glass Solutions |
| William Croxsons & Sons Limited |
| Zenan Glass |
| Boelter Companies, Inc |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors connecting Shanghai to Pacific Northwest ports transmit silica sand and soda ash cost volatility directly into growler landed pricing, concentrating margin pressure on foundries without captive raw material sourcing while enabling price differentiation for brewers with direct taproom channels.
Pricing Analysis
EU Packaging and Packaging Waste Directive dictates the pricing tier structure across the European refillable bottle pool. Three-tier pricing structure across premium cobalt-amber variants, standard amber grades, and economy clear glass separates compliance-driven heavy-wall specifications from same-day taproom consumption formats. Cost compression in standard amber grades is intensifying because natural gas furnace operations face input volatility. Craft breweries with vertical taproom integration show least price sensitivity; beverage distributors managing multi-brand portfolios exhibit highest.
Supply Chain Analysis
Tariff exposure between China and United States dominates supply chain risk calculations for decoration-heavy private-label programs. Foundry capacity clusters in Germany, United States, and China, with Bavarian and Ohio River Valley furnace networks serving distinct regional demand pools. Soda-lime silica production draws from high-purity silica sand deposits, soda ash from Wyoming and Inner Mongolia, and cobalt oxide from African concentrate sources. Single-source vulnerability concentrates in specialty colorant additives. Distribution runs through brewery-direct procurement for 64 oz formats and three-tier wholesale channels for standardized screw-cap specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refill-loop infrastructure expansion represents early-cycle penetration tailwind, with deposit-return scheme adoptions across Oregon, Germany, and Australia creating foundational demand for durable container formats before mainstream craft brewery conversion accelerates.
For Market Incumbents: Insulate furnace margin positions through backward integration into Wyoming soda ash sourcing and captive silica sand procurement. Counter single-use aluminum can substitution threat by embedding swing-top engineering into premium SKU portfolios. Prioritize mold-flexibility investments in Pacific Northwest and New England brewery clusters where seasonal release velocity demands rapid turnaround. For New Entrants and Emerging Players: Build out short-run decoration capabilities targeting metropolitan taproom networks in Denver, Portland, and Melbourne where vertical retail integration bypasses distributor markups. Penetrable white-space concentrates in 32 oz urban consumption formats and home brewer swing-top segments. Go-to-market angle: private-label sleeve accessory programs with 16-week mold turnaround guarantees. For Investors and Strategic Acquirers: Mold-flexible packaging specialists with regional brewery consortium partnerships represent the most defensible acquisition archetype across the 5-to-10 year window. Long-term viability hinges on refill-loop infrastructure maturation rather than one-time bottle replacement cycles. Signal to watch: harmonization of state-level deposit-return schemes enabling multi-state distributing brewery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Captive soda ash and silica sand procurement insulates Owens-Illinois furnace margins from energy price volatility. |
| Short-Run Mold Capability Expansion | Berlin Packaging's 16-week turnaround captures seasonal craft brewery release cycles in Pacific Northwest clusters. |
| Refill-Loop Infrastructure Partnership | Ardagh Group's brewery consortium alliances secure dedicated supply quotas under EU extended producer responsibility mandates. |
| UV-Protective Glass Chemistry Migration | Enhanced iron oxide loading specifications compress price premiums between amber and clear grades for hop-forward portfolios. |
| Swing-Top Closure Engineering Investment | Tool-independent sealing mechanisms accelerate adoption among home brewers and refill-program participants seeking reusable transport. |
Research Methodology
A standing panel of craft brewery operations directors, glass foundry plant managers, beverage distributor procurement leads, and FDA regulatory affairs specialists provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA food-contact substance filings, EU ECHA chemical safety registrations, state-level deposit-return scheme administrative records, and customs trade data for soda-lime silica container imports. Bottom-up volume builds triangulated against top-down industry spend estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without discrete year anchoring. Segmentation dimensions modeled include glass chemistry grade, capacity specification, closure mechanism type, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to segment-level baseline volumes. Industry-specific forecast inputs incorporated natural gas price trajectory assumptions and craft brewery taproom expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese clear-glass exporters or rapid aluminum can technology advancement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Glass Veil Market