
 Sweden Container Glass Market | 2026-2036
Sweden Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Container Glass Market Insights
Sweden is rewriting container glass competitiveness in Northern Europe through sustained capacity investment and energy-efficient furnace upgrades. Ardagh Glass Limmared AB leverages its historic Limmared facility to anchor premium beverage bottle supply across Scandinavia. Stoelzle Glass Group competes through pharmaceutical vial specialization, serving Nordic drug manufacturers with ISO-certified production lines. Gerresheimer Sweden AB dominates medical-grade container segments through GMP-compliant manufacturing and direct hospital channel control.
Container glass consists of silica sand, soda ash, limestone, and recycled cullet melted at temperatures exceeding 1500°C, then formed by blow-and-blow or press-and-blow processes into hollow vessels for liquid and solid product containment. Its primary commercial purpose centers on inert, impermeable, and infinitely recyclable packaging for food, beverages, and pharmaceuticals. Beverage bottles lead volume demand within the product type dimension, while pharmaceutical containers command the strongest margin pools due to GMP validation requirements and low substitution risk. Light weight design types are expanding fastest as brands pursue Scope 3 emissions reductions and logistics cost containment across Nordic distribution networks.
The Swedish Chemicals Agency enforces REACH compliance for surface treatments and decorative coatings, while the Swedish Food Agency mandates migration testing for food-contact glass, collectively elevating quality barriers for imported substitutes. The EU Green Deal's packaging and packaging waste regulation shapes demand by mandating recycled content minimums and extended producer responsibility schemes. Stakeholders must monitor furnace decarbonization technology readiness and cullet supply chain localization decisions as electrification timelines crystallize.
Market Dynamics
Electrification of glass furnaces is compressing capital allocation timelines across Swedish container glass manufacturing, as furnace rebuild cycles collide with EU Green Deal mandates for Scope 1 emissions elimination.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content minimums and extended producer responsibility schemes are pulling lightweight container adoption forward across Nordic beverage supply chains.
- Pharmaceutical serialization requirements:Track-and-trace regulations for drug packaging are cementing glass as the preferred primary container material for Nordic drug manufacturers.
- Stockholm manufacturing corridor concentration:Food and beverage production clustering in the capital region is generating localized demand pull for just-in-time container supply.
Market Restraints
- Natural gas price volatility:Furnace energy input costs remain structurally exposed to European gas market fluctuations despite electrification pilots.
- Cullet supply concentration:Recycled glass feedstock availability concentrates in southern Sweden, creating geographic imbalance for northern furnace operations.
- Aluminum substitution in beverage:Cans are capturing share in carbonated soft drinks and beer segments where brand premiumization is weaker.
Strategic Opportunities
- Gothenburg pharmaceutical hub expansion:The west coast drug manufacturing cluster remains underpenetrated for specialized parenteral container supply.
- Biopharma cold chain packaging:Cell and gene therapy logistics requirements are opening demand for borosilicate glass vials with validated thermal protection.
- Swedish Chemicals Agency coating exemptions:Streamlined approval pathways for organic surface treatments are enabling functional glass differentiation.
Industry Challenges
- Furnace engineering talent scarcity:Electrification retrofit expertise is concentrated among a handful of European equipment suppliers, extending project timelines.
- GMP validation cycle compression:Pharmaceutical customers are demanding concurrent qualification of new container formats, straining quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Container Glass Market |
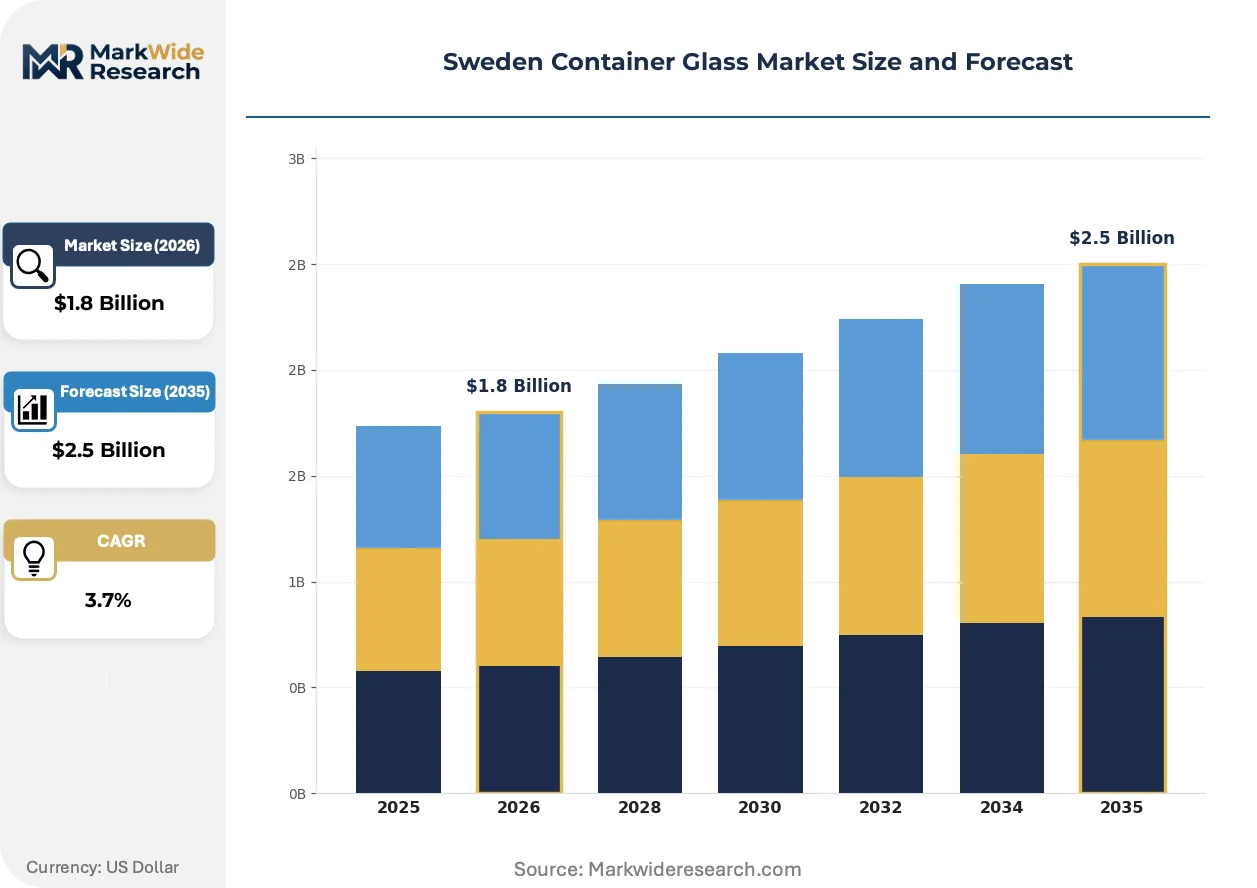
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer Bottles, Beverage Bottles, Food Jars, Cosmetic Containers End Use Industry: Beverage, Food, Pharmaceuticals, Personal Care Design Type: Standard, Custom, Light Weight, Full-Body Shrink Sleeve Capacity: 100-350 ml, 350-750 ml, 750-1000 ml, Over 1000 ml |
| Companies Covered | Ardagh Glass Limmared AB, Stoelzle Glass Group, SGD Group S.A.S., Gerresheimer Sweden AB, Verallia Sweden AB, Ardagh Glass Holmegaard, Holmegaard, Vetropack, Arvid Nordquist HAB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Container Glass Market Trends and Innovations
Oxy-fuel combustion technology and digital furnace control systems are rewriting energy efficiency benchmarks across Swedish glass manufacturing, while regulatory pressure on embodied carbon accelerates material science experimentation.
Electric melting technology is collapsing the conventional furnace rebuild economics that have governed container glass manufacturing for decades. Premium beverage brands in Sweden are piloting all-electric furnace output for carbon-neutral product lines. The technology is collapsing the ten-year capital cycle assumption that has historically delayed sustainability investments.
REACH surface treatment restrictions are forcing reformulation of decorative coatings and organic inks used in Swedish container glass production. The Swedish Chemicals Agency enforcement is elevating compliance costs for imported decorated containers. Pharmaceutical segments are responding by shifting to laser-etched or molded-in branding to eliminate coating dependencies entirely.
Direct procurement relationships between container glass manufacturers and craft beverage brands are displacing traditional distributor-mediated supply arrangements. Stockholm-area microbreweries and spirits producers are negotiating volume-flexible contracts with Limmared-based suppliers. This pattern is most visible in the capital region's food and beverage manufacturing corridor, where batch-size agility outweighs scale economics.
Sweden Container Glass Market Segmentation
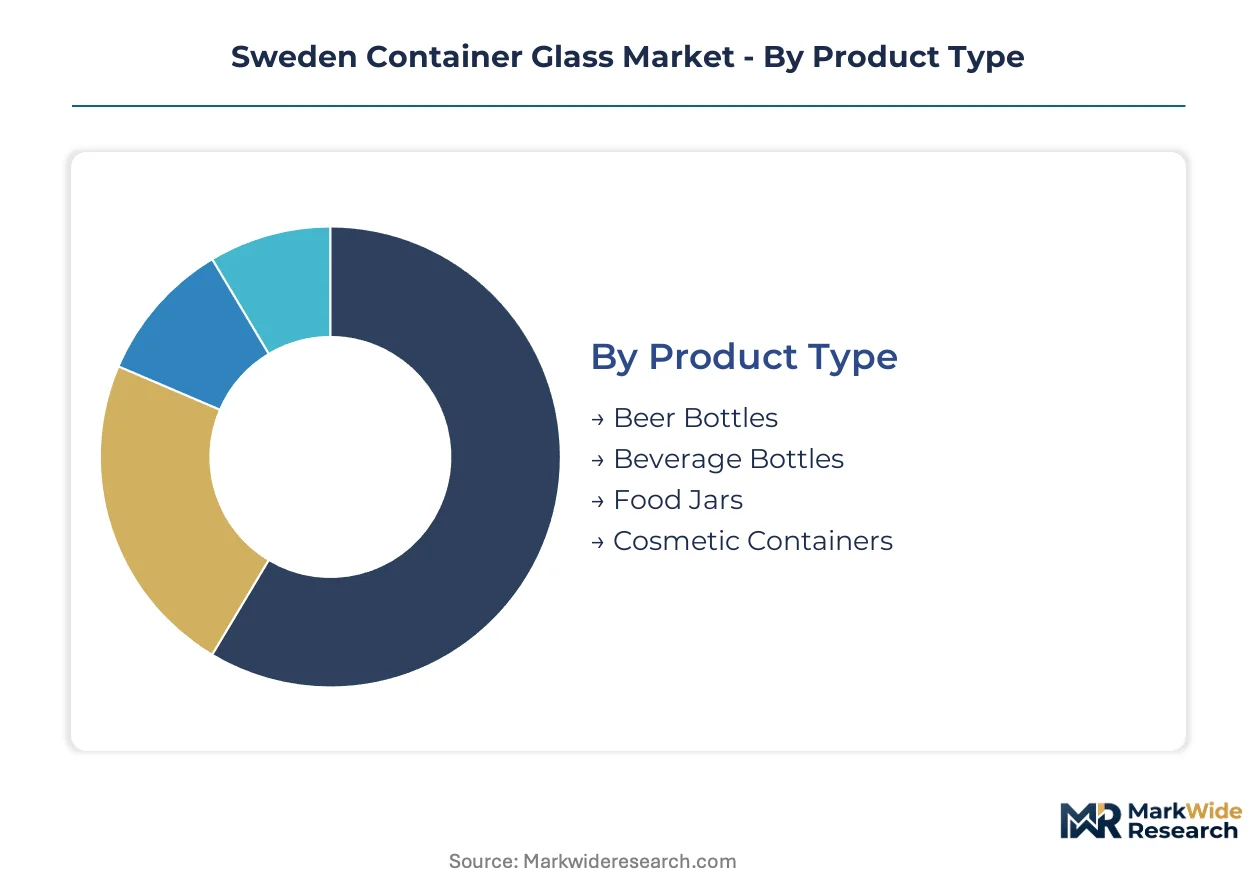
Segmentation in Sweden's container glass market reveals divergent capital cycles and margin structures across product categories. Understanding these distinctions enables suppliers to align furnace capacity with demand velocity and regulatory exposure.
Product Type:
Beverage bottles turn inventory fastest with seasonal demand spikes, while pharmaceutical containers operate on multi-year qualification cycles that lock in supply relationships.
- Beverage Bottles:Soda-lime silica construction with variable wall thickness specifications supports carbonated and still liquid containment. Stockholm's craft spirits producers and microbreweries are pulling demand toward smaller batch formats with shorter lead times.
- Beer Bottles:Amber and flint glass variants with crown finish standardization dominate returnable and single-use formats. Ardagh Glass Limmared AB anchors supply for Nordic brewing conglomerates, though aluminum substitution is compressing volume growth in mainstream lager segments.
- Food Jars:Wide-mouth configurations with vacuum lug finishes for preserved goods and condiments.
- Cosmetic Containers:Premium flint and colored glass with decorative coating compatibility for skincare and fragrance brands.
Beverage bottles dominate installed base. Light weight design types are where expansion concentrates.
End Use Industry:
Margin tiers separate highly regulated pharmaceutical applications from commoditized beverage packaging, with food and personal care occupying intermediate positions.
- Pharmaceuticals:Borosilicate and soda-lime glass vials, ampoules, and syringes manufactured under GMP and ISO 15378 standards. Gerresheimer Sweden AB controls hospital channel distribution, while serialization mandates under EU MDR cement glass as the primary container material for Nordic drug manufacturers.
- Beverage:Carbonated soft drinks, spirits, wine, and beer packaging with high volume velocity and pronounced seasonality.
- Food:Preserved vegetables, sauces, and spreads requiring thermal processing compatibility and migration-tested surfaces per Swedish Food Agency protocols.
- Personal Care:Fragrance, skincare, and haircare containers where decorative differentiation commands premium positioning.
Pharmaceuticals commands margin leadership. Beverage represents the fastest-growing trajectory in absolute volume terms.
Design Type:
Engineering complexity and material efficiency trade-offs define competitive positioning across design categories.
- Light Weight:Wall thickness reduction of 15-30% versus conventional designs through optimized parison programming and enhanced surface coatings. EU Green Deal packaging mandates are accelerating adoption across Nordic beverage supply chains as brands pursue Scope 3 emissions reductions.
- Custom:Proprietary mold designs with embossed branding and unique silhouettes for premium positioning.
- Standard:Industry-common formats with minimal differentiation and lowest unit cost.
- Full-Body Shrink Sleeve:Container geometries optimized for polymer sleeve application, enabling 360-degree decoration without direct glass coating.
Standard designs dominate installed base. Light weight configurations are gaining share fastest as electrification timelines compress.
Capacity:
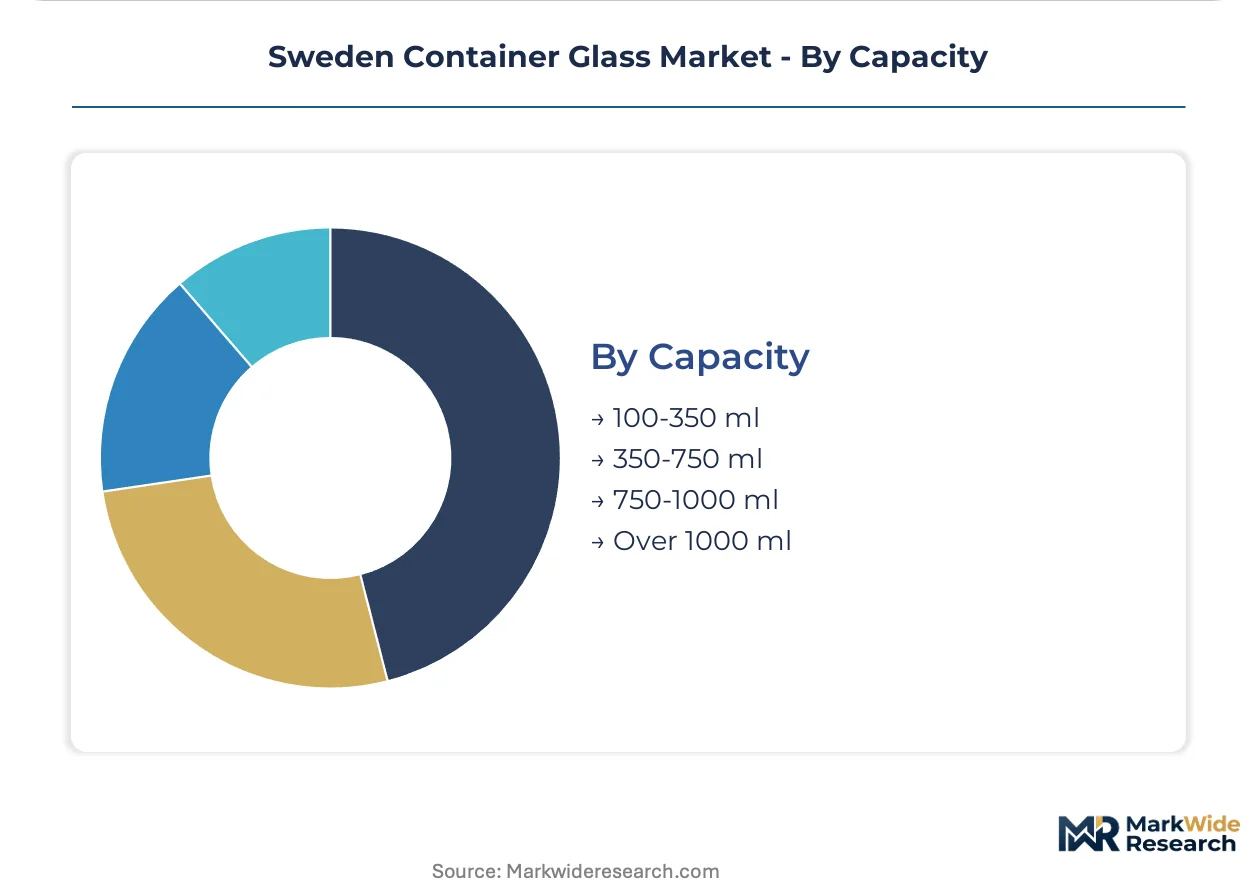
Logistics economics and consumption occasion patterns segment demand across volume thresholds.
- 350-750 ml:Standard wine, spirits, and specialty beverage formats balancing shelf presence with handling efficiency. Stockholm's manufacturing corridor concentrates demand for this mid-range capacity where retail packaging and food service requirements overlap.
- 750-1000 ml:Wine standard and spirits premium formats with established supply chain tooling.
- 100-350 ml:Single-serve beverages, pharmaceutical vials, and travel-size personal care.
- Over 1000 ml:Bulk food service and industrial ingredient containment with lower velocity.
350-750 ml dominates installed base. 100-350 ml is where expansion concentrates for pharmaceutical and premium beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Gothenburg's deep-water container terminals and rail connections to continental Europe anchor Sweden's container glass distribution architecture across the Nordic-Baltic corridor.
Stockholm Manufacturing Corridor
Stockholm County concentrates beverage bottling demand from craft spirits producers and microbreweries seeking just-in-time glass supply. The Swedish Food Agency enforces migration testing protocols for food-contact surfaces. Södertälje's logistics parks host regional distribution centers serving the capital's food and beverage manufacturing cluster.
Gothenburg Pharmaceutical Hub
Västra Götaland County generates specialized demand for parenteral containers from biopharma manufacturing expansion. The EU MDR serialization mandates cement glass primary packaging for Nordic drug producers. Mölndal's life science cluster drives borosilicate vial requirements for cell and gene therapy cold chain applications.
Småland Glass Belt
Kronoberg and Jönköping counties maintain historic furnace operations with cullet recycling infrastructure. REACH compliance for surface treatments elevates quality barriers for imported substitutes. The Limmared facility anchors premium beverage bottle supply across Scandinavia through upgraded oxy-fuel combustion systems.
Skåne Logistics Gateway
Malmö and Helsingborg position recycled glass feedstock consolidation for southern furnace operations. Extended producer responsibility schemes under EU Green Deal packaging regulation shape cullet collection economics. The Öresund Bridge corridor enables just-in-time delivery to Copenhagen-area beverage manufacturers.
Sweden Container Glass Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and equipment fabrication. The Swedish container glass market exhibits consolidated manufacturing capacity with tiered specialization across beverage, pharmaceutical, and food packaging verticals. Three archetypes dominate: integrated multinational furnace operators, pharmaceutical-grade specialists with GMP certification, and regional niche suppliers serving craft beverage segments. Competitive dynamics center on electrification retrofit timelines and direct procurement relationships displacing distributor-mediated supply.
Among Nordic-integrated furnace operators, Ardagh Glass Limmared AB and Verallia Sweden AB exemplify the scale-driven archetype with historic facility assets. Gerresheimer Sweden AB occupies the pharmaceutical-grade specialist position through medical-grade container segments. Stoelzle Glass Group represents the precision-fabrication tier serving pharmaceutical vial demand with ISO-certified production lines. These three anchors illustrate the market's structural segmentation between volume beverage supply and high-margin regulated pharmaceutical packaging.
| Leading Market Players |
|---|
| Ardagh Glass Limmared AB |
| Stoelzle Glass Group |
| SGD Group S.A.S. |
| Gerresheimer Sweden AB |
| Verallia Sweden AB |
| Ardagh Glass Holmegaard |
| Holmegaard |
| Vetropack |
| Arvid Nordquist HAB |
| Others |
Pricing and Supply Chain Analysis
The Öresund Bridge corridor freight dynamics compress delivery cost differentials between southern Swedish furnace operations and Copenhagen-area beverage manufacturers, amplifying volume-discount leverage for multi-site procurement while forcing smaller Stockholm craft producers toward premium positioning.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical GMP-certified containers from commodity beverage bottles, with price differentiation anchored in certification grade and geographic delivery cost. Premium-mid-economy pricing differentiation stratifies across electrification retrofit status, where furnace decarbonization credentials command carbon-neutral product line premiums. Cost compression in standard beverage tiers intensifies because aluminum substitution erodes volume commitments. Craft spirits producers exhibit highest price sensitivity; pharmaceutical serialization mandates render Nordic drug manufacturers least sensitive to unit cost fluctuations.
Supply Chain Analysis
Contract-manufacturing concentration rests on Ardagh Glass Limmared AB and Verallia Sweden AB as dominant furnace operators, with Gerresheimer Sweden AB anchoring pharmaceutical-grade capacity. Geographic supply concentrates in Sweden, Denmark, and Germany as the Nordic-Baltic manufacturing cluster. Raw material dependencies center on silica sand from Nordic quarries, soda ash from European chemical producers, and recycled cullet from southern Swedish collection networks. Single-source vulnerability in cullet feedstock creates geographic imbalance for northern operations. Distribution runs through direct procurement relationships displacing traditional distributor-mediated supply, particularly visible in Stockholm's manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand through furnace retrofit consulting and electrification compliance advisory, where recurring engineering services outpace container hardware growth as EU Green Deal mandates compress capital cycles.
For Market Incumbents: Insulate premium beverage relationships through captive cullet supply contracts in Småland, while accelerating GMP validation bandwidth to capture biopharma cold chain expansion in Mölndal. Aluminum substitution in mainstream lager segments threatens volume commitments; vertical integration into oxy-fuel combustion technology sourcing defends margin position against equipment supplier scarcity. For New Entrants and Emerging Players: Gothenburg pharmaceutical hub parenteral container supply represents the most penetrable entry point, with borosilicate vial thermal protection specialization offering qualification-fast-track potential. Stockholm craft spirits microbreweries present secondary white-space through batch-size-flexible furnace access. Direct procurement negotiation capability, bypassing traditional distributor layers, constitutes the essential go-to-market angle. For Investors and Strategic Acquirers: EU Green Deal packaging regulation implementation reshapes the acquisition landscape toward electrification-ready furnace assets and localized cullet infrastructure control. Five-to-ten year viability favors pharmaceutical-grade specialists with ISO 15378 certification and hospital channel distribution locked through Gerresheimer-type direct relationships. Furnace engineering talent concentration among European equipment suppliers signals the critical inflection indicator for retrofit timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Retrofit | Ardagh's Limmared facility upgrades anchor carbon-neutral premium bottle supply for Nordic beverage brands. |
| Cullet Supply Chain Localization | Southern Sweden recycling infrastructure consolidation reduces feedstock transport cost exposure for northern operations. |
| GMP Validation Cycle Expansion | Gerresheimer's concurrent qualification capacity captures biopharma serialization demand under EU MDR mandates. |
| Direct Procurement Relationship Development | Stockholm microbrewery volume-flexible contracts displace distributor-mediated supply in craft beverage segments. |
| Borosilicate Cold Chain Specialization | Mölndal cell and gene therapy logistics requirements open validated thermal protection vial demand. |
Research Methodology
The analysis maps beverage bottle, pharmaceutical container, food jar, and cosmetic container sub-sectors, each validated through furnace operations managers, pharmaceutical quality assurance directors, and beverage procurement leads. Primary interviews with Swedish Chemicals Agency compliance officers, Nordic brewing conglomerate supply chain heads, and hospital pharmacy procurement managers combined with secondary validation through Swedish Food Agency migration testing protocols, EU MDR serialization guidelines, SEC filings of listed glass manufacturers, and Nordic customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumption sets held EU Green Deal packaging regulation timelines and natural gas price trajectories fixed while varying electrification technology readiness and aluminum substitution rates across scenarios. Segmentation dimensions modeled include product type, end-use industry, design type, and capacity tier across the projection horizon. CAGRs derived from furnace rebuild cycle alignment with regulatory mandates, with industry-specific inputs incorporating pharmaceutical serialization compliance costs and lightweight design adoption curves in beverage supply chains.
Macroeconomic conditions sit as an overlay; deviation in European energy market volatility and recycled glass feedstock availability would shift the trajectory. Forecasts reflect documented assumptions regarding electrification subsidy continuity and REACH surface treatment enforcement intensity. Quarterly review of furnace retrofit project announcements and pharmaceutical GMP inspection outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
China Glass Container Packaging Market