
 Glass Liquor Bottles Market | 2026-2036
Glass Liquor Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Liquor Bottles Market Foresight
Project finance for oxy-fuel furnace retrofits is reshaping capital deployment across container glass manufacturing. Verallia leverages long-term power-purchase agreements to lock in renewable energy for its French and Italian facilities. O-I Glass sustains manufacturing scale through asset-light leasing models in North American markets. Ardagh Group anchors European supply with vertical integration into cullet recovery and batch processing.
Glass liquor bottles are rigid silica-soda-lime containers engineered to 2.5–4.0 mm wall thickness, formed through IS machine blow-and-blow or press-and-blow processes, with thermal shock resistance exceeding 42°C for pasteurization compatibility. Their primary purpose is to protect alcoholic beverages from UV degradation and oxygen ingress while conveying brand equity through tactile and visual properties. Flint bottles command premium positioning in super-premium vodka and gin segments where clarity signals purity. Amber bottles dominate whiskey and aged rum portfolios where UV-blocking properties extend shelf stability. The 750 ml capacity standard occupies the largest volume share across distillery procurement, though 375 ml formats are gaining traction in airport retail and tasting-room channels.
EPA emissions standards under the Clean Air Act constrain furnace rebuild timelines for US-based producers, while REACH and the EU Green Deal mandate cullet incorporation rates that alter batch chemistry and energy intensity. FDA contact-substance regulations for glass packaging require migration testing protocols that add compliance cost but also create barrier-to-entry protection for certified suppliers. Stakeholders must monitor oxy-fuel conversion timelines and carbon-border adjustment mechanisms to anticipate which production bases gain or lose cost-competitive position.
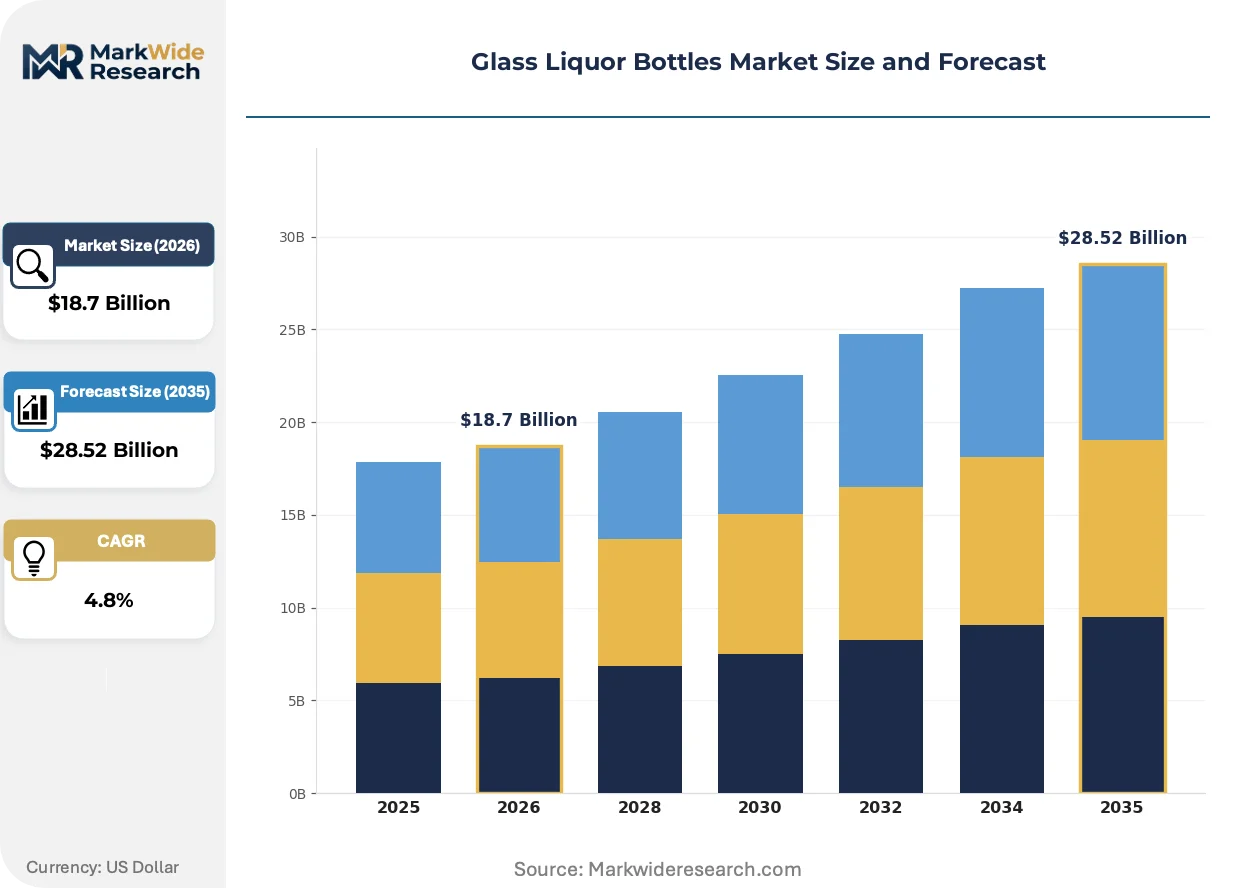
Market Dynamics
Oxy-fuel furnace retrofits are compressing capital cycles across container glass manufacturing as producers race to comply with tightening emissions frameworks while defending energy-intensive production economics.
Growth Catalysts
- EU Green Deal mandates:Binding cullet incorporation targets under the F-Gas Regulation are forcing furnace upgrades that lower per-unit energy consumption and unlock carbon-border adjustment compliance for European exporters.
- Super-premium spirits positioning:Distillers in France and the United States are specifying flint glass for vodka and gin portfolios where bottle clarity signals product purity and commands shelf price premiums.
- Airport retail expansion:The 375 ml format is gaining procurement share in travel retail channels where volume restrictions and tasting-room sampling drive smaller-format demand.
Market Restraints
- Natural gas price volatility:Furnace operations depend on natural gas for 60-70% of thermal energy, exposing producers to input cost swings that compress margin visibility on multi-year supply contracts.
- Concentrated soda ash supply:US and Turkish suppliers dominate global soda ash production, creating geographic concentration risk for batch chemistry inputs.
- Alternative packaging substitution:PET and aluminum bottles are penetrating value-tier spirits segments where UV protection and oxygen barrier requirements are less stringent.
Strategic Opportunities
- Mexico distillery cluster expansion:Tequila and mezcal production growth in Jalisco and Oaxaca is creating localized bottle demand that favors regional glass manufacturing investment over import dependency.
- Renewable energy power-purchase agreements:Long-term PPAs for wind and solar are enabling producers to lock in below-grid electricity rates and meet Scope 2 reduction targets under the EU Green Deal.
- Lightweighting technology convergence:Advanced IS machine controls combined with predictive hot-end coating are enabling wall-thickness reduction without sacrificing thermal shock resistance.
Industry Challenges
- Refractory engineering talent scarcity:Specialized furnace design and rebuild expertise is concentrated among retiring cohorts, constraining oxy-fuel conversion timelines.
- Migration testing certification backlog:FDA contact-substance protocols require extended laboratory timelines that delay new bottle design launches for craft distillers.
- Cullet quality standardization:Inconsistent post-consumer glass recovery streams complicate batch chemistry optimization and color consistency for amber whiskey bottles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Liquor Bottles Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flint Bottles, Amber Bottles, Green Bottles, Colored Bottles, Frosted Bottles Capacity: 187 ml, 375 ml, 500 ml, 750 ml, 1 Liter End User: Distilleries, Bars & Lounges, Retail Stores, Event Organizers, Home Consumers Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Specialty Shops, Supermarkets |
| Companies Covered | Gallo Glass, Verallia, O-I Glass, Saxco International, Saverglass, Ardagh Group, Stoelzle Glass Group, Vitro, Anchor Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Liquor Bottles Market Shifts & Advancements
Electrification of glass melting and digital twin deployment are converging to reshape furnace economics, while regulatory carbon accounting and spirits brand premiumization are rewriting procurement specifications.
Hybrid electric-boost furnace architectures are collapsing the energy intensity gap between conventional fossil-fired systems and full electrification. Ardagh Group and Verallia are piloting 30-50% electric boost configurations at French and Italian facilities. This technology is collapsing the payback period for renewable energy integration by reducing furnace dependence on volatile natural gas combustion.
The EU F-Gas Regulation and companion carbon-border adjustment mechanism are tightening emissions disclosure requirements for imported glass containers. Container glass producers must now document embedded carbon per bottle to maintain access to EU spirits markets. Amber whiskey bottles face the steepest compliance burden due to higher melting temperatures and colorant chemistry complexity.
Direct distillery procurement contracts are displacing traditional distributor-mediated bottle sourcing for mid-sized craft spirits producers. Tasting-room and e-commerce channel growth is enabling brands to specify custom mold designs without minimum volume thresholds imposed by legacy three-tier distribution. This pattern is most visible in United States craft whiskey and gin segments where 750 ml and 375 ml custom flint designs command brand differentiation premiums.
Glass Liquor Bottles Market Segmentation
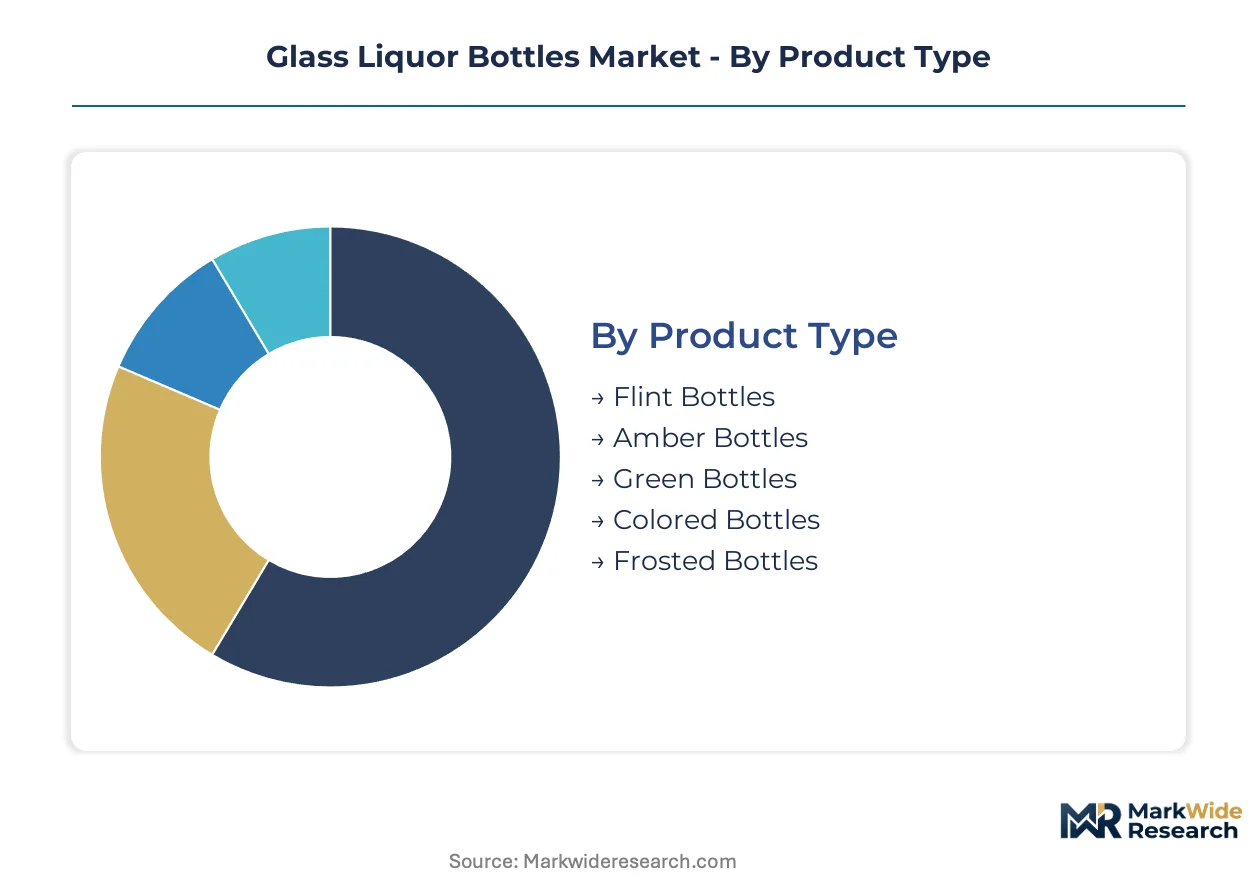
Glass liquor bottle procurement splits across technical specifications, volume formats, and channel economics. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape supplier selection and furnace capacity allocation.
Product Type:
Mature color categories dominate distillery procurement while specialty finishes carve premium positioning.
- Flint Bottles:Silica-soda-lime glass with zero colorant addition delivers maximum clarity and UV transmission for visual purity signaling. Super-premium vodka and gin brands in the United States and France specify flint for shelf differentiation where transparency connotes filtration quality.
- Amber Bottles:Iron-sulfur colorant chemistry absorbs wavelengths below 500 nm, blocking photochemical degradation of lignin-derived flavor compounds. Whiskey and aged rum portfolios across Kentucky and Scotland mandate amber for oxidation stability during multi-year maturation cycles.
- Green Bottles:Chromium oxide coloration provides moderate UV attenuation at lower melting energy than amber variants. Certain wine-spirit hybrids and regional liqueurs specify green for heritage aesthetic alignment.
- Colored Bottles:Cobalt blue and custom Pantone-matched batches serve limited-edition releases and brand anniversary positioning.
- Frosted Bottles:Acid-etched or sandblasted surface treatment creates tactile differentiation for gift-set packaging and duty-free exclusives.
Flint bottles handle the majority of throughput; frosted bottles are expanding most quickly on share.
Capacity:
Format economics track channel restrictions and consumption occasion fragmentation.
- 750 ml:The distillery procurement standard balances production efficiency with three-tier distribution case-pack optimization. This format dominates bonded warehouse inventory and retail shelf placement across the United States and Mexico.
- 375 ml:Half-bottle sizing aligns with airport retail volume restrictions and tasting-room sampling protocols. Travel retail expansion in Dubai and Singapore is accelerating procurement of this format for premium spirits portfolios.
- 187 ml:Single-serve airline and hotel minibar specifications drive batch production in flint and amber variants.
- 500 ml:Regional European markets and craft distillery direct-to-consumer channels favor this intermediate format.
- 1 Liter:Duty-free exclusive and commercial bar back-stock applications concentrate demand in this oversized format.
750 ml commands absolute volume; 375 ml posts the steepest expansion trajectory.
End User:
Customer type determines mold complexity tolerance and order frequency patterns.
- Distilleries:Large-scale producers run annual procurement cycles with dedicated mold investments and color consistency requirements. Brown-Forman and Diageo operations anchor furnace capacity planning for amber whiskey bottles.
- Bars & Lounges:On-premise accounts prioritize breakage resistance and pour-control neck finishes over custom aesthetics.
- Retail Stores:Off-premise merchandising drives label adhesion performance and case-stack stability specifications.
- Event Organizers:Wedding and corporate gifting segments generate seasonal demand spikes for engraved and frosted variants.
- Home Consumers:Direct-to-consumer subscription channels are emerging for curated spirits clubs seeking 375 ml discovery formats.
Distilleries absorb the bulk of production runs; home consumers represent the fastest-climbing demand category.
Distribution Channel:
Channel structure dictates lead time requirements and minimum order thresholds.
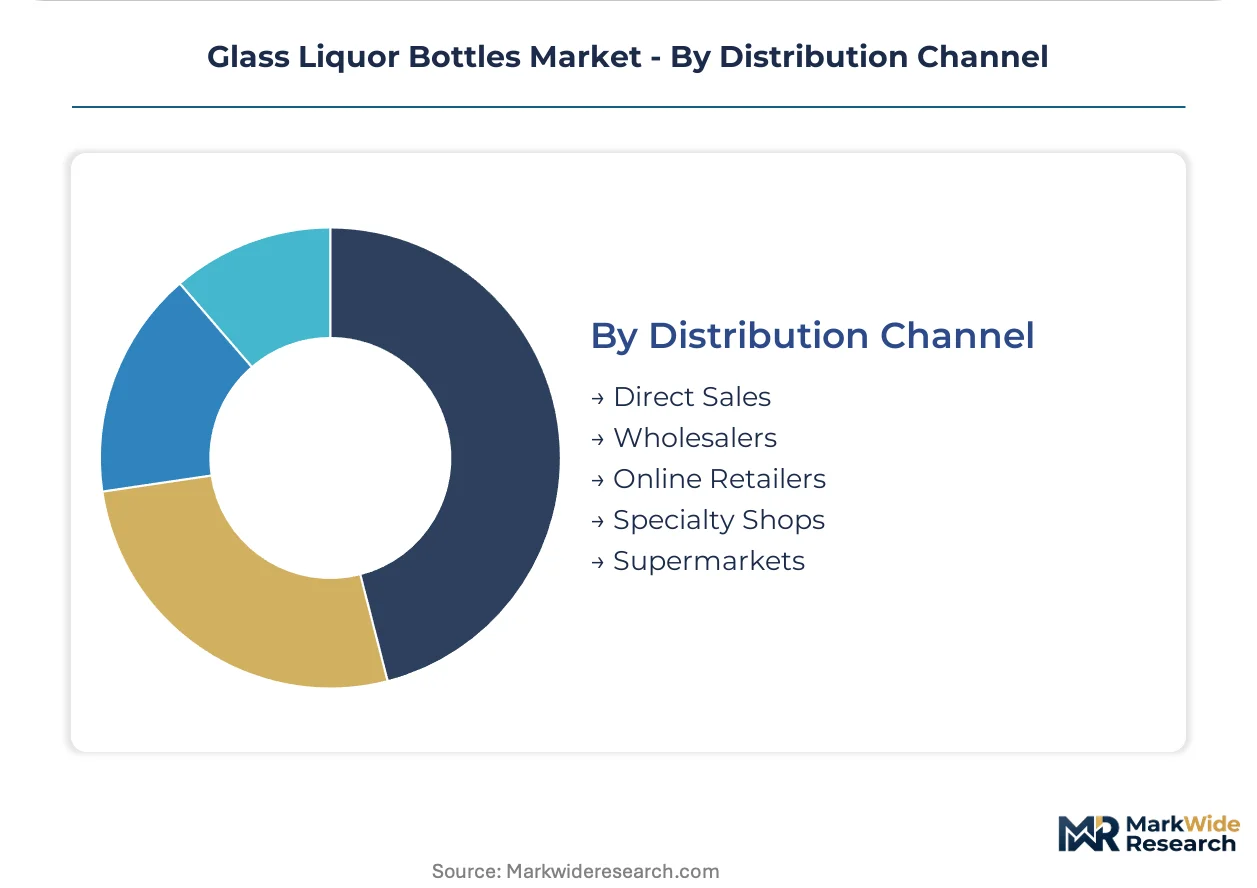
- Direct Sales:Distillery-producer relationships eliminate distributor margin and enable custom mold amortization across multi-year contracts. This channel concentrates in Jalisco tequila clusters and Kentucky bourbon corridors.
- Wholesalers:Three-tier system intermediaries aggregate fragmented craft distillery demand into furnace-minimum batch sizes.
- Online Retailers:E-commerce fulfillment requires enhanced breakage packaging and individual bottle labeling capabilities.
- Specialty Shops:Independent retailers drive SKU proliferation for limited-release and regional spirit varieties.
- Supermarkets:Mass retail chains enforce standardized neck finishes and case dimensions for automated warehousing compatibility.
Direct sales lock in the largest committed volumes; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU carbon-border adjustment mechanisms and US EPA emissions standards are redirecting furnace investment toward jurisdictions with renewable energy access and established distillery clusters.
United States
Kentucky bourbon and Tennessee whiskey producers anchor amber bottle procurement volumes. EPA Clean Air Act timelines constrain furnace rebuild schedules across Ohio and Pennsylvania manufacturing bases. Distillery clusters in Louisville and Nashville sustain dedicated supply contracts with multi-year mold amortization structures.
France
Super-premium vodka and gin brands in Cognac and Champagne regions specify flint glass for clarity-driven shelf positioning. EU Green Deal cullet incorporation mandates alter batch chemistry at furnace operations in Normandy and Alsace. Verallia's renewable energy power-purchase agreements lock in below-grid electricity rates at French facilities.
Mexico
Tequila and mezcal production expansion in Jalisco and Oaxaca generates localized bottle demand exceeding import capacity. Mexican environmental regulators enforce emissions disclosure protocols aligned with EU carbon-border requirements. Glass manufacturing investment concentrates in Guadalajara corridor to serve distillery clusters in Tequila and Arandas.
Italy
Grappa and amaro producers in Piedmont and Veneto sustain mid-volume flint and amber procurement cycles. EU F-Gas Regulation compliance costs favor producers with oxy-fuel retrofit completion at northern Italian furnace sites. Specialty bottle finishing operations cluster around Milan for proximity to luxury spirits brand headquarters.
Germany
Whiskey and craft gin distilleries in Bavaria and Baden-Württemberg drive custom mold demand for limited-release positioning. REACH chemical registration requirements extend migration testing timelines for new bottle designs. Container glass production concentrates in North Rhine-Westphalia with backward integration into regional cullet recovery networks.
Glass Liquor Bottles Market Competitive Landscape
On the supply side, the industry is consolidating around integrated producers with captive cullet supply and renewable energy contracts. Container glass manufacturing exhibits tiered structure with global scale operators, regional specialists, and craft-focused custom mold providers. Strategic archetypes include furnace-scale consolidators, sustainability-first vertically integrated players, and agile custom design specialists. Dominant competitive moves encompass oxy-fuel furnace retrofit acceleration and long-term renewable energy power-purchase agreement execution.
Among European-headquartered producers, Verallia, Saverglass, and Stoelzle Glass Group occupy positions spanning premium custom design through standardized volume production. Verallia exemplifies the sustainability-integrated archetype through renewable energy contracting. Saverglass represents craft-distillery specialization with mold flexibility for smaller batch runs. Stoelzle Glass Group anchors Central European supply with pharmaceutical-grade quality systems adapted to spirits applications.
| Leading Market Players |
|---|
| Gallo Glass |
| Verallia |
| O-I Glass |
| Saxco International |
| Saverglass |
| Ardagh Group |
| Stoelzle Glass Group |
| Vitro |
| Anchor Glass |
| Others |
Supply & Pricing Matrix
Natural gas price volatility determines both furnace operating cost spreads and supply chain regionalization as producers seek renewable energy hedges. Amber whiskey bottles carry the widest premium-to-standard tier gaps due to higher melting temperatures and colorant chemistry complexity.
Pricing Analysis
Certification level creates the primary spread between FDA-grade migration-tested bottles and uncertified commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects flint clarity grades, amber UV-blocking performance, and frosted finish customization. Cost compression in standard flint segments is intensifying because PET substitution threatens volume-tier spirits. Craft distilleries show highest price sensitivity due to minimum order constraints, while super-premium brands absorb premiums for custom mold amortization.
Supply Chain Analysis
Verallia, O-I Glass, and Ardagh Group hold dominant furnace capacity across France, the United States, and Mexico. Batch chemistry draws from concentrated Turkish and US soda ash deposits alongside regional silica sand quarries. Single-source vulnerability in refractory engineering talent constrains oxy-fuel retrofit timelines. Distribution runs through direct distillery contracts in Kentucky and Jalisco corridors alongside three-tier wholesaler aggregation for craft producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Custom mold design services and migration testing certification represent the fastest-expanding recurring revenue layers, outpacing base bottle manufacturing as distillery procurement shifts toward direct relationships.
For Market Incumbents: Harden furnace asset utilization through captive cullet recovery networks in Kentucky and Normandy to defend against lightweighting technology disruption. Accelerate oxy-fuel completion before EPA and EU Green Deal timelines tighten to preserve margin position on amber whiskey contracts.
For New Entrants and Emerging Players: Mid-volume craft gin distilleries in Bavaria and Baden-Württemberg represent the most penetrable entry point given REACH testing backlogs delaying incumbent new design launches. Target 375 ml airport retail formats where volume restrictions and tasting-room sampling create SKU fragmentation tolerance.
For Investors and Strategic Acquirers: EU carbon-border adjustment mechanism implementation reshapes the acquisition landscape toward producers with completed renewable energy PPAs and documented embedded carbon protocols. Five-to-ten year viability favors vertically integrated players with backward cullet control. Monitor oxy-fuel retrofit completion rates as inflection indicator for cost-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | EPA Clean Air Act and EU F-Gas Regulation compliance locks in carbon-border access for European exporters. |
| Renewable Energy Power Purchase Agreement | Verallia's French and Italian PPAs secure below-grid electricity rates meeting Scope 2 reduction targets. |
| Custom Mold Design Service | Direct distillery procurement enables tasting-room and e-commerce channel specification without minimum volume thresholds. |
| Cullet Recovery Network Expansion | Ardagh's batch processing integration stabilizes amber color consistency against post-consumer glass variability. |
| Lightweighting Technology Deployment | Advanced IS machine controls enable wall-thickness reduction without sacrificing thermal shock resistance for pasteurization. |
Research Methodology
The analysis maps flint, amber, green, and specialty finish bottle categories, each validated through furnace operations managers, distillery procurement directors, and regulatory compliance officers. Primary interviews with container glass plant engineers, spirits brand supply chain leads, and customs trade specialists combined with secondary validation from EPA emissions filings, EU ETS disclosure databases, and spirits industry production statistics. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Assumptions held fixed include EU Green Deal cullet incorporation mandates and natural gas price volatility patterns, while oxy-fuel conversion timelines and carbon-border adjustment scope were varied across sensitivity scenarios. Segmentation dimensions modeled encompass color chemistry, capacity format, end-user type, and distribution channel structure. CAGRs derived from production volume trajectories at furnace locations, distillery capacity expansion announcements, and travel retail format mix shifts.
Practitioners should monitor refractory engineering labor availability and FDA migration testing certification backlogs for early signals of supply constraint. Forecasts reflect assumptions about regulatory enforcement intensity and spirits premiumization trends. Quarterly review of oxy-fuel retrofit completion rates and renewable energy PPA signings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Germany Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Philippines Container Glass Market