
 Denmark Container Glass Market | 2026-2036
Denmark Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Container Glass Market Outlook
Specialty food exporters and craft distilleries are bifurcating demand away from mass-market beverage bottlers. Ardagh Glass Holmegaard A/S leverages its Danish heritage and furnace scale to dominate premium decorative segments. Vetropack Group anchors Central European supply lines into Danish distribution. Gerresheimer AG specializes in pharmaceutical-grade vial output for Nordic drug manufacturers.
Container glass denotes soda-lime-silica vessels formed through blow-and-blow or press-and-blow processes, typically containing 70-74% silica with thermal shock resistance between 140-200°C, engineered for product protection, shelf visibility, and chemical inertness. Bottles command the largest volume share across Danish food and beverage channels, though pharmaceutical vials extract superior margins from stringent purity requirements. Rigid glass sustains its position against flexible alternatives due to pressure resistance in carbonated applications and established recycling infrastructure.
Denmark's Environmental Protection Agency enforces packaging waste directives that mandate minimum recycled content thresholds, while the Danish EPA's circular economy roadmap tightens end-of-life accountability for producers. The Danish Medicines Agency aligns pharmaceutical glass standards with EU MDR and GDP guidelines for barrier integrity. Stakeholders must weigh furnace electrification timelines against natural gas dependency before committing capital to capacity expansion.
Market Dynamics
Denmark's container glass sector confronts furnace electrification timelines colliding with natural gas supply contracts, forcing producers to restructure capital deployment before 2030 EU ETS thresholds tighten.
Growth Catalysts
- Deposit-Return System Expansion:Denmark's national bottle return infrastructure now captures over 90% of beverage containers, creating guaranteed feedstock streams for cullet-dependent furnaces and lowering raw material procurement volatility.
- Ardagh Glass Holmegaard A/S:The dominant domestic producer has committed to oxy-fuel furnace technology at its Naestved facility, demonstrating scalable decarbonization pathways that reduce Scope 1 emissions intensity.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for glass packaging are accelerating retrofit investments across Danish manufacturing assets ahead of 2030 compliance deadlines.
Market Restraints
- Natural Gas Price Volatility:Danish furnace operators remain tethered to North Sea gas benchmarks, with energy input costs comprising 35-40% of production expenditure and eroding margin stability during supply shocks.
- Furnace Asset Longevity:Glass melting furnaces operate on 12-15 year campaign cycles, locking producers into technology choices made years before electrification economics matured.
- Lightweight Plastic Substitution:Polyethylene terephthalate bottles are capturing share in non-premium beverage segments where carbonation pressure requirements and brand heritage protection matter less.
Strategic Opportunities
- Pharmaceutical Vial Exports:Nordic drug manufacturers are expanding sterile fill-finish capacity, creating demand for borosilicate and soda-lime vials that command 3-4x beverage bottle margins.
- Biogas Integration:Denmark's agricultural biogas sector offers localized renewable fuel alternatives for hybrid furnace operations, potentially qualifying production for green procurement tenders.
- Direct-to-Consumer Craft Channels:Small-batch distilleries and natural wine producers are bypassing traditional distribution, accepting higher per-unit packaging costs for customized bottle designs and shorter runs.
Industry Challenges
- Furnace Engineering Talent Scarcity:Denmark's technical universities produce fewer thermal process engineers than Nordic furnace retirements demand, forcing producers to recruit from Central European labor pools.
- Electrification Capex Burden:Full furnace electrification requires 200-300 million DKK per installation, straining balance sheets already committed to emissions compliance spending.
- Pharmaceutical GDP Certification Timelines:New entrants face 18-24 month qualification periods with the Danish Medicines Agency before securing supply contracts with established drug manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Container Glass Market |
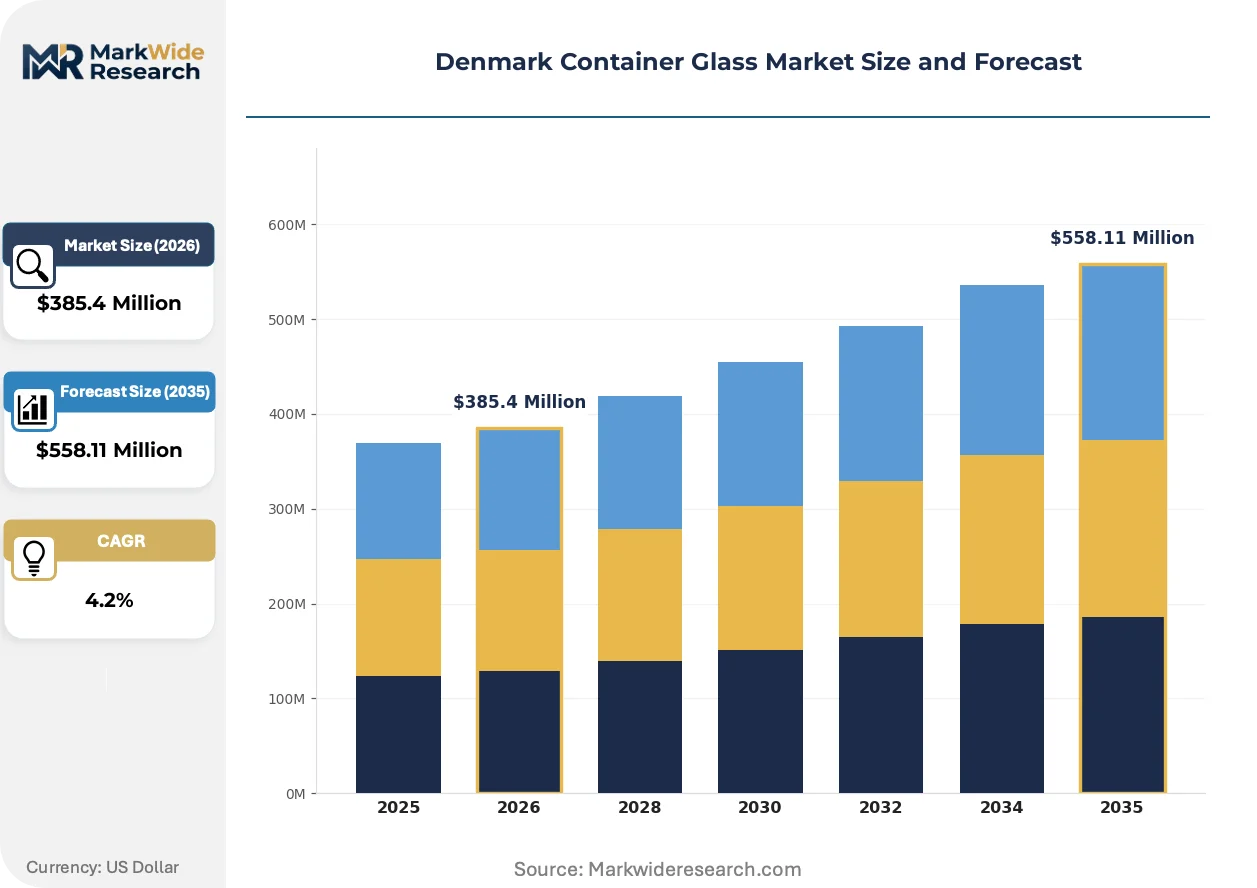
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $558.11 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Closures, Vials End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Form: Rigid Glass, Flexible Glass, Composite Glass, Specialty Glass Distribution Channel: Online Retailers, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Ardagh Glass Holmegaard A/S, Berlin Packaging A/S, Gerresheimer AG, Nova Pack A/S, ABA Packaging Corporation, Vetropack Group, O-I Glass, Inc., Verallia, Vidrala S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Container Glass Market Strategic Shifts
Electrification pathways, regulatory stringency, and buyer fragmentation are simultaneously restructuring production economics and competitive positioning across Danish glass manufacturing.
Oxy-fuel combustion technology is displacing regenerative air-fuel furnaces as the baseline configuration for new Danish capacity. Ardagh Glass Holmegaard A/S has retrofitted its primary Naestved furnace with oxy-fuel burners, cutting NOx emissions by 70% while maintaining thermal efficiency. This technology is displacing conventional furnace architectures as the default specification for Environmental Protection Agency permitting approvals.
Denmark's Environmental Protection Agency is tightening packaging waste enforcement through extended producer responsibility fee structures that penalize virgin material intensity. Industrial consequence: producers now optimize furnace recipes for maximum cullet tolerance, often accepting slight optical variations in favor of recycled content compliance. Premium decorative segments face the steepest fee escalations, forcing Ardagh to segment furnace output between certified high-clarity and standard-grade production lines.
Specialty food exporters are compressing order cycles and expanding SKU proliferation, rejecting the volume commitments that historically justified dedicated furnace campaigns. Danish craft distilleries now request 5,000-unit minimums across 12-15 bottle variants annually, fragmenting production scheduling and elevating changeover costs. This pattern concentrates in Greater Copenhagen's urban distillery cluster, where proximity to export logistics enables just-in-time glass procurement without inventory buffers.
Denmark Container Glass Market Segmentation
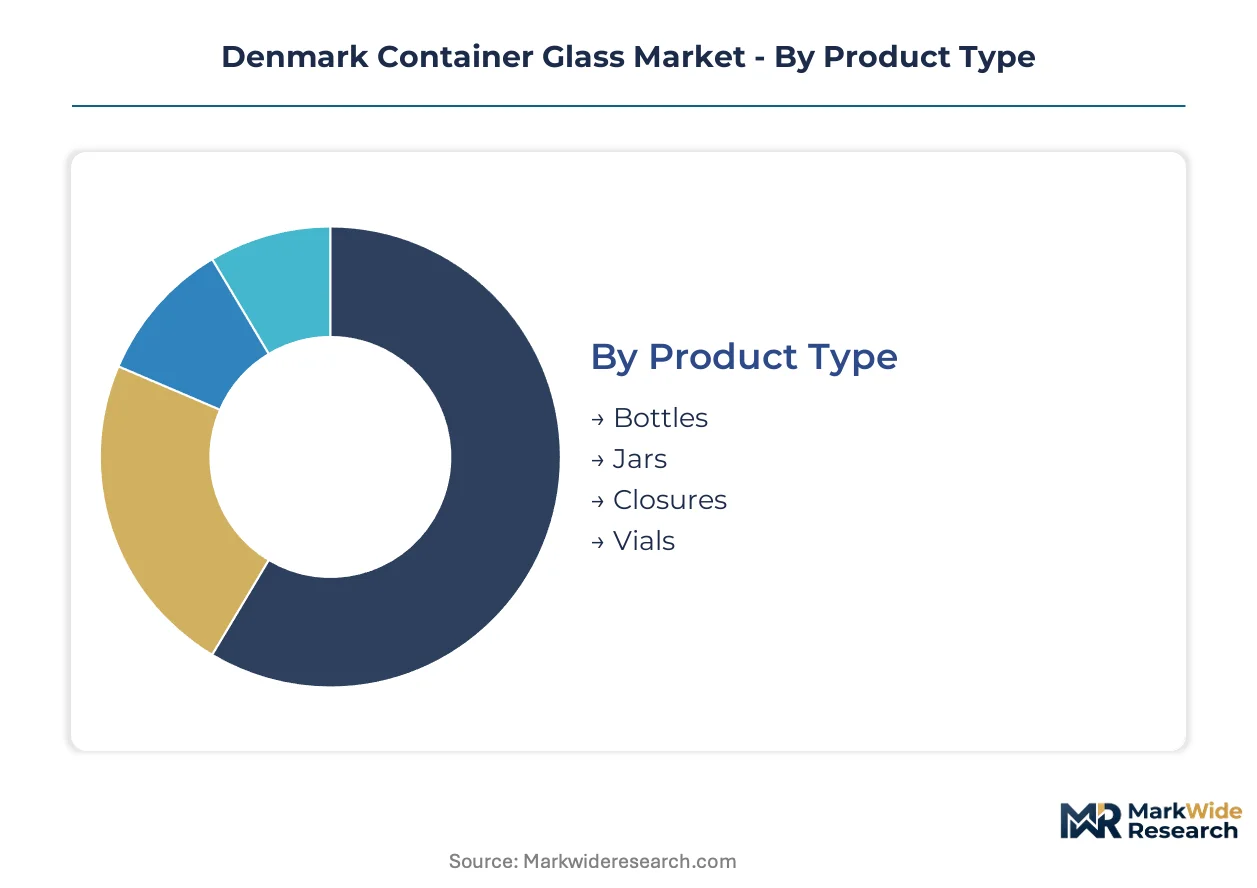
Container glass demand across Denmark fragments across four intersecting dimensions that determine furnace scheduling, cullet tolerance, and margin capture. Product type and end-use specifications dictate thermal process parameters, while distribution channel selection shapes lot sizes and inventory positioning.
Product Type:
Domestic beverage bottlers anchor volume demand in bottles and jars, while pharmaceutical exporters in North Zealand and Medicon Valley drive vial specialization. Closures remain import-dependent with limited Danish furnace adaptation.
- Bottles:Soda-lime-silica construction with 140-200°C thermal shock resistance dominates carbonated beverage and spirits applications. Danish craft distilleries in Greater Copenhagen and Aarhus cluster demand premium heavyweight designs with embossed heritage markings.
- Jars:Wide-mouth configurations with thickened heel walls accommodate thermal processing for preserves and condiments. Specialty food exporters in the Jutland agricultural belt specify hermetic seal surfaces for extended shelf-life logistics to German and Swedish retail.
- Closures:Threaded and lug finishes produced through press-and-blow forming serve matching container threads. Limited domestic production capacity forces reliance on German and Polish supply lines for precision-molded closures.
- Vials:Borosilicate and neutral soda-lime grades meet USP Type I and Type II pharmaceutical standards. Nordic fill-finish contractors in Hillerød and Kalundborg mandate dimensional tolerances within 0.5mm for automated capping lines.
Bottles command the established base. The steepest expansion runs through vials.
End User:
Margin stratification separates commodity beverage contracts from certified pharmaceutical supply agreements, with cosmetics and household products occupying intermediate positions on volume and specification intensity.
- Food & Beverage:Mass-market bottlers in the Odense corridor run dedicated furnace campaigns for standardized amber and flint colors. Deposit-return system compliance mandates specific wall thicknesses for mechanical durability across collection cycles.
- Cosmetics:Decorative flint and cobalt blue containers for skincare and fragrance brands require flame-polished finishes and tight dimensional control. Danish design houses in Copenhagen specify small-batch runs with 48-hour changeover tolerances.
- Pharmaceuticals:Barrier integrity specifications under EU MDR and Danish Medicines Agency guidelines drive borosilicate adoption for parenteral applications. Sterile fill-finish validation protocols extend qualification timelines.
- Household Products:Chemical resistance requirements for cleaning agents and solvents favor thicker wall sections and alkali-resistant surface treatments. Private label concentration in retail chains pressures unit economics.
Food & Beverage anchors volume throughput. Pharmaceuticals extract the highest margin per furnace hour.
Form:
Thermal and mechanical performance specifications divide furnace output between commodity soda-lime and engineered specialty grades, with rigid glass dominating Danish production capacity.
- Rigid Glass:Standard soda-lime-silica composition with 70-74% silica content provides pressure resistance for carbonation and structural integrity for stacking logistics. Danish deposit-return infrastructure depends on rigid durability across reuse cycles.
- Flexible Glass:Ultra-thin drawn sheet configurations below 0.1mm thickness enable conformal wrapping applications. Limited Danish manufacturing presence; primarily sourced from German specialty producers.
- Composite Glass:Polymer-coated or laminated structures combining barrier properties with mechanical flexibility. Emerging adoption in pharmaceutical blister packaging with moisture-sensitive formulations.
- Specialty Glass:Borosilicate and aluminosilicate grades with thermal expansion coefficients below 3.3×10⁻⁶/K serve laboratory and high-temperature applications. Danish technical glass producers in Jutland maintain niche furnace capacity.
Rigid glass dominates installed furnace base. Specialty glass climbs fastest on pharmaceutical certification demand.
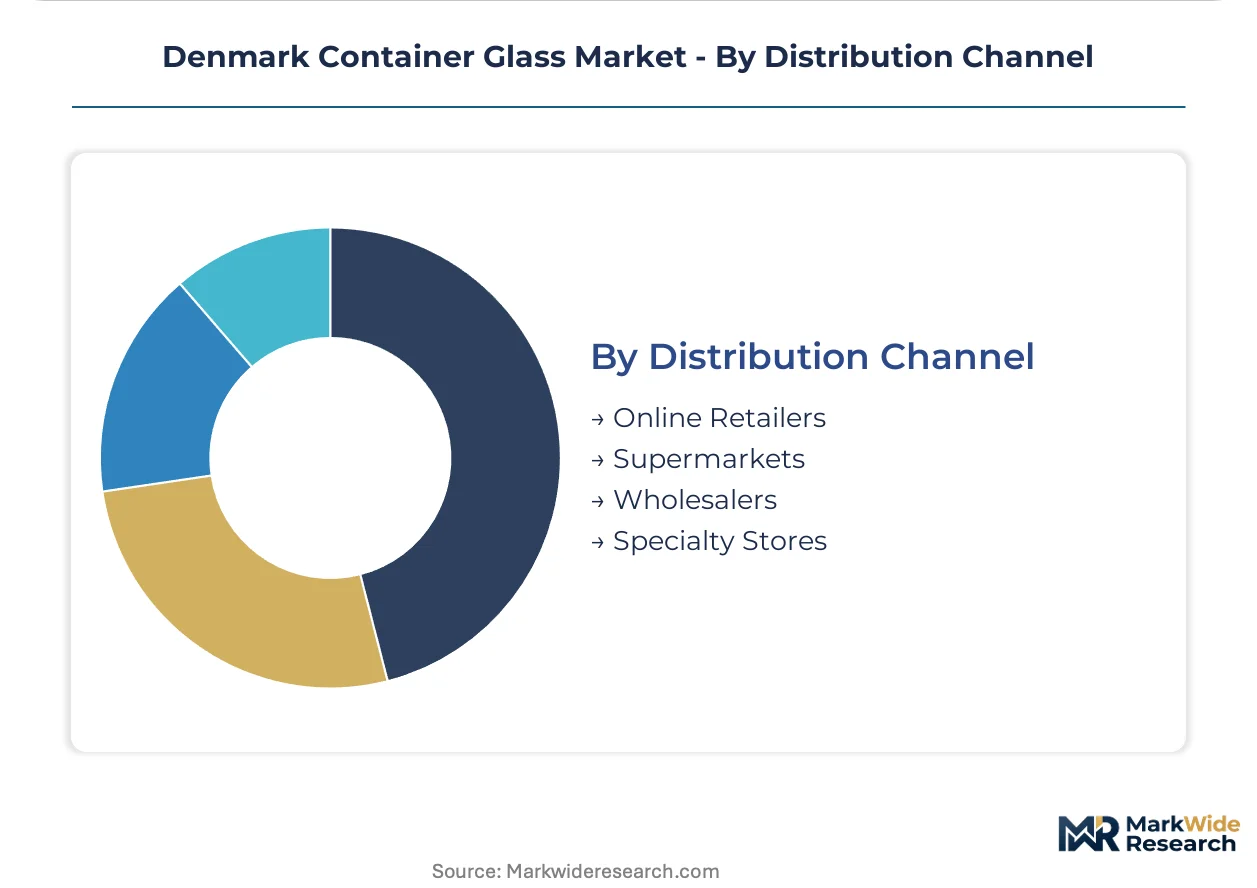
Distribution Channel:
Channel selection determines order fragmentation, with direct procurement from craft producers compressing lead times while supermarket consolidation drives scale economics.
- Online Retailers:E-commerce fulfillment centers demand damage-resistant packaging with standardized dimensions for automated sortation. Last-mile logistics constraints favor lighter-weight designs within rigid specifications.
- Supermarkets:Coordinated procurement through Danish retail cooperatives consolidates volume across private label and branded beverage lines. Shelf-ready packaging requirements influence secondary containment specifications.
- Wholesalers:Inventory pooling across multiple SKUs enables smaller producers to access furnace capacity without dedicated campaign commitments. Regional distributors in Aalborg and Esbjerg coordinate consolidated shipments.
- Specialty Stores:Premium spirits retailers and gourmet food boutiques specify customized embossing and limited-edition color runs. Direct relationships with Ardagh Glass Holmegaard A/S bypass standard distribution tiers.
Supermarkets concentrate volume procurement. Specialty stores expand most quickly on craft beverage fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish container glass demand concentrates in beverage bottlers and pharmaceutical exporters with distinct geographic footprints. Regional production clusters align with industrial infrastructure and export logistics corridors.
Greater Copenhagen
Craft distilleries and urban food producers drive premium bottle demand in the capital region. The Danish Environmental Protection Agency enforces packaging waste directives that mandate recycled content thresholds. The Medicon Valley corridor spanning Copenhagen and North Zealand anchors pharmaceutical vial production for Nordic fill-finish contractors.
North Jutland
Agricultural processors and specialty food exporters in Aalborg and surrounding districts specify hermetic jar configurations for extended shelf-life logistics. Denmark's deposit-return system infrastructure captures over 90% of beverage containers, securing cullet feedstock for regional furnaces. The Aalborg industrial belt coordinates consolidated glass shipments through regional distributors.
East Zealand
Ardagh Glass Holmegaard A/S operates its primary Naestved facility with oxy-fuel furnace technology, cutting NOx emissions by 70%. The Danish EPA's circular economy roadmap tightens end-of-life accountability for producers in this corridor. Naestved's furnace capacity serves both domestic beverage bottlers and export-oriented craft producers.
West Jutland
Specialty glass producers maintain niche furnace capacity for borosilicate and aluminosilicate grades serving laboratory applications. Denmark's agricultural biogas sector offers localized renewable fuel alternatives for hybrid furnace operations in this region. Esbjerg's port infrastructure enables export logistics for technical glass shipments to German and Central European markets.
Funen and South Denmark
The Odense corridor hosts mass-market bottlers running dedicated furnace campaigns for standardized amber and flint colors. Danish Medicines Agency alignment with EU MDR guidelines drives barrier integrity specifications for pharmaceutical glass. Odense's industrial base supports private label concentration in retail chain procurement.
Denmark Container Glass Market Competitive Environment
Player mix skews toward integrated multinationals with furnace scale advantages alongside specialized pharmaceutical-grade producers. Domestic capacity concentrates around a single dominant operator with heritage positioning, while Central European supply lines supplement standard-grade volume. Strategic archetypes include heritage-anchored premium specialists, pharmaceutical purity certifiers, and cross-border volume suppliers. Competitive moves center on furnace technology retrofits for emissions compliance and SKU proliferation to capture craft beverage fragmentation.
Within the heritage-anchored tier, Ardagh Glass Holmegaard A/S exemplifies domestic furnace dominance through its Danish legacy and Naestved facility scale. Vetropack Group occupies a position as the Central European supply anchor into Danish distribution channels. Gerresheimer AG represents the pharmaceutical purity archetype, specializing in certification-intensive vial output for Nordic drug manufacturers. These three anchors illustrate the market's structural division between domestic premium production, regional volume supply, and certified pharmaceutical segments.
| Leading Market Players |
|---|
| Ardagh Glass Holmegaard A/S |
| Berlin Packaging A/S |
| Gerresheimer AG |
| Nova Pack A/S |
| ABA Packaging Corporation |
| Vetropack Group |
| O-I Glass, Inc. |
| Verallia |
| Vidrala S.A. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with indexed energy clauses lock Danish container glass producers into supply access while exposing margins to North Sea gas benchmark volatility. These contracts tie furnace output pricing to regional energy indices and cullet availability, creating visibility for buyers but compressing producer flexibility when EU ETS thresholds tighten.
Pricing Analysis
Cost-plus contracts with North Sea gas indexation dominate procurement between Ardagh Glass Holmegaard A/S and Danish beverage bottlers. Price differentiation separates pharmaceutical-grade borosilicate vials from commodity soda-lime bottles through USP Type I certification tiers and dimensional tolerance guarantees. Pricing pressure stems from lightweight PET substitution in non-premium beverage segments. Mass-market bottlers exhibit highest price sensitivity, while craft distilleries absorbing premium markups show lowest elasticity.
Supply Chain Analysis
Just-in-time procurement preferences among Greater Copenhagen craft distilleries compress inventory buffers and elevate changeover frequency. Raw material sourcing draws from German silica sand deposits, Swedish soda ash supply, and domestic cullet streams from Denmark's deposit-return infrastructure. Single-source vulnerability concentrates in precision-molded closures manufactured in Poland and Germany. Distribution runs through regional wholesalers in Aalborg and Esbjerg coordinating consolidated shipments to smaller producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's container glass market rewards furnace operators who attach technical services to hardware supply. After-sales furnace optimization consulting and emissions compliance advisory are expanding faster than base container sales as producers navigate electrification timelines.
For Market Incumbents: Consolidate furnace campaign scheduling around pharmaceutical vial certification to capture 3-4x beverage margins. Lock in backward integration into biogas supply partnerships before 2030 EU ETS compliance deadlines. Defend against PET substitution by embedding deposit-return system compliance into premium bottle specifications.
For New Entrants and Emerging Players: Lead with specialized borosilicate vial production targeting Nordic fill-finish contractors in Hillerød and Kalundborg. Penetrate the cosmetics decorative segment where Danish design houses demand 48-hour changeover tolerances. Go-to-market through direct relationships with craft distilleries bypassing consolidated wholesale tiers.
For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical purity certifiers with Danish Medicines Agency validation already secured. Long-term viability over a multi-year horizon favors operators with oxy-fuel furnace technology installed and Scope 1 emissions intensity reduction demonstrated. Watch for EU Packaging and Packaging Waste Regulation enforcement tightening as the inflection signal for recycled content capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Retrofit | Oxy-fuel and hybrid electric installations reduce NOx emissions 70% under Danish EPA permitting. |
| Pharmaceutical GDP Certification | Danish Medicines Agency qualification opens 18-24 month supply contracts with Nordic drug manufacturers. |
| Biogas Supply Partnership | Agricultural biogas integration qualifies production for green procurement tenders and EU ETS compliance. |
| Cullet Tolerance Optimization | Extended producer responsibility fees penalize virgin material intensity in premium decorative segments. |
| Craft Channel Direct Sourcing | Direct relationships with urban distilleries capture SKU proliferation demand in Greater Copenhagen cluster. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with furnace engineers at Ardagh Glass Holmegaard A/S, procurement leads at Danish beverage bottlers, regulatory affairs specialists at the Danish Environmental Protection Agency, and pharmaceutical packaging managers at Nordic fill-finish contractors. Secondary validation incorporated Danish EPA circular economy roadmaps, EU ETS threshold documentation, customs records on German and Polish closure imports, and SEC filings from publicly traded glass manufacturers. Bottom-up furnace capacity modeling triangulated against top-down end-use demand segmentation.
Across the analysis window, volume and value outputs reflect segmentation by product type, end user, form, and distribution channel with pharmaceutical certification tiers modeled separately. CAGRs were derived from production capacity expansion timelines, regulatory compliance cost trajectories, and substitution elasticity estimates for PET penetration in non-premium beverage segments. Forecast inputs incorporated furnace campaign cycle constraints, biogas infrastructure buildout rates, and deposit-return system cullet capture efficiency.
Forecasts assume regulatory continuity in Danish EPA packaging waste enforcement and EU ETS threshold schedules; material policy shifts would require re-modeling of furnace electrification economics and extended producer responsibility fee structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Container Glass in the UAE Market