
 United Kingdom Glass Packaging Market | 2026-2036
United Kingdom Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Glass Packaging Market Analytics
Lightweighting technology is fragmenting the traditional manufacturing stack across UK glass packaging, forcing converters to balance thinner wall specifications against mechanical durability requirements. Ardagh Packaging Group leverages its multi-site furnace network to sustain bulk supply contracts with multinational beverage brands. Beatson Clark specializes in pharmaceutical amber glass, occupying a defensible niche against standard container imports. Vidrala SA competes through its Iberian-UK logistics integration, controlling cross-channel distribution costs for premium wine bottlers.
Glass packaging denotes rigid containers formed from silica sand, soda ash, and limestone melted at approximately 1500°C, then molded by blow-and-blow or press-and-blow techniques to create chemically inert, infinitely recyclable vessels for liquid and solid product protection. The bottles segment anchors volume across UK beverage applications, though jars command margin premiums in artisan food preservation where tamper-evident closures justify higher unit economics. Pharmaceutical glass in the end-user dimension leads technical specification intensity, as borosilicate and neutral borosilicate compositions must satisfy MHRA pharmacopeial standards for pH stability and hydrolytic resistance.
The UK Environment Agency enforces Packaging Waste Regulations that mandate producer responsibility obligations, while BSI standards govern dimensional tolerances and thermal shock resistance for food-contact glass. MHRA guidelines extend these requirements to pharmaceutical primary packaging, creating dual compliance pathways that shape converter certification investments and customer qualification timelines. Stakeholders must monitor the trajectory of extended producer responsibility fee structures and furnace decarbonization mandates to calibrate capital allocation between oxy-fuel upgrades and electric melting pilot investments.
Market Dynamics
The UK Plastic Packaging Tax is collapsing converter business models that relied on single-use formats, forcing rapid capital reallocation toward refillable glass infrastructure and lightweighting R&D.
Growth Catalysts
- UK Plastic Packaging Tax:The GBP 200 per tonne levy on virgin plastic packaging is accelerating beverage brand migration to refillable glass formats as a compliance pathway.
- Scottish premium spirits:Whisky and gin distilleries are expanding embossed and colored glass bottle programs to differentiate shelf presence in duty-free and domestic retail.
- Oxy-fuel furnace retrofits:Container glass producers are cutting carbon intensity per tonne by 20-30% through burner technology upgrades ahead of UK ETS phase-in.
Market Restraints
- Natural gas price volatility:Furnace operations depend on natural gas feedstock, exposing margins to UK NBP benchmark swings and carbon border adjustment uncertainties.
- Silica sand supply concentration:High-purity sand for container glass concentrates in Cheshire and Norfolk quarries, creating geographic single-point-of-failure risk.
- Lightweighting durability ceiling:Thinner wall specifications below 180g for standard wine bottles face mechanical failure rates in automated filling lines.
Strategic Opportunities
- Pharmaceutical borosilicate:MHRA pharmacopeial standards for pH stability are creating qualification barriers that favor domestic converters over standard container imports.
- English Midlands cluster expansion:Yorkshire and Staffordshire furnace corridors offer proximity advantages for craft beverage brands seeking 50-mile supply radius claims.
- Extended Producer Responsibility:Modulated fee structures under UK Packaging Waste Regulations reward higher recycled content, favoring glass over competing substrates.
Industry Challenges
- Electric melting pilot scale-up:All-electric furnace technology requires 40-60 MW grid connections that strain local distribution infrastructure in manufacturing corridors.
- MHRA qualification timelines:Pharmaceutical glass converter certification stretches 18-24 months, compressing customer switching flexibility and locking in incumbent relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Glass Packaging Market |
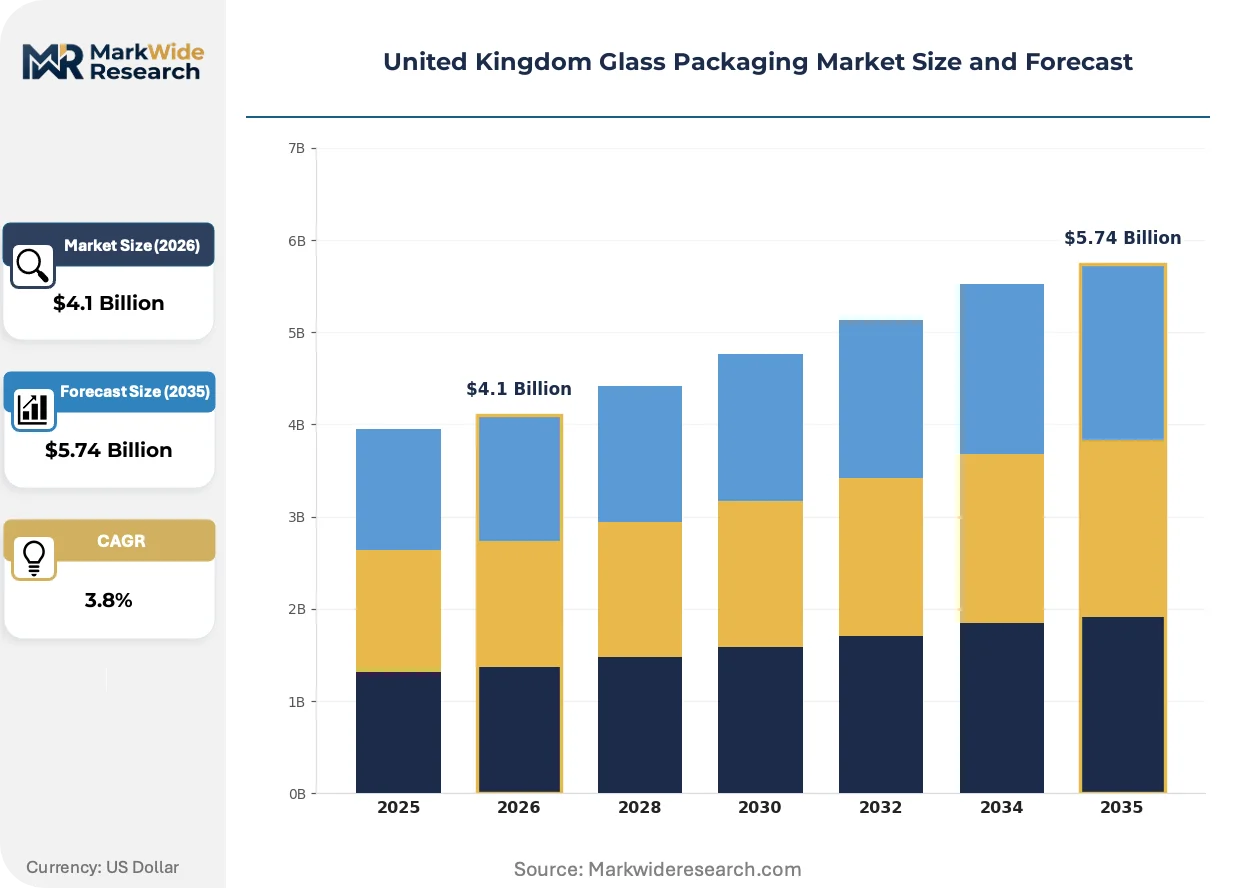
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $5.74 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubes End User: Food & Beverage, Personal Care, Pharmaceuticals, Cosmetics Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales Application: Food Preservation, Beverage Packaging, Storage Solutions, Decorative Use |
| Companies Covered | Ardagh Packaging Group, Owens-Illinois Inc., Berlin Packaging LLC, Vidrala SA, Beatson Clark, Origin Pharma Packaging, Stoelzle Flaconnage Ltd, Ciner Glass Ltd, Glassworks International Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Glass Packaging Market Evolving Landscape
Converter investment priorities are pivoting from capacity expansion to decarbonization and digital manufacturing, with furnace technology and regulatory compliance dominating capital allocation decisions.
Thin-wall blow-and-blow forming is collapsing the traditional weight-performance tradeoff in wine and spirits packaging. Premium bottlers in England are adopting 280g specifications for 75cl formats, down from 400g legacy standards. This compression is enabling freight cost reductions and Scope 3 emissions claims without sacrificing shelf presence.
The UK Environment Agency's Packaging Waste Regulations are tightening producer responsibility obligations through modulated fee structures. Food-contact glass converters must now document recycled content percentages to secure preferential EPR rates. Yorkshire-based container producers are responding by investing in closed-loop cullet sorting to maintain batch chemistry consistency.
Direct-to-consumer subscription models are fragmenting traditional bulk procurement patterns among craft spirits brands. Small-batch distilleries in Scotland and England are bypassing distributor networks to specify custom embossed runs as low as 5,000 units. This channel shift is stretching converter mold inventory management and press changeover scheduling capabilities.
United Kingdom Glass Packaging Market Segmentation
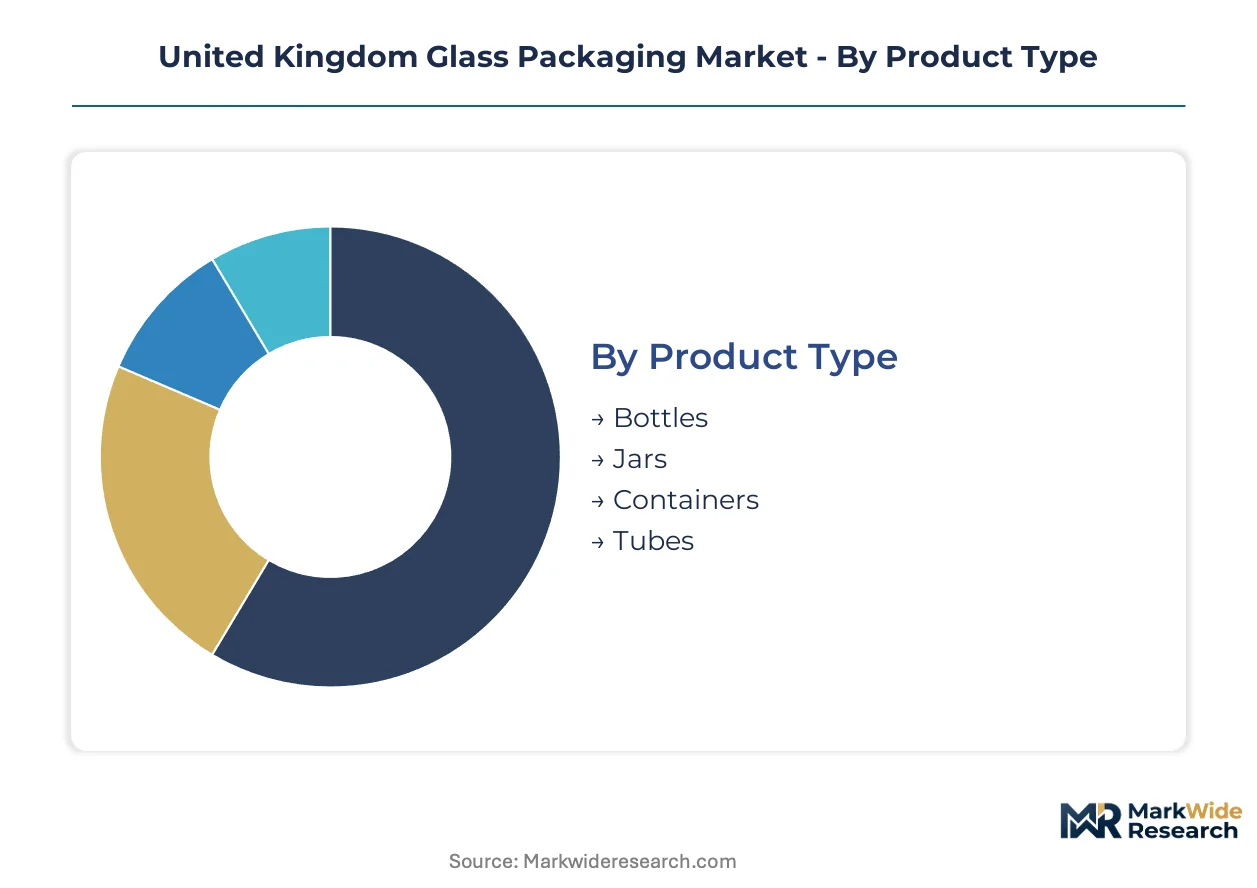
Segmentation in UK glass packaging reflects divergent technical specifications and regulatory burdens across end-use applications. Pharmaceutical and food-contact formats command premium qualification investments, while beverage containers drive volume throughput in Midlands furnace corridors.
Product Type:
After-sales service intensity varies sharply across product categories, with pharmaceutical containers requiring batch traceability support and beverage bottles demanding rapid mold changeover capabilities for seasonal SKUs.
- Bottles:Formed through blow-and-blow or press-and-blow techniques, these vessels dominate beverage applications with wall thickness specifications ranging from 180g lightweight wine formats to 500g premium spirits embossing. Demand concentrates in Scottish whisky and English gin distilleries where embossed and colored glass differentiates shelf presence in duty-free retail.
- Jars:Wide-mouth containers with lug or continuous thread closures serve artisan food preservation where tamper-evident sealing justifies margin premiums. Yorkshire manufacturers report strongest order flow from small-batch preserve producers seeking 50-mile supply radius claims for sustainability marketing.
- Containers:Standardized cylindrical and rectangular formats serve industrial chemical and laboratory applications with lower aesthetic specification intensity.
- Tubes:Narrow cylindrical packaging for pharmaceutical and cosmetic dispensing requires precision neck finish tolerances.
By volume, bottles lead. By growth pace, jars are ahead.
End User:
Cost tier stratification separates qualification-intensive pharmaceutical formats from commodity beverage containers, with MHRA certification investments creating defensible moats for domestic converters.
- Food & Beverage:The anchor demand segment spanning carbonated drinks, spirits, wine, and preserved foods. English Midlands furnace clusters sustain bulk supply contracts through proximity to bottling operations, while the UK Plastic Packaging Tax accelerates brand migration from single-use plastics to refillable glass formats.
- Pharmaceuticals:Borosilicate and neutral borosilicate compositions must satisfy MHRA pharmacopeial standards for pH stability and hydrolytic resistance. Amber glass demand concentrates in domestic converter networks where 18-24 month qualification timelines lock in incumbent relationships against import competition.
- Personal Care:Premium cosmetic bottles and jars command decorative finishing premiums through colored glass and silk-screening applications.
- Cosmetics:Fragrance and skincare packaging emphasizes aesthetic differentiation through custom mold development and surface treatments.
Food & Beverage dominates volume share. Pharmaceuticals exhibits the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation distinguishes bulk procurement patterns from direct-to-consumer subscription models that stretch converter mold inventory management.
- Online:E-commerce fulfillment requires enhanced protective packaging and smaller minimum order quantities for craft spirits brands bypassing traditional distributor networks.
- Retail Stores:Supermarket and specialty retail channels drive standardized SKU volumes with predictable seasonal patterns.
- Wholesale:Distributor networks aggregate demand from multiple brands, enabling converter production scheduling efficiencies.
- Direct Sales:Custom embossed runs as low as 5,000 units serve small-batch distilleries in Scotland and England specifying proprietary bottle designs.
Wholesale channels handle greatest volume. Direct sales channels are climbing the fastest.
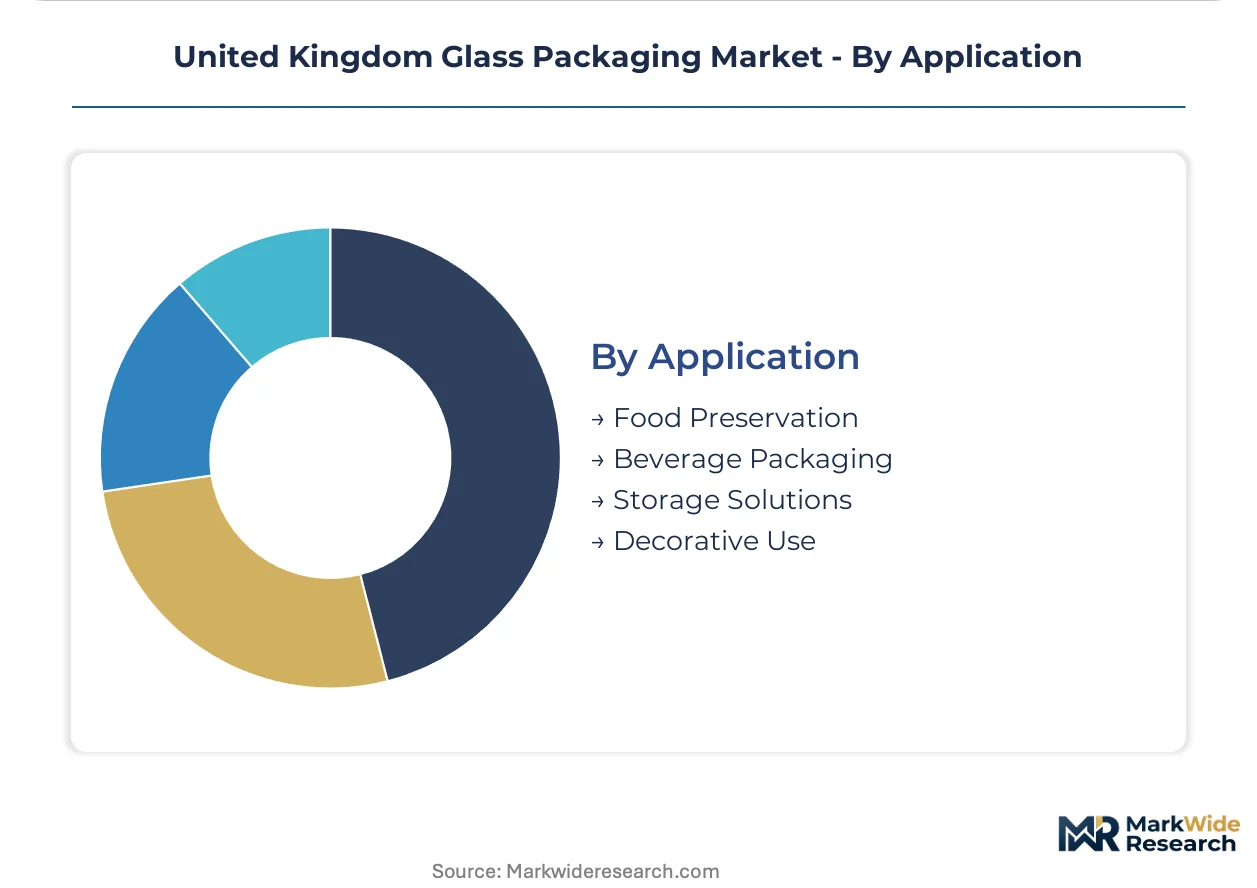
Application:
Supply concentration in Yorkshire and Staffordshire manufacturing corridors shapes regional service capabilities across application types.
- Food Preservation:Hermetic sealing performance in thermal processing applications drives specification intensity for artisan and industrial preserve producers.
- Beverage Packaging:Carbonation retention and UV protection requirements vary across beer, wine, and spirits sub-segments with corresponding color and weight specifications.
- Storage Solutions:Generic containment applications with lower performance barriers face import competition from European container producers.
- Decorative Use:Candle holders, vases, and gift packaging emphasize aesthetic finishing over functional performance.
Beverage packaging leads by volume. Food preservation gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK glass packaging exports flow primarily into European Union beverage markets, with cross-channel logistics integration sustaining premium wine bottler relationships in France and Germany. English Midlands furnace clusters anchor domestic production capacity near Yorkshire and Staffordshire manufacturing corridors.
Scotland
Scottish whisky and gin distilleries drive embossed and colored glass bottle specifications for duty-free retail differentiation. The UK Environment Agency enforces Packaging Waste Regulations that mandate producer responsibility obligations for spirit exporters. Speyside and Glasgow-area bottling operations cluster near container glass supply sources to minimize freight emissions.
England
English craft beverage brands across Yorkshire and the Midlands specify lightweight 280g wine bottles and custom embossed runs as low as 5,000 units for direct-to-consumer channels. The UK Plastic Packaging Tax accelerates migration from single-use plastics to refillable glass formats. Yorkshire manufacturers invest in closed-loop cullet sorting to maintain batch chemistry consistency for food-contact applications.
Wales
Welsh craft spirits producers leverage proximity to English Midlands furnace corridors for 50-mile supply radius sustainability claims. MHRA pharmacopeial standards for pharmaceutical glass create qualification barriers favoring domestic converters over imports. South Wales manufacturing zones concentrate on secondary packaging and distribution rather than primary container production.
Northern Ireland
Northern Ireland beverage bottlers access cross-channel supply chains through Irish Sea logistics corridors serving premium spirits and craft beer segments. Post-Brexit customs arrangements shape inventory positioning and converter qualification timelines. Belfast-area operations focus on distribution consolidation rather than furnace-based primary manufacturing.
United Kingdom Glass Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around multi-site furnace networks and specialized pharmaceutical converters. Container glass production clusters near natural gas infrastructure and beverage bottling corridors. Three archetypes dominate: scale-driven bulk suppliers, pharmaceutical qualification specialists, and premium decorative finishers. Competitive moves center on oxy-fuel furnace retrofits and MHRA certification investments to lock in customer relationships.
Within the scale-driven tier, Ardagh Packaging Group and Vidrala SA exemplify multi-site furnace operators sustaining bulk supply contracts through geographic coverage. Beatson Clark occupies the pharmaceutical specialist position, anchoring amber glass production against standard container imports. These three represent the dominant competitive configurations shaping converter investment priorities across English Midlands and Yorkshire manufacturing corridors.
| Leading Market Players |
|---|
| Ardagh Packaging Group |
| Owens-Illinois Inc. |
| Berlin Packaging LLC |
| Vidrala SA |
| Beatson Clark |
| Origin Pharma Packaging |
| Stoelzle Flaconnage Ltd |
| Ciner Glass Ltd |
| Glassworks International Limited |
| Others |
Value Network & Pricing Analysis
Natural gas price volatility at the UK NBP benchmark determines both furnace operating cost spreads and converter supply chain configuration across English Midlands corridors. This feedstock exposure compresses margins at energy-intensive production tiers while rewarding oxy-fuel retrofit investments that anchor long-term contract pricing power.
Pricing Analysis
Furnace technology-generation pricing gaps separate legacy natural gas-fired operations from oxy-fuel retrofits and pilot electric melting installations. Three-tier pricing structure across premium pharmaceutical borosilicate, standard beverage container, and economy industrial formats reflects MHRA certification intensity and batch chemistry control requirements. Pricing pressure stems from carbon border adjustment uncertainties and Scope 3 emissions accounting demands from multinational beverage brands. Small-batch craft distilleries exhibit highest price sensitivity, while pharmaceutical converters with locked qualification timelines maintain pricing power.
Supply Chain Analysis
Upstream silica sand feedstock draws from Cheshire and Norfolk quarry concentrations, with high-purity deposits anchoring container glass batch chemistry standards. Soda ash imports hinge on European supplier networks, while limestone sources distribute across domestic and Irish extraction sites. Single-source vulnerability concentrates in specialty sand grades for amber pharmaceutical glass. Distribution runs through Midlands furnace clusters with 50-mile radius claims to Yorkshire and Staffordshire bottling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK glass packaging market functions as a defensive-moat story where MHRA qualification timelines create 18-24 month switching costs that entrench incumbent converter relationships against import competition.
For Market Incumbents: Harden furnace network resilience through oxy-fuel retrofit completion ahead of UK ETS phase-in, locking in carbon intensity advantages against unconverted competitors. Deepen backward integration into closed-loop cullet sorting infrastructure to secure preferential Extended Producer Responsibility fee rates. Prioritize pharmaceutical certification maintenance investments to defend against Iberian import challengers.
For New Entrants and Emerging Players: Northern Ireland's post-Brexit customs friction creates geographic underpenetration where Belfast-area distribution consolidation offers white-space entry without furnace capital requirements. Target direct-to-consumer subscription channels serving small-batch Scottish distilleries with 5,000-unit custom embossed capabilities. Pursue mold inventory partnerships with established Yorkshire converters to bypass qualification timeline barriers.
For Investors and Strategic Acquirers: UK ETS phase-in reshapes the acquisition landscape toward oxy-fuel converted assets with verified carbon intensity reductions. Long-term viability favors multi-site furnace networks with pharmaceutical qualification depth over single-location commodity container operations. Monitor MHRA audit frequency acceleration as signal for qualification backlog expansion that would inflate incumbent relationship values.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | UK ETS compliance cuts carbon intensity per tonne by 20-30% ahead of phase-in deadlines. |
| Closed-Loop Cullet Sorting | Yorkshire investments maintain batch chemistry consistency for food-contact EPR preferential rates. |
| Pharmaceutical Certification Expansion | MHRA pharmacopeial qualification barriers lock out standard container imports from Iberian competitors. |
| Direct-to-Consumer Channel Development | Custom embossed runs as low as 5,000 units capture craft spirits subscription fragmentation. |
| 50-Mile Supply Radius Claims | Midlands furnace proximity enables sustainability marketing for English Midlands craft beverage brands. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with furnace operations managers, pharmaceutical procurement leads, craft spirits brand owners, and MHRA regulatory affairs specialists; and secondary validation through UK Environment Agency Packaging Waste Regulations filings, BSI standards documentation, SEC 10-K disclosures from listed packaging groups, and customs trade flow records. Bottom-up volume triangulation across product type and end-use segments converged with top-down macroeconomic anchoring.
Forecast inputs considered furnace capacity utilization rates, natural gas price trajectory assumptions, and regulatory milestone timing across the projection horizon. Segmentation modeling spanned product type, end-user industry, application, and distribution channel dimensions with regional production cluster overlays. CAGRs derived from slope analysis of historical volume trends adjusted for technology substitution and policy intervention intensity, with lightweighting adoption curves and electric melting pilot scale-up timelines as industry-specific modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Iberian cross-channel competitors or accelerated electric melting breakthroughs would shift outcomes. Cross-checking against UK NBP forward curves and MHRA audit queue depth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Russia Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
France Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
India Container Glass Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Container Glass in the UAE Market