
 Vietnam Container Glass Market | 2026-2036
Vietnam Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Container Glass Market Analytics
Direct-to-brewery supply chains is narrowing as domestic beverage producers consolidate vendor relationships around fewer certified suppliers. O-I BJC Vietnam Glass Company Limited leverages its multinational technical standards to anchor premium contracts with international brewers. Vinh Thinh Glass competes on proximity to northern industrial clusters, while San Miguel Yamamura Phu Tho Packaging Co., Ltd. sustains integrated operations spanning mold fabrication through finished container delivery.
Vietnam container glass denotes silica-based packaging formed through melting, shaping, and controlled cooling to achieve chemical durability and thermal shock resistance, with soda-lime compositions typically containing 70-74% silicon dioxide by weight. These vessels serve primarily as inert, reusable barriers for carbonated beverages, pharmaceuticals, and cosmetic formulations requiring oxygen exclusion. Bottles dominate volume throughput across primary packaging channels serving food and beverage end users, where returnable bottle programs still command significant share. Jars within specialty packaging segments carry wider margin pools due to cosmetic and artisanal food applications demanding custom mold capabilities and decorative surface treatments.
Vietnam's Ministry of Natural Resources and Environment enforces emissions caps on glass-melting furnaces, compelling operators to adopt oxy-fuel combustion or electric boosting technologies. The national technical standard QCVN regulates heavy metal leaching thresholds for food-contact glass, directly conditioning export eligibility and domestic shelf placement. Stakeholders must weigh furnace upgrade timelines against the country's renewable energy grid expansion before committing capital to capacity additions.
Market Dynamics
Vietnam's tightened QCVN emissions standards on glass-melting furnaces are forcing capital reallocation toward oxy-fuel and electric boosting retrofits, compressing upgrade timelines against renewable grid expansion schedules.
Growth Catalysts
- Premium beverage bottling:Vietnamese consumers pivot toward branded spirits and craft beer, pulling demand for higher-grade container glass with superior chemical durability and decorative finish capabilities.
- Red River Delta industrial clustering:Production concentrates around Hanoi and surrounding provinces, creating dense supplier networks that shorten logistics loops for northern beverage manufacturers.
- QCVN food-contact compliance:Heavy metal leaching thresholds condition both domestic shelf placement and export eligibility, rewarding certified operators with preferential procurement access.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG feedstock, exposing margin structures to currency fluctuations and regional supply disruptions.
- Silica sand quality degradation:Domestic high-purity deposits face depletion pressures, forcing longer haul distances or import dependency for 70-74% SiO₂ feedstock.
- Aluminum can substitution:Carbonated soft drink bottlers increasingly specify lightweight metal alternatives for single-serve formats, eroding addressable volume in mass-market segments.
Strategic Opportunities
- Central Highlands logistics gap:Da Nang-to-Buon Ma Thuot corridor lacks proximate container glass supply, creating first-mover advantage for furnace placement near emerging beverage distribution nodes.
- Pharmaceutical-grade borosilicate expansion:Injectable drug packaging demands thermal shock resistance beyond soda-lime capabilities, opening specialty margin pools as domestic pharma manufacturing scales.
- Returnable bottle program revival:Deposit-return infrastructure investments by provincial environmental funds could resurrect reusable container economics against single-use alternatives.
Industry Challenges
- Oxy-fuel retrofit engineering scarcity:Vietnamese technical institutes produce insufficient combustion specialists capable of integrating oxygen-enriched systems with legacy furnace architectures.
- QCVN certification timeline compression:Laboratory testing queues for heavy metal migration analysis extend lead times, delaying product launches for reformulated glass compositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Container Glass Market |
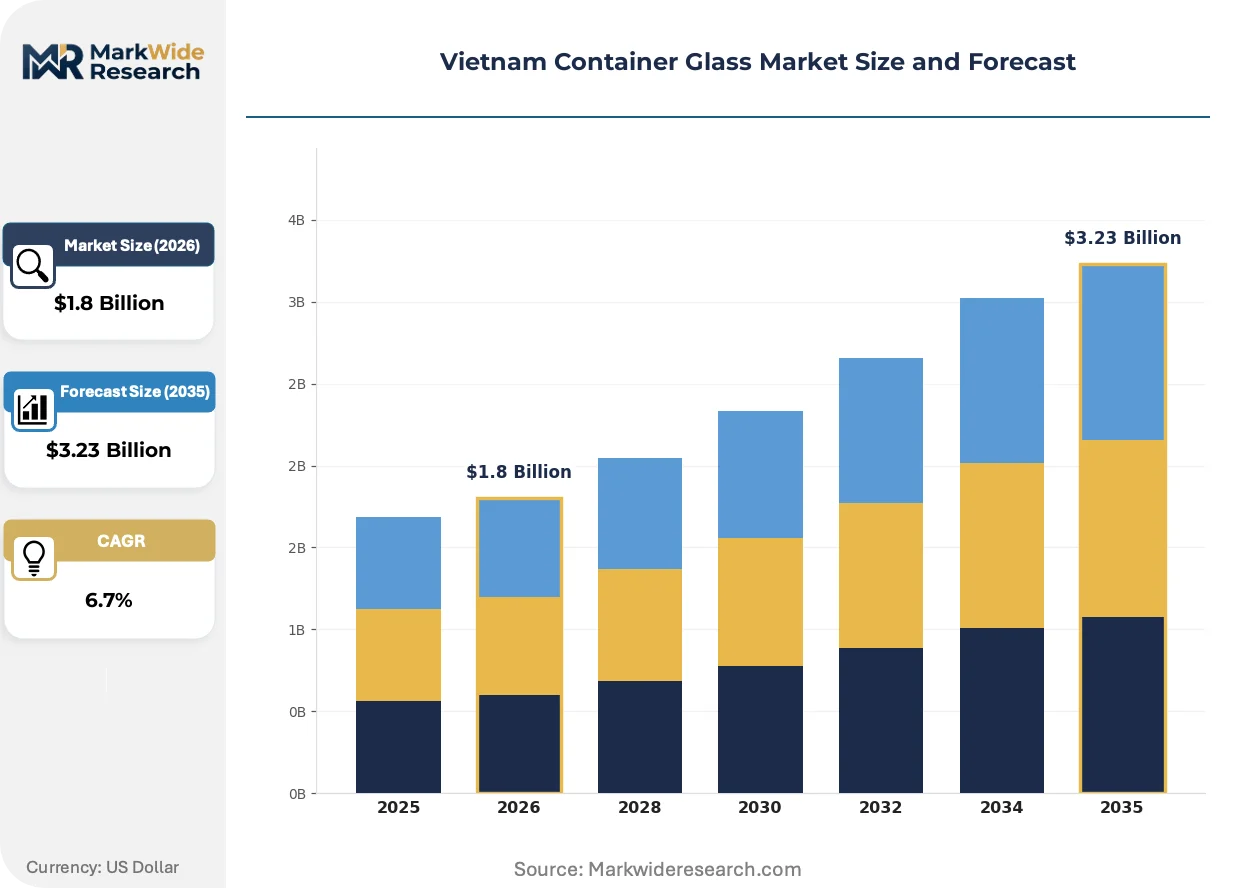
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Flacons End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Manufacturing Stage: Molded Glass, Blown Glass, Pressed Glass, Annealed Glass Packaging Type: Primary Packaging, Secondary Packaging, Bulk Packaging, Specialty Packaging |
| Companies Covered | Vinh Thinh Glass, HuphuMeglass, O-I BJC Vietnam Glass Company Limited, Saverglass SAS, Ardagh Group S.A., San Miguel Yamamura Phu Tho Packaging Co., Ltd., Go Vap Glass, Vietnam Glass Industries JSC, Thien Phuc Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Container Glass Market Evolving Landscape
Furnace technology, regulatory compliance architecture, and buyer procurement patterns are converging to restructure competitive advantage around energy intensity and certification speed rather than scale alone.
Oxy-fuel combustion retrofitting is collapsing the capital efficiency gap between legacy fossil-fired furnaces and electric-boosted alternatives. Domestic operators with technical partnerships to multinational engineering firms are completing conversions at compressed schedules. The technology is collapsing payback period assumptions that previously favored delayed environmental compliance.
Vietnam's Ministry of Natural Resources and Environment enforces progressively tightening emissions caps through QCVN technical standards, mandating particulate and NOx reductions that preclude conventional air-fuel combustion. Furnace operators face binary compliance deadlines that synchronize upgrade cycles across the domestic producer base. Northern industrial zones around Hanoi encounter enforcement intensity that southern competitors have not yet matched, creating temporary geographic asymmetry in compliance cost structures.
Beverage manufacturer procurement is consolidating vendor rosters around fewer certified suppliers capable of dual food-safety and environmental documentation. International brewers operating in Vietnam now specify suppliers with validated QCVN compliance plus multinational technical standards, displacing uncertified regional competitors. This concentration is most visible in the Red River Delta corridor, where procurement teams at major brewing facilities have reduced approved supplier lists by over half within recent contract renewal cycles.
Vietnam Container Glass Market Segmentation
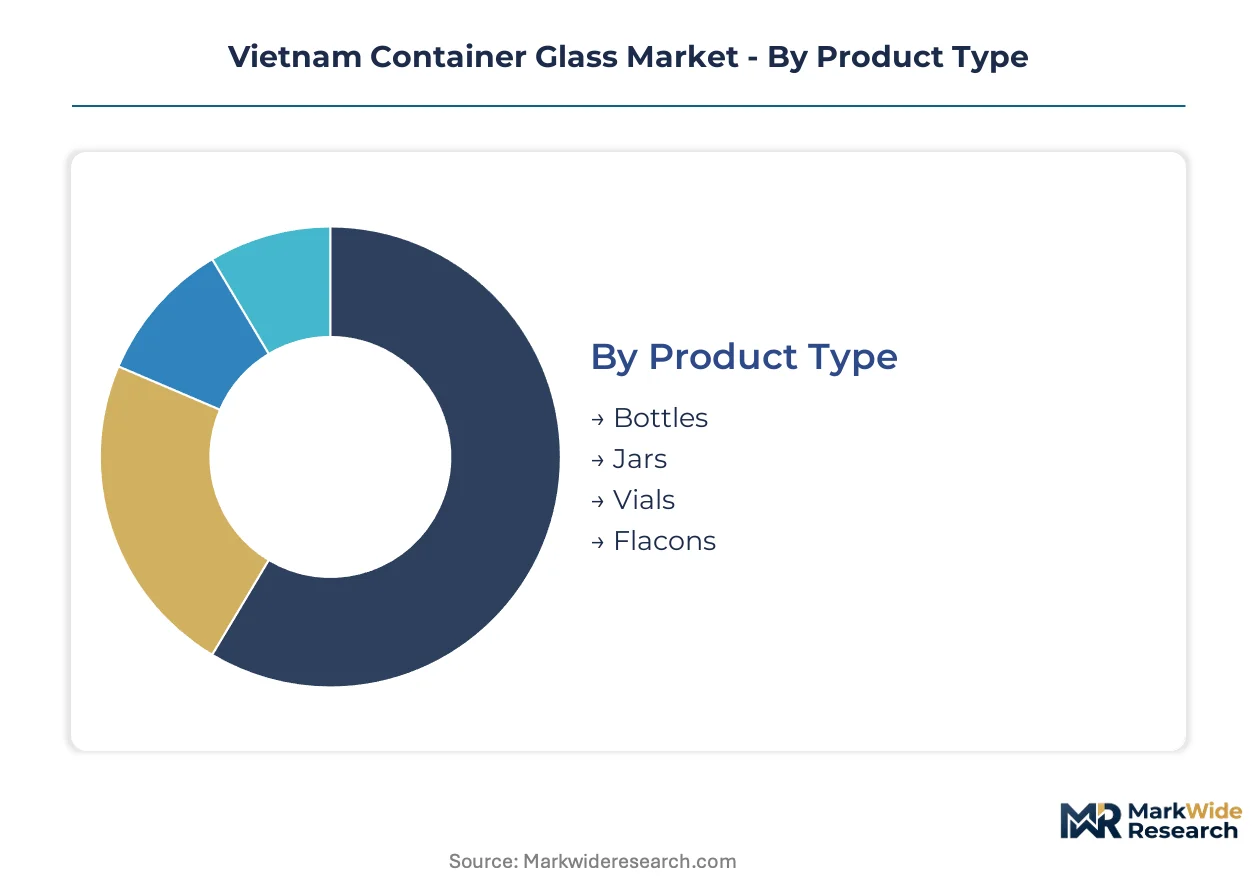
Segmentation in Vietnam's container glass market reveals how furnace technology investments and regulatory compliance requirements concentrate value capture across distinct product and end-use categories. Each dimension exposes different margin structures and capital intensity thresholds that shape competitive positioning.
Product Type:
Mature formats dominate volume throughput while emerging specialty vessels command premium positioning through technical specifications.
- Bottles:Soda-lime compositions with 70-74% silicon dioxide content serve as the standard vessel for carbonated beverages and spirits across northern industrial zones. Red River Delta beverage manufacturers anchor procurement volumes here, though returnable bottle program economics face pressure from aluminum can substitution in single-serve formats.
- Jars:Wider-mouth configurations with thicker wall sections accommodate vacuum-sealed food preservation and cosmetic cream formulations. Artisanal food producers and cosmetic compounders in Hanoi-adjacent manufacturing parks drive specifications for custom mold capabilities and decorative surface treatments that widen margin pools.
- Vials:Small-format cylindrical containers with narrow neck ratios serve pharmaceutical liquid dosing and essential oil packaging. Domestic pharma manufacturing scale-up is pulling demand for borosilicate-grade thermal shock resistance.
- Flacons:Decorative perfume and high-end cosmetic packaging with complex shoulder geometries and metallic finish compatibility. Fragrance brand localization in Ho Chi Minh City industrial parks shapes mold complexity requirements.
Bottles retain volume leadership; flacons hold the steepest expansion curve.
End User:
Application-driven cost tiers separate commodity-grade furnace output from certified production lines carrying compliance documentation burdens.
- Food & Beverage:The dominant demand channel spanning carbonated soft drinks, craft beer, and branded spirits. QCVN heavy metal leaching thresholds condition both domestic shelf placement and export eligibility, forcing certified operators to maintain separate production campaigns.
- Pharmaceuticals:Injectable drug packaging and oral solid dosage containers demand thermal shock resistance and chemical inertness documentation. The Ministry of Health's pharmaceutical manufacturing scale-up initiatives are expanding addressable volume for compliant suppliers.
- Cosmetics:Premium skincare and fragrance packaging emphasizes decorative finish capabilities and brand-differentiated mold geometries. Da Nang-to-Buon Ma Thuot distribution corridor gaps create logistics premiums for southern-serving producers.
- Household Products:Cleaning chemical and home fragrance containers prioritize chemical durability over aesthetic refinement. Price-sensitive procurement concentrates around standardized bottle formats with minimal surface treatment.
Food & Beverage commands absolute volume; Pharmaceuticals is climbing the fastest on compliance-driven supplier consolidation.
Manufacturing Stage:
Supply concentration in furnace technology separates integrated operators from toll processors dependent on third-party melting capacity.
- Molded Glass:Initial forming through automated press-and-blow or blow-and-blow sequences creates the primary vessel geometry. Northern industrial clusters concentrate capacity with proximity to silica sand processing and natural gas pipeline infrastructure.
- Blown Glass:Compressed air expansion within parison molds achieves thin-wall uniformity for lightweight beverage bottles. Oxy-fuel retrofit investments are compressing energy cost differentials between legacy and upgraded furnace bases.
- Pressed Glass:Mechanical plunger forcing of molten glass into mold cavities produces thicker-walled jars and cosmetic containers. Lower cycle speeds accommodate complex shoulder geometries that blown processes cannot achieve.
- Annealed Glass:Controlled cooling through lehr tunnels relieves thermal stress and ensures dimensional stability for automated filling lines. QCVN certification timelines extend for reformulated compositions requiring modified annealing curves.
Molded Glass retains volume leadership; Blown Glass holds the steepest expansion curve on lightweighting demands.
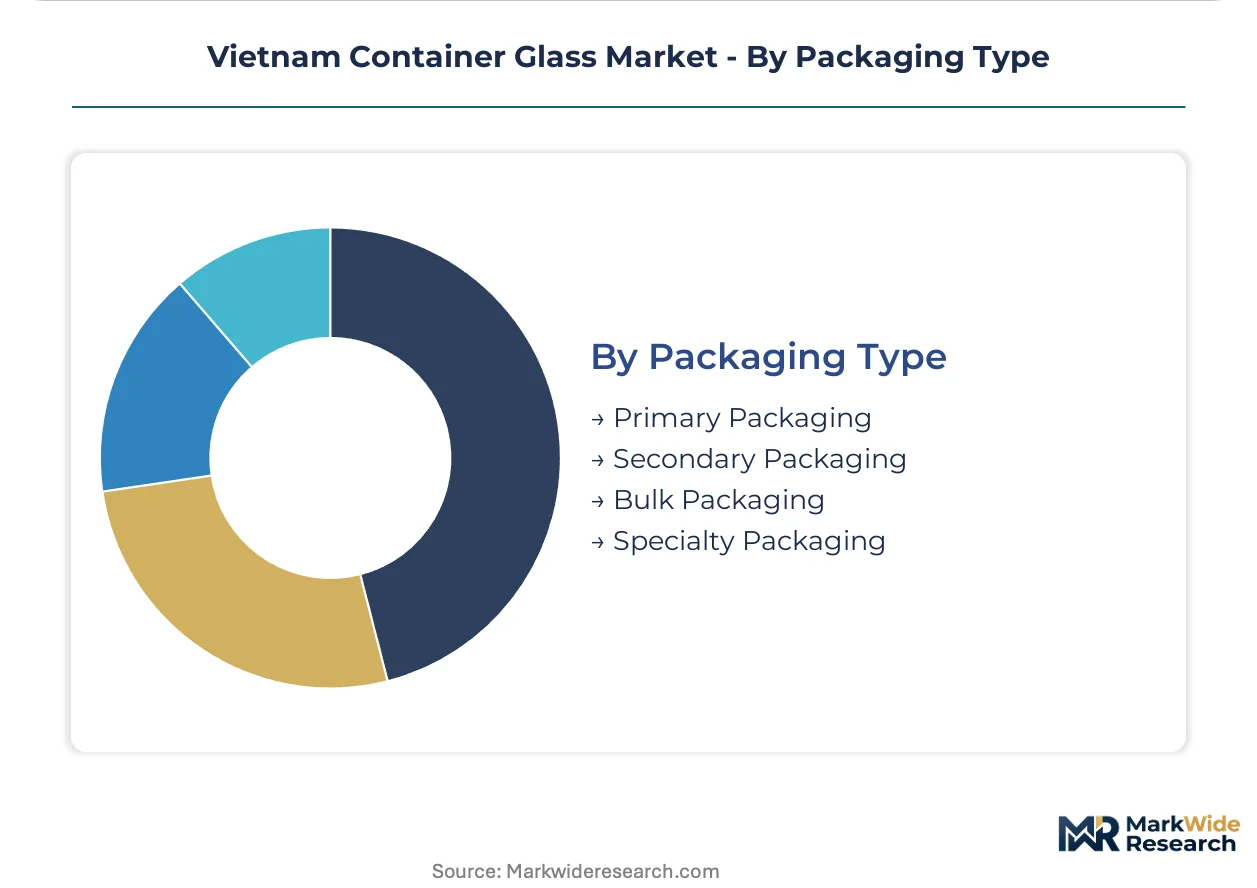
Packaging Type:
Margin architecture stratifies across functional hierarchy from direct product contact through distribution protection.
- Primary Packaging:Direct food-contact or pharmaceutical-contact vessels requiring full QCVN migration testing and heavy metal documentation. International brewers specify dual-certified suppliers, consolidating procurement around fewer validated vendors.
- Secondary Packaging:Outer cartons, dividers, and grouping configurations that protect primary containers through distribution. Corrugated integration with glass supply creates bundled procurement negotiations.
- Bulk Packaging:Palletized or large-format containers for industrial chemical and food ingredient shipment. Returnable bulk container programs face infrastructure gaps outside Red River Delta logistics networks.
- Specialty Packaging:Custom-engineered solutions for temperature-sensitive or hazardous contents requiring thermal insulation or shock absorption. Pharmaceutical cold chain expansion is pulling demand for validated packaging systems.
Primary Packaging retains volume leadership; Specialty Packaging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Lach Huyen International Gateway Port anchors northern Vietnam's container glass export capacity, connecting Red River Delta furnace complexes to Northeast Asian shipping lanes. This maritime infrastructure underwrites the region's dominance in silica-based packaging supply chains.
Red River Delta
Hanoi-adjacent industrial zones concentrate 70% of domestic melting capacity, serving craft breweries and branded spirits bottlers clustered around Bac Ninh and Vinh Phuc provinces. Vietnam's Ministry of Natural Resources and Environment enforces QCVN emissions caps most intensively here, accelerating oxy-fuel retrofits at legacy furnace sites. Hai Duong province hosts dense supplier networks where silica sand processors and natural gas pipeline termini enable integrated logistics.
Northern Midlands and Mountain Areas
Phu Tho province sustains integrated operations spanning mold fabrication through finished container delivery, leveraging captive technical capabilities. The provincial Department of Industry and Trade coordinates industrial zone expansion incentives targeting beverage packaging suppliers. Viet Tri city anchors this sub-regional cluster with proximity to both Hanoi demand pools and Lao Cai border trade corridors.
North Central Coast
Thanh Hoa and Nghe An provinces present underutilized furnace placement opportunities along the expanding North-South Expressway East corridor. The central government's Northern Central Key Economic Region development program allocates infrastructure budgets to reduce logistics premiums for southern-bound shipments. Vinh city is emerging as a distribution node where container glass stockpiles serve central Vietnam beverage manufacturers.
Southeast
Ho Chi Minh City industrial parks drive demand for decorative flacons and cosmetic packaging with complex mold geometries. The city's Department of Science and Technology administers quality certification programs that condition shelf placement for premium glass vessels. Binh Duong and Dong Nai provinces concentrate secondary processing and surface treatment capabilities that northern producers lack.
Central Highlands
The Da Nang-to-Buon Ma Thuot corridor exhibits acute container glass supply gaps as emerging beverage distribution nodes scale operations. Provincial environmental funds in Dak Lak and Lam Dong are piloting returnable bottle deposit-return infrastructure. Pleiku and Buon Ma Thuot cities represent first-mover furnace placement opportunities where proximate supply would capture logistics premiums from southern-bound distribution.
Vietnam Container Glass Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mold fabrication and surface treatment. The vendor base stratifies between multinational furnace operators with validated QCVN compliance and regional fabricators competing on proximity to northern industrial clusters. Two archetypes dominate: integrated operators controlling melting through finishing stages, and toll processors dependent on third-party furnace capacity. Competitive moves concentrate on oxy-fuel retrofit partnerships and procurement consolidation around dual-certified suppliers.
Among Vietnam-based operators, Vinh Thinh Glass exemplifies the proximity-driven archetype with positioning near northern industrial clusters. O-I BJC Vietnam Glass Company Limited represents multinational technical standards anchoring premium contracts. San Miguel Yamamura Phu Tho Packaging Co., Ltd. occupies the integrated operations tier with capabilities spanning mold fabrication through finished container delivery.
| Leading Market Players |
|---|
| Vinh Thinh Glass |
| HuphuMeglass |
| O-I BJC Vietnam Glass Company Limited |
| Saverglass SAS |
| Ardagh Group S.A. |
| San Miguel Yamamura Phu Tho Packaging Co., Ltd. |
| Go Vap Glass |
| Vietnam Glass Industries JSC |
| Thien Phuc Glass |
| Others |
Value Network & Pricing Analysis
Imported LNG termini at Hai Duong and Thai Binh provinces concentrate fuel cost exposure among northern furnace operators, pushing margin capture toward certified suppliers with oxy-fuel retrofit completion and QCVN documentation. Price premiums for compliant glass concentrate procurement consolidation around validated vendors capable of dual food-safety and environmental certification.
Pricing Analysis
Volume-discount tiering structures separate multinational-anchored premium contracts from regional spot purchases, with international brewers commanding lowest unit costs through multi-year offtake commitments. Price differentiation rests on QCVN certification grade and geographic delivery cost, with Red River Delta proximity yielding freight advantages. Cost compression in standard-grade soda-lime bottles is intensifying because aluminum can substitution erodes volume scale. Mass-market beverage bottlers exhibit highest price sensitivity; pharmaceutical and cosmetic compounders accept premium positioning for thermal shock documentation and decorative finish capabilities.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are emerging as competitive weapons among integrated operators with captive mold fabrication, squeezing toll processors dependent on third-party furnace capacity. Geographic supply concentration centers on Vietnam's northern industrial zones, with silica sand feedstock drawing from domestic deposits facing depletion pressures and Australian import alternatives. Furnace operations rest on natural gas pipeline infrastructure and imported LNG, exposing margin structures to currency fluctuation risk. Distribution runs through Red River Delta logistics networks anchored by Lach Huyen International Gateway Port, with southern-bound shipments incurring highway premiums through the North-South Expressway corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's container glass market presents a defensive-moat story anchored in regulatory entrenchment. QCVN certification timelines and oxy-fuel retrofit capital requirements create switching costs that protect validated incumbents from regional price competition.
For Market Incumbents: Harden compliance documentation speed as a competitive weapon by compressing laboratory testing queues for heavy metal migration analysis. Deepen backward integration into captive silica sand processing to offset domestic deposit depletion and secure 70-74% SiO₂ feedstock quality. Aluminum can substitution in single-serve carbonated soft drinks represents the core volume threat; defend position through returnable bottle program economics revival supported by provincial environmental fund infrastructure. For New Entrants and Emerging Players: Establish a beachhead in the Central Highlands corridor spanning Da Nang-to-Buon Ma Thuot, where proximate furnace placement would capture logistics premiums from emerging beverage distribution nodes. Target pharmaceutical-grade borosilicate expansion as the most penetrable specialty segment, with domestic pharma manufacturing scale-up pulling demand beyond soda-lime thermal shock capabilities. Lead with technical partnerships to multinational engineering firms capable of delivering compressed oxy-fuel retrofit schedules. For Investors and Strategic Acquirers: Capital is best deployed toward integrated operators with mold fabrication-through-delivery capabilities and validated QCVN compliance, as procurement consolidation favors dual-certified suppliers. Long-term viability over the mid-term horizon rests on furnace technology partnerships and renewable grid synchronization timing. Watch oxy-fuel retrofit completion rates across northern industrial zones as the signal indicating competitive repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | QCVN emissions compliance collapses payback assumptions and compresses upgrade timelines against renewable grid expansion. |
| Backward Integration into Silica Sand | Domestic deposit depletion pressures force longer haul distances or import dependency for high-purity feedstock. |
| Pharmaceutical-Grade Borosilicate Expansion | Injectable drug packaging demands thermal shock resistance beyond soda-lime capabilities as domestic pharma manufacturing scales. |
| Central Highlands Furnace Placement | Da Nang-to-Buon Ma Thuot corridor gaps create first-mover advantage near emerging beverage distribution nodes. |
| Returnable Bottle Program Revival | Provincial environmental fund deposit-return infrastructure investments could resurrect reusable container economics. |
Research Methodology
Operator-level perspectives from furnace engineering directors, beverage procurement leads, pharmaceutical packaging specialists, and QCVN certification laboratory managers anchored the qualitative base. Secondary validation drew from Vietnam Ministry of Natural Resources and Environment emissions disclosures, QCVN technical standard documentation, customs trade data for silica sand and LNG imports, and industrial zone development filings from Bac Ninh and Hai Duong provinces. Bottom-up capacity modeling triangulated against top-down demand segmentation across beverage, pharmaceutical, and cosmetic end-use channels.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, end-user application, manufacturing stage, and packaging hierarchy. CAGRs were derived from installed furnace capacity trajectories, retrofit completion schedules, and end-use demand elasticity assumptions. Forecast inputs incorporated QCVN enforcement intensity differentials between northern and southern industrial zones, plus renewable energy grid expansion timelines conditioning electric boosting adoption.
Stress conditions across natural gas price volatility bands, silica sand import dependency thresholds, and aluminum can substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
China Glass Container Packaging Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Philippines Container Glass Market