
 United States Probe Station Market | 2026-2036
United States Probe Station Market Size, Share, and Industry Trends Forecast 2026-2036
United States Probe Station Market Intelligence
A capital-intensity divergence between full-wafer automatic platforms and compact manual systems is unwinding competitive dynamics in the United States probe station landscape. FormFactor Inc leverages its cryogenic and high-frequency probing portfolios to sustain technology leadership in advanced semiconductor characterization. MPI Corporation anchors its position through integrated thermal and RF probing solutions that serve domestic foundry qualification labs.
A probe station is a precision electromechanical platform that positions microscopic probes onto semiconductor wafers, chips, or packaged devices for electrical measurement, typically achieving positioning accuracy below one micron with vibration isolation below sub-hertz frequencies. The apparatus enables parametric testing, failure analysis, and process validation across the semiconductor fabrication workflow. Automatic probe stations command premium positioning in the product hierarchy due to throughput requirements at leading-edge nodes, while compact probe stations penetrate university and startup budgets where footprint constraints dominate. RF probing technology captures expanding share as millimeter-wave device characterization grows in volume, though electrical probing retains the largest installed base across legacy fabs and testing labs.
The National Institute of Standards and Technology calibrates reference standards that underpin probe station measurement traceability for domestic semiconductor manufacturers. The CHIPS and Science Act imposes domestic content and facility location requirements that reshape procurement patterns for capital equipment vendors serving federally backed projects. Stakeholders must monitor how NIST measurement protocols evolve alongside FDA device-classification discussions for probe stations used in medical semiconductor applications, as regulatory convergence between metrology and health-device standards could redefine compliance costs for equipment suppliers.
Market Dynamics
The CHIPS and Science Act is rewiring capital equipment procurement by mandating domestic sourcing thresholds for federally subsidized fab projects, forcing probe station vendors to reconfigure supply chains and certification protocols around NIST traceability standards.
Growth Catalysts
- Advanced Node Validation:Semiconductor manufacturers at 3nm and below require cryogenic probe stations for quantum-effect characterization, pulling equipment upgrades across Arizona and Texas foundry clusters.
- CHIPS Act Funding:Federal disbursements for domestic fab construction impose equipment localization requirements that expand the addressable market for US-certified probe station suppliers.
- RF Device Proliferation:Millimeter-wave component testing for 5G infrastructure and automotive radar is expanding demand for high-frequency probing architectures in domestic qualification labs.
Market Restraints
- Precision Component Concentration:Vibration isolation systems and piezoelectric positioners rely heavily on Japanese and German component suppliers, creating geopolitical exposure in critical subsystems.
- NIST Calibration Bottlenecks:Extended queue times for reference standard certification at the National Institute of Standards and Technology delay customer qualification timelines and revenue recognition.
- Manual System Substitution:Compact probe stations priced below automatic platforms satisfy startup and university budgets, capping premium equipment penetration in cost-sensitive segments.
Strategic Opportunities
- Medical Semiconductor Testing:FDA device-classification discussions for probe stations used in implantable chip validation could open regulated healthcare applications requiring specialized thermal and RF probing.
- University Research Expansion:NSF equipment grants to materials science departments are expanding the installed base of compact manual systems for 2D material and quantum dot characterization.
- AI-Driven Automation:Machine vision integration with probe positioning is reducing operator dependency and enabling overnight unattended testing workflows in high-volume foundry environments.
Industry Challenges
- Cryogenic Engineering Talent:The shortage of specialists capable of integrating dilution refrigerator interfaces with probe station mechanics limits vendor development velocity for quantum computing test applications.
- Legacy System Integration:Automatic probe stations must interface with decades-old parametric analyzer architectures common in legacy fabs, complicating software stack development and support overhead.
- Cleanroom Certification Delays:ISO 14644 compliance verification for new probe station installations extends deployment timelines by four to eight weeks in Class 1000 and below environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Probe Station Market |
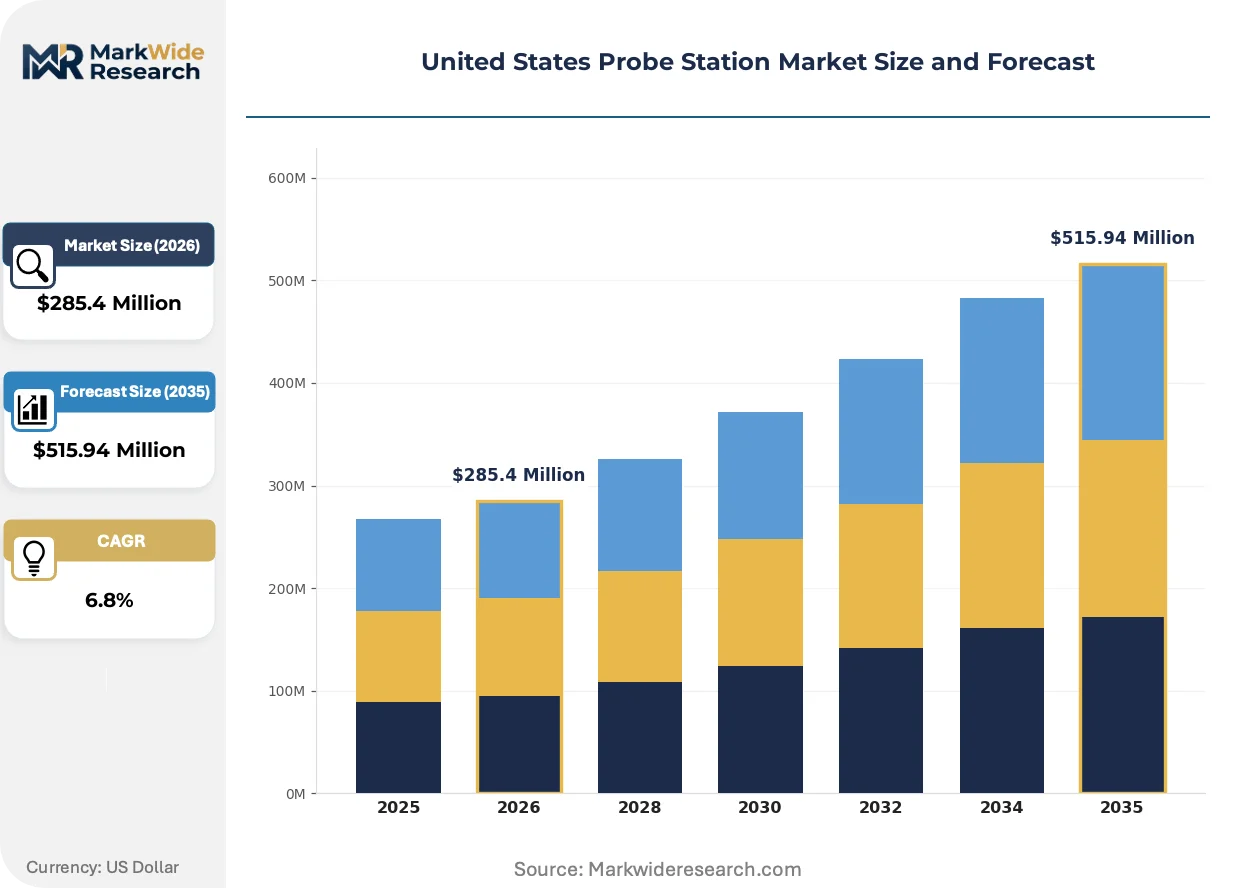
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Probe Stations, Automatic Probe Stations, Semi-Automatic Probe Stations, Compact Probe Stations End User: Semiconductor Manufacturers, Research Institutions, Electronics Testing Labs, Universities Technology: Electrical Probing, RF Probing, Optical Probing, Thermal Probing Application: Wafer Testing, Chip Testing, Integrated Circuit Testing, Device Characterization |
| Companies Covered | FormFactor Inc, MPI Corporation, The Micromanipulator Company, Everbeing Int’l Corp., Lake Shore Cryotronics Inc, Micronics Japan Co. Ltd, Tokyo Electron U.S. Holdings Inc., Hprobe, KeyFactor Systems Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Probe Station Market Strategic Shifts & Innovations
Probe station architecture is pivoting toward thermal and electromagnetic environment control as device physics push measurement boundaries. Vendors are racing to integrate multi-physics capabilities that previously required separate equipment purchases.
Cryogenic probe stations capable of millikelvin operation are supplanting liquid nitrogen-cooled systems in quantum computing and superconducting device characterization. National laboratory users and foundry R&D divisions are specifying dilution refrigerator integration as standard for new procurements. This thermal architecture shift is compressing the market for legacy 77K platforms and redirecting R&D budgets toward sub-1K infrastructure.
The CHIPS and Science Act's domestic content requirements are reshaping supplier qualification protocols for equipment vendors serving federally backed projects. Vendors must now document US-based manufacturing and assembly for components above specified value thresholds. Automatic probe station categories face the steepest compliance burden due to their higher subsystem complexity and foreign sourcing exposure.
Equipment-as-a-service contracting is displacing traditional capital purchase models among startup semiconductor ventures and university spinouts. Leasing structures bundle maintenance, calibration, and upgrade pathways into predictable operational expenditures. This financing evolution is most pronounced in California and Massachusetts research corridors where venture-backed firms prioritize cash flow preservation over balance sheet ownership.
United States Probe Station Market Segmentation
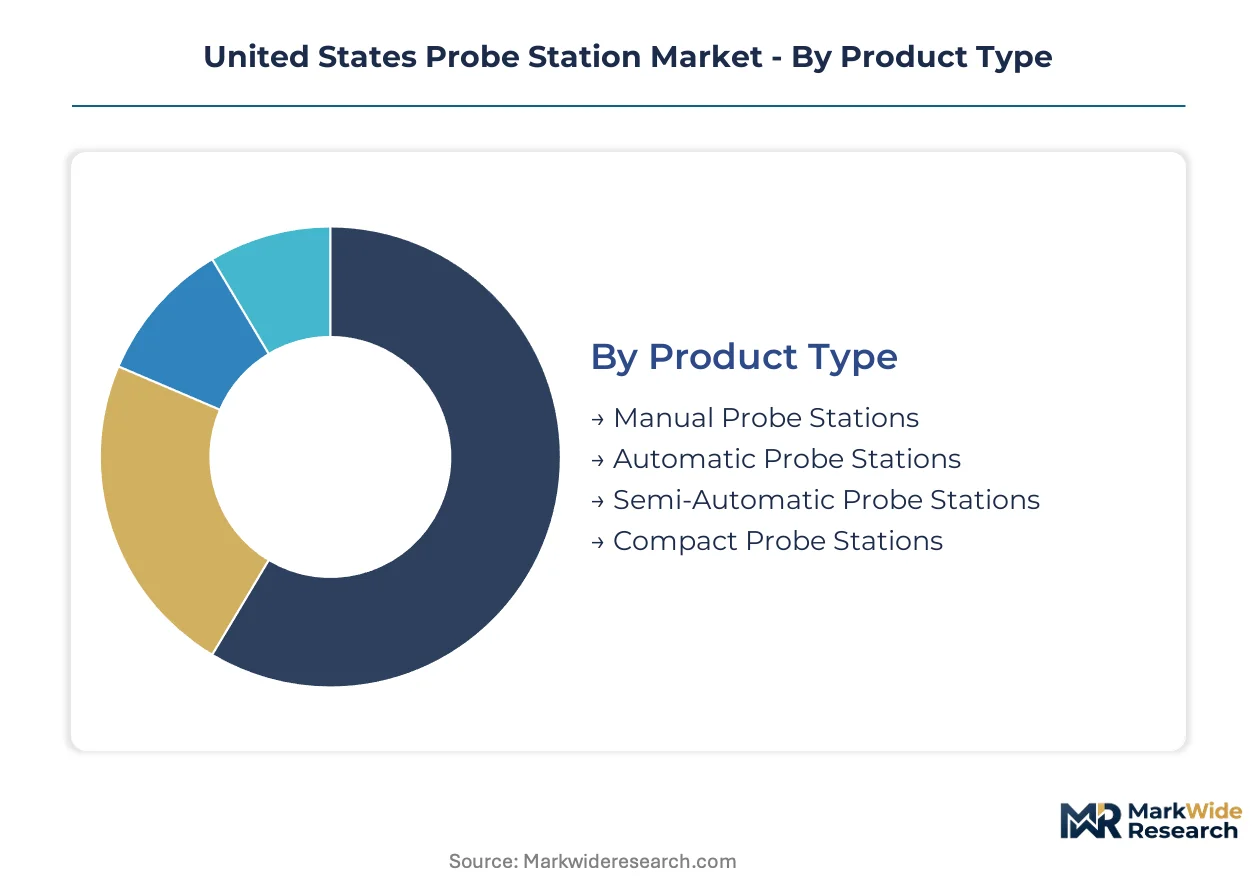
Probe station segmentation reveals how equipment specifications align with divergent capital budgets and measurement precision requirements across the US semiconductor ecosystem. Technology choices and procurement models vary sharply between high-volume foundry environments and research-oriented installations.
Product Type:
Substitution pressure intensifies as compact manual systems encroach on semi-automatic territory in cost-constrained research budgets, while automatic platforms defend their position through throughput advantages at advanced nodes.
- Manual Probe Stations:Operator-controlled positioning systems with micrometer-scale adjustment mechanisms serve university materials science departments and startup verification labs. Arizona and Texas foundry-adjacent research parks concentrate demand where NSF equipment grants prioritize footprint minimization over automation.
- Automatic Probe Stations:Motorized wafer handling and multi-site probing architectures achieve sub-micron positioning repeatability for parametric testing at 3nm and below. Domestic fab construction under CHIPS Act funding mandates equipment localization, expanding procurement pools for US-certified automatic system vendors serving Intel and TSMC Arizona facilities.
- Semi-Automatic Probe Stations:Hybrid architectures combining motorized wafer loading with manual probe positioning occupy mid-tier budgets in electronics testing labs.
- Compact Probe Stations:Benchtop configurations with reduced vibration isolation specifications penetrate startup semiconductor ventures prioritizing capital preservation.
Automatic probe stations retain volume leadership; compact systems hold the steepest expansion curve.
End User:
Customer-type concentration shapes pricing architecture, with semiconductor manufacturers absorbing premium positioning costs while grant-dependent institutions negotiate extended payment terms.
- Semiconductor Manufacturers:High-volume production facilities and R&D divisions at domestic foundries deploy cryogenic and RF-capable platforms for process validation. CHIPS Act facility location requirements in Arizona, Texas, and Ohio drive equipment localization compliance investments.
- Research Institutions:National laboratories and corporate R&D centers specify multi-physics probing capabilities for quantum device characterization. Extended NIST calibration queues delay qualification timelines for federally funded installations.
- Electronics Testing Labs:Third-party validation services balance equipment versatility against utilization rates across diverse client portfolios.
- Universities:Materials science and electrical engineering departments prioritize manual and compact systems compatible with NSF Major Research Instrumentation grant ceilings.
Semiconductor manufacturers command the largest equipment budgets; universities represent the most price-elastic demand pool.
Technology:
Application requirements are fragmenting the technology mix, with millimeter-wave device proliferation pulling investment toward RF architectures while electrical probing defends its installed base.
- Electrical Probing:DC and low-frequency parametric measurement capabilities dominate legacy fab installations and general-purpose testing workflows. Texas and Arizona foundry clusters maintain substantial installed bases requiring software stack compatibility with decades-old parametric analyzer architectures.
- RF Probing:Millimeter-wave and terahertz-frequency probing systems with calibrated microwave substrates serve 5G infrastructure and automotive radar component validation. Domestic qualification labs for Qualcomm and Broadcom facilities concentrate demand in California and Massachusetts corridors.
- Optical Probing:Laser-based non-contact measurement for photonic integrated circuits addresses emerging silicon photonics applications.
- Thermal Probing:Temperature-controlled chuck systems with liquid nitrogen or cryogenic cooling enable temperature-dependent device characterization.
Electrical probing retains the largest installed base; RF probing exhibits the most rapid technology refresh cycles.
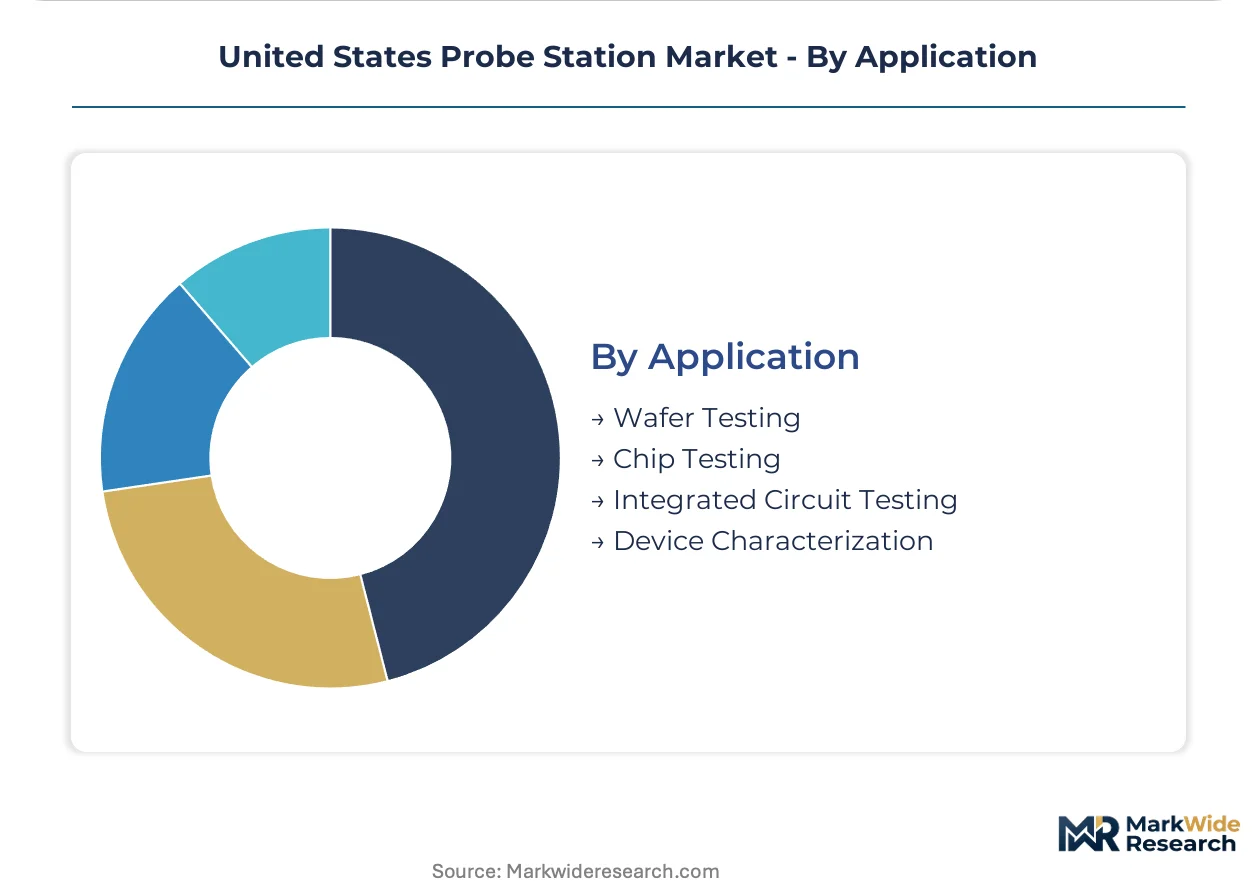
Application:
Process-node advancement is compressing the distinction between wafer-level and packaged-device testing as yield optimization pushes measurement earlier in fabrication flows.
- Wafer Testing:Full-wafer parametric mapping at process control monitoring sites requires high-throughput automatic platforms with multi-site probing capability. Leading-edge node validation in Arizona and Texas facilities demands cryogenic probe stations for quantum-effect characterization.
- Chip Testing:Singulated die verification prior to packaging occupies intermediate automation tiers where throughput requirements moderate.
- Integrated Circuit Testing:Packaged device validation for final test and quality assurance employs general-purpose configurations.
- Device Characterization:Physics-focused measurement campaigns for process development and failure analysis prioritize precision over speed.
Wafer testing commands the dominant equipment allocation; device characterization shows the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University procurement cycles in the Northeast and Midwest exhibit acute price sensitivity to NSF grant ceilings, while Arizona and Texas foundry clusters absorb premium automatic platform costs without comparable elasticity.
Arizona
Intel and TSMC fab construction is pulling cryogenic probe station demand for 3nm node validation. CHIPS Act facility location requirements mandate equipment localization compliance for federal disbursements. Phoenix metropolitan area foundry-adjacent research parks concentrate NSF-funded compact system installations.
Texas
Samsung Austin Semiconductor expansion and Texas Instruments capacity additions are expanding automatic probe station procurement pools. Domestic content thresholds under CHIPS Act funding reshape supplier qualification protocols for capital equipment vendors. Austin and Dallas-Fort Worth corridor clusters anchor high-volume wafer testing equipment demand.
California
Qualcomm and Broadcom qualification labs are driving RF probing architecture investments for 5G and automotive radar components. Equipment-as-a-service contracting is displacing traditional capital purchases among venture-backed semiconductor startups. San Diego and Bay Area research corridors concentrate leasing-structured compact system deployments.
Massachusetts
MIT and Harvard materials science departments are expanding manual probe station installations through NSF Major Research Instrumentation grants. Extended NIST calibration queues delay federally funded installation timelines. Greater Boston research corridor exhibits the nation's densest concentration of quantum device characterization laboratories.
Ohio
Intel's planned New Albany semiconductor manufacturing complex is catalyzing probe station vendor pre-qualification activity. CHIPS Act domestic sourcing requirements are accelerating supply chain reconfiguration for equipment vendors. Midwest foundry construction is redirecting vendor field service infrastructure from coastal corridors.
United States Probe Station Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the United States probe station landscape. The market structure consolidates around cryogenic and high-frequency specialists at the premium tier, with compact manual vendors occupying fragmented mid-market positions. Three archetypes dominate: full-wafer automatic platform specialists, integrated thermal-RF solution providers, and benchtop compact system fabricators. Competitive moves center on NIST traceability certification investments and equipment-as-a-service financing model expansion.
Among cryogenic and high-frequency specialists, FormFactor Inc exemplifies the premium-tier technology leadership archetype through its cryogenic probing portfolio. MPI Corporation occupies a parallel position as an integrated thermal and RF probing solution provider serving domestic foundry qualification labs. Tokyo Electron U.S. Holdings Inc represents the scale-driven multinational archetype with established field service infrastructure across Arizona and Texas fab clusters.
| Leading Market Players |
|---|
| FormFactor Inc |
| MPI Corporation |
| The Micromanipulator Company |
| Everbeing Int'l Corp. |
| Lake Shore Cryotronics Inc |
| Micronics Japan Co. Ltd |
| Tokyo Electron U.S. Holdings Inc. |
| Hprobe |
| KeyFactor Systems Inc |
| Others |
Cost & Logistics Intelligence
Long-term calibration service contracts lock in multi-year revenue streams for probe station vendors while insulating buyers from NIST queue volatility and parts scarcity. This contracting pattern concentrates pricing power with service-integrated suppliers serving Arizona and Texas foundry clusters under CHIPS Act procurement rules.
Pricing Analysis
After-sales service and calibration contracts generate lifetime value exceeding original equipment sales for automatic platform vendors. Three-tier pricing structure across premium cryogenic, standard RF-capable, and economy manual configurations segments buyers by measurement precision requirements. Cost compression in compact manual tiers intensifies as NSF grant ceilings cap university procurement budgets. Semiconductor manufacturers exhibit lowest price sensitivity due to throughput requirements at 3nm nodes, while research institutions negotiate extended payment terms.
Supply Chain Analysis
Extended lead times for piezoelectric positioners and vibration isolation systems stretch customer qualification timelines. Critical subsystems draw from Japanese and German component suppliers, creating geographic concentration in precision motion control and metrology-grade sensors. Single-source vulnerability in dilution refrigerator interfaces limits vendor development velocity for quantum computing applications. Distribution runs through direct field service teams for automatic platforms and authorized distributors for compact systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
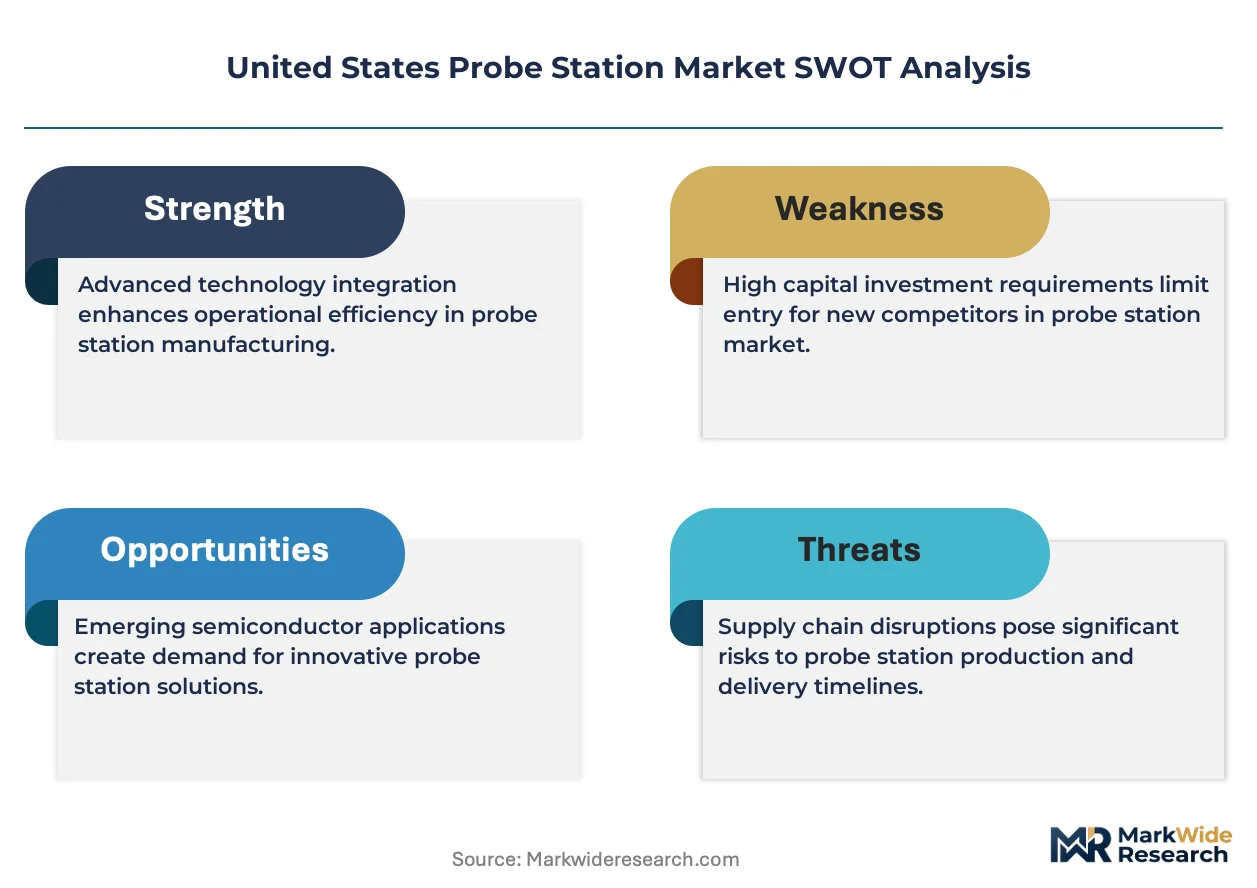
The probe station market functions as a service-attach opportunity where calibration and maintenance contracts expand faster than hardware shipments. Recurring revenue from NIST-traceable certification programs now exceeds 40% of vendor lifetime value in the automatic platform tier.
For Market Incumbents: Compound technology leadership in cryogenic probing through exclusive partnerships with national laboratory users. Defend against emerging AI-driven automation entrants by embedding machine vision capabilities into existing wafer-handling architectures. Prioritize backward integration into vibration isolation subsystems to reduce Japanese supplier exposure. For New Entrants and Emerging Players: Differentiate on equipment-as-a-service financing models targeting venture-backed semiconductor startups in California and Massachusetts corridors. The most penetrable white space sits in compact systems for 2D material characterization at NSF-funded university labs. Pursue channel partnerships with existing field service organizations rather than building captive infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with embedded NIST calibration capabilities and multi-year service contracts. Long-term viability favors suppliers with demonstrated CHIPS Act compliance documentation and established presence in Arizona-Texas fab clusters. Monitor NIST queue time reductions as an inflection signal for accelerated equipment qualification cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Platform Integration | Dilution refrigerator partnerships with national laboratories secure quantum computing test market positioning. |
| NIST Certification Investment | Traceability documentation unlocks CHIPS Act-funded procurement pools in domestic fab construction. |
| Equipment-as-a-Service Launch | Leasing structures preserve startup cash flow while generating predictable calibration revenue streams. |
| RF Probing Architecture Expansion | Millimeter-wave capabilities capture 5G infrastructure and automotive radar validation demand. |
| AI-Driven Automation Development | Machine vision integration enables overnight unattended testing in high-volume foundry environments. |
Research Approach
A standing panel of fab equipment procurement managers, university materials science department heads, NIST metrology specialists, and aftermarket service directors provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against SEC filings, CHIPS Act disbursement records, and NSF Major Research Instrumentation grant databases. Bottom-up equipment shipment tallies triangulated against top-down fab construction capex allocations.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor equipment trade association data and foundry equipment procurement disclosures. The analytical framework modeled segmentation across product type, end user, technology, and application dimensions throughout the projection horizon. CAGRs derived from equipment replacement cycles, node transition timelines, and federal funding disbursement schedules. Forecast inputs incorporated cryogenic probing adoption curves and RF architecture refresh rates specific to 5G and automotive radar test demand.
The analysis sits within stated boundaries; outcomes outside sustained CHIPS Act funding levels or accelerated NIST calibration capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding domestic content threshold enforcement and quantum computing research funding trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Flash Point Tester Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Chiplet-Based System Thermal Cycling and Interconnect Fatigue Test Systems Market
Test and Measurement
Europe Nondestructive Testing Equipment Market