
 IC CMP Slurries and Pads Market | 2026-2036
IC CMP Slurries and Pads Market Size, Share, and Industry Trends Forecast 2026-2036
IC CMP Slurries and Pads Market Analysis
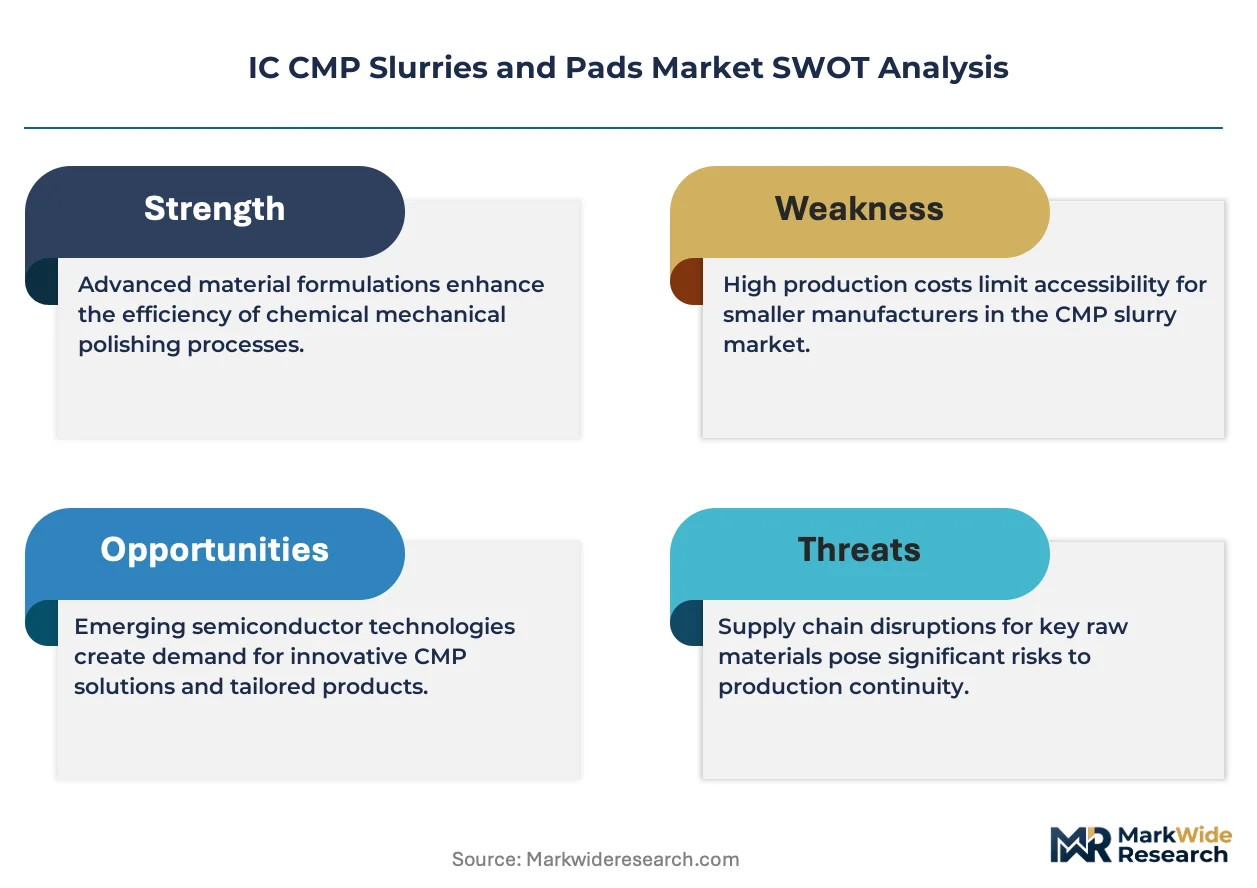
Integrated pad-and-slurry bundling is recalibrating procurement economics for advanced-node foundries. Cabot Microelectronics Corporation leverages its vertical integration across colloidal silica supply to sustain pricing power in copper slurry formulations. Fujimi Corporation anchors its position through specialized cerium oxide compositions for shallow trench isolation layers. Entegris Inc competes by extending its contamination control expertise into pad conditioning and slurry delivery systems.
IC CMP slurries and pads comprise engineered suspensions of abrasive particles and porous polymeric pads used to planarize dielectric and metal films on semiconductor wafers through combined chemical etching and mechanical abrasion, typically operating at downforces below seven pounds per square inch and rotational speeds exceeding one hundred revolutions per minute. Chemical slurries command the deepest margin pools where proprietary particle stabilization chemistry creates formulation lock-in, while polishing pads exhibit longer qualification cycles that protect incumbent positions. Semiconductor manufacturing absorbs the dominant volume share as three-nanometer and two-nanometer ramps multiply CMP steps per wafer, whereas wafer level packaging represents the fastest-growing application as fan-out architectures proliferate.
EPA oversight of per- and polyfluoroalkyl substance discharge constrains fluorinated pad conditioning chemistry in US fabrication facilities, while REACH registration requirements in Europe filter smaller slurry compounders from direct supply to continental foundries. Japan's METI guides domestic pad manufacturers through JIS standard alignment for export qualification to Korean and Taiwanese customers. Stakeholders must monitor how emerging PFAS restrictions in multiple jurisdictions reshape raw material sourcing for both slurry dispersants and pad binders.
Market Dynamics
Node migration below five nanometers is compressing planarization tolerances and multiplying CMP steps per wafer, forcing slurry suppliers to reformulate particle stabilization chemistry for EUV-patterned layers.
Growth Catalysts
- Sub-7nm Foundry Expansion:Taiwan and South Korean integrated device manufacturers are scaling copper and tungsten slurry consumption as transistor density requirements intensify planarization cycles.
- REACH-Driven Formulation Innovation:European ECHA restrictions on colloidal silica dispersants are accelerating aqueous-based slurry development for continental supply qualification.
- Fan-Out Packaging Ramp:Wafer level packaging architectures are proliferating CMP steps for redistribution layer planarization in advanced packaging facilities.
Market Restraints
- PFAS Chemistry Constraints:EPA discharge oversight of per- and polyfluoroalkyl substances limits fluorinated pad conditioning chemistry adoption in US fabrication.
- East Asian Supply Concentration:Colloidal silica precursor production clusters in Taiwan and Japan create geographic vulnerability for non-integrated slurry compounders.
- Pad Qualification Cycles:Eighteen-to-twenty-four-month foundry qualification timelines for new polymeric pad formulations lock incumbents into position.
Strategic Opportunities
- Indian Semiconductor Subsidies:PLI scheme incentives for domestic fab construction create virgin demand for copper and barrier slurry supply relationships.
- Slurry-Pad Bundling Models:Integrated consumable procurement contracts are opening margin capture opportunities for suppliers with captive pad production.
- EU Green Deal Alignment:CSRD reporting requirements favor slurry suppliers with verified lifecycle carbon data for European foundry qualification.
Industry Challenges
- Particle Stabilization Expertise Gap:Formulation chemists with zeta potential control experience for sub-50nm abrasive particles command scarcity premiums.
- Dual-Use Export Classification:US Commerce Department licensing for cerium oxide and specialized colloidal silica delays qualification timelines for non-domestic customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IC CMP Slurries and Pads Market |
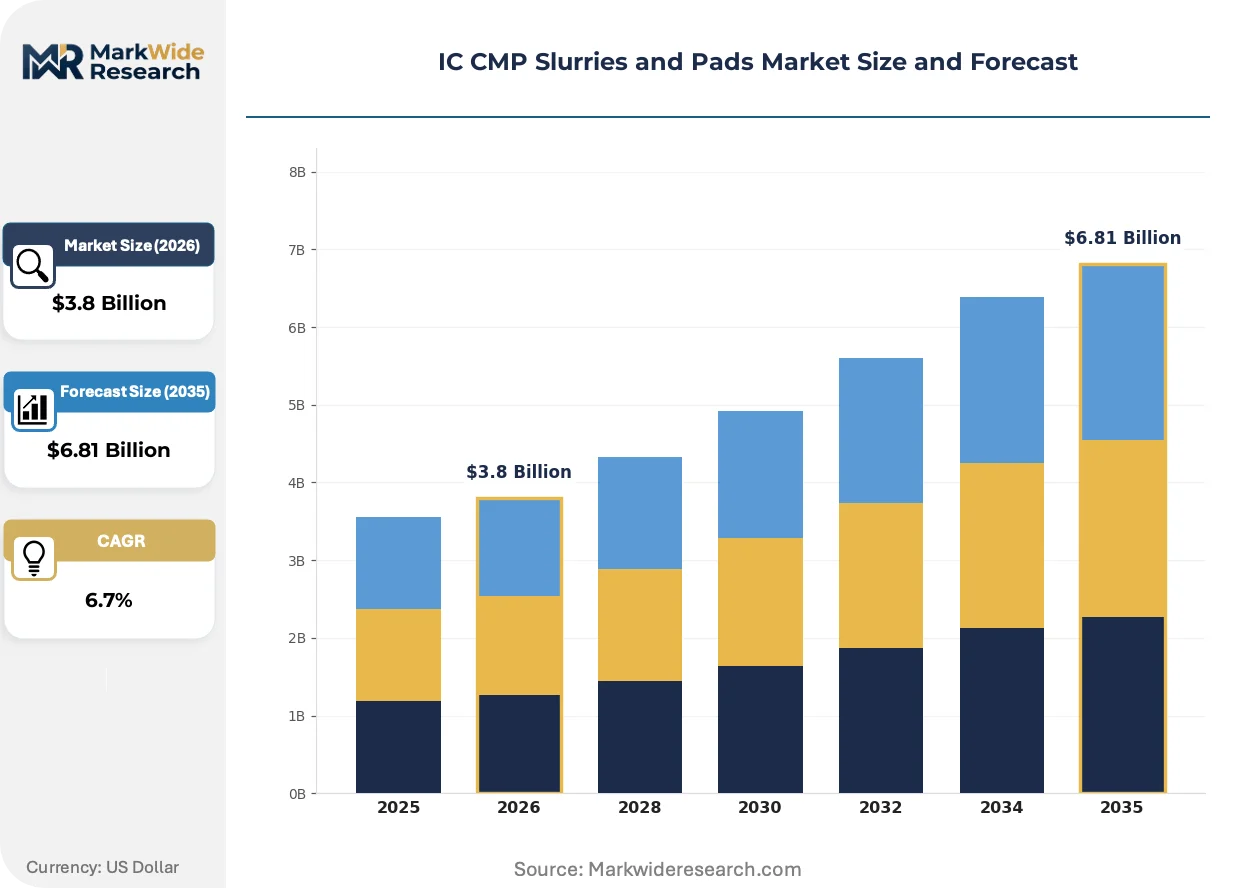
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Slurries, Polishing Pads, Diamond Pads, Abrasive Slurries Application: Wafer Level Packaging, Semiconductor Manufacturing, Hard Disk Drive Production, MEMS Fabrication End User: Foundries, Integrated Device Manufacturers, Electronics Manufacturers, Research Institutions Technology: Wet Processing, Chemical Mechanical Polishing, Surface Finish Technologies, Advanced Coating |
| Companies Covered | Cabot Microelectronics Corporation, Dow Electronic Materials, Fujimi Corporation, Saint-Gobain Ceramics and Plastics, Merck KGaA, Entegris Inc, Applied Materials Inc, 3M Company, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IC CMP Slurries and Pads Market Emerging Trajectories
Process integration between lithography and planarization is collapsing traditional consumable procurement boundaries, with slurry-pad-conditioning system optimization replacing discrete component sourcing.
Engineered cerium oxide abrasives with narrow particle size distribution are electrifying shallow trench isolation applications by enabling atomic-scale oxide removal rates. Memory manufacturers in South Korea are qualifying these formulations for 3D NAND stack planarization. The technology is compressing traditional silica-based slurry market share in dielectric CMP segments.
Japan's METI is aligning domestic pad manufacturers to JIS standards for export qualification to Korean and Taiwanese foundries. This standardization reduces technical barrier variance for cross-border supply agreements. Japanese suppliers are leveraging this framework to displace incumbent European pad positions in East Asian advanced node facilities.
Consolidated consumable procurement contracts are replacing discrete slurry and pad purchasing across Taiwan Semiconductor Manufacturing Company and Samsung Foundry supply chains. Single-source accountability for planarization yield is displacing multi-vendor qualification models. This concentration is most visible in Hsinchu Science Park and Pyeongtaek cluster procurement offices.
IC CMP Slurries and Pads Market Segmentation
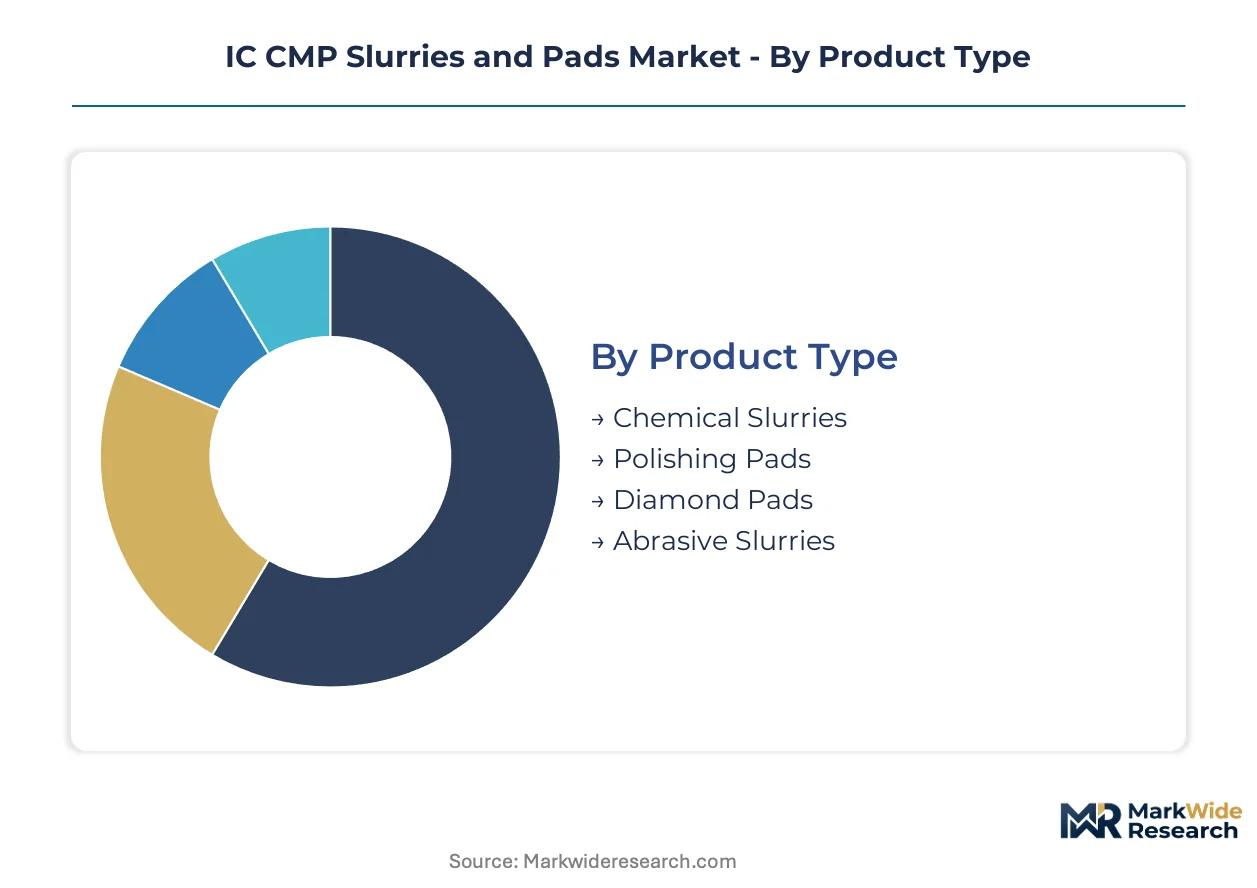
IC CMP consumables fragment across product architectures that determine procurement bundling strategies and qualification economics. Understanding how slurries, pads, and process technologies interlock reveals where suppliers capture margin and where buyers consolidate purchasing power.
Product Type:
Chemical slurries function as standalone consumables requiring precise particle stabilization chemistry, while polishing pads embed into integrated planarization systems with longer qualification cycles.
- Chemical Slurries:Engineered suspensions of colloidal silica, cerium oxide, or aluminum oxide abrasives in aqueous or solvent-based carriers with proprietary dispersant chemistry. Taiwan Semiconductor Manufacturing Company and Samsung Foundry in South Korea concentrate demand for copper and tungsten formulations as EUV-patterned layers tighten planarization tolerances below seven nanometers. REACH restrictions on colloidal silica precursors are forcing European compounders toward aqueous dispersant alternatives.
- Polishing Pads:Porous polyurethane matrices with engineered pore structures and surface grooves that control slurry distribution and debris evacuation during planarization. Japanese pad manufacturers aligned to METI-guided JIS standards are displacing European incumbents in Hsinchu and Pyeongtaek cluster procurement offices through streamlined cross-border qualification.
- Diamond Pads:Fixed-abrasive substrates embedding synthetic diamond particles for aggressive material removal in hard substrate applications.
- Abrasive Slurries:General-purpose formulations without specialized chemical etching components, serving legacy node planarization and substrate preparation steps.
Volume placements concentrate in Chemical Slurries; the faster expansion belongs to Polishing Pads as integrated bundling contracts proliferate.
Application:
Front-end semiconductor processing commands premium pricing through yield-critical planarization steps, while packaging applications scale through step multiplication in fan-out architectures.
- Semiconductor Manufacturing:Front-end wafer processing encompassing dielectric CMP, metal CMP for copper interconnects, and barrier layer planarization. Three-nanometer and two-nanometer ramps at Taiwan and South Korean foundries are multiplying CMP steps per wafer, intensifying consumption of specialized cerium oxide formulations for shallow trench isolation.
- Wafer Level Packaging:Redistribution layer planarization and through-silicon via reveal in advanced packaging architectures. Memory manufacturers in South Korea are qualifying these processes for 3D NAND stack planarization, compressing traditional dielectric slurry market share.
- Hard Disk Drive Production:Substrate polishing for magnetic media manufacturing, requiring controlled surface roughness specifications.
- MEMS Fabrication:Planarization of silicon and glass substrates for microelectromechanical device manufacturing.
Revenue concentration sits with Semiconductor Manufacturing; Wafer Level Packaging climbs the fastest as fan-out architectures multiply planarization cycles per packaged device.
End User:
Integrated device manufacturers internalize process optimization expertise, while foundries externalize consumable selection to dedicated planarization engineering teams.
- Foundries:Pure-play semiconductor manufacturing facilities operating on contract basis for fabless design houses. Taiwan and South Korean foundries are consolidating procurement through single-source slurry-pad-conditioning contracts that displace multi-vendor qualification models.
- Integrated Device Manufacturers:Vertically integrated semiconductor companies combining design and fabrication capabilities. These entities sustain captive process engineering teams that optimize particle stabilization chemistry for proprietary device architectures.
- Electronics Manufacturers:Contract assemblers and subsystem integrators with limited direct CMP consumable exposure.
- Research Institutions:Academic and government laboratories conducting materials science and process development research.
Procurement scale aggregates at Foundries; Integrated Device Manufacturers deepen technical engagement fastest as proprietary node development accelerates.
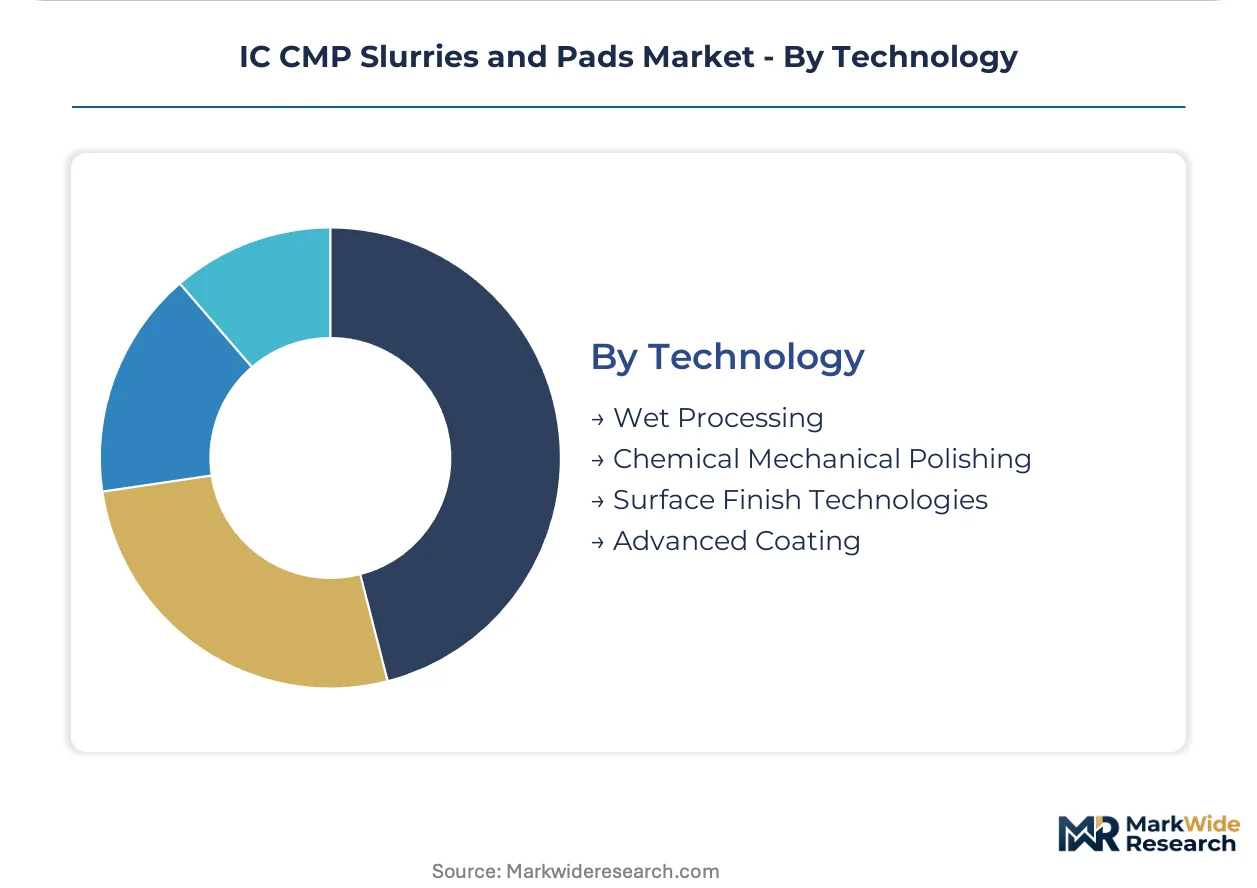
Technology:
Wet processing platforms dominate volume deployment, while advanced coating technologies capture emerging applications through precision thickness control.
- Chemical Mechanical Polishing:The dominant planarization technology combining chemical etching and mechanical abrasion at controlled downforces and rotational speeds. EPA oversight of PFAS discharge constrains fluorinated pad conditioning chemistry adoption in US fabrication facilities using this technology.
- Wet Processing:General liquid-based surface treatment encompassing cleaning, etching, and stripping operations adjacent to CMP.
- Surface Finish Technologies:Precision polishing and buffing methods for final topography control before lithography patterning.
- Advanced Coating:Functional layer deposition and planarization for emerging memory and logic architectures.
Deployment mass concentrates in Chemical Mechanical Polishing; Advanced Coating gains share fastest as novel memory architectures demand precision thickness control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of colloidal silica precursors and polyurethane pad substrates clusters in Taiwan and Japan, while consumption concentrates at advanced-node foundries in South Korea and Taiwan. This geographic mismatch forces non-integrated compounders to navigate concentrated supply chains and extended qualification timelines.
United States
Domestic foundry construction under the CHIPS and Science Act is creating virgin demand for copper and barrier slurry supply relationships. EPA oversight of PFAS discharge constrains fluorinated pad conditioning chemistry adoption in fabrication facilities. Arizona and Texas cluster development is accelerating procurement timelines for consumable suppliers seeking foundry qualification.
Taiwan
TSMC and UMC are multiplying CMP steps per wafer as three-nanometer production ramps, intensifying consumption of specialized cerium oxide formulations. The National Development Council coordinates domestic pad manufacturer alignment to international qualification standards. Hsinchu Science Park procurement offices are consolidating slurry-pad-conditioning contracts into single-source accountability models.
South Korea
Samsung Foundry and SK Hynix are scaling tungsten slurry consumption for EUV-patterned layer planarization below five nanometers. MFDS chemical registration requirements filter smaller compounders from direct supply to domestic fabs. Pyeongtaek cluster facilities are driving the fastest qualification cycles for integrated consumable bundling contracts.
Japan
Domestic pad manufacturers supply porous polyurethane matrices to Korean and Taiwanese foundries through METI-guided JIS standard alignment. The Ministry of Economy, Trade and Industry streamlines cross-border technical barrier variance for export qualification. Osaka and Nagoya industrial corridors anchor captive colloidal silica production for proprietary slurry formulations.
Germany
European headquarters of major slurry compounders face ECHA REACH restrictions on colloidal silica dispersants, forcing aqueous-based formulation development. The EU Green Deal CSRD reporting requirements favor suppliers with verified lifecycle carbon data for foundry qualification. Dresden and Bavarian semiconductor clusters are emerging as qualification gateways for continental advanced node supply.
IC CMP Slurries and Pads Market Vendor Landscape
The competitive structure tilts toward integrated material suppliers with captive abrasive production and in-house pad manufacturing capabilities. Three tiers have crystallized: diversified chemical conglomerates with semiconductor divisions, specialized consumable pure-plays, and equipment-integrated solution providers. Consolidation is accelerating through backward integration into colloidal silica supply and strategic partnerships between slurry compounders and pad fabricators.
Among specialized consumable pure-plays, Cabot Microelectronics Corporation, Fujimi Corporation, and Entegris Inc exemplify divergent strategic positioning. Cabot Microelectronics occupies a position anchored in colloidal silica supply chain control. Fujimi Corporation represents the specialized abrasive formulation archetype with cerium oxide expertise. Entegris Inc sits within the contamination control extension model, leveraging clean transport systems into planarization consumables.
| Leading Market Players |
|---|
| Cabot Microelectronics Corporation |
| Dow Electronic Materials |
| Fujimi Corporation |
| Saint-Gobain Ceramics and Plastics |
| Merck KGaA |
| Entegris Inc |
| Applied Materials Inc |
| 3M Company |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Advanced-node foundry procurement offices in Hsinchu and Pyeongtaek anchor contract-based long-term offtake agreements that compress spot-market pricing variability for consumable suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies according to particle stabilization chemistry complexity and qualification depth with specific device manufacturers.
Pricing Analysis
Margin tightening in premium cerium oxide formulations reflects eighteen-to-twenty-four-month foundry qualification timelines that protect incumbent positions. Price differentiation hinges on proprietary zeta potential control expertise and ISO-classified cleanroom manufacturing certification. Cost-down pressure on standard colloidal silica slurries accelerates because REACH restrictions filter smaller European compounders from direct supply. Packaging applications exhibit highest price sensitivity; advanced-node foundries show lowest sensitivity due to yield-critical planarization requirements.
Supply Chain Analysis
Regional distribution centers in Osaka and Nagoya feed hub-and-spoke patterns into Korean and Taiwanese cluster facilities. Geographic supply concentration centers on Japan, Taiwan, and South Korea for both colloidal silica precursors and polyurethane pad substrates. Raw material dependencies draw from high-purity abrasive ores, fluorinated dispersant chemistries, and synthetic diamond substrates. Single-source vulnerability in Taiwanese precursor production creates structural risk. Distribution runs through integrated pad-and-slurry bundling contracts directly to foundry procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IC CMP consumables sector operates as a vertical-integration race where captive colloidal silica production and in-house pad manufacturing determine margin capture. Players pursue backward integration into abrasive supply as the decisive upstream lever.
For Market Incumbents: Extend formulation lock-in through specialized cerium oxide expertise for shallow trench isolation applications. Deepen captive supply of colloidal silica precursors to defend against Japanese pad manufacturers displacing European positions. Counter emerging aqueous-based slurry compounders by accelerating JIS standard alignment for cross-border qualification. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer white-space entry around legacy distributor relationships. Indian PLI scheme semiconductor subsidies create virgin demand for copper and barrier slurry supply relationships. Target wafer level packaging applications as the fastest-growing segment with abbreviated qualification cycles compared to front-end manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized consumable pure-plays with captive abrasive production in East Asian industrial corridors. Long-term viability across the five-to-ten year horizon rests on integration depth rather than formulation breadth. Monitor EPA PFAS discharge rulemaking as the critical inflection signal for fluorinated chemistry exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colloidal Silica | Cabot Microelectronics leverages captive supply to sustain pricing power in copper formulations. |
| JIS Standard Alignment for Export Qualification | Japanese pad manufacturers streamline cross-border technical barriers for Korean and Taiwanese foundry access. |
| Aqueous-Based Formulation Development | European compounders adapt to ECHA REACH restrictions on colloidal silica dispersants for continental supply. |
| Integrated Pad-and-Slurry Bundling Contracts | TSMC and Samsung Foundry consolidate procurement into single-source accountability models. |
| PFAS-Free Pad Conditioning Chemistry | Suppliers preempt EPA discharge constraints in Arizona and Texas CHIPS Act cluster facilities. |
Methodological Framework
Document review covered SEC 10-K filings, customs and trade data, and ECHA REACH registration databases, complemented by interviews with planarization engineering directors, foundry procurement managers, and colloidal silica plant managers. Primary fieldwork engaged slurry formulation chemists, pad manufacturing technical leads, and contamination control specialists. Secondary validation drew from METI industrial policy briefings, MFDS chemical registration filings, and Taiwan National Development Council semiconductor cluster reports. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Cross-referencing historical consumption patterns with expert panel input shaped the analytical framework. Segmentation dimensions modeled include product architecture, application layer, end-user procurement model, and planarization technology platform. CAGRs were derived through iterative convergence of supply-side capacity expansion and demand-side step multiplication at advanced nodes. Forecast inputs incorporated EUV lithography ramp schedules and fan-out packaging architecture proliferation rates.
Inputs from foundry procurement offices and pad manufacturer technical documentation were available through the study window; gaps in proprietary particle stabilization chemistry specifications introduce uncertainty bands around formulation market share allocations. Forecasts reflect documented assumptions regarding qualification timeline stability and regulatory restriction implementation pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Silicon Wafer Reclaim Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Advanced Process Control Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
Thin Film Semiconductor Deposition Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Silicon Turners Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Electronic Manufacturing Services (EMS) Market
Semiconductor Manufacturing
Global Overall EUV Lithography Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Photoresist Stripper Market