
 United States Photoresist and Photoresist Ancillaries Market | 2026-2036
United States Photoresist and Photoresist Ancillaries Market Size, Share, and Industry Trends Forecast 2026-2036
United States Photoresist and Photoresist Ancillaries Market Intelligence
EUV lithography is rewriting the material requirements for advanced patterning, forcing reformulations across the entire photoresist stack. DuPont de Nemours leverages its heritage in polymer science to anchor positions in chemically amplified resists for deep UV nodes. JSR Corporation competes through specialized EUV resist platforms optimized for high-NA exposure systems. Tokyo Ohka Kogyo dominates ancillary material supply, extending its footprint in developers and removers that pair with leading resist chemistries.
Photoresist denotes a light-sensitive polymer formulation that undergoes solubility switching upon exposure to specific wavelengths, enabling sub-micron pattern transfer onto silicon wafers through subsequent development and etch steps. The material typically incorporates photoacid generators, quenchers, and protective groups tuned to exposure wavelengths ranging from 436 nm G-line down to 13.5 nm EUV. Semiconductor manufacturing applications absorb the dominant value pool as foundries and IDMs push resolution limits, while MEMS fabrication sustains steady demand for thicker, more mechanically robust resist films. Extreme UV formulations represent the fastest-growing product type as high-volume manufacturing migrates toward two-nanometer-class nodes.
EPA oversight of per- and polyfluoroalkyl substance discharge shapes reformulation timelines for fluorinated components historically used in topcoat layers. FDA and OSHA frameworks govern worker exposure limits during resist coating and stripping operations, particularly in OSAT facilities with less automated handling infrastructure than leading foundries. The CHIPS Act funding disbursements from the Department of Commerce are conditioning capital allocation decisions across the supply chain. Stakeholders must monitor how NIST calibration standards for EUV metrology evolve, as these directly determine which resist platforms qualify for federal subsidy-linked procurement.
Market Dynamics
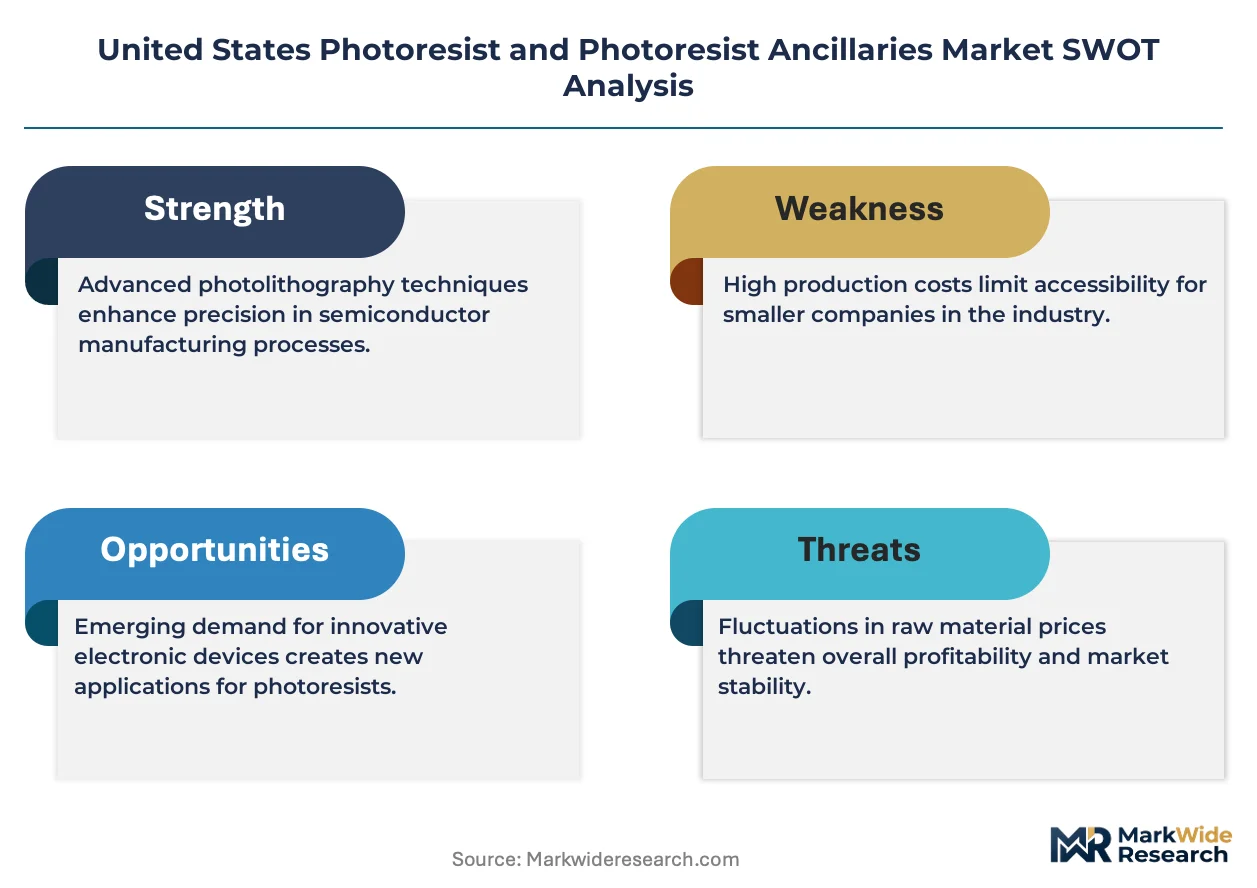
The CHIPS and Science Act is restructuring domestic semiconductor supply chains by conditioning federal subsidies on domestic photoresist procurement, forcing foundries to qualify US-based resist formulations ahead of foreign alternatives.
Growth Catalysts
- High-NA EUV Deployment:Intel and TSMC Arizona fabs are qualifying next-generation photoresist platforms for 0.55 numerical aperture lithography systems, expanding addressable demand for chemically amplified resists.
- CHIPS Act Subsidies:Department of Commerce disbursements require domestic content verification, accelerating qualification timelines for US-manufactured photoresist ancillaries in developers and edge-bead removers.
- Node Migration Below 3nm:Advanced logic foundries in Texas and Arizona are consuming EUV resist volumes at multiples of previous DUV generations as patterning complexity compounds.
Market Restraints
- Fluorinated Feedstock Constraints:EPA restrictions on PFAS discharge are forcing reformulation of topcoat chemistries, extending R&D cycles and raising qualification costs for resist stack suppliers.
- Monoclonal Supply Concentration:Japanese resin and PAG suppliers control critical polymer backbones, exposing US formulators to currency and logistics risk on imported raw materials.
- EUV Throughput Limitations:Source power constraints on ASML scanners cap wafer-per-hour economics, dampening resist consumption velocity relative to installed capacity plans.
Strategic Opportunities
- Underpenetrated MEMS Photonics:Silicon photonics fabs in Colorado and Massachusetts are adopting thick-film i-line resists for waveguide patterning, opening volume demand outside leading-edge logic.
- Domestic Ancillary Production:Texas and Arizona chemical infrastructure investments are enabling onshore formulation of developers, thinners, and removers previously imported from Asian suppliers.
- NIST Metrology Alignment:Federal calibration standard development for EUV mask inspection is creating procurement preference for resist platforms validated against NIST reference materials.
Industry Challenges
- EUV Chemist Talent Scarcity:Photoresist formulation expertise concentrates in Japan and Korea, forcing US employers to relocate senior polymer scientists or accept extended training timelines.
- Cleanroom Capital Intensity:Sub-10nm resist qualification requires Class 1 fab access, limiting testing capacity to a handful of federally subsidized pilot lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Photoresist and Photoresist Ancillaries Market |
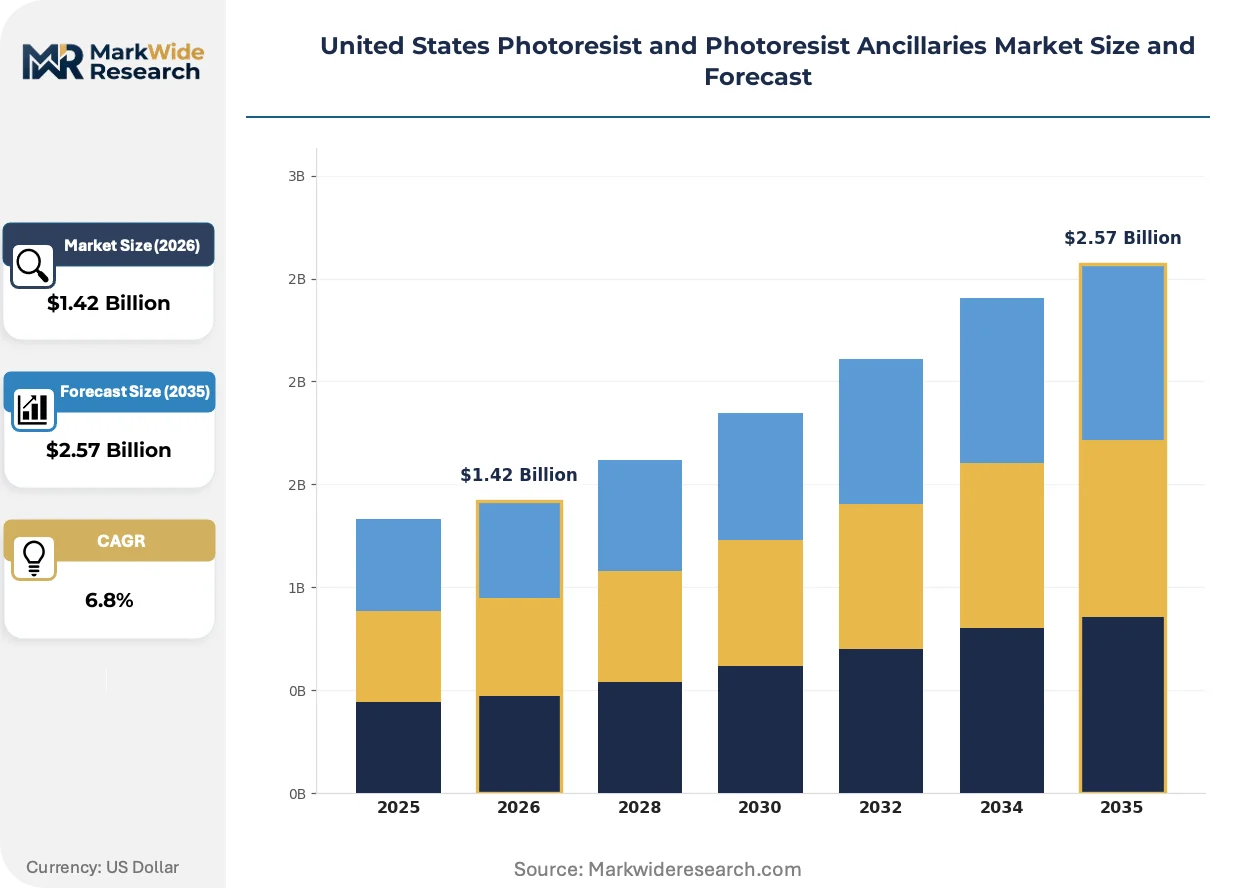
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: G-Line, I-Line, Deep UV, Extreme UV Application: Semiconductor Manufacturing, MEMS, Display Fabrication, Photovoltaics End User: Foundries, IDM, OSAT, R&D Centers Formulation Type: Positive Resist, Negative Resist, Ancillary Materials, Solutions |
| Companies Covered | DuPont de Nemours, JSR Corporation, Tokyo Ohka Kogyo, Shin-Etsu Chemical, FUJIFILM Corporation, Sumitomo Chemical, Allresist, Merck Group, DJ MicroLaminates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Photoresist and Photoresist Ancillaries Market Strategic Shifts & Innovations
EUV lithography is compressing development cycles across the resist stack while environmental regulations force molecular redesign of legacy fluorinated chemistries.
Metal oxide resists are virtualizing patterning resolution by incorporating tin-oxide nanoparticles that absorb 13.5nm wavelength more efficiently than organic polymers. Intel's Portland development fab is qualifying these platforms for 2nm-class nodes ahead of 2025 high-NA production ramps. This virtualization is collapsing the traditional trade-off between line-edge roughness and photospeed that constrained chemically amplified organic resists.
EPA enforcement of PFAS discharge limits under the Clean Water Act is forcing elimination of fluorinated topcoats and surfactants from resist formulations. Semiconductor facilities in Arizona and Texas face NPDES permit modifications requiring zero liquid discharge for fluorinated process chemistries. Formulators are responding with hydrocarbon-based alternatives that sacrifice some receding contact angle performance for regulatory compliance.
Consolidated procurement contracts are compressing supplier margins as CHIPS Act recipients negotiate multi-year resist and ancillary bundles to satisfy domestic content reporting requirements. OSAT facilities in California and Oregon are migrating from spot purchasing to sole-source agreements with volume commitments and technical service embeds. This concentration is most visible among mid-size analog and power semiconductor fabs seeking to streamline supply base management.
United States Photoresist and Photoresist Ancillaries Market Segmentation
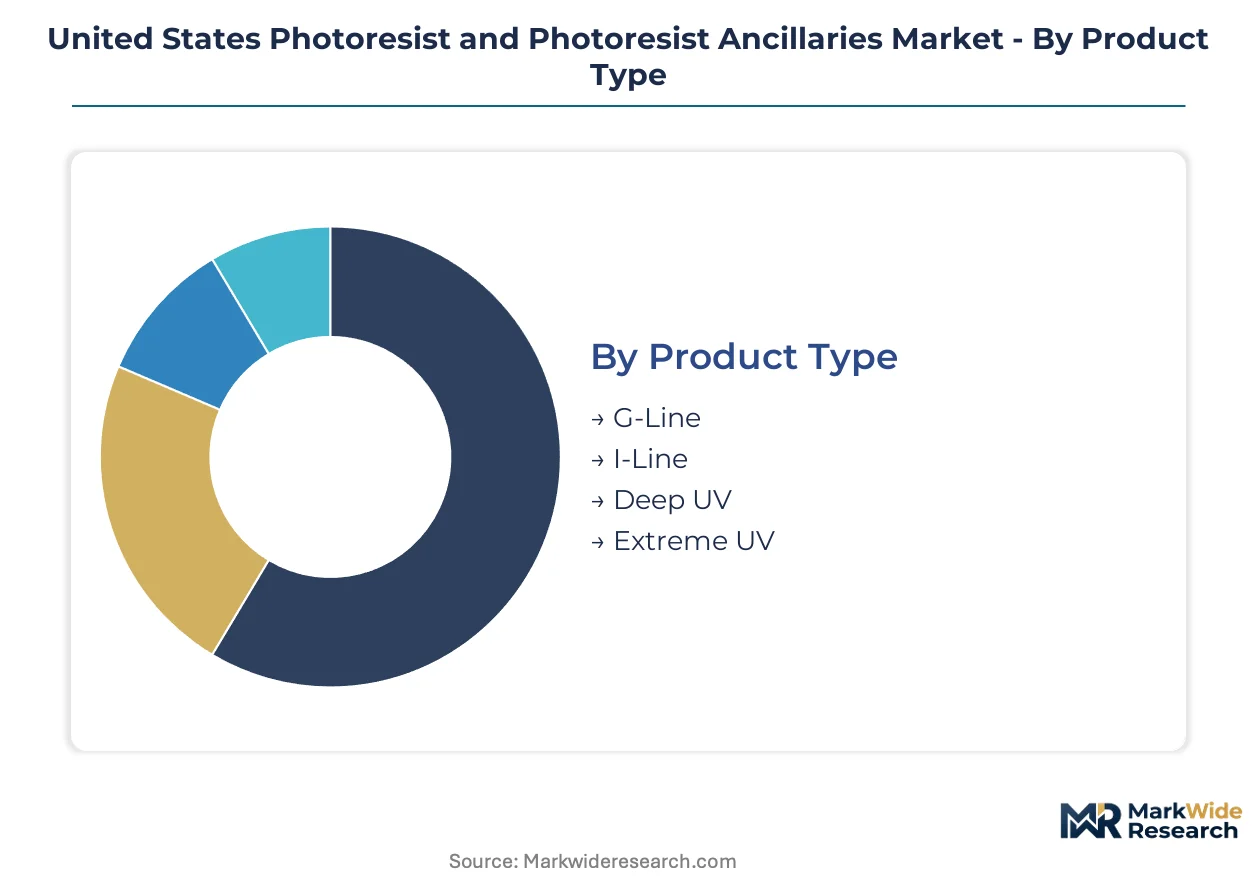
Photoresist segmentation reveals distinct consumption velocities across wavelength generations and end-use categories. Cycle-time compression at advanced nodes creates divergent inventory profiles between legacy and leading-edge formulations.
Product Type:
G-Line formulations turn inventory slowest while EUV resists rotate fastest due to qualification volatility and node migration pressures.
- G-Line:Mercury vapor lamp formulations at 436nm wavelength serve mature analog and power semiconductor fabs with minimal reformulation cycles. Arizona and Texas legacy fabs consume steady volumes for discrete device patterning where resolution requirements plateau below 500nm.
- I-Line:365nm wavelength chemistry dominates MEMS and power semiconductor applications requiring thicker film builds. Colorado silicon photonics fabs are absorbing elevated I-line volumes for waveguide structures that demand aspect ratios exceeding chemically amplified alternatives.
- Deep UV:248nm and 193nm formulations anchor mature logic and memory production at nodes above 7nm.
- Extreme UV:13.5nm wavelength platforms command concentrated development resources as Intel and TSMC Arizona facilities scale high-NA qualification.
Deep UV anchors the volume base while Extreme UV gains share at the steepest rate.
Application:
Margin profiles diverge sharply between commodity display coating and precision semiconductor patterning.
- Semiconductor Manufacturing:Logic and memory fabs consume the highest-purity resist grades with sub-ppt metallic contamination specifications. Texas and Arizona foundry expansions under CHIPS Act disbursements are concentrating demand for 193nm immersion and EUV platforms.
- MEMS:Microelectromechanical systems require thicker resist films with enhanced mechanical stability for deep silicon etch masking. Massachusetts and Colorado facilities are adopting specialized i-line formulations for accelerometer and gyroscope fabrication.
- Display Fabrication:Large-area coating applications prioritize cost efficiency over resolution limits.
- Photovoltaics:Solar cell metallization patterning consumes lower-grade resist with relaxed particulate specifications.
Semiconductor Manufacturing commands the premium tier while MEMS offers the most durable margin stability.
End User:
Procurement sophistication separates capital-intensive foundries from price-sensitive assembly operations.
- Foundries:Pure-play wafer fabrication facilities negotiate multi-year resist bundles with technical service embeds and volume commitments. TSMC Arizona and Intel's expanding domestic footprint are consolidating supplier relationships to satisfy CHIPS Act domestic content verification.
- IDM:Integrated device manufacturers maintain captive formulation expertise for proprietary process nodes. Texas Instruments and Analog Devices operate established supply chains with backward integration into resist specification development.
- OSAT:Outsourced semiconductor assembly and test facilities face compressed margins on legacy packaging resist consumption.
- R&D Centers:NIST and DOE national laboratories drive qualification protocols for next-generation EUV platforms.
Foundries concentrate procurement volume while R&D Centers determine future qualification standards.
Formulation Type:
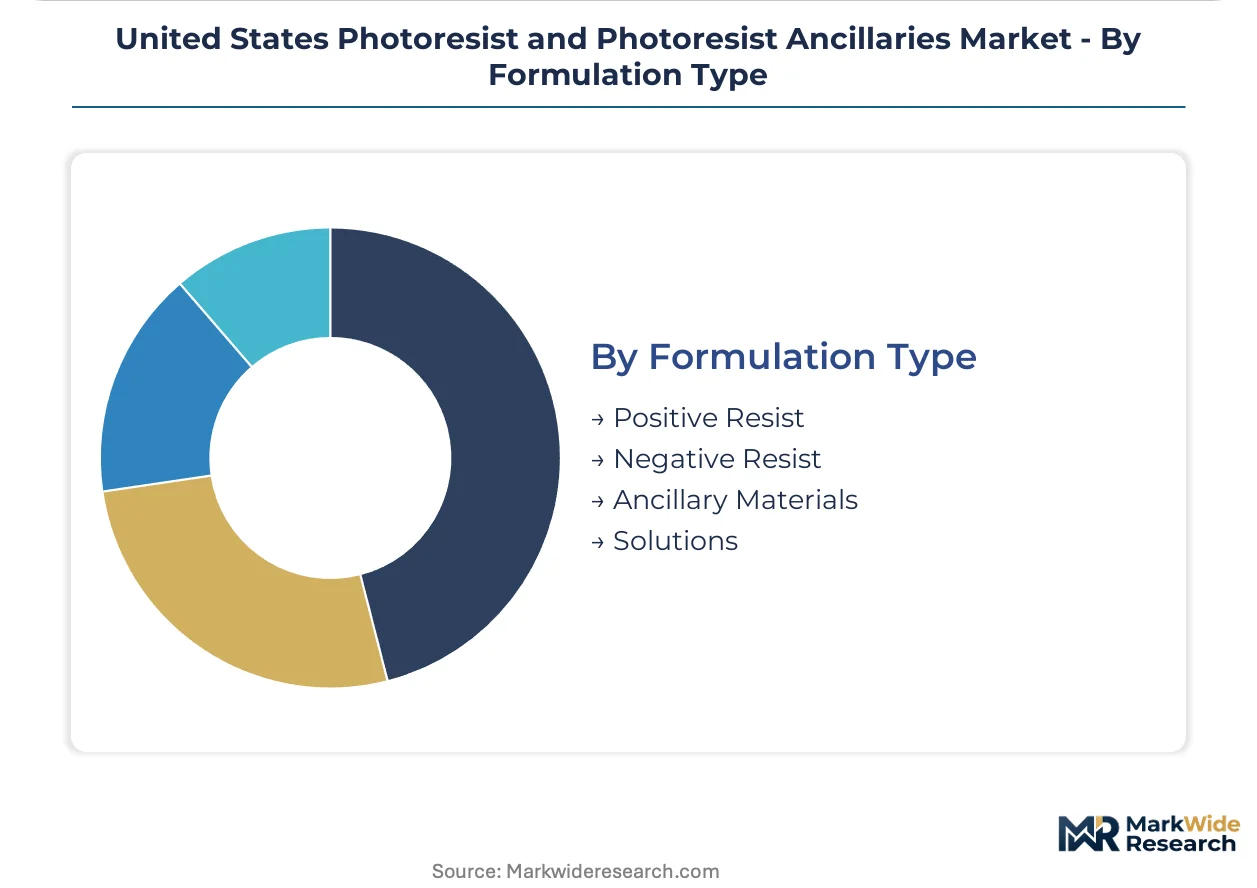
Positive-tone chemistry dominates commercial volumes but negative-tone platforms are penetrating specific patterning applications.
- Positive Resist:Photoacid-catalyzed deprotection mechanisms enable sub-20nm resolution in chemically amplified platforms. Arizona foundries are consuming positive-tone EUV resists at accelerating rates as high-NA exposure systems enter pilot production.
- Negative Resist:Crosslinking chemistry suits applications requiring solvent resistance and mechanical durability. MEMS fabs in Massachusetts are qualifying negative-tone formulations for deep reactive ion etch masking where positive alternatives suffer adhesion failures.
- Ancillary Materials:Developers, removers, and edge-bead cleaners complete the process stack.
- Solutions:Pre-mixed resist formulations reduce on-site blending complexity for smaller fabrication facilities.
Positive Resist supplies the dominant volume pool while Negative Resist expands fastest in specialty MEMS applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese photoresist exports supply Arizona and Texas foundries through established Pacific trade corridors, while domestic formulation capacity expands under federal subsidy programs. Regional demand concentrates in semiconductor manufacturing clusters where CHIPS Act disbursements accelerate facility construction.
Arizona
TSMC's Phoenix megafab and Intel's Chandler expansion drive EUV resist consumption at volumes exceeding previous DUV generations. EPA NPDES permit modifications enforce zero liquid discharge for fluorinated process chemistries, forcing reformulation of legacy topcoat layers. The Phoenix-Tucson corridor anchors domestic high-NA qualification activity as ASML scanner installations proceed.
Texas
Samsung Austin and Texas Instruments Sherman facilities expand 193nm immersion and EUV resist procurement under domestic content verification requirements. Department of Commerce CHIPS Act funding conditions preferential sourcing from US-based formulators. The Austin-Dallas-Fort Worth triangle concentrates resist ancillary production investments in developers and edge-bead removers.
California
Applied Materials and Lam Research headquarters sustain R&D demand for next-generation resist platforms, while OSAT facilities in San Jose migrate to sole-source procurement agreements. FDA and OSHA frameworks govern worker exposure limits during resist coating operations in less automated packaging facilities. Silicon Valley maintains qualification protocol development through NIST-aligned metrology partnerships.
Massachusetts
Silicon photonics fabs in Greater Boston adopt thick-film i-line resists for waveguide patterning, opening volume demand outside leading-edge logic. State-level clean energy incentives complement federal subsidies for domestic chemical infrastructure. The Route 128 corridor hosts specialized MEMS resist qualification for accelerometer and gyroscope fabrication.
Oregon
Intel Hillsboro anchors Pacific Northwest resist consumption through development fab access for sub-10nm qualification. OSHA enforcement targets worker exposure protocols in coating and stripping operations across OSAT facilities. The Portland metro area sustains metal oxide resist validation programs ahead of high-NA production ramps.
United States Photoresist and Photoresist Ancillaries Market Key Industry Players
Channel-controlling players compete with product-specialist players across formulation tiers, creating a concentrated structure where polymer science heritage anchors premium positioning. Japanese suppliers dominate resin and photoacid generator backbones, forcing US formulators into qualification partnerships or captive raw material strategies. Three archetypes populate the landscape: integrated chemical conglomerates with resist divisions, specialized photoresist pure-plays, and ancillary-focused process chemical suppliers. Competitive moves center on multi-year procurement bundles with technical service embeds, and domestic formulation investments to satisfy CHIPS Act domestic content verification.
Among the integrated chemical conglomerates, DuPont de Nemours and Merck Group occupy positions anchored in polymer science capabilities, while JSR Corporation exemplifies the specialized photoresist pure-play archetype with concentrated EUV platform development. Tokyo Ohka Kogyo represents the ancillary-focused supplier model, extending formulation expertise into developers and removers that complete the process stack. These three patterns illustrate how competitive positioning derives from historical capability accumulation rather than recent market entry.
| Leading Market Players |
|---|
| DuPont de Nemours |
| JSR Corporation |
| Tokyo Ohka Kogyo |
| Shin-Etsu Chemical |
| FUJIFILM Corporation |
| Sumitomo Chemical |
| Allresist |
| Merck Group |
| DJ MicroLaminates |
| Others |
Cost & Logistics Intelligence
Japanese resin and photoacid generator concentration determines both pricing tier spreads and supply chain shape for US formulators. EPA restrictions on PFAS discharge create regulatory chokepoints that compress margins on legacy fluorinated topcoat formulations while accelerating qualification premiums for compliant alternatives.
Pricing Analysis
EUV-to-DUV pricing gaps exceed ten-to-one on a per-liter basis as high-NA qualification demands concentrate procurement among three qualified suppliers. Three-tier pricing structure across EUV premium, DUV standard, and G-line economy levels reflects contamination specification differentials and volume scale. Cost compression in DUV immersion tiers is intensifying because foundries are consolidating procurement bundles under CHIPS Act domestic content verification. OSAT facilities in California exhibit the highest price sensitivity, while Intel and TSMC Arizona fabs prioritize technical service embeds over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese resin suppliers stretch working capital for US formulators, forcing supply-chain finance facilities to bridge raw material procurement cycles. Geographic supply concentration centers on Japan for polymer backbones and photoacid generators, South Korea for specialty solvents, and domestic Texas-Arizona chemical infrastructure for formulation and blending. Raw material dependencies draw from fluorinated feedstocks facing EPA discharge restrictions, tin-oxide nanoparticles for metal oxide resist platforms, and hydrocarbon-based surfactant replacements. Single-source vulnerability runs through Shin-Etsu Chemical's controlled oligomer supply for chemically amplified resists. Distribution runs through direct foundry contracts with technical service embeds, bypassing traditional chemical distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against metal oxide resist platforms that threaten to displace organic polymer formulations at sub-3nm nodes. Incumbents must navigate the virtualization of patterning resolution that collapses traditional chemically amplified resist economics.
For Market Incumbents: Harden formulation portfolios through backward integration into photoacid generator production, capturing margin pools currently extracted by Japanese suppliers. Anchor positions in NIST-aligned EUV metrology standards to create procurement preference lock-in for CHIPS Act-linked foundry contracts. Defensive patent filings around hydrocarbon-based topcoat alternatives neutralize EPA-driven reformulation threats from specialty chemical entrants.
For New Entrants and Emerging Players: Build out MEMS photonics capabilities in Colorado and Massachusetts, where thick-film i-line demand for silicon waveguides remains underserved by leading-edge focused incumbents. Target ancillary material production—developers, removers, and edge-bead cleaners—where domestic qualification timelines are shorter than EUV resist platforms. Go-to-market leverage rests on sole-source procurement agreements with mid-size analog fabs seeking supply base simplification.
For Investors and Strategic Acquirers: The market sits at a qualification consolidation phase that favors ancillary-focused process chemical suppliers with established foundry technical service relationships. Long-term viability over the next decade hinges on exposure to domestic formulation capacity rather than raw material trading positions. Acquisition targets should exhibit captive blending infrastructure in Texas or Arizona with CHIPS Act subsidy-linked volume commitments. The signal to watch is NIST calibration standard adoption rates, which determine which resist platforms qualify for federal procurement preference.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Formulation Capacity Expansion | Texas and Arizona chemical infrastructure investments satisfy CHIPS Act domestic content verification requirements for foundry procurement. |
| Backward Integration into PAG Production | Captive photoacid generator supply reduces Japanese resin supplier dependency and currency exposure for US formulators. |
| Metal Oxide Resist Platform Development | Intel's Portland validation programs for tin-oxide nanoparticle formulations threaten organic resist economics at 2nm-class nodes. |
| PFAS-Free Topcoat Reformulation | EPA NPDES permit modifications in Arizona enforce zero liquid discharge, forcing molecular redesign of fluorinated chemistries. |
| NIST Metrology Alignment Partnership | Federal calibration standard development creates procurement preference for resist platforms validated against NIST reference materials. |
Research Approach
Operator-level perspectives from fab process engineers, resist formulation chemists, foundry procurement directors, and EPA compliance officers anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, Department of Commerce CHIPS Act disbursement records, EPA NPDES permit databases, and ASML scanner installation disclosures. Bottom-up resist consumption modeling triangulated against top-down foundry capacity expansion announcements.
Scenario-bracketing around high-NA EUV deployment timelines and PFAS regulatory enforcement stringency shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include wavelength generation, application category, end-user procurement sophistication, and formulation chemistry type. CAGRs derived from installed scanner capacity projections, node migration velocity assumptions, and resist consumption intensity per wafer layer. Industry-specific forecast inputs incorporated CHIPS Act funding disbursement schedules and NIST metrology standard development timelines.
Practitioners should monitor EPA enforcement actions on fluorinated discharge permits and ASML high-NA scanner delivery schedules for early signals of demand inflection. Forecasts reflect assumptions on domestic qualification timelines, Japanese supplier pricing discipline, and foundry yield ramp trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Semiconductor Bonding Machine Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Semiconductor Polishing Pads Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Solder Paste Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
EUV Lithography Service Market
Semiconductor Manufacturing
Chip Melting Furnace Market
Semiconductor Manufacturing
Photomask Market
Semiconductor Manufacturing
Middle East and Africa Cell Manufacturing Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market