
 Thermal Conductive Polymer Materials Market | 2026-2036
Thermal Conductive Polymer Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Conductive Polymer Materials Market Intelligence
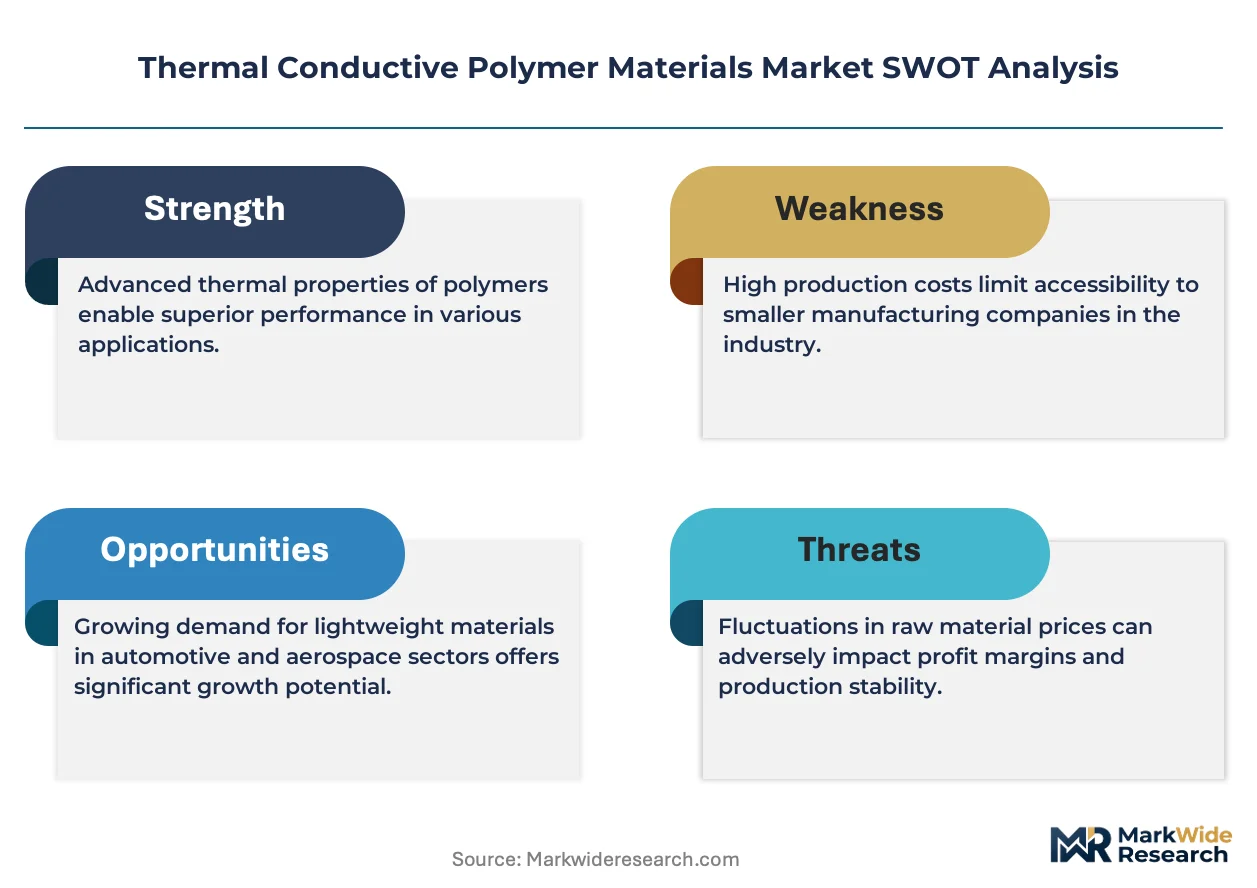
High-thermal-conductivity grades above 5 W/m·K is reorganizing supplier hierarchies as OEMs tighten thermal management specifications for power electronics. BASF SE leverages its ultramid polyamide portfolio to anchor European automotive supply chains with halogen-free formulations. Covestro AG competes through polycarbonate-based solutions optimized for LED luminaire housings, while RTP Company specializes in custom-compounded masterbatches that extend design flexibility for mid-tier processors.
Thermal conductive polymer materials are engineered resin systems loaded with ceramic or metallic fillers to achieve thermal conductivities typically between 1 and 20 W/m·K, replacing metal heat spreaders in weight-sensitive assemblies. Their primary purpose is to dissipate heat from concentrated electronic sources while maintaining electrical isolation and injection-molding processability. Conductive thermoplastics dominate volume flows due to recyclability alignment with automotive circularity mandates, whereas composites command margin pools in aerospace radome and satellite applications where outgassing limits constrain metal alternatives. Films are gaining traction in flexible consumer electronics as foldable display architectures proliferate.
The EPA regulates flame retardancy thresholds under TSCA Section 6 for electronics enclosures, while the EU RoHS directive restricts hazardous substances in polymer additives used for thermal interface materials. China's GB standards for electronic product safety, administered by SAMR, mandate thermal stability testing that shapes formulation choices for export-oriented compounders. Stakeholders must monitor how REACH candidate list expansions affect boron nitride and aluminum oxide filler classifications, as substitution costs could restructure raw material sourcing within the next regulatory cycle.
Market Dynamics
The EU F-Gas Regulation phase-down of hydrofluorocarbons is redirecting capital toward polymer-based passive cooling architectures, compressing timelines for thermal management system redesigns across automotive and electronics supply chains.
Growth Catalysts
- Electric vehicle thermal management:Battery pack manufacturers are accelerating procurement of thermally conductive thermoplastics to replace metal heat spreaders in weight-constrained pack designs.
- REACH candidate list expansions:Boron nitride filler classifications are tightening, forcing compounders toward halogen-free polyamide formulations that command specification premiums.
- Stuttgart-Munich corridor concentration:Germany's automotive supplier ecosystem is consolidating procurement around qualified polymer compounders with certified automotive quality systems.
Market Restraints
- Ceramic filler cost volatility:Aluminum oxide and boron nitride prices fluctuate with energy-intensive production economics, squeezing compounder margins on fixed-price OEM contracts.
- High-performance grade supply concentration:Thermal conductivity above 5 W/m·K depends on specialized compounding capabilities concentrated among European and Japanese suppliers.
- Metal heat sink substitution threat:Aluminum extrusion cost reductions in China retain cost advantage for non-weight-sensitive electronics enclosures.
Strategic Opportunities
- Foldable display architectures:Flexible thermal conductive films are penetrating consumer electronics as foldable smartphone and tablet form factors proliferate.
- Aerospace radome applications:Outgassing-compliant thermally conductive composites are displacing metal alternatives in satellite thermal control systems.
- EU Green Deal circularity mandates:Recyclable thermoplastic formulations align with automotive end-of-life directives, creating specification advantages over thermoset alternatives.
Industry Challenges
- Thermal-mechanical modeling expertise:Filler orientation simulation and anisotropic conductivity prediction require specialized CAE capabilities scarce among mid-tier processors.
- Automotive qualification timelines:PPAP cycles and thermal cycling validation protocols extend 18-24 months, compressing returns on R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Conductive Polymer Materials Market |
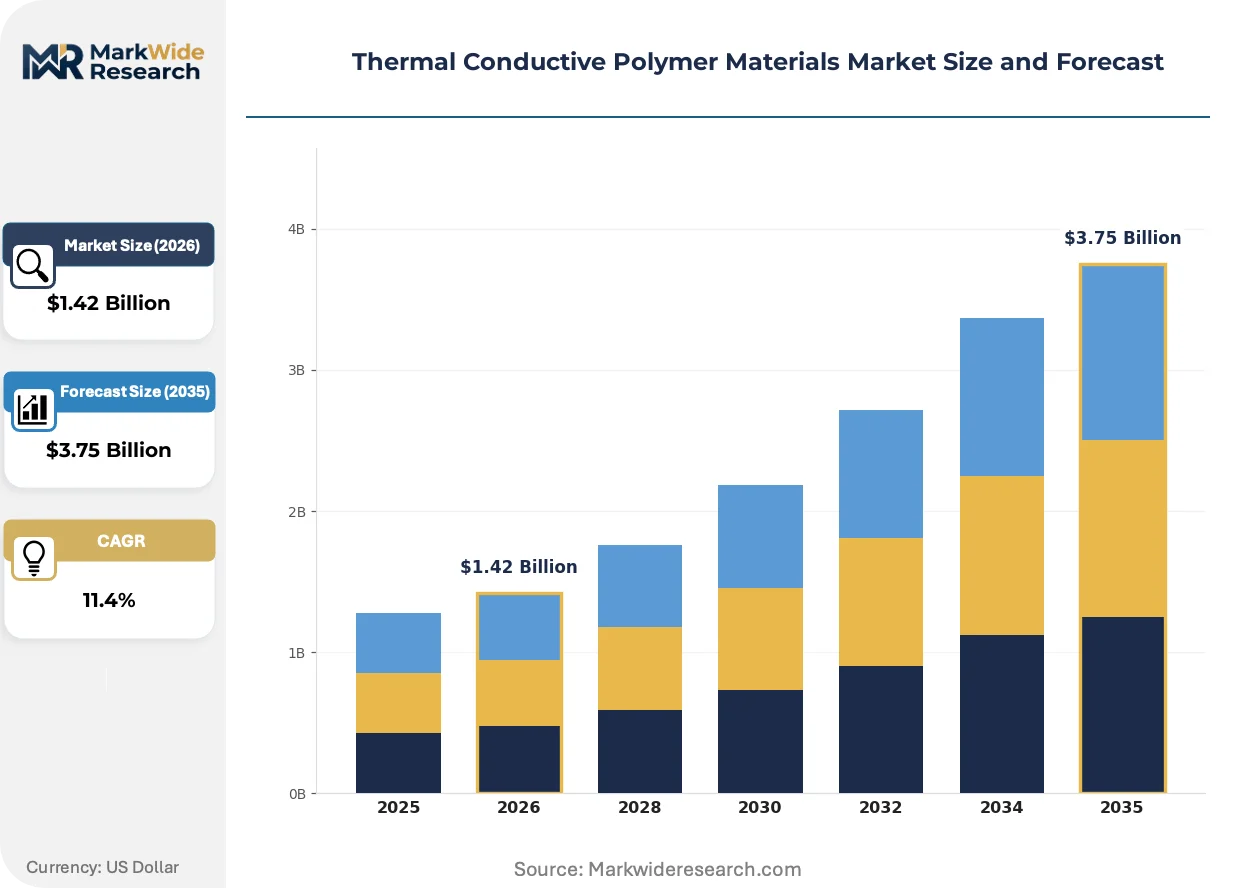
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conductive Thermoplastics, Thermosetting Polymers, Composites, Films End User: Electronics, Automotive, Aerospace, Industrial Equipment Application: Heat Sinks, Thermal Interface Materials, LED Lighting, Consumer Electronics Form: Powder, Sheet, Coating, Masterbatch |
| Companies Covered | Celanese Corporation, RTP Company, SABIC, Covestro AG, BASF SE, PolyOne Corporation, Royal DSM, Mitsubishi Engineering-Plastics Corporation, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Conductive Polymer Materials Market Strategic Shifts & Innovations
Formulation science and regulatory chemistry are converging to redefine material specifications across automotive, electronics, and aerospace end-uses. Three developments are restructuring competitive positioning.
Boron nitride-filled polyamide compounds are displacing aluminum heat spreaders in LED luminaire housings and power electronics modules. Lighting OEMs and EV inverter manufacturers are specifying these grades for weight reduction and electrical isolation. The shift is compressing metal stamping demand while expanding injection molding capacity requirements for thermal-grade resins.
REACH candidate list expansions are tightening controls on boron nitride and aluminum oxide filler classifications. Compounders face substitution costs that restructure raw material sourcing toward synthetic graphite and carbon-based alternatives. Electronics enclosure suppliers in Germany and France are reformulating ahead of regulatory deadlines to maintain CE marking compliance.
Automotive procurement teams are consolidating supplier panels around compounders with integrated material characterization and thermal simulation capabilities. Tier-1 thermal management suppliers are bypassing distributors to contract directly with BASF, Covestro, and RTP Company for custom masterbatch development. This channel compression is most visible in Germany's automotive supplier corridor, where qualified compounder status determines specification access.
Thermal Conductive Polymer Materials Market Segmentation
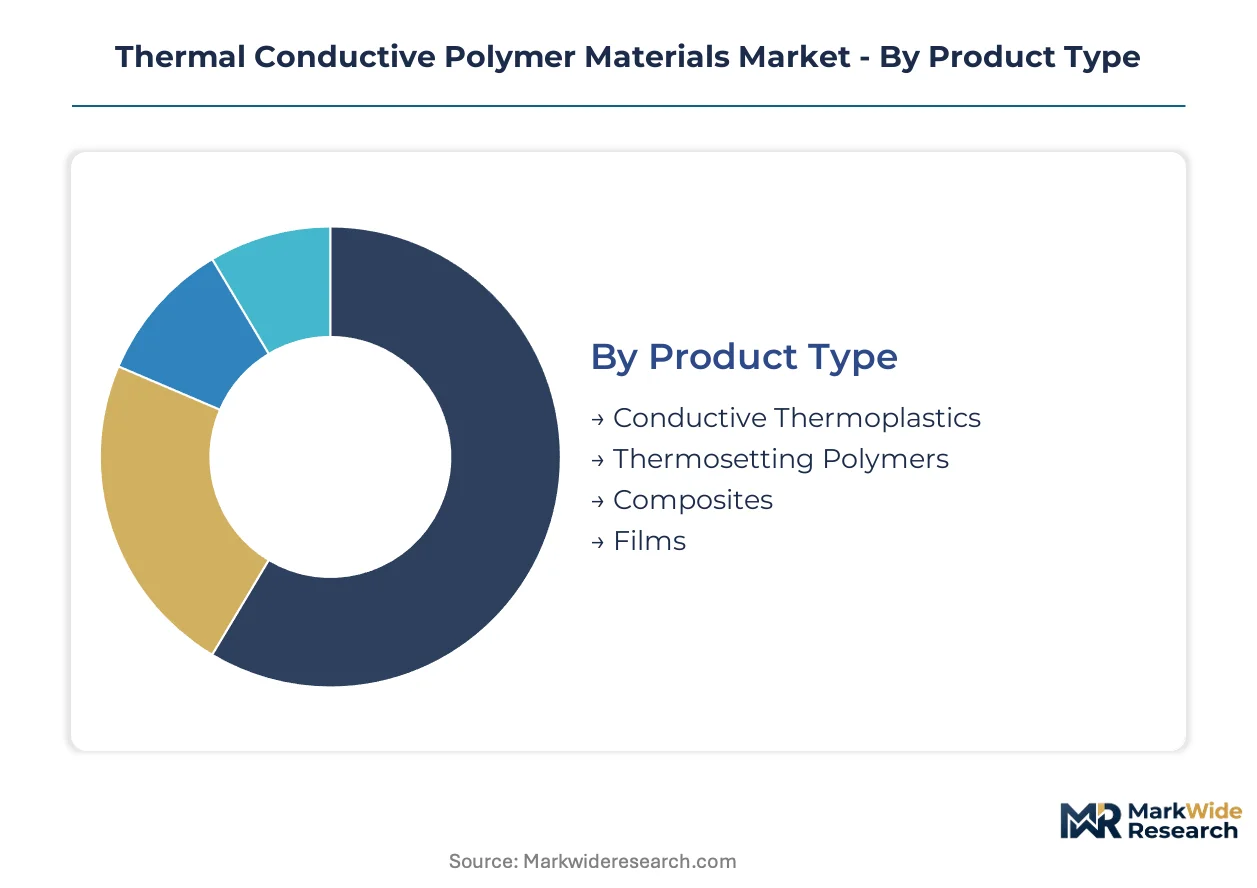
Material form and thermal conductivity specifications determine substitution economics against metal heat spreaders. Procurement teams segment suppliers by filler loading capabilities and automotive qualification status rather than resin chemistry alone.
Product Type:
Substitution pressure from aluminum extrusion cost reductions in China hits powder and sheet forms hardest, while injection-moldable grades defend position through design integration.
- Conductive Thermoplastics:Ceramic-filled polyamide and polycarbonate compounds achieve 1-10 W/m·K thermal conductivity while maintaining recyclability. Battery pack manufacturers in Germany's Stuttgart-Munich corridor specify these grades for weight-constrained module housings under EU automotive circularity mandates.
- Thermosetting Polymers:Epoxy and silicone-based systems loaded with boron nitride or aluminum oxide serve high-temperature applications exceeding thermoplastic limits. Aerospace radome and satellite thermal control applications favor these grades for outgassing compliance, though REACH candidate list expansions threaten filler availability.
- Composites:Continuous fiber-reinforced systems command aerospace margins where metal alternatives fail outgassing protocols.
- Films:Flexible substrates penetrate foldable display architectures as thermal management layers in consumer electronics.
Conductive thermoplastics retain volume leadership; films hold the steepest expansion curve.
End User:
Application margins cluster where thermal-mechanical modeling expertise creates specification barriers to entry.
- Electronics:Power electronics modules and LED luminaire housings drive demand for 5+ W/m·K grades with electrical isolation. EPA TSCA Section 6 flame retardancy thresholds and EU RoHS hazardous substance restrictions shape formulation choices for enclosure suppliers.
- Automotive:EV inverter and battery pack thermal management systems accelerate procurement of halogen-free polyamide formulations. Tier-1 suppliers contract directly with compounders holding certified automotive quality systems, compressing distributor channels.
- Aerospace:Satellite thermal control systems specify outgassing-compliant composites displacing metal alternatives.
- Industrial Equipment:Motor housing and power supply applications balance cost against thermal performance in non-weight-sensitive designs.
Automotive commands specification premiums; aerospace maintains the highest margin pool.
Application:
Functional requirements separate injection-moldable housing opportunities from interface material commodity pressures.
- Heat Sinks:Polymer replacements for aluminum extrusions concentrate in weight-sensitive LED luminaire and automotive electronics housings. Boron nitride-filled compounds displace metal stamping where electrical isolation adds value.
- Thermal Interface Materials:Gap-filling pads and phase-change materials compete on thermal resistance metrics against silicone greases and graphite sheets.
- LED Lighting:Luminaire manufacturers specify thermally conductive housings integrating heat dissipation with electrical isolation.
- Consumer Electronics:Foldable smartphones and tablets drive flexible film penetration as form factors evolve.
Heat sinks anchor revenue concentration; consumer electronics generates the most volatile demand swings.
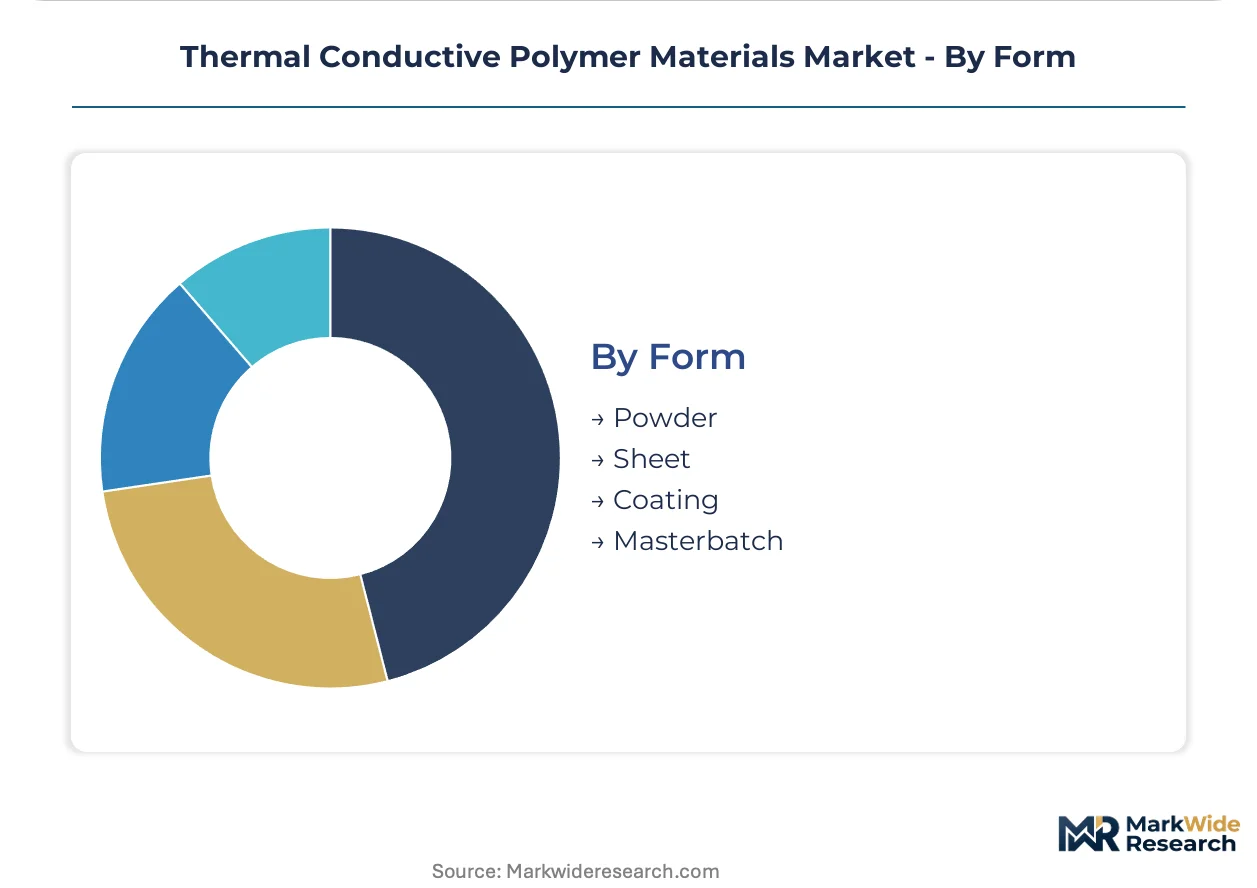
Form:
Processing method determines compounder capabilities required and customer technical support intensity.
- Powder:Spray-applied coatings and compression molding feedstocks serve industrial equipment and specialty aerospace applications with limited volume scale.
- Sheet:Thermoformed and die-cut shapes target LED lighting reflectors and industrial housings competing with aluminum sheet metal.
- Coating:Dispensed thermal interface layers and conformal coatings address electronics assembly integration challenges.
- Masterbatch:Custom-compounded concentrates enable mid-tier processors to achieve thermal conductivity without captive compounding investment. RTP Company specializes in this segment, extending design flexibility for processors lacking specialized CAE capabilities.
Masterbatch captures processor outsourcing trends; powder remains the most constrained by application scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compounding capabilities cluster among German, Japanese, and US suppliers with certified automotive quality systems. Tier-1 procurement teams consolidate supplier panels around compounders with integrated thermal simulation and material characterization expertise.
Germany
EV battery pack manufacturers in the Stuttgart-Munich corridor accelerate procurement of halogen-free polyamide formulations. The EU F-Gas Regulation phase-down redirects investment toward polymer-based passive cooling solutions. BASF SE anchors European supply chains with ultramid polyamide portfolios from Ludwigshafen.
United States
Power electronics and LED luminaire OEMs specify 5+ W/m·K grades with electrical isolation for thermal management. EPA TSCA Section 6 regulates flame retardancy thresholds for electronics enclosures. RTP Company specializes in custom-compounded masterbatches from Winona, Minnesota, extending design flexibility for mid-tier processors lacking captive compounding.
Japan
Automotive and electronics manufacturers drive demand for high-thermal-conductivity grades above 5 W/m·K. METI oversees industrial standards alignment with international thermal stability protocols. Mitsubishi Engineering-Plastics Corporation and Toray Industries occupy positions among specialized compounders serving precision electronics applications.
China
Domestic EV production scales procurement of thermally conductive thermoplastics for battery module housings. SAMR-administered GB standards mandate thermal stability testing for export-oriented compounders. Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate injection molding capacity for consumer electronics thermal solutions.
South Korea
Display panel and semiconductor packaging manufacturers integrate flexible thermal conductive films into foldable device architectures. MFDS oversees material safety standards for electronics applications. Seoul Capital Area compounders serve Samsung and LG supply chains with customized boron nitride-filled formulations.
Thermal Conductive Polymer Materials Market Key Industry Players
Concentration sits with diversified chemical conglomerates and specialized compounders serving automotive qualification requirements. The supplier base organizes around three strategic archetypes: resin producers with captive compounding capabilities, independent custom compounders, and regional processors dependent on masterbatch sourcing. Dominant competitive moves include direct contracting with tier-1 thermal management suppliers and integrated material characterization service offerings.
Within the diversified chemical conglomerate tier, BASF SE, Covestro AG, and SABIC exemplify scale-driven positions anchored by captive resin production and automotive quality certifications. RTP Company occupies a specialist position among custom compounders, extending thermal conductivity capabilities to mid-tier processors through masterbatch formats without requiring their compounding investment. Celanese Corporation and Royal DSM represent material science portfolios spanning engineered polymers and thermoplastic compounds.
| Leading Market Players |
|---|
| Celanese Corporation |
| RTP Company |
| SABIC |
| Covestro AG |
| BASF SE |
| PolyOne Corporation |
| Royal DSM |
| Mitsubishi Engineering-Plastics Corporation |
| Toray Industries |
| Others |
Cost & Logistics Intelligence
Specialized compounding capacity utilization above 80 percent at German and Japanese facilities creates scale economies that simultaneously concentrate supply-side pricing power and establish minimum viable price floors for thermal conductivity grades. This capacity tightness feeds directly into procurement negotiations, with automotive OEMs accepting premium positioning for qualified compounders while mid-tier processors face margin compression from masterbatch dependency.
Pricing Analysis
EU REACH candidate list expansions dictate the pricing tier structure across halogen-free polyamide formulations, with certified automotive grades commanding substantial premiums over standard electronics grades. Price differentiation rests on IATF certification status and filler loading precision above 5 W/m·K. Pricing pressure stems from ceramic filler cost volatility squeezing compounder margins on fixed-price OEM contracts. Battery pack manufacturers exhibit lowest price sensitivity due to weight-constrained design mandates, while LED luminaire producers face acute cost pressure from aluminum extrusion alternatives.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compound lead time variability for boron nitride and aluminum oxide feedstocks sourced from Chinese and Japanese producers. Raw material sourcing draws from energy-intensive ceramic production clusters in China, synthetic graphite processing in Japan, and specialty polyamide resin production in Germany. Single-source vulnerability concentrates around high-purity boron nitride suppliers facing REACH regulatory pressure. Distribution runs through direct contracting between tier-1 thermal management suppliers and qualified compounders, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry opportunities as EV battery architectures proliferate distinct thermal management specifications that resist standardization. This demand-side heterogeneity rewards specialized formulation capabilities over commodity scale.
For Market Incumbents: Secure specification lock-in through integrated thermal-mechanical modeling services that embed compounders early in OEM design cycles. Threats from metal heat sink cost reductions in China intensify price competition in non-automotive electronics segments. Priority levers include backward integration into specialty filler processing and capacity expansion in the Stuttgart-Munich corridor to defend automotive qualification status. For New Entrants and Emerging Players: Differentiate on flexible film formulations for foldable display architectures where incumbent compounders lack dedicated production assets. White-space targets include South Korean display panel supply chains and Chinese consumer electronics molding clusters. The most penetrable segment sits in thermal interface material masterbatches for mid-tier processors lacking captive compounding. A direct technical sales model with embedded CAE support accelerates specification adoption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with automotive quality certifications and demonstrated REACH compliance adaptation. Long-term viability hinges on formulation IP portability across evolving regulatory chemistry constraints. Acquisition targets should demonstrate filler orientation simulation capabilities and established relationships with tier-1 thermal management suppliers. The signal to watch is EU F-Gas Regulation enforcement intensity redirecting capital toward polymer-based passive cooling architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Filler Processing | Captive boron nitride sourcing insulates margins from REACH-driven supply disruptions. |
| Automotive Quality Certification Investment | IATF certification unlocks direct contracting with Stuttgart-Munich corridor OEM procurement teams. |
| Integrated Thermal Simulation Service Launch | CAE capabilities embed compounders in early-stage OEM design cycles, creating specification stickiness. |
| Flexible Film Production Capacity Expansion | Dedicated assets for foldable display architectures capture South Korean and Chinese electronics demand. |
| Halogen-Free Formulation R&D Partnership | Collaboration with resin producers accelerates REACH-compliant polyamide grade development ahead of regulatory deadlines. |
Research Approach
Desk research of trade association publications, customs filings, and regulatory databases preceded structured interviews with compounder technical directors, automotive tier-1 procurement managers, thermal management system engineers, and resin producer R&D leads. Primary fieldwork validated secondary estimates of filler loading capabilities and automotive qualification timelines. Bottom-up volume modeling across product types and end-use segments was cross-checked against top-down chemical industry consumption data.
Variance decomposition across the projection horizon isolates volume growth from mix-shift effects and price trajectory assumptions. Segmentation dimensions include material form, thermal conductivity tier, end-use industry, and regional production cluster. CAGR derivation incorporated EV battery pack production forecasts, LED luminaire shipment trends, and aerospace satellite launch schedules. Industry-specific inputs encompass REACH regulatory timeline scenarios and F-Gas Regulation phase-down implementation pace.
The analysis sits within stated boundaries; outcomes outside sustained EV adoption rates, stable ceramic filler supply economics, or unchanged REACH candidate list scope would require recalibration. Forecasts reflect documented assumptions regarding automotive qualification cycle durations and compounder capacity expansion plans. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Carbon Foam Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Global Tank Insulation Market