
 Global Tank Insulation Market | 2026-2036
Global Tank Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tank Insulation Market Foresight
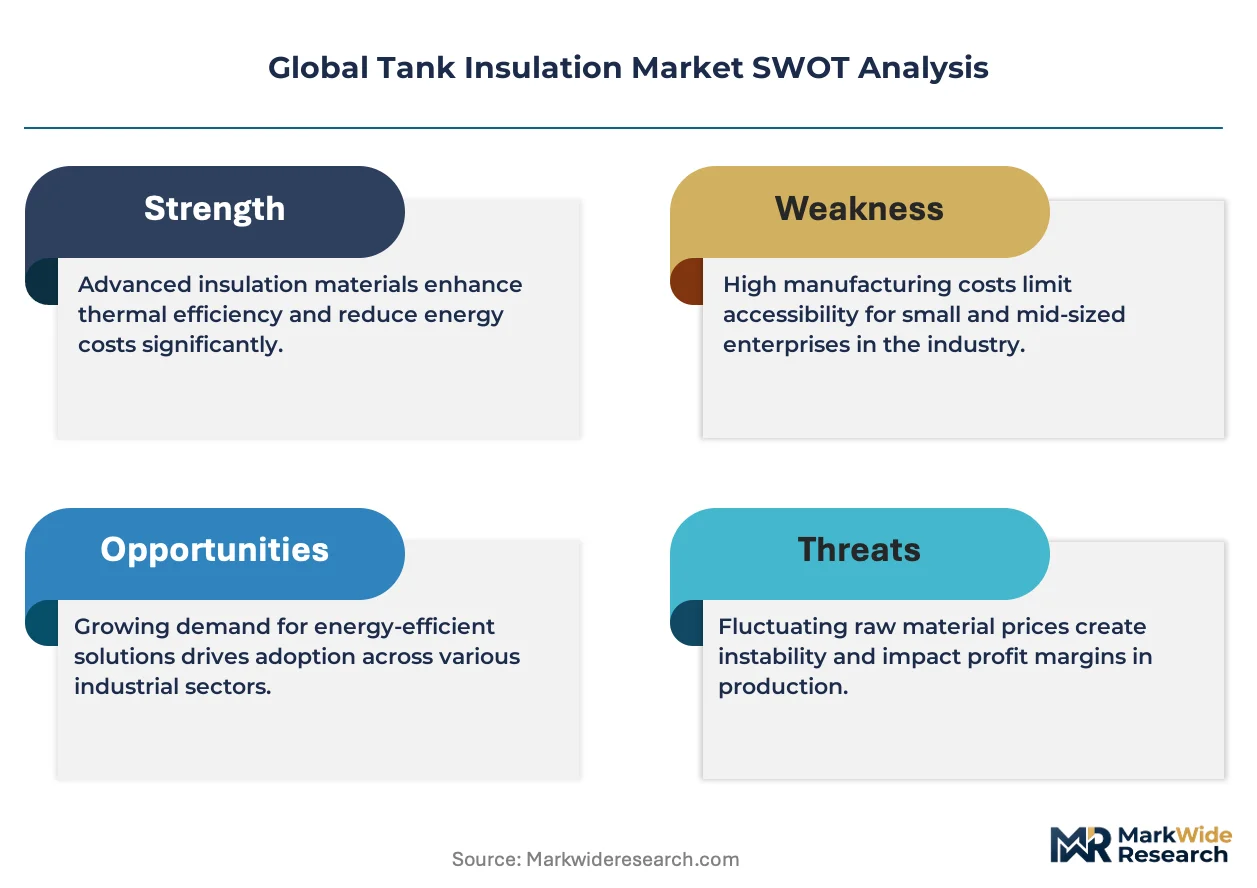
Project finance structures for LNG terminal buildouts is reconfiguring competitive access across the tank insulation supply chain. Owens Corning leverages its glass wool manufacturing scale to dominate cryogenic system contracts in North American energy corridors. Johns Manville anchors its position through mineral wool specialization for petrochemical storage applications with extreme temperature cycling. Rockwool International A/S competes on basalt-based formulations that sustain thermal stability across European chemical manufacturing clusters.
Tank insulation comprises engineered thermal barriers applied to aboveground, underground, horizontal, vertical, and cylindrical vessels to minimize heat transfer and maintain stored media at specified temperatures, typically using polyurethane foam, mineral wool, expanded polystyrene, cellular glass, or aerogel with lambda values ranging from 0.020 to 0.040 W/mK depending on material density and operating conditions. Its primary industrial purpose spans petrochemical storage, liquefied gas containment, water tanks, cryogenic systems, and chemical storage where thermal bridging risks product degradation, energy loss, or hazardous phase changes. Aerogel segments command premium positioning due to superinsulation performance in LNG containment, while mineral wool occupies volume leadership across energy and power plant retrofits where fire resistance ratings govern specification. Polyurethane foam extends fastest in water treatment and food and beverage processing where moisture resistance and lightweight installation reduce structural load requirements.
EPA standards for volatile organic compound emissions from storage vessels, EU F-Gas Regulation phase-down schedules for high-global-warming-potential blowing agents, and API thermal insulation specifications collectively tighten material compliance burdens and specification complexity for insulation contractors. ISO thermal conductivity testing protocols and ASTM fire performance classifications further segment supplier qualification tiers across pharmaceutical and chemical manufacturing end users. Stakeholders must monitor evolving building code adoptions for cryogenic facilities and assess backward integration into blowing agent chemistry as regulatory chemistry restrictions compress formulation options.
Market Dynamics
LNG infrastructure buildouts across the United States, Qatar, and Australia are compressing specification cycles for cryogenic insulation systems as terminal operators race to lock in thermal performance guarantees before construction deadlines.
Growth Catalysts
- EU F-Gas Regulation phase-down:The mandated reduction in high-global-warming-potential blowing agents is accelerating reformulation investment toward low-lambda polyurethane systems for aboveground storage.
- Australian LNG export corridor expansion:Energy transition capital is concentrating in Queensland and Western Australia, pulling cryogenic insulation demand into concentrated procurement windows.
- Cellular glass material advancement:Improved compressive strength in cellular glass is penetrating hydrocarbon storage applications where thermal cycling resistance governs specification.
Market Restraints
- Polyol feedstock volatility:Propylene oxide price swings are compressing margin predictability for polyurethane foam contractors serving petrochemical terminals.
- Basalt fiber supply concentration:Rockwool International A/S and limited European suppliers control high-purity basalt sourcing, creating bottleneck risk for mineral wool system availability.
- Cryogenic thermal bridging:Penetration details and support structure interfaces remain unresolved engineering constraints in large-diameter LNG tank construction.
Strategic Opportunities
- India LNG import terminal buildout:Underpenetrated demand for full-containment tanks at Dahej and Hazira is opening specification windows for aerogel-composite systems.
- API 625 compliance acceleration:The updated concrete-encased tank standard is mandating upgraded insulation performance verification, creating certification-based differentiation.
- Digital twin integration:Convergence of thermal modeling software with IoT sensor networks is enabling predictive maintenance contracts for insulation system lifecycle management.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified technicians for 9% nickel steel tank fabrication are concentrated in South Korean and Japanese shipyard networks, constraining project staffing.
- Multi-layer insulation installation complexity:Field assembly of perlite-powder and glass-fiber composite systems requires specialized crews that cannot be scaled rapidly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tank Insulation Market |
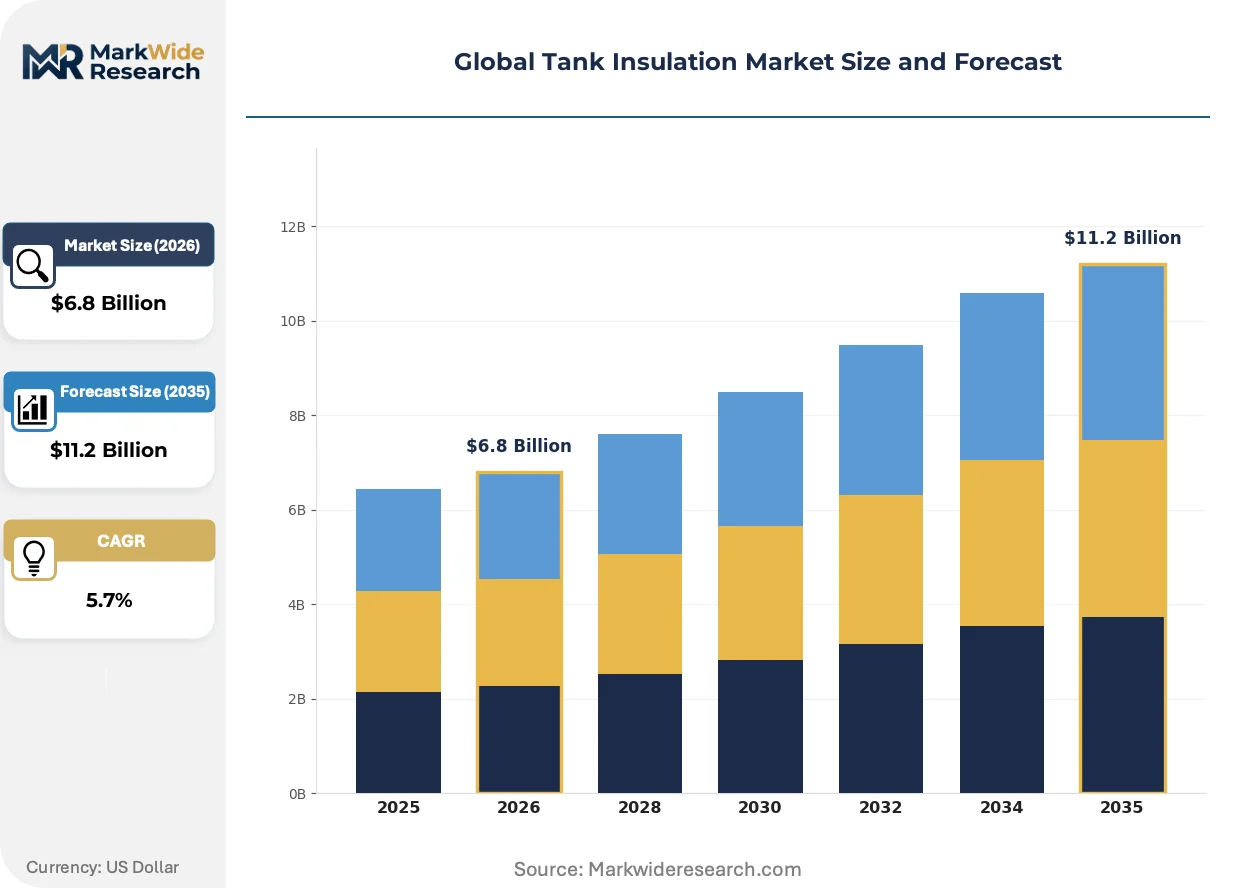
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insulation Material: Polyurethane Foam, Mineral Wool, Expanded Polystyrene, Cellular Glass, Aerogel Application: Petrochemical Storage, Liquefied Gas Containment, Water Tanks, Cryogenic Systems, Chemical Storage Tank Type: Aboveground, Underground, Horizontal, Vertical, Cylindrical End User Industry: Energy & Power Plants, Food & Beverage Processing, Pharmaceuticals, Water Treatment Facilities, Chemical Manufacturing |
| Companies Covered | Owens Corning, Johns Manville, Rockwool International A/S, Knauf Insulation, Kingspan Group, BASF SE, Saint-Gobain, Armacell, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tank Insulation Market Shifts & Advancements
Material science convergence with digital specification tools is compressing the gap between laboratory thermal performance and field-installed outcomes across cryogenic and petrochemical storage applications.
Aerogel blanket technology is hybridizing with conventional polyurethane foam in LNG containment systems, combining superinsulation lambda values with structural load-bearing capacity. Japanese LNG terminal operators are piloting these composite systems for full-containment tanks above 160,000 cubic meters. The hybrid approach is compressing overall insulation thickness requirements while maintaining boil-off gas targets.
EPA volatile organic compound standards for storage vessel emissions are tightening thermal performance verification protocols for aboveground tanks in petrochemical corridors. The regulatory pressure is forcing insulation contractors to adopt continuous thermal monitoring rather than point-in-time commissioning. Gulf Coast refining clusters are responding with embedded fiber-optic temperature sensing during installation.
Buyers are consolidating specification authority into centralized engineering-procurement-construction contractors rather than fragmented owner-operator decisions. This concentration is displacing regional insulation subcontractors with tier-one system integrators capable of warranty-backed performance guarantees. The shift is most visible in Qatar and Australian LNG developments where single-source accountability governs contractor selection.
Global Tank Insulation Market Segmentation
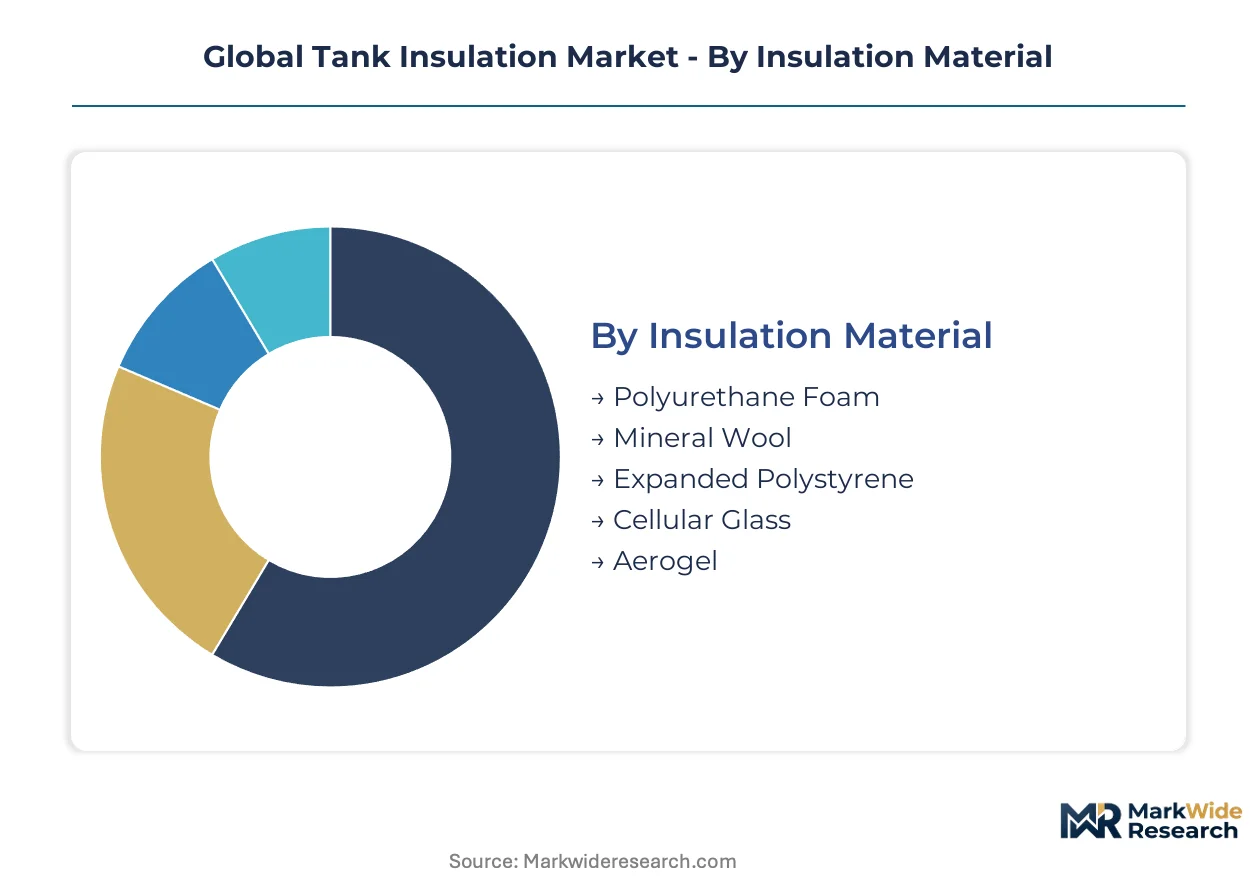
Tank insulation specification diverges sharply across temperature regimes, structural loads, and regulatory exposure. Material selection determines thermal performance boundaries, while application context governs fire resistance and moisture barrier requirements.
Insulation Material:
Cost tier stratification separates commodity bulk insulation from engineered superinsulation systems in project specifications.
- Polyurethane Foam:Closed-cell rigid foam delivers lambda values near 0.022 W/mK with integral vapor barriers. Water treatment and food processing facilities in the United States specify spray-applied systems for lightweight structural compatibility.
- Mineral Wool:Basalt or slag-based fibers withstand continuous temperatures exceeding 750°C with non-combustible ratings. Energy and power plant retrofits across Germany and Poland drive volume procurement for boiler feedwater tank insulation.
- Expanded Polystyrene:Molded bead foam provides cost-effective thermal resistance for ambient water storage. Australian municipal water authorities specify EPS for underground reservoir applications.
- Cellular Glass:Impermeable glass foam blocks resist hydrocarbon absorption and thermal cycling. Petrochemical terminals in Rotterdam and Houston specify cellular glass for crude oil tank base insulation.
- Aerogel:Silica-based nanoporous blankets achieve lambda values below 0.020 W/mK at cryogenic temperatures. LNG containment systems in Qatar and Australia integrate aerogel-polyurethane composites for boil-off gas reduction.
Mineral wool commands the established base. The steepest expansion runs through aerogel composites.
Application:
Operating temperature extremes and hazard classification segment engineering complexity and material certification requirements.
- Petrochemical Storage:Aboveground tanks for crude oil, refined products, and intermediates require fire-rated insulation meeting API 2023 thermal protection standards. Gulf Coast refining clusters specify cellular glass and mineral wool hybrids.
- Liquefied Gas Containment:LNG and LPG storage at -162°C to -42°C demands multi-layer cryogenic systems with perlite powder and glass fiber composites. Full-containment tanks in Japan and South Korea anchor specification intensity.
- Water Tanks:Potable and process water storage prioritizes moisture resistance and biological growth prevention. Municipal utilities across Brazil specify polyurethane foam for elevated tank insulation.
- Cryogenic Systems:Industrial gas containment for nitrogen, oxygen, and argon requires thermal cycling stability. Air separation units in China and India drive demand for perlite-insulated cold boxes.
- Chemical Storage:Aggressive media including acids and caustics demand chemical-resistant jacketing systems. Pharmaceutical manufacturing in Switzerland and Ireland specifies PTFE-coated mineral wool for GMP compliance.
Petrochemical storage anchors volume procurement. Cryogenic systems claim the highest specification value per square meter.
Tank Type:
Structural configuration determines insulation application method, access constraints, and thermal bridging risk at support interfaces.
- Aboveground:Vertical cylindrical tanks with external insulation accessible for maintenance and inspection. EPA emissions standards for volatile organic compounds tighten thermal performance verification protocols in United States petrochemical corridors.
- Underground:Buried horizontal or spherical tanks requiring moisture-resistant external cladding and cathodic protection compatibility. Fuel storage facilities in Germany and France specify cellular glass with bituminous coating.
- Horizontal:Shop-fabricated vessels with insulation applied in controlled factory conditions. LPG distribution terminals across India prefer pre-insulated horizontal tanks for rapid field installation.
- Vertical:Field-erected tanks exceeding 50,000 cubic meters with insulation applied in circumferential bands. LNG import terminals in Turkey and Italy specify vertical full-containment designs.
- Cylindrical:Standardized geometry enabling modular insulation panel systems with reduced field labor. Water treatment facilities in Canada specify cylindrical tanks with factory-applied polyurethane foam.
Aboveground configurations dominate retrofit activity. Vertical tank insulation captures the largest project scale.
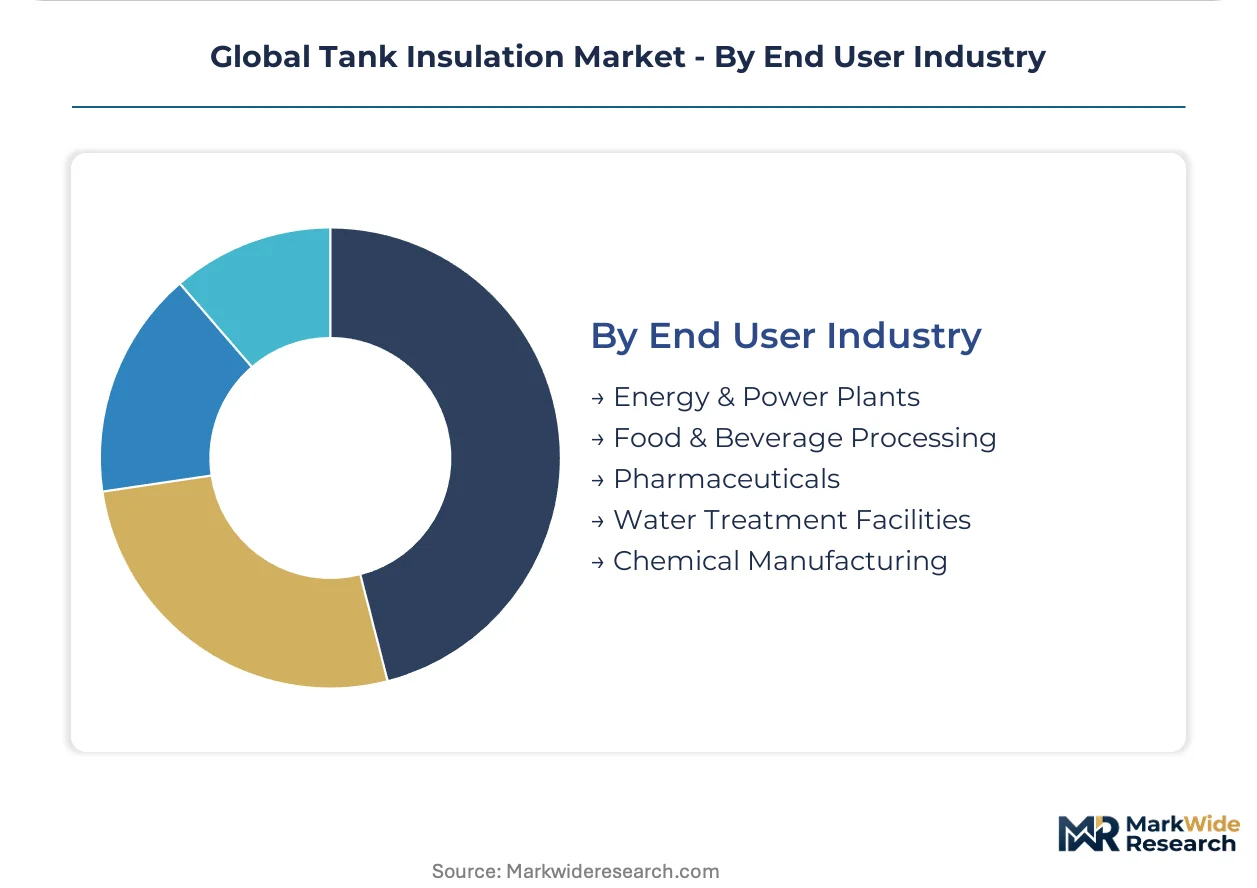
End User Industry:
Regulatory exposure and process criticality segment procurement authority between owner-operators and engineering-procurement-construction contractors.
- Energy & Power Plants:Boiler feedwater, condensate, and fuel oil storage with combined cycle and coal-fired facilities. Indian thermal power stations under CEA efficiency mandates drive insulation retrofit programs.
- Food & Beverage Processing:Dairy, brewing, and cold chain storage requiring hygienic surface finishes and thermal shock resistance. European dairies specify stainless steel-clad polyurethane systems.
- Pharmaceuticals:Water-for-injection and pure steam storage with FDA and EMA validation requirements. Injectable manufacturing facilities in Ireland and Singapore specify seamless insulation with continuous documentation.
- Water Treatment Facilities:Potable water storage and wastewater processing with NSF/ANSI 61 material certification. Australian desalination plants specify cellular glass for brine tank insulation.
- Chemical Manufacturing:Process vessel and intermediate storage with REACH and OSHA Process Safety Management compliance. German chemical parks specify fire-rated mineral wool for ethylene oxide storage.
Energy and power plants anchor volume demand. Pharmaceutical applications command the strictest qualification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal tax credits for LNG export infrastructure in the United States, combined with EU F-Gas Regulation enforcement, are redirecting capital toward compliant cryogenic insulation systems across major energy corridors.
United States
Gulf Coast LNG terminal construction in Texas and Louisiana is accelerating procurement timelines for cellular glass and aerogel composite systems. EPA volatile organic compound standards for storage vessels mandate continuous thermal monitoring rather than point-in-time commissioning. Houston petrochemical clusters are embedding fiber-optic temperature sensing during insulation installation to satisfy verification protocols.
Germany
Energy and power plant retrofits across North Rhine-Westphalia and Bavaria are driving volume demand for mineral wool insulation in boiler feedwater tank applications. EU F-Gas Regulation phase-down schedules for high-global-warming-potential blowing agents are forcing reformulation toward low-lambda polyurethane systems. Chemical parks in Ludwigshafen specify fire-rated mineral wool for ethylene oxide storage under REACH compliance.
Qatar
North Field expansion projects are compressing specification cycles for full-containment LNG tanks exceeding 160,000 cubic meters. National energy investment frameworks prioritize single-source contractor accountability for thermal performance guarantees. Ras Laffan Industrial City is concentrating procurement authority into centralized engineering-procurement-construction contractors.
Australia
Queensland and Western Australia LNG export corridor expansion is pulling cryogenic insulation demand into concentrated procurement windows. Australian municipal water authorities specify expanded polystyrene for underground reservoir applications in parallel with energy infrastructure buildout. Desalination plants in Perth and Adelaide specify cellular glass for brine tank insulation under NSF/ANSI 61 certification.
India
Dahej and Hazira LNG import terminal buildouts are opening specification windows for aerogel-composite systems in underpenetrated full-containment tank markets. Central Electricity Authority efficiency mandates for thermal power stations are accelerating insulation retrofit programs across Maharashtra and Gujarat. Air separation units in Odisha and Tamil Nadu drive demand for perlite-insulated cold boxes.
Global Tank Insulation Market Competitive Landscape
On the supply side, the industry is tiered between multinational material science conglomerates with integrated manufacturing scale and specialized insulation contractors serving regional project markets. Owens Corning, Johns Manville, and Rockwool International A/S anchor the upper tier through captive raw material sourcing and warranty-backed performance guarantees. Strategic moves concentrate on backward integration into blowing agent chemistry and certification-based differentiation under API 625 compliance acceleration.
Within the premium cryogenic tier, Owens Corning leverages glass wool manufacturing scale to dominate North American energy corridor contracts. Johns Manville anchors positioning through mineral wool specialization for petrochemical storage with extreme temperature cycling. Rockwool International A/S competes on basalt-based formulations that sustain thermal stability across European chemical manufacturing clusters. These three exemplify how material origin and fire resistance ratings govern specification authority in high-hazard applications.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Rockwool International A/S |
| Knauf Insulation |
| Kingspan Group |
| BASF SE |
| Saint-Gobain |
| Armacell |
| Cabot Corporation |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors impose cost volatility that compresses margin buffers for polyurethane foam contractors while amplifying price spreads between certified and uncertified insulation systems across European chemical manufacturing clusters.
Pricing Analysis
Certification level creates the primary spread between ISO-verified cryogenic systems and uncertified commodity insulation. Project-based contract pricing dominates LNG terminal procurement, with API 625 compliance commanding substantial premiums over standard thermal protection. Price differentiation rests on thermal performance guarantees and fire resistance ratings, with boil-off gas reduction targets tightening margin pressure on non-specialized contractors. Municipal water utilities exhibit highest price sensitivity, while Qatar National Petroleum and comparable national energy frameworks prioritize single-source accountability over unit cost.
Supply Chain Analysis
Extended payment terms from engineering-procurement-construction contractors now stretch 90-120 days, forcing insulation subcontractors toward supply-chain finance facilities. Manufacturing concentrates in the United States, Germany, and China, with Owens Corning and Johns Manville anchoring North American glass wool and mineral wool supply. Raw material flows draw from propylene oxide derivatives, basalt fiber feedstock, and silica aerogel precursors. Single-source vulnerability concentrates in South Korean 9% nickel steel tank fabrication networks. Distribution runs through tier-one system integrators rather than fragmented regional subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration for thermal lifecycle management is reconfiguring this market toward platform economics, with IoT sensor convergence creating interoperability standards that favor integrated system providers over component suppliers.
For Market Incumbents: Pre-empt displacement by aerogel-polyurethane composite specialists through captive R&D in hybrid insulation systems. Anchor backward integration into blowing agent chemistry before EU F-Gas Regulation phase-down compresses formulation options. Defend Qatari and Australian LNG corridor positions through API 625 certification acceleration.
For New Entrants and Emerging Players: Indian LNG import terminals at Dahej and Hazira present underpenetrated specification windows for full-containment tank insulation. Target pharmaceutical manufacturing in Ireland and Singapore with FDA-grade seamless insulation systems. Pursue engineering-procurement-construction contractor partnerships rather than direct owner-operator sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant insulation assets lacking cryogenic certification. Long-term viability hinges on thermal performance verification capabilities rather than commodity manufacturing scale. Monitor API 625 compliance acceleration as the inflection signal separating certified from uncertified supplier tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| API 625 Certification Investment | Creates defensible positioning in Qatar and Australian LNG terminal procurement cycles. |
| Backward Integration into Blowing Agent Chemistry | Secures formulation flexibility under tightening EU F-Gas Regulation phase-down schedules. |
| Digital Twin Platform Development | Enables predictive maintenance contracts with Japanese LNG terminal operators. |
| Aerogel-Polyurethane Composite R&D | Captures boil-off gas reduction premiums in full-containment tanks above 160,000 cubic meters. |
| India Manufacturing Footprint Establishment | Addresses Dahej and Hazira LNG import terminal buildout procurement windows. |
Research Methodology
A standing panel of EPC procurement directors, cryogenic welding technicians, LNG terminal operators, and insulation contractors provided ongoing calibration across the study. Primary interviews with plant engineers at Rotterdam and Houston petrochemical clusters, thermal R&D directors at major material science conglomerates, and aftermarket service heads at regional insulation subcontractors were cross-validated against customs data, API specification filings, SEC 10-K disclosures from listed suppliers, and project development databases tracking LNG terminal construction. Bottom-up volume estimates from material consumption patterns were triangulated with top-down value projections from contract award tracking.
Scenario bracketing around regulatory enforcement intensity and LNG infrastructure investment cycles anchored the analytical framework across the projection horizon. Segmentation modeling incorporated insulation material type, application temperature regime, tank structural configuration, and end-user industry regulatory exposure. CAGRs were derived from installed base expansion rates and replacement cycle analysis, with specific inputs from propylene oxide price volatility indices and basalt fiber supply concentration metrics.
Practitioners should monitor EU F-Gas Regulation enforcement timing and South Korean 9% nickel steel fabrication capacity for early signals of supply constraint or specification shift. Forecasts reflect documented assumptions about LNG terminal construction schedules and thermal performance verification protocol adoption. Macroeconomic deviation in energy transition capital allocation, regulatory chemistry restriction acceleration, or breakthrough superinsulation material commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Active Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Technical Foam Market