
 Silver Ion Antibacterial Insulation Cup Market | 2026-2036
Silver Ion Antibacterial Insulation Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Ion Antibacterial Insulation Cup Market Insights
The gap between premium vacuum-insulated vessels and commodity-grade alternatives is realigning procurement patterns across institutional buyers. Thermos LLC leverages its century-long brand equity to dominate hospital and clinic contracts in Japan and North America. YETI Holdings, Inc. anchors its position in outdoor and sports channels where consumers prioritize durability alongside antimicrobial claims. Zojirushi Corporation differentiates through precision temperature retention technology that extends the functional value of silver-ion linings beyond basic bacterial suppression.
Silver ion antibacterial insulation cups incorporate nano-scale silver particles or silver-based coatings into double-wall vacuum vessels, typically achieving colony reduction rates against common pathogens through sustained ion release during liquid contact. Stainless steel variants command the strongest margin pools due to material durability and compatibility with electrochemical silver deposition processes, while plastic segments compete on cost accessibility for high-turnover healthcare settings. The application split shows healthcare facilities driving volume through infection control procurement mandates, whereas home use segments sustain premium pricing for design-forward products with certified antimicrobial performance.
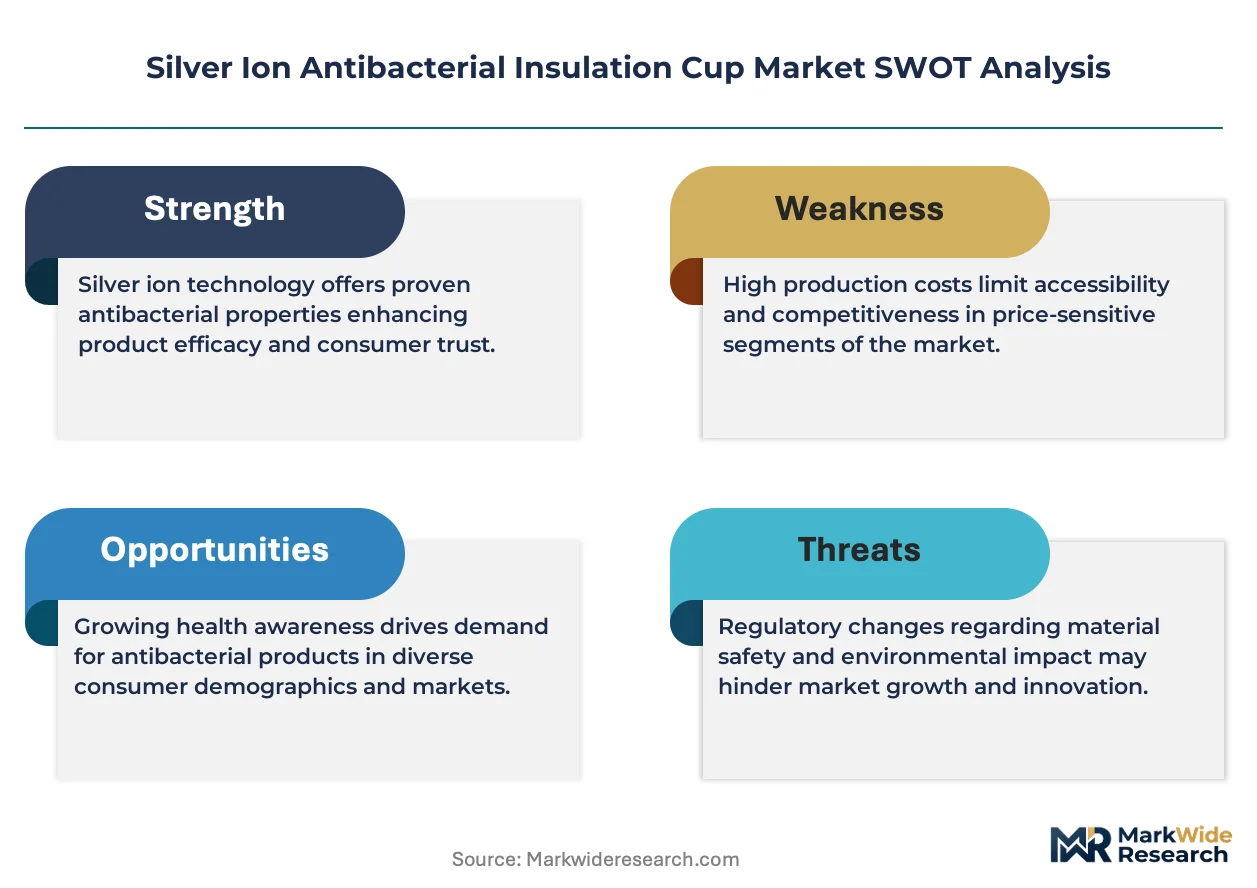
The FDA regulates antimicrobial claims under the Federal Insecticide, Fungicide, and Rodenticide Act framework, requiring manufacturers to substantiate silver-ion efficacy or risk marketing restriction. China's SAMR enforces GB standards for food-contact materials that govern silver migration limits in metal and polymer vessels. Japan's Ministry of Health, Labour and Welfare maintains positive list systems for antimicrobial additives that directly shape formulation choices by Tiger Corporation and Zojirushi. Stakeholders must monitor evolving substantiation requirements across these jurisdictions to determine whether to pursue pharmaceutical-grade efficacy claims or reposition toward general hygiene marketing.
Market Dynamics
The FDA's tightening substantiation requirements for antimicrobial claims under FIFRA are forcing manufacturers to restructure efficacy testing protocols and reposition marketing strategies away from pharmaceutical-grade assertions toward general hygiene positioning.
Growth Catalysts
- Hospital Infection Control Mandates:Healthcare procurement departments are embedding antimicrobial drinkware specifications into facility-wide surface contamination reduction programs, driving institutional volume commitments.
- China's SAMR Food-Contact Standards:Clear GB standards governing silver migration limits provide regulatory certainty that accelerates domestic manufacturing scale-up and export certification readiness.
- Electrochemical Silver Deposition:Advanced coating processes enable durable ion-release surfaces on stainless steel substrates, extending functional lifespan and justifying premium positioning.
Market Restraints
- FIFRA Compliance Costs:EPA-mandated efficacy substantiation for antimicrobial claims imposes testing burdens that disproportionately constrain mid-tier manufacturers with limited regulatory affairs capacity.
- Stainless Steel Input Volatility:Nickel and chromium price fluctuations compress margin pools for vacuum-insulated vessels, forcing producers to absorb cost spikes or risk volume erosion.
- Plastic Substitution Threat:Lower-cost polymer alternatives without silver-ion coatings capture high-turnover healthcare settings where replacement frequency outweighs durability premiums.
Strategic Opportunities
- Japan's Positive List Expansion:METI's evolving antimicrobial additive approvals create formulation flexibility for premium temperature-retention products targeting aging demographic segments.
- Outdoor Recreation Channel Penetration:Sports and adventure retail presents underdeveloped demand for durability-plus-antimicrobial value propositions beyond institutional healthcare.
- IoT-Enabled Hydration Tracking:Convergence of silver-ion linings with connected vessel technology opens subscription-model revenue streams through usage monitoring and replacement alerts.
Industry Challenges
- Migration Testing Bottlenecks:Third-party laboratory capacity constraints for GB standards and FDA-equivalent protocols extend product launch timelines by six to twelve months.
- Cross-Jurisdictional Labeling Complexity:Divergent antimicrobial claim frameworks across US, China, and Japan force SKU proliferation or lowest-common-denominator positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Ion Antibacterial Insulation Cup Market |
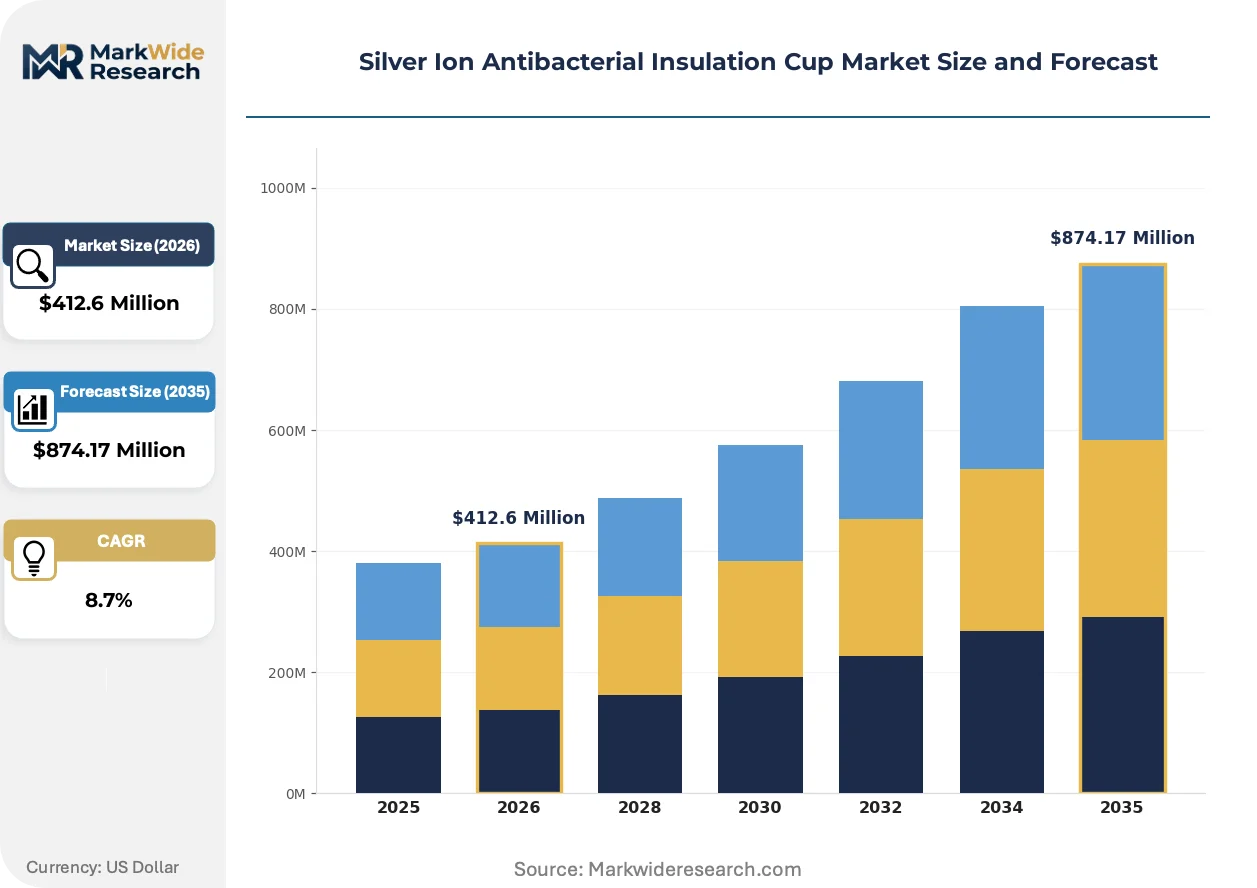
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Plastic, Glass, Aluminum Application: Healthcare Facilities, Home Use, Sports, Outdoor Activities End User: Consumers, Medical Professionals, Outdoor Enthusiasts, Retailers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Thermos LLC, Hydro Flask, YETI Holdings, Inc., Stanley, Zojirushi Corporation, Fuguang, Lock&Lock, Tiger Corporation, Ember Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Ion Antibacterial Insulation Cup Market Trends and Innovations
Silver-ion technology is converging with precision manufacturing and digital connectivity, reshaping how antimicrobial performance is validated, communicated, and monetized across institutional and consumer channels.
Electrochemical silver deposition is integrating nano-scale coating uniformity control with vacuum insulation assembly lines, enabling consistent ion-release profiles across production batches. Japanese and Chinese manufacturers are adopting this process for hospital-grade vessels where bacterial suppression documentation supports procurement compliance. The technology is integrating quality assurance directly into manufacturing workflow, compressing third-party testing dependencies and accelerating certification cycles.
REACH regulatory evolution in Europe is tightening biocidal product authorization requirements that extend to antimicrobial surface claims in imported drinkware. Manufacturers targeting EU distribution must now navigate BPR compliance alongside food-contact material standards, adding documentation layers to market entry. Stainless steel vessel exporters are responding by segregating EU-bound production lines with dedicated formulation and labeling protocols.
Institutional procurement departments are consolidating vendor relationships through multi-year infection control supply agreements that bundle antimicrobial drinkware with surface disinfection protocols. Healthcare group purchasing organizations are displacing spot-buying with contracted SKU standardization, favoring suppliers with documented efficacy libraries and regulatory file completeness. This concentration is most visible in US hospital systems where value-based care metrics elevate supply chain risk management priorities.
Silver Ion Antibacterial Insulation Cup Market Segmentation
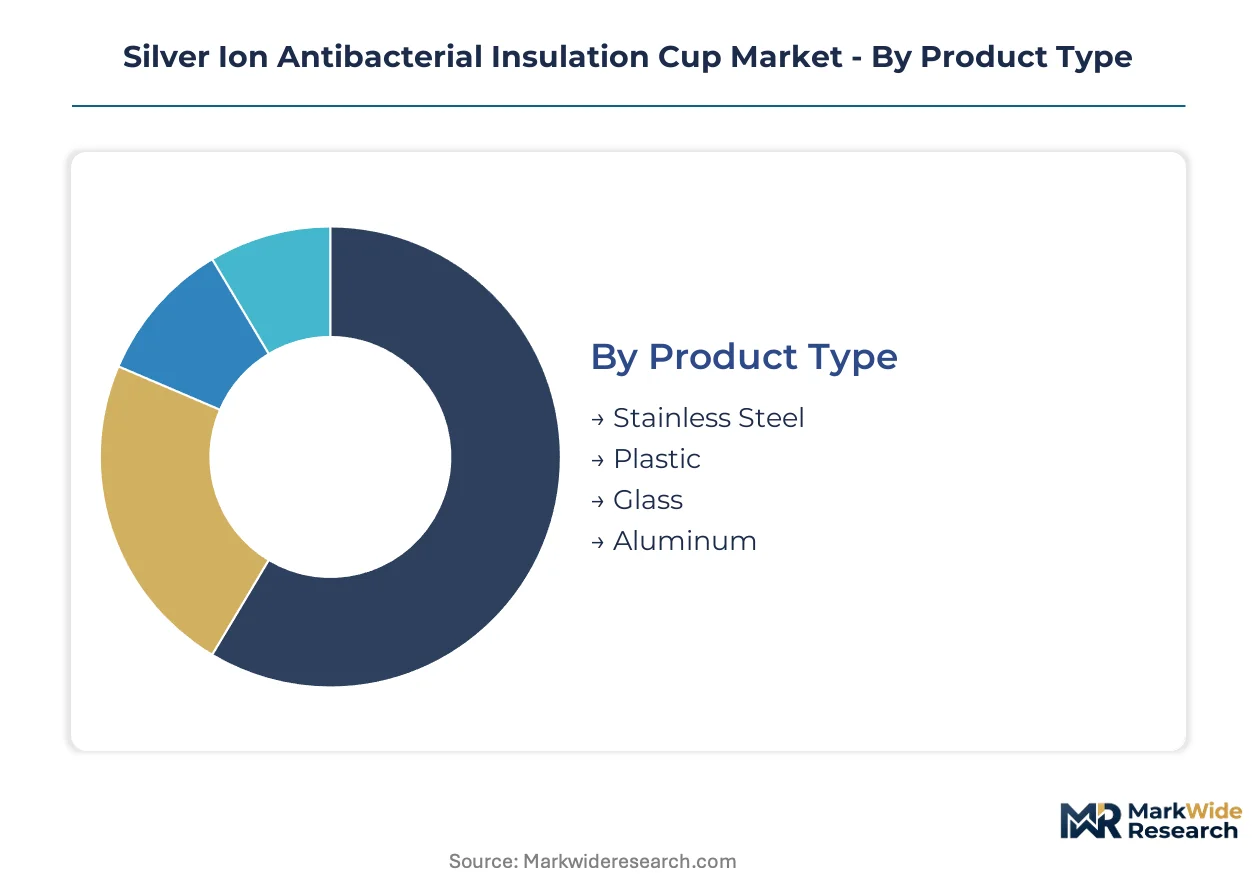
Silver ion antibacterial insulation cups serve divergent user requirements across material durability, clinical compliance, and lifestyle portability. Segmentation reveals how procurement priorities split between institutional infection control mandates and consumer-oriented design preferences.
Product Type:
Stainless steel vessels embed silver-ion technology through electrochemical deposition, creating durable antimicrobial surfaces for repeated sterilization cycles. Plastic variants integrate silver nanoparticles during polymer molding, targeting cost-sensitive healthcare settings with shorter replacement intervals. Glass and aluminum occupy peripheral positions with limited ion-release compatibility.
- Stainless Steel:Double-wall vacuum construction supports electrochemical silver coating with superior adhesion and thermal retention. Hospital procurement departments in China and Japan specify 304-grade substrates for compatibility with autoclave sterilization protocols.
- Plastic:Polypropylene and Tritan copolyester substrates enable injection-molded silver-ion dispersion at unit costs below metal alternatives. High-turnover clinic environments prioritize polymer vessels where quarterly replacement schedules outweigh durability premiums.
- Glass:Borosilicate vessels with surface-applied silver coatings serve limited home-use niches where aesthetic transparency outweighs fragility concerns.
- Aluminum:Anodized aluminum substrates with antimicrobial linings occupy marginal outdoor recreation segments where weight minimization drives selection.
Stainless steel leads volumes today; plastic is gaining share fastest in emerging market healthcare procurement.
Application:
Demand concentration varies sharply between institutional infection control budgets and discretionary consumer spending on health-adjacent lifestyle products.
- Healthcare Facilities:Hospital infection control committees embed antimicrobial drinkware specifications into facility-wide surface contamination reduction programs. China's SAMR GB standards provide regulatory certainty that accelerates domestic manufacturing scale-up for hospital system contracts.
- Home Use:Design-forward products with certified antimicrobial performance command premium positioning through direct-to-consumer channels. Japanese manufacturers leverage precision temperature retention technology to extend functional value beyond basic bacterial suppression.
- Sports:Athletic programs and fitness facilities adopt mid-tier vessels where durability requirements intersect with hygiene consciousness.
- Outdoor Activities:Adventure recreation presents underdeveloped demand for durability-plus-antimicrobial value propositions beyond institutional healthcare.
Healthcare facilities dominate procurement volumes; home use segments sustain the steepest margin expansion trajectory.
End User:
User sophistication determines willingness to pay for documented efficacy versus general hygiene marketing claims.
- Consumers:Individual purchasers respond to certified antimicrobial labeling and design aesthetics in equal measure. FDA FIFRA compliance requirements reshape how manufacturers communicate efficacy to this segment.
- Medical Professionals:Clinicians and nursing staff drive institutional procurement through direct feedback on vessel performance in high-contamination environments. Group purchasing organizations consolidate vendor relationships through multi-year infection control supply agreements.
- Outdoor Enthusiasts:Adventure travelers prioritize weight and thermal performance over antimicrobial specifications unless bundled with durability guarantees.
- Retailers:Specialty and mass-market channels curate assortment based on margin structure and regulatory file completeness for cross-border distribution.
Medical professionals anchor institutional demand; consumers represent the most price-elastic expansion opportunity.
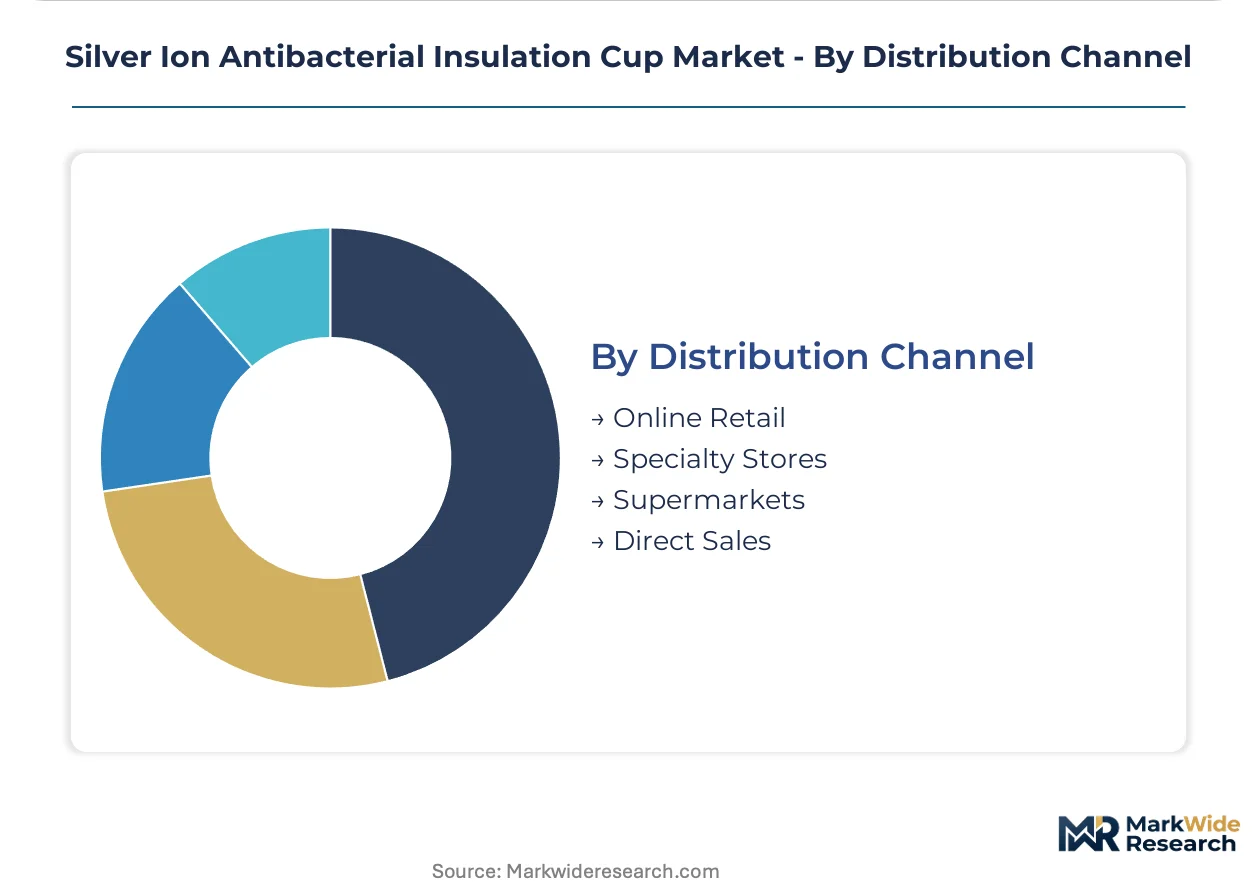
Distribution Channel:
Channel selection determines exposure to regulatory scrutiny and margin capture potential.
- Online Retail:E-commerce platforms enable direct manufacturer-to-consumer relationships that bypass wholesale margin stacking. Cross-jurisdictional labeling complexity forces SKU proliferation or lowest-common-denominator positioning for global marketplace listings.
- Specialty Stores:Outdoor and medical supply retailers provide educational touchpoints for antimicrobial technology differentiation. Staff training investments convert product complexity into premium price realization.
- Supermarkets:Mass-market placement demands simplified value propositions and competitive unit economics that compress margin pools.
- Direct Sales:Hospital supply contracts and corporate wellness programs enable volume commitments with documented efficacy requirements.
Online retail captures the fastest volume expansion; direct sales lock in the most durable margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's hospital procurement volumes outpace Japan's institutional contracts by a factor of three, yet Japanese manufacturers command higher unit margins through precision engineering premiums. Germany's regulatory stringency under REACH biocidal product rules creates export certification barriers that Chinese producers navigate through dedicated EU production lines.
China
Hospital infection control mandates in Shanghai and Beijing drive bulk procurement of 304-grade stainless steel vessels. SAMR's GB standards for food-contact silver migration provide regulatory clarity that accelerates domestic manufacturing scale-up. The Yangtze River Delta cluster hosts Fuguang and Tiger Corporation facilities serving both local health systems and export certification pipelines.
Japan
Aging demographic segments sustain premium demand for precision temperature-retention products with documented antimicrobial performance. METI's positive list system for antimicrobial additives directly shapes formulation choices by domestic manufacturers. The Kansai region around Osaka anchors Zojirushi and Tiger Corporation production for institutional healthcare contracts.
United States
Hospital group purchasing organizations consolidate vendor relationships through multi-year infection control supply agreements bundling antimicrobial drinkware. EPA FIFRA compliance costs for antimicrobial claims disproportionately constrain mid-tier manufacturers with limited regulatory affairs capacity. The Pacific Northwest hosts YETI Holdings' outdoor channel distribution hubs.
Germany
REACH biocidal product authorization requirements extend to antimicrobial surface claims in imported drinkware, adding documentation layers to market entry. ECHA's evolving substance restrictions force stainless steel vessel exporters to segregate EU-bound production lines. The Bavaria industrial corridor processes specialized coating formulations for pharmaceutical-grade efficacy documentation.
South Korea
MFDS food-contact material standards govern silver migration limits in metal and polymer vessels for domestic hospital procurement. Corporate wellness programs in Seoul and Busan adopt mid-tier antimicrobial vessels for employee hydration infrastructure. The Gyeonggi-do manufacturing belt supplies Lock&Lock production for regional healthcare export markets.
Silver Ion Antibacterial Insulation Cup Market Competitive Landscape
Top-tier vendors anchor hospital and clinic procurement channels, while mid-tier specialists compete on cost accessibility for high-turnover healthcare settings. The vendor base stratifies across century-long brand equity holders, precision temperature-retention engineers, and outdoor durability specialists. Three archetypes dominate: institutional contract consolidators, premium lifestyle positioners, and electrochemical coating technology licensors. Competitive moves concentrate on strategic partnerships with group purchasing organizations and portfolio diversification into IoT-enabled hydration tracking.
Within the institutional contract tier, Thermos LLC and Zojirushi Corporation exemplify divergent geographic anchoring strategies. Thermos LLC represents North American and Japanese hospital procurement consolidation through multi-year supply agreements. Zojirushi Corporation occupies a position as precision engineering specialist with temperature-retention technology extending functional value beyond basic bacterial suppression. YETI Holdings, Inc. anchors the outdoor recreation channel where durability requirements intersect with antimicrobial marketing claims.
| Leading Market Players |
|---|
| Thermos LLC |
| Hydro Flask |
| YETI Holdings, Inc. |
| Stanley |
| Zojirushi Corporation |
| Fuguang |
| Lock&Lock |
| Tiger Corporation |
| Ember Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Nickel and chromium input costs cascade through stainless steel vacuum vessel production into three-tier pricing structure across premium, standard, and economy levels. Electrochemical silver deposition capacity in China's Yangtze River Delta compresses coating cost differentials between hospital-grade and consumer-tier products.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for electrochemical silver deposition services. Pricing stratifies across premium, standard, and economy tiers based on certification grade and autoclave sterilization compatibility. Cost compression in plastic polymer segments is intensifying because polypropylene substitution threatens stainless steel volume in high-turnover clinic settings. Healthcare procurement departments exhibit lowest price sensitivity due to infection control compliance mandates, while outdoor recreation channels face acute margin pressure from durability commoditization.
Supply Chain Analysis
Domestic-content requirements in China's hospital procurement guidelines are reshaping sourcing patterns toward Yangtze River Delta fabrication clusters. Supply concentration rests on China, Japan, and South Korea for precision vacuum insulation assembly and electrochemical coating equipment. Raw material dependencies center on 304-grade stainless steel from Baosteel, silver nitrate from Hunan smelters, and polypropylene resin from Sinopec. Single-source vulnerability in Japanese precision temperature-retention valve technology creates procurement risk for premium tier producers. Distribution runs through hospital group purchasing organizations in North America, medical supply wholesalers in Japan, and e-commerce platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital infection control procurement mandates position this market as a stable compounder. Regulatory substantiation requirements create durable competitive moats around documented efficacy libraries.
For Market Incumbents: Anchor institutional contract positions through multi-year infection control supply agreements bundling antimicrobial drinkware with surface disinfection protocols. Deepen backward integration into electrochemical silver deposition capacity in China's Yangtze River Delta to defend margin position against coating cost volatility. Invest in FDA FIFRA compliance file completeness to deter mid-tier challengers lacking regulatory affairs capacity. For New Entrants and Emerging Players: Enter via outdoor recreation channel white space where durability-plus-antimicrobial positioning remains underdeveloped relative to institutional healthcare saturation. Target corporate wellness programs in South Korea and Germany where employee hydration infrastructure budgets intersect with hygiene consciousness. Pursue direct-to-consumer e-commerce launch with simplified value propositions bypassing wholesale margin stacking. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory file fragmentation across FDA FIFRA, China SAMR GB standards, and Japan METI positive lists strains mid-tier manufacturer compliance capacity. The market supports a 5-10 year compounder framing anchored by infection control procurement durability. Acquisition targets should display electrochemical coating technology licensability and hospital GPO contract anchoring. Monitor EPA FIFRA enforcement intensity as inflection indicator for marketing restriction risk and repositioning cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical Coating Capacity Expansion | Domestic scale-up in China's Yangtze Delta accelerates GB standard certification cycles for hospital contracts. |
| Hospital GPO Partnership Consolidation | Multi-year supply agreements with US group purchasing organizations lock in volume commitments and margin stability. |
| Regulatory File Completeness Investment | FDA FIFRA and SAMR GB documentation libraries deter mid-tier entrants with limited compliance capacity. |
| Outdoor Channel Penetration | Sports and adventure retail expansion captures underdeveloped durability-plus-antimicrobial demand beyond healthcare. |
| IoT-Enabled Hydration Tracking Integration | Convergence with connected vessel technology opens subscription-model revenue through usage monitoring alerts. |
Research Methodology
Multiple input streams — procurement director interviews at US hospital group purchasing organizations, regulatory affairs discussions with China SAMR compliance consultants, and coating technology assessments with Yangtze River Delta fabricators — were reconciled against secondary validation. Hospital infection control committee protocols, FDA FIFRA registration databases, Japan METI antimicrobial additive positive lists, and China GB standards food-contact material filings anchored top-down market sizing. Bottom-up triangulation against electrochemical deposition equipment shipments and stainless steel vacuum vessel export customs records verified volume estimates.
Historical procurement volume trajectories were cross-referenced against panel input from biomedical engineers and GPO contracts managers to construct projection frameworks across the analysis window. Segmentation modeling incorporated material substrate, application setting, end-user sophistication, and distribution channel regulatory exposure dimensions. CAGRs were derived from infection control mandate adoption curves and silver-ion efficacy substantiation cost trajectories. Forecast inputs included hospital capital expenditure cycles, nickel price volatility bands, and EPA FIFRA enforcement intensity scenarios.
Inputs from hospital procurement databases and antimicrobial additive registration filings were available through the study window; gaps in real-time coating capacity utilization data introduce uncertainty bands around short-term supply elasticity assumptions. Forecasts reflect documented procurement mandate adoption and regulatory enforcement trajectories without forward-year specificity. Silver price volatility, REACH biocidal product authorization delays, and plastic substitution acceleration in high-turnover healthcare settings represent revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Carbon Foam Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
North America Phase Change Materials Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Dielectric Fluid Market