
 Fiberglass Duct Wrap Insulation Market | 2026-2036
Fiberglass Duct Wrap Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Duct Wrap Insulation Market Intelligence
Commercial building retrofits are repositioning specification priorities toward higher thermal performance in fiberglass duct wrap insulation. Owens Corning leverages its building science expertise to dominate specification channels for large-scale mechanical infrastructure. Johns Manville sustains manufacturing scale across multiple North American facilities, ensuring consistent supply to mechanical contractors. Knauf Insulation differentiates through integrated mineral wool and fiberglass portfolios that address diverse HVAC application requirements.
Fiberglass duct wrap insulation consists of flexible, non-combustible glass fibers bonded with thermosetting resins, typically manufactured in densities ranging from 0.75 to 3.0 pounds per cubic foot with factory-applied vapor retarder facings. This material reduces thermal energy loss from sheet metal ductwork while controlling condensation on cold air distribution systems. Blanket and sheet configurations command the largest volume positions due to their adaptability across rectangular duct geometries, while board and panel formats capture premium margin pools in industrial process applications requiring rigid dimensional stability. HVAC Systems applications lead absolute demand, though Cold Storage and Soundproofing segments demonstrate faster specification velocity as operators seek multifunctional insulation solutions.
ASHRAE Standard 90.1, the International Energy Conservation Code, and OSHA workplace safety guidelines collectively shape product certification requirements, installation protocols, and market access conditions for fiberglass insulation manufacturers. The EPA's formaldehyde emissions standards and evolving state-level building performance mandates further constrain formulation choices and manufacturing processes. Stakeholders must monitor code adoption timelines across jurisdictions and assess backward integration into raw glass fiber supply as strategic decisions that will determine cost position and specification retention.
Market Dynamics
Commercial building retrofits are repositioning demand toward higher R-value fiberglass duct wrap products as ASHRAE Standard 90.1 and evolving energy codes tighten thermal performance requirements across cooling-dominated HVAC markets.
Growth Catalysts
- ASHRAE Standard 90.1:Tightening thermal performance mandates in North America are forcing specification upgrades toward higher-density fiberglass duct wrap with factory-applied vapor retarders.
- Sun Belt metropolitan concentration:Cooling-dominated HVAC loads across southern United States cities are prioritizing condensation control and thermal efficiency in mechanical infrastructure.
- Cold Storage vertical expansion:Multifunctional insulation requirements in refrigerated warehousing are pulling fiberglass duct wrap into low-temperature distribution applications.
Market Restraints
- Formaldehyde emissions compliance:EPA emissions standards constrain resin formulation choices and elevate manufacturing complexity for thermosetting binder systems.
- Mineral wool substitution:Integrated insulation portfolios from competing material categories capture specification share in fire-rated and high-temperature mechanical applications.
- Raw glass fiber supply concentration:Backward integration requirements into molten glass production limit new entrant participation and consolidate cost position among established manufacturers.
Strategic Opportunities
- Soundproofing application expansion:Acoustic attenuation specifications in commercial HVAC are creating incremental demand for dual-function thermal-acoustic fiberglass wrap systems.
- Industrial process rigid board formats:Panel and board configurations command premium positioning in manufacturing facilities requiring dimensional stability under mechanical stress.
- State-level building performance mandates:California Title 24 and comparable state energy codes are accelerating retrofit timelines and specification refresh cycles.
Industry Challenges
- Certification timeline compression:Multi-jurisdictional code adoption schedules force manufacturers to maintain parallel product certification tracks across varying thermal performance thresholds.
- Installation labor specialization:Proper vapor retarder sealing and density-matched cutting techniques require trained mechanical contractor crews, constraining deployment velocity in tight construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Duct Wrap Insulation Market |
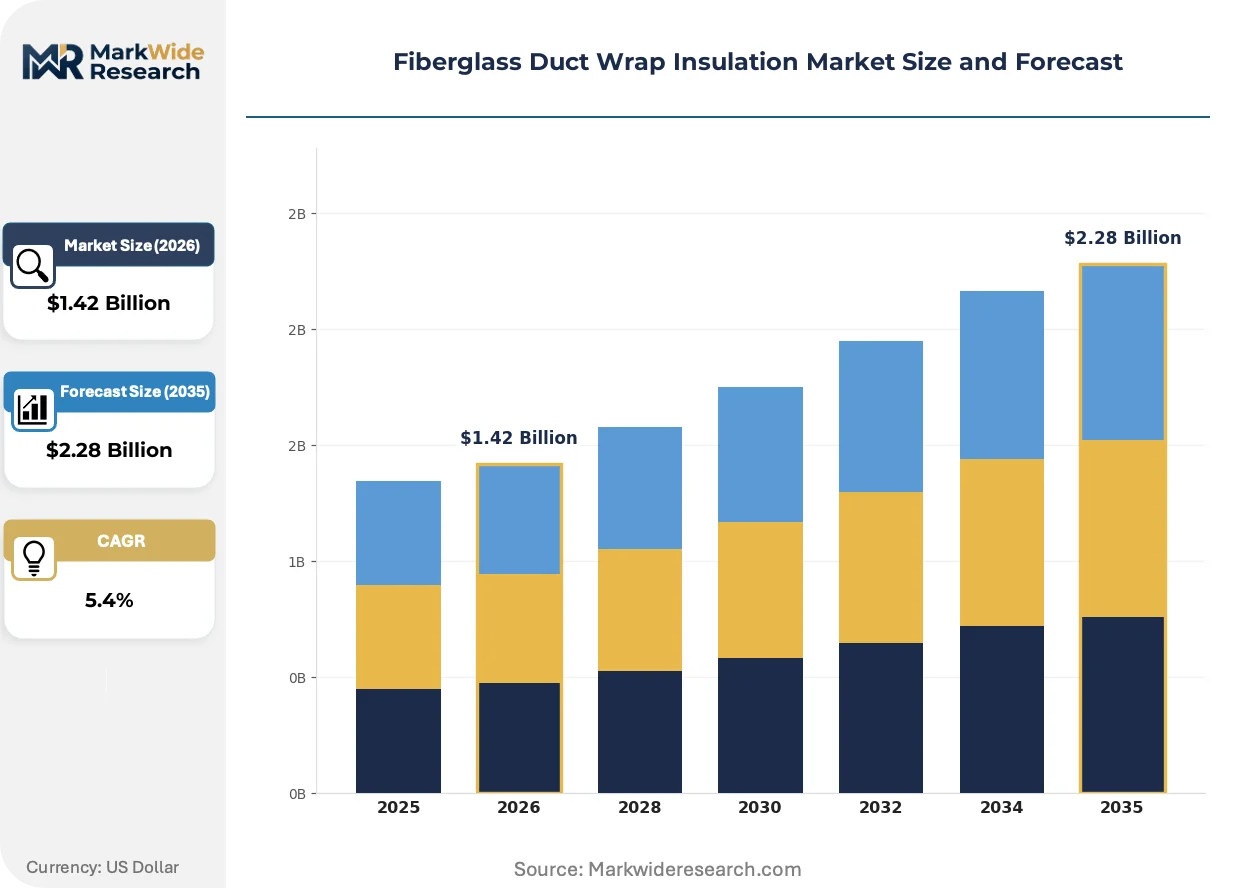
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanket, Pipe Wrap, Sheet, Board, Panel Application: HVAC Systems, Industrial Facilities, Commercial Buildings, Cold Storage, Soundproofing End User: Construction Contractors, Mechanical Contractors, Facility Managers, Insulation Specialists Installation Method: Adhesive Bonding, Mechanical Fastening, Wire Tie, Tape Wrapping, Spray Application |
| Companies Covered | Owens Corning, Johns Manville, Knauf Insulation, CertainTeed, Manson Insulation, Mag-Isover, Frost King & Thermwell Products, GAF, Lamtec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Duct Wrap Insulation Market Strategic Shifts & Innovations
Digital specification tools and automated thermal modeling are compressing the design-to-procurement cycle for mechanical insulation, while regulatory stringency and multifunctional performance demands reshape product development priorities.
Factory-applied smart vapor retarder technologies with variable permeance ratings are automating moisture management across seasonal humidity swings. Large-scale mechanical contractors in the Sun Belt region are specifying these adaptive facings at accelerating rates. The technology is automating condensation risk calculations that previously required manual psychrometric analysis, compressing engineering review timelines.
The International Energy Conservation Code adoption cascade across U.S. jurisdictions is mandating stepped R-value increments in commercial mechanical systems. Industrial consequence includes accelerated obsolescence of legacy low-density wrap inventories held by regional distributors. Higher R-value product categories are capturing specification share fastest in Texas, Florida, and Arizona metropolitan construction markets.
Integrated building energy modeling platforms are consolidating insulation specification authority within MEP engineering firms and away from traditional distributor influence. Mechanical contractors are receiving pre-specified thermal performance packages rather than selecting products independently. This channel shift is most visible in design-build commercial projects across cooling-dominated climate zones where energy code compliance liability concentrates with the engineer-of-record.
Fiberglass Duct Wrap Insulation Market Segmentation
Product configuration and installation protocol choices in fiberglass duct wrap insulation carry direct implications for code compliance burden, labor cost structure, and thermal performance warranty terms. Specification decisions cascade through HVAC system design, with each segment category imposing distinct certification requirements on manufacturers and contractors.
Product Type:
ASHRAE Standard 90.1 compliance timelines vary sharply across product formats, with factory-applied vapor retarder systems facing accelerated recertification cycles versus bare insulation substrates.
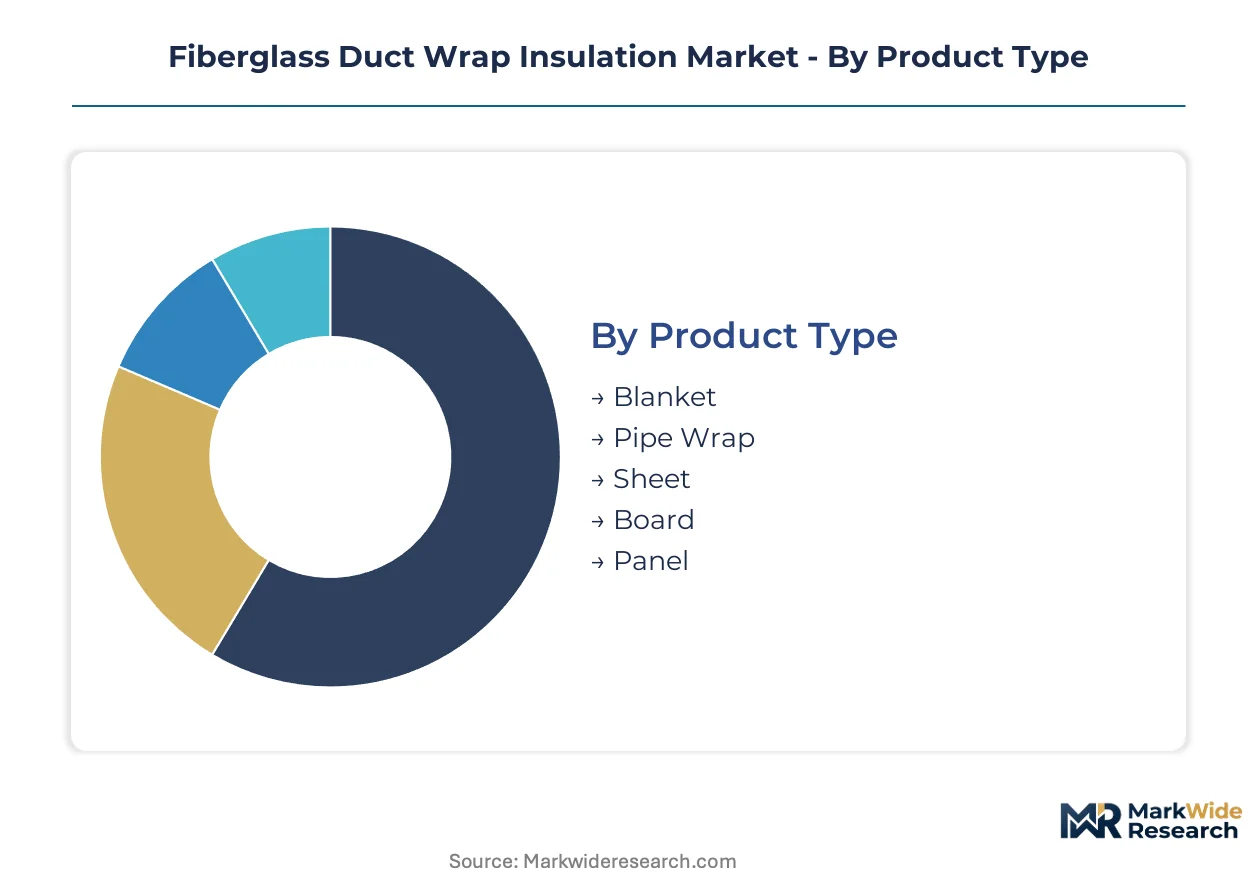
- Blanket:Flexible rolls of glass fiber bonded with thermosetting resin, typically supplied at 0.75 to 1.5 pounds per cubic foot density with reinforced foil or vinyl facing. Demand concentrates in commercial building retrofits across Sun Belt metropolitan areas where cooling-dominated HVAC loads prioritize thermal efficiency and condensation control in rectangular duct geometries.
- Sheet:Pre-cut flat sections enabling rapid field fabrication around irregular ductwork configurations, commonly specified with factory-laminated vapor retarders. Mechanical contractors in Texas and Florida are specifying sheet formats at accelerating rates for design-build commercial projects with compressed installation windows.
- Pipe Wrap:Pre-formed cylindrical sections engineered for round duct and piping applications, typically manufactured at higher densities to withstand mechanical compression during installation. Industrial process facilities specify pipe wrap for chilled water distribution lines.
- Board:Rigid fiberglass panels delivering dimensional stability under mechanical stress, commanding premium positioning in manufacturing facilities requiring structural integrity in exposed applications.
- Panel:Large-format rigid sections with reinforced edges, specified for industrial air handling units and custom-built plenum assemblies where flatness tolerances are critical.
Blanket sits at the top of the volume ranking, with Sheet climbing the fastest.
Application:
End-use concentration patterns reveal margin tiering, with multifunctional performance requirements in specialized environments extracting premium pricing versus commodity HVAC specifications.
- HVAC Systems:Thermal energy conservation and condensation management for commercial and institutional air distribution infrastructure, representing the foundational demand pool for fiberglass duct wrap across cooling-dominated climate zones.
- Cold Storage:Refrigerated warehousing and distribution facilities requiring simultaneous thermal resistance, vapor barrier integrity, and structural durability under cyclic temperature loading. Operators in Florida and Arizona are specifying fiberglass wrap for low-temperature distribution applications at expanding rates.
- Soundproofing:Acoustic attenuation specifications in commercial HVAC creating incremental demand for dual-function thermal-acoustic systems. Mechanical engineers in Texas metropolitan markets are integrating soundproofing wrap into open-plan office mechanical designs.
- Industrial Facilities:Process air handling and pollution control systems requiring chemical resistance and elevated temperature tolerance, typically specifying higher-density board configurations.
- Commercial Buildings:General construction applications spanning office, retail, and institutional occupancies, with specification authority consolidating within MEP engineering firms away from distributor influence.
HVAC Systems maintains absolute volume leadership, though Cold Storage and Soundproofing are expanding most quickly as operators seek multifunctional insulation solutions.
End User:
Procurement authority distribution shapes channel strategy, with specification control shifting upstream toward engineering firms and away from traditional distributor relationships.
- Mechanical Contractors:Field installation crews executing HVAC system construction and retrofit, requiring trained labor for proper vapor retarder sealing and density-matched cutting techniques. Sun Belt contractors face compressed certification timelines under evolving energy code adoption schedules.
- Construction Contractors:General builders coordinating multi-trade commercial projects, increasingly receiving pre-specified thermal performance packages from engineer-of-record rather than selecting insulation independently.
- Insulation Specialists:Dedicated subcontractors with certified installation protocols and manufacturer direct relationships, capturing premium-margin work in complex industrial and cold storage applications.
- Facility Managers:Building operators executing maintenance-driven replacement and energy upgrade projects, typically sourcing through distribution channels with shorter lead time requirements.
Mechanical Contractors dominate procurement volume, with Insulation Specialists gaining share fastest in premium application segments.
Installation Method:
Labor skill requirements and productivity rates vary substantially across attachment protocols, influencing contractor preference and project cost structure.
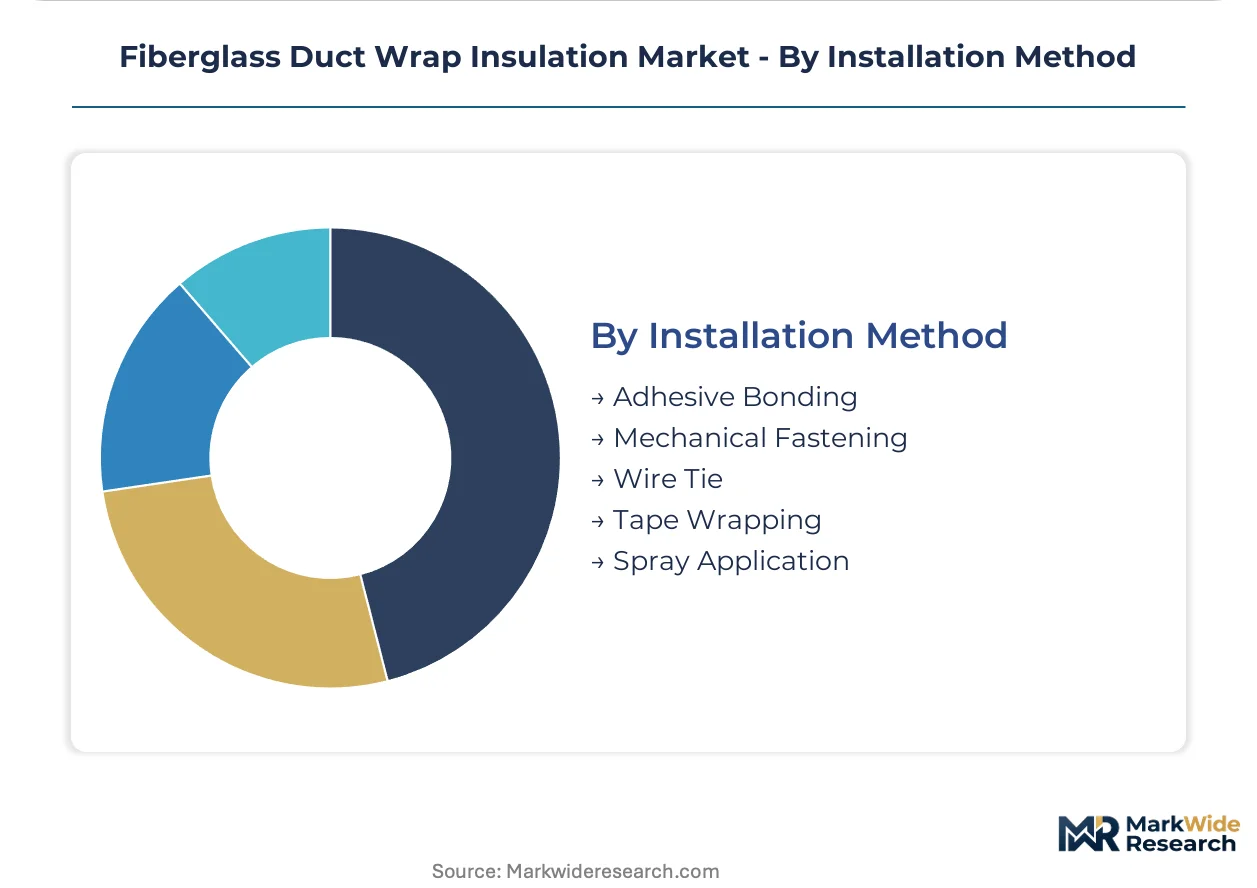
- Adhesive Bonding:Pressure-sensitive or contact adhesive application requiring substrate preparation and cure time management, specified for smooth duct surfaces in clean indoor environments.
- Mechanical Fastening:Pin, clip, or staple attachment systems enabling rapid deployment across large surface areas, preferred by mechanical contractors in high-volume commercial construction.
- Wire Tie:Metal wire lacing securing wrap around cylindrical or irregular geometries, specified for industrial process applications where mechanical durability is paramount.
- Tape Wrapping:Self-adhesive foil or vinyl tape sealing seams and facing joints, critical for vapor retarder continuity and condensation control compliance.
- Spray Application:Field-applied coating systems for irregular surfaces or repair scenarios, limited to specialized remediation and custom fabrication contexts.
Mechanical Fastening leads installation protocol selection by volume, with Tape Wrapping protocols expanding most quickly as vapor retarder performance requirements tighten under ASHRAE Standard 90.1.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fiberglass duct wrap insulation production geography, as manufacturers relocate capacity to jurisdictions with lower compliance costs for formaldehyde emissions standards and energy code enforcement. This migration pattern concentrates supply in regions with established glass fiber infrastructure and permissive environmental timelines.
United States
Sun Belt metropolitan areas including Houston, Phoenix, and Miami are driving specification velocity for higher R-value products as ASHRAE Standard 90.1 adoption accelerates across cooling-dominated climate zones. The EPA's formaldehyde emissions standards constrain resin formulation choices for domestic manufacturers. Texas and Florida construction markets are absorbing premium-density fiberglass duct wrap at expanding rates for commercial retrofit applications.
Germany
Industrial process facilities in the Ruhr region and Bavaria are specifying rigid board configurations for manufacturing air handling systems requiring dimensional stability. The EU Green Deal and national building energy efficiency regulations are tightening thermal performance mandates for mechanical infrastructure. Stuttgart and Munich engineering consultancies are consolidating specification authority for large-scale HVAC projects away from distributor channels.
China
Dual carbon goals and GB standards for building energy conservation are accelerating demand for high-performance insulation in commercial construction across the Yangtze River Delta. The Ministry of Ecology and Environment enforces emissions controls on thermosetting resin production that elevate manufacturing complexity. Shanghai and Shenzhen developers are integrating fiberglass duct wrap into green building certification portfolios at expanding scale.
India
Commercial building stock expansion in Maharashtra and Karnataka is creating specification opportunities for condensation control in cooling-intensive HVAC systems. The Bureau of Indian Standards and state-level energy conservation codes are gradually tightening thermal performance requirements for mechanical systems. Mumbai and Bengaluru contractors are specifying factory-applied vapor retarder systems for high-humidity climate applications.
Canada
Cold climate HVAC applications in Ontario and Quebec are prioritizing thermal resistance and vapor barrier integrity for heating-dominated mechanical systems. Health Canada and the National Energy Code of Canada for Buildings establish certification requirements for insulation products in commercial construction. Toronto and Montreal retrofit markets are absorbing higher-density fiberglass wrap as energy code compliance deadlines approach.
Fiberglass Duct Wrap Insulation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with specification-controlled commercial projects favoring established building science brands while commodity retrofits accommodate regional fabricators. The market exhibits moderate consolidation around integrated glass fiber producers with captive resin formulation capabilities. Three archetypes dominate: multinational building materials conglomerates with full vertical control, regional insulation specialists serving mechanical contractor networks, and private-label converters supplying distribution channels. Competitive maneuvering centers on backward integration into raw glass fiber supply and strategic partnerships with MEP engineering firms to secure specification lock-in.
Among North American building materials conglomerates, Owens Corning, Johns Manville, and Knauf Insulation occupy positions that exemplify the integrated-manufacturer archetype. Owens Corning represents specification-channel dominance through building science expertise and mechanical infrastructure focus. Johns Manville anchors manufacturing scale advantages across multiple production facilities. Knauf Insulation sits within the diversified-portfolio tier, leveraging integrated mineral wool and fiberglass capabilities to address varied HVAC application requirements. These three entities collectively illustrate how raw material integration and engineering relationships determine competitive position in code-driven markets.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| Knauf Insulation |
| CertainTeed |
| Manson Insulation |
| Mag-Isover |
| Frost King & Thermwell Products |
| GAF |
| Lamtec Corporation |
| Others |
Cost & Logistics Intelligence
Mechanical contractor labor pools concentrated across Texas, Florida, and Arizona metropolitan areas compress installation cost differentials that separate premium specification tiers from commodity retrofit pricing. ASHRAE Standard 90.1 compliance burdens and EPA formaldehyde emissions requirements widen spreads between certified high-R-value products and bare insulation substrates as manufacturers pass regulatory compliance costs downstream.
Pricing Analysis
Distributor margin layers capture specification-controlled commercial projects through MEP engineering firm relationships, while direct-to-mechanical-contractor channels absorb price compression in high-volume retrofit markets. Pricing stratifies across premium factory-applied smart vapor retarder systems, standard foil-faced blanket configurations, and economy bare insulation substrates driven by certification grade and thermal performance tier. Cost compression in economy tiers intensifies as regional fabricators compete for facility manager maintenance-driven replacement volume. Price sensitivity concentrates among construction contractors receiving pre-specified thermal performance packages, while insulation specialists demonstrate lowest sensitivity in complex cold storage and industrial process applications.
Supply Chain Analysis
Reverse-logistics flows for fiberglass duct wrap remain minimal given the disposable nature of insulation materials, though job-site waste reclamation programs are emerging in California and New York jurisdictions with construction debris diversion mandates. Manufacturing concentration centers on the United States, Germany, and China where established glass fiber infrastructure supports captive resin formulation capabilities. Raw material dependencies rest on molten glass production, thermosetting binder chemicals, and reinforced facing substrates. Single-source vulnerability in formaldehyde-compliant resin supply elevates risk exposure for manufacturers without backward integration into chemical production. Distribution runs through mechanical insulation distributors serving regional contractor networks, with specification channel control shifting toward direct manufacturer relationships with MEP engineering firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the shift toward higher R-value products in Sun Belt commercial retrofits as energy code compliance deadlines compress specification refresh cycles.
For Market Incumbents: Lock in specification authority with MEP engineering firms through building science expertise and automated thermal modeling tool partnerships. Deepen backward integration into formaldehyde-compliant resin supply to defend cost position against mineral wool substitution threats. Expand manufacturing scale in Texas and Florida to capture accelerating demand in cooling-dominated HVAC markets. For New Entrants and Emerging Players: Regional insulation specialists serving mechanical contractor networks represent an underserved buyer archetype with fragmented loyalty and compressed certification timelines. Penetrate the soundproofing application segment where dual-function thermal-acoustic systems command premium positioning with limited established competition. Pursue private-label converter relationships with national distribution chains seeking shorter lead times for facility manager maintenance-driven replacement volume. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators without captive glass fiber supply facing margin compression from raw material volatility. Long-term viability over the medium-term projection horizon favors integrated manufacturers with specification channel control and backward integration into molten glass production. Monitor ASHRAE Standard 90.1 adoption cascades across U.S. jurisdictions as the inflection indicator for accelerated specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive formaldehyde-compliant binder production defends cost position against EPA emissions constraints. |
| Smart Vapor Retarder Technology Launch | Variable permeance facings automate moisture management and compress engineering review timelines for Sun Belt specifications. |
| MEP Engineering Firm Partnership | Direct specification relationships consolidate channel control as procurement authority shifts upstream from distributors. |
| Texas Manufacturing Footprint Expansion | Proximity to Houston and Dallas-Fort Worth construction markets reduces logistics costs for high-volume commercial retrofits. |
| Cold Storage Application Development | Multifunctional insulation requirements in refrigerated warehousing extract premium pricing versus commodity HVAC specifications. |
Research Approach
Multiple input streams — primary interviews with mechanical contractors, MEP engineering firms, and insulation distributors; secondary validation through ASHRAE documentation, EPA emissions filings, and state energy code adoption records; plus customs and trade data for glass fiber raw materials — were reconciled through bottom-up and top-down triangulation. Plant managers at fiberglass manufacturing facilities, procurement leads at mechanical contracting firms, technical R&D directors at resin suppliers, and specification sales executives at building materials conglomerates provided qualitative demand and competitive intelligence. Secondary sources included International Energy Conservation Code adoption databases, OSHA workplace safety guidelines, and manufacturer product certification filings.
Data-stream reconciliation across product configuration, application vertical, end-user procurement authority, and installation method dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value buildups validated against macro construction indicators and HVAC equipment shipment trends. Modeled inputs incorporated climate zone cooling-degree-day differentials, energy code compliance deadline schedules, and formaldehyde emissions standard enforcement timelines.
Inputs from mechanical contractor interviews and state regulatory filings were available through the study window; gaps in real-time distributor inventory positioning introduce uncertainty bands around short-term demand fluctuation estimates. Forecasts reflect documented assumptions regarding code adoption velocity and raw material supply stability. Practitioners should monitor ASHRAE Standard 90.1 jurisdiction-level adoption triggers and EPA formaldehyde emissions enforcement actions for early signals of specification and cost structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Technical Foam Market
Insulation Materials
France Foam Insulation Market