
 Refrigeration Insulation Materials Market | 2026-2036
Refrigeration Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration Insulation Materials Market Intelligence
China's rapid expansion of cold storage capacity is rewriting the supply chain for high-performance insulation materials. Kingspan Group leverages its expertise in advanced, prefabricated panel systems for rapid deployment in large-scale warehouses. Dow Inc. competes on the chemical formulation of its polyurethane foams, offering customized solutions for industrial freezers. Meanwhile, Saint-Gobain positions itself through a diversified portfolio that serves both new construction and retrofit projects across multiple end-user segments.
Refrigeration insulation materials are specialized substances engineered to minimize thermal energy transfer in low-temperature environments, thereby reducing energy consumption. Performance is measured by thermal conductivity and R-value per inch, with materials like vacuum insulation panels offering superior resistance. Polyurethane foam remains the dominant product type due to its cost-effectiveness, while extruded polystyrene is favored in cold storage warehouses. However, aerogel and phenolic foam are gaining traction in specialized pharmaceutical storage applications where space and fire resistance are critical.
Regulations such as the European Union's F-Gas Regulation and the US EPA's SNAP program are forcing a transition toward blowing agents with lower global warming potential. Energy efficiency standards for commercial buildings in countries like Germany and Japan also mandate higher performance levels for insulation. The key decision for manufacturers is whether to invest in developing new material chemistries or focus on optimizing existing foam technologies for better compliance and thermal performance.
Market Dynamics
The central tension in the refrigeration insulation market is the collision between stringent environmental regulations, like the EU's F-Gas rules, and the urgent need for rapid cold chain infrastructure expansion, particularly in China, forcing accelerated innovation in material chemistry.
Growth Catalysts
- Pharmaceutical Cold Chain Integrity:The global expansion of biologics and vaccine distribution networks requires ultra-reliable, high-performance insulation to maintain strict temperature ranges, directly stimulating demand for materials like phenolic foam and vacuum insulation panels.
- EU F-Gas Regulation:This legislative framework is forcing the phase-out of high GWP blowing agents, creating a direct catalyst for the development and adoption of insulation formulated with environmentally benign alternatives like HFOs and CO2.
- Food E-commerce Expansion:The proliferation of online grocery and meal-kit delivery services necessitates advanced insulation for refrigerated vans and last-mile cold boxes, opening a significant market for materials optimized for mobile applications.
Market Restraints
- Chemical Feedstock Volatility:The prices of core polyurethane components, specifically MDI and polyols, are subject to significant fluctuation based on petrochemical market dynamics, creating cost uncertainty for foam manufacturers.
- Performance Trade-offs:Enhancing one material property, such as adding fire retardants to polyurethane foam, can negatively impact other key metrics like thermal conductivity or increase processing complexity and cost.
- High Capital Cost of VIPs:While offering superior thermal resistance, vacuum insulation panels (VIPs) have a much higher upfront cost and are more susceptible to damage during installation, limiting their use to niche, high-value applications.
Strategic Opportunities
- Bio-Based Formulations:Developing and commercializing polyols derived from renewable feedstocks like soy or recycled PET presents an opportunity to capture demand from customers with strong corporate sustainability mandates.
- Aerogel-Foam Composites:Integrating aerogel particles into traditional foam matrices offers a pathway to create next-generation hybrid insulation with superior thermal performance and fire resistance for specialized applications like LNG transport.
- Indian Cold Storage Modernization:Underdeveloped cold chain infrastructure in India represents a major growth frontier, with government incentives and private investment poised to drive large-scale demand for warehouse insulation panels.
Industry Challenges
- Blowing Agent Transition Complexity:Migrating production lines from HFC to new low-GWP blowing agents like HFOs requires significant capital investment in equipment and implementation of new safety protocols to handle their increased flammability.
- Installation Skill Gaps:A persistent shortage of certified technicians for the proper on-site application of spray polyurethane foam (SPF) acts as a bottleneck, particularly in the building retrofit and commercial construction sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration Insulation Materials Market |
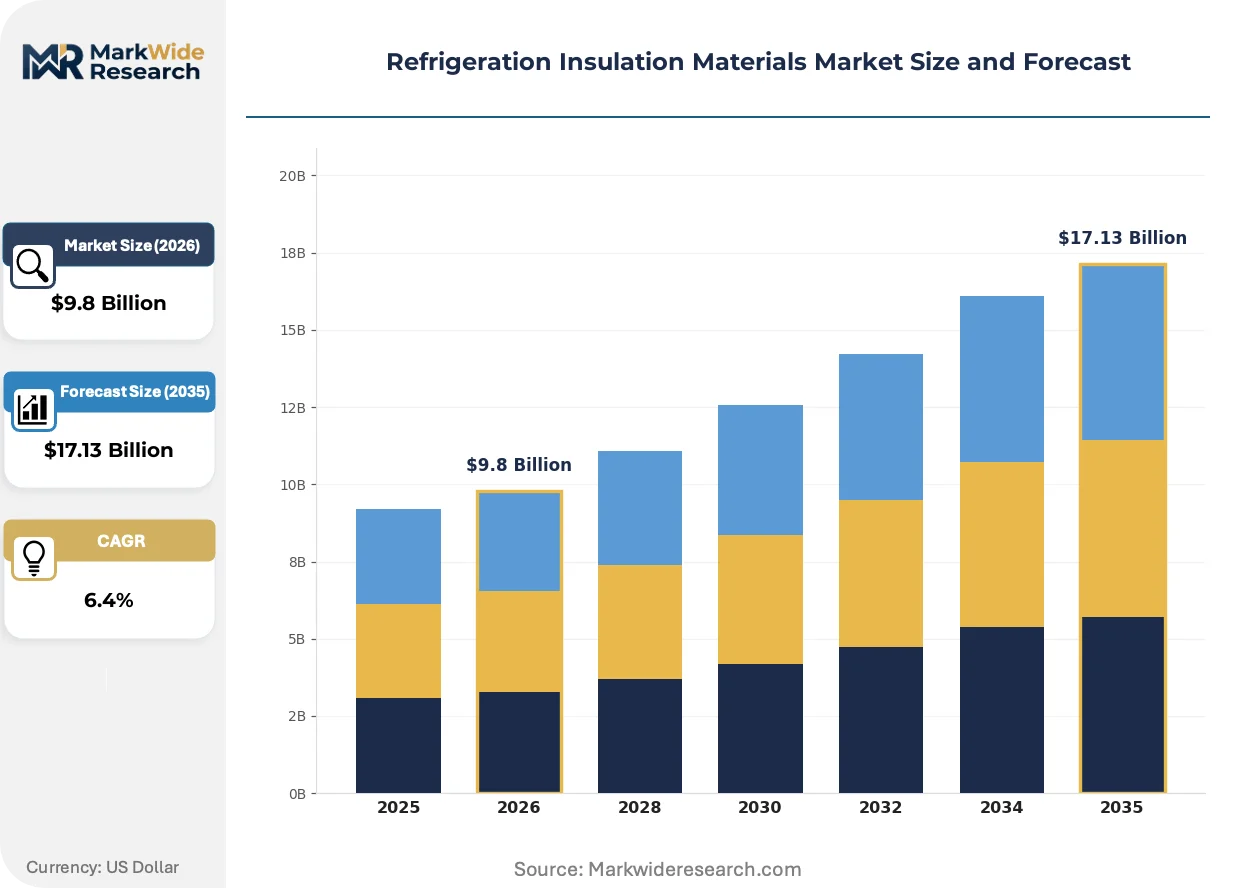
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Extruded Polystyrene, Vacuum Insulation Panels, Phenolic Foam, Aerogel, Expanded Polystyrene Application: Cold Storage Warehouses, Transport Refrigeration Units, Commercial Refrigerators, Industrial Freezers, Pharmaceutical Storage, Food Processing Plants Installation Type: New Construction, Retrofit Projects, Portable Units, Modular Systems End User: Logistics Providers, Food & Beverage Manufacturers, Pharmaceutical Companies, Retail Chains |
| Companies Covered | Johns Manville, Dow Inc., Armacell International, Knauf Insulation, Rockwool, Owens Corning, BASF SE, Saint-Gobain, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration Insulation Materials Market Strategic Shifts & Innovations
The convergence of energy efficiency mandates and environmental compliance is pushing material science beyond thermal resistance alone. Innovation is now centered on creating intelligent, sustainable, and system-integrated insulation solutions that contribute to overall building performance and lifecycle cost reduction.
Smart insulation panels embedded with fiber-optic or thermocouple sensors provide real-time thermal monitoring. Large-scale cold storage operators and pharmaceutical logistics firms are early adopters, seeking to prevent product loss. This integration of data capture is digitizing the building envelope, converting a passive material into an active component of a facility's energy and risk management system.
Regulations such as the US EPA's Significant New Alternatives Policy (SNAP) program are fundamentally altering foam chemistry. The policy mandates the phase-down of hydrofluorocarbons (HFCs) as blowing agents due to their high global warming potential. Polyurethane and polystyrene foam producers must invest in reformulating products using next-generation agents like hydrofluoroolefins (HFOs), impacting both material costs and manufacturing processes.
Specification patterns are evolving from purchasing individual material components to demanding fully integrated, prefabricated panel systems. This shift disrupts the traditional construction model by favoring suppliers who can deliver a complete, factory-finished building envelope solution. The trend is most visible in the rapid construction of data centers in Northern Europe and hyperscale cold storage facilities across Asia.
Refrigeration Insulation Materials Market Segmentation
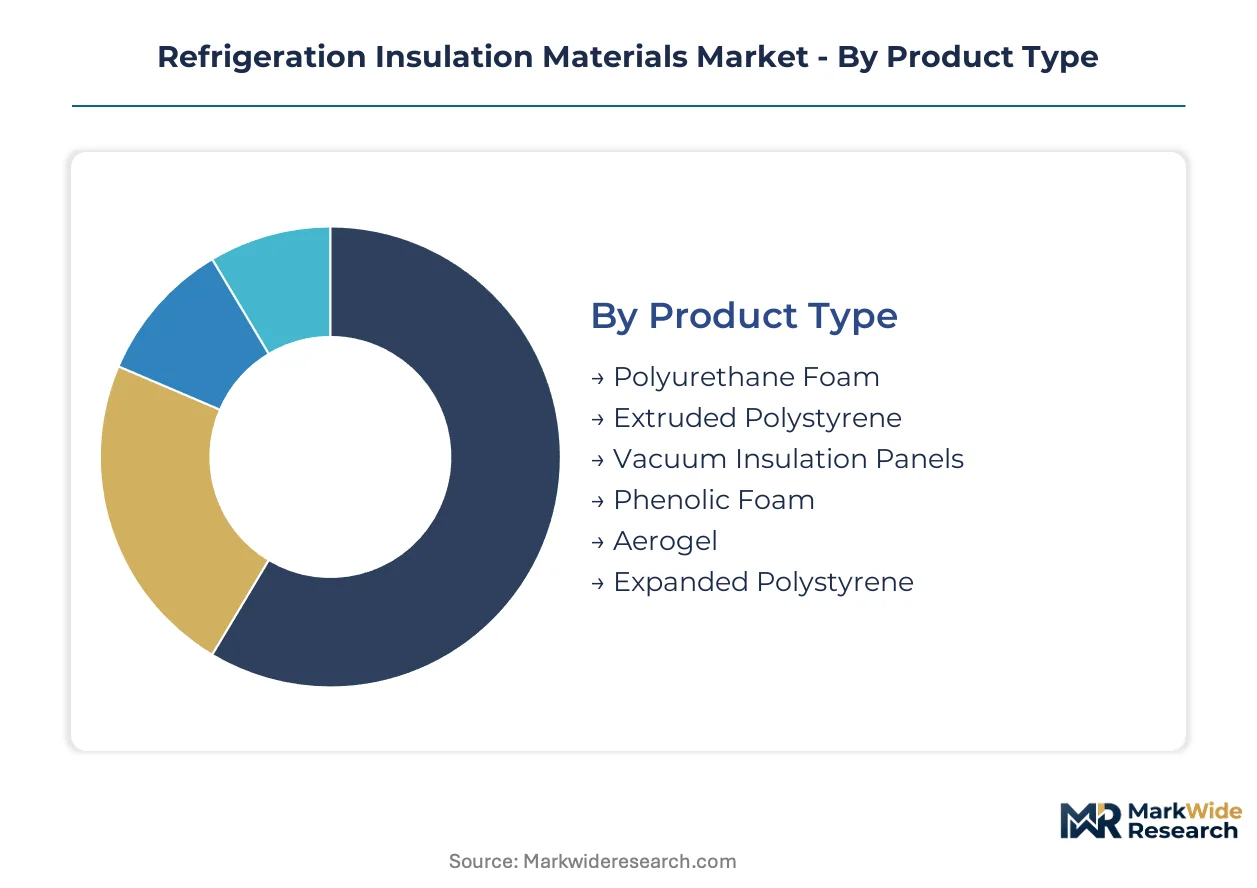
The refrigeration insulation materials market exhibits diverse requirements driven by varied end-use applications and regulatory pressures. Understanding this segmentation clarifies how material properties, installation methods, and customer needs influence product development and market penetration strategies across different industry verticals.
Product Type:
Material composition defines performance across the refrigeration insulation market.
- Polyurethane Foam:This material remains dominant due to its cost-effectiveness and versatile thermal performance. Demand concentrates in cold storage warehouses and commercial refrigerators, driven by ongoing energy efficiency needs.
- Vacuum Insulation Panels:These panels offer superior thermal resistance within minimal thickness, making them ideal for space-constrained applications. Demand concentrates in high-value pharmaceutical storage and mobile transport units, where space and precise temperature control are critical.
- Extruded Polystyrene:Its closed-cell structure provides good moisture resistance and structural integrity. This material is widely favored in cold storage warehouses for flooring and wall insulation.
- Phenolic Foam:Offering excellent fire resistance alongside strong thermal performance, phenolic foam is utilized in specialized pharmaceutical storage and high-specification cold rooms.
- Aerogel:Known for ultra-low thermal conductivity, aerogel is applied in niche, high-performance insulation solutions. Its use cases include specialized cryogenics and high-value equipment insulation.
- Expanded Polystyrene:A cost-effective and lightweight insulation material, expanded polystyrene is commonly used in basic cold chain packaging and smaller, less demanding refrigeration units.
Polyurethane Foam holds installed capacity. Vacuum Insulation Panels are rotating up the share rankings.
Application:
End-use environments dictate the specific insulation requirements and material choices.
- Cold Storage Warehouses:These large-scale facilities require robust, cost-effective insulation panels for maintaining consistent temperatures over vast areas. Demand is accelerating in China due to massive government-backed cold chain infrastructure expansion.
- Pharmaceutical Storage:This segment demands ultra-precise temperature control and often requires enhanced fire resistance for sensitive products. Demand for advanced materials like phenolic foam and VIPs is driven by global biologics and vaccine distribution networks.
- Transport Refrigeration Units:Mobile applications in refrigerated vans and trucks demand lightweight and durable insulation solutions. These units are critical for last-mile delivery services, especially for food e-commerce.
- Commercial Refrigerators:Retail display units and back-of-house storage require efficient insulation to meet energy consumption standards. Material selection here balances performance with cost and aesthetic integration.
- Industrial Freezers:Operating at very low temperatures, these units need high-performance, robust insulation capable of withstanding extreme conditions. Customized polyurethane foams provide effective solutions for these demanding environments.
- Food Processing Plants:These facilities maintain strict hygiene and temperature stability during production and storage. Insulated panels are crucial for preventing spoilage and ensuring compliance with food safety regulations.
The cold chain expansion in Asia is accelerating demand for warehouse insulation. Pharmaceutical cold chain integrity drives material innovation.
Installation Type:
The method of deployment influences material form factors and project timelines.
- New Construction:This category encompasses large-scale projects like data centers and hyperscale cold storage facilities. Prefabricated panel systems are favored for rapid deployment, consistency, and structural integrity.
- Retrofit Projects:These involve upgrading existing structures to improve energy efficiency and meet evolving regulatory compliance. Often, retrofit applications utilize spray foam or custom-cut insulation panels to adapt to existing building envelopes.
- Portable Units:Small-scale, mobile refrigeration solutions for temporary storage or specialized transport fall into this segment. These units demand lightweight and compact insulation materials for ease of movement.
- Modular Systems:Factory-built, scalable units allow for quick setup and expansion of cold storage capacity. These systems rely on standardized insulation panels for efficient assembly and consistent performance.
Government incentives for energy efficiency are expanding retrofit project volumes. Modular systems are gaining traction for rapid deployment needs.
End User:
The primary business function of the customer dictates specific performance and regulatory compliance needs.
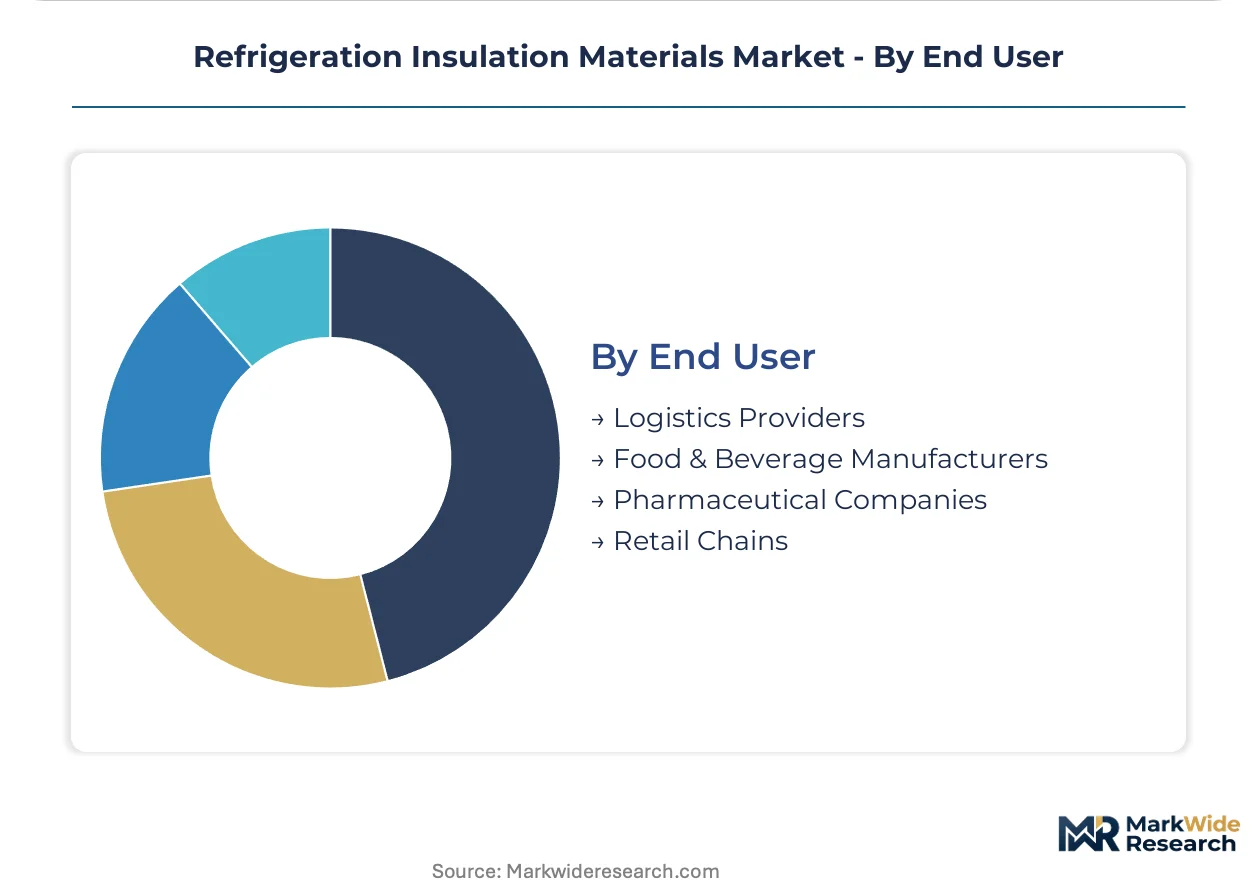
- Logistics Providers:These companies operate extensive cold chain networks, including warehouses and transport fleets. They prioritize durable, energy-efficient insulation to minimize operational costs and ensure product integrity during transit and storage.
- Pharmaceutical Companies:This segment requires stringent temperature control for sensitive products, often necessitating specialized insulation materials. Demand is for high-performance solutions like phenolic foam and VIPs to ensure product efficacy and regulatory compliance.
- Food & Beverage Manufacturers:These entities need insulation for processing areas, storage facilities, and distribution channels. Their focus is on hygienic, moisture-resistant materials that meet food safety and quality standards.
- Retail Chains:Retailers utilize insulation for in-store refrigeration, display cases, and backroom cold storage. Energy efficiency, aesthetic integration, and compliance with local environmental regulations are key considerations for these customers.
Expansion of e-commerce is intensifying demand from logistics providers. Pharmaceutical companies are driving innovation in high-performance materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's government-backed cold chain expansion significantly drives demand for refrigeration insulation materials. The European Union's F-Gas Regulation also accelerates the shift towards environmentally benign alternatives, influencing material development. These regulatory and infrastructure developments create distinct regional market dynamics.
China
China's massive government-backed expansion of its national cold chain logistics network fuels demand for insulation panels. The nation's dual carbon goals promote energy-efficient construction practices. Large-scale cold storage facilities are rapidly deploying across the Yangtze River Delta.
Germany
Germany's stringent energy efficiency standards for commercial buildings mandate higher performance levels for insulation. The EU F-Gas Regulation directly impacts blowing agent choices for foam manufacturers. Specialized pharmaceutical storage applications in Bavaria require advanced materials.
United States
The United States sees sustained demand from expanding food e-commerce and pharmaceutical cold chains. The US EPA's SNAP program forces a transition to low-GWP blowing agents. New data centers and logistics hubs in California require advanced prefabricated panel systems.
India
India's significant cold storage modernization initiatives represent a major growth frontier. Government incentives and private investment drive the construction of new temperature-controlled warehouses. Large-scale cold storage projects in Maharashtra create substantial demand for panels.
Japan
Japanese energy efficiency standards for commercial refrigerators and industrial freezers drive demand for high-performance insulation. METI promotes sustainable building practices and material innovation. The Tokyo metropolitan area experiences steady demand for efficient insulation.
Refrigeration Insulation Materials Market Key Industry Players
Integrated solutions providers and specialized material science firms split the refrigeration insulation market. The industry exhibits a tiered structure, with large players offering comprehensive systems alongside niche innovators. Key strategic archetypes include those focused on prefabricated panel systems and chemical formulation specialists. Dominant competitive moves involve significant investment in material chemistry R&D and strategic capital deployment for production technology upgrades.
Within the integrated solutions provider archetype, Kingspan Group occupies a strong position, leveraging its expertise in advanced prefabricated panel systems for rapid deployment. Dow Inc., a global chemical company, represents a material science specialist, focusing on the chemical formulation of its polyurethane foams for customized industrial applications. Saint-Gobain, a diversified building materials group, serves both new construction and retrofit projects across multiple end-user segments. These companies anchor different segments of the value chain, driving innovation through their distinct approaches.
| Leading Market Players |
|---|
| Johns Manville |
| Dow Inc. |
| Armacell International |
| Knauf Insulation |
| Rockwool |
| Owens Corning |
| BASF SE |
| Saint-Gobain |
| Kingspan Group |
| Others |
Cost & Logistics Intelligence
The Asia-Europe freight corridor's cost dynamics directly influence the pricing of insulation materials, particularly given manufacturing concentration in China, which then impacts price differentiation for specialized products across global markets.
Pricing Analysis
Geographic price spreads for refrigeration insulation materials vary significantly, reflecting regional demand and regulatory compliance costs. The dominant pricing structure involves contract-based long-term offtake for large-volume projects and per-unit transactional pricing for specialized or smaller orders. Price differentiation stems from R-value performance, specific fire resistance certifications, and customization levels for industrial applications. Pricing softness is evident in commodity-grade foams due to feedstock volatility, while high-performance materials for pharmaceutical storage maintain premium pricing. Cold storage warehouse operators often exhibit higher price sensitivity compared to pharmaceutical logistics providers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly critical for managing cash flow among insulation material suppliers, particularly those sourcing raw materials globally. The supply chain for refrigeration insulation materials concentrates in China for extruded polystyrene and polyurethane foams, with specialized chemical components often sourced from Germany and the United States. Raw material dependencies include MDI and polyols for polyurethane, alongside advanced blowing agents like HFOs and CO2. Commodity price volatility for petrochemical feedstocks presents a structural risk. Distribution runs through direct sales channels to large construction firms and OEMs, complemented by specialized distributors for retrofit projects and mobile units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is undergoing high-growth disruption, primarily driven by the EU's F-Gas Regulation and the concurrent need for advanced cold chain infrastructure globally.
For Market Incumbents:Build a regulatory compliance moat by accelerating investment in low-GWP blowing agent technologies, such as HFOs and CO2, to mitigate the threat of stringent environmental regulations. Consolidate market share through strategic acquisitions of specialized material science firms focused on aerogel or vacuum insulation panels. Leverage existing production scale to drive down costs for sustainable formulations, defending against emerging material chemistries and margin pressure from feedstock volatility.
For New Entrants and Emerging Players:Pursue niche applications where high-performance materials are critical and less price-sensitive, such as specialized cryogenics or mobile pharmaceutical cold boxes. The Indian cold storage modernization initiative represents a highly penetrable geography for innovative, cost-effective insulation solutions. Focus go-to-market strategies on integrated smart insulation panels that offer real-time thermal monitoring and data analytics, addressing the demand for active energy and risk management systems.
For Investors and Strategic Acquirers:High-performance material specialists and cold chain technology integrators represent attractive long-term viability within the refrigeration insulation market. Target companies with proprietary bio-based formulations or advanced aerogel-foam composite technologies for their superior sustainability and performance profiles. The signal to watch is the accelerated adoption rate of HFOs in new construction projects, indicating a broader market shift towards compliant and efficient insulation solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Manufacturers must invest in sustainable production processes to meet evolving environmental mandates and customer demand. |
| Technology Licensing for Blowing Agents | Securing access to next-generation low-GWP blowing agents is crucial for regulatory compliance and product innovation. |
| Capacity Expansion in Asia | Increasing production capabilities in Asia directly supports the rapid build-out of cold chain infrastructure, particularly in China and India. |
| Product Launch: Aerogel-Foam Composites | Introducing hybrid insulation materials with superior thermal performance and fire resistance opens new high-value application segments. |
| Joint Venture for Smart Insulation | Collaborations to integrate sensors and data analytics into insulation panels create intelligent solutions for enhanced cold chain integrity. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with extensive secondary validation. Stakeholders included cold chain logistics managers, insulation material R&D directors, construction project managers, and regulatory compliance officers. Secondary data sources encompassed EU F-Gas Regulation documents, US EPA SNAP program reports, national cold chain development plans from China and India, and relevant industry association reports. This approach facilitated a robust bottom-up and top-down triangulation of market data.
The calibration approach integrates market sizing and forecasting across the analysis window, utilizing a proprietary analytical framework. Segmentation dimensions modeled include product type, application, installation type, end user, and blowing agent type. Compound annual growth rates were derived through a weighted average of historical trends and projected market drivers. Key forecast inputs included cold chain infrastructure investment rates in emerging economies and regulatory phase-out schedules for high-GWP hydrofluorocarbons.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new material science firms or major regulatory bodies would shift outcomes for the refrigeration insulation market. Forecasts reflect assumptions regarding feedstock price stability and the pace of technological adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Global Extruded Polypropylene Foam Market