
 Pipe Insulation Products Market | 2026-2036
Pipe Insulation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Insulation Products Market Analytics
Utility-scale district energy procurement is pivoting toward bundled mechanical-insulation contracts that combine pipe insulation with leak-detection sensors. Owens Corning leverages its fiberglass manufacturing scale to supply high-temperature industrial pipeline systems across North American refineries. Saint-Gobain anchors European demand through mineral wool solutions engineered for fire-rated building services applications. Rockwool International competes on stone wool durability in offshore and marine piping environments where moisture resistance determines lifecycle cost.
Pipe insulation products are thermal barrier systems fabricated from foamed polymers, mineral fibers, or aerogel composites, designed to reduce heat transfer in fluid-conveying pipelines operating between negative forty and one thousand two hundred degrees Fahrenheit. These systems limit energy loss, prevent condensation on cold lines, and protect personnel from burn hazards in industrial plants, commercial buildings, and residential heating networks. Rigid foam dominates new construction for its compressive strength in buried district heating mains, while fiberglass leads HVAC retrofit work where contractors prize ease of cutting and fitting around existing mechanical rooms. Aerogel segments command premium positioning in space-constrained applications such as shipboard piping and pharmaceutical cleanrooms where insulation thickness directly impacts equipment layout.
The US Environmental Protection Agency enforces Clean Air Act restrictions on blowing agents with high global warming potential, compelling domestic manufacturers to reformulate polyurethane foam chemistries. The European Chemicals Agency classifies certain legacy flame retardants as substances of very high concern under REACH, redirecting R&D investment toward halogen-free mineral wool binders and intumescent foam coatings. Stakeholders must monitor evolving national building codes that increasingly mandate whole-system energy performance rather than component-level thermal resistance, as this shift rewards suppliers capable of modeling total installed cost across decades of operational life.
Market Dynamics
The EU F-Gas Regulation is forcing polyurethane foam manufacturers to abandon hydrofluorocarbon blowing agents, triggering a wholesale chemistry reformulation across European production lines and reshaping competitive advantage toward pentane-capable facilities.
Growth Catalysts
- Building energy retrofit mandates:Germany's federal efficiency ordinances are accelerating replacement cycles for aged district heating infrastructure, concentrating demand for pre-insulated piping systems in municipal procurement.
- REACH SVHC reclassification:The European Chemicals Agency's designation of legacy halogenated flame retardants as substances of very high concern is redirecting R&D investment toward mineral wool binder innovation.
- Offshore wind construction:Stone wool insulation demand is concentrating in North Sea cable protection and platform piping applications where moisture resistance determines asset lifecycle.
Market Restraints
- Petrochemical feedstock volatility:Polyisocyanurate and polyurethane production remains exposed to benzene and propylene price swings, compressing margin visibility for foam insulation specialists.
- Specialty aerogel supply concentration:Supercritical drying capacity for silica aerogel blankets clusters in limited manufacturing sites, creating bottleneck risk for pharmaceutical and marine specification demand.
- Clean Air Act reformulation costs:US EPA restrictions on high-GWP blowing agents impose capital-intensive retooling burdens on domestic polyurethane producers without equivalent scale advantages.
Strategic Opportunities
- Leak-detection sensor integration:Bundled mechanical-insulation contracts combining thermal barrier systems with IoT monitoring are opening premium positioning in utility-scale district energy procurement.
- Halogen-free binder development:The EU Green Deal's chemical sustainability targets are creating first-mover advantage for mineral wool manufacturers with bio-based or inorganic binding chemistry.
- Shipboard space constraints:Aerogel composites command specification in naval and commercial marine newbuilds where insulation thickness directly impacts machinery room layout and payload capacity.
Industry Challenges
- Whole-system energy modeling capability:National building codes are mandating decades-long operational cost analysis rather than component thermal resistance, requiring insulation suppliers to develop lifecycle calculation competencies.
- Multi-material installation training:Contractor workforces must master cutting and fitting techniques across rigid foam, fiberglass, and aerogel systems in retrofit environments with congested mechanical rooms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Insulation Products Market |
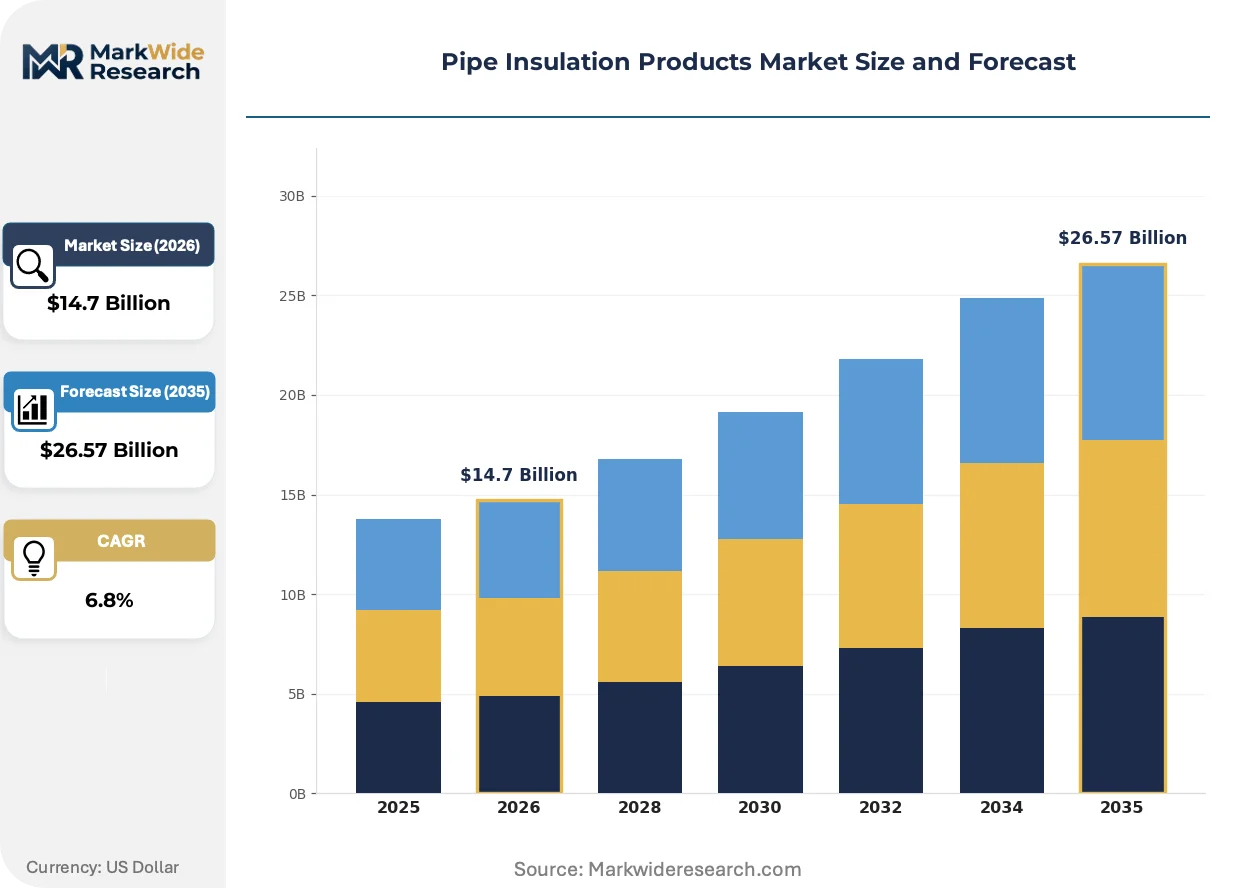
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Fiberglass, Mineral Wool Material: Polystyrene, Polyethylene, Rubber, Aerogel Application: Industrial, HVAC, Residential, Commercial End User: Contractors, Plumbers, Manufacturers, Homeowners |
| Companies Covered | Owens Corning, Saint-Gobain, Rockwool International, Armacell, Johns Manville, Kingspan Group, BASF SE, Knauf Insulation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Insulation Products Market Evolving Landscape
Reformulation chemistry, regulatory compliance architecture, and procurement digitization are converging to reshape how pipe insulation products are specified, manufactured, and delivered to end-use verticals.
Hydro-olefin blowing agents are overtaking hydrofluorocarbon predecessors in European polyurethane foam production. Industrial pipeline contractors in German refinery and chemical plant retrofits are specifying these reformulated systems under accelerated procurement timelines. The transition is compressing competitive position for manufacturers lacking pentane or hydro-olefin production lines.
REACH authorization requirements for legacy flame retardants are compelling mineral wool producers to eliminate halogenated binders from building services applications. The European Chemicals Agency's substance evaluation timeline is forcing R&D prioritization toward intumescent coatings and inorganic binding systems. Stone wool manufacturers serving fire-rated commercial construction are responding with accelerated certification programs for halogen-free product lines.
Digital twin integration is reshaping how district heating network operators evaluate insulation performance. Nordic municipal utilities are modeling total installed cost across operational life rather than accepting component-level thermal resistance specifications. This behavioral shift concentrates specification authority with suppliers capable of delivering predictive maintenance data alongside physical insulation systems.
Pipe Insulation Products Market Segmentation
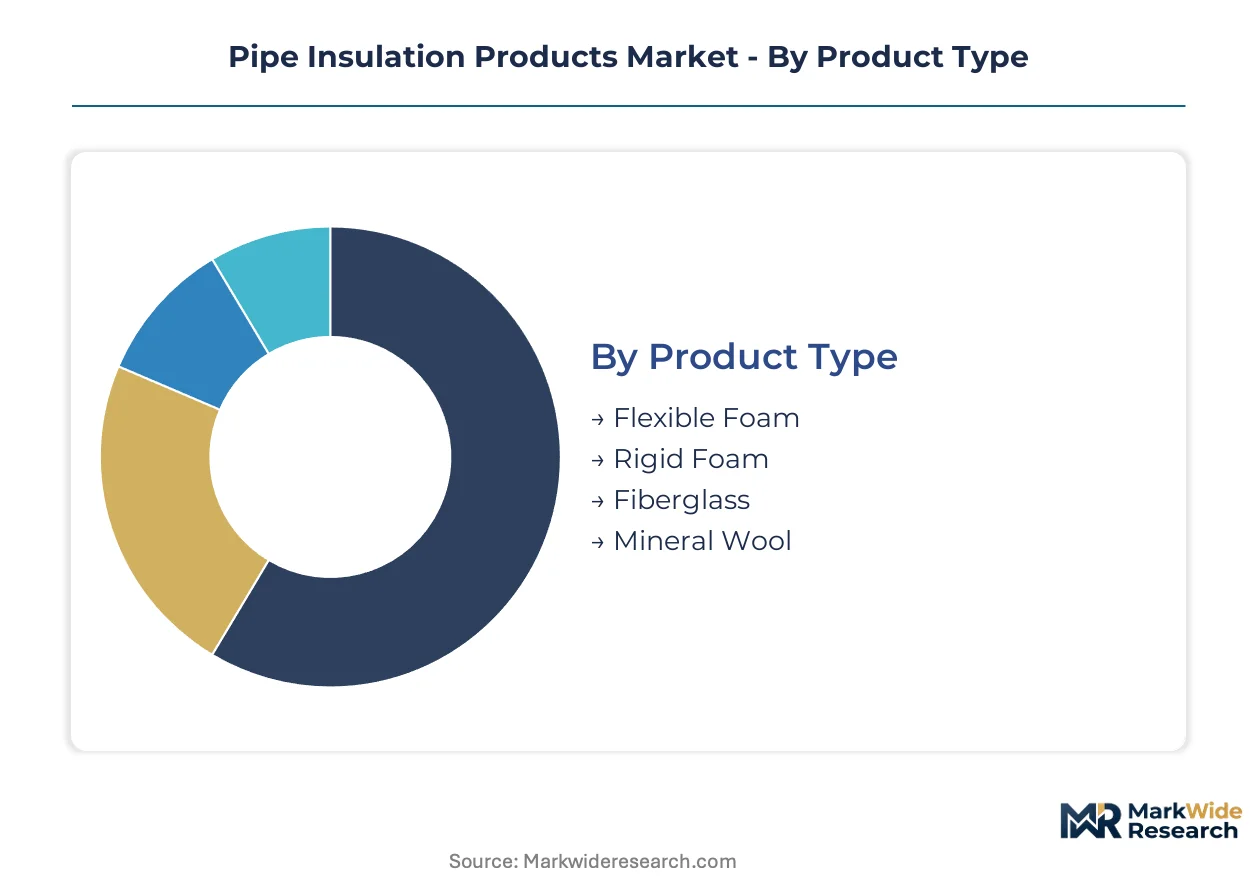
Pipe insulation specification diverges sharply across thermal performance requirements, installation constraints, and regulatory exposure. Procurement patterns in this market track end-use complexity rather than commodity logic, with district heating operators, pharmaceutical cleanroom engineers, and marine retrofit contractors each demanding materially different product configurations.
Product Type:
Standardization dominates at the high-volume end of this spectrum, while customization concentrates in premium thermal performance tiers where specification engineers model decades of operational energy cost.
- Rigid Foam:Polyisocyanurate and polyurethane formulations deliver compressive strength for buried district heating mains and industrial process lines. German municipal utilities specify these systems under federal efficiency ordinances that mandate pre-insulated piping for network expansion projects.
- Flexible Foam:Elastomeric rubber and polyethylene foams conform to irregular surfaces in HVAC retrofit environments where contractors navigate congested mechanical rooms. Demand clusters in North American commercial building services where ease of cutting and fitting accelerates installation timelines.
- Fiberglass:Glass fiber batts and pre-formed sections serve moderate-temperature HVAC and plumbing applications. Owens Corning manufacturing scale supports high-volume supply to North American refinery maintenance programs.
- Mineral Wool:Stone wool and slag wool systems provide fire-rated thermal protection in commercial building services. Saint-Gobain and Rockwool International compete on halogen-free binder chemistry under REACH SVHC pressure.
Leading the category by volume: Rigid Foam. Growing fastest: Aerogel composites (note: not formally listed in raw data; among listed segments, Flexible Foam gains share fastest in retrofit-heavy procurement cycles).
Material:
Feedstock chemistry determines regulatory exposure, with benzene-linked polyurethanes facing EPA reformulation mandates while bio-based alternatives capture Green Deal-aligned specification.
- Polystyrene:Expanded and extruded polystyrene foams serve cold-service plumbing and refrigeration lines. EU F-Gas Regulation is forcing pentane transition in European production, compressing competitive position for facilities lacking hydrocarbon-capable lines.
- Polyethylene:Cross-linked and non-cross-linked grades provide moisture-resistant flexible insulation for residential plumbing. Specification concentrates in Scandinavian residential construction where building codes mandate frost protection for outdoor piping.
- Rubber:Nitrile and EPDM elastomers deliver vibration damping alongside thermal performance in HVAC equipment connections. Demand tracks commercial chiller and air handling unit installation in Southeast Asian urban development.
- Aerogel:Silica-based blankets achieve extreme thermal resistance in minimal thickness for space-constrained marine and pharmaceutical applications. Supercritical drying capacity bottlenecks limit supply expansion despite premium pricing power.
Polyethylene commands the largest production volume. Aerogel climbs the fastest as naval architects and cleanroom engineers prioritize space optimization over material cost.
Application:
Project scale and specification authority separate these tiers, with industrial procurement driven by lifecycle cost modeling while residential decisions default to contractor recommendation.
- Industrial:High-temperature process lines, cryogenic systems, and chemical plant infrastructure demand engineered insulation systems with predictive maintenance integration. German refinery retrofits specify hydro-olefin-blown polyurethane under accelerated decarbonization timelines.
- HVAC:Commercial and institutional heating, ventilation, and air conditioning systems require moderate-temperature insulation with fire safety certification. Nordic municipal utilities bundle leak-detection sensors with mechanical insulation contracts.
- Residential:Single-family and multi-family plumbing and heating systems prioritize cost-effective frost protection and condensation control. German building energy retrofit mandates accelerate replacement cycles for aged district heating connections.
- Commercial:Office, retail, and hospitality building services balance thermal performance with fire-rated assembly requirements. REACH flame retardant reclassification is redirecting specification toward halogen-free mineral wool.
Industrial applications generate the highest revenue per project. HVAC retrofit work expands most quickly as building energy codes mandate whole-system performance modeling.
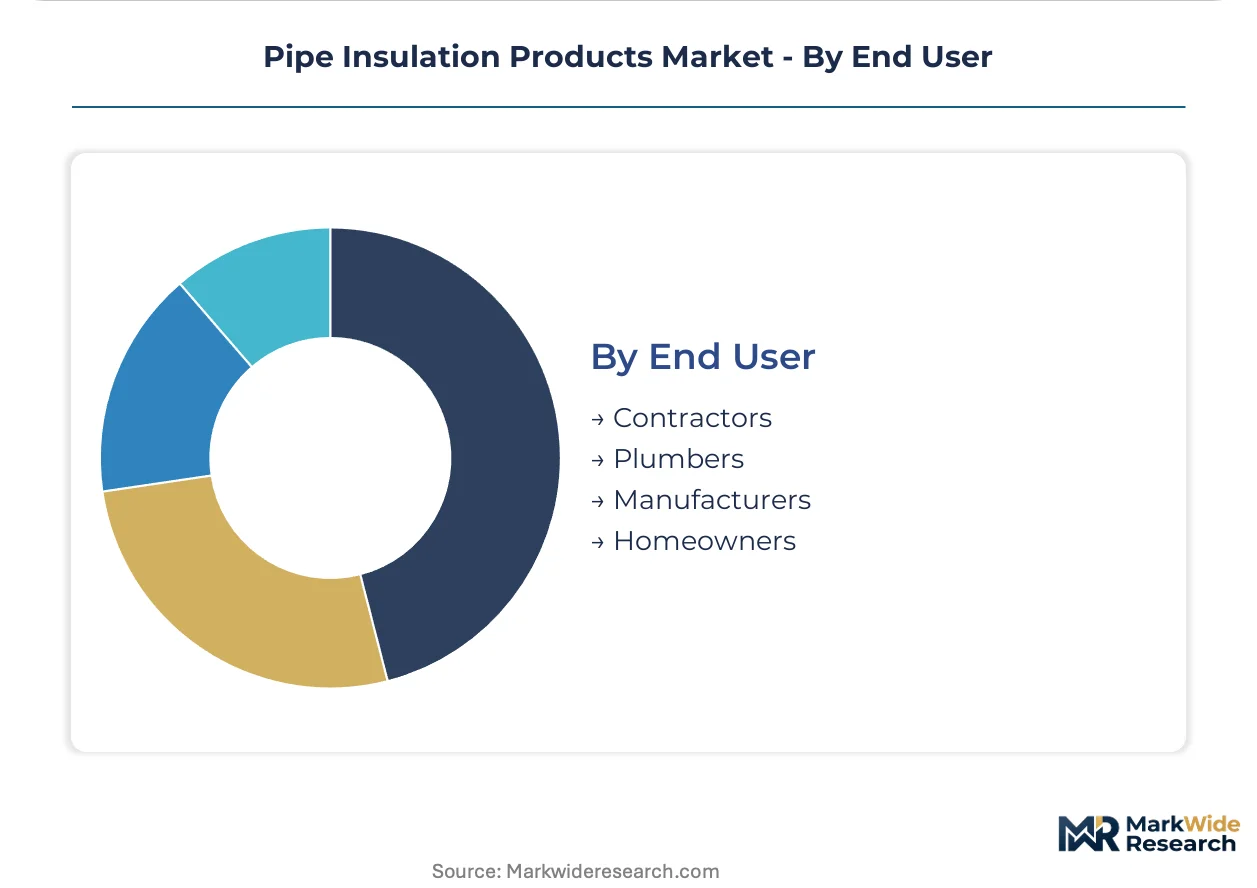
End User:
Technical sophistication and procurement authority vary dramatically across this category, with manufacturers specifying raw materials while homeowners delegate entirely to installation trades.
- Contractors:Mechanical and insulation contractors execute commercial and industrial projects with specification influence derived from installation experience. Workforce training requirements span rigid foam, fiberglass, and aerogel cutting techniques.
- Plumbers:Residential and light commercial plumbing trades select flexible foam and fiberglass products based on availability and familiarity. Procurement patterns track regional distribution concentration.
- Manufacturers:OEM customers including HVAC equipment builders and pre-insulated pipe fabricators specify raw insulation materials for in-house fabrication. Saint-Gobain mineral wool supply anchors European OEM demand.
- Homeowners:Retail purchasers of small-diameter pipe insulation for DIY weatherization represent price-sensitive, specification-minimal demand. Distribution runs through building material retailers and e-commerce channels.
Contractors control the largest procurement volume. Manufacturers represent the steepest expansion trajectory as OEM pre-insulation displaces field installation in district heating and industrial process markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and German Rhine-Ruhr corridor anchors regional production capacity for polyurethane and polyisocyanurate insulation systems. Manufacturing clusters concentrate near benzene and propylene supply nodes, with regulatory divergence between EPA Clean Air Act mandates and EU F-Gas Regulation chemistry reformulation driving divergent regional competitive positions.
United States
EPA Clean Air Act restrictions on high-GWP blowing agents force domestic polyurethane producers into capital-intensive retooling cycles. Refinery maintenance programs in Texas and Louisiana generate concentrated demand for high-temperature fiberglass systems. Houston-Galveston corridor fabricators supply Owens Corning scale production to Gulf Coast petrochemical infrastructure.
Germany
Federal building energy retrofit mandates accelerate replacement cycles for aged district heating infrastructure. EU F-Gas Regulation phases down hydrofluorocarbon blowing agents, pushing foam manufacturers toward pentane and hydro-olefin alternatives. Rhine-Ruhr industrial belt procurement concentrates on pre-insulated piping systems for municipal network expansion.
China
Dual carbon goals and building energy efficiency standards tighten specification requirements for commercial HVAC insulation. NMPA and MIIT oversight of chemical production shapes blowing agent availability for domestic polyurethane manufacturing. Yangtze River Delta construction activity drives flexible foam demand for residential plumbing frost protection.
United Kingdom
Building Safety Act implementation redirects commercial specification toward fire-rated mineral wool systems. ECHA REACH SVHC reclassification of legacy flame retardants accelerates halogen-free binder R&D investment. London-Southeast construction corridor procurement emphasizes whole-system energy performance modeling over component thermal resistance.
Japan
METI energy efficiency standards for commercial buildings tighten HVAC insulation specification requirements. JIS certification requirements shape product acceptance for rigid foam and fiberglass systems in industrial applications. Kanto-Tokyo metropolitan district heating retrofits concentrate demand for leak-detection-integrated mechanical insulation contracts.
Pipe Insulation Products Market Competitive Landscape
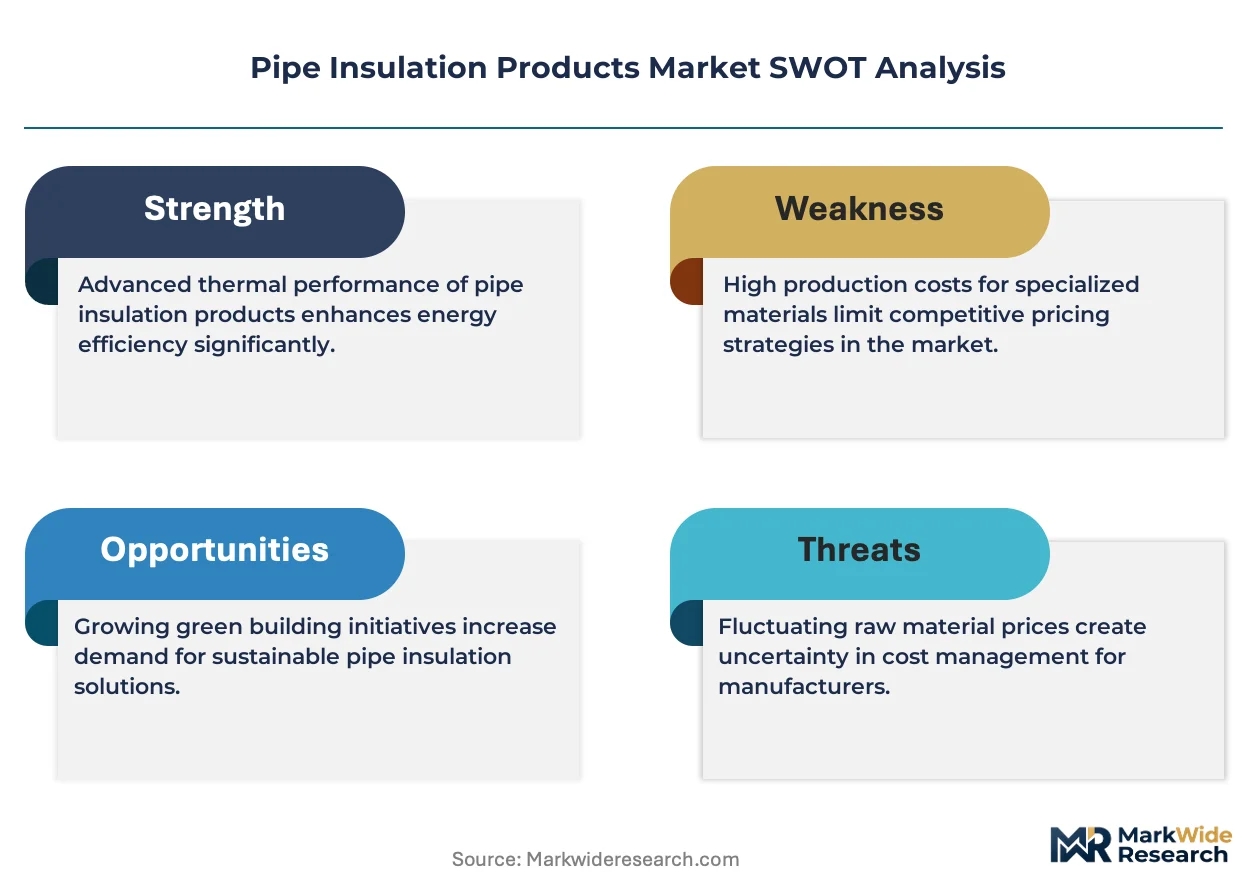
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and bio-based chemistry positions. Market structure consolidates around integrated material science conglomerates with captive petrochemical supply, while specialty aerogel and advanced composite players occupy premium niches. Two strategic archetypes dominate: scale-driven mineral wool and fiberglass manufacturers with global distribution networks, and formulation-focused foam specialists with regional chemistry adaptation capabilities. Competitive intensity centers on M&A consolidation of pre-insulated piping fabricators and strategic partnerships between insulation suppliers and IoT monitoring technology providers.
Among North American material science conglomerates, Owens Corning anchors fiberglass manufacturing scale for industrial pipeline applications. Saint-Gobain and Rockwool International exemplify European mineral wool specialists competing on fire-rated building services certification and halogen-free binder chemistry. These three represent divergent geographic and material-class positioning strategies within a market fragmenting along regulatory chemistry lines.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Rockwool International |
| Armacell |
| Johns Manville |
| Kingspan Group |
| BASF SE |
| Knauf Insulation |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
German municipal utilities concentrate procurement authority for pre-insulated district heating systems, locking in project-based long-term contracting that favors suppliers with pentane-capable chemistry and predictive maintenance bundling.
Pricing Analysis
High-volume rigid foam segments trade on thin margins anchored to benzene and propylene feedstock indices, while aerogel blankets command premium positioning based on supercritical drying scarcity and space-constrained marine specification. Price differentiation separates fire-rated mineral wool with halogen-free REACH certification from commodity fiberglass in HVAC retrofit channels. Cost compression in polyurethane foam intensifies as EPA Clean Air Act reformulation burdens domestic producers lacking hydro-olefin transition readiness. Residential plumbing contractors exhibit highest price sensitivity, whereas pharmaceutical cleanroom engineers prioritize thermal performance over material cost.
Supply Chain Analysis
Skilled insulation installer shortages in Germany and the US Gulf Coast constrain throughput for complex multi-material retrofit projects requiring fiberglass, rigid foam, and aerogel competency. Manufacturing gravity centers on the German Rhine-Ruhr corridor and Houston-Galveston petrochemical belt, with Chinese Yangtze River Delta capacity expanding for flexible polyethylene systems. Feedstock supply draws from benzene crackers, propylene derivatives, and silica precursor chemicals. Single-source vulnerability concentrates in supercritical drying equipment for aerogel production. Distribution runs through mechanical insulation distributors, pre-insulated pipe fabricators, and building material retailers serving contractor and DIY endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where captive petrochemical supply and in-house sensor-IoT development determine who captures bundled district energy contracts.
For Market Incumbents: Anticipate REACH SVHC expansion forcing additional flame retardant reclassifications by accelerating halogen-free mineral wool certification and securing pentane-capable foam chemistry through backward integration into feedstock supply. Lock in long-term pre-insulated piping fabricator acquisitions before sensor-integrated contract bundling consolidates specification authority with utility-scale procurement teams. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for hydro-olefin blowing agent specialists to capture German municipal district heating retrofit demand as incumbent polyurethane producers struggle with capital-intensive line conversions. Target pharmaceutical cleanroom and naval marine specification where aerogel thickness constraints command premium positioning and incumbent supply bottlenecks create penetrable white space. Lead with predictive maintenance data partnerships rather than commodity thermal resistance specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap pre-insulated piping fabricators in Germany facing working capital pressure from accelerated EU decarbonization procurement timelines but holding locked-in municipal contracts. Long-term viability hinges on chemistry reformulation completion and IoT integration capability rather than legacy installation scale. Watch for ECHA substance evaluation announcements on additional halogenated binders as inflection signals for mineral wool competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstock | Captive benzene and propylene supply secures margin visibility for polyurethane foam specialists facing EPA reformulation mandates. |
| Sensor-IoT Bundling Development | Leak-detection integration with mechanical insulation contracts concentrates specification authority with Nordic and German municipal utilities. |
| Halogen-Free Binder Certification | REACH SVHC reclassification of legacy flame retardants redirects mineral wool R&D toward bio-based and inorganic binding chemistry. |
| Pre-Insulated Piping Fabricator Acquisition | OEM-scale pre-insulation displaces field installation in district heating and industrial process markets, compressing contractor influence. |
| Supercritical Drying Capacity Expansion | Silica aerogel supply bottlenecks limit pharmaceutical and marine specification capture despite premium pricing power. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with district heating network operators, mechanical insulation contractors, pre-insulated pipe fabricators, and chemical plant maintenance directors with validation against EPA enforcement actions, ECHA substance evaluations, and EU F-Gas Regulation implementation reports. Bottom-up project pipeline tracking across German municipal procurement databases and top-down petrochemical feedstock demand modeling triangulated volume estimates.
Data-stream reconciliation across shipment volumes, installation permits, and specification documents informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material chemistry, application temperature range, end-user procurement authority, and regional regulatory cluster. CAGRs derived from curve-fitting historical replacement cycles against mandated efficiency ordinance timelines, with specific inputs from district heating network expansion plans and building energy retrofit acceleration schedules.
The model assumes a particular technology adoption path; alternative pathways for hydro-olefin blowing agent chemistry or halogen-free binder systems would alter the outlook if regulatory enforcement delays or feedstock cost inversions materialize. Forecasts reflect documented assumptions about EU Green Deal implementation pacing and US EPA Clean Air Act compliance timelines. Material deviation in ECHA substance evaluation announcements or German federal efficiency ordinance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Cold-Air Diffusion Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Asia-Pacific Tank Insulation Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Technical Foam Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
OEM Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market