
 North America Tank Insulation Market | 2026-2036
North America Tank Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tank Insulation Market Insights
Advanced aerogel composite layering is rewriting thermal protection protocols for cryogenic and high-temperature storage vessels across North American industrial sites. Owens Corning leverages its fiberglass manufacturing scale to supply dense-pack insulation systems for oil storage terminals along the Gulf Coast. Johns Manville sustains R&D intensity in mineral wool formulations that meet API 12B tank standards for fire resistance. ROCKWOOL International A/S anchors its North American position through stone wool products engineered for chemical processing environments.
North America tank insulation encompasses engineered thermal barrier systems—typically 50–200 mm thick layers of foam, fiberglass, mineral wool, or polyurethane—applied to above-ground and underground storage vessels to minimize heat transfer, prevent condensation, and reduce energy loss in liquid containment operations. The primary industrial purpose centers on maintaining process fluid temperatures within specified ranges while protecting structural integrity against thermal cycling and ambient weather exposure. Fiberglass dominates retrofit installations across aging oil storage infrastructure due to cost-effectiveness and established contractor familiarity, while polyurethane foam captures fastest growth in new construction segments where spray-applied seamless coverage eliminates thermal bridging at weld seams and penetrations. Mineral wool commands premium positioning in chemical storage and power generation end uses where fire resistance ratings and acoustic dampening add dual-functional value beyond pure thermal performance.
EPA emissions regulations and OSHA workplace safety standards jointly elevate insulation performance requirements for above-ground storage tanks handling volatile substances across the United States. NRC guidelines for nuclear power generation facilities in Illinois and Pennsylvania impose additional thermal qualification protocols that filter supplier eligibility. Canadian provinces reference CSA B51 boiler and pressure vessel codes alongside provincial environmental permits that mandate minimum R-values for heated water storage in industrial food processing. Stakeholders must monitor evolving state-level carbon intensity benchmarks in California and New York that threaten to recategorize insulation thickness as a reportable emissions reduction pathway rather than optional capital expenditure.
Market Dynamics
EPA energy efficiency mandates and OSHA process safety standards are compressing installation timelines and elevating material specifications for above-ground storage tanks across the United States and Canada. Refinery operators now face simultaneous pressure to retrofit aging Gulf Coast terminals while qualifying new insulation systems for chemical storage applications under tighter thermal performance thresholds.
Growth Catalysts
- OSHA Process Safety Management:Mandatory mechanical integrity programs for highly hazardous chemicals are forcing systematic insulation replacement cycles at petrochemical facilities.
- Texas-Louisiana Gulf Coast corridor:Refinery and terminal expansions are generating concentrated retrofit demand for dense-pack fiberglass systems in oil storage infrastructure.
- Polyurethane spray foam:Seamless application eliminating thermal bridging at weld seams is accelerating specification in new tank construction projects.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate price swings compress margins for polyurethane insulation contractors serving the storage tank segment.
- Specialized applicator concentration:Certified spray foam contractors cluster in Texas and Louisiana, creating regional bottlenecks for project execution elsewhere.
- Mineral wool density limitations:Stone wool's higher weight per thermal unit restricts deployment on older tank roofs with load-bearing constraints.
Strategic Opportunities
- Canadian Prairie provinces:Underpenetrated oil storage and agricultural chemical tank infrastructure present retrofit expansion potential outside the saturated Gulf Coast.
- Carbon intensity benchmarking:California and New York state-level reporting frameworks are recategorizing insulation thickness as verifiable emissions reduction infrastructure.
- Aerogel-fiberglass hybrid systems:Layering thin aerogel blankets with conventional mineral wool is opening cryogenic LNG storage applications previously closed to standard materials.
Industry Challenges
- API 12B fire certification timelines:Third-party testing protocols for mineral wool tank insulation extend product qualification cycles by 8-14 months.
- Thermal imaging technician scarcity:Infrared inspection capability required for post-installation verification outpaces certified workforce supply in the Midwest and Northeast.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tank Insulation Market |
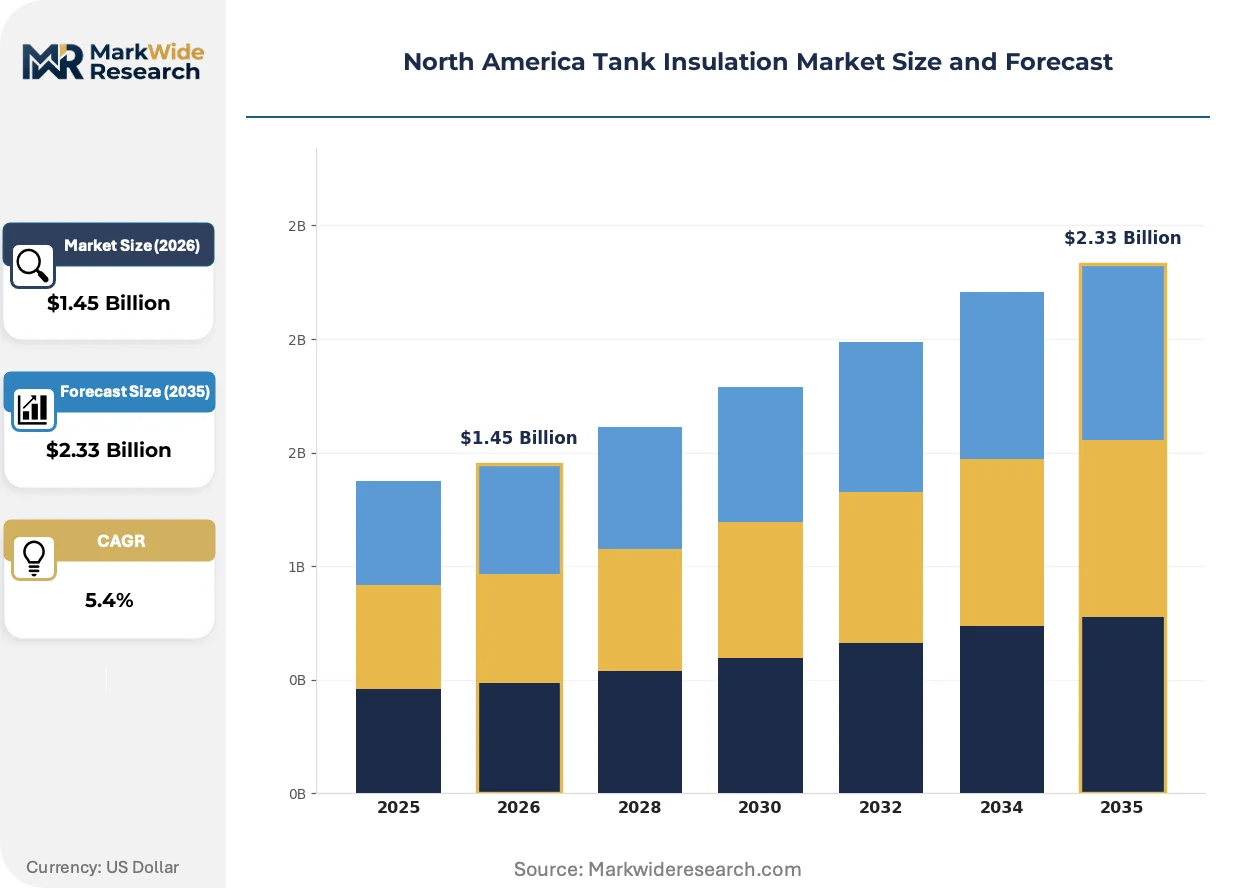
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Fiberglass, Mineral Wool, Polyurethane Application: Oil Storage, Chemical Storage, Water Heating, Food Processing End User: Industrial Facilities, Oil & Gas Companies, Pharmaceutical Plants, Power Generation Installation Type: New Construction, Retrofit, Maintenance, Custom Installation |
| Companies Covered | Owens Corning, Johns Manville, ROCKWOOL International A/S, Knauf Insulation, Saint-Gobain, Kingspan Group, Armacell LLC, Cabot Corporation, ITW Insulation Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tank Insulation Market Trends and Innovations
Material science convergence and regulatory digitization are compressing traditional specification cycles. Tank insulation procurement now demands real-time thermal performance verification rather than static R-value certificates.
Multilayer aerogel composite systems are penetrating cryogenic storage applications through sub-10 mm thickness achieving equivalent thermal resistance of 100 mm mineral wool. LNG terminal operators in Louisiana and Texas are specifying these laminates for boil-off gas reduction. The technology is digitizing thermal monitoring by embedding fiber-optic sensors directly into insulation matrices, enabling continuous heat flux measurement rather than periodic manual inspection.
EPA's updated Greenhouse Gas Reporting Program requirements for petroleum and natural gas systems are mandating documented thermal efficiency for storage tanks above 300,000 barrels capacity. Facility operators must now submit insulation specifications as part of emissions calculations. Chemical storage terminals in the Houston Ship Channel are responding by pre-qualifying suppliers against consolidated thermal and emissions performance databases.
Integrated service contracts bundling insulation installation with ongoing thermal monitoring are displacing discrete material procurement at major refinery operators. Engineering-procurement-construction firms are capturing specification authority previously held by maintenance departments. This consolidation is most visible along the Gulf Coast, where Marathon Petroleum and Valero Energy have centralized insulation vendor selection under long-term facility management agreements.
North America Tank Insulation Market Segmentation
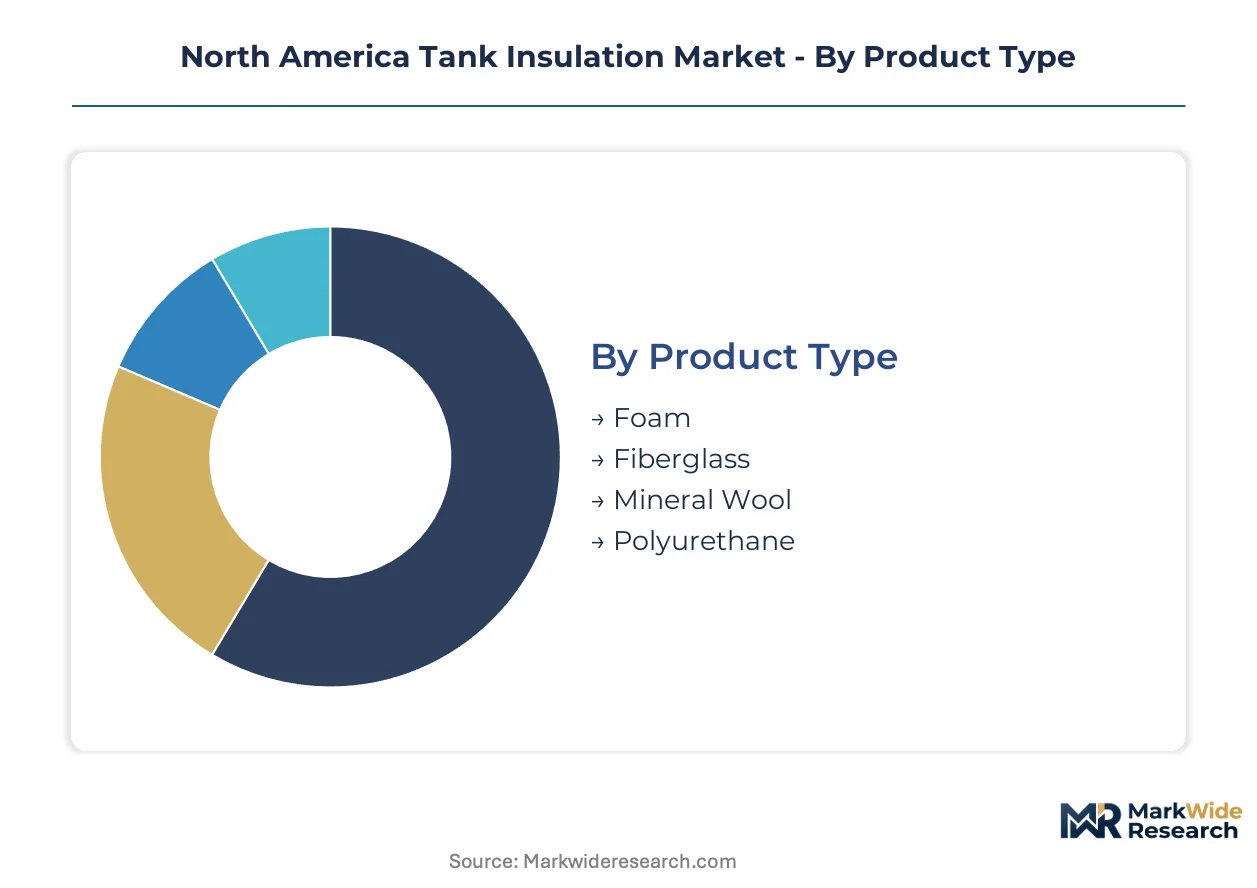
Tank insulation procurement varies sharply across product chemistry and installation context, with replacement cycles and specification complexity driving fundamentally different service models. Understanding these segment boundaries clarifies where technical consulting intensity outweighs commodity supply economics.
Product Type:
After-sales service intensity diverges dramatically by material chemistry, with spray-applied systems demanding continuous applicator certification and rigid board products requiring less frequent technical intervention.
- Foam:Rigid cellular polymers—primarily polystyrene and polyisocyanurate—deliver cost-effective thermal barriers for ambient-temperature water storage. Demand clusters in municipal and industrial water heating infrastructure across the Great Lakes states where freeze protection drives specification.
- Fiberglass:Dense-pack glass fiber systems dominate retrofit economics for aging oil storage terminals along the Texas-Louisiana Gulf Coast, where contractor familiarity and established supply chains compress mobilization timelines for tank farm operators.
- Mineral Wool:Stone wool formulations engineered for API 12B fire resistance command premium positioning in chemical processing environments.
- Polyurethane:Spray-applied seamless coverage eliminates thermal bridging at weld seams, accelerating adoption in new construction where geometric complexity rewards fluid application.
By volume, fiberglass leads. By growth pace, polyurethane is ahead.
Application:
Cost tier stratification separates commodity thermal management from specification-intensive containment where fire ratings and emissions compliance dominate procurement decisions.
- Oil Storage:Above-ground crude and refined product tanks face EPA Greenhouse Gas Reporting Program mandates for documented thermal efficiency above 300,000 barrels capacity. Gulf Coast refinery operators now bundle insulation specifications into emissions compliance submissions.
- Chemical Storage:Highly hazardous materials trigger OSHA Process Safety Management mechanical integrity programs that enforce systematic insulation replacement cycles. Houston Ship Channel terminals pre-qualify suppliers against consolidated thermal and emissions performance databases.
- Water Heating:Industrial boiler systems and heated water storage in food processing facilities reference CSA B51 codes in Canadian provinces and ASME standards in the United States.
- Food Processing:Heated storage for edible oils and syrups demands sanitary-grade jacketing systems with cleanable exterior surfaces.
Oil storage commands the largest installed base. Chemical storage posts the steepest expansion trajectory as OSHA enforcement tightens.
End User:
Customer type determines specification authority—engineering departments at integrated oil companies versus maintenance managers at independent industrial facilities.
- Industrial Facilities:Petrochemical complexes and manufacturing plants with captive maintenance crews favor long-term service contracts bundling installation with thermal monitoring.
- Oil & Gas Companies:Marathon Petroleum and Valero Energy have centralized vendor selection under facility management agreements that displace discrete material procurement.
- Pharmaceutical Plants:Temperature-sensitive active ingredient storage demands validated thermal qualification protocols with documentation burdens exceeding standard industrial practice.
- Power Generation:Nuclear facilities in Illinois and Pennsylvania operate under NRC thermal qualification protocols that filter supplier eligibility to pre-approved vendors.
Oil and gas companies drive the largest contract values. Pharmaceutical plants require the highest service touch density per dollar spent.
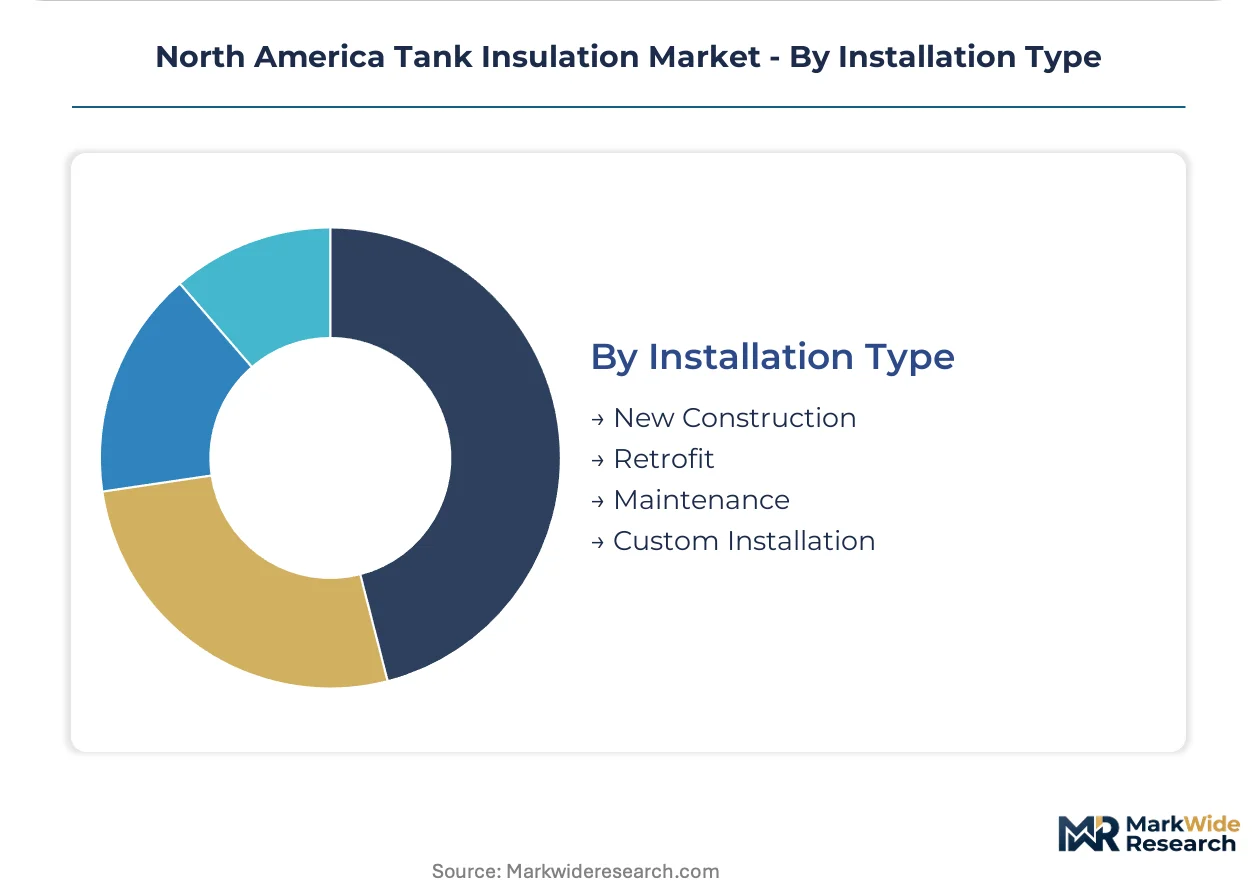
Installation Type:
Volume concentration in retrofit work contrasts with margin concentration in custom engineering for non-standard vessel geometries.
- New Construction:Greenfield tank projects specify polyurethane spray systems during fabrication, enabling seamless coverage before field assembly complicates access.
- Retrofit:Aging infrastructure replacement dominates the Texas-Louisiana corridor where refinery expansions trigger simultaneous terminal upgrades.
- Maintenance:Scheduled replacement cycles under OSHA mechanical integrity programs generate predictable revenue streams for certified contractors.
- Custom Installation:Cryogenic LNG storage and spherical pressure vessels require engineered multilayer systems with embedded fiber-optic thermal monitoring.
Retrofit work leads by project count. Custom installation captures the highest margin per thermal unit installed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian Prairie provinces export insulation-grade mineral wool to U.S. petrochemical buyers along the Gulf Coast, while Texas-Louisiana terminal operators source dense-pack fiberglass systems from domestic fabricators.
United States
EPA Greenhouse Gas Reporting Program mandates now require documented thermal efficiency for above-ground storage tanks exceeding 300,000 barrels capacity. OSHA Process Safety Management standards enforce systematic insulation replacement cycles at facilities handling highly hazardous chemicals. The Houston Ship Channel anchors the continent's densest concentration of chemical storage terminals, where operators pre-qualify suppliers against consolidated thermal performance databases.
Canada
CSA B51 boiler and pressure vessel codes establish minimum R-value requirements for heated water storage in industrial food processing across Ontario and Quebec. Provincial environmental permits in Alberta and Saskatchewan mandate thermal protection standards for oil storage infrastructure serving the Athabasca oil sands. The Prairie Provinces present underpenetrated retrofit potential for aging agricultural chemical tank infrastructure outside the saturated U.S. Gulf Coast market.
Mexico
Pemex refinery modernization programs are driving specification of polyurethane spray systems for new above-ground storage construction at Salina Cruz and Cadereyta facilities. Secretaría de Energía efficiency standards are tightening compliance requirements for petroleum product terminals along the Gulf of Mexico coast. The Tula-Villahermosa industrial corridor is attracting insulation contractor investment as domestic refining capacity expands to reduce fuel import dependence.
North America Tank Insulation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct specification tiers. The vendor base clusters around three strategic archetypes: integrated building materials conglomerates with fiberglass manufacturing scale, dedicated insulation specialists with formulated mineral wool expertise, and engineered foams providers with spray-applied system capabilities. Consolidation pressure favors long-term facility management agreements that displace discrete material procurement. Dominant competitive moves include backward integration into raw mineral fiber production and geographic expansion into underpenetrated Canadian Prairie markets.
Among North American building materials conglomerates, Owens Corning and Johns Manville exemplify the scale-driven archetype with established Gulf Coast supply chain presence. ROCKWOOL International A/S occupies a position within the fire-resistant mineral wool specialist tier, anchoring premium positioning for chemical processing applications. These three entities represent contrasting strategic postures: domestic manufacturing scale versus European-engineered specialty formulations versus integrated service bundling.
| Leading Market Players |
|---|
| Owens Corning |
| Johns Manville |
| ROCKWOOL International A/S |
| Knauf Insulation |
| Saint-Gobain |
| Kingspan Group |
| Armacell LLC |
| Cabot Corporation |
| ITW Insulation Systems |
| Others |
Pricing and Supply Chain Analysis
Polyol and isocyanate feedstock volatility compresses contractor margins for polyurethane spray systems while simultaneously widening the spread between premium mineral wool formulations and economy-grade fiberglass alternatives across the Texas-Louisiana Gulf Coast corridor. This input cost instability forces buyers into longer-term offtake contracts that reshape supplier consolidation incentives and regional distribution density.
Pricing Analysis
The technology-generation pricing gap separates next-generation aerogel-fiberglass hybrid laminates from incumbent dense-pack fiberglass and conventional mineral wool systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by fire certification grade and thermal performance tier, with API 12B-compliant mineral wool commanding substantial premiums over uncertified alternatives. Pricing pressure stems from petrochemical feedstock swings in polyurethane polyols, compressing margins for spray-applied contractors serving new construction segments. Independent industrial facilities exhibit highest price sensitivity due to discrete procurement budgets, while integrated oil and gas operators under long-term facility management agreements demonstrate lowest sensitivity through bundled service contracting.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates raw mineral fiber sourcing decisions for stone wool manufacturers serving chemical processing applications. Supply concentrates in the United States for dense-pack fiberglass fabrication, Canada for insulation-grade mineral wool extraction, and Mexico for emerging polyurethane system assembly serving Pemex modernization programs. Raw material dependencies include glass fiber feedstock, basalt and slag for stone wool, and polyol-isocyanate chemical streams. Single-source vulnerability concentrates in certified spray foam applicator pools clustered along the Gulf Coast, creating regional execution bottlenecks. Distribution runs through engineering-procurement-construction firms that have consolidated specification authority previously held by maintenance departments at major refinery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized vendor selection under long-term facility management agreements at Marathon Petroleum and Valero Energy, shifting procurement leverage from discrete material suppliers toward integrated service bundlers.
For Market Incumbents: Build switching-cost moats through embedded fiber-optic thermal monitoring systems that digitize post-installation verification and create ongoing service revenue streams. Deepen backward integration into raw mineral fiber production to insulate margin structures from Canadian export pricing volatility. Acquire certified spray foam applicator networks in the Midwest and Northeast to relieve Gulf Coast contractor concentration bottlenecks before emerging regional players capture this capacity. For New Entrants and Emerging Players: Build out aerogel composite layering capabilities for cryogenic LNG storage applications where sub-10 mm thermal performance opens specification doors closed to conventional materials. Target Canadian Prairie provinces for aging agricultural chemical tank retrofit demand outside the saturated Texas-Louisiana corridor. Pursue pre-qualification against consolidated thermal and emissions performance databases at Houston Ship Channel terminals to bypass incumbent supply relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service bundlers with captive applicator networks and real-time thermal monitoring capabilities. Long-term viability over the coming decade hinges on regulatory digitization of EPA emissions reporting and OSHA mechanical integrity verification, favoring players with data infrastructure over pure material suppliers. Monitor California and New York state-level carbon intensity benchmarking frameworks as the critical inflection signal—the recategorization of insulation thickness as verifiable emissions reduction infrastructure would fundamentally revalue installed base economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Fiber Production | Owens Corning and Johns Manville secure captive glass fiber supply against Canadian mineral wool export pricing swings. |
| Certified Applicator Network Acquisition | ROCKWOOL International A/S relieves Gulf Coast contractor concentration by building Midwest spray foam capacity. |
| Embedded Sensor Technology Development | Aerogel-fiberglass hybrid systems embed fiber-optic thermal monitoring for continuous EPA compliance verification. |
| Long-term Facility Management Agreements | Marathon Petroleum and Valero Energy displace discrete procurement through bundled installation and monitoring contracts. |
| Prairie Province Market Entry | Underpenetrated Alberta and Saskatchewan agricultural chemical tank infrastructure offers retrofit expansion outside saturated U.S. markets. |
Research Methodology
The analysis maps fiberglass, mineral wool, polyurethane foam, and aerogel composite sub-sectors, each validated through plant engineers, maintenance directors at petrochemical facilities, EPC contractor procurement leads, and thermal insulation applicators. Primary interviews with these stakeholders combined with secondary validation against EPA Greenhouse Gas Reporting Program filings, OSHA Process Safety Management enforcement records, API certification databases, and SEC 10-K disclosures from building materials conglomerates. Bottom-up project pipeline enumeration across the Texas-Louisiana Gulf Coast and top-down macroeconomic factor modeling triangulate volume estimates.
Assumptions held fixed include current EPA and OSHA regulatory enforcement intensity, existing API 12B fire certification timelines, and observed petrochemical feedstock volatility patterns. Segmentation dimensions modeled encompass material chemistry, application context across oil storage and chemical containment, end-user type from integrated oil companies to independent industrial facilities, and installation type spanning new construction through retrofit and maintenance cycles. CAGRs derive from regression analysis against historical insulation retrofit cycles and projected refinery terminal expansion schedules. Industry-specific inputs include OSHA mechanical integrity program compliance rates and EPA emissions reporting threshold adjustments for above-ground storage tank capacity tiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated EPC firms or mineral wool specialists with aerogel layering capabilities would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Radiation Shielding Materials Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Insulation Boards Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Asia-Pacific Tank Insulation Market