
 Carbon Foam Market | 2026-2036
Carbon Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Foam Market Analysis
Subscription-based thermal management audits are decoupling hardware sales from long-term client relationships in the carbon foam sector. SGL Carbon SE leverages captive carbon fiber precursor production to control feedstock quality across European aerospace programs. ERG Aerospace anchors its position through open-cell reticulated formulations optimized for molten metal filtration. Poco Graphite Inc. specializes in graphitic carbon foam with tailorable thermal conductivity for semiconductor process equipment.
Carbon foam is a cellular material derived from pitch or thermosetting resins, manufactured through controlled pyrolysis at temperatures exceeding 1,000°C to yield a graphitic or vitreous carbon skeleton with porosity exceeding 70%. Its primary industrial purpose is to provide lightweight, thermally stable structures for applications where metallic foams would oxidize or polymer foams would degrade. Rigid foam dominates current volume due to established qualification pathways in aerospace primary structures, while open-cell architectures represent the fastest-expanding category as battery manufacturers adopt them for electrode substrates. Composite panels command premium positioning because they integrate carbon foam cores with face sheets in single-source supply agreements that lock in multi-year procurement contracts.
The FAA certifies carbon foam components under flame penetration and smoke toxicity standards for commercial aircraft interiors, while the EPA monitors pyrolysis emissions under Clean Air Act permitting for domestic manufacturers. REACH compliance in Europe requires full substance registration for imported carbon foam precursors, creating a documentation burden that favors vertically integrated producers with in-house analytical laboratories. Stakeholders must track how evolving battery safety standards in multiple jurisdictions redefine thermal runaway containment specifications for electric vehicle battery packs.
Market Dynamics
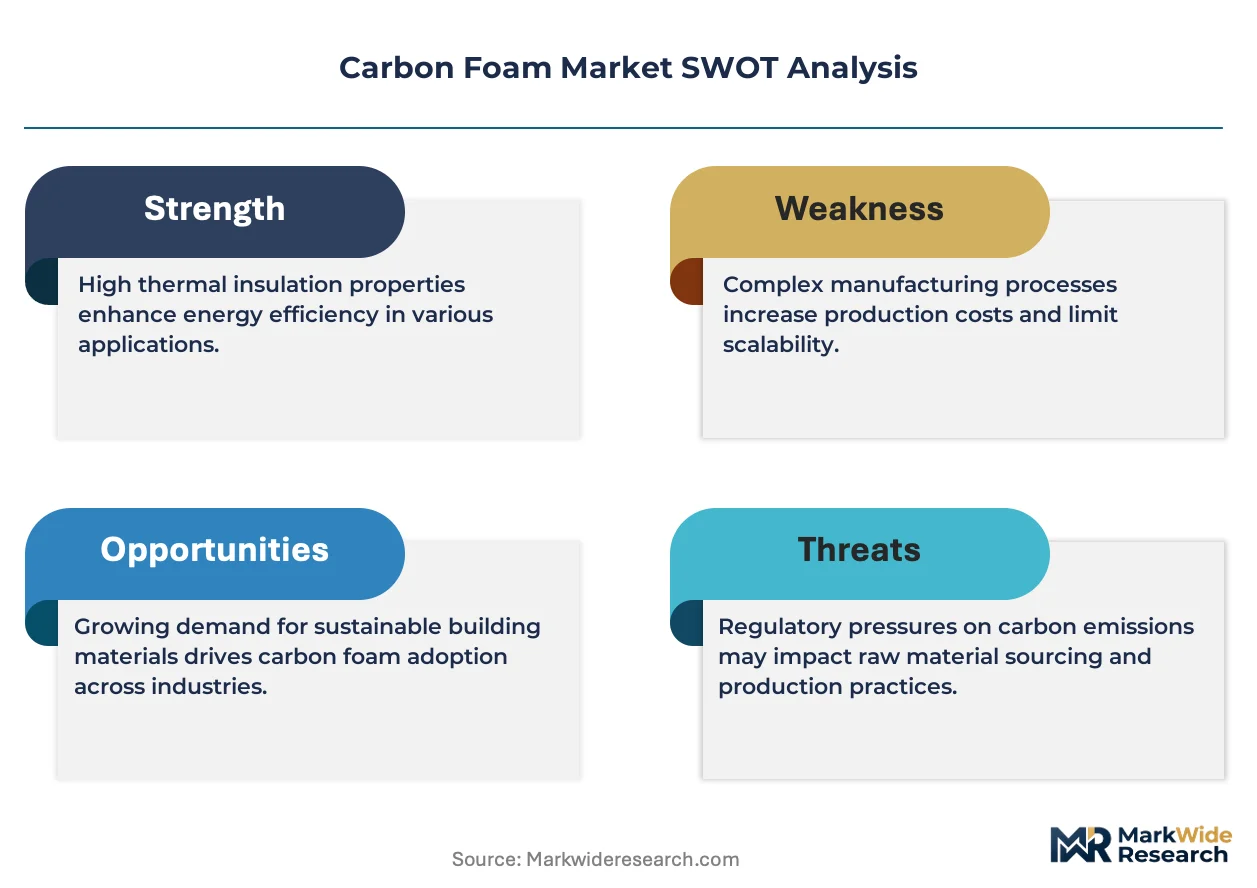
The EU F-Gas Regulation is systematically eliminating hydrofluorocarbon-based thermal insulation from aerospace and industrial applications, forcing specification engineers to requalify carbon foam alternatives across satellite thermal management and process equipment supply chains.
Growth Catalysts
- Aerospace thermal management demand:Satellite manufacturers in Germany and the United States are expanding procurement of carbon foam core materials for orbital thermal control systems. Bavaria's aerospace cluster anchors European qualification activity.
- F-Gas phase-out mandate:The EU F-Gas Regulation redirects insulation specification toward carbon foam in applications where hydrofluorocarbon foams previously dominated. California's defense subcontractor corridor mirrors this transition.
- Battery electrode substrate adoption:Open-cell reticulated architectures are penetrating lithium-ion cell manufacturing as lightweight current collector substrates. This application category accelerates faster than rigid foam qualification pathways.
Market Restraints
- Precursor feedstock concentration:Mesophase pitch supply concentrates among specialty carbon material producers in Japan and the United States, creating input cost volatility for foam manufacturers without captive carbon fiber production.
- Pyrolysis energy intensity:Controlled carbonization above 1,000°C demands continuous furnace operation with natural gas or electricity inputs, exposing producers to regional energy price fluctuations.
- Polymer foam substitution in non-critical thermal applications:Melamine and polyimide foams retain cost advantages in commercial aircraft interiors where FAA smoke toxicity standards permit their use.
Strategic Opportunities
- Semiconductor process equipment expansion:Graphitic carbon foam with tailorable thermal conductivity is penetrating wafer handling and chamber components as foundries expand domestic capacity.
- Subscription-based thermal audit services:Hardware manufacturers are unbundling long-term client relationships from product sales through performance-based thermal management contracts.
- Electric vehicle battery pack containment:Evolving thermal runaway standards across multiple jurisdictions are redefining specification requirements for inter-cell barrier materials.
Industry Challenges
- REACH documentation burden:European substance registration requirements for imported precursors favor vertically integrated producers with in-house analytical laboratories, disadvantaging smaller compounders.
- FAA certification timeline compression:Commercial aircraft interior applications require flame penetration and smoke toxicity qualification that extends development cycles for new foam formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Foam Market |
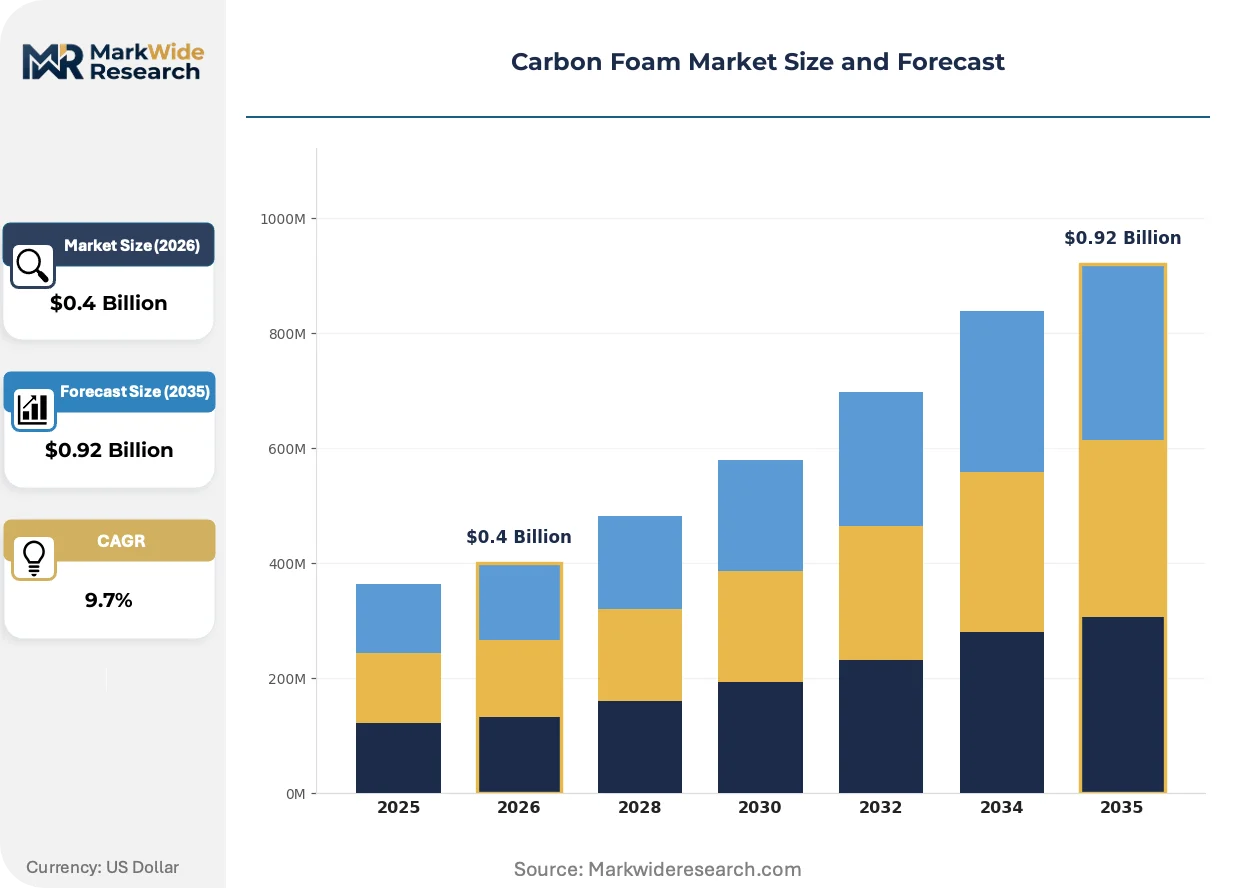
| Market Size in 2026 | $0.4 Billion |
| Market Size in 2035 | $0.92 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Cell Foam, Closed-Cell Foam, Flexible Foam, Rigid Foam End Use Industry: Aerospace, Automotive, Electronics, Construction Application: Thermal Insulation, Acoustic Insulation, Energy Absorption, Filtration Form: Sheets, Blocks, Custom Shapes, Composite Panels |
| Companies Covered | Touchstone Advanced Composites, Entegris Inc., ERG Aerospace, Koppers Inc., Ultramet, CFOAM Limited, Poco Graphite Inc., SGL Carbon SE, Mersen S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Foam Market Emerging Trajectories
Active materials development is absorbing computational design methods and closed-loop pyrolysis control, compressing the gap between laboratory formulation and aerospace qualification. These converging forces reshape how carbon foam producers engage specification engineers.
Graphitic carbon foam with gradient porosity is absorbing thermal shock loads in semiconductor process equipment where metallic alternatives oxidize. Wafer handling equipment manufacturers in the United States and South Korea are accelerating adoption. This material architecture is absorbing qualification timelines from traditional ceramics, compressing supplier selection cycles for chamber component procurement.
REACH compliance requirements in Europe are absorbing analytical capacity across the supplier base, forcing importers to build in-house testing infrastructure or exit the market. The regulation's substance registration deadlines compress procurement options for specification engineers. Composite panel integrators with captive laboratory capabilities are absorbing market share from distributors lacking documentation resources.
Long-term thermal performance contracts are absorbing traditional hardware-only sales relationships in aerospace and defense procurement. Satellite prime contractors in Germany and the United States now bundle carbon foam core supply with predictive thermal modeling services. This service unbundling concentrates in California's defense subcontractor corridor and Bavaria's aerospace cluster, where multi-year platform development programs justify integrated supplier relationships.
Carbon Foam Market Segmentation
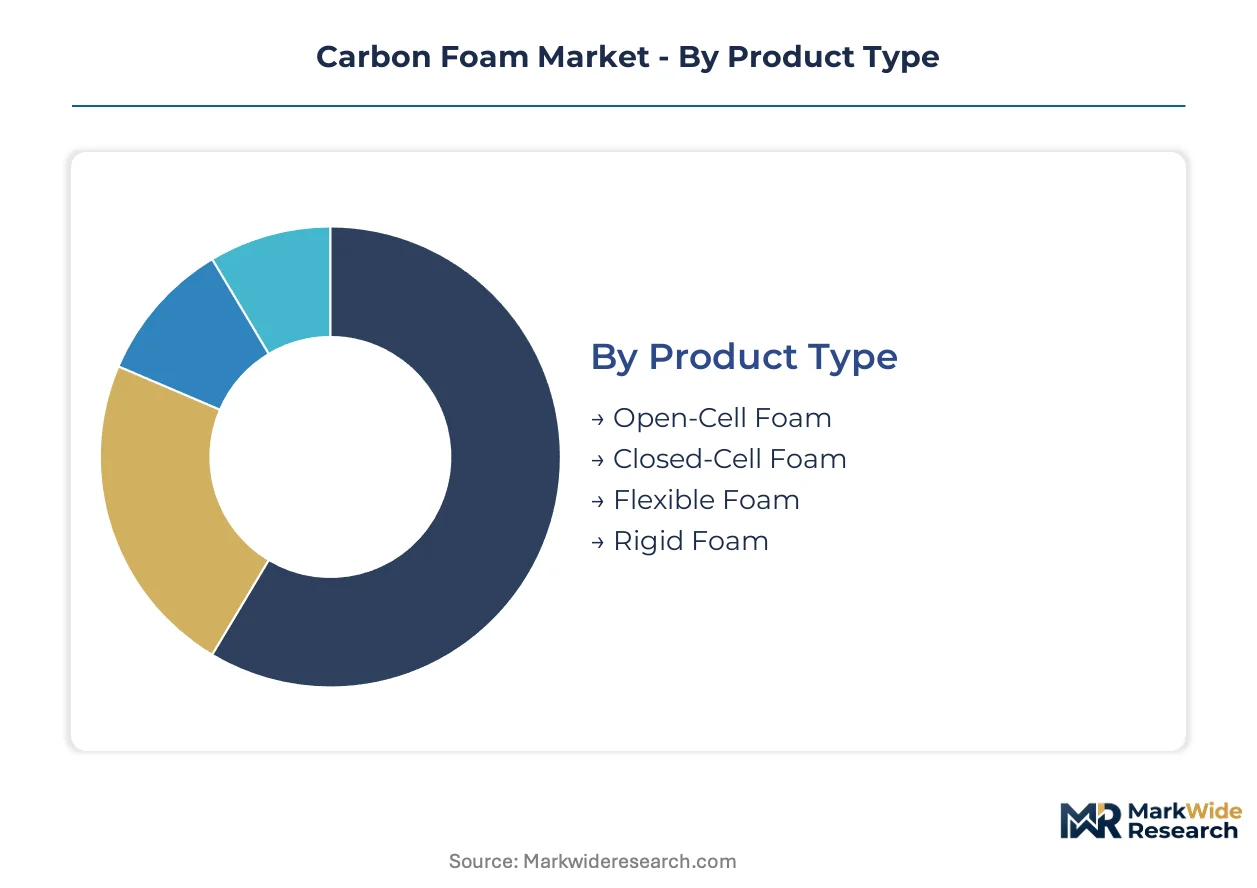
Carbon foam procurement decisions pivot on thermal performance requirements, regulatory compliance pathways, and integration complexity with adjacent materials. Specification engineers navigate trade-offs between open-cell architectures for emerging applications and rigid foam for established aerospace qualification.
Product Type:
Upgrade cycles in satellite thermal management and battery manufacturing are displacing earlier foam generations with architectures optimized for specific conductivity and porosity requirements.
- Open-Cell Foam:Reticulated structures with interconnected porosity exceeding 70% serve as lightweight current collector substrates in lithium-ion cell manufacturing. Battery electrode substrate adoption concentrates in South Korean and German cell production facilities where energy density targets drive material selection.
- Rigid Foam:Dense carbon skeletons manufactured through controlled pyrolysis above 1,000°C provide structural integrity for aerospace primary structures. Bavaria's aerospace cluster and California's defense subcontractor corridor anchor qualification activity for satellite thermal management systems.
- Closed-Cell Foam:Isolated pore structures deliver moisture resistance for marine and industrial applications requiring environmental sealing.
- Flexible Foam:Compressible formulations accommodate irregular geometries in gasketing and conformal insulation applications.
Rigid foam sits at the top of the volume ranking, with open-cell foam climbing the fastest.
End Use Industry:
Customer procurement sophistication varies sharply across industries, with aerospace demanding full traceability and construction prioritizing cost-per-thermal-unit metrics.
- Aerospace:Satellite manufacturers in Germany and the United States specify carbon foam cores for orbital thermal control systems. FAA flame penetration and smoke toxicity certification requirements extend development cycles but lock in multi-year supply agreements for qualified materials.
- Automotive:Electric vehicle battery pack manufacturers are redefining inter-cell barrier specifications as thermal runaway standards evolve across multiple jurisdictions. Open-cell architectures penetrate fastest where weight reduction targets intersect with safety mandates.
- Electronics:Semiconductor process equipment manufacturers specify graphitic carbon foam with tailorable thermal conductivity for wafer handling components.
- Construction:Building envelope applications remain limited by cost premiums relative to conventional insulation, with adoption concentrating in specialized fire-rated assemblies.
Aerospace commands the highest margin tier, with automotive gaining share fastest as battery production scales.
Application:
Performance specifications diverge based on whether the primary function is heat management, mechanical protection, or media separation.
- Thermal Insulation:Low thermal conductivity carbon foams replace hydrofluorocarbon-based insulation as the EU F-Gas Regulation phases out high-global-warming-potential alternatives. Specification engineers in Germany and California redirect procurement toward carbon foam for satellite and defense applications.
- Filtration:Open-cell reticulated formulations from ERG Aerospace optimize molten metal filtration in foundry operations. Pore size gradation enables particle capture across aluminum and titanium casting processes.
- Acoustic Insulation:Porous carbon structures absorb broadband vibration in aircraft engine nacelles and industrial equipment enclosures.
- Energy Absorption:Crushable foam cores manage impact loads in crash structures and protective packaging for sensitive components.
Thermal insulation dominates current procurement volume, with filtration expanding most quickly in advanced manufacturing sectors.
Form:
Supply chain configuration determines whether customers source raw material or integrated subassemblies, with implications for inventory carrying costs and technical risk allocation.
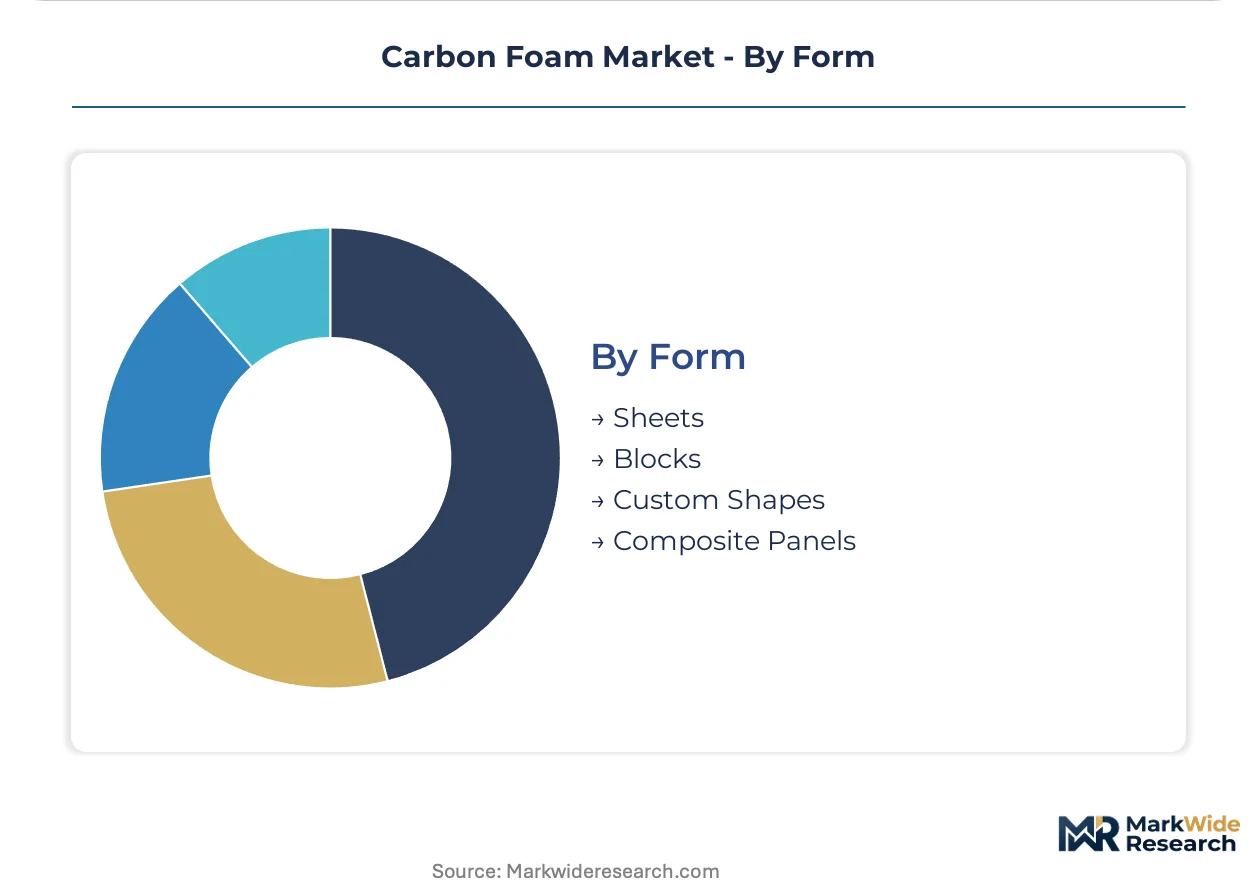
- Composite Panels:Carbon foam cores bonded to face sheets in single-source supply agreements capture premium positioning through multi-year procurement contracts. SGL Carbon SE leverages captive carbon fiber precursor production to control feedstock quality across European aerospace programs.
- Custom Shapes:CNC-machined or molded geometries reduce assembly labor for complex thermal management assemblies in semiconductor process equipment.
- Sheets:Standard planar formats serve prototyping and low-volume production where customers maintain in-house fabrication capabilities.
- Blocks:Bulk billet supply enables maximum flexibility for machine shops serving diversified industrial accounts.
Composite panels anchor the value ranking, with custom shapes steepest in expansion trajectory as equipment manufacturers outsource fabrication complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production is migrating toward jurisdictions with established carbon fiber precursor supply chains and streamlined environmental permitting for high-temperature pyrolysis operations. The cost-of-compliance gap between REACH-registered European facilities and emerging Asian carbonization capacity is reshaping investment flows. Manufacturers prioritize locations where captive feedstock integration offsets energy intensity penalties.
United States
Satellite prime contractors in California's defense subcontractor corridor are expanding carbon foam procurement for orbital thermal management systems. The FAA certifies components under flame penetration and smoke toxicity standards for commercial aircraft interiors. Domestic pyrolysis operations fall under EPA Clean Air Act permitting, with continuous furnace operations concentrated in energy-cost-advantaged states.
Germany
Bavaria's aerospace cluster anchors European qualification activity for rigid foam cores in satellite primary structures. The EU F-Gas Regulation eliminates hydrofluorocarbon-based insulation from aerospace applications, redirecting specification engineers toward carbon foam alternatives. SGL Carbon SE leverages captive carbon fiber precursor production to control feedstock quality across European aerospace programs.
China
Semiconductor process equipment manufacturers are accelerating adoption of graphitic carbon foam for wafer handling components as foundries expand domestic capacity. The Ministry of Ecology and Environment monitors pyrolysis emissions under air quality regulations that vary by provincial jurisdiction. Yangtze River Delta industrial zones concentrate carbonization capacity near specialty carbon material feedstock suppliers.
Japan
Mesophase pitch supply concentrates among specialty carbon material producers serving foam manufacturers without captive carbon fiber production. METI industrial policy supports advanced materials development through targeted R&D funding mechanisms. Osaka-based chemical conglomerates maintain backward integration into pitch precursor refining for aerospace-qualified foam formulations.
South Korea
Battery cell manufacturers in domestic production facilities are adopting open-cell reticulated architectures as lightweight current collector substrates. Energy density targets in electric vehicle supply chains drive material selection toward high-porosity carbon structures. Seoul Capital Area battery producers coordinate specification requirements with carbon foam suppliers for thermal runaway containment applications.
Carbon Foam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace thermal management favoring qualified single-source agreements while battery electrode substrates permit multi-source procurement. The vendor base organizes around three strategic archetypes: vertically integrated carbon fiber producers controlling precursor quality, specialty foam fabricators with captive pyrolysis capacity, and composite panel integrators bundling core supply with fabrication services. Competitive moves concentrate on backward integration into mesophase pitch refining and geographic expansion toward battery manufacturing clusters.
Among European-based material producers, SGL Carbon SE exemplifies the captive-feedstock archetype through controlled carbon fiber precursor production. ERG Aerospace occupies a position within specialty reticulated foam fabrication, while Poco Graphite Inc. represents the tailorable-thermal-conductivity segment serving semiconductor process equipment requirements. These three anchors illustrate how competitive positioning diverges based on end-use specialization and integration depth rather than scale alone.
| Leading Market Players |
|---|
| Touchstone Advanced Composites |
| Entegris Inc. |
| ERG Aerospace |
| Koppers Inc. |
| Ultramet |
| CFOAM Limited |
| Poco Graphite Inc. |
| SGL Carbon SE |
| Mersen S.A. |
| Others |
Supply Flow & Price Mechanics
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by eliminating hydrofluorocarbon-based insulation alternatives, forcing specification engineers toward carbon foam producers with REACH-registered precursors and captive pyrolysis capacity. Aerospace prime contractors in Bavaria and California's defense corridor now pay certification premiums for materials with full traceability documentation, while battery manufacturers in South Korea negotiate volume-scaled contracts for open-cell substrates.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade carbon foam as domestic semiconductor foundries expand procurement. Contract-based long-term offtake dominates aerospace thermal management, with price differentiation resting on FAA certification tier and captive precursor integration. Pricing pressure stems from energy cost volatility in European pyrolysis operations. Automotive battery pack manufacturers exhibit highest price sensitivity; satellite prime contractors show lowest sensitivity due to platform-lock-in effects.
Supply Chain Analysis
Freight costs for mesophase pitch precursors from Japan amplify input volatility for European foam manufacturers lacking backward integration. Supply concentrates in Germany, the United States, and Japan, with raw material dependencies on pitch refining, carbon fiber precursor supply, and high-temperature furnace equipment. Single-source vulnerability runs through Japanese specialty carbon material producers. Distribution runs through qualified direct supply agreements for aerospace and spot procurement for industrial filtration applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon foam offers margin expansion potential as pyrolysis energy efficiency improvements compress production costs and aerospace qualification premiums widen. Specification engineers increasingly bundle hardware with predictive thermal modeling services, shifting value capture toward integrated suppliers.
For Market Incumbents: Acquire captive mesophase pitch refining assets to secure feedstock quality and REACH documentation compliance. Expand pyrolysis capacity in energy-cost-advantaged US states to offset European energy price exposure. Polymer foam substitution in non-critical aircraft interiors threatens rigid foam volume; defend through FAA certification timeline acceleration and composite panel fabrication integration. For New Entrants and Emerging Players: Digital thermal audit platforms enable service-led market entry without capital-intensive pyrolysis investment. Target South Korean battery electrode substrate demand as the most penetrable segment, where open-cell architecture specifications remain fluid and multi-source procurement is accepted. Pursue foundry partnerships in China's Yangtze River Delta for semiconductor process equipment qualification. For Investors and Strategic Acquirers: Roll-up economics work for specialty foam fabricators with captive pyrolysis capacity because REACH compliance burdens favor consolidated analytical infrastructure. Five-to-ten-year viability hinges on electric vehicle battery safety standard harmonization. Target mid-cap producers with aerospace qualification pathways. Watch for thermal runaway containment specification convergence across US, EU, and Chinese jurisdictions as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pitch Precursor Refining | SGL Carbon SE's captive carbon fiber production secures feedstock quality for European aerospace programs. |
| Subscription-Based Thermal Audit Services | Hardware manufacturers unbundle long-term client relationships from product sales through performance contracts. |
| Composite Panel Fabrication Integration | Single-source supply agreements for carbon foam cores with face sheets lock in multi-year procurement contracts. |
| Open-Cell Reticulated Capacity Expansion | Battery cell manufacturers in South Korea adopt lightweight current collector substrates for energy density targets. |
| Semiconductor Process Equipment Qualification | Graphitic carbon foam with tailorable thermal conductivity penetrates wafer handling components in US and South Korean foundries. |
Methodological Framework
Coverage spans Germany, the United States, China, Japan, and South Korea, with primary inputs from each jurisdiction's carbon material specialists. The analysis combines structured interviews with aerospace procurement managers, battery cell manufacturing engineers, semiconductor process equipment designers, and carbon foam plant operations directors with secondary validation from SEC filings, ECHA REACH registration databases, FAA certification records, and customs trade data. Bottom-up volume modeling triangulates against top-down industry spend estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation across product architecture, end-use industry, thermal performance specification, and supply form factor. CAGRs derive from fitted growth curves calibrated to qualification timeline data and regulatory phase-out schedules. Industry-specific inputs include EU F-Gas Regulation implementation pacing and battery thermal runaway standard evolution across jurisdictions.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook. Forecasts reflect assumptions about aerospace platform development continuity and pyrolysis energy cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Dielectric Materials Market