
 Global Industrial Insulators Market | 2026-2036
Global Industrial Insulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Insulators Market Foresight
The divergence between premium and commodity tiers is hardening as aerospace-grade ceramic insulators command qualification protocols that commodity mineral wool cannot satisfy. NGK Insulators Ltd. dominates advanced ceramic formulations for ultra-high-voltage transmission. Siemens AG leverages integrated energy-system expertise to bundle insulators with switchgear contracts. Aditya Birla Insulators anchors cost-competitive production serving India's domestic power grid expansion.
Industrial insulators are engineered materials designed to inhibit thermal, acoustic, electrical, or fire propagation across industrial equipment and infrastructure, typically rated for dielectric strength above 20 kV/mm or thermal conductivity below 0.05 W/m·K depending on application. Ceramic products retain the largest installed base due to proven performance in high-voltage environments exceeding 765 kV, though aerogel segments are gaining fastest in cryogenic LNG processing where thermal efficiency penalties carry heavy operating costs. Cellular glass occupies a defensible niche in chemical processing against corrosive subsoil conditions where moisture ingress destroys competing materials.
FERC grid-reliability standards in the United States, EU F-Gas Regulation restricting fluorinated greenhouse gases in foam insulants, and India's BIS certification mandates for electrical equipment collectively reshape product specifications and supplier eligibility across major economies. China's GB standards and dual carbon goals further filter market access for foreign manufacturers. Stakeholders must monitor evolving national carbon-border mechanisms and material traceability requirements that will determine which insulation technologies retain cost competitiveness against emerging bio-based alternatives.
Market Dynamics
Grid modernization mandates across major economies are forcing wholesale replacement cycles in high-voltage transmission infrastructure, compressing supplier qualification timelines while elevating performance specifications for ceramic and composite insulator systems.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases in foam insulants are redirecting specification committees toward mineral wool and aerogel alternatives in HVAC and industrial process equipment.
- India's PLI scheme for power equipment:Domestic manufacturing incentives are accelerating localized ceramic insulator capacity to serve the country's 765 kV transmission corridor buildout.
- LNG cryogenic processing:Thermal efficiency penalties in liquefaction trains are pulling demand toward silica aerogel blankets that cut boil-off gas losses versus conventional perlite systems.
Market Restraints
- Alumina price volatility:Raw material cost swings for high-purity feedstocks used in electrical-grade ceramics compress margin predictability for formulation specialists.
- China supply concentration:Dominant share of global ceramic insulator manufacturing capacity creates geographic risk exposure for procurement teams seeking qualified second sources.
- REACH substance restrictions:Ongoing candidate list expansions for SVHCs complicate legacy binder chemistries in mineral wool products, forcing reformulation investments.
Strategic Opportunities
- Brazil transmission expansion:Underpenetrated 500 kV network buildout creates demand pull for porcelain long-rod insulators in Amazon basin humidity conditions.
- CCUS infrastructure:Carbon capture pipeline networks require specialized high-pressure electrical isolation systems absent from current product catalogs.
- EU Green Deal industrial heat:Electrification mandates for process temperature applications above 1000°C are opening specification windows for advanced oxide fiber boards.
Industry Challenges
- High-voltage test engineering talent:Shortage of specialists capable of designing 765 kV+ qualification protocols extends product validation timelines.
- Legacy asbestos abatement:Remediation of installed refractory ceramic fiber containing legacy binders requires specialized handling certifications that slow retrofit project execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Insulators Market |
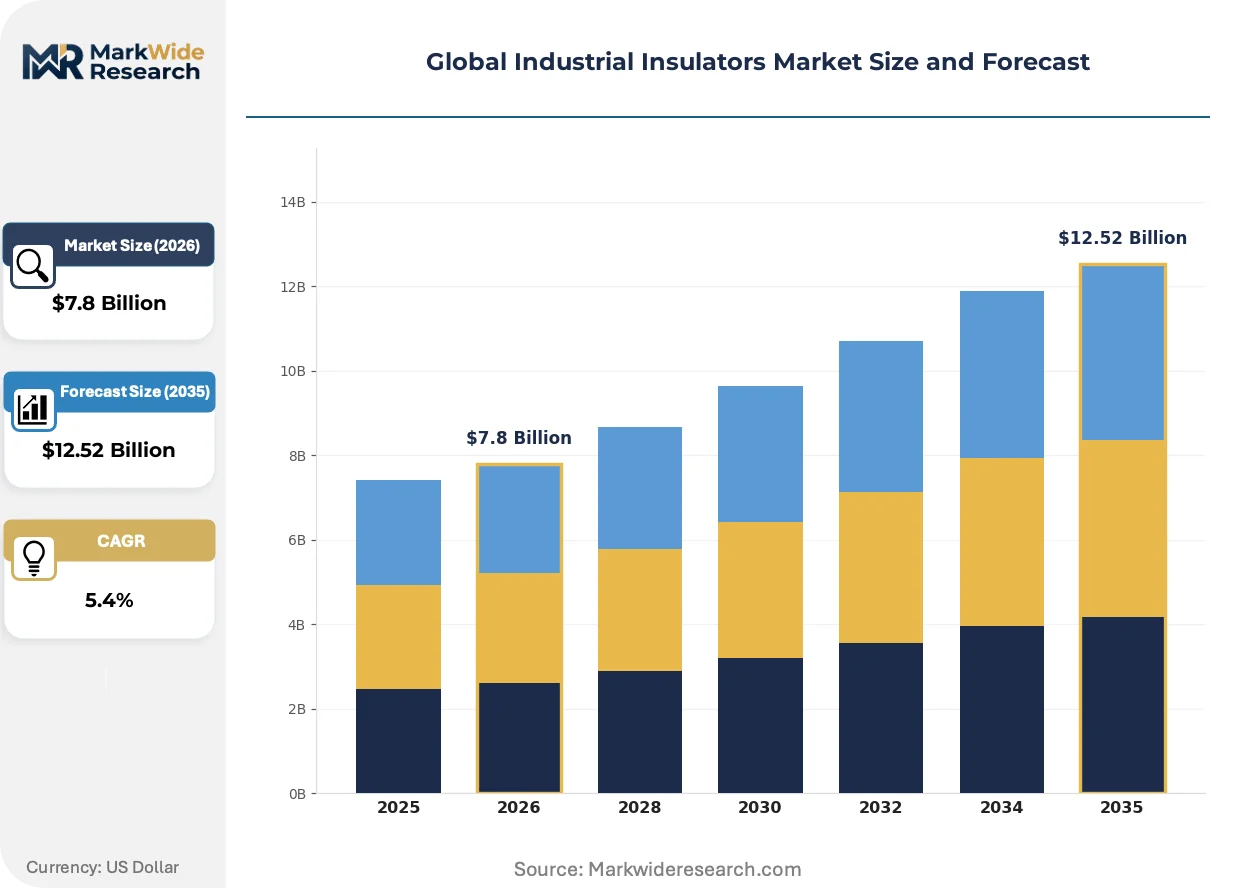
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic, Fiberglass, Mineral Wool, Cellular Glass, Aerogel, Calcium Silicate Technology: Thermal Insulation, Acoustic Insulation, Electrical Insulation, Cryogenic Insulation, Fireproof Insulation, Radiant Barrier Application: Power Generation, Oil Refining, Chemical Processing, Aerospace Manufacturing, Food Processing, Shipbuilding End User Industry: Energy Producers, Petrochemical Plants, Aerospace Firms, Food Producers, Maritime Constructors, Manufacturing Facilities |
| Companies Covered | ABB Ltd., Siemens AG, General Electric, NGK Insulators Ltd., Toshiba Corporation, Aditya Birla Insulators, Lapp Insulators GmbH, Hubbell Incorporated, TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Insulators Market Shifts & Advancements
Material science advances are compressing the performance gap between established ceramic systems and emerging nanostructured alternatives, while digital specification tools are shortening buyer decision cycles in utility procurement.
Silica aerogel composite blankets are integrating into LNG liquefaction train cold-box insulation packages, replacing perlite loose-fill in base-load export facilities. QatarEnergy and Cheniere specification teams have adopted aerogel for newbuild trains due to thermal conductivity advantages below 0.02 W/m·K. The technology is integrating project delivery timelines by eliminating the settling and compaction maintenance cycles that disrupt perlite-based systems.
China's GB standards for ultra-high-voltage transmission equipment have tightened dielectric withstand requirements for 1100 kV DC lines, forcing foreign suppliers to establish domestic testing partnerships. The State Grid Corporation of China now mandates in-country type testing for all suspension insulator lots exceeding 300 kN mechanical rating. European and Japanese manufacturers are responding with joint venture laboratory investments in Xiangtan and Suzhou to retain qualification access.
Utility procurement committees are consolidating supplier panels from fifteen-plus qualified vendors to four-to-six strategic partners with full lifecycle service capabilities. Siemens Energy and Hitachi Energy have captured expanded scope by bundling insulator replacement with digital condition monitoring subscriptions. This concentration is most visible in Germany's TenneT and 50Hertz transmission zones, where framework agreements now span ten-year horizons with integrated predictive maintenance clauses.
Global Industrial Insulators Market Segmentation
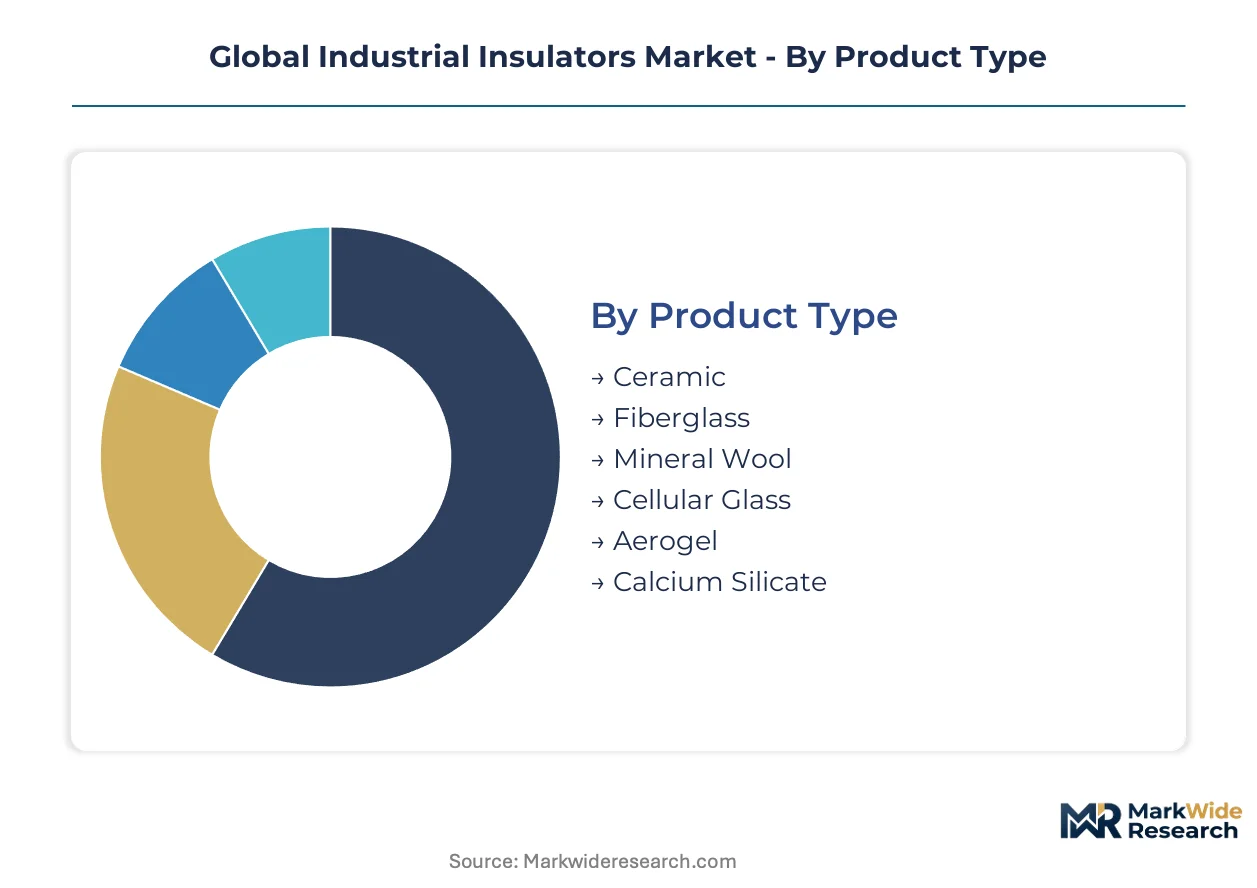
Industrial insulators serve radically different performance envelopes across electrical, thermal, and acoustic functions, forcing suppliers to maintain parallel formulation capabilities. Segmentation clarity determines procurement strategy, as aerospace-grade electrical specifications bear little overlap with cryogenic LNG insulation requirements.
Product Type:
Capital intensity varies sharply across product categories, with ceramic and aerogel manufacturing demanding specialized sintering furnaces and supercritical drying equipment that mineral wool production avoids entirely.
- Ceramic:Alumina and porcelain formulations dominate ultra-high-voltage transmission infrastructure above 765 kV, with dielectric strength ratings exceeding 20 kV/mm. State Grid Corporation of China and India's Power Grid Corporation anchor procurement volumes for suspension and post-type insulators serving 1100 kV DC corridor buildouts. REACH substance restrictions on legacy binders are forcing European suppliers toward borosilicate glass alternatives.
- Aerogel:Silica-based blankets achieve thermal conductivity below 0.02 W/m·K through nanostructured porosity, enabling LNG liquefaction train applications where boil-off gas losses carry heavy operating cost penalties. QatarEnergy and Cheniere specification teams have adopted aerogel composites for base-load export facility cold-box insulation, displacing conventional perlite loose-fill systems.
- Fiberglass:Borosilicate glass fiber mats serve HVAC ductwork and industrial pipe insulation across mid-temperature process applications.
- Mineral Wool:Slag and rock wool products retain cost advantage in commercial building and mid-tier industrial thermal insulation.
- Cellular Glass:Closed-cell glass foam blocks resist moisture ingress in buried chemical pipeline applications where subsoil corrosion destroys competing materials.
- Calcium Silicate:Hydrated calcium silicate boards serve high-temperature steam piping and industrial oven insulation up to 650°C continuous operation.
Ceramic absorbs the bulk of installed capacity; aerogel is expanding most quickly.
Technology:
Technology selection tracks directly to the physical hazard being mitigated, with electrical and cryogenic segments commanding premium pricing through qualification-intensive certification protocols.
- Thermal Insulation:Dominant by installed volume, spanning mineral wool, calcium silicate, and cellular glass systems for process heat containment across petrochemical and power generation facilities. EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are redirecting HVAC specification committees toward mineral wool and aerogel alternatives in industrial process equipment.
- Electrical Insulation:Ceramic and composite polymer systems serve high-voltage transmission, switchgear, and transformer applications where dielectric withstand determines system reliability. FERC grid-reliability standards in the United States mandate accelerated replacement cycles for aging porcelain insulator fleets.
- Cryogenic Insulation:Aerogel blankets and perlite systems compete for LNG liquefaction, storage, and regasification infrastructure where thermal efficiency penalties dominate lifecycle economics.
- Acoustic Insulation:Mineral wool and fiberglass batts attenuate industrial noise in manufacturing facilities and power plants.
- Fireproof Insulation:Intumescent coatings and ceramic fiber boards protect structural steel and electrical cable trays in high-hazard process environments.
- Radiant Barrier:Aluminum-faced reflective membranes reduce radiative heat transfer in high-temperature furnace applications and aerospace thermal protection systems.
Thermal insulation carries the largest installed base; cryogenic insulation climbs the fastest on LNG infrastructure buildout.
Application:
Application segmentation reveals divergent procurement patterns, with power generation and aerospace demanding multi-year qualification timelines that oil refining and food processing rarely require.
- Power Generation:Ceramic suspension insulators, bushing assemblies, and transformer insulation systems serve coal, gas, nuclear, and renewable generation assets. Grid modernization mandates across Germany, India, and China are forcing wholesale replacement cycles in high-voltage transmission infrastructure, compressing supplier qualification timelines while elevating performance specifications.
- Chemical Processing:Cellular glass and calcium silicate systems resist corrosive chemical exposure and thermal cycling in refinery and petrochemical plant process streams. Brazil's underpenetrated 500 kV network buildout creates demand pull for specialized electrical isolation in Amazon basin humidity conditions.
- Oil Refining:High-temperature insulation packages for fired heaters, catalytic crackers, and hydroprocessing units.
- Aerospace Manufacturing:Oxide fiber boards and advanced ceramic composites for engine thermal protection and airframe insulation systems.
- Food Processing:Sanitary-grade thermal insulation for ovens, refrigeration, and steam distribution systems.
- Shipbuilding:Fire-rated bulkhead and deck insulation for commercial and naval vessel construction.
Power generation commands the deepest installed capacity; chemical processing is gaining share fastest on CCUS infrastructure development.
End User Industry:
End user concentration determines contract structure, with energy producers consolidating supplier panels toward strategic partnerships while manufacturing facilities retain fragmented spot purchasing.
- Energy Producers:Vertically integrated utilities and independent power producers specify ceramic and composite insulator systems for generation, transmission, and distribution assets. Germany's TenneT and 50Hertz transmission zones have consolidated framework agreements to four-to-six strategic partners with ten-year horizons and integrated predictive maintenance clauses.
- Petrochemical Plants:Integrated refinery and chemical complex operators procure thermal and electrical insulation for process units, storage, and utilities. India's PLI scheme for power equipment is accelerating localized ceramic insulator capacity to serve domestic 765 kV transmission corridor buildout.
- Aerospace Firms:Prime contractors and engine manufacturers impose qualification protocols that commodity mineral wool cannot satisfy.
- Food Producers:Facility operators prioritize sanitary compliance and thermal efficiency in processing and packaging operations.
- Maritime Constructors:Shipyards specify fire-rated and acoustic insulation packages for newbuild and retrofit programs.
- Manufacturing Facilities:Diverse industrial end users procure thermal and acoustic insulation for process equipment and building envelopes.
Energy producers absorb the dominant share of procurement volume; petrochemical plants are expanding fastest on industrial heat electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xiangtan and Suzhou anchor qualification laboratory investments for foreign manufacturers seeking State Grid Corporation of China access. Grid modernization mandates and renewable energy buildouts are reshaping procurement patterns across major economies.
China
State Grid Corporation mandates in-country type testing for suspension insulator lots exceeding 300 kN mechanical rating. GB standards for 1100 kV DC lines have tightened dielectric withstand requirements. European and Japanese manufacturers are responding with joint venture laboratory investments in Xiangtan and Suzhou to retain qualification access.
India
Power Grid Corporation anchors procurement volumes for 765 kV transmission corridor buildouts. The PLI scheme for power equipment accelerates localized ceramic insulator capacity. Manufacturing clusters in Gujarat and Maharashtra are expanding to serve domestic grid infrastructure expansion.
Germany
TenneT and 50Hertz transmission zones consolidate framework agreements to four-to-six strategic partners with ten-year horizons. EU F-Gas Regulation phase-down schedules redirect HVAC specification committees toward mineral wool and aerogel alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia host integrated energy-system providers.
United States
FERC grid-reliability standards mandate accelerated replacement cycles for aging porcelain insulator fleets. Cheniere specification teams have adopted aerogel composites for base-load LNG export facility cold-box insulation. Gulf Coast liquefaction train buildouts pull demand toward thermal efficiency solutions.
Brazil
Underpenetrated 500 kV network buildout creates demand pull for porcelain long-rod insulators in Amazon basin humidity conditions. ANVISA and national electrical regulators shape equipment certification requirements. Industrial corridors in São Paulo and Minas Gerais concentrate transmission infrastructure procurement.
Global Industrial Insulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification protocol intensity and lifecycle service bundling. The vendor base organizes into three tiers: integrated energy-system providers with digital monitoring subscriptions, specialized ceramic formulation houses with ultra-high-voltage testing capabilities, and cost-competitive regional fabricators serving domestic grid buildouts. Dominant competitive moves include strategic partnership consolidation for qualification access and capacity expansion to capture localized procurement incentives.
Within the integrated systems tier, Siemens AG and ABB Ltd. exemplify bundled insulator-switchgear offerings with predictive maintenance clauses. NGK Insulators Ltd. anchors the specialized ceramic formulation segment. Aditya Birla Insulators occupies a position within cost-competitive regional supply serving domestic transmission corridor expansion.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| General Electric |
| NGK Insulators Ltd. |
| Toshiba Corporation |
| Aditya Birla Insulators |
| Lapp Insulators GmbH |
| Hubbell Incorporated |
| TE Connectivity Ltd. |
| Others |
Supply & Pricing Matrix
Silica aerogel manufacturing transitions from supercritical drying batch processes to continuous ambient-pressure methods, simultaneously collapsing unit production costs and redrawing supplier concentration maps as new entrants bypass legacy capital barriers. This technology shift feeds directly into procurement committee specifications at QatarEnergy and Cheniere, where thermal conductivity guarantees now trade at narrower premiums against conventional perlite systems.
Pricing Analysis
Value-based pricing anchors to boil-off gas reduction guarantees in LNG liquefaction applications, with aerogel suppliers capturing premiums tied to measurable thermal efficiency outcomes. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade ceramic qualification protocols from commodity mineral wool specifications. Cost compression in mid-tier electrical ceramics is intensifying because alumina price volatility compresses margin predictability for formulation specialists. Utility procurement teams show lowest price sensitivity in ultra-high-voltage transmission segments, while commercial HVAC contractors drive hardest bargain on mineral wool volumes.
Supply Chain Analysis
Dual-sourcing requirements mandated by European transmission operators and India's Power Grid Corporation force procurement teams to qualify second-source suppliers beyond dominant Chinese ceramic insulator manufacturers. Geographic supply concentration centers on China, Germany, and India for finished insulator systems, with high-purity alumina feedstock drawing from Australian and Brazilian mining operations. Single-source vulnerability runs through 1100 kV DC suspension insulator testing capacity, where State Grid Corporation mandates in-country qualification laboratories. Distribution runs through direct utility framework agreements and EPC contractor specifications in power infrastructure, with spot purchasing dominating commercial building applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial insulators market sits in a technology-transition phase as silica aerogel displaces perlite loose-fill in LNG cold-box applications, reshaping competitive positioning between nanostructured and conventional thermal insulation suppliers.
For Market Incumbents: Deepen backward integration into high-purity alumina feedstock supply to defend margin position against raw material cost swings. Secure captive testing capacity in Xiangtan or Suzhou to retain State Grid Corporation qualification access as GB standards tighten. Expand digital condition monitoring subscriptions to capture ten-year framework agreements following TenneT and 50Hertz consolidation patterns. For New Entrants and Emerging Players: Engineering-procurement-construction contractors in Brazil's Amazon basin transmission buildout represent the most penetrable channel partner type for porcelain long-rod insulator specialists lacking established utility relationships. Target underqualified humidity-resistant specifications where incumbent testing investments lag local regulatory requirements. Partner with regional fabricators in Gujarat or Maharashtra to access India's PLI scheme incentives without greenfield facility costs. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated energy-system providers seeking insulator-switchgear bundling capabilities. Long-term viability favors specialized ceramic formulation houses with 765 kV+ testing protocols and established utility qualification records. Watch for inflection in carbon-border mechanism implementation timelines, which would shift cost competitiveness between domestic and imported insulation technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Laboratory Investment | European and Japanese manufacturers establish Xiangtan and Suzhou facilities to retain State Grid Corporation qualification access. |
| Backward Integration into Alumina Supply | Ceramic formulation specialists secure feedstock cost predictability against Australian and Brazilian mining price volatility. |
| Digital Condition Monitoring Subscription | Siemens Energy and Hitachi Energy bundle predictive maintenance clauses to capture expanded utility framework agreement scope. |
| Aerogel Manufacturing Scale-Up | Continuous ambient-pressure production methods collapse unit costs to compete with perlite in base-load LNG facilities. |
| Localized Capacity Expansion | Gujarat and Maharashtra manufacturing clusters capture India's PLI scheme incentives for 765 kV corridor buildout. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across utility procurement officers, EPC contractor specification teams, ceramic formulation R&D directors, and LNG facility engineering managers. Secondary sources included FERC reliability filings, EU ECHA REACH substance registrations, State Grid Corporation tender announcements, and customs import records for alumina and finished insulator categories. Bottom-up demand modeling triangulated against top-down macroeconomic indicators to validate volume estimates.
Data-stream reconciliation across product type, application, technology, and end-user industry dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level demand buildups incorporating grid modernization investment cycles, LNG liquefaction train order backlogs, and regulatory phase-down schedules for fluorinated greenhouse gases. Industry-specific inputs included transmission voltage upgrade timelines and aerogel manufacturing capacity expansion announcements.
Caveats apply where alumina price volatility, carbon-border mechanism implementation, or REACH substance restriction expansions could materially shift the outlook. Forecasts reflect documented assumptions regarding infrastructure investment continuity and regulatory enforcement timelines. Deviation in State Grid Corporation qualification requirements or EU F-Gas Regulation phase-down acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Thermal Tapes Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
High Temperature Insulation Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Polyisocyanurate Insulation Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market