
 Global Industrial Foam Market | 2026-2036
Global Industrial Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Foam Market Foresight
Polymer chemist shortages across European and North American manufacturing hubs is redrawing competitive boundaries for advanced foam formulations. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply of isocyanate precursors for rigid polyurethane systems. Covestro AG anchors its position through specialized aliphatic polyurethane research aimed at UV-stable outdoor applications. Huntsman Corporation differentiates via operational scale at its Rotterdam facility, supplying construction and appliance manufacturers across the Benelux region.
Industrial foam comprises cellular polymer structures with controlled pore sizes ranging from 10 to 800 microns, manufactured through gas-blowing reactions that reduce material density while preserving mechanical integrity for thermal insulation, impact absorption, and acoustic dampening in heavy industry. Polyurethane foam dominates value generation due to its versatility across temperature extremes and bonding compatibility with metals and composites. Phenolic foam occupies a premium niche where fire resistance ratings governed by EN 13501-1 and similar national codes command specification in commercial aviation and rail infrastructure. Spray foam applications within construction are expanding fastest as retrofit energy efficiency mandates tighten across multiple jurisdictions.
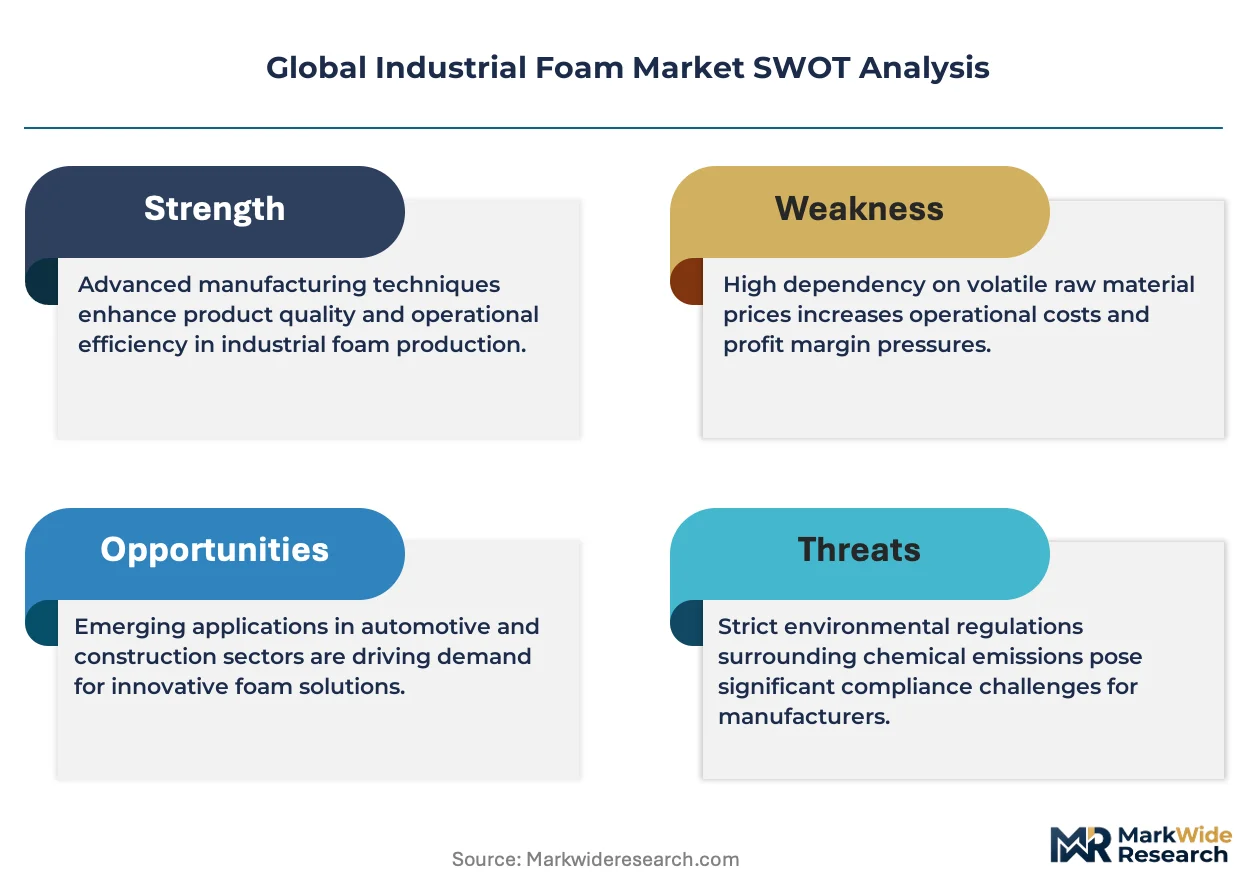
EPA SNAP program restrictions on hydrofluorocarbon blowing agents are forcing reformulation timelines for US-based producers, while REACH substance authorization requirements in Europe constrain legacy additive chemistries. China's GB standards for building materials and Japan's JIS fire safety classifications add further compliance layers for multinational suppliers operating across regulatory boundaries. Stakeholders must monitor polymer feedstock volatility and blowing agent transition costs as dual pressures from climate policy and energy security reshape input economics through the forecast horizon.
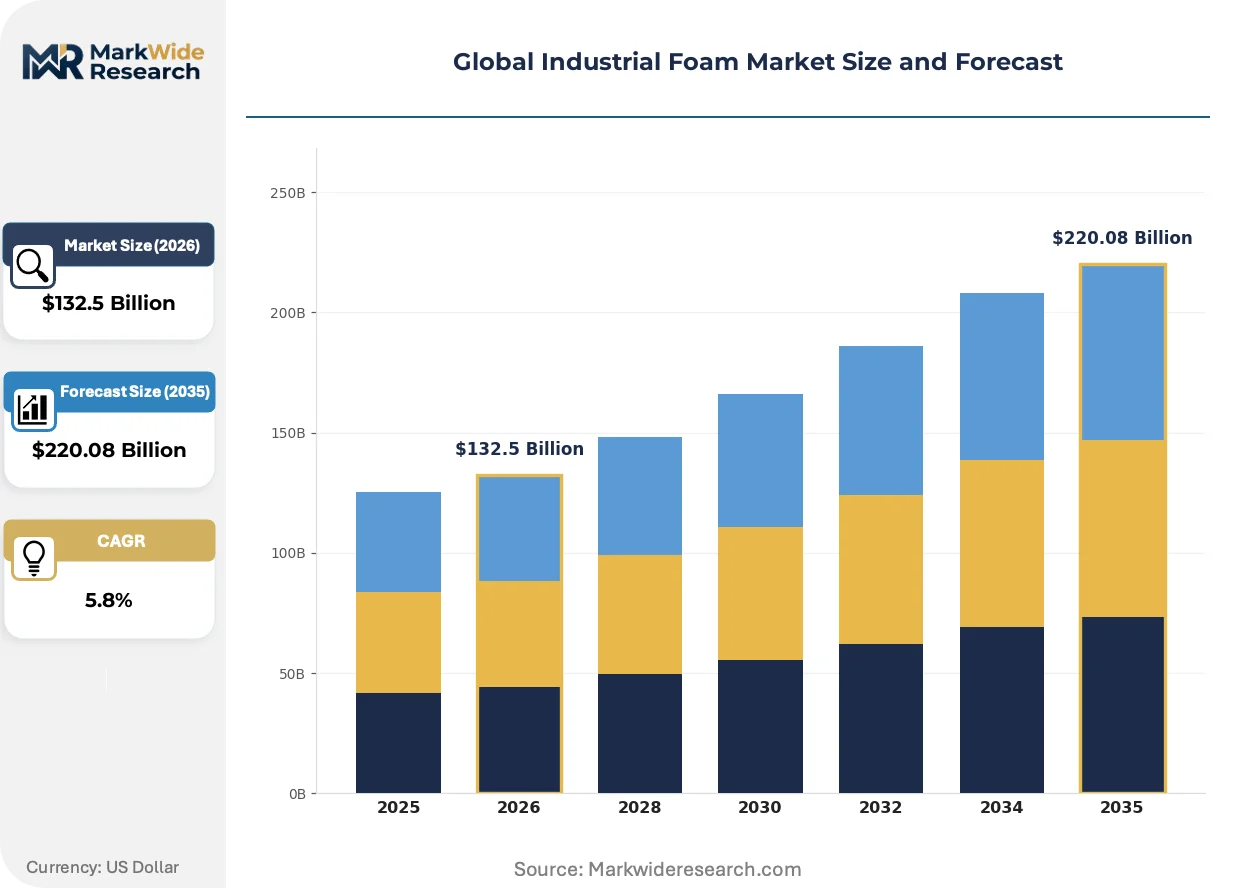
Market Dynamics
Automotive lightweighting mandates and building energy retrofit programs are compressing formulation cycles across polyurethane, polystyrene, and phenolic foam systems as manufacturers race to qualify low-GWP blowing agents.
Growth Catalysts
- EU F-Gas Regulation phase-down:The staged reduction of hydrofluorocarbon blowing agents is compelling appliance and construction sectors to adopt hydro-olefin and hydrocarbon alternatives, expanding addressable demand for reformulated rigid foam systems.
- China's eastern coastal manufacturing clusters:Concentrated appliance and electronics production in Jiangsu, Zhejiang, and Guangdong provinces is sustaining bulk consumption of polyurethane slabstock and molded foam for refrigeration insulation and packaging applications.
- Spray polyurethane foam retrofit mandates:Germany's Building Energy Act and similar efficiency codes across Nordic markets are accelerating specification of high-performance insulation in existing building envelopes.
Market Restraints
- Isocyanate feedstock concentration:MDI and TDI precursor supply remains concentrated among integrated petrochemical complexes in Germany, China, and the US Gulf Coast, exposing foam producers to input volatility and force majeure risks.
- REACH substance authorization timelines:Legacy flame retardant and catalyst chemistries face sunset dates under ECHA review, forcing costly reformulation without guaranteed performance parity in fire-rated applications.
- Phenolic foam brittleness limitations:Inherent friability and moisture sensitivity constrain phenolic systems to niche aviation and rail specifications despite superior fire resistance ratings under EN 13501-1.
Strategic Opportunities
- India's cold chain infrastructure buildout:National cold chain mission targets and FSSAI food safety mandates are opening specification windows for polyurethane insulated panels and refrigerated transport foam in a historically underpenetrated market.
- Bio-based polyol convergence:Soy-derived and castor oil polyol streams are achieving cost parity with petroleum feedstocks in select formulations, enabling carbon footprint differentiation for sustainability-committed construction clients.
- Japan's ZEB (Net Zero Energy Building) certification:METI-backed efficiency standards are creating premium tier demand for vacuum-insulated panel hybrids and high-R-value spray foam in commercial newbuilds.
Industry Challenges
- Polymer chemist talent scarcity:Specialized formulation expertise for aliphatic polyurethane and next-generation blowing agent compatibility is concentrating at legacy European and North American research hubs, constraining R&D velocity elsewhere.
- Dual certification burden:Foam producers supplying multinational appliance manufacturers must simultaneously satisfy US EPA SNAP, EU F-Gas, and China GB standards, extending qualification timelines and testing expenditure.
- Legacy equipment retrofit requirements:Transition to low-pressure or variable-ratio dispensing equipment for new blowing agent chemistries demands capital deployment across installed contractor bases in construction spray foam segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Foam Market |
| Market Size in 2026 | $132.5 Billion |
| Market Size in 2035 | $220.08 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Polyethylene Foam, Polyvinyl Chloride Foam, Phenolic Foam Application: Insulation, Packaging, Cushioning, Filtration, Sealing End User Industry: Construction, Consumer Electronics, Aerospace, Marine, Furniture Manufacturing Manufacturing Process: Reaction Injection Molding, Extrusion, Spray Foam, Compression Molding, Pouring |
| Companies Covered | BASF SE, Covestro AG, The Dow Chemical Company, Huntsman Corporation, Sekisui Chemical Co., Ltd., Saint-Gobain, DuPont, Armacell International S.A., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Foam Market Shifts & Advancements
Reformulation chemistry and application equipment are converging to enable higher-performance insulation at reduced embodied carbon, reshaping competitive advantage away from scale economics toward formulation agility.
Hydrofluoroolefin (HFO) blowing agents are displacing legacy HFC systems in rigid polyurethane formulations for commercial refrigeration and construction insulation. Cold storage facility operators and supermarket chains across Germany and the US are specifying HFO-based foam to preempt regulatory phase-outs and secure utility incentive eligibility. This displacement is compressing margins for producers slow to secure HFO supply agreements and qualification data.
The EU F-Gas Regulation's 2030 phase-down trajectory is forcing accelerated R&D timelines for alternative blowing agent portfolios. Foam system houses must now validate thermal performance, dimensional stability, and long-term aging characteristics for hydrocarbon, HFO, and water-blown formulations in parallel. Construction and appliance segments face the steepest compliance curves, with German and French specifiers already restricting HFC-containing materials from public procurement frameworks.
Specification authority is migrating from general contractors to energy performance consultants and sustainability officers in commercial construction procurement. These technical buyers demand cradle-to-grave carbon accounting and third-party EPD verification, displacing traditional distributor-centric purchasing relationships. This shift is most pronounced in Nordic markets and California, where building code stringency and corporate net-zero commitments intersect.
Global Industrial Foam Market Segmentation
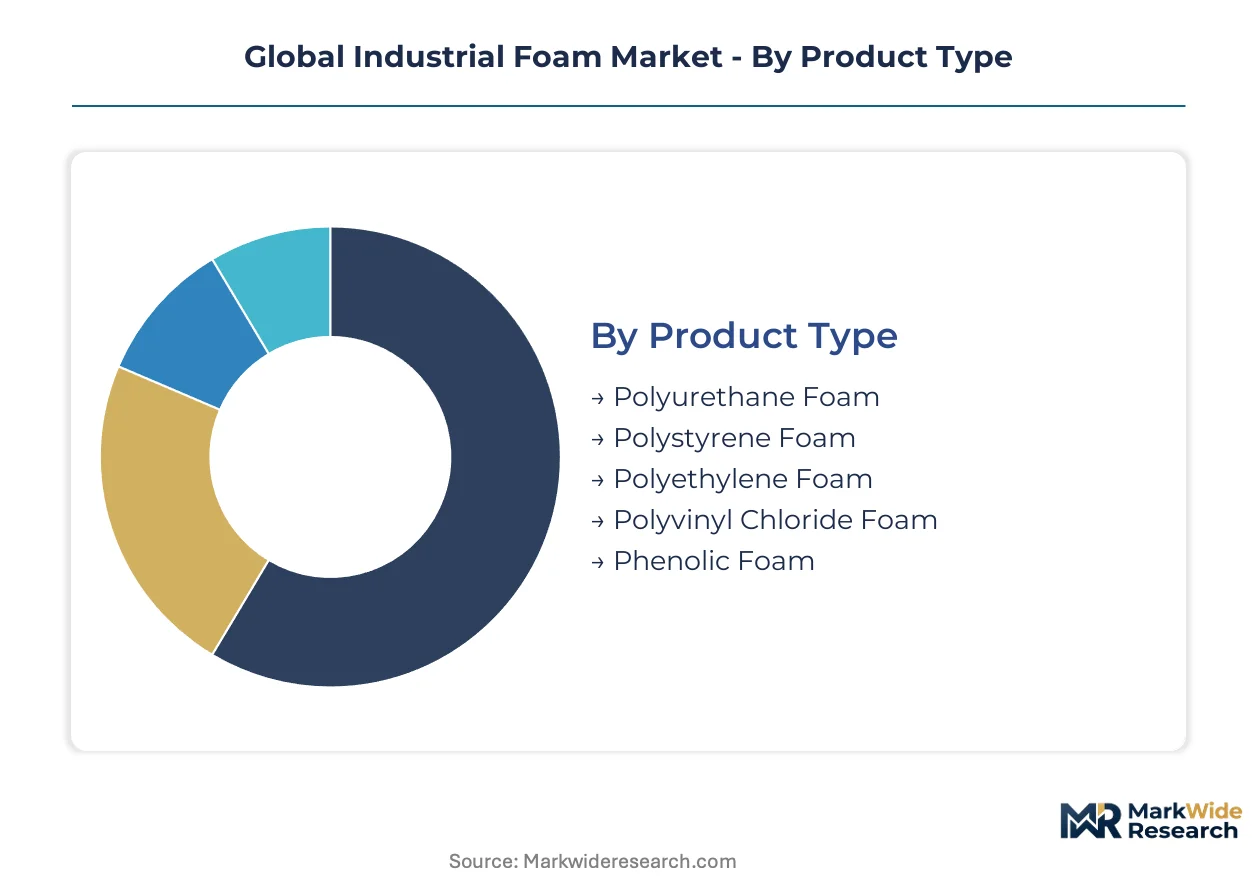
Industrial foam markets fragment across material chemistry, application method, and end-use performance requirements. Channel access and specification authority vary sharply by segment, with construction and automotive OEMs demanding direct technical engagement while packaging flows through distributor networks.
Product Type:
Polyurethane systems move through direct sales channels to appliance OEMs and construction specifiers, while commodity polystyrene routes through regional distributors serving packaging converters.
- Polyurethane Foam:Cellular structures formed from isocyanate-polyol reactions deliver tunable density gradients from 10 to 800 kg/m³. Demand concentrates in Germany's building retrofit sector and China's eastern coastal appliance clusters, where REACH-compliant formulations and GB standard thermal performance drive specification. Polyurethane dominates installed base. Phenolic systems are where expansion concentrates for fire-rated aviation and rail applications.
- Polystyrene Foam:Expanded bead structures provide cost-optimized thermal insulation at densities below 30 kg/m³. Construction contractors across India's cold chain buildout and US residential retrofits specify bulk volumes, though EU F-Gas phase-down pressures are compressing margins. Polystyrene dominates installed base. Polyethylene systems are where expansion concentrates for moisture-resistant marine and electronics packaging.
- Polyethylene Foam:Closed-cell cross-linked structures absorb impact energy without moisture absorption, serving marine flotation and consumer electronics cushioning.
- Polyvinyl Chloride Foam:Semi-rigid open-cell formulations bond aggressively to substrates, finding use in automotive interior trim and marine decking.
- Phenolic Foam:Thermoset networks with superior fire resistance ratings under EN 13501-1 command premium positioning in commercial aviation insulation and rail infrastructure.
Material selection increasingly hinges on blowing agent compliance timelines rather than base polymer economics alone.
Application:
Cost tier stratification separates specification-grade insulation from commodity packaging, with filtration and sealing occupying mid-tier technical niches.
- Insulation:Rigid polyurethane and phenolic panels reduce thermal bridging in building envelopes and refrigerated transport. German Building Energy Act mandates and Japan's ZEB certification accelerate spray foam retrofit demand, while EU F-Gas Regulation forces HFO blowing agent transitions. Insulation dominates installed base. Sealing applications are where expansion concentrates for electric vehicle battery thermal management.
- Packaging:Expanded polystyrene and polyethylene foams protect electronics and pharmaceuticals through controlled cushioning and moisture barriers. E-commerce fulfillment centers across China's Pearl River Delta and India's logistics corridors drive volume, though sustainability pressures favor recycled content and bio-based alternatives. Packaging dominates installed base. Filtration is where expansion concentrates for HVAC and medical device applications.
- Cushioning:Viscoelastic polyurethane formulations absorb impact in furniture, bedding, and transportation seating.
- Filtration:Reticulated polyurethane structures with engineered pore sizes capture particulates in industrial air handling and medical devices.
- Sealing:Elastomeric foams compress to form environmental barriers in automotive, marine, and building envelope joints.
Application mix is shifting toward higher-margin technical specifications as commodity packaging faces circular economy compliance costs.
End User Industry:
Customer type fragmentation separates project-based construction procurement from continuous manufacturing demand in electronics and furniture.
- Construction:Building envelope retrofits and cold storage facilities specify rigid foam systems through energy performance consultants rather than traditional distributors. Germany's Building Energy Act and California Title 24 mandates compress qualification timelines for low-GWP formulations. Construction dominates installed base. Consumer electronics are where expansion concentrates for protective packaging and thermal interface materials.
- Consumer Electronics:Precision-molded polyethylene and polyurethane foams protect high-value components through automated packaging lines. Jiangsu and Guangdong province manufacturing clusters sustain concentrated demand, with sustainability officers now requiring EPD verification for cradle-to-grave carbon accounting. Consumer electronics dominates installed base. Aerospace is where expansion concentrates for lightweight fire-rated insulation.
- Aerospace:Phenolic and advanced polyurethane systems meet FAR 25.853 fire safety standards for cabin and cargo insulation.
- Marine:Buoyancy foams and deck core materials resist saltwater degradation in recreational and commercial vessel construction.
- Furniture Manufacturing:Flexible polyurethane slabstock and molded cushions serve bedding and seating producers through just-in-time delivery contracts.
End user concentration in China's manufacturing clusters exposes suppliers to regional demand volatility and local content requirements.
Manufacturing Process:
Maturity gradients separate established extrusion and molding from emerging spray foam application methods requiring contractor equipment upgrades.
- Reaction Injection Molding:High-pressure impingement mixing delivers complex automotive and furniture components with rapid cycle times. OEM qualification protocols at German and Japanese automotive lightweighting programs demand precise density control and surface finish consistency. Reaction injection molding dominates installed base. Spray foam is where expansion concentrates for on-site building envelope retrofits.
- Spray Foam:Portable dispensing equipment applies polyurethane systems directly to construction substrates, eliminating panel fabrication and shipping costs. Contractor bases across Nordic markets and US weatherization programs face capital deployment requirements for low-pressure equipment compatible with HFO and hydrocarbon blowing agents. Spray foam dominates installed base. Extrusion is where expansion concentrates for continuous panel and film production.
- Extrusion:Continuous bead expansion produces polystyrene boardstock and polyethylene film at scale for packaging and construction.
- Compression Molding:Heated tool consolidation shapes recycled and virgin foam composites into automotive and marine components.
- Pouring:Open-mold gravity filling produces large-block slabstock for subsequent fabrication into furniture and insulation products.
Process selection increasingly couples with blowing agent transition timelines, as legacy equipment retrofit costs reshape competitive economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand dynamics, while China's GB standards and Japan's METI efficiency programs shape procurement patterns across Asia-Pacific manufacturing clusters.
United States
EPA SNAP program restrictions on hydrofluorocarbon blowing agents are compressing reformulation timelines for construction and appliance producers. California Title 24 building codes and federal weatherization programs accelerate spray foam retrofit specifications. The US Gulf Coast petrochemical corridor sustains captive isocyanate supply for integrated foam system houses serving the domestic market.
Germany
The Building Energy Act mandates deep retrofit insulation across existing commercial and residential envelopes. REACH substance authorization timelines under ECHA review constrain legacy flame retardant chemistries in fire-rated applications. Ludwigshafen and the broader Rhine-Ruhr industrial region concentrate polyurethane precursor production and advanced formulation R&D capabilities.
China
GB standards for building materials and dual carbon policy targets reshape thermal insulation specifications in construction and cold chain infrastructure. Jiangsu, Zhejiang, and Guangdong provinces sustain concentrated appliance and electronics manufacturing clusters driving bulk polyurethane slabstock consumption. Eastern coastal manufacturing bases dominate regional foam demand through integrated supply chains.
Japan
METI-backed ZEB certification creates premium-tier demand for vacuum-insulated panel hybrids and high-R-value spray foam in commercial newbuilds. JIS fire safety classifications constrain phenolic and polyurethane system approvals for rail and aviation applications. The Kanto and Kansai industrial corridors anchor automotive lightweighting programs accelerating aliphatic polyurethane adoption.
India
FSSAI food safety mandates and national cold chain mission targets open specification windows for polyurethane insulated panels and refrigerated transport foam. BIS certification requirements and PLI scheme incentives attract domestic manufacturing investment in insulation systems. Maharashtra and Gujarat logistics corridors drive cold storage facility construction specifying rigid foam envelope solutions.
Global Industrial Foam Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive isocyanate supply and formulation agility determining competitive position. The structure concentrates around petrochemical-integrated system houses, application-equipment specialists, and regional foam fabricators serving construction and packaging end-uses. Two strategic archetypes dominate: vertically integrated precursors-to-systems operators, and formulation-focused system houses with deep technical service capabilities. Capacity expansion into low-GWP blowing agent qualifications and strategic partnerships for bio-based polyol sourcing represent the dominant competitive moves.
Among German-integrated chemical conglomerates, BASF SE and Covestro AG occupy positions exemplifying the captive-supply archetype, with Ludwigshafen and Leverkusen sites anchoring European isocyanate and specialty polyurethane production. Huntsman Corporation represents the multinational system-house model, with Rotterdam operational scale supplying construction and appliance manufacturers across the Benelux region. These three entities illustrate how geographic proximity to precursor production and regulatory stringency concentration shapes competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| The Dow Chemical Company |
| Huntsman Corporation |
| Sekisui Chemical Co., Ltd. |
| Saint-Gobain |
| DuPont |
| Armacell International S.A. |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German polyurethane system houses and appliance OEMs lock in MDI precursor supply while capping price volatility exposure for both parties. This structure concentrates pricing power among Ludwigshafen and Rotterdam-integrated producers who control captive isocyanate output, while smaller compounders absorb margin compression from spot-market TDI purchases.
Pricing Analysis
Price spreads between German REACH-compliant formulations and Chinese GB-standard alternatives run wide enough to sustain parallel sourcing strategies for multinational appliance manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates aliphatic UV-stable systems from commodity rigid insulation and recycled-content packaging grades. Cost compression in commodity polystyrene is intensifying because EU F-Gas phase-down forces stranded HFC inventory liquidation. Construction specifiers show lowest price sensitivity, prioritizing EPD-verified carbon footprints over unit economics.
Supply Chain Analysis
Inventory cycles for MDI and TDI precursors stretch 6-8 weeks from German and US Gulf Coast petrochemical complexes to European foam fabricators. Supply draws from concentrated isocyanate production in Germany, China, and the US Gulf Coast, with specialty aliphatic polyols sourcing from Japanese Kanto chemical corridors. Single-source vulnerability in HFO blowing agent supply creates qualification bottlenecks for construction spray foam contractors. Distribution runs through direct technical sales to appliance OEMs and construction specifiers, with packaging flowing via regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Industrial Foam Market is cycling through a capital equipment replacement wave as contractors and fabricators retool for low-GWP blowing agent compatibility. This recovery phase favors producers with qualified HFO formulations and equipment financing capabilities.
For Market Incumbents: Consolidate formulation expertise around aliphatic polyurethane and next-generation blowing agent compatibility to defend against specialty chemical entrants from Asian R&D hubs. Prioritize captive MDI supply expansion at Ludwigshafen-scale integrated sites to offset feedstock volatility. Lock in long-term offtake with German appliance OEMs before REACH authorization timelines sunset legacy flame retardant chemistries. For New Entrants and Emerging Players: Lead with bio-based polyol formulations targeting sustainability-committed Nordic construction specifiers and California Title 24 retrofit mandates. India's cold chain infrastructure buildout offers the most penetrable geography, with FSSAI compliance creating specification barriers incumbents have not fully exploited. Partner with European equipment manufacturers for low-pressure dispensing technology transfer to accelerate contractor base qualification. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap system houses with qualified HFO portfolios and established contractor financing programs. The 5-10 year viability window favors producers with backward integration into isocyanate precursors or exclusive bio-based polyol supply agreements. Watch for inflection when EU F-Gas phase-down accelerates beyond current 2030 trajectory, compressing margins for non-compliant inventory holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Precursors | Ludwigshafen-scale captive MDI supply insulates margin from feedstock volatility and force majeure risk. |
| Long-term Supply Agreement for HFO Blowing Agents | Exclusive offtake with Honeywell or Chemours secures qualification data lead time over reformulation-lagged competitors. |
| Joint Venture for Bio-based Polyol Production | Castor oil and soy-derived feedstock partnerships with agricultural processors enable carbon footprint differentiation. |
| Capacity Expansion in India Cold Chain Corridor | Maharashtra and Gujarat facility investment captures FSSAI-mandated refrigerated transport foam demand. |
| Green Manufacturing Transition | EPD verification and cradle-to-grave carbon accounting unlocks premium pricing with Nordic energy performance consultants. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with polyurethane plant managers, appliance OEM procurement leads, construction energy performance consultants, and spray foam contractor networks; and secondary validation through customs/trade data, SEC 10-K filings of listed chemical conglomerates, ECHA REACH authorization databases, and German Building Energy Act implementation records. Bottom-up triangulation across formulation-grade consumption estimates and top-down reconciliation against isocyanate precursor production volumes anchored value and volume outputs.
Across the projection horizon, the analytical framework modeled segmentation dimensions including material chemistry tier, end-use industry vertical, blowing agent compliance status, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating appliance production forecasts, building retrofit mandate penetration rates, and cold chain infrastructure investment pipelines. Key inputs included EU F-Gas phase-down trajectory assumptions and China dual carbon policy implementation intensity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of low-GWP transitions or alternative feedstock cost parity would require recalibration. Forecasts reflect assumptions around polymer chemist talent availability and HFO supply scale-up timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Europe MDI-Based PU Technical Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Global Electrical Insulation Materials Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
Global Acoustic Insulation Material Market
Insulation Materials
Thermal Tapes Market