
 Global Thermal Interface Materials Market | 2026-2036
Global Thermal Interface Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Interface Materials Market Foresight
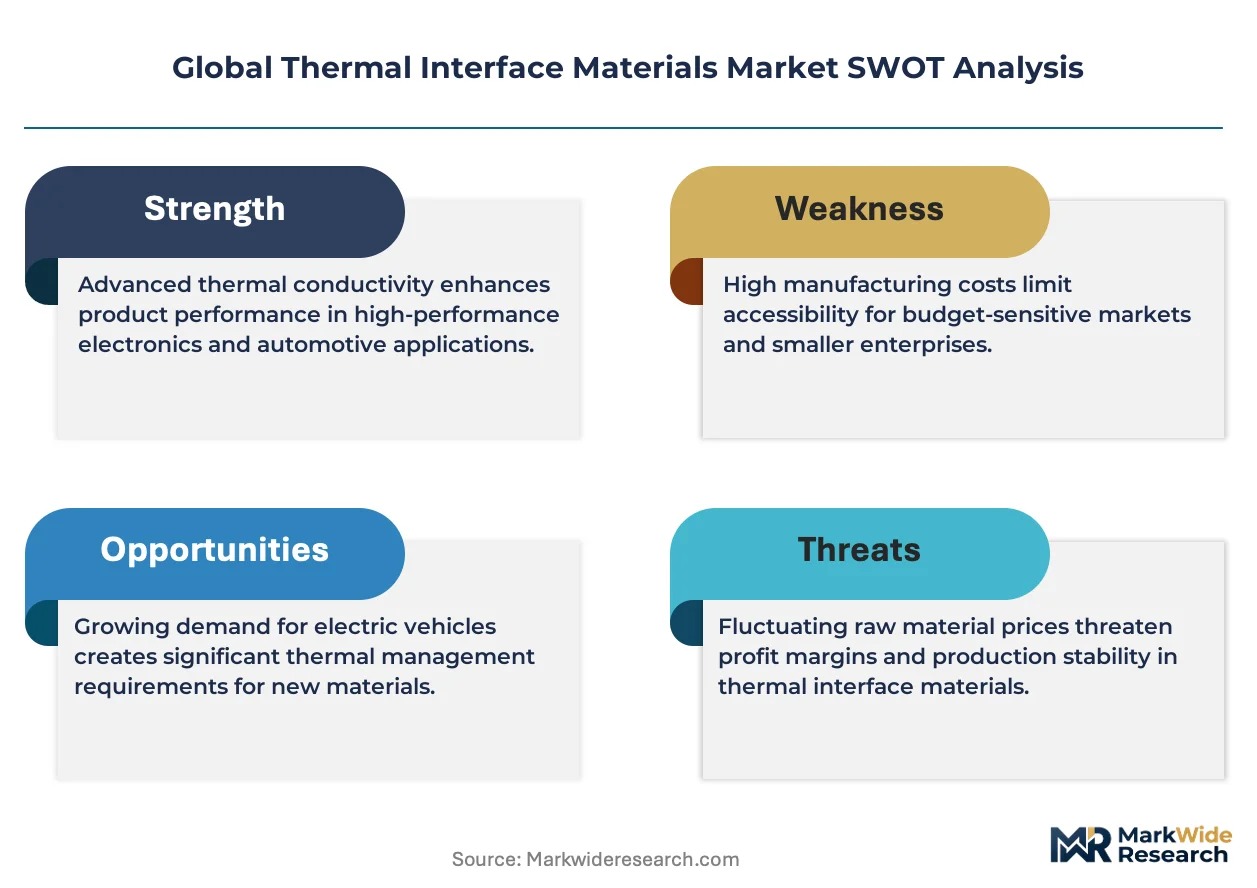
Data center operators is redrawing procurement priorities across the thermal interface materials landscape, shifting volume toward high-performance formulations that manage power-dense chip architectures. Honeywell International Inc. leverages its fluoropolymer expertise to anchor positions in aerospace and semiconductor cooling segments. Henkel AG & Co. KGaA sustains broad adhesive and phase change portfolios that span automotive electronics and consumer device assembly. Indium Corporation specializes in solder-based metal TIMs that occupy premium niches where thermal conductivity thresholds exceed conventional polymer capabilities.
Thermal interface materials are engineered substances applied between heat-generating components and heat dissipation hardware to minimize thermal resistance at mating surfaces, typically achieving bulk conductivities ranging from one to over fifty watts per meter-kelvin depending on filler loading and matrix chemistry. Their primary purpose is to eliminate air gaps—poor thermal conductors—and ensure efficient heat transfer in electronics packaging, power modules, and LED assemblies. Phase change materials dominate margins in server and telecom applications where interface stability under thermal cycling commands price premiums. Carbon-based TIMs represent the fastest-growing product category as graphene and carbon nanotube loadings displace legacy metal oxide formulations in high-frequency computing. Silicone technology retains volume leadership across consumer electronics due to process compatibility and established supply chains.
The EPA regulates volatile organic compound emissions from TIM manufacturing facilities in the United States, while REACH compliance in Europe restricts certain filler chemistries and mandates substance registration for imported formulations. China's MEE enforces dual carbon-aligned efficiency standards that elevate thermal performance requirements in domestic electronics production. ISO thermal conductivity test methods provide the measurement protocols that OEMs and contract manufacturers reference in supplier qualification. Stakeholders must monitor evolving halogen-free mandates and carbon border adjustment mechanisms as these frameworks increasingly determine market access and product formulation roadmaps.
Market Dynamics
Power density thresholds in AI accelerators and high-performance computing chips are forcing thermal interface materials to bridge ever-widening gaps between heat generation and dissipation capacity, compressing supplier qualification timelines and elevating performance specifications across procurement cycles.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbon-based cooling systems are redirecting capital toward solid-state and phase-change TIM formulations in European data center construction.
- Silicone-carbon hybrid chemistries:Next-generation filler loadings combining boron nitride with aligned carbon nanotubes are unlocking conductivity thresholds previously reserved for solder-based metal TIMs at polymer price points.
- Taiwan semiconductor packaging clusters:Concentrated advanced packaging investment around Hsinchu and Tainan Science Parks is generating captive demand for ultra-thin bondline TIMs in chiplet architectures.
Market Restraints
- Silver and indium price volatility:Metal TIM formulations remain exposed to precious metal commodity swings, compressing margin stability for solder-based product lines.
- Fluoropolymer supply concentration:Perfluorinated polymer precursors for high-performance TIM matrices concentrate among Japanese and Chinese chemical producers, creating single-source vulnerability.
- REACH substance authorization delays:Pending ECHA decisions on certain boron compound classifications are freezing formulation roadmaps for European-bound product families.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly are seeding greenfield TIM demand in Noida and Bengaluru corridors.
- Two-phase immersion cooling convergence:Dielectric fluid systems paired with engineered TIM layers are opening architectural redesign opportunities in hyperscale server deployments.
- Direct-to-OEM digital channels:Specification tools and thermal simulation platforms are collapsing traditional distributor layers in mid-volume electronics procurement.
Industry Challenges
- Thin-film metrology expertise:Sub-50-micron bondline characterization requires specialized thermal conductivity measurement capabilities that outpace current technician training pipelines.
- Multi-jurisdiction substance registration:Simultaneous EPA TSCA, REACH, and China MEE filing requirements are extending new product introduction timelines by 18-24 months.
- Legacy equipment retrofit compatibility:Next-generation high-viscosity TIMs face dispensing system recalibration requirements that slow adoption in established automotive electronics lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Interface Materials Market |
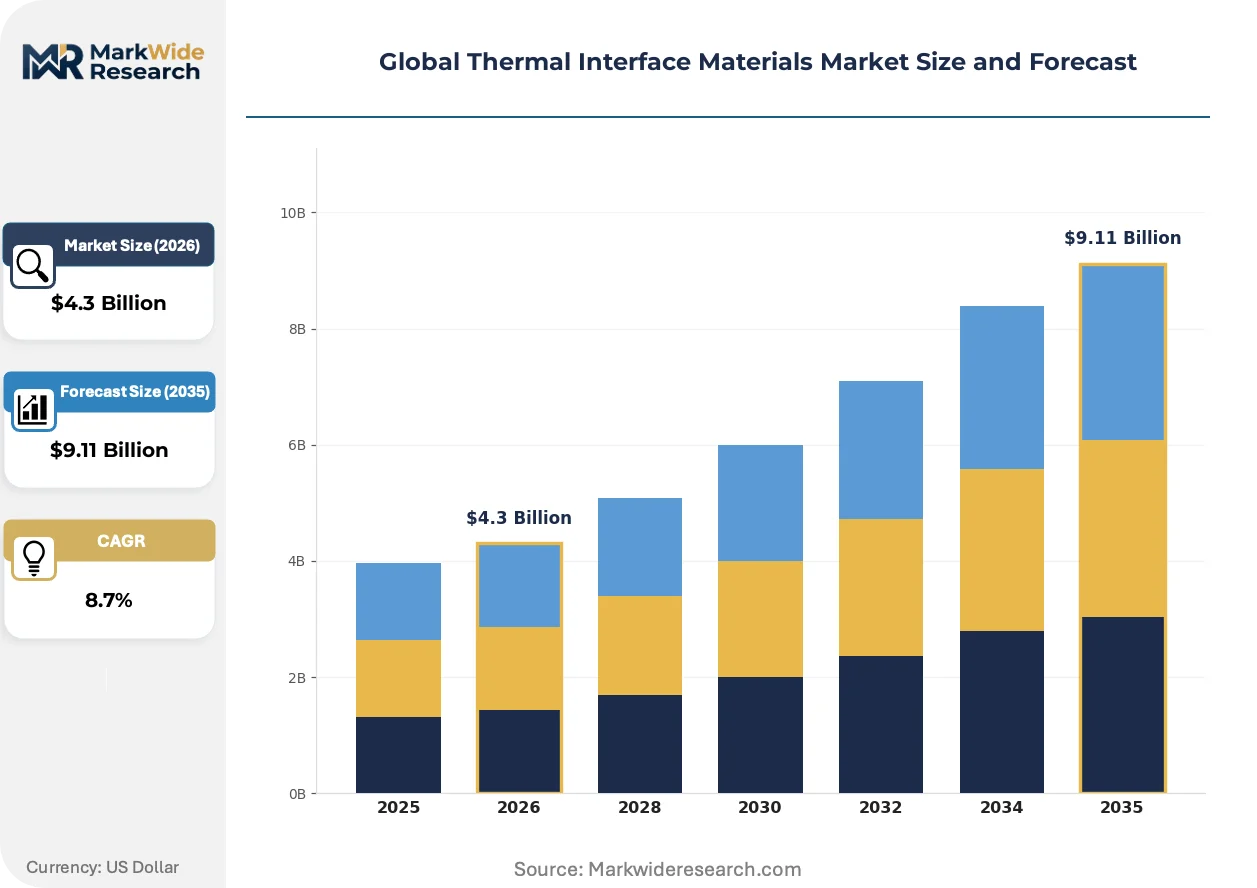
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $9.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Grease, Thermal Pads, Phase Change Materials, Metal-Based TIMs, Carbon-Based TIMs Technology: Silicone, Epoxy, Acrylic, Polyimide, Ceramics Application: Consumer Electronics, Data Centers, LED Lighting, Telecommunication Equipment, Aerospace End User: OEMs, Contract Manufacturers, Aftermarket Service Providers, Electronics Assembly Companies |
| Companies Covered | Honeywell International Inc., 3M, Henkel AG & Co. KGaA, Parker Hannifin Corporation, Dow, Indium Corporation, Shin-Etsu Chemical, Momentive, Laird Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Interface Materials Market Shifts & Advancements
Graphene-loaded polymer matrices and automated precision dispensing systems are compressing the performance-cost frontier, while regulatory chemistry restrictions and buyer consolidation are simultaneously reshaping supplier competitive terrain.
Graphene-enhanced silicone TIMs are achieving bulk conductivities exceeding 15 W/m-K through aligned filler networks and controlled exfoliation processes. Data center operators in Singapore and the Netherlands are qualifying these formulations for direct-die cooling in GPU clusters. The technology is miniaturizing thermal management footprints, enabling denser server rack configurations without liquid cooling infrastructure retrofits.
China's MEE enforcement of dual carbon-aligned efficiency standards is elevating thermal performance verification requirements for domestically manufactured electronics. Domestic OEMs must now submit third-party validated thermal resistance data for products above specified power thresholds. Server and telecom equipment categories face the steepest compliance ramps, with Shenzhen and Suzhou manufacturers accelerating TIM specification upgrades to maintain market access.
Hyperscale buyers are consolidating supplier rosters from 15-20 qualified vendors toward 5-7 strategic partners with full-stack thermal simulation support. Contract manufacturers in Malaysia and Vietnam report compressed switching cycles as OEMs demand faster qualification of alternative TIM sources. Automotive power module assembly represents the most visible vertical for this pattern, where tier-one suppliers now require dedicated application engineering presence at their thermal design centers.
Global Thermal Interface Materials Market Segmentation
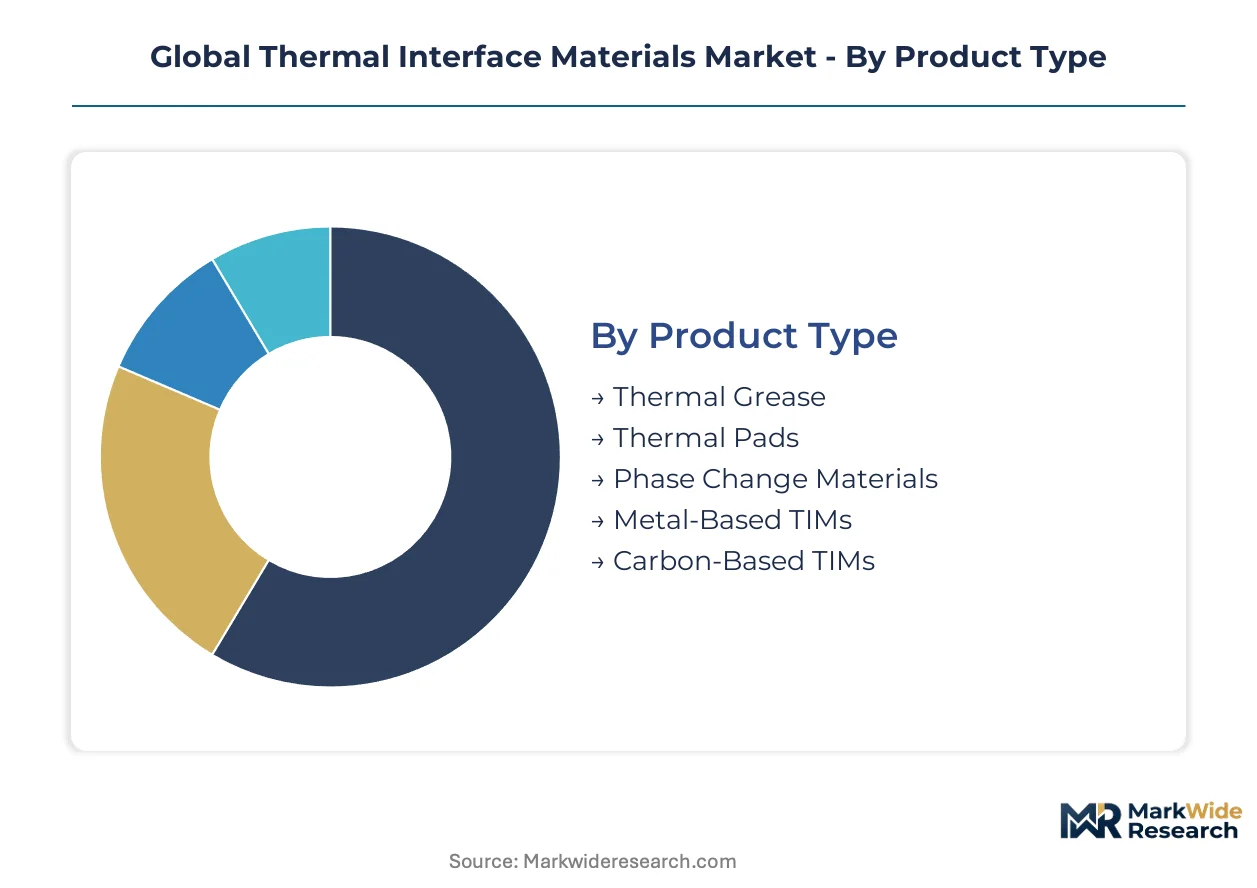
Thermal interface materials segmentation reflects divergent technical requirements across power density thresholds, with substitution pressure intensifying where legacy formulations face displacement by advanced filler technologies. Product architecture, base chemistry, application environment, and procurement channel each reshape supplier positioning and margin structures.
Product Type:
Carbon-based TIMs exert the strongest substitution pressure on incumbent metal and polymer formulations, leveraging graphene and aligned nanotube loadings to match solder-based conductivity at reduced weight and cost.
- Thermal Grease:Silicone or hydrocarbon carriers loaded with metal oxide or ceramic fillers achieve bondlines below 25 microns for CPU-GPU cooling in consumer laptops. Procurement concentrates among Shenzhen and Dongguan contract manufacturers serving notebook OEMs, though pump-out failures under thermal cycling constrain automotive qualification timelines.
- Phase Change Materials:Solid-to-liquid transition formulations at 45-60°C melt points eliminate pump-out while maintaining conformability under clamp pressure. Data center operators in Singapore and the Netherlands are qualifying these for direct-die GPU cooling, where interface stability across thousands of thermal cycles commands price premiums over grease alternatives.
- Thermal Pads:Pre-cured silicone or acrylic sheets with fiberglass reinforcement provide consistent thickness for automated assembly in LED backlight modules and power supplies.
- Metal-Based TIMs:Indium, tin-bismuth, and silver-filled solders occupy aerospace and high-reliability power module niches where thermal conductivity exceeds 50 W/m-K.
- Carbon-Based TIMs:Graphene and carbon nanotube loadings in silicone or epoxy matrices are displacing legacy metal oxide formulations in 5G base stations and AI accelerators.
Thermal grease anchors the volume base while carbon-based TIMs gain share at the steepest rate.
Technology:
Silicone chemistry dominates cost-tier positioning, with epoxy and polyimide alternatives capturing premium applications where outgassing constraints or extended temperature ranges justify formulation switching costs.
- Silicone:Dimethylsiloxane backbones with boron nitride or alumina fillers retain process compatibility across consumer electronics assembly lines in Taiwan and Vietnam. Hsinchu packaging houses specify these for chiplet architectures where reworkability and established supply chains outweigh conductivity limitations.
- Ceramics:Aluminum nitride and boron nitride particulate compacts achieve thermal conductivities above 30 W/m-K for direct-bonded copper substrates in electric vehicle power modules. Japanese automotive tier-one suppliers in Nagoya and Toyota City are qualifying these for 800V inverter platforms where dielectric strength and thermal performance must coexist.
- Epoxy:Rigid thermoset matrices with silica or metal fillers serve automotive underhood sensors and LED encapsulation where silicone volatility is prohibited.
- Acrylic:Lower-cost alternatives with moderate conductivity target white goods and appliance motor controllers in cost-sensitive procurement environments.
- Polyimide:Aromatic polymer backbones withstand continuous operation above 200°C in aerospace avionics and downhole drilling electronics.
Silicone technology captures the broadest application footprint while ceramics expand most quickly in electrified transportation.
Application:
Data center infrastructure is driving the steepest specification upgrades, with AI accelerator power densities forcing TIM performance thresholds that outpace legacy consumer electronics requirements.
- Data Centers:Hyperscale operators in Northern Virginia and Frankfurt are consolidating supplier rosters around vendors offering full-stack thermal simulation, with direct-die cooling for GPU clusters requiring sub-40-micron bondlines and validated reliability data. Two-phase immersion cooling architectures are opening engineered TIM layer opportunities.
- Consumer Electronics:Smartphone and tablet assembly in Zhengzhou and Chennai relies on thin-film silicone TIMs for processor heat spreading, though thermal design margins are compressing as chassis volumes shrink.
- LED Lighting:Streetlight and high-bay fixture manufacturers in Dongguan specify thermally conductive pads for COB array mounting.
- Telecommunication Equipment:5G massive MIMO radios and baseband units require TIMs surviving outdoor temperature extremes across deployment climates.
- Aerospace:Satellite and avionics applications demand outgassing-tested formulations meeting ASTM E595 standards for vacuum environments.
Consumer electronics anchors the volume base while data center applications gain share at the steepest rate.
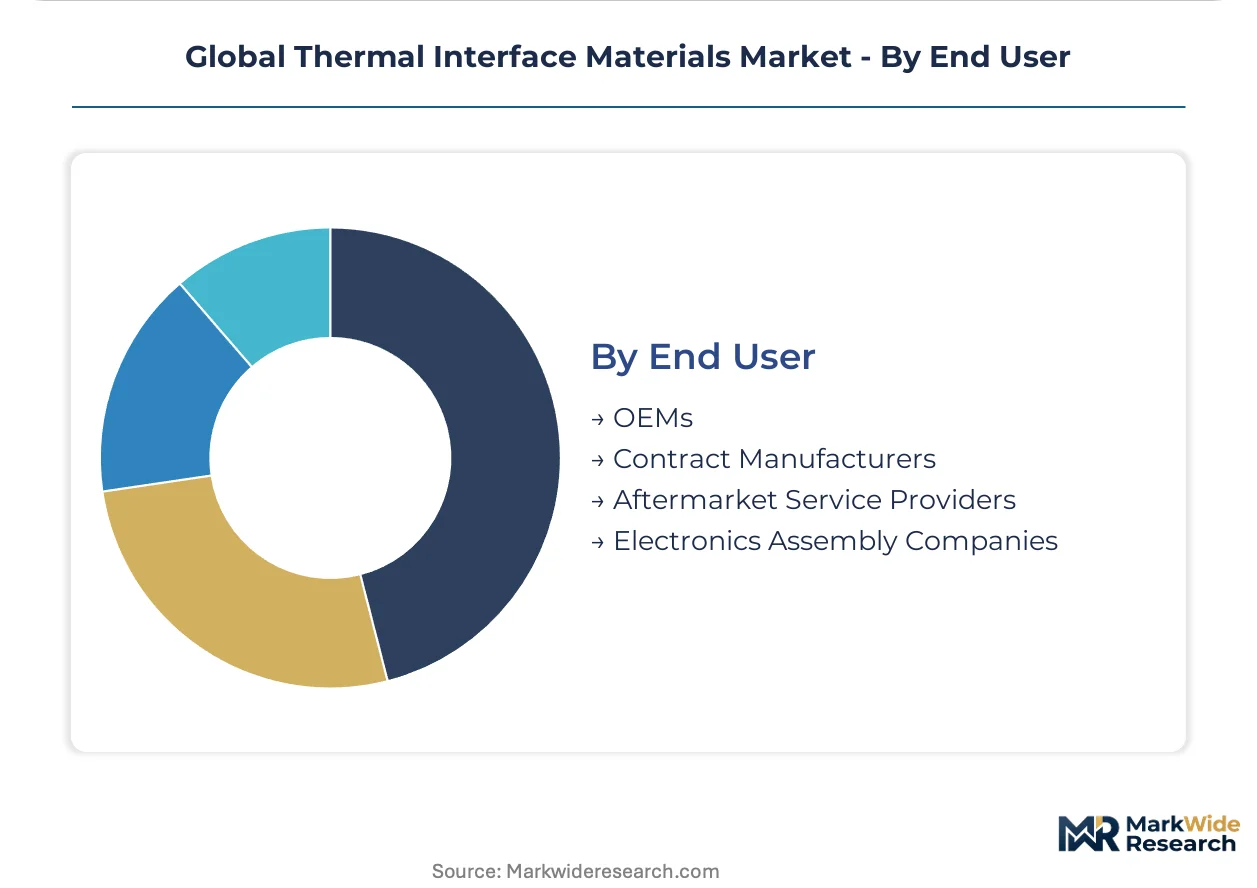
End User:
Contract manufacturers are consolidating procurement influence, leveraging scale to compress supplier margins while demanding faster qualification cycles and dedicated application engineering support.
- OEMs:Apple, Dell, and HP thermal design centers specify TIM performance thresholds and validate supplier processes directly, though increasing reliance on ODM partners is shifting procurement execution downward.
- Contract Manufacturers:Foxconn, Pegatron, and Jabil facilities in Malaysia and Vietnam report compressed switching cycles as OEMs demand dual-source TIM qualification within 90-day windows, with dedicated application engineering presence now required for automotive power module awards.
- Electronics Assembly Companies:Mid-tier EMS providers serving industrial and medical device markets prioritize inventory flexibility and technical support over minimum pricing.
- Aftermarket Service Providers:Repair shops and refurbishment operations consume bulk thermal grease and pad formats for laptop and gaming console servicing.
Contract manufacturers anchor the volume base while OEM direct procurement gains share at the steepest rate in high-reliability segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical precursors for high-performance TIM matrices concentrate among Japanese and Chinese producers, creating geographic supply dependencies that shape procurement strategies across end-use sectors. Taiwan and South Korea host the densest concentrations of advanced packaging demand, while regulatory divergence between Washington, Brussels, and Beijing is fragmenting compliance roadmaps.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is absorbing premium phase-change TIM formulations for direct-die GPU cooling. The EPA regulates volatile organic compound emissions from manufacturing facilities under TSCA, tightening environmental compliance for domestic production. Intel and AMD thermal design centers in Hillsboro and Austin are validating sub-40-micron bondline specifications for AI accelerator packages.
China
Domestic OEMs are accelerating TIM specification upgrades to meet MEE-enforced dual carbon-aligned efficiency standards for electronics above specified power thresholds. The country's national environmental regulator mandates third-party validated thermal resistance data for server and telecom equipment categories. Shenzhen and Suzhou manufacturers face the steepest compliance ramps as they supply global notebook and smartphone assembly lines.
Germany
Automotive tier-one suppliers in Stuttgart and Munich are qualifying ceramic TIM compacts for 800V electric vehicle inverter platforms where dielectric strength and thermal performance must coexist. The EU F-Gas Regulation phase-down mandates for hydrofluorocarbon-based cooling systems are redirecting capital toward solid-state TIM formulations in Frankfurt data center construction. Bavarian industrial clusters anchor European demand for high-reliability power module thermal management.
Japan
Perfluorinated polymer precursors for aerospace-grade TIM matrices concentrate among domestic chemical producers, creating single-source vulnerability for global supply chains. METI oversees industrial standards alignment with international thermal conductivity test protocols. Nagoya and Toyota City packaging houses are expanding capacity for chiplet architectures requiring ultra-thin bondline control.
Singapore
Data center operators are qualifying graphene-enhanced silicone TIMs for direct-die cooling in GPU clusters without liquid cooling infrastructure retrofits. The city-state's national environmental agency enforces efficiency standards that elevate thermal performance verification requirements. Tuas and Changi North facilities represent Southeast Asia's densest concentration of hyperscale server deployment.
Global Thermal Interface Materials Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and specialized thermal management firms that span multiple technology tiers. The vendor base organizes around three strategic archetypes: fluoropolymer specialists leveraging aerospace heritage, adhesive formulators with broad electronics assembly portfolios, and metal TIM purists occupying premium conductivity niches. Competitive dynamics revolve around M&A activity consolidating formulation capabilities and strategic partnerships locking in hyperscale data center supply agreements.
Among diversified industrial conglomerates, Honeywell International Inc. and 3M occupy positions that exemplify the fluoropolymer-specialist archetype, while Henkel AG & Co. KGaA represents the adhesive-formulator model with broad chemistry reach. Indium Corporation sits within the metal-TIM specialist tier. These three anchors illustrate how competitive positioning fragments across thermal conductivity thresholds and end-use reliability requirements rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corporation |
| Dow |
| Indium Corporation |
| Shin-Etsu Chemical |
| Momentive |
| Laird Technologies |
| Others |
Supply & Pricing Matrix
Carbon-based filler substitution for legacy metal oxide formulations is redrawing procurement geography while compressing unit economics across performance tiers. Graphene and aligned nanotube loadings sourced from Chinese and Japanese chemical producers now match solder-based conductivity at polymer price points, forcing incumbent suppliers to recalibrate margin structures.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European data center procurement, with phase-down mandates for hydrofluorocarbon cooling systems redirecting capital toward solid-state and phase-change TIM formulations. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified metal TIMs from automotive ceramic compacts and consumer electronics silicone grades. Cost compression in mid-tier silicone formulations is intensifying because contract manufacturers in Vietnam and Malaysia are consolidating supplier rosters. Hyperscale data center operators exhibit the lowest price sensitivity due to thermal failure cost exposure, while white goods assemblers in cost-sensitive procurement environments drive aggressive standard-tier negotiation.
Supply Chain Analysis
Port congestion on Shanghai-Ningbo and Busan-Long Beach trade lanes is elevating inbound logistics costs for boron nitride and fluoropolymer precursor shipments. Perfluorinated polymer matrices concentrate among Japanese and Chinese chemical producers, while silicone base resins draw from South Korean and German petrochemical complexes. Single-source vulnerability pervades aerospace-grade fluoropolymer supply, with METI-aligned producers in Japan controlling critical precursor technology. Distribution runs through regional chemical distributors serving Hsinchu and Tainan packaging clusters, with direct-to-OEM digital channels collapsing traditional layers in mid-volume electronics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hyperscale data center operators consolidate supplier rosters from 15-20 qualified vendors toward 5-7 strategic partners, fragmenting incumbent pricing leverage.
For Market Incumbents: Secure captive supply of boron nitride and fluoropolymer precursors through backward integration into Japanese and Chinese chemical production. Defend automotive power module positions by embedding dedicated application engineering teams at Nagoya and Toyota City thermal design centers. Carbon-based TIM substitution represents the primary margin compression threat requiring formulation roadmap acceleration. For New Entrants and Emerging Players: Lead with graphene-enhanced silicone formulations targeting Singapore and Netherlands data center operators qualifying direct-die GPU cooling without liquid infrastructure retrofits. India's PLI scheme for electronics manufacturing seeds greenfield demand in Noida and Bengaluru corridors with limited incumbent saturation. Digital specification tools paired with thermal simulation platforms enable bypass of established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed adhesive formulators lacking carbon-based TIM capabilities or full-stack thermal simulation support. Long-term viability hinges on 5-10 year positioning within AI accelerator supply chains as power densities force specification upgrades. Monitor ECHA decisions on boron compound classifications as inflection indicator for European-bound product family valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemicals | Japanese fluoropolymer producers anchor aerospace-grade TIM matrices with single-source control. |
| Carbon-Based Formulation Launch | Graphene-loaded silicones displace metal oxide legacy in 5G base stations and AI accelerators. |
| Direct-to-OEM Digital Channel | Specification tools collapse distributor layers for mid-volume electronics procurement. |
| Application Engineering Embedding | Automotive tier-one suppliers now require dedicated presence at thermal design centers. |
| Long-Term Hyperscale Supply Agreement | Consolidated vendor rosters in Northern Virginia and Frankfurt lock in strategic partners. |
Research Methodology
A standing panel of thermal design engineers at semiconductor packaging houses, procurement leads at contract manufacturers, and application engineering directors at TIM suppliers provided ongoing calibration across the study period. Primary interviews with plant managers at Hsinchu and Tainan facilities, OEM thermal architects in Hillsboro and Austin, and distribution channel partners in Southeast Asia combined with secondary validation from SEC filings, customs trade data, and EPA TSCA registration databases. Bottom-up unit consumption models and top-down chemical industry shipment data underwent cross-triangulation to reconcile volume estimates.
Consistency checks against external benchmarks validated projections across the modeling period. Segmentation dimensions included product architecture, base chemistry, application environment, and procurement channel, with additional modeling of thermal conductivity tier and bondline thickness specification. CAGRs derived from fitted trend analysis incorporating AI accelerator deployment curves, dual carbon compliance ramps in China, and EU F-Gas Regulation phase-down timelines. Industry-specific inputs encompassed hyperscale data center capex disclosures and automotive power module production forecasts.
Underlying assumptions cover sustained AI accelerator power density escalation, continued dual carbon enforcement by China's MEE, and REACH substance authorization timelines, with deviation risk concentrated in precious metal commodity swings and fluoropolymer supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Global Electrochromic Materials Market
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Advanced Composite Materials Market
Advanced Materials
Global Aerogel Insulation Market
Advanced Materials
Thermal Spray Materials Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Graphite Materials Market
Advanced Materials
Global Glass Filled Nylon Market
Advanced Materials
Cold Plasma Market
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Advanced Carbon Materials Market