
 Global Advanced Insulation Material Market | 2026-2036
Global Advanced Insulation Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Insulation Material Market Foresight
Aerospace thermal management is restructuring procurement patterns across the advanced insulation value chain. Aspen Aerogels specializes in silica aerogel blankets rated for extreme temperature gradients in aviation and space applications. BASF SE leverages its polymer science base to compete in polyurethane foam systems for high-performance building envelopes. Johns Manville Corporation anchors North American supply through mineral wool and fiberglass platforms serving commercial construction and industrial OEMs.
Advanced insulation materials encompass engineered substances designed to minimize heat transfer through low thermal conductivity matrices, often achieving lambda values below 0.020 W/m·K via vacuum-depleted cores or nanoporous structures. These materials serve critical functions in energy conservation, process temperature control, and fire safety across industrial and built environments. Aerogel segments command premium positioning due to weight-specific performance in aerospace and cold-chain logistics, while vacuum insulation panels occupy the fastest-expanding niche in net-zero building retrofits where floor space constraints dominate. Fiberglass maintains volume leadership in cost-sensitive construction markets, though margin pools concentrate in composite and spray foam technologies serving automotive underhood and energy sector applications.
The EU Green Deal and F-Gas Regulation are mandating stepped reductions in blowing agent global warming potential, forcing reformulation across European foam producers. EPA energy conservation standards and OSHA workplace exposure limits shape product development trajectories and installation protocols in the United States. China's GB standards and dual carbon goals are accelerating domestic vacuum panel capacity while tightening import certification requirements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate material qualification costs and supply chain reconfiguration needs.
Market Dynamics
EU F-Gas Regulation is forcing stepped reductions in hydrofluorocarbon blowing agents across European polyurethane foam production. This regulatory compression is triggering material reformulation investments and supply chain reconfiguration toward low-GWP alternatives.
Growth Catalysts
- Aerospace thermal barrier procurement:OEMs are expanding aerogel blanket specifications for extreme temperature gradients in aviation and space applications.
- German industrial retrofit programs:Passive house construction and building envelope upgrades are accelerating vacuum insulation panel specification.
- China's dual carbon goals:Domestic GB standards are tightening energy efficiency mandates and accelerating vacuum panel manufacturing capacity expansion.
Market Restraints
- Silica precursor cost volatility:Aerogel production depends on alkoxide feedstock prices subject to petrochemical supply fluctuations.
- Panel manufacturing concentration:Vacuum insulation core production clusters in East Asian specialized fabricators, creating single-source vulnerability.
- Polyurethane blowing agent transition friction:EPA SNAP program restrictions and EU F-Gas phasedowns force capital-intensive formulation retooling without immediate performance parity.
Strategic Opportunities
- Indian cold-chain infrastructure:Temperature-controlled logistics expansion offers aerogel blanket penetration in pharmaceutical and food distribution.
- Building-integrated photovoltaics convergence:Vacuum insulation panels combined with solar thermal systems enable net-zero envelope retrofits in dense urban cores.
- US Inflation Reduction Act credits:Residential energy efficiency tax incentives are expanding contractor training programs for advanced insulation installation.
Industry Challenges
- Certification timeline compression:Fire safety testing under EN 13501-2 and ASTM E84 protocols extends product qualification cycles for new formulations.
- Installer skill scarcity:Vacuum panel handling protocols and aerogel dust containment require specialized training absent in conventional insulation trades.
- Legacy building integration complexity:Historical envelope retrofits demand custom panel sizing and vapor barrier coordination incompatible with standardized product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Insulation Material Market |
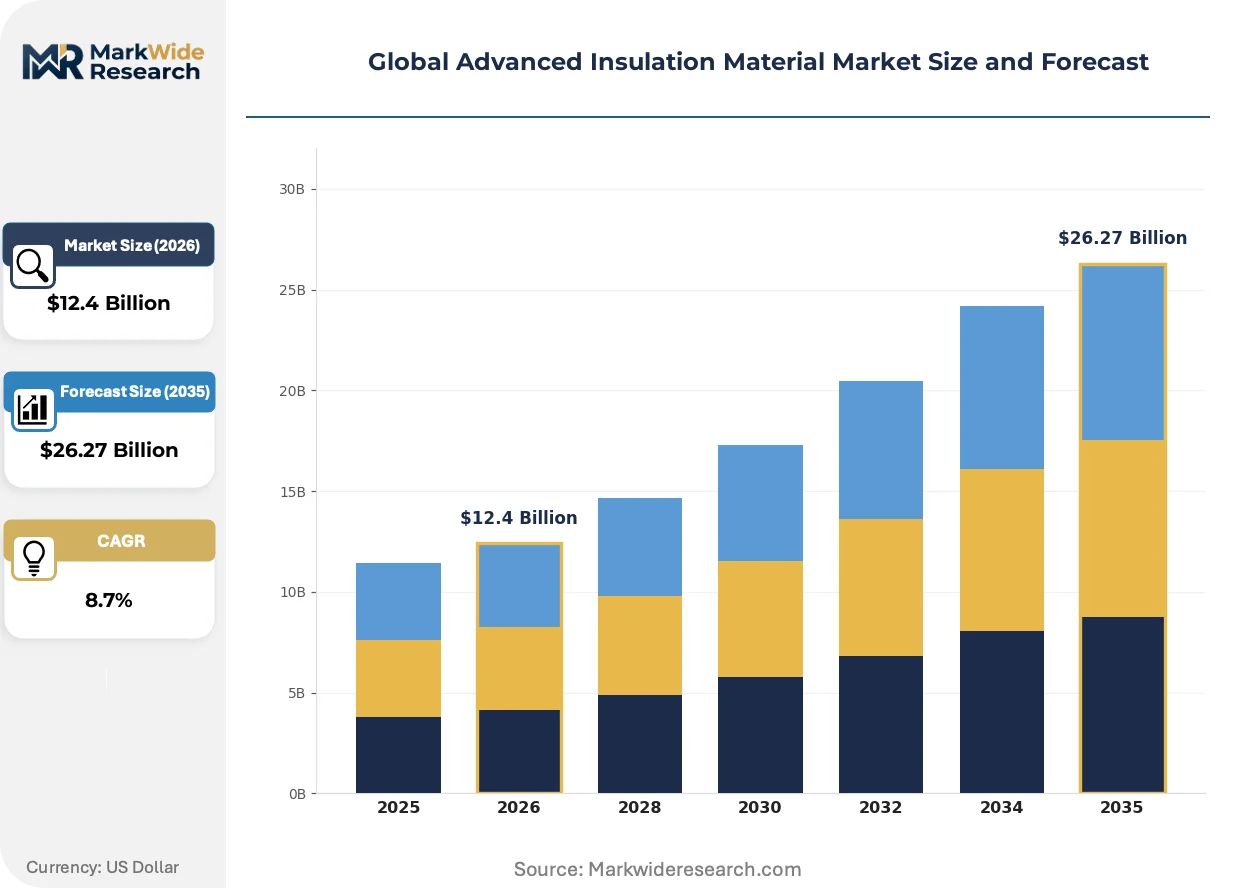
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
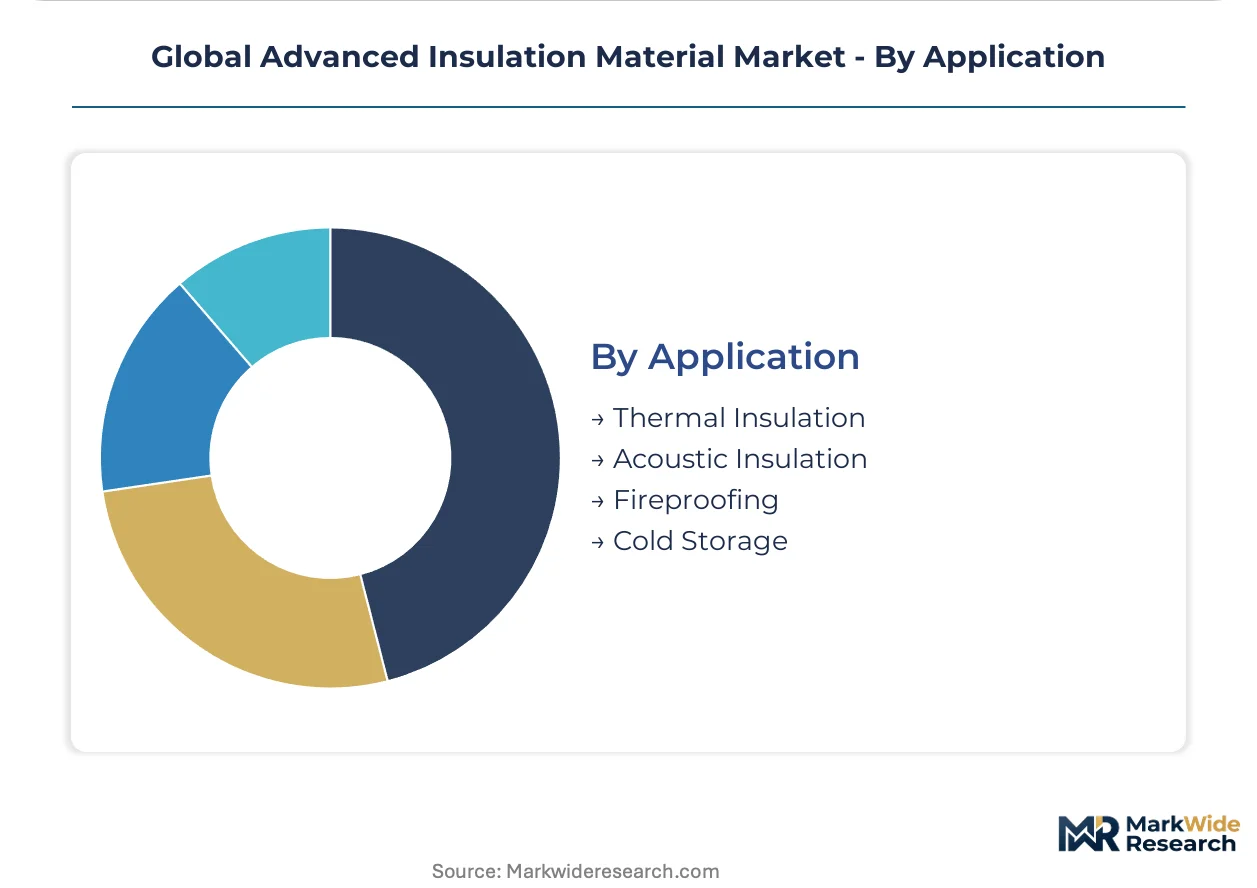
| Segmentation | Product Type: Foam, Fiberglass, Cellulose, Aerogel End User: Construction, Automotive, Aerospace, Energy Technology: Vacuum Insulation, Reflective Insulation, Composite Materials, Spray Foam Application: Thermal Insulation, Acoustic Insulation, Fireproofing, Cold Storage |
| Companies Covered | 3M Company, Dow Inc., Aspen Aerogels, Inc., Johns Manville Corporation, BASF SE, Rogers Corporation, Luyang Energy-saving Materials Co., Ltd., Morgan Advanced Materials plc, RHI Magnesita GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Insulation Material Market Shifts & Advancements
Material science convergence with digital manufacturing is compressing development cycles and enabling property-specific customization previously uneconomical at scale.
Machine learning-driven formulation optimization is automating the discovery of nanoporous structures with tailored thermal conductivity profiles. Materials startups and chemical conglomerates alike are deploying generative algorithms to accelerate silica aerogel density tuning. This capability is compressing R&D timelines from multi-year development cycles to iterative quarterly releases.
REACH authorization requirements are restricting legacy flame retardant chemistries in European construction foams. BASF and Covestro are reformulating polyisocyanurate systems to maintain fire ratings without halogenated additives. German and French building inspectors are now requiring third-party environmental product declarations alongside thermal performance certificates.
Buyers are consolidating specification authority into centralized procurement functions with engineering-grade technical requirements. Facility managers and sustainability officers are displacing traditional contractor-driven material selection through pre-approved product lists and performance-based contracting. This concentration is most visible in Nordic commercial real estate portfolios pursuing BREEAM Outstanding certification.
Global Advanced Insulation Material Market Segmentation
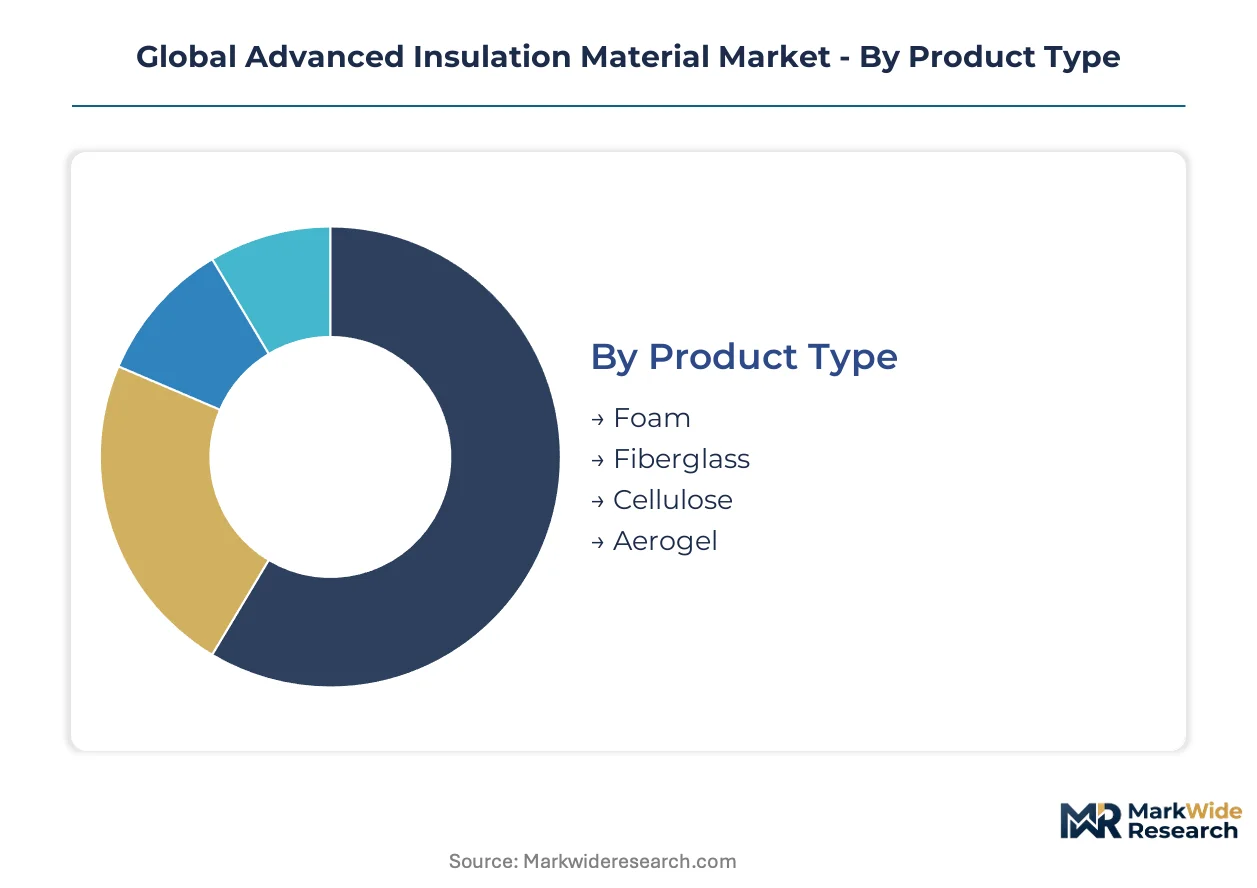
Advanced insulation material procurement diverges sharply across end-use requirements. Specification authority concentrates in engineering functions for aerospace and energy applications, while contractor networks dominate construction selection.
Product Type:
Customization intensity spans from commodity bulk materials to precision-engineered nanoporous systems with application-specific density tuning.
- Aerogel:Silica-based nanoporous solids achieve thermal conductivity below 0.020 W/m·K through supercritical drying processes. Aerospace OEMs in Germany and the United States specify aerogel blankets for engine nacelle thermal barriers where weight reduction overrides cost premiums.
- Foam:Polyurethane and polyisocyanurate systems dominate building envelope applications through spray, board, and poured formulations. EU F-Gas Regulation is forcing European foam producers toward hydrofluoroolefin blowing agents with reduced global warming potential.
- Fiberglass:Melt-spun glass fibers bound with phenolic or bio-based resins serve cost-sensitive construction markets across India and Brazil.
- Cellulose:Recycled paper fiber treated with borates for fire resistance fills cavity walls in residential retrofits throughout the United States and Canada.
Leading the category by volume: fiberglass. Expanding most quickly: aerogel.
End User:
Specification complexity escalates from standardized building codes to mission-critical performance validation across industrial verticals.
- Construction:Building envelope retrofits and passive house standards drive vacuum insulation panel specification in Germany, Austria, and Switzerland where floor space constraints dominate.
- Aerospace:Thermal protection systems for commercial aviation and space launch vehicles require aerogel blankets rated for extreme temperature gradients from cryogenic to re-entry conditions.
- Automotive:Underhood thermal management and electric vehicle battery pack insulation utilize composite foam systems from Japanese and South Korean tier suppliers.
- Energy:LNG transport vessels and pipeline insulation demand cryogenic-rated materials from specialized fabricators in China and South Korea.
Dominating procurement volume: construction. Climbing the fastest: aerospace.
Technology:
Manufacturing sophistication separates laboratory-scale fabrication from continuous production systems capable of construction-grade throughput.
- Vacuum Insulation:Fumed silica or glass fiber cores sealed in metallized polymer films achieve lambda values near 0.007 W/m·K. German industrial retrofit programs and Chinese dual carbon goals are accelerating panel specification in dense urban cores.
- Spray Foam:On-site polyurethane reaction systems conform to irregular substrates in commercial roofing and industrial tank insulation across the United States.
- Reflective Insulation:Aluminum foil laminates with polyethylene bubble cores address radiant heat transfer in Middle Eastern and Australian building envelopes.
- Composite Materials:Hybrid systems combining aerogel particles with fiber reinforcements serve automotive and energy sector applications requiring mechanical durability.
Highest volume deployment: spray foam. Steepest expansion trajectory: vacuum insulation.
Application:
Performance validation protocols vary from standardized R-value testing to multi-hazard certification for life safety applications.
- Thermal Insulation:Conductivity reduction drives specification across building envelopes, industrial equipment, and transport containers. China's GB standards and the EU Green Deal are tightening energy efficiency mandates.
- Fireproofing:Intumescent coatings and mineral fiber boards protect structural steel in high-rise construction subject to EN 13501-2 and ASTM E84 protocols.
- Cold Storage:Temperature-controlled logistics infrastructure in India and Southeast Asia utilizes aerogel blankets and vacuum panels for pharmaceutical distribution.
- Acoustic Insulation:Mineral wool and fiberglass batts address sound transmission in commercial buildings and transportation equipment.
Capturing largest volume share: thermal insulation. Gaining share fastest: cold storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate vacuum insulation panel manufacturing capacity serving domestic retrofit programs and export markets. Germany's Ruhr industrial corridor and Bavarian manufacturing belt anchor European demand for high-performance thermal barriers. The United States Sun Belt construction boom and Indian pharmaceutical cold-chain expansion create divergent regional growth vectors across the forecast window.
United States
Residential energy efficiency tax credits under the Inflation Reduction Act expand contractor training programs for advanced insulation installation. EPA SNAP program restrictions on hydrofluorocarbon blowing agents force polyurethane foam reformulation across Gulf Coast chemical producers. Texas and Florida construction markets drive spray foam specification in commercial roofing and residential envelopes.
Germany
Industrial retrofit programs and passive house construction accelerate vacuum insulation panel specification in dense urban cores. EU F-Gas Regulation mandates stepped reductions in hydrofluorocarbon blowing agents across polyurethane foam production. Bavarian and North Rhine-Westphalian building inspectorates now require third-party environmental product declarations alongside thermal performance certificates.
China
Dual carbon goals and tightening GB standards accelerate domestic vacuum panel manufacturing capacity expansion. MIIT industrial policy directs subsidies toward fumed silica core production in Jiangsu and Zhejiang provinces. Shanghai and Suzhou industrial clusters specialize in metallized film sealing equipment for construction-grade panel output.
India
Temperature-controlled pharmaceutical logistics expansion creates aerogel blanket penetration opportunities in Mumbai and Hyderabad distribution hubs. BIS certification requirements for imported insulation materials tighten qualification timelines for European and Chinese suppliers. Gujarat and Maharashtra state industrial parks attract cold-storage infrastructure investment with land allocation preferences.
Japan
METI energy efficiency mandates for commercial buildings drive vacuum insulation panel adoption in Tokyo and Osaka high-rise retrofits. JIS standards for thermal performance testing create qualification barriers for non-domestic suppliers. Nagoya automotive tier suppliers integrate composite foam systems for electric vehicle battery pack thermal management.
Global Advanced Insulation Material Market Competitive Landscape
Top-tier vendors anchor premium aerogel and vacuum insulation segments, while mid-scale chemical conglomerates compete on polyurethane foam formulation breadth. The vendor base stratifies across three archetypes: nanoporous material specialists, diversified chemical producers with polymer science platforms, and mineral fiber incumbents with construction distribution lock-in. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity concentrated in East Asian vacuum panel fabricators and European fire-retardant additive suppliers.
Within the nanoporous specialization tier, Aspen Aerogels, Inc. exemplifies extreme-temperature material engineering, while Luyang Energy-saving Materials Co., Ltd. occupies a position among Chinese industrial insulation fabricators. BASF SE anchors the diversified chemical producer archetype with polymer science capabilities spanning multiple insulation chemistries. These three entities represent distinct strategic postures: technology-driven premium positioning, scale-oriented Asian manufacturing, and formulation breadth across construction and industrial end-uses.
| Leading Market Players |
|---|
| 3M Company |
| Dow Inc. |
| Aspen Aerogels, Inc. |
| Johns Manville Corporation |
| BASF SE |
| Rogers Corporation |
| Luyang Energy-saving Materials Co., Ltd. |
| Morgan Advanced Materials plc |
| RHI Magnesita GmbH |
| Others |
Supply & Pricing Matrix
Aerospace OEMs in Germany and the United States are consolidating aerogel blanket procurement into multi-year framework agreements with technical performance guarantees, forcing suppliers to carry inventory buffers and absorb alkoxide feedstock volatility in exchange for volume commitments.
Pricing Analysis
Lead-time compression commands premium positioning in vacuum insulation panel procurement, with German passive house developers paying significant markups for four-week delivery against standard twelve-week cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal conductivity certification and fire rating tier. Price differentiation hinges on EN 13501-2 classification and environmental product declaration availability. Cost compression in polyurethane foam systems is intensifying because EU F-Gas Regulation mandates hydrofluoroolefin transition without immediate manufacturing scale. Construction contractors in India and Brazil exhibit highest price sensitivity, while aerospace thermal management teams prioritize performance over unit economics.
Supply Chain Analysis
Specialized technician scarcity in Jiangsu and Zhejiang provinces constrains metallized film sealing equipment throughput, capping vacuum panel output expansion despite fumed silica core availability. Supply concentrates in China, Germany, and South Korea for precision-manufactured thermal barriers. Raw material flows draw from petrochemical alkoxide streams, metallized polymer films, and boron-treated recycled cellulose. Single-source vulnerability clusters in East Asian vacuum core fabricators with limited qualified alternatives. Distribution runs through technical distributor networks serving commercial construction, direct OEM supply agreements in aerospace, and cold-chain logistics integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory qualification cost escalation is compressing viable participation to well-capitalized players with fire testing laboratory relationships and environmental certification infrastructure.
For Market Incumbents: Acquire fumed silica core production assets in Jiangsu province to secure vacuum panel supply chain control against Chinese domestic capacity absorption. Anchor defensive positioning through backward integration into alkoxide precursor manufacturing, mitigating petrochemical price volatility exposure. Pursue EN 13501-2 Extended Application certification ahead of 2025 building code harmonization to disqualify reformulation-lagged competitors. For New Entrants and Emerging Players: The mid-market price-point gap between aerospace-grade aerogel and commodity fiberglass creates white-space opportunity for composite material hybrids targeting automotive battery pack thermal management. Penetrate Indian pharmaceutical cold-chain logistics through Mumbai distribution hub relationships and BIS certification fast-track programs. Deploy technical training partnerships with regional contractor associations to overcome installer skill scarcity barriers. For Investors and Strategic Acquirers: The window for entry favors nanoporous material specialists with aerospace qualification track records and scalable supercritical drying infrastructure. Long-term viability centers on dual-use technology platforms serving both aviation thermal barriers and energy sector cryogenic applications. Monitor EU F-Gas Regulation phase-down compliance timelines as inflection indicator for polyurethane foam incumbent distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxide Precursor Supply | Aspen Aerogels and BASF SE competitors secure petrochemical feedstock cost control against volatile silica precursor markets. |
| EN 13501-2 Extended Application Certification Investment | Johns Manville Corporation and European mineral wool incumbents build regulatory moats ahead of building code tightening. |
| Joint Venture with Chinese Vacuum Panel Fabricators | German and Japanese insulation specialists access Yangtze River Delta manufacturing capacity for European passive house retrofit demand. |
| Long-term Supply Agreement with Aerospace OEMs | Specialized aerogel producers anchor revenue visibility through Boeing and Airbus thermal barrier program specifications. |
| Green Manufacturing Transition to HFO Blowing Agents | BASF SE and Covestro reformulate polyisocyanurate systems to maintain EU market access under F-Gas Regulation mandates. |
Research Methodology
Independent corroboration across plant managers at German and Chinese insulation manufacturing facilities, procurement leads at aerospace OEMs, and technical R&D directors at chemical conglomerates underwrites the qualitative findings. Primary interviews with cold-chain logistics operators in Mumbai and Hyderabad, distribution channel partners serving Nordic commercial real estate, and aftermarket service heads for industrial equipment insulation combined with secondary validation. Secondary sources include customs and trade data from EU and Chinese export registries, SEC 10-K filings from listed chemical producers, Cefic and ACC industry reports, and building certification databases tracking BREEAM and passive house completions. Bottom-up demand modeling and top-down supply capacity assessment triangulate volume estimates.
Comparable-period anchoring to historical retrofit program deployment rates and aerospace production cycles established the forecast window baseline. Segmentation modeling spans product type, end-use industry, technology platform, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating energy efficiency mandate stringency indices and construction activity forecasts. Industry-specific inputs include EN 13501-2 fire testing pipeline volumes, MIIT subsidy disbursement patterns for Chinese vacuum panel capacity, and Inflation Reduction Act residential credit uptake trajectories.
Inputs from aerospace procurement officers and German building inspectorates were available through the study window; gaps in real-time alkoxide spot pricing and Chinese provincial subsidy allocation introduce uncertainty bands around cost projections. Forecasts embed assumptions regarding F-Gas Regulation phase-down adherence and GB standard implementation pacing. Material deviation in EU regulatory enforcement intensity, Chinese dual carbon policy continuity, or aerospace production rate adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Italy Industrial Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
Multi-Layer Cryogenic Insulation Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
OEM Insulation Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Insulation Materials Market
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Passive Fire Protection Materials Market