
 High-Performance Insulation Materials Market | 2026-2036
High-Performance Insulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
High-Performance Insulation Materials Market Outlook
The capital-intensity divergence between integrated mineral wool producers and asset-light foam specialists is unwinding competitive stability across the sector. Saint-Gobain leverages captive raw material sourcing and fused silica capabilities to dominate European industrial fireproofing contracts. Owens Corning anchors North American residential demand through fiberglass batt manufacturing scale and builder channel control. RHI Magnesita specializes in refractory-grade alumina-silicate formulations for steel and cement kiln applications where operating temperatures exceed 1,200°C.
High-performance insulation materials are engineered thermal barriers with thermal conductivity values typically below 0.025 W/m·K, manufactured through melt-spinning of basalt or slag fibers, chemical blowing of polyisocyanurate foams, or aerogel supercritical drying processes, designed to minimize heat transfer in energy-intensive building envelopes and industrial systems. Mineral wool leads installed volume across European commercial retrofits where non-combustibility ratings under EN 13501-1 dominate specification sheets, while spray foam captures the fastest growth in North American residential attic applications where air-sealing integration reduces HVAC load calculations. Fiberglass occupies mature, price-competitive territory in standard residential wall cavities where R-value per dollar governs contractor selection.
The EPA's Significant New Alternatives Policy program restricts high-GWP blowing agents in spray foam formulations, redirecting R&D spending toward hydro-olefin and water-blown systems. REACH compliance through ECHA mandates disclosure of flame retardant chemistries in mineral wool binders, elevating testing costs for exporters into EU member states. Building codes under the International Energy Conservation Council and ASHRAE 90.1 standards are tightening minimum R-value requirements across climate zones. Stakeholders must monitor evolving fire-safety certifications and carbon-accounting rules for embodied insulation content as procurement criteria shift toward whole-life carbon metrics.
Market Dynamics
The EU F-Gas Regulation and EPA Significant New Alternatives Policy are forcing simultaneous reformulation of blowing-agent chemistries across polyisocyanurate and spray-foam product lines, compressing development cycles while elevating compliance costs for mid-scale manufacturers lacking captive R&D infrastructure.
Growth Catalysts
- Passive House construction standards:Germany's tightening envelope-performance mandates under the Energy Saving Ordinance (EnEV) are pulling vacuum-insulated panels and aerogel blankets into multi-family residential specifications previously dominated by mineral wool.
- Data center cooling retrofits:Hyperscale operators in Northern Virginia and Frankfurt are specifying high-R-value phenolic foam and cellular glass for thermal management of AI training clusters, displacing conventional HVAC load calculations.
- REACH disclosure mandates:ECHA's expanded flame-retardant reporting requirements for mineral wool binders are accelerating substitution toward bio-based phenolic resins and inorganic starch binders in commercial building retrofits.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs for polyurethane foam production swing with crude-oil and natural-gas pricing, compressing margin stability for non-integrated foam specialists lacking backward integration into propylene oxide supply.
- Basalt fiber supply concentration:Melt-spinning capacity for stone wool concentrates in Russian and Chinese smelter complexes, exposing European and North American insulation producers to sanctions-related supply interruptions and freight-cost spikes.
- Silica aerogel manufacturing scale limits:Supercritical drying infrastructure requires pressurized CO2 vessels and solvent-recovery systems that lock capital for 7-10 year payback periods, constraining unit-cost reductions needed for residential market penetration.
Strategic Opportunities
- Industrial heat-recovery applications:Steel and cement kiln operators in India and Southeast Asia are piloting microporous silica and calcium-magnesium-silicate boards for exhaust-duct insulation above 800°C, opening refractory-adjacent volume outside traditional building-construction channels.
- Whole-life carbon procurement mandates:France's RE2020 environmental regulation and the UK's Future Homes Standard are embedding embodied-carbon thresholds into public-tender evaluation criteria, advantaging mineral wool and recycled-glass foam with verified Environmental Product Declarations.
- Prefabricated panel integration:Offsite construction specialists in the Netherlands and Sweden are specifying factory-integrated vacuum-insulated panels for timber-frame modules, compressing on-site installation labor and air-leakage risk.
Industry Challenges
- Fire-safety certification timelines:EN 13501-1 reaction-to-fire testing for novel bio-based foam formulations requires 12-18 month validation cycles through notified bodies, delaying product launches behind reformulation-driven regulatory windows.
- Installation skill fragmentation:Spray-foam application certification under manufacturer warranty programs concentrates qualified contractor pools in metropolitan markets, leaving secondary cities and rural construction segments underserved.
- Legacy building stock compatibility:Historic masonry structures in Central European city centers require breathable, capillary-open insulation systems that conflict with conventional vapor-barrier approaches, demanding custom hygrothermal modeling and material selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Performance Insulation Materials Market |
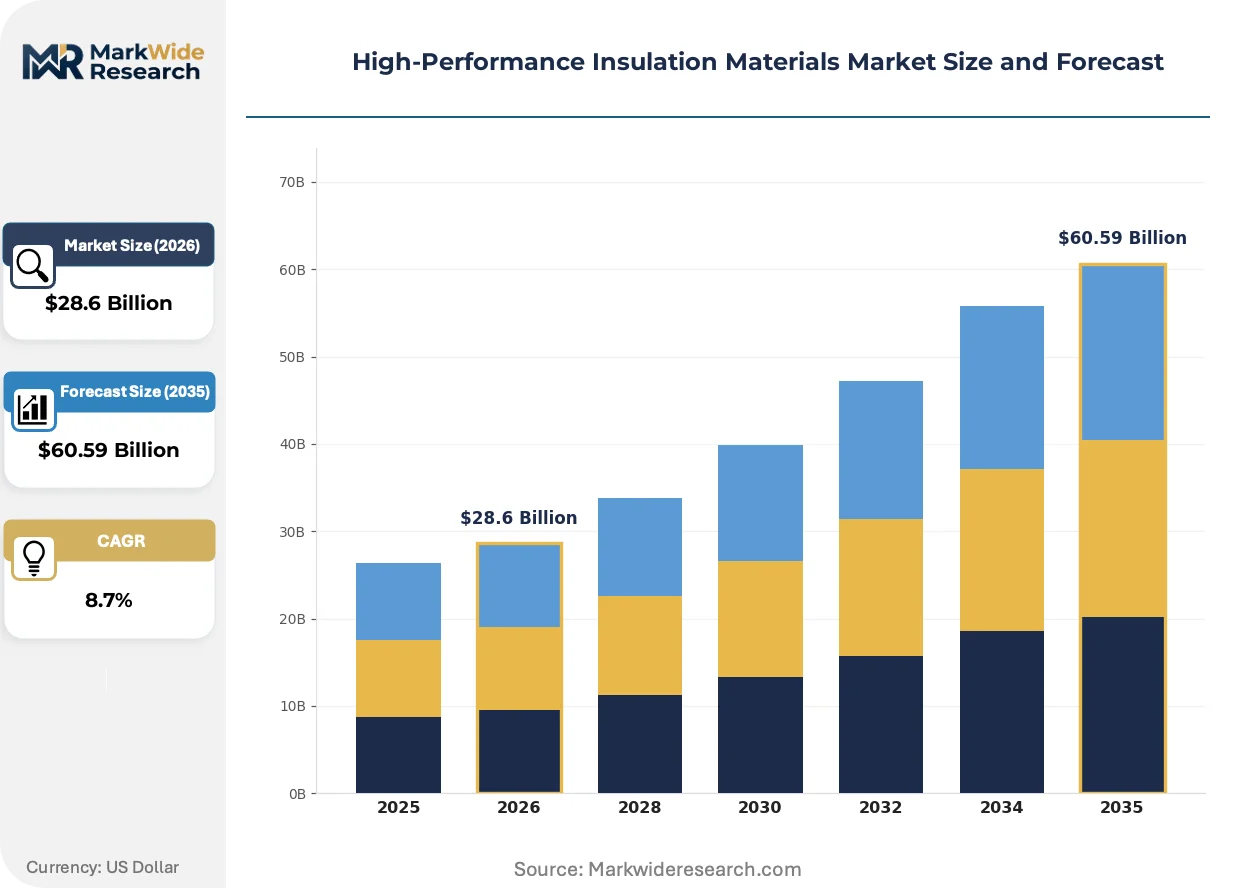
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam Board, Spray Foam, Mineral Wool End User: Residential Buildings, Commercial Buildings, Industrial Facilities, HVAC Systems Application: Thermal Insulation, Acoustic Insulation, Fireproofing, Refrigeration Installation Method: Pre-Installed, On-Site, Self-Adhesive, Retrofit |
| Companies Covered | 3M, Morgan Advanced Materials, RHI Magnesita, Luyang Energy-saving Materials, Etex Group, Owens Corning, Saint-Gobain, Kingspan Group, Rockwool International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Performance Insulation Materials Market Strategic Shifts
Aerogel composite manufacturing is migrating from batch supercritical drying toward ambient-pressure processing, collapsing unit economics while expanding addressable segments beyond aerospace and cold-chain logistics into mainstream building envelopes.
Silica aerogel blanket production is fragmenting across multiple industrial pathways. Ambient-pressure drying methods pioneered at German Fraunhofer institutes are cutting capital intensity by 60 percent versus legacy CO2-based systems. Window and facade manufacturers in Stuttgart and Munich are sampling sub-5mm aerogel glazing inserts for triple-pane retrofits. The incumbent vacuum-insulated panel segment faces compression as aerogel achieves comparable thermal resistance without evacuation infrastructure.
The EPA's Significant New Alternatives Policy is restricting hydrofluorocarbon blowing agents in spray polyurethane foam formulations. Hydro-olefin (HFO) alternatives from Honeywell and Chemours are capturing specification share despite 15-20 percent material cost premiums. Residential builders in California and Washington State are absorbing these costs to maintain utility-rebate eligibility under Title 24 and state energy codes.
Buyers are consolidating specification authority into centralized procurement functions at multi-site developers and REITs. Single-family homebuilders in Texas and Florida are ceding insulation selection to national purchasing agreements negotiated by parent holding companies. This compression of decision nodes is squeezing regional distributors and favoring manufacturers with direct-contracting capabilities and national logistics networks.
High-Performance Insulation Materials Market Segmentation
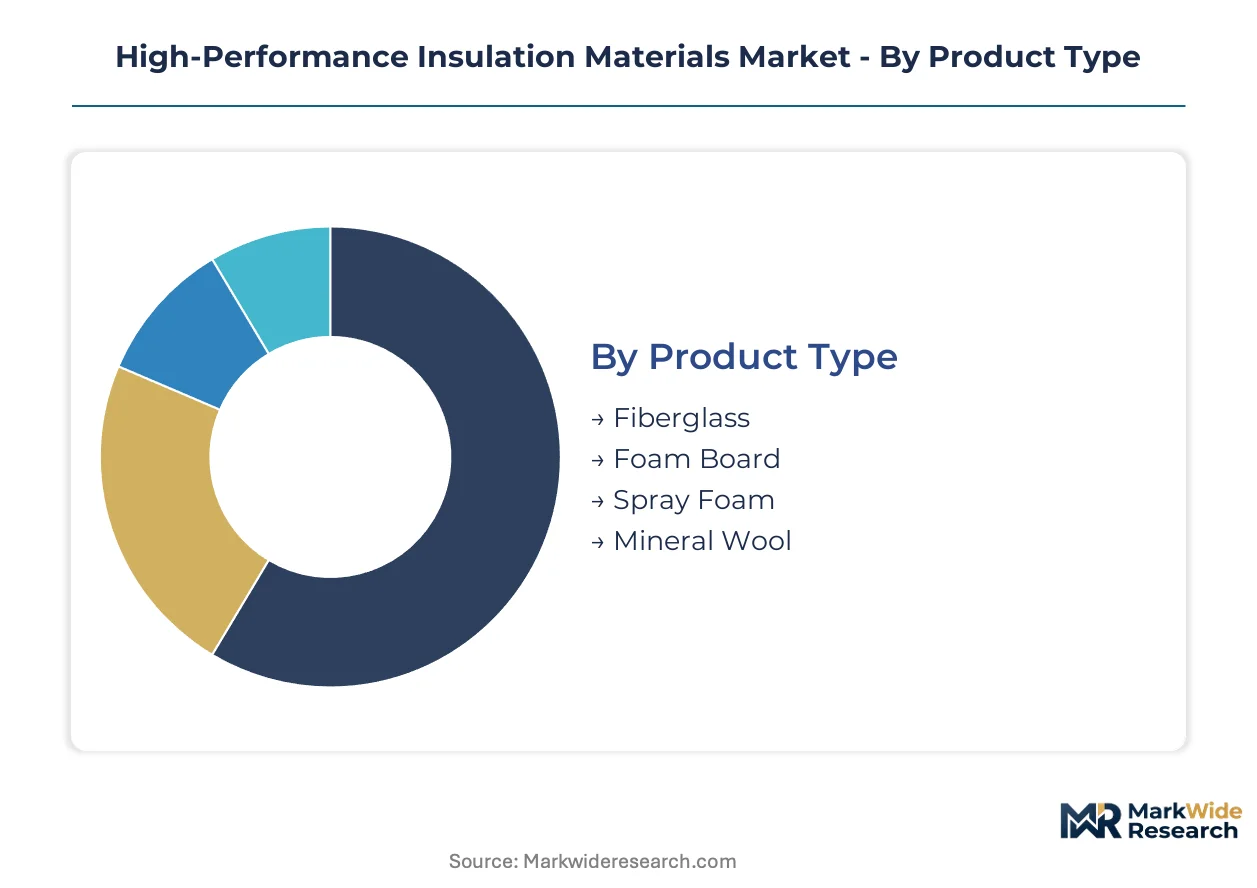
Segmentation in high-performance insulation materials reveals divergent margin structures and channel strategies across product categories. Specification authority concentrates differently by end-use, with industrial procurement favoring long-term supply contracts while residential demand flows through distributor networks.
Product Type:
Channel mix varies sharply by product chemistry, with mineral wool and fiberglass dominating bulk distributor relationships while spray foam and advanced foams route through certified applicator networks.
- Fiberglass:Melt-spun soda-lime glass fibers bound with phenolic resins, formed into batts and loose-fill densities. Residential contractors in Texas and Florida specify fiberglass for standard wall cavities where R-value per dollar governs selection. Distributor margins compress as national purchasing agreements consolidate volume.
- Spray Foam:Polyurethane systems chemically blown with hydro-olefin or water-based agents, applied through plural-component equipment for seamless air barriers. Northern Virginia data center operators specify closed-cell formulations for thermal management of AI training clusters, absorbing 15-20 percent cost premiums to maintain utility rebate eligibility.
- Mineral Wool:Basalt and slag fibers melt-spun into non-combustible batts and boards meeting EN 13501-1 A1 ratings. German passive house construction and commercial retrofits drive volume through specification channels.
- Foam Board:Extruded polystyrene and polyisocyanurate rigid panels factory-laminated with facers for moisture control. Foundation and below-grade applications in North American residential basements anchor demand.
By volume, fiberglass leads. By growth pace, spray foam is ahead.
End User:
Cost tier stratification separates premium-specified industrial applications from price-sensitive residential retrofits, with commercial buildings occupying a contested middle ground where energy code compliance and first-cost pressure collide.
- Commercial Buildings:Office towers, healthcare facilities, and retail envelopes specifying high-R-value assemblies for code compliance and green certification. Frankfurt and Northern Virginia hyperscale data centers are retrofitting with phenolic foam and cellular glass for thermal management.
- Industrial Facilities:Steel mills, cement kilns, and petrochemical plants operating above 800°C where refractory-grade alumina-silicate and microporous silica boards are required. Indian and Southeast Asian kiln operators are piloting calcium-magnesium-silicate exhaust-duct insulation.
- Residential Buildings:Single-family and multi-family construction where batt insulation dominates new build and retrofit attic applications. California and Washington State builders absorb HFO blowing-agent premiums to maintain Title 24 compliance.
- HVAC Systems:Chilled water piping, ductwork, and equipment enclosures requiring closed-cell elastomeric or fiberglass with vapor-barrier facings. Replacement cycles and efficiency standards drive aftermarket demand.
Commercial buildings command the highest specification intensity. Residential buildings generate the largest unit volumes.
Application:
Maturity curves separate established thermal performance markets from emerging acoustic and fireproofing segments where certification requirements and liability exposure reshape competitive entry.
- Thermal Insulation:The foundational application minimizing conductive and convective heat transfer across building envelopes and industrial systems. Vacuum-insulated panels and aerogel blankets are penetrating German multi-family residential specifications previously dominated by mineral wool.
- Fireproofing:Passive fire protection for structural steel, penetration seals, and compartment barriers requiring tested fire-resistance ratings. Saint-Gobain leverages fused silica capabilities to dominate European industrial fireproofing contracts.
- Acoustic Insulation:Sound transmission class and noise reduction coefficient optimization for interior partitions and mechanical rooms. Mineral wool density grades serve recording studios and open-plan offices.
- Refrigeration:Cold-chain logistics, walk-in coolers, and cryogenic applications demanding closed-cell foam with low lambda values. Cellular glass and phenolic foam displace legacy materials in sub-zero distribution centers.
Thermal applications dominate current revenue. Fireproofing offers the steepest expansion trajectory as building codes tighten.
Installation Method:
Customer type fragmentation separates factory-integrated prefabrication from field-applied retrofits, with skill requirements and warranty structures determining manufacturer channel strategy.
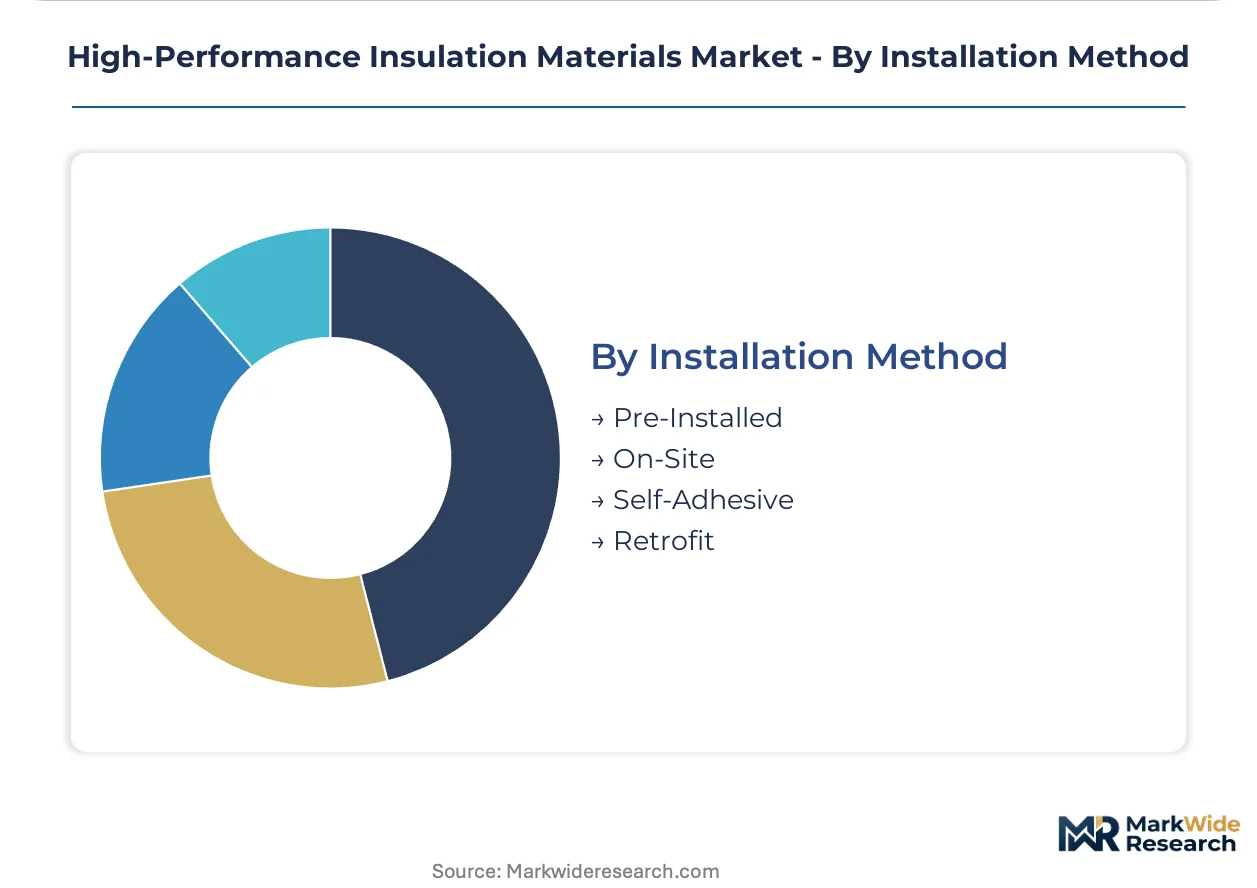
- On-Site:Batt, board, and loose-fill products installed by construction trades during new build or renovation. Installation quality variability creates callback risk and energy performance gaps.
- Pre-Installed:Factory-integrated insulation within prefabricated wall, roof, and facade modules. Dutch and Swedish timber-frame specialists specify vacuum-insulated panels to compress on-site labor and air-leakage risk.
- Retrofit:Existing building upgrades including blown-in attic insulation, exterior wall overcladding, and HVAC system replacement. EU Green Deal and national efficiency mandates accelerate commercial and residential retrofit volumes.
- Self-Adhesive:Peel-and-stick membranes and tapes for air-sealing continuity and targeted thermal bridges. Complementary to primary insulation systems rather than standalone solutions.
On-site installation still handles the majority of volume. Pre-installed methods are climbing the fastest as offsite construction scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb 40-60 percent premiums for passive house-certified assemblies, while Texas residential contractors select strictly on R-value per dollar. This demand-elasticity gap separates specification-driven Northern European markets from price-sensitive North American residential construction.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are retrofitting with phenolic foam and cellular glass for AI cluster thermal management. EPA's Significant New Alternatives Policy restricts hydrofluorocarbon blowing agents, redirecting formulation R&D toward hydro-olefin systems. California and Washington State builders absorb 15-20 percent material cost premiums to maintain Title 24 and state energy code compliance.
Germany
Passive house construction standards under the Energy Saving Ordinance are pulling vacuum-insulated panels and aerogel blankets into multi-family residential specifications. EU F-Gas Regulation and REACH compliance through ECHA mandate disclosure of flame retardant chemistries, elevating testing costs for mineral wool binder formulations. Stuttgart and Munich facade manufacturers are sampling sub-5mm aerogel glazing inserts for triple-pane retrofits.
China
Basalt fiber melt-spinning capacity concentrates in domestic smelter complexes, supplying stone wool feedstock for regional insulation producers. The country's national environmental regulator enforces dual carbon goals that tighten industrial facility efficiency mandates. Yangtze River Delta construction markets are piloting microporous silica boards for high-temperature exhaust-duct applications above 800°C.
India
Steel and cement kiln operators in Maharashtra and Gujarat are testing calcium-magnesium-silicate exhaust-duct insulation for refractory-adjacent heat recovery. The Bureau of Indian Standards mandates fire-safety certifications for commercial building materials, extending validation timelines for imported mineral wool assemblies. Mumbai-Pune industrial corridor facilities represent the primary demand concentration for high-temperature insulation above 1,000°C.
Netherlands
Offsite construction specialists in the Randstad region specify factory-integrated vacuum-insulated panels for timber-frame modules, compressing on-site installation labor. The country's national building code embeds whole-life carbon thresholds into public procurement evaluation criteria. Eindhoven-area prefabrication plants are scaling pre-installed insulation methods fastest across European markets.
High-Performance Insulation Materials Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the sector. Integrated mineral wool producers with captive raw material sourcing command premium positions in fire-rated industrial specifications, while asset-light foam specialists compete on formulation agility and regional distribution density. Three archetypes dominate: backward-integrated mineral wool conglomerates with fused silica capabilities; mid-scale polyurethane foam formulators with certified applicator networks; and refractory-grade alumina-silicate specialists serving steel and cement kiln operators above 1,200°C. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for blowing-agent technology licensing.
Among European-based material conglomerates, Saint-Gobain and Rockwool International occupy positions representing integrated mineral wool production with non-combustibility certification dominance. Owens Corning anchors North American residential demand through fiberglass manufacturing scale and builder channel relationships. RHI Magnesita exemplifies the refractory-specialist archetype, serving industrial heat-management applications where operating temperatures exceed 1,200°C.
| Leading Market Players |
|---|
| 3M |
| Morgan Advanced Materials |
| RHI Magnesita |
| Luyang Energy-saving Materials |
| Etex Group |
| Owens Corning |
| Saint-Gobain |
| Kingspan Group |
| Rockwool International |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day basalt fiber inventory cycles in European mineral wool plants concentrate pricing power with Russian and Chinese smelter operators, forcing downstream insulation manufacturers to absorb freight-cost volatility or cede margin to integrated conglomerates with captive raw material sourcing.
Pricing Analysis
After-sales service revenue from certified applicator warranty programs and thermal-performance guarantees drives lifetime value in spray foam segments. Three-tier pricing structure across premium, standard, and economy levels separates EN 13501-1 A1-certified mineral wool assemblies from commodity fiberglass batts and project-specific aerogel retrofits. Cost compression in mid-scale polyurethane foam tiers is intensifying because hydro-olefin blowing-agent premiums compress margins for non-integrated formulators. Texas and Florida residential contractors exhibit the highest price sensitivity, selecting strictly on R-value per dollar, while Frankfurt data center operators absorb material cost premiums for thermal-management specifications.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp chemical corridors and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for isocyanate and polyol feedstocks. Basalt fiber melt-spinning capacity concentrates in Russia and China, while phenolic resin binders draw from German and Belgian chemical complexes. Single-source vulnerability in stone wool feedstock exposes European insulation producers to sanctions-related supply interruptions. Distribution runs through bulk distributor relationships for mineral wool and fiberglass, with certified applicator networks handling spray foam and advanced foam installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of supercritical drying infrastructure and qualified aerogel process engineers constrains capacity expansion in advanced insulation tiers, amplifying returns for first-movers who secure ambient-pressure manufacturing licenses.
For Market Incumbents: Secure captive basalt fiber supply through long-term offtake agreements with Russian and Chinese smelter operators, insulating margin stability against freight-cost spikes. Defend specification authority in German passive house construction by accelerating EN 13501-1 certification for bio-based phenolic resin binders ahead of REACH disclosure mandate expansion. For New Entrants and Emerging Players: Anchor in Indian steel and cement kiln exhaust-duct insulation, where calcium-magnesium-silicate board demand outpaces domestic refractory-grade supply and import certification timelines create incumbent vulnerability. Target go-to-market partnerships with Maharashtra-based EPC contractors for high-temperature microporous silica pilot installations. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European building-material conglomerates seeking to divest non-core insulation assets amid portfolio rationalization. Long-term viability hinges on Environmental Product Declaration verification capabilities as France's RE2020 and UK Future Homes Standard embed embodied-carbon thresholds into public procurement. Watch for ambient-pressure aerogel processing license acquisitions as inflection indicators for manufacturing cost-curve shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Fiber Supply | Captive raw material sourcing insulates Saint-Gobain and Rockwool from Russian supply disruption risk. |
| Hydro-Olefin Blowing-Agent Transition | EPA SNAP compliance redirects Owens Corning and foam specialists toward Honeywell and Chemours licensing partnerships. |
| Ambient-Pressure Aerogel Manufacturing Scale-Up | Fraunhofer institute licensing collapses capital intensity for German facade manufacturers sampling glazing inserts. |
| Prefabricated Panel Integration Partnership | Dutch and Swedish timber-frame specialists compress on-site labor through factory-integrated vacuum-insulated panel specifications. |
| Environmental Product Declaration Certification | Verified EPDs for mineral wool and recycled-glass foam secure specification advantage under EU Green Deal procurement criteria. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and building-code databases through structured interviews with plant managers at integrated mineral wool producers, procurement leads at hyperscale data center operators, certified spray foam applicators, and technical R&D directors at polyurethane formulators. Bottom-up volume estimates triangulate against top-down market sizing from construction permit data and industrial facility upgrade announcements.
Segmentation dimensions modeled span product chemistry, end-use application, installation method, and regional regulatory cluster across the analysis window. CAGRs derive from regression analysis of historical construction spending, energy code tightening trajectories, and industrial capacity expansion announcements. Forecast inputs incorporate EPA SNAP enforcement timelines, EU F-Gas Regulation phase-down schedules, and passive house construction permit growth in German metropolitan markets.
Decision-makers should treat outputs as directional under assumptions of continued regulatory enforcement stringency and no major basalt fiber supply disruptions; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Global Insulation Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Seismic Reinforcement Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Fire Resistant Cable Materials Market