
 Thalassemia Market | 2026-2036
Thalassemia Market Size, Share, and Industry Trends Forecast 2026-2036
Thalassemia Market Intelligence
Companion diagnostic services integrated with novel therapeutics is pivoting the commercial model from simple drug sales to comprehensive treatment packages. Novartis AG leverages its extensive portfolio in hematology to maintain a strong market presence. bluebird bio, Inc. specializes in gene therapies, targeting the underlying genetic causes of the disease. Vertex Pharmaceuticals Incorporated competes on the basis of its innovative pipeline in genetic disorders, expanding beyond its core focus areas to address conditions like thalassemia.
Thalassemia is an inherited blood disorder defined by the reduced synthesis of either the alpha or beta globin chains of hemoglobin. This genetic defect results in chronic anemia, requiring lifelong management to mitigate complications such as iron overload. While blood transfusions and iron chelation therapy remain the standard of care, emerging gene therapy options represent the most significant area of innovation. Among treatment modalities, biologics and cell therapies are gaining traction over conventional small-molecule pharmaceuticals.
Regulatory frameworks established by the US FDA and the European Medicines Agency (EMA) are critical for the approval of novel gene and cell therapies. These agencies' requirements for clinical trial data on safety and long-term efficacy directly shape market access for new treatments. In China, the NMPA's accelerated review pathways for orphan drugs influence development timelines. Stakeholders must now focus on developing reimbursement models that balance the high upfront cost of curative therapies with broad patient access.
Market Dynamics
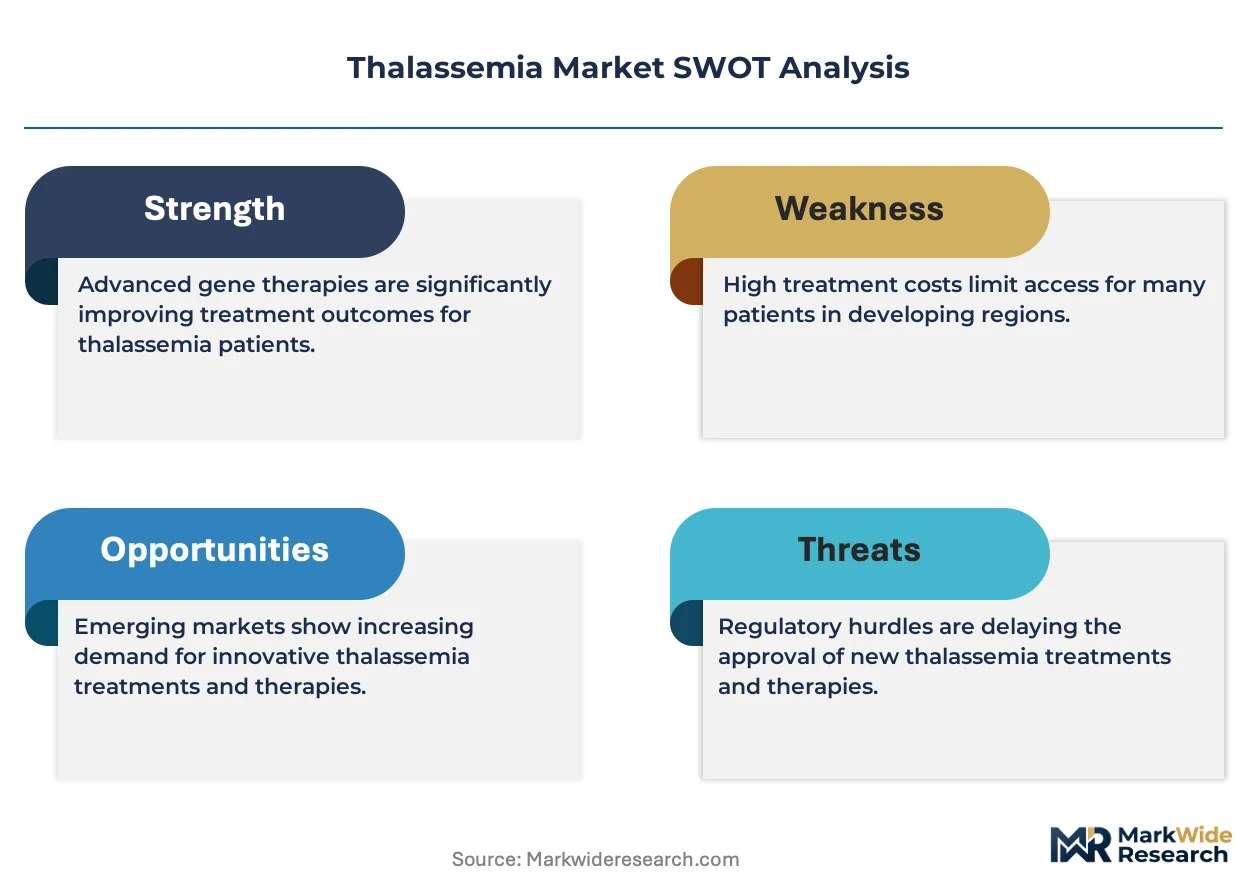
The transition from chronic disease management to one-time curative treatments is the central market force. This shift creates tension between the high cost of gene therapies and the need for equitable patient access globally.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation provides market exclusivity and development support, encouraging investment in therapies for inherited blood disorders.
- Gene Editing Platforms:Advances in CRISPR-Cas9 and lentiviral vectors enable potentially curative treatments by directly correcting the underlying genetic defect.
- Concentrated Patient Demand:High disease prevalence in India and Mediterranean nations creates predictable, geographically focused demand for effective treatments.
Market Restraints
- Prohibitive Therapy Cost:The high upfront price of gene therapies creates immense reimbursement challenges for health systems and payers, limiting access.
- Specialized Infrastructure Deficit:Administering cell therapies requires certified centers with apheresis and cell processing capabilities, which are globally scarce.
- Regulatory Scrutiny on Durability:The EMA's requirement for long-term follow-up data on gene therapy efficacy creates a significant development hurdle.
Strategic Opportunities
- Companion Diagnostic Integration:Developing diagnostics to identify ideal patients for specific gene therapies enables value-based pricing and improves outcomes.
- Targeted Infrastructure Development:Partnering with health ministries in high-prevalence regions like Southeast Asia to build specialized treatment centers addresses a major access gap.
- Outcome-Based Payment Models:Structuring annuity-based payments tied to patient outcomes helps health systems manage the high cost of curative therapies.
Industry Challenges
- Scarcity of Trained Clinicians:A global shortage of hematologists and genetic counselors with expertise in cell and gene therapy protocols limits the capacity to deliver these treatments.
- Autologous Supply Chain Complexity:Managing the patient-specific logistics of collecting, modifying, and re-infusing cells is a major operational hurdle that risks treatment delays and failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thalassemia Market |
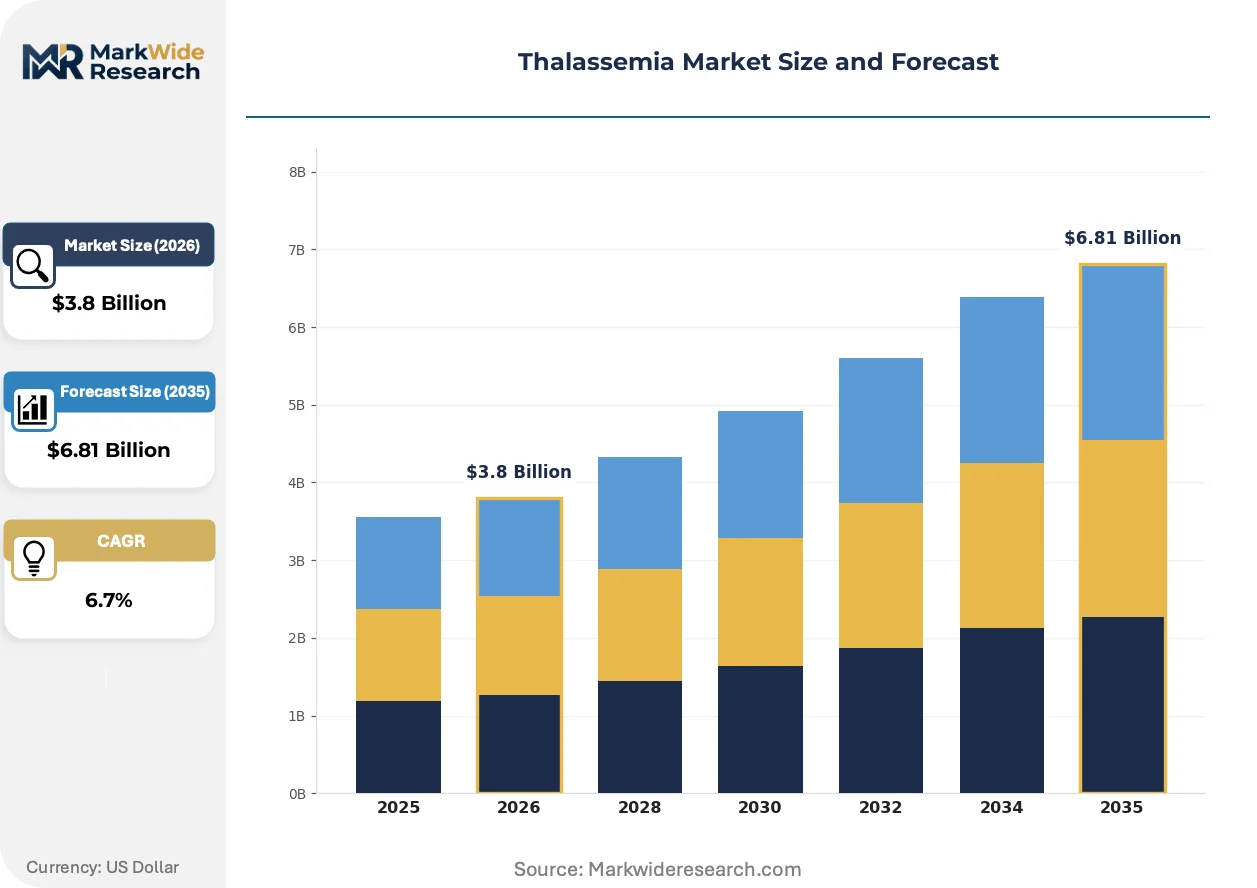
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusions, Iron Chelation Therapy, Bone Marrow Transplant, Gene Therapy End User: Hospitals, Specialty Clinics, Home Healthcare, Research Laboratories Treatment Modality: Pharmaceuticals, Biologics, Cell Therapy, Combination Therapy Delivery Method: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | Novartis AG, bluebird bio, Inc., Bristol-Myers Squibb Company, Pfizer Inc., Apotex Inc., Vertex Pharmaceuticals Incorporated, Chiesi Farmaceutici S.p.A., Sun Pharmaceutical Industries Ltd., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thalassemia Market Strategic Shifts & Innovations
The market is bifurcating between established management therapies and emerging high-cost curative options. This dynamic forces a re-evaluation of treatment value, reimbursement frameworks, and the standard of care across different global healthcare systems.
Lentiviral vector-based gene addition therapy introduces a functional copy of the globin gene into a patient's own stem cells. Specialized hematology centers are the primary adopters for patients with transfusion-dependent thalassemia. This approach is modularizing the treatment pathway, separating the one-time genetic intervention from the lifelong burden of chronic transfusions and iron chelation.
Regulatory frameworks like the US FDA’s Regenerative Medicine Advanced Therapy (RMAT) designation provide an expedited pathway for promising cell and gene therapies. This policy accelerates clinical development timelines and offers more intensive guidance from the agency. Gene therapy developers are most affected, as they must balance rapid development with the need to generate robust long-term safety and efficacy data post-approval.
A shift is occurring from transactional drug purchasing to strategic negotiations over comprehensive treatment packages. Payers, including national health services in Europe, engage directly with manufacturers to create complex access agreements. This trend is most pronounced in the US and EU, where high-cost gene therapies are evaluated for coverage.
Thalassemia Market Segmentation
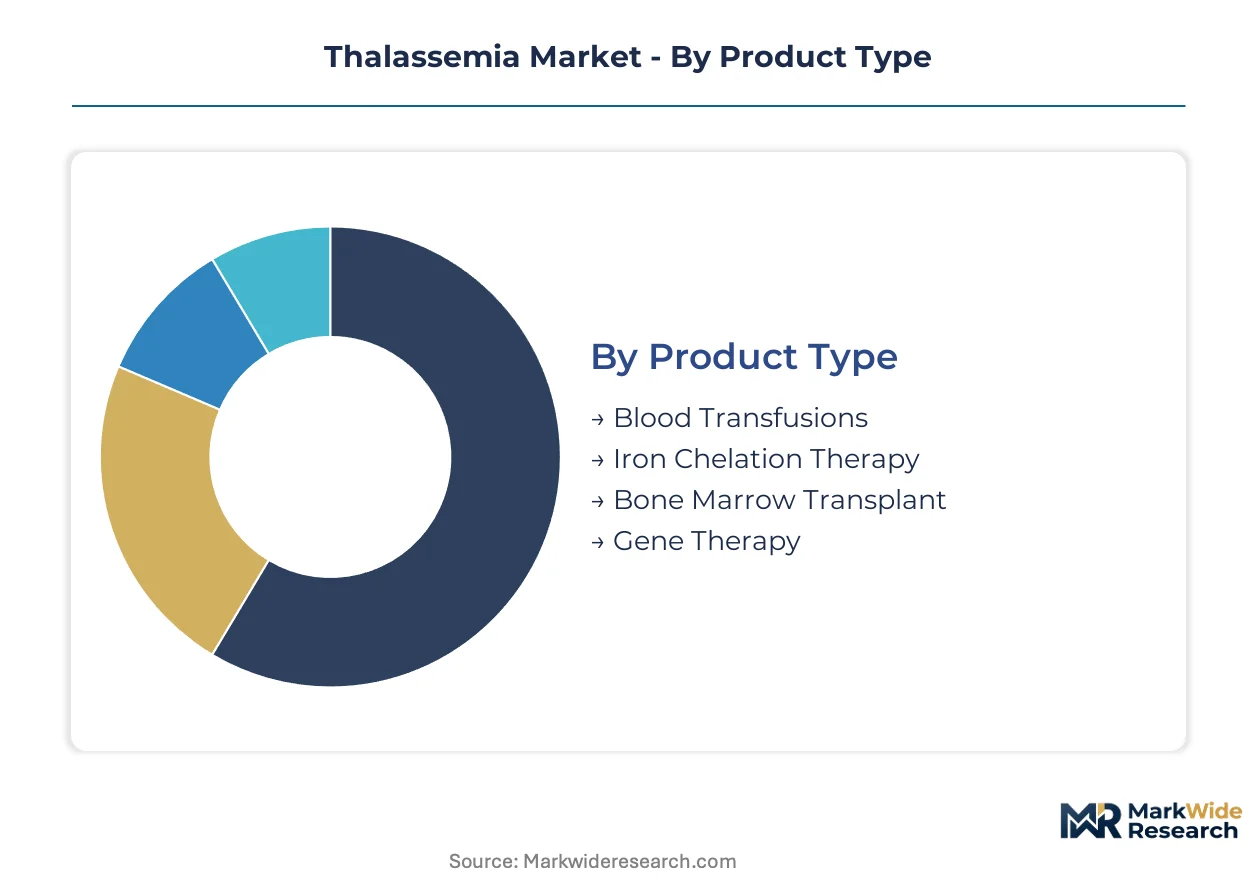
The Thalassemia Market segmentation provides a granular view of treatment approaches, patient care settings, and therapeutic innovations. Understanding these distinct segments helps stakeholders identify areas of concentrated investment and evolving patient needs within the global healthcare system.
Product Type:
Gene therapy and bone marrow transplant demand substantial upfront investment for specialized infrastructure and highly trained personnel.
- Gene Therapy:This modality introduces functional globin genes into a patient's own stem cells using viral vectors, offering a potential one-time cure for the underlying genetic defect. Demand is concentrating in specialized centers in the US and Europe, driven by significant investment in R&D and regulatory fast-tracking.
- Bone Marrow Transplant:This procedure replaces diseased bone marrow with healthy stem cells, often from a compatible donor, to restore normal blood cell production. This complex intervention requires extensive pre- and post-transplant care, primarily performed in large academic hospitals with strong hematology programs.
- Blood Transfusions:This standard therapy provides red blood cells to manage chronic anemia, requiring regular infusions throughout a patient's life.
- Iron Chelation Therapy:This treatment administers agents to remove excess iron accumulated from repeated blood transfusions, preventing organ damage.
Blood Transfusions absorbs the bulk of installed capacity; Gene Therapy is expanding most quickly.
End User:
The reach of thalassemia treatment varies significantly across different end-user settings, from acute care to long-term management.
- Hospitals:These institutions provide comprehensive care for thalassemia patients, including emergency transfusions, complex surgeries, and initial gene therapy administration. Large medical centers in India and the Mediterranean region manage a high burden of newly diagnosed and severe cases.
- Specialty Clinics:These facilities focus on chronic disease management, offering regular transfusions, iron chelation, and monitoring for long-term complications. These clinics are increasingly integrating advanced diagnostic services to support personalized treatment plans for patients across Europe.
- Home Healthcare:This segment supports patients with less severe conditions or stable management plans, primarily for routine iron chelation or less frequent transfusions.
- Research Laboratories:These entities conduct studies on disease mechanisms, develop novel therapies, and perform genetic screening for thalassemia carriers.
Hospitals handle the highest volume of acute cases, while specialty clinics manage chronic care more efficiently.
Treatment Modality:
The market for thalassemia treatment modalities spans from established chemical compounds to cutting-edge cellular interventions.
- Cell Therapy:This modality involves the use of living cells, such as hematopoietic stem cells in gene therapy, to correct the underlying genetic defect or replace diseased cells. This approach represents a paradigm shift towards curative outcomes, with significant investment from companies like bluebird bio.
- Biologics:These therapeutics comprise proteins, antibodies, or other complex molecules derived from living organisms, often used to manage complications or enhance treatment efficacy. These agents offer targeted action and are gaining traction for specific patient populations.
- Pharmaceuticals:This category includes small-molecule drugs primarily used for iron chelation therapy and managing symptoms associated with chronic anemia.
- Combination Therapy:This approach integrates multiple treatment methods, such as blood transfusions with iron chelation, to optimize patient outcomes and mitigate side effects.
Cell therapy offers the highest potential for curative outcomes but carries substantial costs, while pharmaceuticals provide cost-effective symptom management.
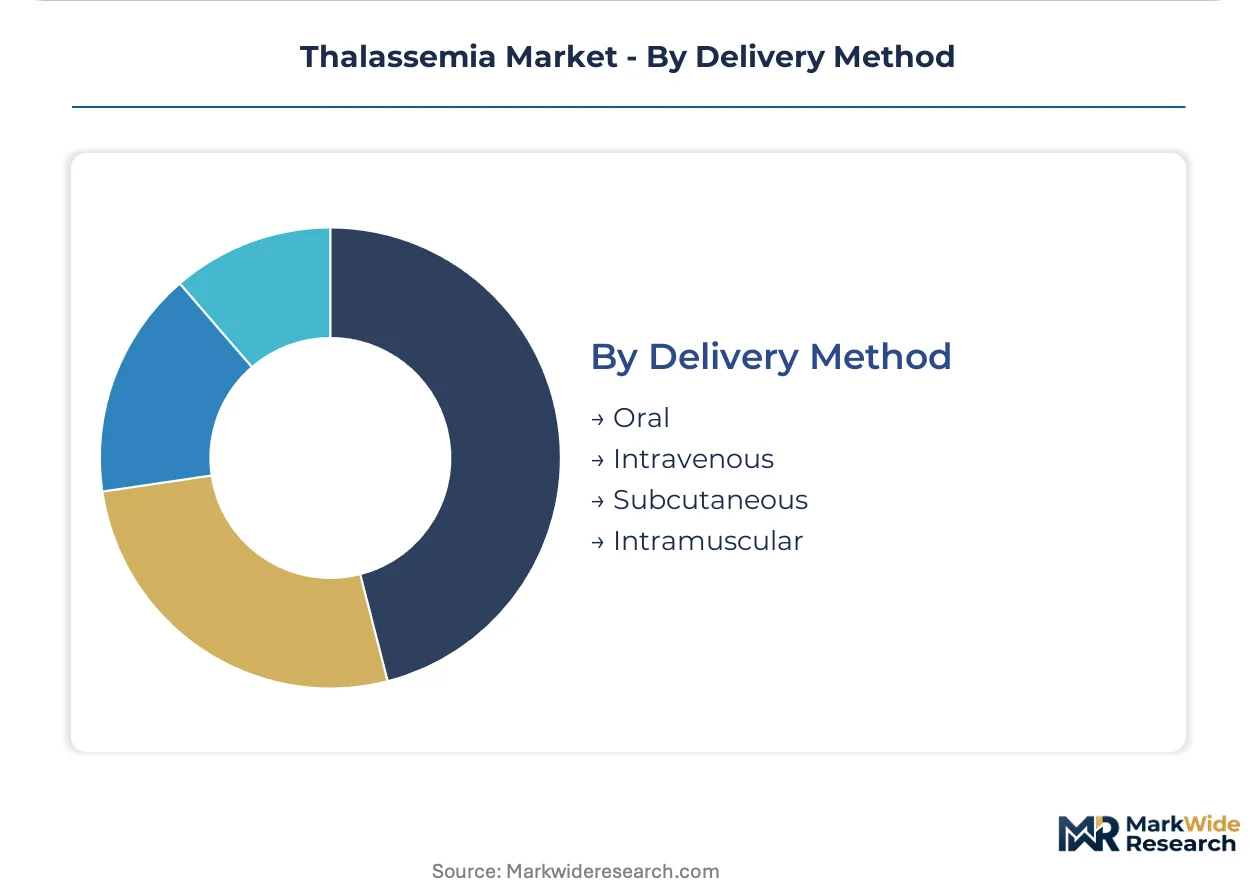
Delivery Method:
The choice of delivery method significantly impacts patient adherence and the required healthcare infrastructure.
- Intravenous:This method administers treatments directly into the bloodstream, essential for blood transfusions and some advanced gene therapies, requiring clinical settings. This approach ensures rapid and complete systemic delivery, critical for acute interventions and high-dose therapies.
- Oral:This method involves taking medication by mouth, primarily for iron chelation agents, offering convenience for long-term home-based management. This non-invasive route improves patient adherence for chronic conditions, reducing the need for frequent clinic visits.
- Subcutaneous:This method delivers medication into the tissue layer just under the skin, often used for specific iron chelation drugs or growth factors.
- Intramuscular:This method involves injecting medication into a muscle, a less common approach for routine thalassemia management but used for certain ancillary treatments.
Oral administration offers the greatest patient convenience for long-term management, whereas intravenous methods demand professional medical supervision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global thalassemia market exhibits a distinct split between regions with high disease prevalence and those driving advanced therapeutic innovation. Demand for effective treatments concentrates in historical epicenters, while research and development for curative gene therapies largely originate in economically developed nations. This dynamic shapes investment flows and access strategies across different healthcare systems.
India
India presents a significant demand for thalassemia treatments due to its high patient burden and large population. The country's national pharmaceutical regulator, the CDSCO, influences market access for both traditional and advanced therapies. Mumbai and Chennai serve as critical hubs for specialty clinics and academic medical centers managing chronic cases and exploring new treatment options.
United States
The United States drives innovation in gene therapy and advanced diagnostics for thalassemia, fueled by substantial R&D investment. The US FDA's orphan drug designation and Regenerative Medicine Advanced Therapy (RMAT) pathways accelerate market entry for novel treatments. Boston and Philadelphia are key biotechnology clusters where gene therapy developers and specialized treatment centers are concentrated.
Germany
Germany represents a major European market for thalassemia management, characterized by a strong healthcare infrastructure and a focus on advanced medical technologies. The European Medicines Agency (EMA) sets stringent requirements for gene therapy approval, impacting market access throughout the EU. Cities like Berlin and Munich host leading university hospitals and research institutions specializing in hematology.
Italy
Italy, a Mediterranean nation, experiences a high prevalence of thalassemia, leading to consistent demand for both standard and emerging therapies. The Italian Medicines Agency (AIFA) works within the EMA framework to evaluate and approve new treatments for genetic disorders. Milan and Rome feature prominent hematology centers that provide comprehensive care and participate in clinical trials.
China
China's thalassemia market is expanding, driven by a large patient population and government initiatives to improve healthcare access. The NMPA's accelerated review pathways for orphan drugs encourage domestic and international pharmaceutical companies to introduce novel therapies. Shanghai and Beijing are key centers for clinical research and the establishment of specialized treatment facilities for inherited blood disorders.
Thalassemia Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the thalassemia market, creating a tiered competitive structure. The market is consolidating around companies with broad hematology portfolios and those specializing in advanced genetic interventions. Strategic archetypes include established pharmaceutical giants, innovative gene therapy developers, and niche diagnostic providers. Dominant competitive moves involve portfolio diversification into cell and gene therapies and strategic partnerships to develop specialized treatment infrastructure.
Specialists in advanced therapies, such as bluebird bio, Inc., focus on developing gene therapies targeting the underlying genetic causes of thalassemia. Novartis AG, a global pharmaceutical leader, leverages its extensive portfolio in hematology to maintain a strong market presence across various treatment modalities. Vertex Pharmaceuticals Incorporated exemplifies a company expanding beyond its core genetic disorder focus to address conditions like thalassemia through innovative pipeline development. These companies anchor the high-value segment of the market, driven by the shift towards curative treatments.
| Leading Market Players |
|---|
| Novartis AG |
| bluebird bio, Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Apotex Inc. |
| Vertex Pharmaceuticals Incorporated |
| Chiesi Farmaceutici S.p.A. |
| Sun Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Others |
Cost & Logistics Intelligence
The high cost of lentiviral vectors, central to gene therapy manufacturing, directly impacts the premium pricing of curative treatments. This upstream component significantly influences patient access models and reimbursement strategies downstream.
Pricing Analysis
Pricing pressure intensifies in the gene therapy segment as health systems balance innovative curative treatments with budget constraints. Value-based pricing models, including annuity-based payments tied to patient outcomes, define the dominant structure. Clinical efficacy and long-term durability drive price differentiation for these advanced therapies. Payers and national health services exhibit high price sensitivity, necessitating complex access agreements with manufacturers.
Supply Chain Analysis
Regional distribution centers for apheresis kits and specialized cell processing facilities anchor the advanced therapy supply chain. Manufacturing of critical components like lentiviral vectors concentrates heavily in the United States and select European nations. The supply chain draws from highly specialized raw materials, including cell culture media and cryopreservation agents. Autologous supply chain complexity, involving patient-specific logistics, represents a significant structural risk for treatment delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thalassemia market is undergoing a vertical-integration race as companies pursue control over advanced gene therapy development and specialized treatment delivery. This shift aims to capture value from one-time curative interventions rather than lifelong disease management.
For Market Incumbents: Deepen investment in next-generation gene editing platforms to counter the threat from specialized biotech firms. Consolidate market presence through strategic partnerships with specialty clinics to build certified treatment infrastructure in high-prevalence regions. Leverage existing hematology portfolios to cross-sell diagnostic services and traditional therapies while transitioning patients to curative options. This defensive strategy mitigates margin pressure from high-cost, one-time treatments.
For New Entrants and Emerging Players: Price-point gaps exist in regions with high thalassemia prevalence but limited access to advanced therapies, such as parts of India and Southeast Asia. Target these underserved geographies by developing localized, modular treatment solutions that reduce infrastructure requirements. Focus on companion diagnostics integration to identify ideal patient cohorts for gene therapy, enabling value-based pricing negotiations. This go-to-market angle addresses both access and cost challenges.
For Investors and Strategic Acquirers: Successful long-term reimbursement agreements for gene therapies in major European markets is the leading indicator that the market is transitioning to sustainable curative models. The long-term viability of this sector hinges on broad patient access and payer acceptance of high upfront costs. Acquire specialized gene therapy developers or diagnostic firms with robust pipelines and validated platforms. Watch for increasing investment in specialized treatment infrastructure in high-prevalence nations.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates development of novel gene therapies, enabling earlier patient access to curative options. |
| Manufacturing Scale-Up | Reduces per-dose costs of cell therapies and improves global availability for patients. |
| Regulatory Approval Pathway | Secures market access for innovative treatments under frameworks like the US FDA's RMAT designation. |
| Hospital System Partnership | Establishes specialized treatment centers required for complex cell therapy administration. |
| Companion Diagnostic Integration | Optimizes patient selection for gene therapies, enhancing treatment efficacy and value propositions. |
Research Approach
US FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for this analysis, complemented by national health agency reports. Primary interviews with hematologists, genetic counselors, pharmaceutical R&D executives, and payer representatives provided qualitative insights. This approach ensured robust bottom-up and top-down triangulation of market data.
A bottom-up approach estimated demand across patient segments, while a top-down method validated overall market sizing throughout the forecast period. Segmentation dimensions modeled included product type, end user, treatment modality, delivery method, and regional disease prevalence. Compound annual growth rates were derived from historical trends and projected gene therapy adoption curves.
Inputs from published clinical trial data and regulatory guidance were available through the study window; gaps in long-term gene therapy efficacy data introduce uncertainty bands. Forecasts reflect assumptions regarding future regulatory approvals and reimbursement policy evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Nanomedicine Market
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Serum Lactate Testing Market