
 Iga Nephropathy (Igan) Market | 2026-2036
Iga Nephropathy (Igan) Market Size, Share, and Industry Trends Forecast 2026-2036
Iga Nephropathy (Igan) Market Intelligence
Specialty clinics is rotating toward precision-guided IgA nephropathy protocols as hospital-based nephrology departments face capacity constraints. Calliditas Therapeutics anchors European commercial infrastructure for taribavirin-class assets. Travere Therapeutics differentiates through sparsentan development in proteinuria reduction. Novartis leverages its renal rare-disease franchise to sustain competitive positioning across major markets.
IgA nephropathy constitutes a chronic glomerular disease characterized by mesangial deposition of galactose-deficient IgA1 immune complexes, triggering progressive renal inflammation and fibrosis. Its primary clinical purpose centers on delaying end-stage renal disease through proteinuria suppression and immunomodulation. Biologics command the fastest-expanding product type segment as B-cell and complement-targeted mechanisms enter Phase III programs. Pharmacotherapy dominates treatment strategy revenue, though conservative management retains substantial volume in early-stage patients across European reimbursement systems.
The FDA's accelerated approval framework and EMA's orphan drug incentives shape how developers prioritize surrogate endpoints and post-market commitments. Japan's PMDA maintains distinct renal biopsy requirements that filter market entry for foreign biologics. Stakeholders must monitor how complement inhibitor readouts alter physician prescribing hierarchies and payer access negotiations across major markets.
Market Dynamics
The FDA's accelerated approval pathway for rare renal diseases is compressing commercialization timelines and forcing developers to build post-market infrastructure before launch. This regulatory mechanism rewards surrogate endpoints while demanding rigorous confirmatory evidence, reshaping capital allocation across the IgA nephropathy therapeutic landscape.
Growth Catalysts
- Orphan Drug Incentives:EMA's framework grants market exclusivity and fee waivers for developers targeting rare renal indications, accelerating pipeline progression across European markets.
- Biopsy-Stratified Protocols:Oxford classification systems enable precision patient selection, expanding addressable populations for targeted immunomodulatory candidates.
- Specialty Clinic Networks:United States nephrology centers are consolidating referral pathways, concentrating high-value patients into sites equipped for complex biologic administration.
Market Restraints
- Biologic Manufacturing Complexity:Single-use bioreactor capacity constraints and viral clearance validation requirements extend lead times for complement inhibitor commercial supply.
- Reimbursement Heterogeneity:Germany's G-BA assessment protocols impose outcome-based pricing conditions that compress net revenue versus US list prices.
- Diagnostic Access Gaps:Renal biopsy infrastructure remains concentrated in tertiary centers across Japan, limiting patient identification in community settings.
Strategic Opportunities
- Non-Invasive Biomarker Panels:Galactose-deficient IgA1 serum assays are supplanting tissue-based diagnostics, enabling community-based screening and earlier therapeutic intervention.
- Complement Cascade Expansion:Factor B and properdin targeting mechanisms offer differentiated positioning beyond C5 inhibition, opening novel mechanism-of-action categories.
- Japan PMDA Alignment:Harmonized renal biopsy data requirements with Western regulators would streamline foreign biologic entry into Asia's second-largest nephrology market.
Industry Challenges
- Nephrology Workforce Constraints:Fellowship program bottlenecks in the United States limit principal investigator availability for multi-site Phase III renal trials.
- Post-Market Evidence Generation:FDA-mandated confirmatory studies require extended follow-up periods that strain cash reserves and complicate partnership negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iga Nephropathy (Igan) Market |
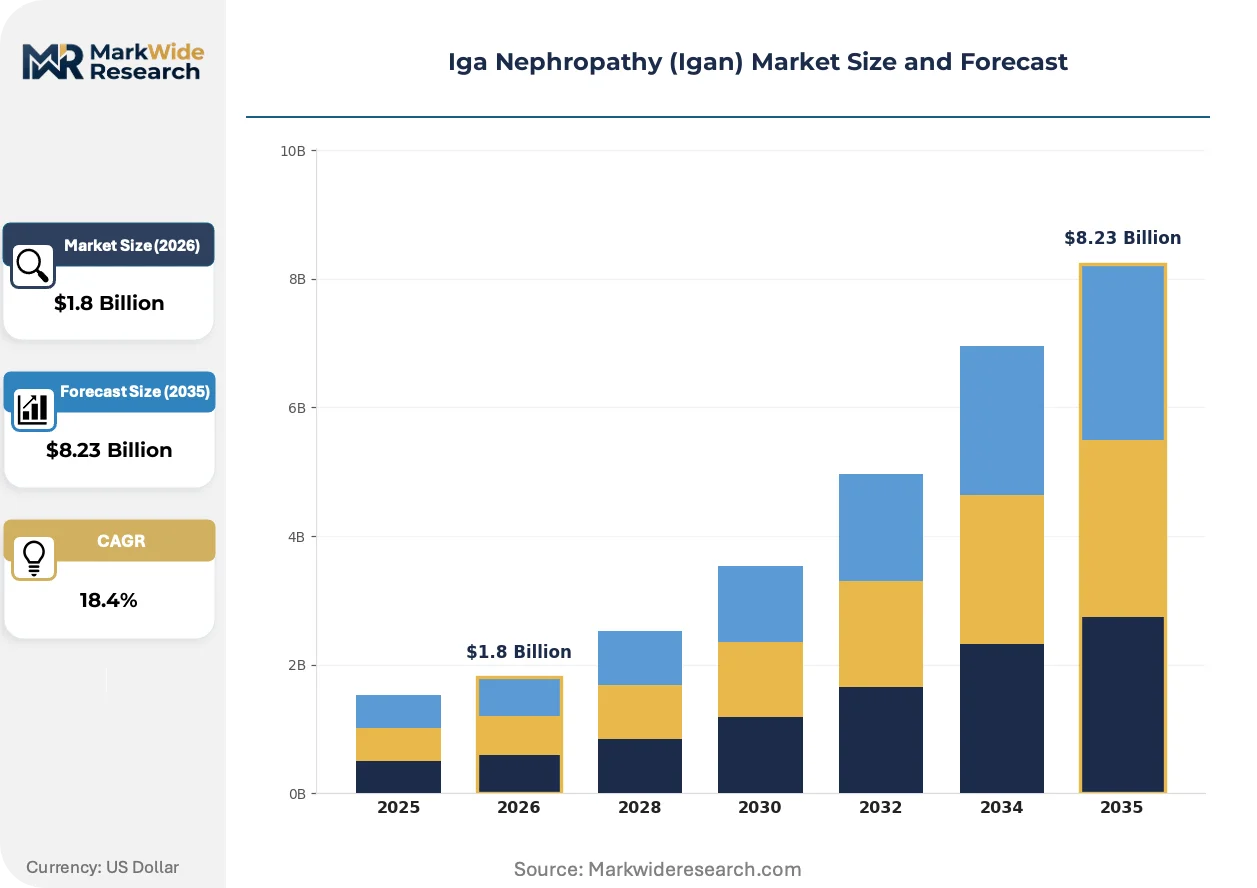
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Corticosteroids, Biologics, Supportive Care End User: Hospitals, Specialty Clinics, Homecare, Research Laboratories Treatment Strategy: Conservative Management, Renal Replacement Therapy, Pharmacotherapy, Lifestyle Modification Diagnosis Method: Urinalysis, Blood Tests, Kidney Biopsy, Imaging Techniques |
| Companies Covered | Novartis, Calliditas Therapeutics, Travere Therapeutics, AstraZeneca, Vertex Pharmaceuticals, Otsuka Pharmaceutical, Biogen, Vera Therapeutics, Ionis Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iga Nephropathy (Igan) Market Strategic Shifts & Innovations
Targeted immunomodulation is displacing broad immunosuppression as the therapeutic paradigm, with B-cell and complement-directed mechanisms commanding development priority. This shift demands new clinical endpoints, biomarker infrastructure, and payer engagement models.
B-cell depletion therapies targeting APRIL and BAFF signaling pathways are supplanting calcineurin inhibitors in high-risk proteinuria populations. Academic medical centers in the United States and Sweden are adopting these protocols for rapid-progression phenotypes. The mechanism is compressing reliance on corticosteroid-sparing regimens and forcing recalibration of safety monitoring frameworks.
EMA's adaptive licensing pilot for rare diseases is enabling conditional market access based on intermediate proteinuria endpoints rather than hard renal survival data. Developers must construct robust post-authorization study frameworks to retain authorization. This mechanism most directly affects European commercial strategy, where Germany and France are piloting outcome-based reimbursement contracts tied to eGFR slope preservation.
Patient advocacy organizations are consolidating purchasing influence through specialty pharmacy networks, bypassing traditional hospital formulary committees. United States nephrology practices are responding by embedding clinical pharmacists within care teams to manage prior authorization workflows. This behavioral shift concentrates demand negotiation leverage with national payer organizations rather than individual institutions.
Iga Nephropathy (Igan) Market Segmentation
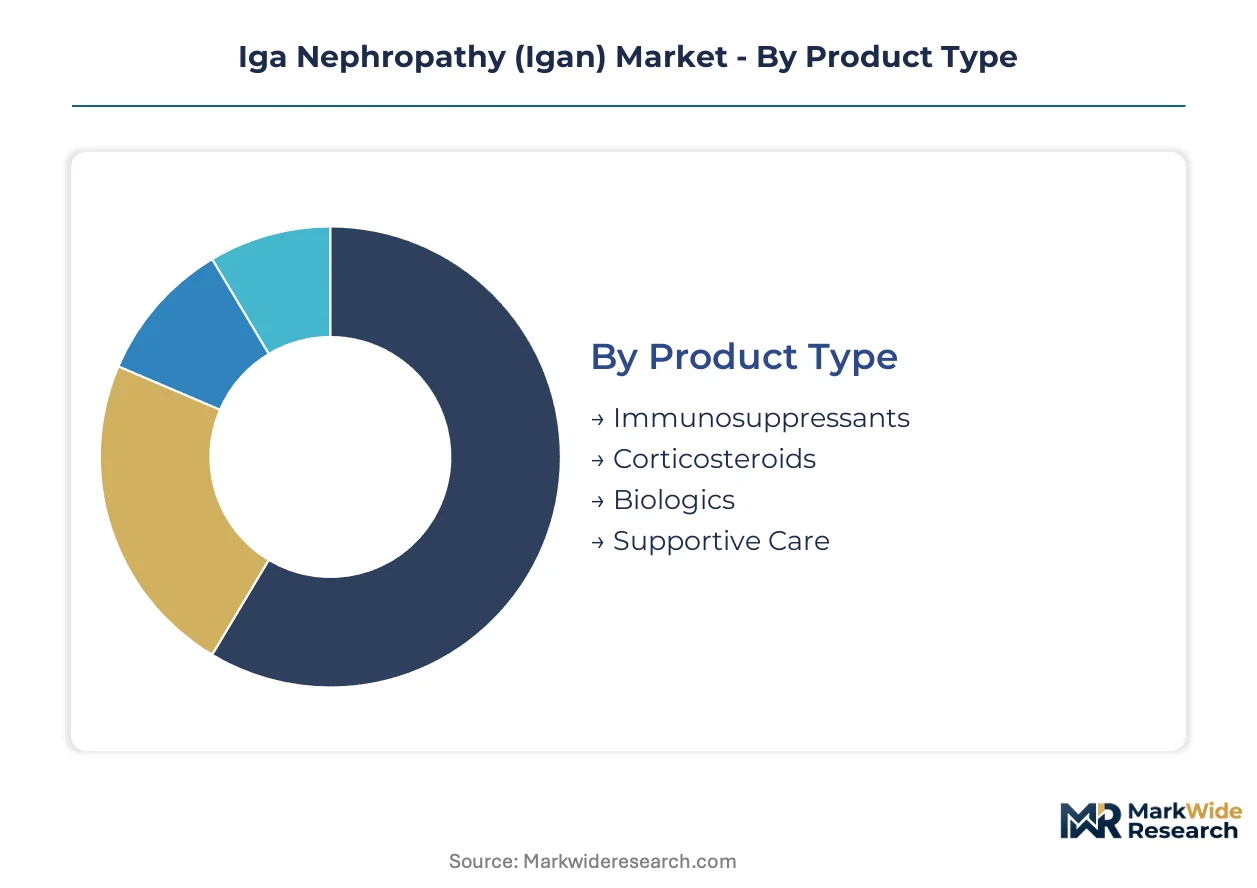
IgA nephropathy treatment pathways fragment across therapeutic intensity, care setting, and diagnostic infrastructure. Each segmentation axis reveals distinct margin dynamics and competitive entry points for developers navigating renal rare-disease commercialization.
Product Type:
Premium pricing concentrates in mechanism-driven biologics, while volume pools sit with chronic immunosuppressant maintenance regimens.
- Biologics:B-cell and complement-targeted antibodies command development priority as FDA accelerated approvals reward surrogate proteinuria endpoints. United States nephrology networks drive adoption through specialty pharmacy integration, though manufacturing complexity constrains supply scalability.
- Immunosuppressants:Calcineurin inhibitors and mycophenolate mofetil retain substantial volume in progressive disease stages. European reimbursement systems favor these agents in early intervention protocols where biologic access remains restricted.
- Corticosteroids:Budesonide-targeted release formulations address mucosal immune origins with reduced systemic exposure.
- Supportive Care:ACE inhibitors and ARBs form the backbone of proteinuria suppression in watchful waiting populations.
The dominant share belongs to Immunosuppressants, while Biologics is closing the gap fastest.
End User:
Care delivery economics shift dramatically between institutional settings and distributed administration models.
- Specialty Clinics:United States nephrology centers consolidate complex biologic infusions and protocol-driven patient monitoring. These sites capture the highest per-patient revenue through bundled reimbursement for immunomodulatory therapy administration.
- Hospitals:Tertiary academic medical centers anchor diagnostic infrastructure for renal biopsy and rapid-progression phenotypes. Capacity constraints are pushing stable patients toward outpatient alternatives.
- Homecare:Subcutaneous biologic formulations and remote monitoring technologies enable treatment decentralization.
- Research Laboratories:Biomarker validation and companion diagnostic development concentrate in academic-industry partnerships.
Specialty Clinics capture the highest-margin procedures, with Homecare expanding most quickly through subcutaneous delivery innovations.
Treatment Strategy:
Revenue pools align with intervention timing, from early conservative protocols to late-stage renal replacement.
- Pharmacotherapy:Targeted immunomodulation and proteinuria suppression agents generate recurring revenue across disease stages. Payer negotiations center on eGFR slope preservation as a measurable outcome metric.
- Conservative Management:RAAS inhibition and blood pressure control retain substantial patient volume in low-risk categories. German G-BA assessments impose outcome-based pricing conditions that compress margins versus active immunotherapy.
- Renal Replacement Therapy:Dialysis and transplantation represent end-stage economic burden rather than pharmaceutical opportunity.
- Lifestyle Modification:Dietary sodium restriction and smoking cessation support pharmaceutical efficacy.
Pharmacotherapy commands the deepest revenue pools, though Conservative Management retains the broadest patient base.
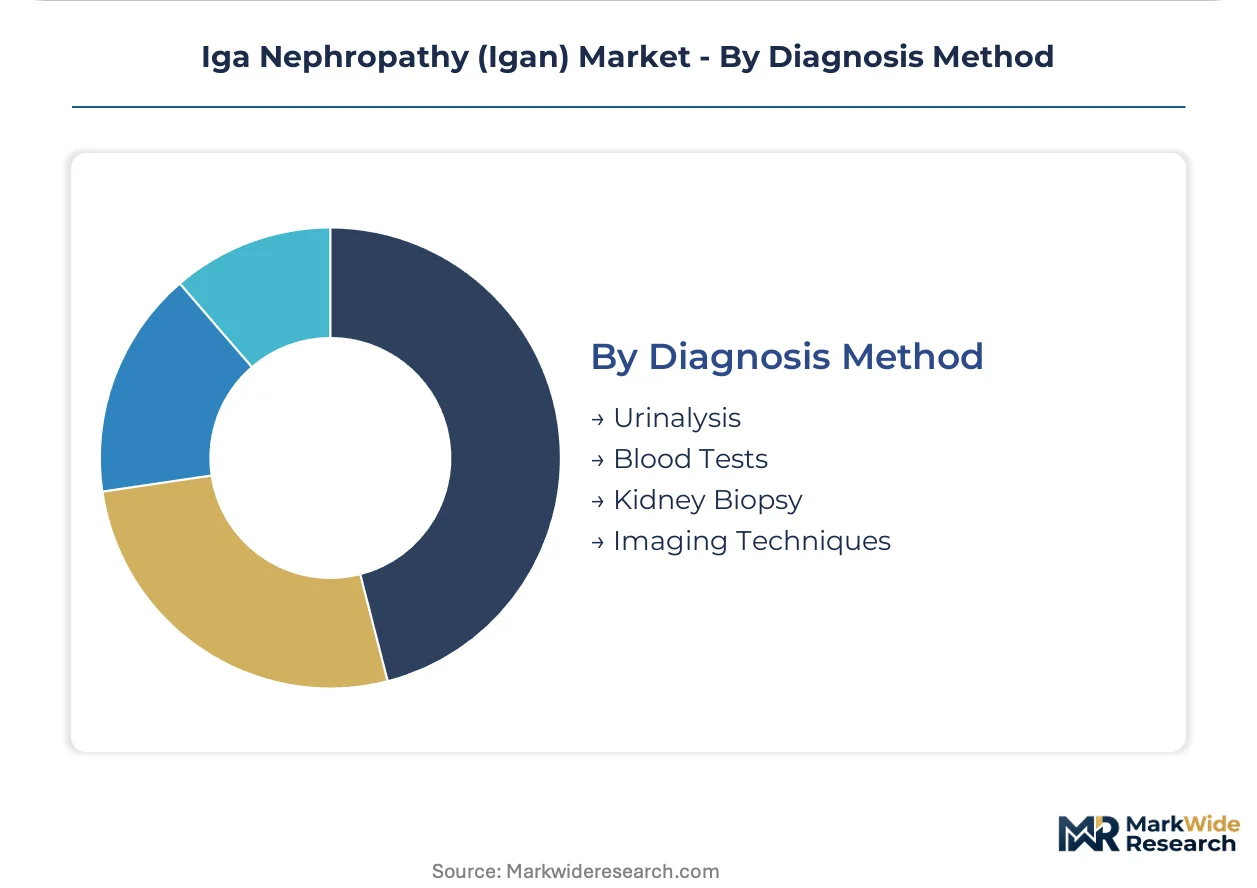
Diagnosis Method:
Diagnostic economics favor less invasive alternatives as biomarker science matures.
- Kidney Biopsy:Oxford classification scoring remains the reference standard for risk stratification and trial enrollment. Japan's PMDA maintains distinct histological requirements that filter foreign biologic market entry.
- Blood Tests:Galactose-deficient IgA1 serum assays are displacing tissue-based confirmation in community screening protocols. These panels enable earlier therapeutic intervention outside tertiary centers.
- Urinalysis:Proteinuria quantification provides accessible monitoring for disease progression.
- Imaging Techniques:Renal ultrasound supports structural assessment where biopsy contraindications exist.
Kidney Biopsy anchors clinical decision-making, while Blood Tests are gaining share fastest through non-invasive screening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's nephrology referral network anchors United States patient concentration, channeling high-complexity IgA nephropathy cases through tertiary diagnostic infrastructure. This institutional density underwrites premium biologic adoption rates that exceed European benchmarks.
United States
FDA's accelerated approval pathway compresses commercialization timelines for surrogate endpoint-driven biologics. The agency's orphan drug incentives reward developers targeting rare renal indications with extended exclusivity periods. Boston's Longwood Medical Area and the Mayo Clinic's Rochester campus concentrate Phase III trial enrollment and specialist referral volume.
Germany
G-BA assessment protocols impose outcome-based pricing conditions that compress net revenue versus US list prices for immunomodulatory therapies. EMA's adaptive licensing pilot enables conditional market access based on intermediate proteinuria endpoints rather than hard renal survival data. Heidelberg and Berlin anchor the country's renal biopsy infrastructure and academic nephrology research clusters.
Japan
PMDA maintains distinct renal biopsy requirements that filter market entry for foreign biologics, creating regulatory friction for developers. The country's national health insurance system reimburses conservative management protocols more generously than novel immunotherapy. Tokyo and Osaka metropolitan areas concentrate the nation's limited tertiary nephrology capacity.
Sweden
Academic medical centers in Stockholm and Gothenburg pioneered B-cell depletion protocols targeting APRIL and BAFF signaling pathways for rapid-progression phenotypes. The Swedish Orphan Drug Act aligns with EMA frameworks to accelerate rare renal disease therapy access. Uppsala's biomarker research cluster advances galactose-deficient IgA1 serum assay validation.
United Kingdom
NICE technology appraisals impose cost-effectiveness thresholds that restrict biologic access to high-risk proteinuria populations. The NHS's specialized commissioning framework concentrates IgA nephropathy biologic administration in designated renal units. London's Guy's Hospital and Manchester Royal Infirmary anchor the country's clinical trial and referral infrastructure.
Iga Nephropathy (Igan) Market Key Industry Players
Concentration sits with rare-disease specialists possessing integrated regulatory and commercial infrastructure. The competitive structure fragments across three tiers: large-cap pharmaceutical conglomerates with renal franchises, mid-cap biotechs with single-asset precision strategies, and emerging platforms targeting complement cascade mechanisms. Strategic moves center on surrogate endpoint validation for accelerated approval pathways and post-market confirmatory study infrastructure buildout.
Within the rare-disease specialist tier, Calliditas Therapeutics, Travere Therapeutics, and Novartis occupy distinct positioning vectors. Calliditas anchors European commercial infrastructure for mucosal-targeted immunomodulation. Travere exemplifies the proteinuria-reduction endpoint strategy through single-asset development concentration. Novartis represents the diversified pharmaceutical archetype, leveraging cross-therapeutic area regulatory relationships and existing nephrology sales infrastructure across major markets.
| Leading Market Players |
|---|
| Novartis |
| Calliditas Therapeutics |
| Travere Therapeutics |
| AstraZeneca |
| Vertex Pharmaceuticals |
| Otsuka Pharmaceutical |
| Biogen |
| Vera Therapeutics |
| Ionis Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Single-use bioreactor capacity utilization rates above 85% in United States and Irish contract manufacturing sites compress marginal production costs for complement inhibitors while establishing hard price floors for biosimilar entrants. This scale concentration enables originator biologics to sustain premium positioning against immunosuppressant alternatives across nephrology networks.
Pricing Analysis
Volume-discount tiering structures separate originator biologics from authorized generics and corticosteroid formulations across United States specialty pharmacy networks. Pricing stratifies across premium, standard, and economy tiers based on mechanism novelty and FDA approval pathway, with accelerated-approval biologics commanding the highest per-dose positioning. Cost compression in the immunosuppressant tier intensifies as calcineurin inhibitor generics proliferate through 180-day exclusivity windows. Community nephrology practices exhibit the greatest price sensitivity, while academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Inventory lead times for viral clearance validation and fill-finish capacity extend 14-18 months for complement-targeted antibodies, constraining responsive supply scaling. Manufacturing concentrates in the United States, Ireland, and Singapore, with single-source dependencies on Chinese-sourced chromatography resins and German-engineered bioreactor hardware. Tariff exposure on imported active pharmaceutical ingredients threatens margin stability for developers with limited backward integration. Distribution runs through cold-chain specialty pharmacy networks anchored by McKesson and AmerisourceBergen infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution pressure from B-cell depletion therapies threatens calcineurin inhibitor incumbents, forcing defensive portfolio restructuring across immunosuppressant manufacturers.
For Market Incumbents: Fortify formulary positioning through outcome-based contracts with United States nephrology networks that tie reimbursement to eGFR slope preservation. Accelerate backward integration into galactose-deficient IgA1 diagnostic assay production to capture upstream margin from biomarker-driven patient selection. The priority lever centers on embedding clinical pharmacists within specialty clinics to manage prior authorization workflows and defend against biosimilar displacement.
For New Entrants and Emerging Players: Differentiate on complement cascade mechanism novelty, specifically Factor B and properdin targeting beyond saturated C5 inhibition categories. White-space opportunity concentrates in Japan's community nephrology settings, where biopsy infrastructure gaps delay biologic adoption. A direct-to-specialist education model bypassing traditional hospital formulary committees offers the most penetrable go-to-market angle for subcutaneous formulation developers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with post-market confirmatory study infrastructure already contracted, ensuring FDA accelerated approval retention. Long-term viability hinges on pipeline diversification across immunomodulatory mechanisms rather than single-asset concentration. The acquisition target archetype combines European regulatory relationships with United States specialty pharmacy distribution contracts. Watch for EMA adaptive licensing pilot expansion signals as inflection indicators for European commercial strategy value.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment in Oxford classification-stratified populations accelerates surrogate endpoint validation for FDA accelerated approval. |
| Regulatory Approval Pathway | Orphan drug designation secures EMA fee waivers and United States exclusivity extensions for rare renal indications. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Irish sites reduces viral clearance validation bottlenecks for complement inhibitors. |
| Pipeline Diversification | APRIL and BAFF signaling pathway candidates hedge against C5 inhibitor saturation in proteinuria reduction. |
| Licensing Agreement | Japanese distribution partnerships circumvent PMDA biopsy data requirements through local regulatory expertise. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation. Sources included FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation converged on segment-level estimates.
Variance decomposition across treatment line, administration route, patient risk stratification, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from fitted adoption curves calibrated to historical rare-disease biologic launch trajectories. Forecast inputs incorporated nephrology workforce growth constraints and biopsy infrastructure expansion rates.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA adaptive licensing regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Global Hormone Refractory Breast Cancer Market
Medical Biotechnology
Cancer RNA Expression Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Amoxicillin Market