
 Smart Drug Discovery Market | 2026-2036
Smart Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Drug Discovery Market Insights
Clinical-grade predictive accuracy is collapsing the traditional boundary between computational screening and wet-lab validation. NVIDIA Corporation leverages its GPU architecture to train foundation models on molecular dynamics at scale. Schrödinger, Inc. sustains leadership in physics-based simulation software for lead optimization. Insilico Medicine anchors its position with generative AI platforms that design novel molecular structures de novo.
Smart drug discovery integrates artificial intelligence, machine learning, and large-scale biological data processing to identify therapeutic targets, optimize molecular candidates, and predict clinical outcomes with reduced reliance on traditional high-throughput screening. The technology stack typically processes genomic sequences, protein structures, and chemical libraries through neural architectures that score compound viability against ADMET parameters. Machine Learning dominates the technology segment as the workhorse algorithm class for target identification and property prediction, while AI platforms capture expanding margin pools through end-to-end workflow integration from hit discovery to preclinical candidate nomination. Pharmaceutical Companies represent the largest end user category by committed R&D spend, though Biotechnology Firms show the fastest adoption velocity for AI-native discovery infrastructures.
FDA's emerging framework for AI-enabled drug development tools shapes validation standards for predictive models used in regulatory submissions, while the EU AI Act imposes risk-classification requirements on clinical decision-support algorithms deployed in European trials. EMA's qualification opinion pathway for novel methodologies creates a structured route for computational platforms to gain regulatory acceptance. Stakeholders must monitor how divergence between FDA model validation guidance and EU algorithmic risk tiers affects platform deployment strategies across jurisdictions.
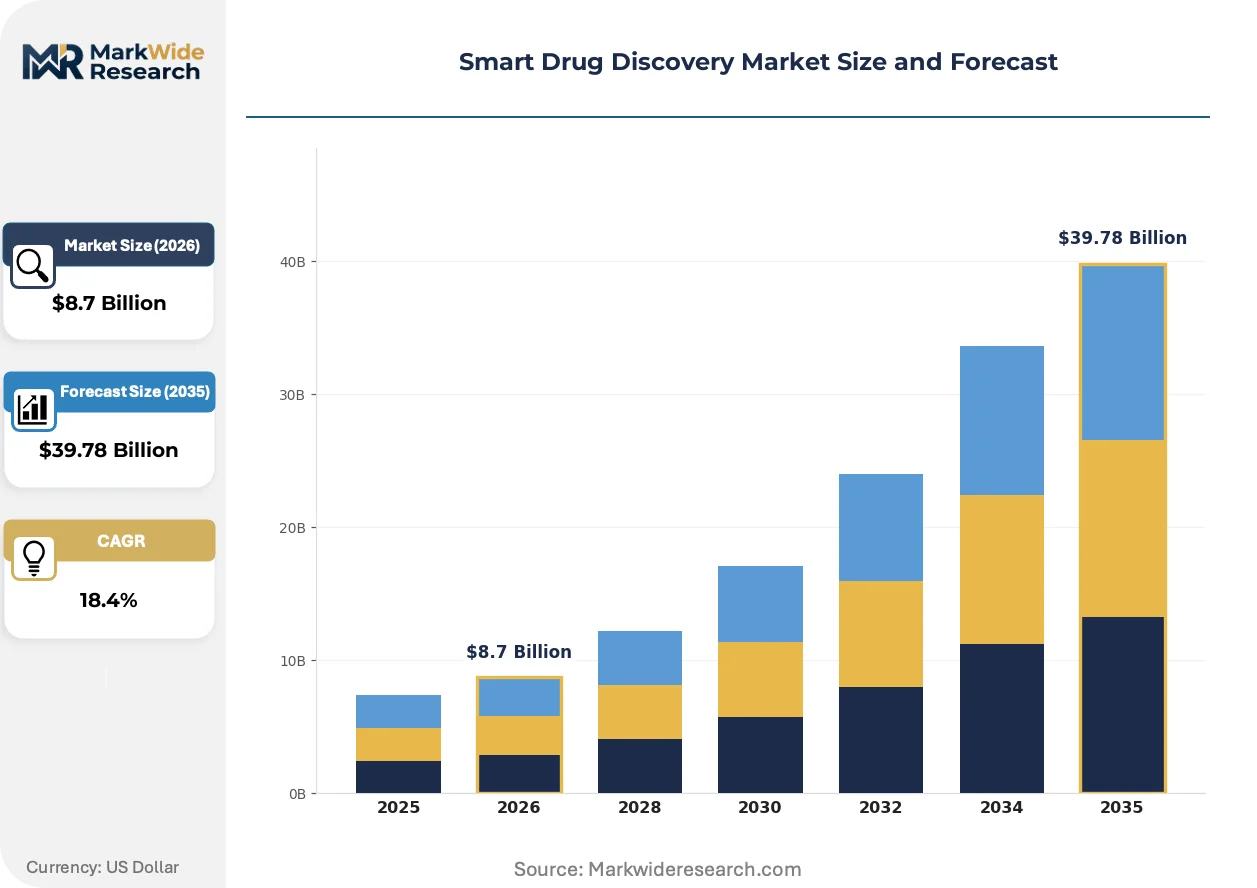
Market Dynamics
AI-enabled molecular simulation is collapsing the traditional handoff between computational chemistry and wet-lab validation, forcing pharmaceutical R&D organizations to restructure their discovery workflows around predictive model confidence rather than empirical throughput.
Growth Catalysts
- FDA's AI/ML-Based SaMD Guidance:The framework provides explicit validation pathways for predictive algorithms in drug development, reducing regulatory uncertainty for sponsors deploying machine learning models in IND-enabling studies.
- Foundation model architectures:Transformer-based neural networks trained on protein structure databases accelerate target identification timelines from months to weeks for biotechnology firms with limited structural biology expertise.
- Germany:The country's concentrated cluster of contract research organizations and AI-native biotech startups creates dense knowledge spillovers that compress platform development cycles.
Market Restraints
- GPU compute cost volatility:Training runs for large molecular dynamics simulations require sustained access to NVIDIA H100 clusters, with spot pricing fluctuations creating unpredictable opex burdens for mid-cap discovery platforms.
- EU AI Act high-risk system classification:Clinical decision-support algorithms deployed in European trials face mandatory conformity assessments, extending validation timelines by 12-18 months for computational platforms.
- Data silo fragmentation:Proprietary chemical libraries held by major pharmaceutical companies remain inaccessible to external AI vendors, limiting training set diversity for generative molecular design models.
Strategic Opportunities
- India:The country's CDSCO is streamlining digital health tool approvals, creating a regulatory arbitrage window for AI-native discovery platforms to establish clinical validation footholds ahead of US and EU submissions.
- Antibody-drug conjugate design:Generative AI platforms that optimize linker-payload combinations represent an emerging application with limited incumbent competition and high sponsor willingness-to-pay.
- Quantum-classical hybrid simulation:Convergence of quantum computing hardware with classical molecular dynamics workflows promises step-change accuracy for protein-ligand binding predictions in lead optimization.
Industry Challenges
- Computational biologist scarcity:The intersection of deep learning expertise and structural biology knowledge remains critically underpopulated, with pharmaceutical companies competing for the same limited talent pool in Boston and San Francisco.
- Legacy IT integration friction:Enterprise LIMS and ELN systems at established pharmaceutical companies lack API architectures compatible with real-time AI model inference, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Drug Discovery Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platforms, Tools, Databases Technology: Machine Learning, Big Data Analytics, AI, Genomics Application: Target Identification, Lead Optimization, Preclinical Testing, Clinical Trials End User: Pharmaceutical Companies, Research Institutes, Biotechnology Firms, Academic Institutions |
| Companies Covered | NVIDIA Corporation, Exscientia, Insilico Medicine, Recursion, BenevolentAI, Schrödinger, Inc., Atomwise Inc., Google, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Drug Discovery Market Trends and Innovations
Generative chemistry platforms are resequencing the traditional medicinal chemistry workflow, compressing the iteration loop between target validation and preclinical candidate nomination from years to months.
Diffusion models for molecular generation is fragmenting the incumbent structure-based design paradigm. These architectures predict 3D atomic coordinates conditioned on target binding pockets. Mid-cap biotechnology firms are adopting them aggressively for hit expansion campaigns. The technology is fragmenting competitive advantage away from crystallography infrastructure toward data curation and model fine-tuning capabilities.
EMA's qualification opinion pathway for novel methodologies is formalizing regulatory acceptance for computational platforms. The structured route enables sponsors to obtain binding scientific advice on model validation standards before pivotal trial initiation. European biotechnology firms with AI-native discovery engines are prioritizing this pathway to de-risk regulatory submissions.
Pharmaceutical procurement departments are unbundling AI platform licensing from full-stack service contracts. Sponsors increasingly prefer API-accessible molecular property predictors over end-to-end discovery partnerships. This shift concentrates vendor selection criteria on model accuracy benchmarks rather than therapeutic area expertise, favoring specialized algorithm developers over integrated CROs in the United States.
Smart Drug Discovery Market Segmentation
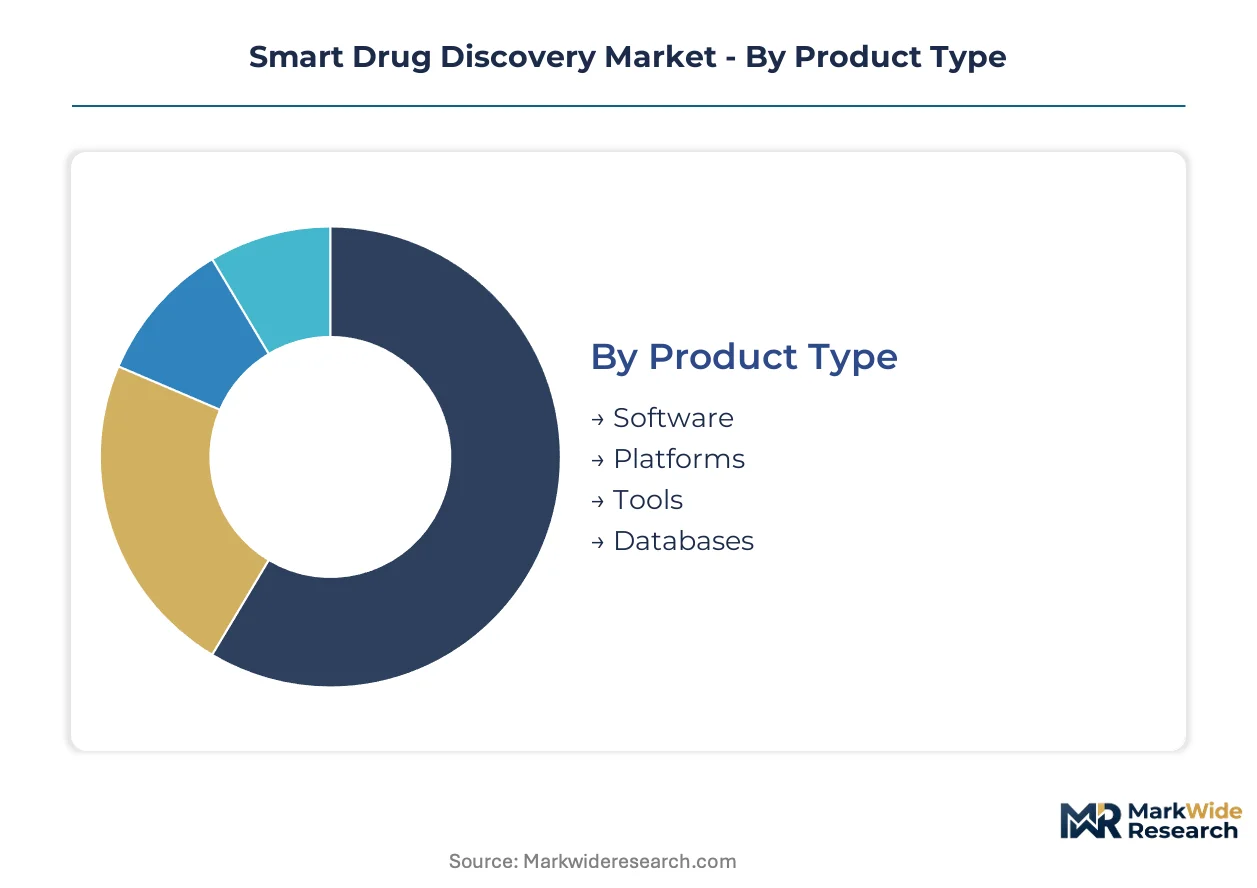
Segmentation in smart drug discovery reveals how computational investment patterns diverge across technology maturity levels and regulatory exposure zones. Pharmaceutical procurement teams allocate budgets differently depending on whether platforms face FDA validation requirements or EU AI Act risk classifications.
Product Type:
FDA's emerging framework for AI-enabled drug development tools creates tiered validation obligations that segment procurement priorities across software licensing models.
- Software:Modular molecular property predictors deploy through API architectures that integrate with existing ELN systems. Pharmaceutical companies in the United States favor these for lead optimization workflows where FDA model validation guidance demands reproducible algorithmic outputs.
- Platforms:End-to-end discovery environments span target identification through preclinical candidate nomination. Biotechnology firms in Germany adopt these most aggressively, leveraging the country's dense CRO cluster to compress platform customization cycles.
- Tools:Specialized utilities for protein-ligand docking or ADMET prediction serve crystallography groups with discrete computational needs.
- Databases:Curated chemical libraries and genomic datasets underpin training pipelines for generative molecular design models.
Established volume favors Software; emerging adoption favors Platforms.
Technology:
Compute cost structures and talent availability determine which algorithm classes dominate R&D budgets across sponsor organizations.
- Machine Learning:Supervised learning architectures for target identification and property prediction remain the workhorse technology class. These models require less specialized infrastructure than foundation architectures, attracting mid-cap biotechnology firms with constrained GPU budgets.
- AI:Transformer-based neural networks and generative architectures command premium licensing fees but compress discovery timelines from years to months. Sponsors in China prioritize these platforms where NMPA digital health guidance creates faster regulatory feedback loops than Western jurisdictions.
- Big Data Analytics:Multi-omics integration pipelines process genomic, transcriptomic, and proteomic datasets for target prioritization.
- Genomics:Sequence-based target discovery tools align CRISPR screening data with disease-associated variants.
Machine Learning captures committed spend; AI commands expanding margin pools.
Application:
Wet-lab validation requirements create sharp divergence in sponsor willingness-to-pay across the discovery-to-clinic continuum.
- Target Identification:Foundation models trained on protein structure databases accelerate target prioritization from months to weeks. Biotechnology firms with limited structural biology expertise concentrate demand here, particularly in Boston and San Francisco where computational biologist talent pools overlap.
- Lead Optimization:Physics-based simulation and generative chemistry platforms compress medicinal chemistry iteration loops. Pharmaceutical companies in Germany deploy these aggressively, exploiting the country's concentrated CRO infrastructure for rapid model validation.
- Preclinical Testing:Predictive toxicology and pharmacokinetic models reduce animal study requirements for IND-enabling packages.
- Clinical Trials:Patient stratification algorithms face EU AI Act high-risk system classification, extending validation timelines for European deployments.
Lead Optimization concentrates incumbent spend; Target Identification attracts insurgent investment.
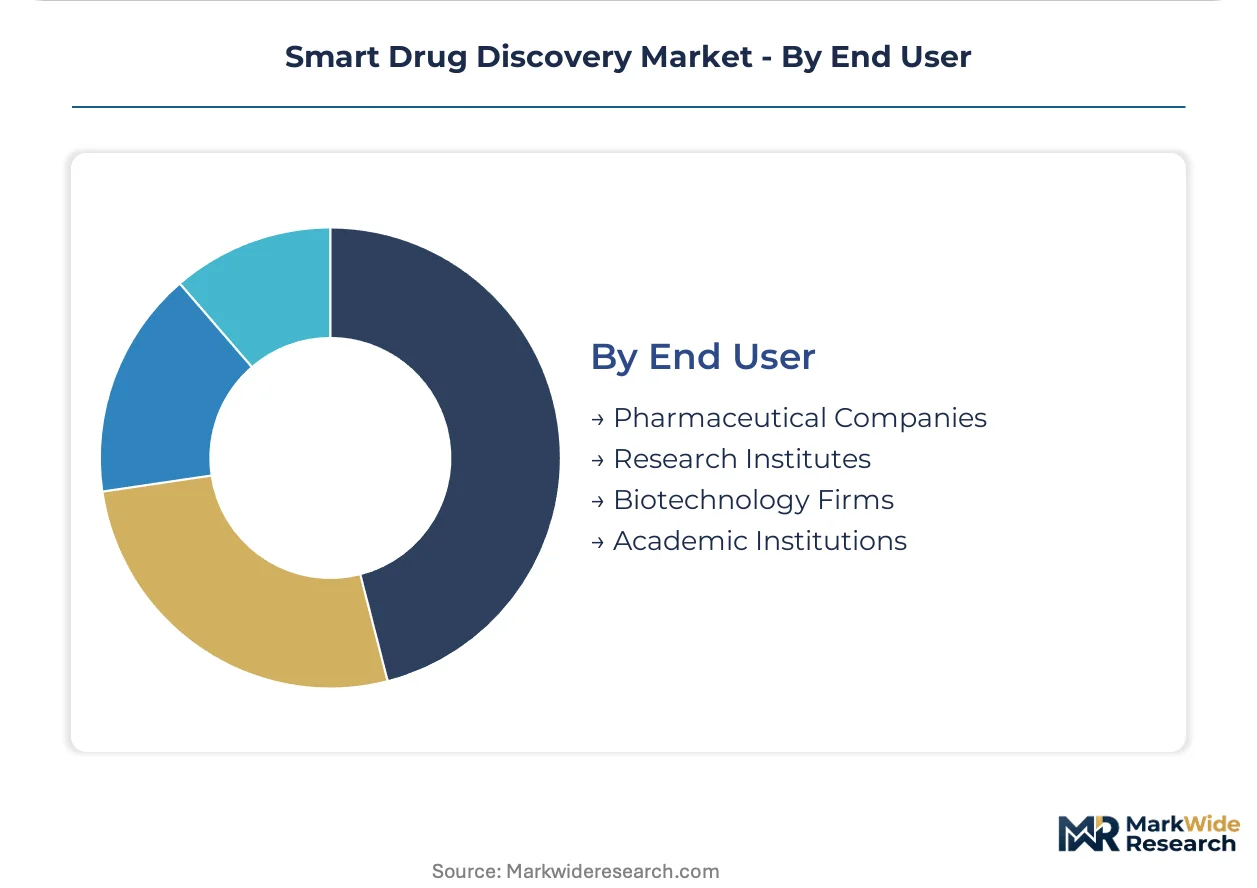
End User:
Organizational scale and legacy IT architecture determine adoption velocity for AI-native discovery infrastructures.
- Pharmaceutical Companies:Enterprise R&D organizations commit the largest absolute budgets but face legacy LIMS and ELN integration friction. These sponsors in the United States increasingly unbundle platform licensing from full-stack service contracts, favoring API-accessible predictors over end-to-end partnerships.
- Biotechnology Firms:AI-native startups without incumbent IT debt adopt generative platforms fastest. These organizations in China leverage NMPA regulatory agility to establish clinical validation footholds ahead of US and EU submissions.
- Research Institutes:Academic and government laboratories prioritize open-source toolchains and public dataset access.
- Academic Institutions:University groups train foundational talent but lack procurement scale for enterprise platform licenses.
Pharmaceutical Companies anchor revenue concentration; Biotechnology Firms drive technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in computational drug discovery services favor net exporters with dense AI talent clusters and regulatory clarity. The United States, Germany, and China dominate cross-border platform licensing, while India and Switzerland capture arbitrage opportunities through streamlined validation pathways.
United States
FDA's AI/ML-Based SaMD Guidance provides explicit validation pathways for predictive algorithms, reducing regulatory uncertainty for sponsors deploying machine learning models in IND-enabling studies. The Boston and San Francisco metropolitan areas concentrate computational biologist talent pools where pharmaceutical companies compete aggressively for hybrid expertise. NVIDIA Corporation leverages its GPU architecture to train foundation models on molecular dynamics at scale from its Santa Clara headquarters.
Germany
The country's concentrated cluster of contract research organizations and AI-native biotech startups creates dense knowledge spillovers that compress platform development cycles. EMA's qualification opinion pathway for novel methodologies formalizes regulatory acceptance for computational platforms through binding scientific advice. Heidelberg and Munich anchor the European pharmaceutical AI corridor where physics-based simulation software dominates lead optimization workflows.
China
NMPA digital health guidance creates faster regulatory feedback loops than Western jurisdictions, attracting biotechnology firms seeking clinical validation footholds ahead of US and EU submissions. Sponsors in Shanghai and Beijing prioritize transformer-based neural networks and generative architectures that compress discovery timelines from years to months. The Yangtze River Delta concentration of AI-native discovery engines exploits regulatory agility to establish preclinical candidate nomination records.
India
CDSCO streamlining of digital health tool approvals creates a regulatory arbitrage window for AI-native discovery platforms to establish clinical validation footholds. Bangalore and Hyderabad host expanding computational biology service centers that process genomic sequences and protein structures for Western sponsors. The country's pharmaceutical software exports concentrate in modular molecular property predictors that deploy through API architectures.
Switzerland
Swissmedic maintains alignment with EMA qualification pathways while offering faster scientific advice timelines for computational platform sponsors. Basel and Zurich concentrate precision medicine AI ventures that optimize antibody-drug conjugate linker-payload combinations. The regulatory environment attracts sponsors seeking de-risked European trial initiation for patient stratification algorithms.
Smart Drug Discovery Market Competitive Landscape
Listed leaders compete with private specialists across hardware infrastructure and algorithmic specialization dimensions. The vendor base stratifies into three tiers: semiconductor giants supplying computational substrate, platform developers integrating end-to-end workflows, and boutique algorithm shops selling modular predictors. Strategic archetypes include GPU-dependent foundation model trainers, physics-based simulation incumbents, and generative chemistry insurgents. Dominant competitive moves center on API-accessible unbundling of platform services and vertical integration into proprietary therapeutic pipelines.
Within the semiconductor substrate tier, NVIDIA Corporation occupies a position as the dominant GPU architecture provider for molecular dynamics training runs. Physics-based simulation specialists exemplify Schrödinger, Inc. and its sustained leadership in lead optimization software. Generative AI insurgents include Insilico Medicine, which anchors its market presence with de novo molecular structure design platforms. These three archetypes represent the competitive structure where hardware access, scientific computing heritage, and algorithmic novelty respectively concentrate advantage.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Exscientia |
| Insilico Medicine |
| Recursion |
| BenevolentAI |
| Schrödinger, Inc. |
| Atomwise Inc. |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
GPU cloud compute substitution for on-premise H100 clusters is redrawing supply geography toward NVIDIA-dominated data center regions while compressing pricing power for mid-cap discovery platforms locked into volatile spot-market contracts.
Pricing Analysis
Pharmaceutical procurement teams anchor platform licensing economics around API-accessible molecular property predictors rather than full-stack service contracts. Pricing stratifies across foundation-model tiers, physics-based simulation modules, and modular ADMET predictors, with differentiation driven by FDA validation documentation and model accuracy benchmarks. Cost compression in mid-tier machine learning platforms is intensifying because biotechnology sponsors unbundle services and demand per-inference pricing. Early-stage AI-native biotech firms exhibit highest price sensitivity, while top-20 pharmaceutical companies prioritize validation pedigree over licensing cost.
Supply Chain Analysis
Strategic stockpiling of GPU compute reservations dominates procurement behavior as training run continuity outweighs just-in-time cost optimization for foundation model developers. Hardware supply concentrates in the United States, Taiwan, and South Korea, with NVIDIA H100 clusters feeding molecular dynamics workflows. Software dependencies draw from proprietary chemical libraries held by major pharmaceutical companies and open protein structure databases. Single-source vulnerability around NVIDIA GPU architecture creates concentration risk. Distribution runs through cloud marketplace APIs and direct enterprise licensing agreements with pharmaceutical IT procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates niche opportunities for platforms that master validation pathway arbitrage between FDA, EMA, and NMPA submission requirements.
For Market Incumbents: Consolidate API-accessible predictor portfolios through targeted acquisition of specialized ADMET algorithm shops, defending against generative chemistry insurgents displacing physics-based simulation incumbents. Deepen backward integration into proprietary therapeutic pipelines to capture downstream value beyond platform licensing fees.
For New Entrants and Emerging Players: Regulatory validation services for EU AI Act conformity assessments represent the most penetrable white-space target, as established vendors lack dedicated compliance engineering teams. Target mid-cap biotechnology firms in Germany seeking EMA qualification opinion support. Lead with bundled validation-documentation offerings rather than raw algorithm accuracy.
For Investors and Strategic Acquirers: FDA's final AI/ML-Based SaMD guidance reshapes the acquisition landscape by elevating platforms with documented model validation protocols. Long-term viability centers on sponsors capable of bridging computational prediction with regulatory acceptance across multiple jurisdictions. Monitor EMA qualification opinion receipt rates as the critical inflection signal for platform de-risking.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Opinion Pursuit | Binding scientific advice de-risks regulatory submissions for AI-native discovery engines. |
| API-First Platform Unbundling | Modular molecular property predictors integrate with legacy ELN systems at pharmaceutical sponsors. |
| GPU Compute Reservation Lock-in | Sustained H100 cluster access secures training run continuity for foundation model development. |
| Antibody-Drug Conjugate Specialization | Generative linker-payload optimization captures high sponsor willingness-to-pay in oncology. |
| Regulatory Arbitrage Establishment | CDSCO and NMPA validation footholds accelerate clinical entry ahead of Western submissions. |
Research Methodology
The analysis maps machine learning platforms, generative AI architectures, physics-based simulation software, and molecular database providers, each validated through drug development executives, regulatory affairs leads, computational biology directors, and pharmaceutical procurement managers. Primary interview findings triangulate against FDA filings, EMA qualification opinions, ClinicalTrials.gov records, and hyperscaler GPU capex disclosures. Bottom-up platform licensing revenue estimates reconcile with top-down pharmaceutical R&D spend allocation patterns.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology type, application stage, end-user organization scale, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves incorporating AI adoption velocity, GPU compute cost trajectories, and regulatory pathway timeline assumptions specific to computational drug development tool qualification.
Underlying assumptions cover FDA guidance finalization timelines, EU AI Act enforcement intensity, and NVIDIA GPU supply continuity, with deviation risk concentrated in regulatory divergence between jurisdictions. Revision becomes warranted when EMA qualification opinion issuance rates or NMPA digital health approval velocities cross material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Blau Syndrome Market
Medical Biotechnology
Medroxyprogesterone Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Cellular Epigenetics Market
Medical Biotechnology
Human Placental Protein Market