
 Gene Therapy in CNS Disorder Market | 2026-2036
Gene Therapy in CNS Disorder Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Therapy in CNS Disorder Market Foresight
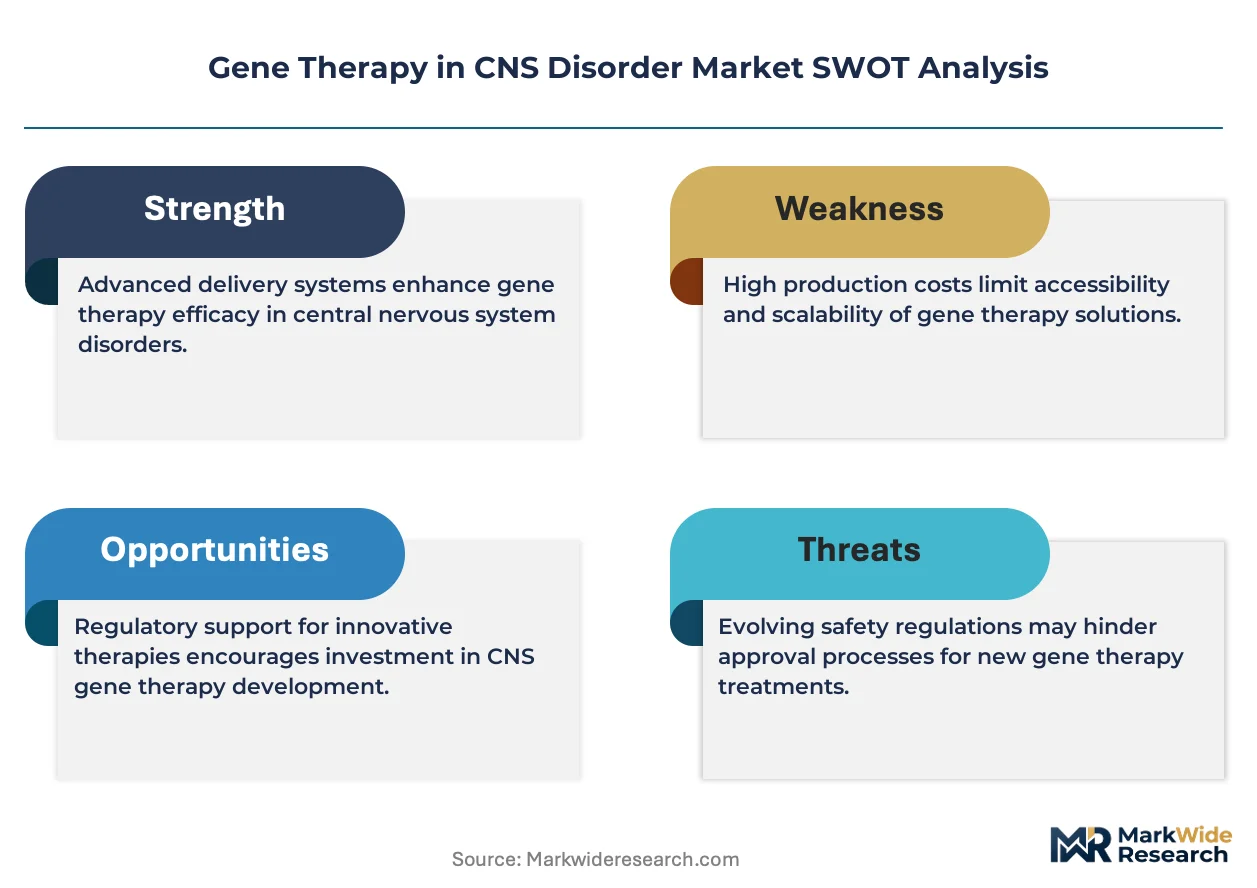
Platform licensing revenue is reconfiguring competitive economics in neurodegenerative gene delivery. Novartis leverages its Zolgensma infrastructure to sustain manufacturing scale across spinal muscular atrophy and broader CNS indications. Biogen anchors its position through antisense and gene therapy convergence in amyotrophic lateral sclerosis, while Sarepta Therapeutics differentiates via Duchenne muscular dystrophy expertise that extends to CNS-targeted programs.
Gene therapy in CNS disorders deploys engineered viral vectors—predominantly adeno-associated virus serotypes with tissue-specific capsid modifications—to deliver functional genetic payloads across the blood-brain barrier, achieving therapeutic protein expression in neuronal populations with single-administration durability. AAV vector platforms dominate current clinical pipelines due to established safety profiles and scalable suspension manufacturing in HEK293 or Sf9 systems. Lentiviral vectors occupy specialized niches in ex vivo hematopoietic stem cell gene therapy with CNS trafficking potential, while intrathecal delivery modes command premium positioning against intravenous alternatives for direct cerebrospinal fluid access.
FDA regenerative medicine advanced therapy designation and EMA priority medicines status compress development timelines for CNS gene therapies, though reimbursement complexity under CMS and national health technology assessment bodies constrains commercial rollout velocity. The EU AI Act and GDPR impose algorithmic transparency requirements on AI-driven patient stratification tools increasingly deployed in gene therapy trials. Stakeholders must monitor evolving manufacturing standards from ISO and national pharmacopeias as autologous and allogeneic vector production scales toward commercial viability.
Market Dynamics
Vector manufacturing concentration among contract development organizations is creating supply bottlenecks for neurodegenerative programs, forcing academic medical centers and biopharmas to internalize production capacity or face clinical trial delays.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy:Compressed review timelines for spinal muscular atrophy and Huntington's disease candidates accelerate patient access and reduce development risk.
- AAV capsid engineering:Tissue-specific modifications to adeno-associated virus serotypes improve blood-brain barrier penetration and neuronal targeting precision.
- Intrathecal delivery infrastructure:Academic medical centers in Boston, Basel, and Singapore are building dedicated cerebrospinal fluid administration suites for direct CNS access.
Market Restraints
- HEK293 suspension manufacturing costs:Plasmid DNA and transfection reagent expenses constrain margin expansion for high-dose CNS indications.
- Single-source plasmid suppliers:Concentration among North American CDMOs creates vulnerability for vector producers scaling commercial batches.
- EU AI Act algorithmic transparency:GDPR-mandated explainability requirements complicate deployment of AI-driven patient stratification tools in European gene therapy trials.
Strategic Opportunities
- Underpenetrated amyotrophic lateral sclerosis:Antisense and gene therapy convergence creates white space for disease-modifying interventions beyond symptomatic management.
- EMA Priority Medicines status:Accelerated assessment pathways for CNS gene therapies reduce time-to-market for qualifying candidates.
- Lentiviral ex vivo platforms:Hematopoietic stem cell modification with CNS trafficking potential opens autologous delivery routes for neurodegenerative storage disorders.
Industry Challenges
- Bioprocess engineering talent scarcity:Shortage of specialists in Sf9 baculovirus systems and adherent-to-suspension scale-up constrains in-house vector manufacturing buildouts.
- ISO cell and gene therapy standards:Evolving international manufacturing guidelines require continuous facility requalification during commercial scale-up.
- CMS one-time therapy reimbursement:Novel payment mechanism negotiation complexity delays hospital pharmacy budget allocation for administered gene therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Therapy in CNS Disorder Market |
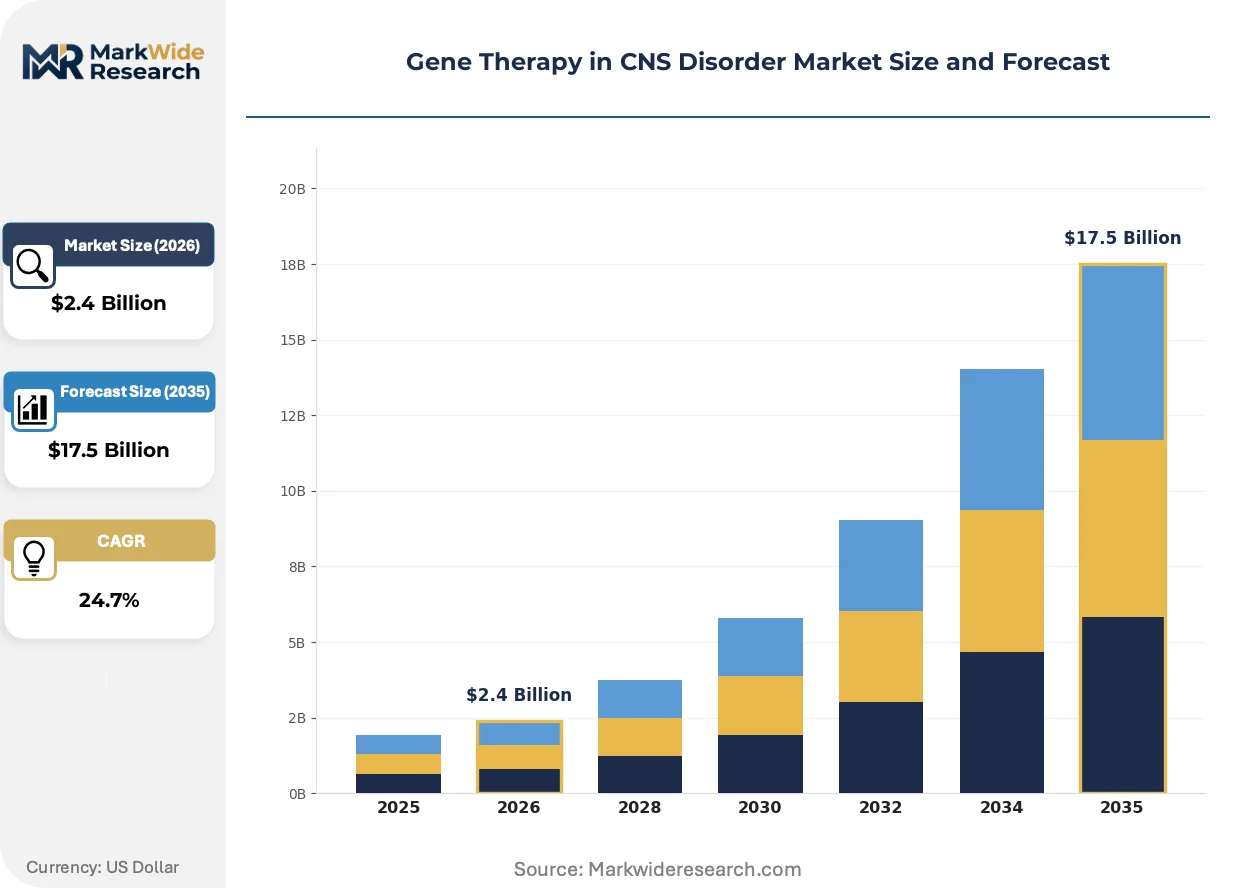
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $17.5 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vector, AAV Vector, Lentiviral Vector, Plasmid DNA Therapy Area: Neurological Disorders, Genetic Disorders, Metabolic Disorders, Autoimmune Disorders End User: Research Institutions, Hospitals, Clinics, Biotech Companies Delivery Mode: Intravenous, Intrathecal, Intraocular, Oral |
| Companies Covered | Novartis, Biogen, Spark Therapeutics, UniQure, Voyager Therapeutics, Sarepta Therapeutics, REGENXBIO, Bluebird Bio, Neurogene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Therapy in CNS Disorder Market Shifts & Advancements
Next-generation delivery technologies and regulatory pathway innovations are compressing development timelines while reshaping how therapeutic genetic payloads reach neuronal populations. Three developments dominate current strategic planning.
Next-generation AAV serotypes with engineered capsid surface proteins are collapsing the historical trade-off between CNS tropism and immunogenicity risk. Biopharma developers are adopting these variants for high-dose intravenous programs previously limited to intrathecal routes. The structural consequence is a reallocation of clinical investment toward systemic administration modalities that expand addressable patient populations.
EMA's integration of the EU AI Act into clinical trial oversight is forcing algorithmic disclosure for patient selection biomarkers. Sponsors must now document training data provenance and decision logic for AI tools stratifying Huntington's disease progression. European gene therapy programs are responding by establishing dedicated regulatory affairs functions for machine learning validation.
Hospital pharmacy procurement for one-time therapies is fragmenting across accountable care organizations and specialty pharmacy networks. Traditional wholesale distribution is losing share to direct-to-site contracting with outcome guarantees. The United States exhibits the most pronounced shift, where CMS innovation center models are testing episode-based payment for spinal muscular atrophy treatments.
Gene Therapy in CNS Disorder Market Segmentation
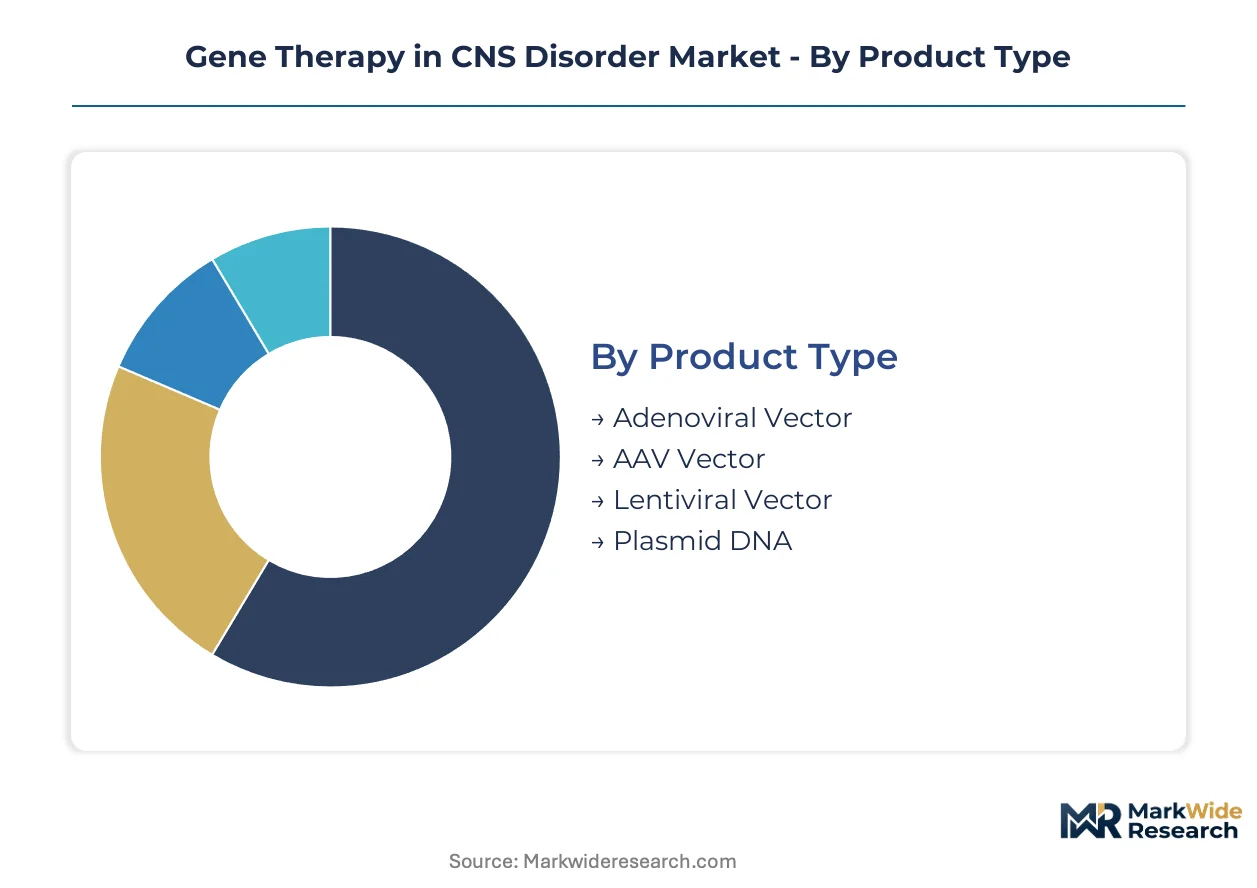
Gene therapy in CNS disorders fragments across vector biology, clinical indication, and administration route. Each segmentation axis carries distinct regulatory, manufacturing, and reimbursement implications that determine commercial viability and development prioritization.
Product Type:
Vector platforms span a functional spectrum from transient expression to genomic integration, with manufacturing complexity and immunogenicity risk defining competitive positioning.
- AAV Vector:Adeno-associated virus serotypes with tissue-specific capsid modifications deliver durable therapeutic expression in neuronal populations. Demand concentrates in intrathecal programs for spinal muscular atrophy and Huntington's disease, where established suspension manufacturing in HEK293 systems supports scalable supply.
- Lentiviral Vector:Integrating retroviral platforms enable permanent genomic modification in dividing and non-dividing cells alike. Academic medical centers in Boston and Basel are deploying lentiviral ex vivo approaches for hematopoietic stem cell programs with CNS trafficking potential, though Sf9 baculovirus production complexity limits widespread adoption.
- Adenoviral Vector:High-capacity transient expression systems serve specialized applications requiring large transgene payloads.
- Plasmid DNA:Non-viral naked DNA approaches offer reduced immunogenicity for specific metabolic indications.
The dominant share belongs to AAV Vector, while Lentiviral Vector is closing the gap fastest through ex vivo platform expansion.
Therapy Area:
Clinical indications stratify by disease prevalence, unmet need severity, and regulatory pathway maturity.
- Neurological Disorders:Amyotrophic lateral sclerosis and Parkinson's disease programs command premium R&D investment due to substantial patient populations and symptomatic standard-of-care limitations. FDA regenerative medicine advanced therapy designation compresses timelines for qualifying candidates.
- Genetic Disorders:Monogenic conditions including spinal muscular atrophy and Huntington's disease offer clear mechanistic targets with measurable biomarker endpoints. Singapore's academic medical centers are scaling dedicated manufacturing for these indications.
- Metabolic Disorders:Lysosomal storage diseases with CNS involvement require cross-correction strategies.
- Autoimmune Disorders:Emerging applications in multiple sclerosis and neuromyelitis optica remain preclinical.
Neurological Disorders anchors current revenue, with Genetic Disorders expanding most quickly through approved therapies.
End User:
Customer archetypes diverge sharply in procurement authority, technical sophistication, and outcome risk tolerance.
- Hospitals:Integrated delivery networks with dedicated gene therapy centers negotiate directly with manufacturers for one-time therapy administration. CMS innovation center episode-based payment models are reshaping budget allocation for spinal muscular atrophy treatments in United States systems.
- Biotech Companies:Development-stage sponsors drive preclinical and clinical vector demand through contract manufacturing relationships. Concentration among North American CDMOs creates supply vulnerability for scaling commercial batches.
- Research Institutions:Academic medical centers in Boston, Basel, and Singapore are building in-house Sf9 and HEK293 capacity to secure supply for neurodegenerative programs.
- Clinics:Outpatient specialty centers require simplified logistics for administration.
Hospitals command the largest procurement volume, while Biotech Companies are gaining share fastest through pipeline expansion.
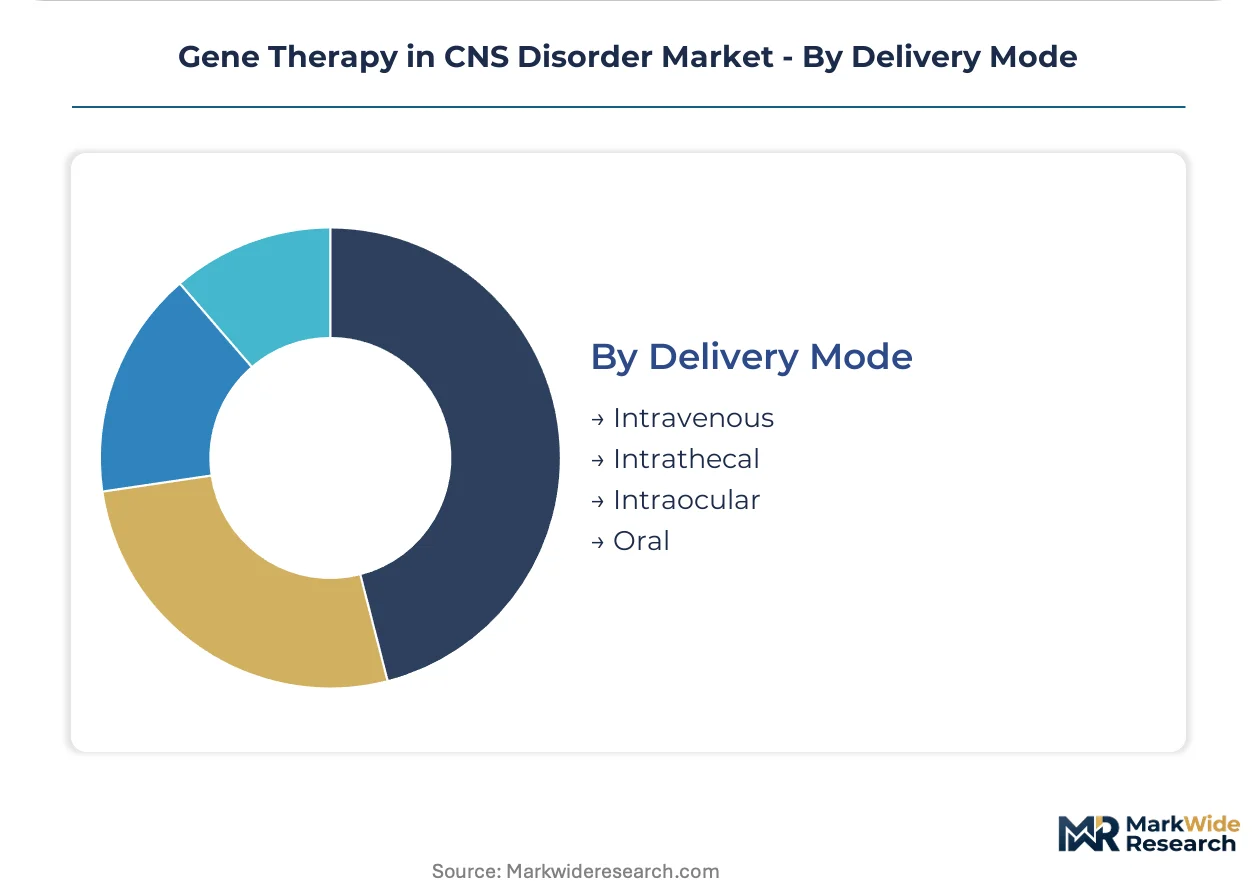
Delivery Mode:
Administration routes determine blood-brain barrier penetration, dosing requirements, and reimbursement complexity.
- Intrathecal:Direct cerebrospinal fluid injection achieves concentrated CNS exposure with lower systemic vector loads. Academic medical centers are building dedicated administration suites in Boston, Basel, and Singapore to support this premium positioning.
- Intravenous:Systemic administration expands addressable populations through simplified logistics, though higher doses increase manufacturing cost and immunogenicity risk. Next-generation AAV capsids with engineered surface proteins are collapsing the historical trade-off between CNS tropism and safety.
- Intraocular:Compartmentalized delivery for retinal manifestations of CNS storage disorders.
- Oral:Non-viral and exosome-mediated approaches remain experimental.
Intrathecal administration holds the leading position, with Intravenous delivery climbing the fastest through capsid engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vector manufacturing capacity clusters in three national hubs where academic medical centers and contract producers co-locate. FDA, EMA, and Singapore's national pharmaceutical regulator each compress development timelines through accelerated review pathways.
United States
CMS innovation center models test episode-based payment for spinal muscular atrophy treatments, reshaping hospital pharmacy budgets. FDA regenerative medicine advanced therapy designation compresses review timelines for Huntington's disease candidates. Boston's academic medical centers scale in-house HEK293 suspension manufacturing to secure vector supply for neurodegenerative programs.
Switzerland
Basel anchors European vector production with dedicated Sf9 baculovirus manufacturing infrastructure for lentiviral platforms. Swissmedic coordinates with EMA on priority medicines status for CNS gene therapies. The city's academic medical centers build cerebrospinal fluid administration suites for intrathecal delivery programs.
Singapore
The national pharmaceutical regulator accelerates assessment pathways for genetic disorder indications with clear mechanistic targets. Bioprocessing talent initiatives address scarcity in adherent-to-suspension scale-up specialists. Academic medical centers expand in-house vector manufacturing to reduce dependence on North American contract development organizations.
Germany
EMA priority medicines status reduces time-to-market for qualifying amyotrophic lateral sclerosis candidates. EU AI Act algorithmic transparency requirements complicate deployment of patient stratification tools in clinical trials. Heidelberg and Munich clusters concentrate ex vivo hematopoietic stem cell modification expertise with CNS trafficking potential.
United Kingdom
NHS England negotiates outcome-based contracts for one-time gene therapies, creating precedent for reimbursement complexity. MHRA post-Brexit alignment with EMA standards maintains regulatory coherence for CNS trials. London's research institutions deploy AI-driven biomarker validation under GDPR-mandated explainability frameworks.
Gene Therapy in CNS Disorder Market Competitive Landscape
Integrated pharmaceutical conglomerates and gene therapy specialists split the market into distinct capability tiers. Consolidation around manufacturing scale and regulatory expertise favors players with captive vector production. Three archetypes dominate: platform licensors with established capsid libraries, indication-focused developers with clinical trial momentum, and manufacturing-integrated sponsors securing supply chain control. Capacity expansion and strategic partnerships constitute the dominant competitive moves as supply bottlenecks force vertical integration decisions.
Within the platform licensor tier, Novartis and Sarepta Therapeutics exemplify divergent strategic positions. Novartis leverages Zolgensma infrastructure across spinal muscular atrophy and broader CNS indications. Sarepta Therapeutics occupies a position defined by Duchenne muscular dystrophy expertise extending to CNS-targeted programs. Among gene therapy specialists, Voyager Therapeutics sits within the next-generation delivery technology segment, representing capsid engineering approaches to blood-brain barrier penetration.
| Leading Market Players |
|---|
| Novartis |
| Biogen |
| Spark Therapeutics |
| UniQure |
| Voyager Therapeutics |
| Sarepta Therapeutics |
| REGENXBIO |
| Bluebird Bio |
| Neurogene |
| Others |
Supply & Pricing Matrix
North American plasmid DNA suppliers command pricing power over AAV vector producers scaling commercial batches for high-dose CNS indications. Margin pools concentrate downstream with hospital systems negotiating episode-based payment models for one-time gene therapies, while upstream raw material concentration forces vector manufacturers into long-term offtake commitments or backward integration.
Pricing Analysis
Outcome-based contracts with hospital systems now drive lifetime value capture for gene therapy developers beyond the initial administration event. Pricing stratifies across premium intrathecal programs, standard intravenous formulations, and economy-tier research-grade vectors differentiated by GMP certification level and HEK293 suspension manufacturing scale. Cost compression in research-grade supply is intensifying as academic medical centers internalize production capacity. Biotech companies with preclinical pipelines exhibit the highest price sensitivity, while integrated hospital networks with dedicated gene therapy centers prioritize supply security over per-dose cost.
Supply Chain Analysis
US Commerce Department export controls on gene synthesis equipment and dual-use bioprocessing technology limit flows to certain national pharmaceutical regulators, constraining capacity buildouts in emerging vector manufacturing hubs. Plasmid DNA production concentrates in the United States, Germany, and Singapore, while Sf9 baculovirus systems and HEK293 suspension media draw from specialized suppliers in Switzerland and Japan. Single-source vulnerability in transfection reagent supply creates exposure for commercial batch scaling. Distribution runs through direct-to-site contracting with outcome guarantees rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy in CNS disorders faces substitution pressure from antisense oligonucleotide platforms and CRISPR-based editing approaches that compete for the same amyotrophic lateral sclerosis and Huntington's disease development budgets.
For Market Incumbents: Insulate manufacturing margins through captive HEK293 suspension capacity in Boston or Basel, locking in plasmid supply through multi-year offtake agreements before competitors secure limited Sf9 baculovirus talent. Priority defensive moves include FDA regenerative medicine advanced therapy designation maintenance for pipeline candidates and direct hospital system contracting that blocks new entrant access to intrathecal administration suites. For New Entrants and Emerging Players: Build out lentiviral ex vivo platforms for hematopoietic stem cell programs with CNS trafficking potential, targeting the white space in lysosomal storage disorders where AAV immunogenicity limits repeat dosing. Singapore offers the most penetrable geography given national bioprocessing talent initiatives and reduced dependence on North American CDMOs. Go-to-market positioning should emphasize autologous delivery routes that bypass vector manufacturing bottlenecks entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract development organizations that consolidated during the pandemic and now face margin pressure as biopharma sponsors internalize vector production. Five-to-ten year viability hinges on regulatory pathway execution rather than manufacturing scale alone. Watch for EMA priority medicines status grants to Huntington's disease candidates as an inflection signal for European reimbursement negotiability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | In-house HEK293 suspension capacity secures supply against North American plasmid bottlenecks. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines for qualifying candidates. |
| Licensing Agreement | Platform capsid libraries from academic medical centers accelerate blood-brain barrier penetration programs. |
| Clinical Trial Advancement | Intrathecal delivery infrastructure in Boston and Basel supports direct cerebrospinal fluid access trials. |
| Pipeline Diversification | Antisense and gene therapy convergence in amyotrophic lateral sclerosis hedges against single-modality failure. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads, hospital procurement managers, vector manufacturing executives, and payer access specialists, then refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down vector demand estimates were triangulated to cross-check segment sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning vector platform type, therapy area, administration route, and regional regulatory cluster. CAGRs were derived from patient prevalence trajectories, approval probability-weighted revenue forecasts, and manufacturing capacity expansion schedules. Industry-specific inputs included intrathecal administration suite buildout timelines and CMS innovation center payment model adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by antisense platform developers or CRISPR-based editing companies would shift outcomes beyond modeled ranges. Material shifts in FDA regenerative medicine advanced therapy designation criteria or EMA priority medicines status eligibility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Gene Delivery Technologies Market