
 DNA Modifying Agents Market | 2026-2036
DNA Modifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Modifying Agents Market Outlook
Market Context
A capital-intensity divergence between integrated platform providers and reagent specialists is bifurcating competitive dynamics in DNA modifying agents. Thermo Fisher Scientific leverages end-to-end workflow control across instrumentation and consumables to sustain premium positioning in gene editing workflows. New England Biolabs anchors its standing through concentrated R&D in enzyme engineering, while Promega Corporation differentiates via luminescence-based validation technologies that extend into nucleic acid delivery applications.
Technical and Segment Structure
DNA modifying agents comprise molecular tools—enzymes, synthetic nucleases, and chemically modified oligonucleotides—that alter nucleic acid sequences, methylation states, or expression profiles, typically operating at nanomolar concentrations with sequence-specific recognition mechanisms. CRISPR systems dominate current gene editing procurement due to programmable RNA-guided targeting, while antisense oligonucleotides occupy mature positions in genetic disorder pipelines where splice-switching mechanisms have validated regulatory pathways. Agricultural biotechnology applications represent the fastest-expanding demand pool as gene silencing technologies enable trait development without transgenic integration.
Regulatory Environment
FDA oversight of gene therapy products and EMA's ATMP framework collectively shape clinical-grade DNA modifying agent standards, with both agencies tightening purity and potency specifications for nucleic acid delivery vectors. ISO 13485 certification requirements for in vitro diagnostic applications further constrain supplier qualification timelines. Stakeholders must monitor evolving germline editing prohibitions and somatic therapy guidance documents to anticipate demand shifts between research and clinical segments.
Market Dynamics
CRISPR-Cas9 platform standardization is compressing R&D timelines across therapeutic pipelines while fragmenting supplier margins between research-grade and clinical-grade reagent tiers.
Growth Catalysts
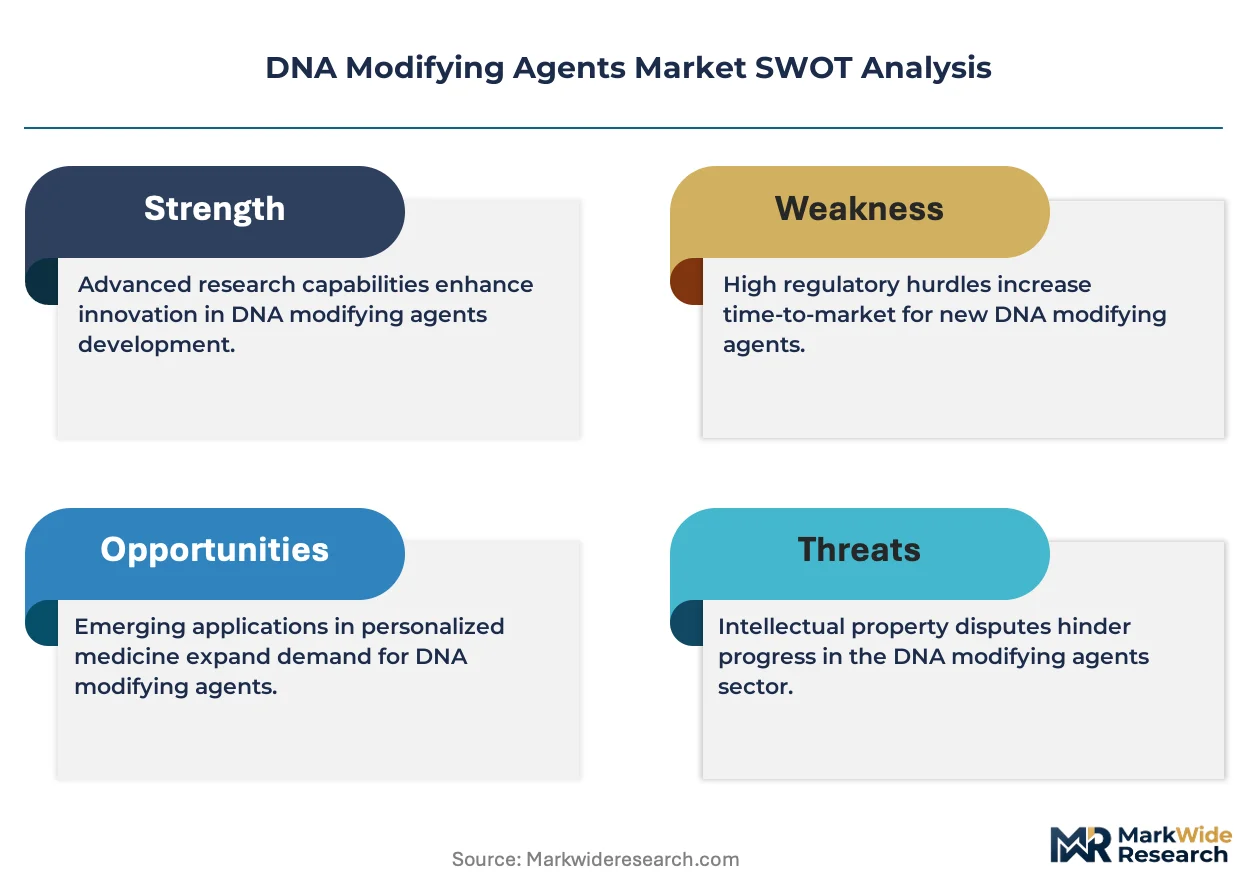
- FDA Gene Therapy Guidance:Streamlined IND pathways for somatic cell therapies accelerate clinical transitions for antisense oligonucleotide developers.
- Base Editing Maturation:Cytosine and adenine base editors reduce off-target liabilities, expanding addressable indications in hematologic disorders.
- Research Triangle Procurement:North Carolina's biotech corridor concentrates annual reagent procurement from Duke, UNC, and emerging cell therapy startups.
Market Restraints
- GMP Plasmid Scarcity:Clinical-grade plasmid DNA manufacturing capacity concentrates among three CDMOs in the United States and Switzerland.
- Guide RNA Synthesis Costs:Phosphoramidite chemistry and HPLC purification steps impose 40-60% cost premiums over research-grade equivalents.
- Homology-Directed Repair Limitations:Low efficiency in non-dividing cells restricts therapeutic applications for precise gene correction.
Strategic Opportunities
- Allogeneic Cell Therapy Scale-Up:Off-the-shelf CAR-T manufacturing demands bulk CRISPR reagent supply contracts with integrated quality systems.
- Prime Editing Convergence:Reverse transcriptase-integrated nickases combine search-and-replace precision with reduced double-strand break risks.
- IRA Price Negotiation Exemptions:Gene therapies under FDA's accelerated approval pathway retain pricing autonomy through 2028, preserving R&D reinvestment rates.
Industry Challenges
- ISO 13485 Certification Timelines:In vitro diagnostic applications require 18-24 month supplier qualification cycles that delay product launches.
- Guide RNA Bioinformatics Talent:Computational design of high-specificity gRNAs competes with broader AI/ML hiring markets for scarce PhD-level specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Modifying Agents Market |
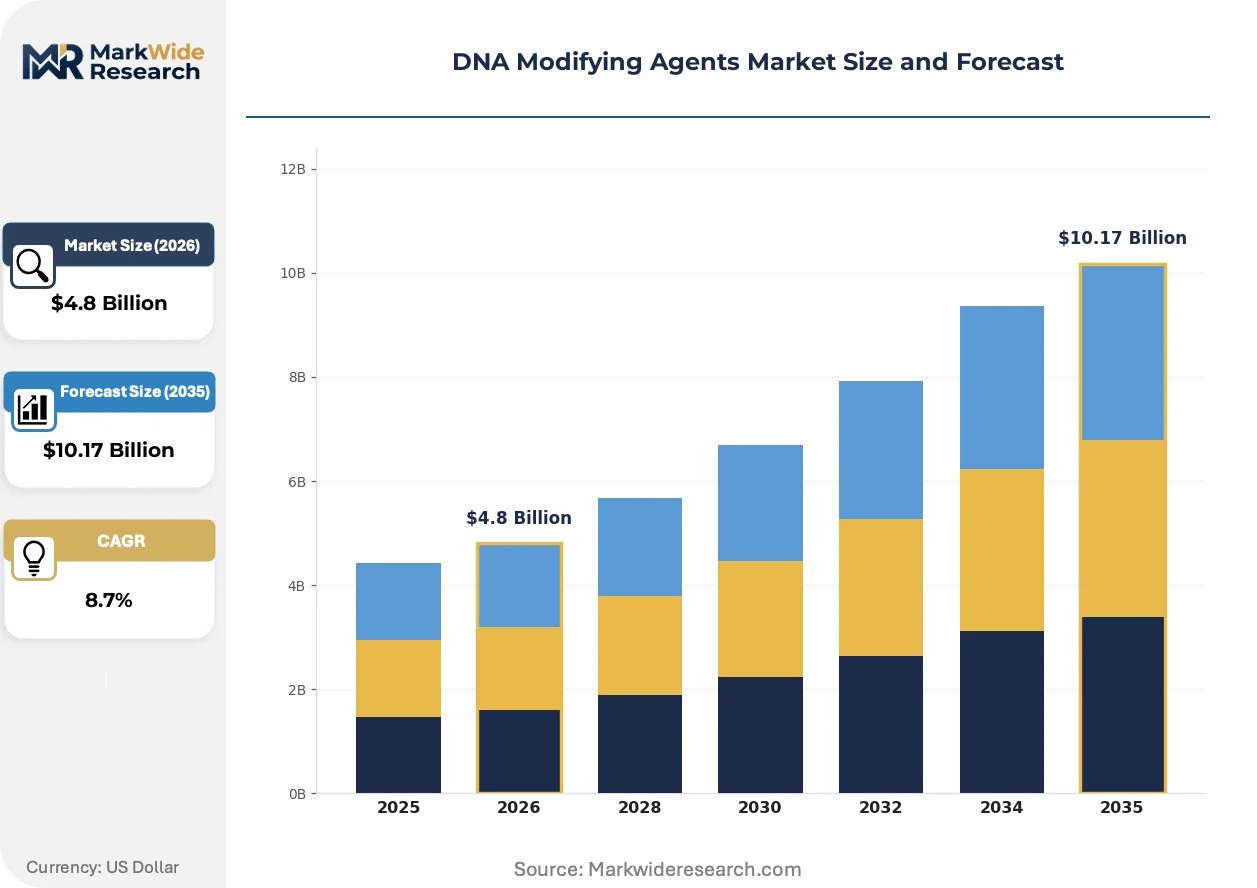
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, ZFN, TALEN, Antisense Oligonucleotides Technology: Gene Editing, Gene Silencing, Gene Therapy, Nucleic Acid Delivery Application: Oncology, Genetic Disorders, Infectious Diseases, Agricultural Biotechnology End User: Research Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotech Firms |
| Companies Covered | Thermo Fisher Scientific, Promega Corporation, Merck, Takara Bio, Bio-Rad Laboratories, New England Biolabs, NZYTech, Agilent Technologies, LGC Biosearch Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Modifying Agents Market Strategic Shifts
Engineered nuclease architectures and regulatory clarity around somatic editing are converging to compress development timelines while elevating quality standards for clinical-grade reagents.
Prime editing systems incorporating M-MLV reverse transcriptase fused to Cas9 nickase are displacing conventional HDR-dependent approaches in precision medicine pipelines. Large pharma gene therapy units adopt these platforms for inherited retinal disorders and sickle cell disease programs. The shift is compressing demand for donor template DNA while elevating requirements for pegRNA synthesis fidelity.
EMA's ATMP framework revision tightens potency assay requirements for gene editing medicinal products entering European markets. Manufacturers must demonstrate consistent editing efficiency across patient-derived cell lots. Clinical-stage developers are responding by investing in in-house analytical development rather than outsourcing to CROs.
Consolidated procurement through centralized biobanks and shared reagent repositories is reshaping purchasing patterns among academic consortia. The Broad Institute's reagent distribution model is being replicated by the Max Planck Society and RIKEN. Germany and Japan exhibit the fastest migration toward collective bargaining for high-volume CRISPR components.
DNA Modifying Agents Market Segmentation
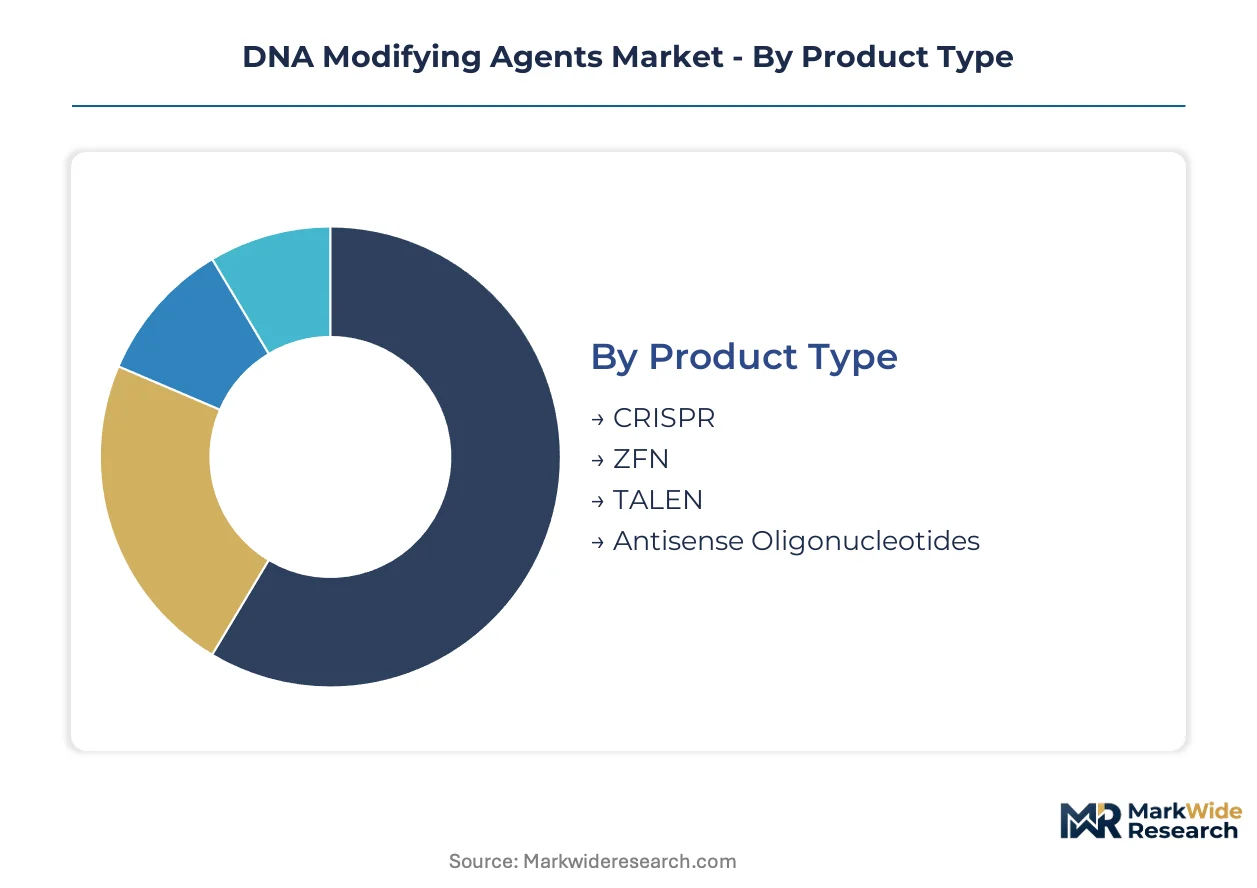
Segmentation in DNA modifying agents separates technology platforms by their regulatory maturity, manufacturing complexity, and therapeutic addressability. Distinct procurement patterns emerge between research-grade reagent buyers and clinical developers seeking GMP-certified supply chains.
Product Type:
CRISPR systems face accelerating substitution pressure from next-generation base editors and prime editing architectures that reduce double-strand break liabilities.
- CRISPR:RNA-programmable nucleases operate through Cas9 or Cas12a effectors with PAM-dependent cleavage specificity. Pharmaceutical procurement concentrates in Cambridge, Massachusetts and Basel, Switzerland, driven by allogeneic cell therapy manufacturing scale-up.
- Antisense Oligonucleotides:Chemically modified single-stranded DNA or RNA molecules modulate gene expression through RNase H recruitment or splice-site interference. Ionis Pharmaceuticals and Biogen anchor demand in neurodegenerative and rare disease portfolios.
- ZFN:Zinc finger protein-DNA binding domains fused to FokI nuclease domains enable targeted genome modification.
- TALEN:Transcription activator-like effector nucleases offer programmable specificity through repeat-variable di-residue arrays.
Antisense oligonucleotides retain volume leadership; CRISPR holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive viral vector manufacturing from synthetic chemistry approaches with lower facility barriers.
- Gene Editing:Programmable nucleases, base editors, and prime editors induce precise DNA sequence alterations. Clinical-stage developers in the Research Triangle and San Francisco Bay Area drive reagent procurement for sickle cell and inherited retinal disorder programs.
- Gene Therapy:Viral and non-viral vector systems deliver therapeutic transgenes or gene-modifying payloads. AAV manufacturing capacity constraints in the United States and Switzerland limit supply availability for late-stage trials.
- Gene Silencing:RNA interference and antisense mechanisms suppress target gene expression without permanent genomic alteration.
- Nucleic Acid Delivery:Lipid nanoparticle and polymer formulations enable intracellular transport of mRNA, siRNA, and gene editing components.
Gene editing commands premium pricing tiers; nucleic acid delivery is gaining share fastest through COVID-19 vaccine platform expansion.
Application:
Customer type fragmentation separates acute therapeutic intervention from trait development timelines spanning multiple growing seasons.
- Oncology:CAR-T cell engineering and tumor-infiltrating lymphocyte modification dominate therapeutic gene editing deployment. Memorial Sloan Kettering and MD Anderson anchor academic procurement volumes.
- Genetic Disorders:Sickle cell disease, beta-thalassemia, and Duchenne muscular dystrophy represent validated regulatory pathways with established clinical endpoints.
- Infectious Diseases:Prophylactic and curative approaches target HIV, hepatitis B, and emerging viral pathogens through host factor modification or direct viral genome cleavage.
- Agricultural Biotechnology:Gene silencing and editing enable trait development without transgenic classification in regulatory jurisdictions.
Oncology retains the largest absolute expenditure; agricultural biotechnology shows the steepest expansion trajectory.
End User:
Supply concentration among three GMP plasmid CDMOs in the United States and Switzerland shapes qualification timelines for clinical-grade procurement.
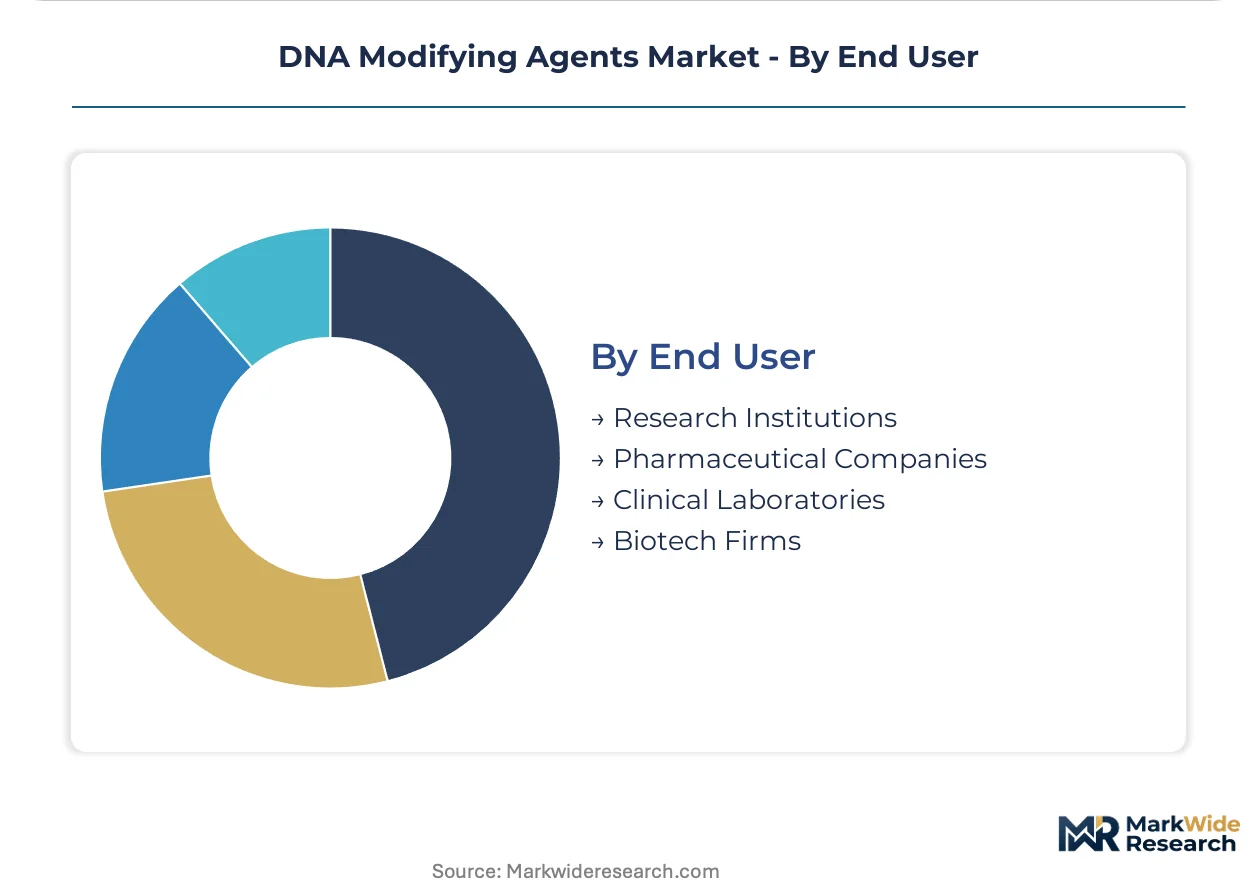
- Pharmaceutical Companies:Integrated gene therapy units at large pharma firms negotiate multi-year CRISPR reagent supply agreements with embedded quality systems. Vertex Pharmaceuticals and CRISPR Therapeutics exemplify captive manufacturing investments.
- Research Institutions:Academic laboratories and core facilities at Duke, UNC, and the Broad Institute concentrate annual procurement through collective bargaining arrangements.
- Biotech Firms:Venture-backed developers outsource analytical development and GMP manufacturing to specialized CDMOs.
- Clinical Laboratories:Diagnostic applications require ISO 13485 certification with 18-24 month supplier qualification cycles.
Pharmaceutical companies dominate value capture; biotech firms are expanding most quickly through platform company formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Switzerland and the United States, where GMP plasmid manufacturing scarcity elevates clinical-grade reagent premiums above research-tier equivalents. Germany and Japan extract intermediate value through specialized enzyme engineering competencies. China and India compete primarily on synthesis scale rather than regulatory certification depth.
United States
FDA gene therapy guidance and IRA price negotiation exemptions drive pharmaceutical procurement concentration. The Research Triangle—Duke, UNC, and emerging cell therapy startups—anchors reagent demand for sickle cell programs. Cambridge, Massachusetts and the San Francisco Bay Area cluster allogeneic CAR-T manufacturing investments.
Switzerland
Swissmedic ATMP oversight and GMP plasmid scarcity position the country as a clinical-grade supply gatekeeper. Basel concentrates gene editing procurement from large pharma captive units. Zurich and Geneva host specialized CDMOs serving European trial networks with ISO 13485-certified workflows.
Germany
EMA framework revisions and ISO 13485 diagnostic certification requirements shape supplier qualification timelines. The Max Planck Society replicates Broad Institute collective bargaining models for CRISPR component procurement. Munich and Heidelberg anchor academic core facility networks.
Japan
PMDA somatic therapy guidance and METI biotechnology investment programs accelerate base editor pipeline transitions. RIKEN institutes pioneer shared reagent repository structures. Osaka and Tokyo bioclusters concentrate antisense oligonucleotide demand for neurodegenerative portfolios.
China
NMPA gene therapy product standards and dual carbon goals reshape agricultural biotechnology applications. Yangtze River Delta manufacturing bases compete on phosphoramidite chemistry scale. Beijing-Tianjin-Hebei research institutes drive domestic CRISPR platform development.
DNA Modifying Agents Market Competitive Environment
Concentration sits with integrated life science conglomerates controlling end-to-end workflow instrumentation. Three structural tiers separate platform owners from reagent specialists and regional synthesis providers. Dominant competitive moves include captive manufacturing investments by large pharma gene therapy units and multi-year supply agreements embedding quality systems.
Among integrated platform providers, Thermo Fisher Scientific exemplifies workflow control spanning instrumentation and consumables. New England Biolabs occupies a position within the enzyme engineering specialist tier, while Promega Corporation represents luminescence-based validation technology differentiation. These three anchors illustrate how competitive positioning separates premium clinical-grade certification from research-tier commodity supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Promega Corporation |
| Merck |
| Takara Bio |
| Bio-Rad Laboratories |
| New England Biolabs |
| NZYTech |
| Agilent Technologies |
| LGC Biosearch Technologies |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification requirements gate both supplier qualification timelines and price differentiation between research-grade and clinical-grade reagent tiers, compressing margins for uncertified providers while elevating premiums for GMP-compliant manufacturers. Buyers face extended procurement cycles that amplify total cost of ownership beyond unit pricing alone.
Pricing Analysis
Configured-to-order pricing for clinical-grade plasmids and guide RNA synthesis commands 40-60% premiums over standard research-tier equivalents due to phosphoramidite chemistry purity requirements and HPLC purification steps. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified supply agreements from research-grade bulk contracts and spot-market enzyme purchases. Cost compression in research-grade CRISPR reagents is intensifying because platform standardization erodes proprietary formulation premiums. Academic core facilities and early-stage biotech firms exhibit highest price sensitivity, while pharmaceutical gene therapy units prioritize supply security over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate research-grade enzyme procurement, whereas clinical-stage developers maintain strategic stockpiles of GMP plasmids to mitigate single-source vulnerability. Manufacturing capacity concentrates in the United States, Switzerland, and Germany, with phosphoramidite chemistry feedstocks and specialized FokI nuclease domains drawing from concentrated chemical synthesis bases. Single-source vulnerability pervades clinical-grade plasmid DNA supply, where three CDMOs control qualified capacity. Distribution runs through direct-to-manufacturer contracts for pharmaceutical buyers and biobank-mediated collective purchasing for academic consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as base editing and prime editing architectures displace conventional CRISPR platforms, creating specialist niches for enzyme engineering and pegRNA synthesis providers. Demand-side shift toward allogeneic cell therapy manufacturing fragments procurement patterns between bulk supply contracts and precision reagent customization.
For Market Incumbents: Compound workflow integration advantages by embedding quality systems into multi-year pharmaceutical supply agreements, while expanding captive GMP manufacturing capacity in the Research Triangle to defend against emerging CDMO competition. Thermo Fisher Scientific's end-to-end instrumentation control and New England Biolabs' enzyme engineering depth illustrate defensible positioning against reagent commoditization. For New Entrants and Emerging Players: FDA streamlined IND pathway fast-tracks present entry points for antisense oligonucleotide specialists targeting neurodegenerative disease portfolios, where regulatory validation precedes CRISPR clinical maturity. Agricultural biotechnology applications in China and Japan offer the most penetrable geography-application intersection, with gene silencing trait development bypassing transgenic regulatory classification. Go-to-market execution should prioritize biobank partnerships for collective procurement access over direct academic sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across nucleic acid delivery platform development, as lipid nanoparticle formulation expertise becomes portable between mRNA vaccine and gene editing applications. Five-to-ten year viability favors acquisition targets possessing ISO 13485 certification infrastructure and pegRNA synthesis fidelity capabilities rather than undifferentiated CRISPR reagent catalogs. Prime editing pipeline advancement into sickle cell and inherited retinal disorder programs signals inflection timing for valuation recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Captive plasmid production at Vertex Pharmaceuticals reduces CDMO dependency for clinical trials. |
| Regulatory Approval Pathway | FDA streamlined IND guidance accelerates antisense oligonucleotide transitions from research to clinical phases. |
| Platform Integration | Thermo Fisher Scientific's workflow control spans instrumentation through consumables for gene editing laboratories. |
| Strategic Partnership | Collective bargaining arrangements at the Broad Institute and Max Planck Society concentrate academic procurement volumes. |
| Acquisition of Specialist Firm | Prime editing platform capabilities command premium valuations as M-MLV reverse transcriptase fusion architectures mature. |
Study Parameters
A spread of perspectives from gene therapy unit heads, regulatory affairs leads at EMA and FDA, academic core facility directors, and GMP manufacturing officers converged on the working assumptions shaping this analysis. Primary interview insights combined with secondary validation from FDA gene therapy guidance documents, EMA ATMP framework revisions, ClinicalTrials.gov pipeline tracking, and ISO 13485 certification databases. Bottom-up reagent procurement volume estimates and top-down pharmaceutical R&D expenditure analysis triangulated on market sizing.
Segmentation dimensions modeled span technology platform, application area, end-user category, and regional regulatory cluster across the analysis window. CAGRs derived from weighted average of historical procurement growth, pipeline transition rates, and regulatory approval velocity assumptions. Forecast inputs incorporated GMP plasmid manufacturing capacity constraints, base editing clinical trial progression, and agricultural biotechnology regulatory pathway evolution.
Decision-makers should treat outputs as directional under assumptions of continued FDA and EMA somatic therapy guidance stability; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding CRISPR platform substitution rates and CDMO capacity expansion timelines. Revision becomes warranted when prime editing clinical efficacy data crosses regulatory submission thresholds or GMP plasmid manufacturing capacity expansion accelerates beyond current three-provider concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Knock Out Mouse Model Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
France Gene Editing Market