
 Blau Syndrome Market | 2026-2036
Blau Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Blau Syndrome Market Analysis
Specialty-grade biologics targeting the NOD2 mutation pathway is rotating toward the center of competitive strategy in Blau Syndrome. Novartis AG anchors its position through deep immunology R&D infrastructure. Pfizer leverages established rare-disease commercialization networks across North America and Europe. AbbVie Inc differentiates through precision immunology platforms that address granulomatous inflammation mechanisms.
Blau Syndrome constitutes a rare autosomal dominant autoinflammatory disorder driven by mutations in the NOD2 gene, clinically presenting with triad manifestations of granulomatous dermatitis, symmetric polyarthritis, and recurrent uveitis, with systemic inflammation requiring targeted immunomodulation. The condition demands therapies that interrupt aberrant innate immune signaling cascades. Biologics command the dominant revenue position within product type segmentation due to established efficacy in cytokine blockade and premium pricing structures. Gene therapy represents the fastest-expanding category as vector delivery technologies mature for monogenic autoinflammatory targets. Rheumatology maintains the largest therapy area footprint, though pediatrics is gaining specialist attention as early-intervention protocols develop.
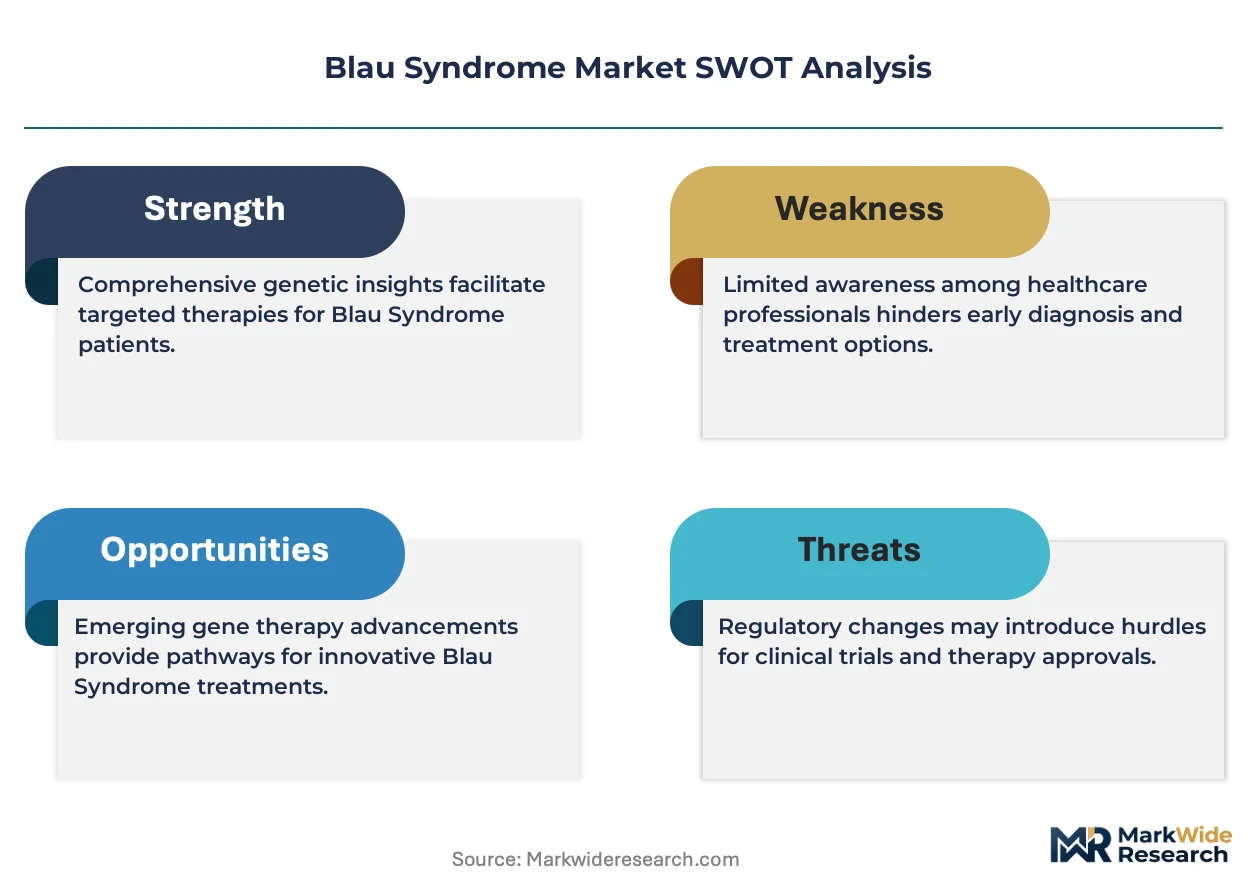
The FDA orphan drug program shapes development economics through tax credits and market exclusivity incentives for Blau Syndrome indications. EMA's PRIME designation and EMA parallel scientific advice accelerate European access timelines for ultra-rare immunology therapies. Stakeholders must monitor regulatory precedents for gene therapy durability requirements and corresponding reimbursement frameworks as novel modalities advance through clinical pipelines.
Market Dynamics
The FDA's orphan drug designation framework is compressing development timelines for ultra-rare autoinflammatory indications, while pediatric rheumatology networks in Germany, France, and Japan expand biologic adoption protocols. This regulatory acceleration collides with vector delivery maturation in gene therapy, creating a dual-track competitive environment.
Growth Catalysts
- EMA PRIME Designation:Parallel scientific advice mechanisms in Europe compress European access timelines for immunology therapies targeting NOD2 mutation pathways.
- Biologics Efficacy:Cytokine blockade mechanisms demonstrate established clinical outcomes in granulomatous dermatitis and uveitis management.
- Pediatric Early Intervention:Specialist referral networks in the United States concentrate prescribing volume through accelerated approval pathways.
Market Restraints
- Vector Manufacturing Bottlenecks:Gene therapy production capacity constraints limit scalable supply of AAV-based delivery systems for monogenic targets.
- Reimbursement Uncertainty:Payers in France and Germany impose durability requirements on novel modalities that exceed current clinical follow-up periods.
- Diagnostic Fragmentation:NOD2 mutation testing access varies across pediatric rheumatology clinics, delaying treatment initiation.
Strategic Opportunities
- Gene Therapy Convergence:CRISPR editing platforms combined with lipid nanoparticle delivery open durable correction pathways for autosomal dominant disorders.
- Japan Market Entry:PMDA's Sakigake designation offers priority review for pediatric autoinflammatory therapies with limited treatment options.
- Direct-to-Clinic Distribution:Specialty pharmacy channels bypass traditional hospital procurement for ultra-rare disease biologics.
Industry Challenges
- Pediatric Trial Design:Small patient populations complicate randomized controlled study enrollment for rare disease indications.
- Gene Therapy Integration:Health systems lack infrastructure for one-time curative administration and long-term monitoring protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blau Syndrome Market |
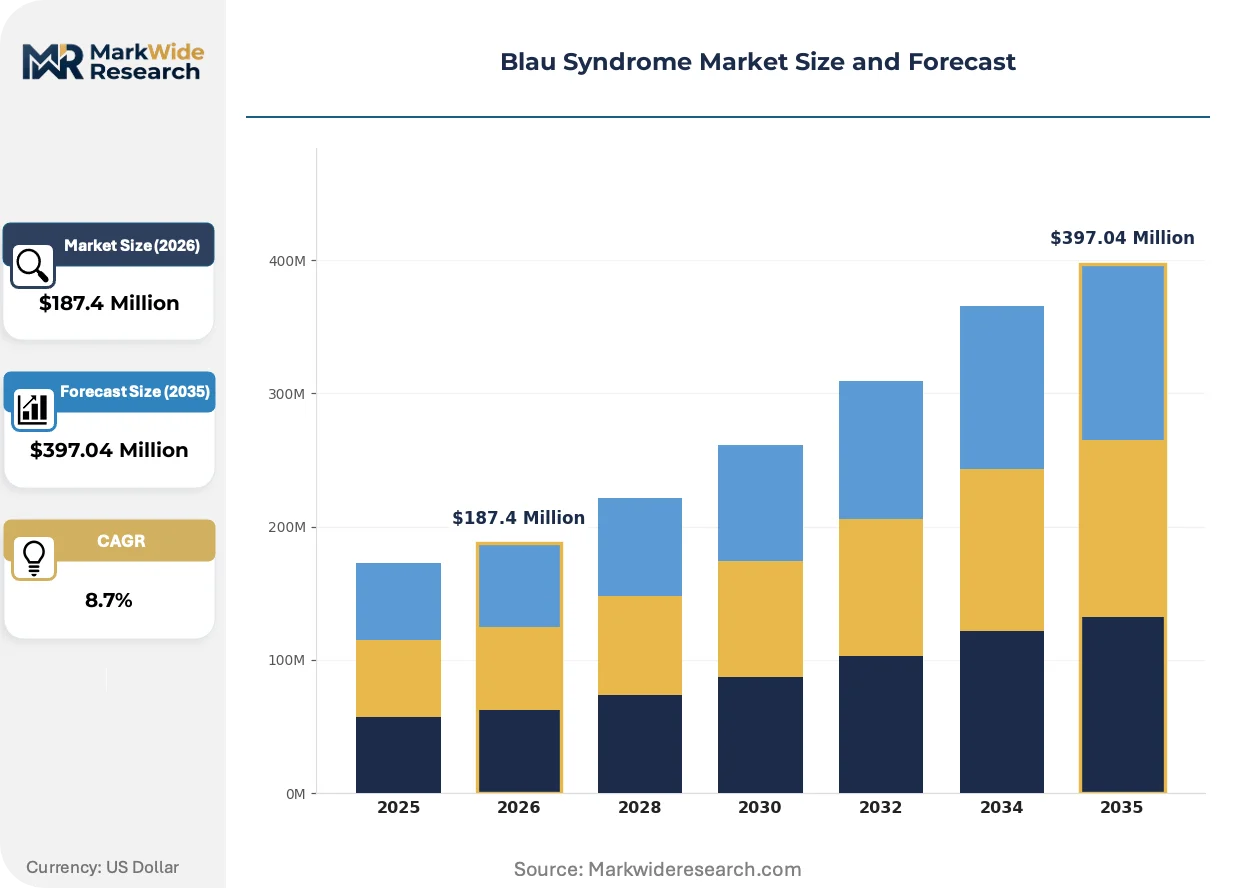
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Gene Therapy, Biosimilars Therapy Area: Rheumatology, Immunology, Dermatology, Pediatrics End User: Hospitals, Clinics, Research Institutions, Homecare Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Pfizer, Novartis AG, AbbVie Inc, Amgen Inc, Teva Pharmaceuticals, Johnson & Johnson, Roche Holding AG, Sanofi S.A., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blau Syndrome Market Emerging Trajectories
Vector delivery technologies are bifurcating competitive strategy between incremental biologic optimization and curative gene correction platforms. This technological divergence demands parallel capability investments from developers.
AAV-based gene therapy is bifurcating the treatment paradigm for monogenic autoinflammatory disorders. Pediatric academic medical centers in the United States and Germany are establishing dedicated gene therapy infusion units. The technology is bifurcating patient selection criteria toward earlier intervention windows before irreversible organ damage.
EMA's PRIME designation and FDA's rare pediatric disease priority review voucher program are compressing regulatory timelines for first-in-class immunomodulators. Developers now front-load natural history studies to support accelerated approval pathways. Pediatric rheumatology networks in France and Japan are adapting clinical trial infrastructure to accommodate these compressed schedules.
Specialist procurement is consolidating through integrated delivery networks that negotiate outcomes-based contracts for high-cost biologics. Hospital systems in Germany and the United States are unbundling pharmacy benefit management from general procurement. This shift is most visible in academic medical centers with established rare disease centers of excellence.
Blau Syndrome Market Segmentation
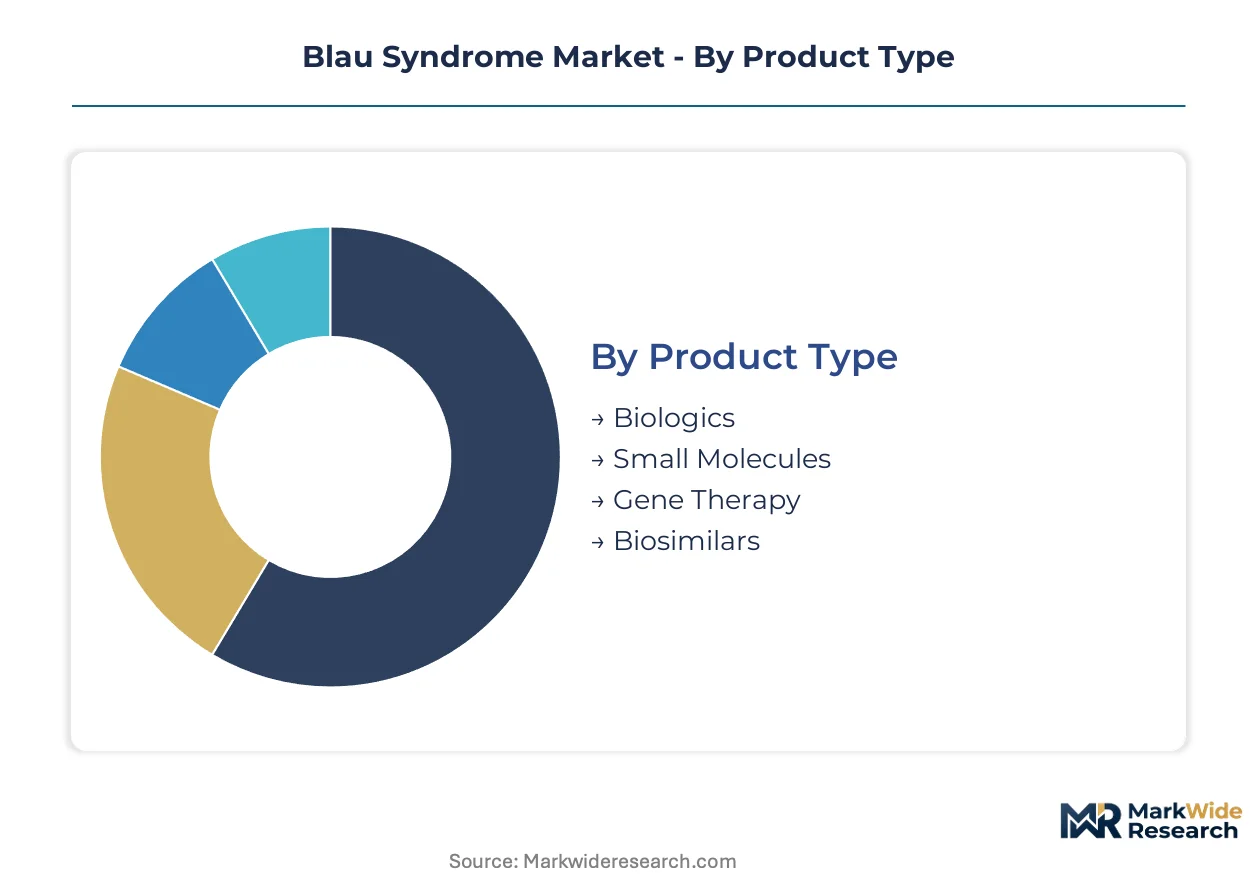
Blau Syndrome treatment pathways fragment across therapeutic modalities and care settings, with each segment commanding distinct commercial infrastructure. Understanding these divisions reveals where pricing power concentrates and where access bottlenecks emerge for ultra-rare disease management.
Product Type:
Biologics dominate prescribing in the United States and Germany through established immunology infrastructure, while gene therapy development concentrates in academic medical centers with vector manufacturing partnerships.
- Biologics:Monoclonal antibodies and fusion proteins interrupt cytokine signaling cascades downstream of NOD2 mutations. Demand clusters in pediatric rheumatology clinics across the United States and France, where specialist networks manage granulomatous inflammation through IL-1 and TNF blockade protocols.
- Gene Therapy:AAV-based delivery systems target durable correction of autosomal dominant NOD2 mutations. Development pipelines concentrate in Boston and Basel research clusters, with first-in-human protocols requiring dedicated gene therapy infusion units and decade-long follow-up commitments.
- Small Molecules:Oral immunomodulators offer outpatient administration advantages for maintenance therapy.
- Biosimilars:Follow-on biologics expand access in European markets with reference product patent expirations.
Biologics holds the largest share; momentum sits with gene therapy as durability data mature.
Therapy Area:
Cost tier stratification separates acute intervention from chronic maintenance, with highest reimbursement attaching to organ-threatening complications.
- Rheumatology:Symmetric polyarthritis management drives the majority of treatment initiations, with joint-preserving therapy goals shaping biologic selection. Academic medical centers in Germany and Japan operate dedicated pediatric rheumatology units with embedded clinical trial access.
- Immunology:Systemic inflammation control requires innate immune pathway modulation beyond single-organ manifestations. Precision dosing protocols in France and the United States tailor cytokine blockade intensity to inflammatory biomarker profiles.
- Dermatology:Granulomatous skin lesions respond to topical and systemic immunosuppression combinations.
- Pediatrics:Early intervention windows before skeletal maturation create distinct efficacy endpoints and toxicity monitoring requirements.
Rheumatology commands the revenue base; pediatrics is climbing the fastest as newborn screening expands NOD2 mutation detection.
End User:
Volume concentration varies by therapy complexity, with infusion-dependent biologics requiring hospital infrastructure and oral agents shifting toward ambulatory settings.
- Hospitals:Inpatient and infusion center administration handles biologic loading doses and acute uveitis flares. Major children's hospitals in Chicago, Paris, and Tokyo anchor regional referral networks for complex multi-organ disease.
- Clinics:Outpatient rheumatology and ophthalmology practices manage maintenance therapy and monitoring. Community specialist access in the United States varies by insurance network density, creating geographic treatment gaps.
- Research Institutions:Academic medical centers host natural history studies and gene therapy trials.
- Homecare:Subcutaneous biologic administration shifts selected therapies to domestic settings with nursing support.
Hospitals retain the procedural revenue; homecare is gaining share fastest as subcutaneous formulations expand.
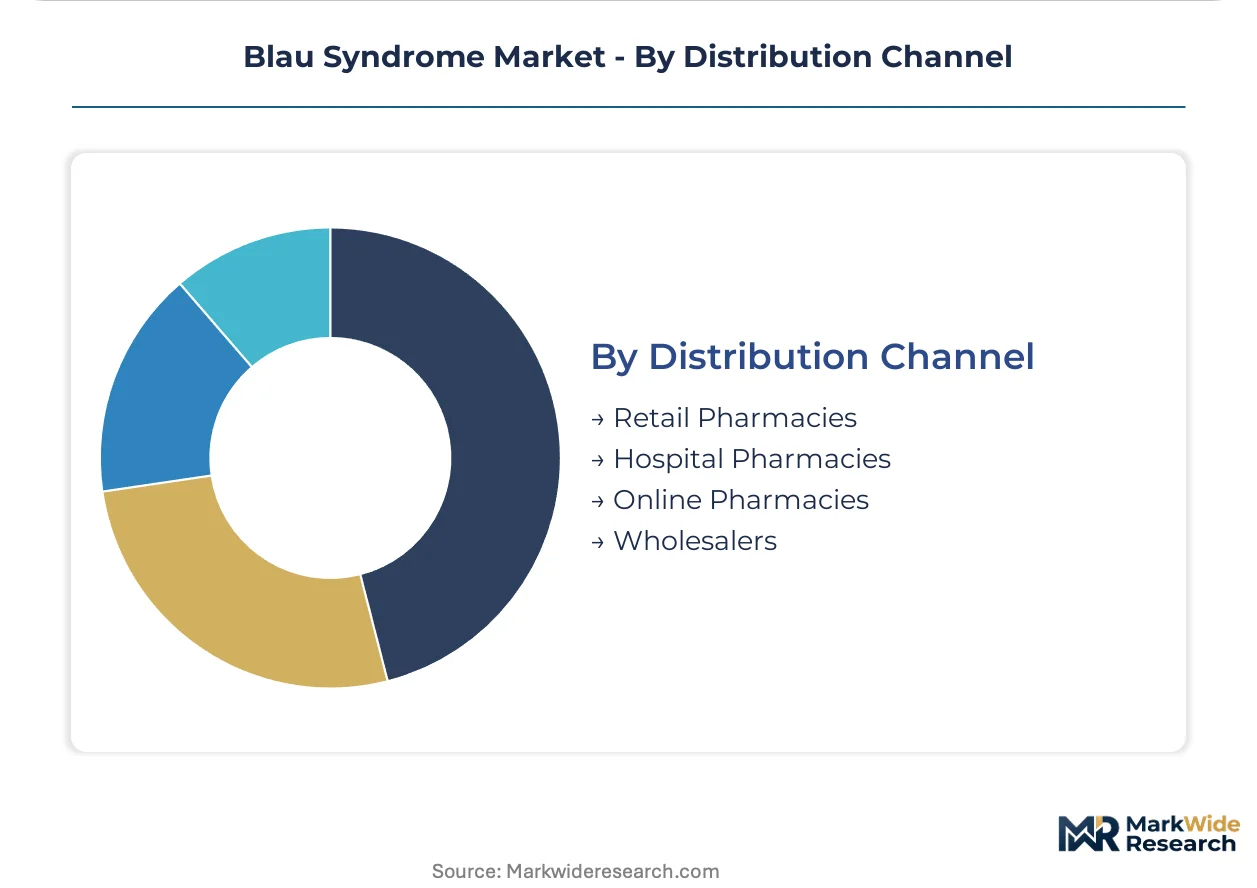
Distribution Channel:
Supply concentration in specialty pharmacy channels reflects cold-chain requirements and patient registry obligations for rare disease tracking.
- Hospital Pharmacies:Captures biologic dispensing tied to infusion center visits and inpatient admissions. Integrated delivery networks in Germany and the United States negotiate outcomes-based contracts directly with manufacturers.
- Retail Pharmacies:Limited role given restricted distribution requirements and specialist prescribing concentration.
- Online Pharmacies:Emerging channel for oral maintenance therapies with established safety profiles.
- Wholesalers:Three national distributors in the United States manage logistics for hospital and specialty pharmacy customers.
Hospital pharmacies hold the dispensing volume; specialty channel direct distribution is expanding fastest as manufacturers unbundle from traditional wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist referral networks and gene therapy manufacturing clusters concentrate prescribing volume and development activity across five national markets. Pediatric rheumatology infrastructure and regulatory acceleration mechanisms determine competitive positioning in each geography.
United States
FDA orphan drug tax credits and priority review vouchers compress development timelines for NOD2-targeted therapies. Major children's hospitals in Chicago and Boston anchor regional referral networks for complex multi-organ disease management. Academic medical centers in these cities host natural history studies and first-in-human gene therapy protocols.
Germany
EMA PRIME designation and parallel scientific advice accelerate European access timelines for ultra-rare immunology therapies. Pediatric rheumatology clinics in Munich and Heidelberg expand biologic adoption protocols through integrated care networks. Hospital pharmacies negotiate outcomes-based contracts directly with manufacturers for high-cost biologics.
France
ANSM early access programs and hospital exemption pathways enable pre-approval use of novel autoinflammatory therapies. Payers impose durability requirements on gene therapy that exceed current clinical follow-up periods. Parisian academic medical centers adapt clinical trial infrastructure to accommodate compressed regulatory schedules.
Japan
PMDA Sakigake designation offers priority review for pediatric autoinflammatory therapies with limited treatment options. Pediatric rheumatology units in Tokyo and Osaka establish dedicated gene therapy infusion capabilities. Subcutaneous biologic formulations expand homecare administration with nursing support networks.
United Kingdom
NHS England specialized commissioning frameworks concentrate ultra-rare disease treatment in designated centers of excellence. MHRA innovation passports accelerate regulatory timelines for promising therapies. London and Cambridge research clusters drive vector delivery technology development for monogenic targets.
Blau Syndrome Market Vendor Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing rare-disease commercialization infrastructure and immunology R&D depth. The competitive structure tiers between global biopharma leaders with established pediatric networks and emerging gene therapy specialists building vector manufacturing partnerships. Three archetypes dominate: integrated immunology platforms, rare disease commercialization specialists, and precision gene correction developers. M&A activity targets vector manufacturing capabilities, while strategic partnerships concentrate on pediatric trial network access.
Within the integrated immunology tier, Novartis AG and Pfizer exemplify archetype positioning through deep therapeutic area infrastructure. AbbVie Inc occupies a distinct position emphasizing precision immunology platforms. These three anchors represent the dominant competitive positioning visible in development pipelines and commercialization networks for NOD2 pathway modulation.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| AbbVie Inc |
| Amgen Inc |
| Teva Pharmaceuticals |
| Johnson & Johnson |
| Roche Holding AG |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Vector manufacturing scale economies in Basel and Boston gene therapy clusters concentrate production capacity among three contract manufacturers, compressing unit costs for AAV-based delivery systems while establishing price floors that reflect decade-long follow-up commitments and dedicated infusion infrastructure requirements.
Pricing Analysis
FDA orphan drug tax credits and market exclusivity incentives dictate the pricing tier structure for Blau Syndrome therapies. Three-tier pricing separates gene therapy curative interventions from maintenance biologics and acute rescue protocols. Price differentiation rests on durability guarantees and pediatric indication breadth. Cost compression in the biologics maintenance tier is intensifying as biosimilar entry nears for reference anti-TNF products. Pediatric rheumatology clinics in Germany exhibit highest price sensitivity due to hospital budget caps, while United States academic medical centers demonstrate lowest sensitivity through outcomes-based contracting mechanisms.
Supply Chain Analysis
Just-in-time manufacturing dominates biologic production, though gene therapy developers maintain strategic stockpiles of GMP-grade plasmids and viral seed banks to mitigate batch failure risks. Supply concentrates in Switzerland, the United States, and Germany for vector manufacturing and fill-finish operations. Raw material dependencies include HEK293 cell lines, helper plasmids, and lipid nanoparticle formulations. Single-source vulnerability in AAV capsid supplier networks creates concentration risk for first-in-human protocols. Distribution runs through specialty pharmacy channels with cold-chain custody requirements and patient registry integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platform economics are bifurcating competitive returns between one-time curative pricing and recurring biologic maintenance models, with interoperability between pediatric rheumatology networks and gene therapy infusion centers determining patient access velocity.
For Market Incumbents: Fortify immunology R&D infrastructure through captive vector manufacturing partnerships that reduce dependency on external CDMO capacity. Deepen pediatric clinical trial network penetration in Tokyo and Munich to preempt emerging gene therapy specialists from securing first-mover gene therapy trial sites. Lock in exclusive formulary positioning with integrated delivery networks before durability data from competing curative platforms mature. For New Entrants and Emerging Players: FDA rare pediatric disease priority review voucher fast-tracks offer compressed regulatory timelines that offset capital disadvantages against established biopharma infrastructure. Target the Japan market through PMDA Sakigake designation pathways where pediatric autoinflammatory expertise concentrates in Tokyo academic medical centers. Pursue direct-to-clinic distribution partnerships that bypass traditional hospital procurement committees for subcutaneous biologic formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated immunology platforms with established pediatric rheumatology commercial networks. Long-term viability favors developers possessing both biologic maintenance portfolios and gene therapy optionality across the NOD2 mutation pathway. Acquisition targets should demonstrate vector manufacturing partnerships or in-house GMP capabilities. Watch for durability readouts from first-in-human gene therapy protocols as the inflection signal for portfolio reallocation toward curative modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | CDMO partnerships in Basel and Boston anchor vector supply security for NOD2-targeted programs. |
| Pediatric Trial Network Expansion | Academic medical centers in Chicago and Heidelberg accelerate enrollment for rare disease protocols. |
| Regulatory Approval Pathway Optimization | FDA orphan drug designation compresses timelines through tax credit and priority review mechanisms. |
| Outcomes-Based Contracting | German hospital pharmacies negotiate durability-guaranteed pricing for gene therapy interventions. |
| Direct-to-Clinic Distribution | Specialty pharmacy channels bypass wholesale markups for ultra-rare disease biologics in the United States. |
Methodological Framework
Operator-level perspectives from pediatric rheumatologists, gene therapy manufacturing executives, hospital pharmacy procurement directors, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA orphan drug designations, EMA PRIME submissions, ClinicalTrials.gov protocols, and hospital formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation cross-validated segment estimates.
Sensitivity analysis tested forecast robustness across vector manufacturing yield assumptions and regulatory approval probability scenarios. Segmentation modeling incorporated product type, therapy area, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from epidemiological prevalence projections, treatment penetration curves, and pricing evolution assumptions. Gene therapy durability benchmarks and biologic biosimilar entry timelines served as key forecast inputs.
Decision-makers should treat outputs as directional under stable NOD2 mutation detection rates and sustained orphan drug incentive frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding regulatory acceleration mechanisms and reimbursement durability requirements. Vector manufacturing bottlenecks, pediatric trial enrollment delays, or gene therapy safety signals represent specific revision triggers. Revision becomes warranted when gene therapy durability data from ongoing protocols crosses prespecified efficacy thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Cell and Tissue Preservation Market