
 Vanishing Bone Disease Market | 2026-2036
Vanishing Bone Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Vanishing Bone Disease Market Outlook
Project finance for rare disease infrastructure is tilting competitive dynamics toward institutions with dedicated orthopedic research funding. Novartis AG leverages its established biologics manufacturing footprint to sustain supply continuity for enzyme replacement therapies. Amgen Inc. anchors its position through deep R&D investment in bone metabolism pathways. Pfizer Inc. competes via broad distribution reach across academic medical centers.
Vanishing bone disease, or Gorham-Stout disease, constitutes a rare lymphovascular disorder characterized by progressive osteolysis and bone resorption mediated by abnormal vascular proliferation, with diagnosis relying on radiographic evidence of intramedullary and cortical bone loss without consistent inflammatory markers. The condition primarily serves orthopedic and rheumatology specialists seeking to halt disease progression and stabilize skeletal integrity. Biologics command the strongest margin pools within product type segments due to orphan pricing authority and limited therapeutic substitutes. Injectable delivery modes dominate clinical practice for biologic administration, while specialty clinics represent the fastest-growing end user channel as centers of excellence consolidate complex case management.
FDA orphan drug incentives shape development economics by granting market exclusivity and tax credits for qualifying therapies, while EMA's parallel designation framework accelerates European access pathways. The EU's MDR requirements for implantable devices add compliance costs for surgical intervention segments. Stakeholders must monitor how payer policy on rare disease coverage evolves alongside clinical trial readouts for novel anti-resorptive mechanisms.
Market Dynamics
The FDA's Orphan Drug Act tax credits and market exclusivity provisions are restructuring development economics, pulling venture capital toward biologics targeting Gorham-Stout disease while academic medical centers consolidate complex case volumes into specialty clinic networks.
Growth Catalysts
- EMA parallel designation framework:The European Medicines Agency's streamlined orphan drug pathway accelerates European patient access, reducing regulatory lag between US and EU commercialization timelines for enzyme replacement therapies.
- Specialty clinic consolidation:Academic medical centers with dedicated orthopedic research programs are centralizing vanishing bone disease case management, creating referral networks that concentrate demand and justify premium biologic pricing.
- Anti-resorptive mechanism R&D:Deep investment in bone metabolism pathway research is yielding novel therapeutic targets that interrupt lymphovascular-mediated osteolysis, expanding the addressable patient population beyond palliative care.
Market Restraints
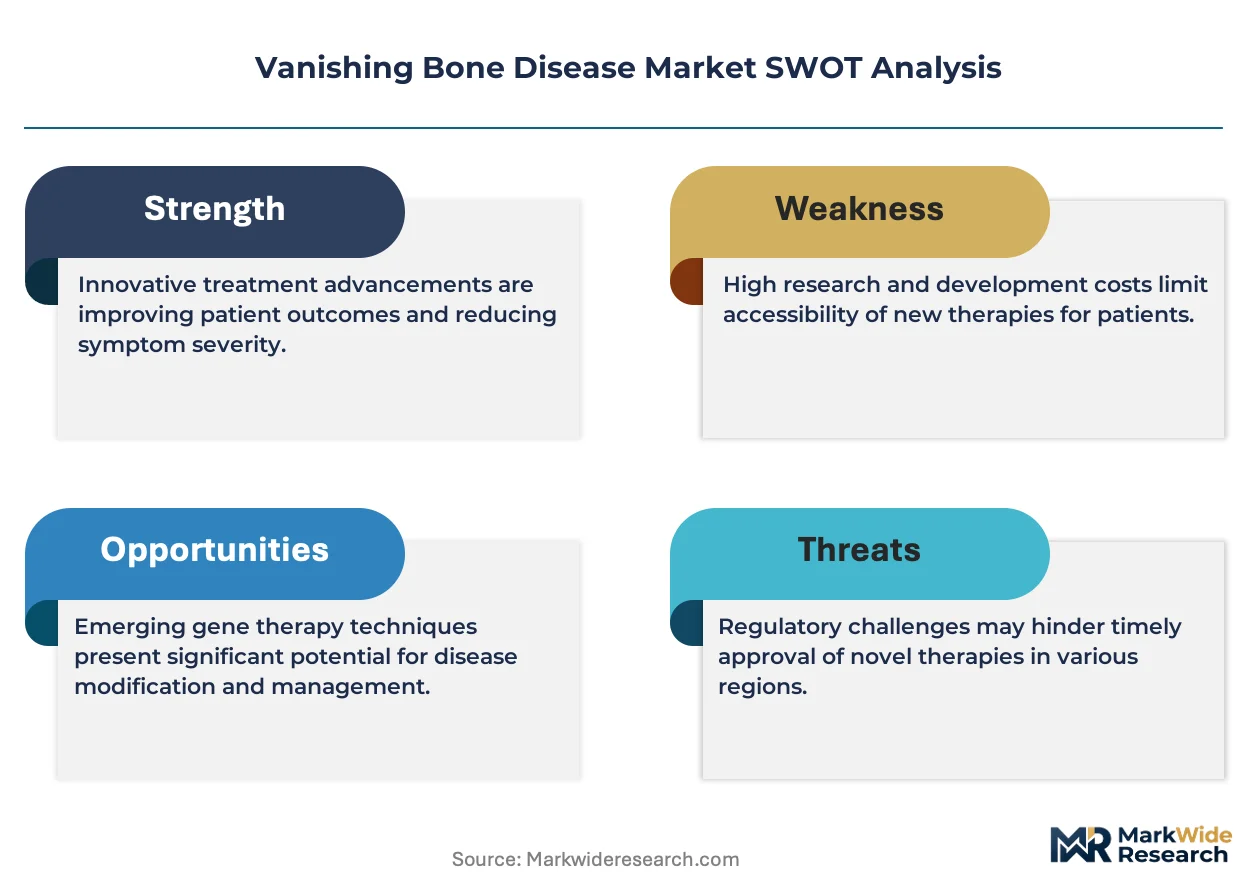
- Biologics manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Massachusetts control critical capacity for orphan biologics, creating single-source vulnerability for enzyme replacement supply continuity.
- Diagnostic radiography limitations:Intramedullary bone loss detection requires advanced imaging protocols unavailable in community hospital settings, delaying diagnosis and compressing the treatable window.
- Reimbursement fragmentation:Payer policy on rare disease coverage varies across US state Medicaid programs and European national health systems, creating access inequities that limit market penetration.
Strategic Opportunities
- Underpenetrated Japanese market:Japan's PMDA orphan drug designation system remains underutilized for lymphovascular skeletal disorders, presenting first-mover advantage for sponsors establishing local clinical trial infrastructure.
- Injectable-to-implantable convergence:Combination product development merging biologic reservoirs with orthopedic implants promises sustained local drug delivery, reducing injection burden for progressive osteolysis patients.
- EU MDR compliance arbitrage:The Medical Device Regulation's stringent implantable device requirements create competitive moats for manufacturers with established quality management systems, disadvantaging new surgical intervention entrants.
Industry Challenges
- Specialized orthopedic radiologist shortage:Interpretation of Gorham-Stout radiographic patterns requires fellowship-trained musculoskeletal radiologists concentrated at tertiary centers, creating diagnostic bottlenecks.
- Clinical trial recruitment friction:Ultra-rare disease prevalence necessitates multi-site international protocols, complicating regulatory harmonization across FDA, EMA, and PMDA jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanishing Bone Disease Market |
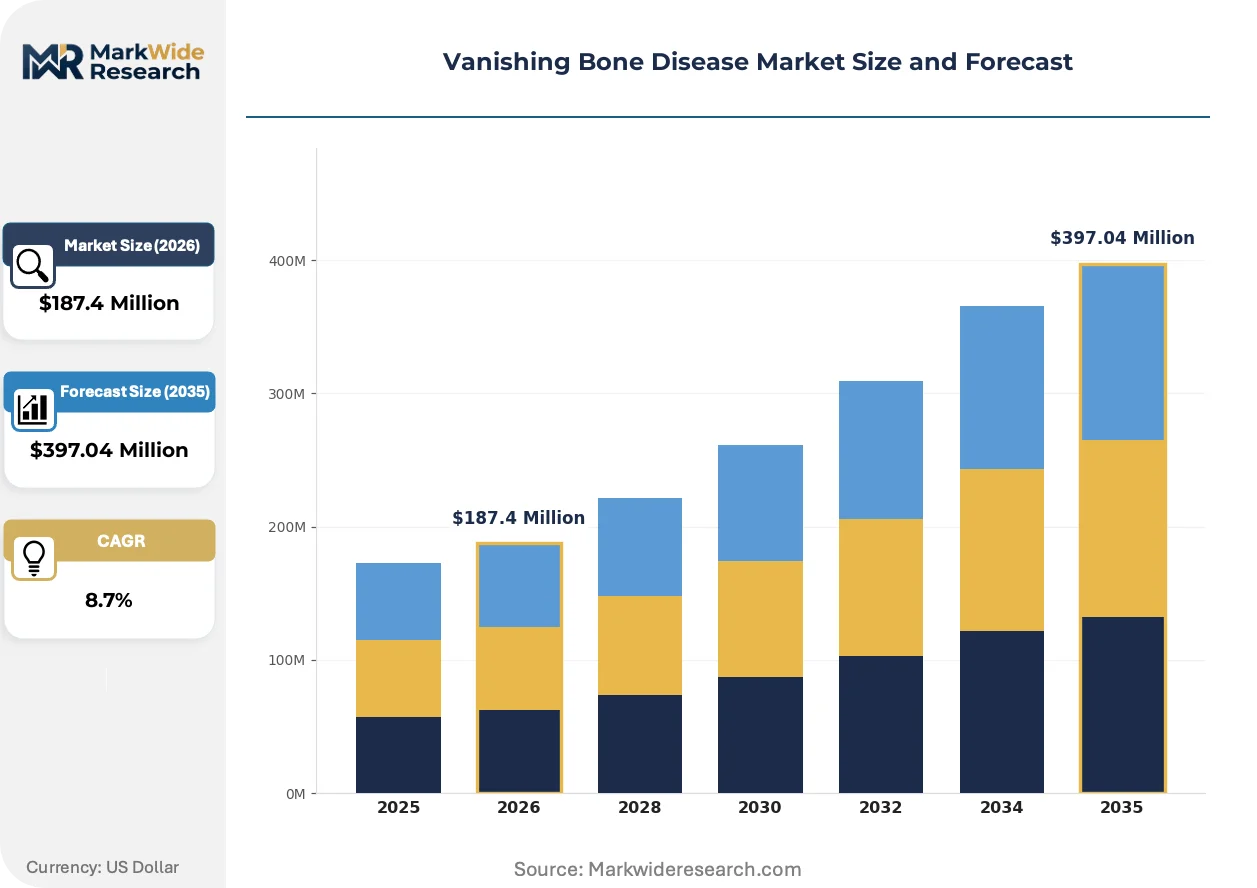
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Medical Devices, Nutraceuticals Delivery Mode: Injectable, Oral, Topical, Surgical End User: Hospitals, Specialty Clinics, Home Care, Rehabilitation Centers Therapy Area: Orthopedics, Rheumatology, Pain Management, Endocrinology |
| Companies Covered | Novartis AG, Amgen Inc., Pfizer Inc., Merck & Co., Inc., Sanofi S.A., Roche Holding AG, Johnson & Johnson, Medtronic plc, Elekta AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanishing Bone Disease Market Strategic Shifts
Research pipelines are pivoting from symptom management toward disease-modifying mechanisms, with molecular imaging and targeted biologics converging to enable earlier intervention and personalized dosing protocols.
Positron emission tomography tracers specific to lymphovascular proliferation are collapsing the diagnostic latency between symptom onset and definitive Gorham-Stout identification. Orthopedic oncology departments at Mayo Clinic and Memorial Sloan Kettering are adopting these imaging agents ahead of community hospitals. This compression of diagnostic timelines is enabling pre-emptive biologic initiation before catastrophic bone loss.
The EU's Medical Device Regulation implementation is forcing surgical intervention manufacturers to revalidate implantable hardware for osteolysis stabilization under enhanced clinical evidence requirements. European notified bodies are prioritizing pediatric orthopedic device submissions, creating queue delays for adult vanishing bone disease applications. Biologic sponsors are responding by decoupling drug-device combination strategies to avoid MDR compliance scope.
Academic medical centers are unbundling after-surgical monitoring from implant provision, shifting toward separate reimbursement for longitudinal bone density surveillance. Specialty clinics in Boston and Philadelphia are piloting subscription-based care coordination models that cover imaging, biologic administration, and orthopedic consultation under single bundled payments. This restructuring is most advanced in US markets with concentrated commercial payer negotiation leverage.
Vanishing Bone Disease Market Segmentation
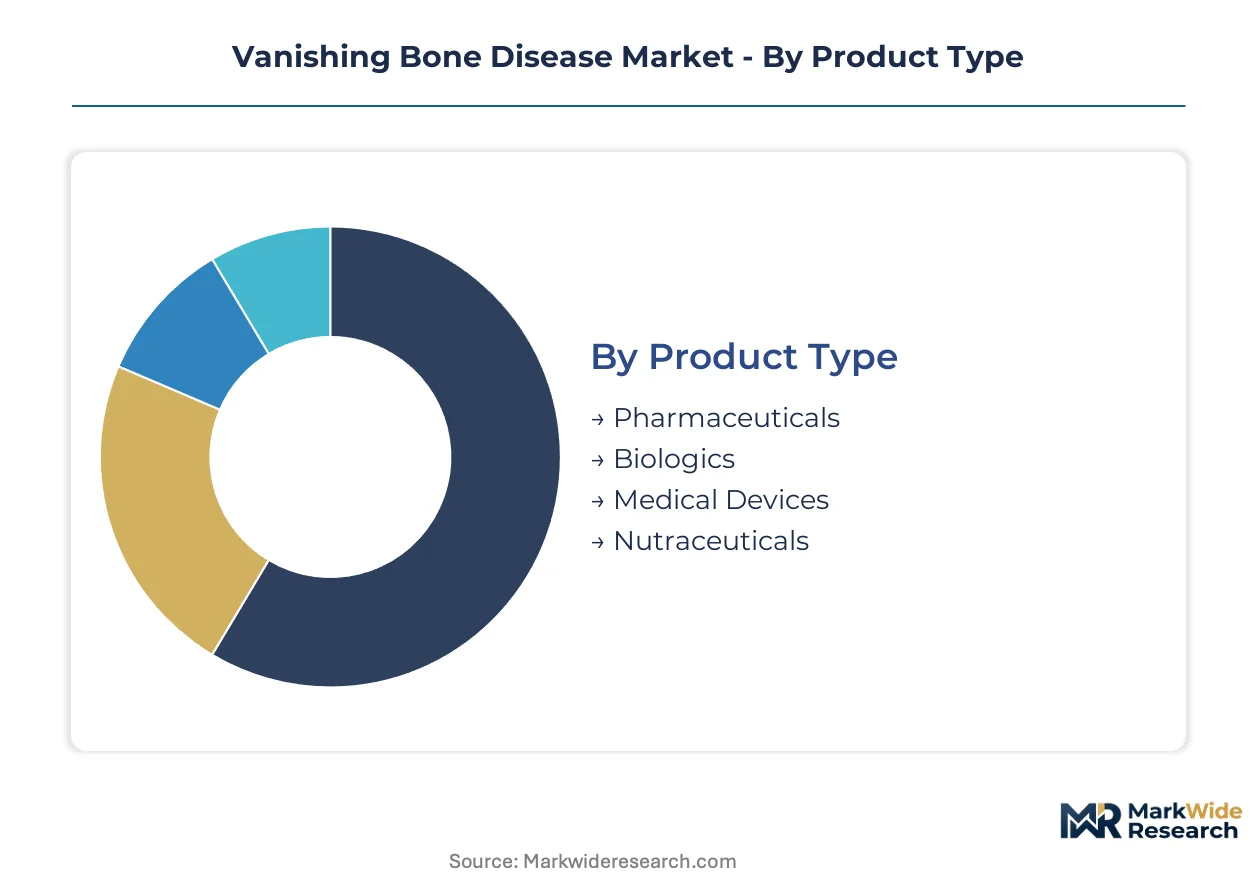
Vanishing bone disease treatment pathways fragment across four intersecting dimensions that determine reimbursement codes, procurement cycles, and clinical adoption curves. Understanding segment velocity reveals where orphan drug economics concentrate versus where commoditization pressures build.
Product Type:
Inventory turnover varies dramatically across this category, with biologics cycling through cold-chain logistics on weekly rhythms while medical devices sit in consignment stock for months.
- Biologics:Enzyme replacement therapies and monoclonal antibodies targeting lymphovascular proliferation command premium orphan pricing with limited manufacturing sources. Demand clusters at Mayo Clinic, Memorial Sloan Kettering, and other academic medical centers with dedicated orthopedic research programs due to FDA Orphan Drug Act exclusivity provisions.
- Pharmaceuticals:Small-molecule anti-resorptives and adjuvant therapies provide palliative management with broader formulary access but narrower margins. Prescription volume concentrates in US markets with concentrated commercial payer leverage and state Medicaid rare disease carve-outs.
- Medical Devices:Orthopedic implants for osteolysis stabilization including plates, screws, and custom prosthetics.
- Nutraceuticals:Calcium and vitamin D supplementation protocols supporting bone density maintenance.
Pharmaceuticals anchors the volume base while biologics gains share at the steepest rate.
Delivery Mode:
Cost tier separation is pronounced here, with surgical interventions carrying facility fees that dwarf outpatient administration economics.
- Injectable:Subcutaneous and intravenous biologic administration dominates clinical practice for Gorham-Stout disease, requiring specialized infusion centers with cold-chain handling capabilities. Specialty clinics in Boston and Philadelphia are piloting bundled payment models covering injection scheduling, monitoring, and orthopedic consultation.
- Surgical:Open reduction and internal fixation procedures for pathologic fractures carry the highest per-procedure reimbursement but depend on fellowship-trained orthopedic oncologists concentrated at tertiary centers.
- Oral:Small-molecule bisphosphonates and calcitonin formulations for maintenance therapy.
- Topical:Transdermal delivery systems for localized pain management adjacent to osteolytic lesions.
Injectable delivery anchors the volume base while surgical gains share at the steepest rate.
End User:
Customer type determines purchasing authority and formulary control, with hospitals maintaining centralized procurement versus specialty clinics with physician-driven preference.
- Specialty Clinics:Academic medical centers with dedicated orthopedic research programs are consolidating complex case management into centers of excellence, creating referral networks that justify premium biologic pricing. These facilities in the United States are expanding service lines fastest due to concentration of payer negotiation leverage.
- Hospitals:General acute care facilities handle emergency presentations and surgical stabilization with standardized implant contracts.
- Home Care:Subcutaneous self-administration protocols for stable patients on maintenance biologics.
- Rehabilitation Centers:Post-surgical physical therapy and functional restoration following orthopedic intervention.
Hospitals anchors the volume base while specialty clinics gains share at the steepest rate.
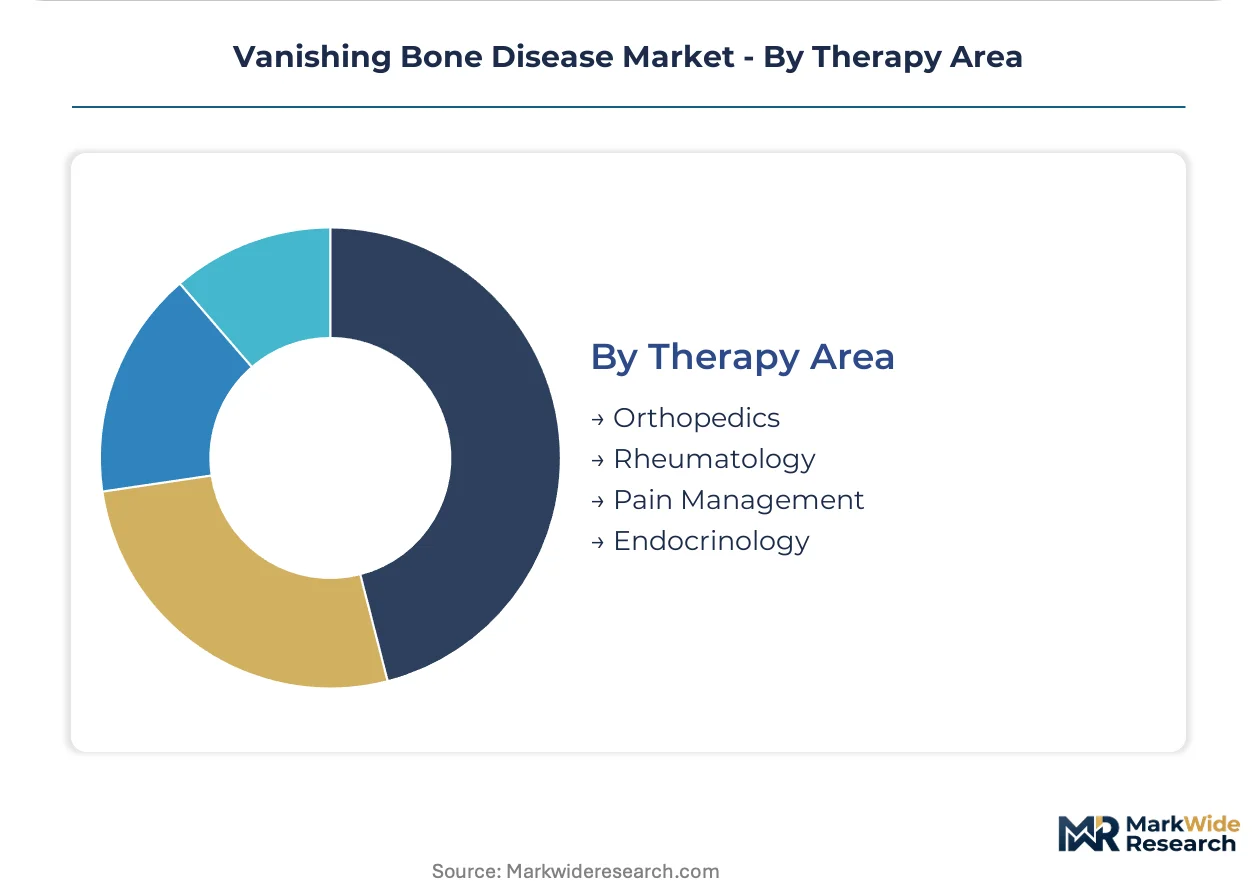
Therapy Area:
Application maturity diverges sharply, with orthopedics holding decades of procedural coding history against emerging rheumatology protocols still seeking Category 1 CPT recognition.
- Orthopedics:Surgical stabilization and limb-salvage procedures constitute the historical treatment backbone, with established DRG reimbursement and fellowship-trained specialist networks. Orthopedic oncology departments at tertiary US centers are adopting molecular imaging agents ahead of community hospitals.
- Rheumatology:Systemic biologic therapy for lymphovascular-mediated osteolysis represents the frontier of disease-modifying intervention, with clinical protocols still evolving and payer coverage determinations pending.
- Pain Management:Analgesic protocols and nerve block procedures for symptomatic control of osteolytic lesions.
- Endocrinology:Metabolic bone disease assessment and calcium homeostasis monitoring.
Orthopedics anchors the volume base while rheumatology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives pull venture capital toward US biologics development, while EMA parallel pathways compress transatlantic regulatory lag. Academic medical centers in concentrated metropolitan clusters drive diagnostic capacity and treatment demand.
United States
Mayo Clinic and Memorial Sloan Kettering anchor diagnostic imaging adoption for lymphovascular skeletal disorders. FDA Orphan Drug Act tax credits sustain biologics manufacturing investment in Massachusetts and California clusters. Boston specialty clinics pilot bundled payment models covering biologic administration and orthopedic consultation.
Germany
EMA centralized procedures accelerate orphan drug market access for enzyme replacement therapies. The country's national pharmaceutical regulator maintains stringent post-market surveillance for biologics under national drug law provisions. Heidelberg and Munich academic hospitals concentrate fellowship-trained orthopedic oncology specialists.
Japan
PMDA orphan drug designation remains underutilized for lymphovascular skeletal conditions, creating first-mover opportunities. METI industrial policy supports domestic clinical trial infrastructure for rare disease biologics. Tokyo and Osaka medical centers build referral networks for complex osteolysis case management.
Switzerland
Swissmedic alignment with EMA standards streamlines dual jurisdiction filings for biologics sponsors. Contract development and manufacturing organizations in Basel and Zurich control critical cold-chain capacity for orphan enzyme therapies. The country's pharmaceutical cluster attracts R&D investment through stable regulatory predictability.
United Kingdom
NHS England specialized commissioning frameworks concentrate vanishing bone disease treatment at designated tertiary centers. The national pharmaceutical regulator maintains orphan drug incentive parity with pre-Brexit EMA provisions. London and Manchester academic medical centers consolidate complex orthopedic oncology case volumes.
Vanishing Bone Disease Market Competitive Environment
On the supply side, the industry is consolidating around biologics manufacturers with established orphan drug portfolios and orthopedic device specialists with MDR-compliant quality systems. Three archetypes dominate: integrated pharmaceutical conglomerates with biologics manufacturing footprints, mid-cap orthopedic device specialists, and contract research organizations managing ultra-rare disease clinical trials. Competitive moves center on strategic partnerships between biologics sponsors and academic medical centers, plus geographic expansion of specialty clinic networks to concentrate case volumes.
Within the integrated pharmaceutical tier, Novartis AG and Amgen Inc. exemplify supply-side concentration through established biologics infrastructure. Pfizer Inc. occupies a position bridging broad distribution reach with academic medical center penetration. These three entities anchor the competitive structure by representing distinct strategic postures: manufacturing scale, R&D depth, and channel breadth respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Amgen Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Sanofi S.A. |
| Roche Holding AG |
| Johnson & Johnson |
| Medtronic plc |
| Elekta AB |
| Others |
Value Chain & Pricing Dynamics
Swiss and Massachusetts-based contract development and manufacturing organizations control critical cold-chain capacity for orphan enzyme therapies, anchoring margin capture at the biologics tier while compressing returns for surgical hardware segments facing EU MDR compliance burdens.
Pricing Analysis
Certification level creates the primary spread across the vanishing bone disease market, with FDA orphan drug exclusivity commanding premium positioning against CE-marked surgical implants facing MDR revalidation costs. Three-tier pricing structure across orphan biologics, specialty pharmaceuticals, and commoditized nutraceuticals reflects R&D intensity and manufacturing complexity. Pricing pressure stems from Medicaid reimbursement fragmentation across US state programs, squeezing pharmaceutical margins. Academic medical centers demonstrate lowest price sensitivity due to bundled payment pilot authority, while community hospitals face acute budget constraints on diagnostic imaging procurement.
Supply Chain Analysis
Upstream biologics manufacturing feeds from Swiss and US East Coast CDMO clusters, with Basel and Zurich facilities specializing in cold-chain enzyme replacement production. Raw material dependencies include recombinant protein cell lines, monoclonal antibody feedstocks, and orthopedic-grade titanium alloys. Single-source vulnerability concentrates in orphan biologics capacity, where qualified facility switching requires multi-year regulatory re-approval. Distribution runs through specialty clinic networks with direct-to-site cold delivery, bypassing traditional wholesale channels for temperature-sensitive therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vanishing bone disease market operates as a defensive-moat arena where FDA orphan drug exclusivity creates seven-year regulatory entrenchment against competitive entry, locking in incumbent pricing power and manufacturing relationships.
For Market Incumbents: Harden orphan drug exclusivity positions through backward integration into biologics manufacturing capacity in Massachusetts and California clusters. Deepen academic medical center partnerships to secure referral network control against emerging rheumatology-focused competitors. Prioritize PMDA orphan designation filing in Japan before first-mover window narrows. For New Entrants and Emerging Players: Pursue underpenetrated Japanese market entry via METI-supported clinical trial infrastructure, where lymphovascular skeletal disorder designation remains available. Target combination product development merging biologic reservoirs with orthopedic implants, a segment where EU MDR compliance has disadvantaged new surgical entrants. Establish payer access specialist teams to navigate Medicaid rare disease carve-out negotiations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap orthopedic device specialists carrying MDR-validated quality systems but lacking biologics pipelines. Five-to-ten-year viability hinges on successful pivot from hardware-centric to biologics-integrated therapeutic platforms. Watch FDA breakthrough therapy designation signals for novel anti-resorptive mechanisms as inflection indicators for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Exclusivity Extension | FDA market exclusivity provisions sustain premium pricing for enzyme replacement therapies at academic medical centers. |
| PMDA Designation Pursuit | Japan's underutilized orphan drug pathway offers first-mover advantage for sponsors establishing Tokyo clinical infrastructure. |
| Specialty Clinic Network Expansion | Boston and Philadelphia bundled payment pilots concentrate case volumes and justify biologic administration premium. |
| Combination Product Development | Biologic-implant convergence reduces injection burden while navigating EU MDR surgical device compliance scope. |
| Molecular Imaging Adoption | Mayo Clinic and Memorial Sloan Kettering PET tracer deployment collapses diagnostic latency for pre-emptive intervention. |
Study Parameters
A standing panel of orthopedic oncology specialists, biologics manufacturing executives, payer access strategists, and specialty clinic operations directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FDA orphan drug filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol databases, and hospital procurement contract repositories. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue analytics.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying regulatory approval timelines and reimbursement policy shifts. Segmentation dimensions included product type, delivery mode, end user channel, and therapy area, with regional regulatory clusters layered as a cross-cutting variable. CAGRs derived from spline-interpolated annual growth rates applied to orphan drug pricing elasticity parameters and surgical procedure volume trends.
Macroeconomic conditions sit as an overlay; deviation in biotech venture capital availability, Medicaid federal matching rates, or cold-chain logistics costs would shift the trajectory. Cross-checking against CMS Medicare rare disease spending data and EMA orphan drug market access timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Antimicrobial Peptides Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Isogenic Cell Lines Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Botulism Illness Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Iga Nephropathy (Igan) Market