
 Global Diagnostic Specialty Enzymes Market | 2026-2036
Global Diagnostic Specialty Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diagnostic Specialty Enzymes Market Foresight
Asset-light contract manufacturing and enzyme tolling arrangements are reshaping competitive entry in diagnostic specialty enzymes. Novozymes A/S leverages its fermentation scale to supply bulk recombinant enzymes under long-term supply contracts. Merck KGaA anchors its position through backward integration into precision fermentation and downstream purification. Thermo Fisher Scientific competes by bundling enzymes with analyzer platforms and consumables workflows.
Diagnostic specialty enzymes are purified biocatalysts—typically recombinant proteins with defined specific activity, pH optima, and temperature stability profiles—engineered for quantitative signal generation in clinical test systems. These enzymes catalyze chromogenic, fluorogenic, or chemiluminescent reactions that enable detection of analytes ranging from metabolic markers to infectious disease antigens. Proteases and oxidoreductases dominate current revenue as workhorse reagents in clinical chemistry and immunoassay kits. Molecular diagnostics applications represent the fastest-expanding consumption vector as PCR and isothermal amplification protocols multiply test menu breadth. Hydrolases occupy a mature, high-volume niche in legacy enzymatic assays where cost minimization outweighs performance premium.
FDA's in vitro diagnostic regulations and the EU's MDR framework enforce analytical performance documentation that elevates barriers for unvalidated enzyme suppliers. ISO 13485 quality management systems and GMP-compliant fermentation records have become baseline requirements for contract qualification by diagnostic OEMs. China's NMPA now mandates domestic clinical evidence for imported enzyme-containing kits, redirecting registration investment toward local partnership structures. Stakeholders must monitor evolving equivalency standards between reference methods and emerging point-of-care formats.
Market Dynamics
Automated immunoassay platform expansion in Germany and the United States is compressing enzyme procurement cycles while elevating performance specifications for recombinant biocatalysts. Contract manufacturers now face tiered qualification demands that separate qualified suppliers from commodity enzyme vendors.
Growth Catalysts
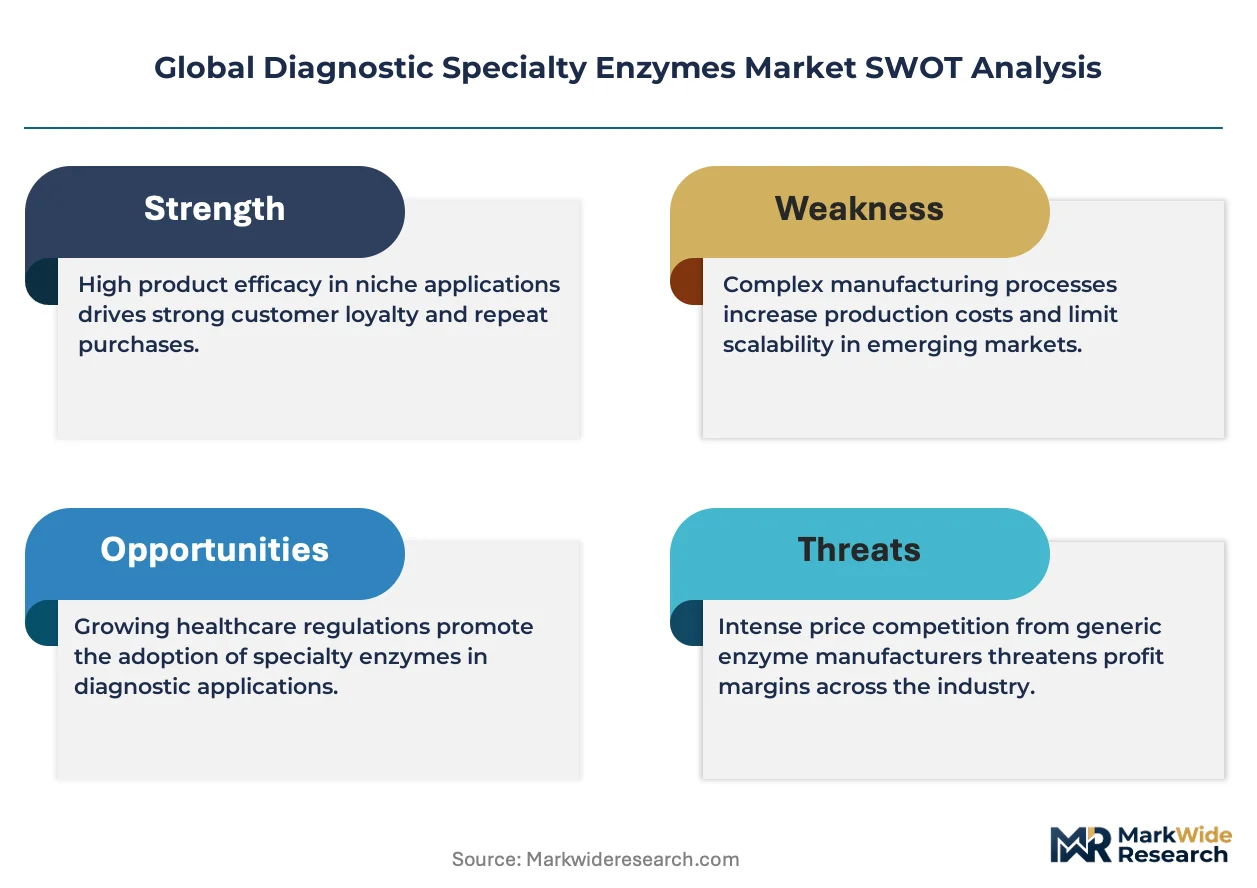
- EU MDR framework:Analytical performance documentation requirements elevate barriers for unvalidated enzyme suppliers, directing diagnostic OEMs toward ISO 13485-certified contract manufacturers with GMP-compliant fermentation records.
- PCR protocol multiplication:Molecular diagnostics applications consume hydrolases and polymerases at accelerating rates as test menu breadth expands across infectious disease and oncology panels.
- Shanghai biotech corridor:Domestic diagnostic manufacturers in China's Yangtze River Delta region scale enzyme sourcing for NMPA-registered kits, redirecting registration investment toward local partnership structures.
Market Restraints
- Fermentation capacity concentration:Bulk recombinant enzyme supply concentrates among large-scale fermentation operators in Denmark and Germany, creating single-source vulnerability for mid-tier diagnostic kit manufacturers.
- Precision purification capex:Downstream chromatography and tangential flow filtration systems require capital intensity that excludes emerging regional suppliers from high-purity enzyme segments.
- NMPA clinical evidence mandate:China's requirement for domestic clinical validation of imported enzyme-containing kits extends registration timelines and redirects investment toward local partnership structures.
Strategic Opportunities
- Isothermal amplification convergence:Loop-mediated isothermal amplification and recombinase polymerase amplification protocols create demand for thermostable enzymes with modified kinetic profiles, opening formulation service opportunities.
- Point-of-care format expansion:Lateral flow and microfluidic platforms in India and Brazil require lyophilized enzyme preparations with extended ambient stability, enabling regional toll-manufacturing arrangements.
- ISO 13485 certification gap:Diagnostic OEMs in South Korea and Australia face supplier qualification bottlenecks, creating entry points for contract manufacturers with existing quality management systems.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up and downstream purification expertise concentrates among specialists in Basel and Copenhagen, constraining regional capacity expansion.
- Reference method equivalency disputes:Point-of-care enzyme-based assays face analytical validation challenges against centralized laboratory reference methods, compressing product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diagnostic Specialty Enzymes Market |
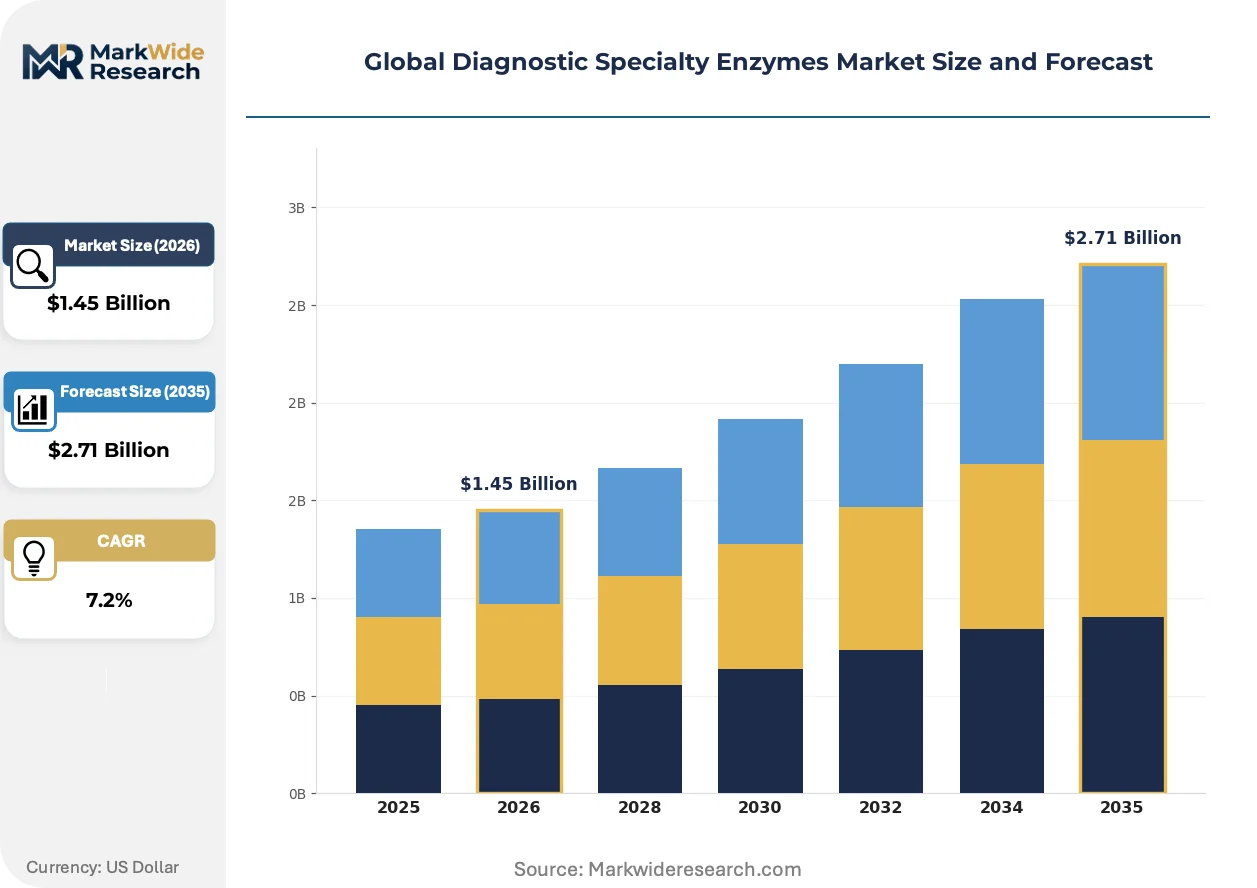
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.71 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Oxidoreductases, Transferases, Hydrolases, Lyases Application: Clinical Chemistry, Molecular Diagnostics, Immunoassays, Food Testing, Environmental Monitoring End User: Diagnostic Laboratories, Academic Research Centers, Pharmaceutical Companies, Biotech Firms, Government Agencies Deployment: In Vitro, Point of Care, Laboratory Information Systems, Automated Analyzer Integration, Mobile Diagnostic Platforms |
| Companies Covered | Advanced Enzymes Technologies, Novozymes A/S, F. Hoffmann-La Roche Ltd, Merck KGaA, Codexis, Thermo Fisher Scientific, BBI Solutions, SEKISUI Diagnostics, Amano Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diagnostic Specialty Enzymes Market Shifts & Advancements
Engineered enzyme variants with altered temperature stability and substrate specificity profiles are displacing wild-type biocatalysts in quantitative diagnostic applications. This molecular evolution compresses reaction times while expanding operating range.
Solid-phase enzyme immobilization on magnetic beads and nanoparticle scaffolds is rendering obsolete liquid-phase reagent formats in high-throughput clinical chemistry analyzers. Reference laboratories in Germany and the United States adopt these surface-tethered systems to reduce reagent consumption and simplify wash protocols. The shift compresses cost-per-test metrics while elevating supplier qualification barriers for surface chemistry expertise.
FDA's classification reforms for in vitro diagnostic substances compress product registration timelines for enzyme-containing reagents. The agency's streamlined 510(k) pathways for well-characterized biocatalysts redirect regulatory investment toward novel enzyme engineering rather than documentation burden. Molecular diagnostics segments benefit most as polymerase and reverse transcriptase variants gain expedited clearance.
Diagnostic OEM procurement teams consolidate supplier relationships around full-service contract manufacturers offering bundled fermentation, purification, and regulatory documentation services. This concentration displaces fragmented sourcing across multiple specialty vendors. The pattern is most visible in China's biotech corridor, where domestic manufacturers prioritize single-source accountability over cost minimization.
Global Diagnostic Specialty Enzymes Market Segmentation
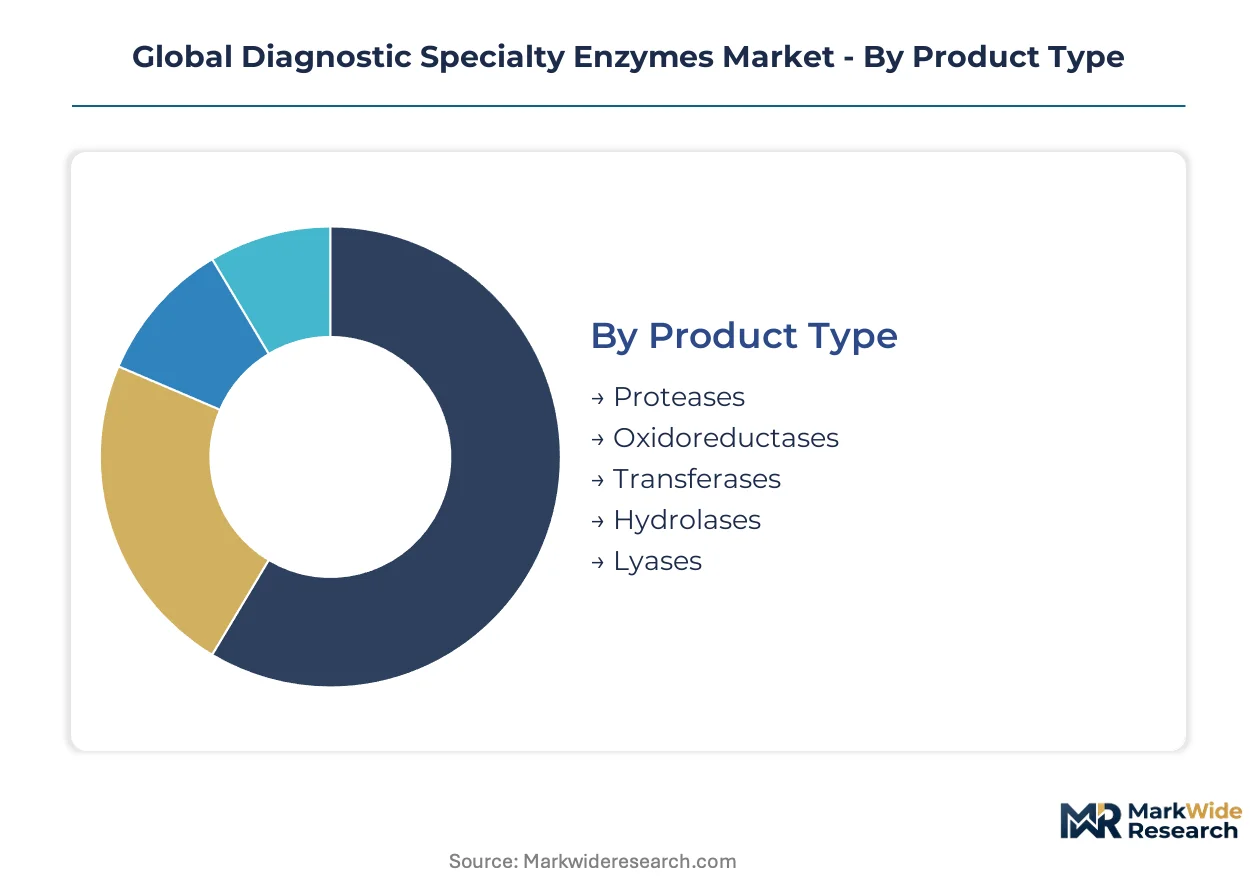
Diagnostic specialty enzymes serve heterogeneous performance requirements across clinical, industrial, and research contexts. Segmentation reveals where formulation complexity commands premium pricing versus where bulk supply economics dominate procurement decisions.
Product Type:
Cost tier differentiation separates high-purity recombinant enzymes from commodity fermentation extracts.
- Proteases:Serine and metalloprotease variants with defined specific activity and inhibitor profiles cleave peptide substrates in clinical chemistry analyzers. Demand concentrates in automated immunoassay workflows across Germany and the United States where wash-stringency specifications elevate purity requirements.
- Oxidoreductases:Horseradish peroxidase and glucose oxidase variants catalyze chromogenic and chemiluminescent signal generation. Consumption clusters in infectious disease panels within China's Yangtze River Delta biotech corridor as domestic manufacturers scale NMPA-registered kit production.
- Transferases:Kinase and phosphotransferase preparations enable metabolic marker quantification in specialized clinical assays.
- Hydrolases:Esterase and lipase biocatalysts occupy mature, high-volume niches in legacy enzymatic assays where cost minimization outweighs performance premium.
- Lyases:Decarboxylase and aldolase enzymes support carbon-carbon bond cleavage applications in targeted diagnostic formulations.
Proteases hold installed capacity. Oxidoreductases is rotating up the share rankings.
Application:
Application segmentation tracks how enzyme performance specifications align with regulatory validation burdens and throughput requirements.
- Clinical Chemistry:Enzymatic assays for metabolic markers, cardiac enzymes, and liver function panels require thermostable biocatalysts with narrow batch-to-batch variation. Reference laboratories in Germany specify GMP-compliant fermentation records and ISO 13485 documentation for contract qualification.
- Molecular Diagnostics:PCR, isothermal amplification, and nucleic acid detection protocols consume thermostable polymerases and reverse transcriptases at accelerating rates. China's NMPA clinical evidence mandate redirects registration investment toward domestic partnership structures for imported enzyme-containing kits.
- Immunoassays:Signal-generating enzymes conjugated to antibodies or antigens enable quantitative detection in sandwich and competitive assay formats.
- Food Testing:Pathogen detection and allergen quantification applications require enzyme preparations with extended ambient stability for field-deployable formats.
- Environmental Monitoring:Biosensor-integrated biocatalysts detect heavy metals and organic contaminants in water quality assessment protocols.
Clinical chemistry commands the largest revenue base. Molecular diagnostics is climbing the fastest as test menu breadth expands across oncology and infectious disease panels.
End User:
Customer type determines procurement scale, quality system requirements, and technical service intensity.
- Diagnostic Laboratories:Hospital-affiliated and independent reference labs in the United States and Germany consolidate supplier relationships around full-service contract manufacturers offering bundled fermentation, purification, and regulatory documentation services.
- Academic Research Centers:University and institute laboratories purchase research-grade enzyme preparations for assay development and protocol optimization where analytical validation requirements remain internal.
- Pharmaceutical Companies:Companion diagnostic development programs require GMP-grade enzymes with comprehensive regulatory support files for FDA 510(k) and EU MDR submissions.
- Biotech Firms:Venture-backed developers in Shanghai and Boston source customized enzyme formulations for novel platform technologies.
- Government Agencies:Public health laboratories procure validated enzyme reagents for surveillance and screening programs under tender-based procurement frameworks.
Diagnostic laboratories anchor volume demand. Biotech firms is gaining share fastest as venture funding flows toward platform differentiation.
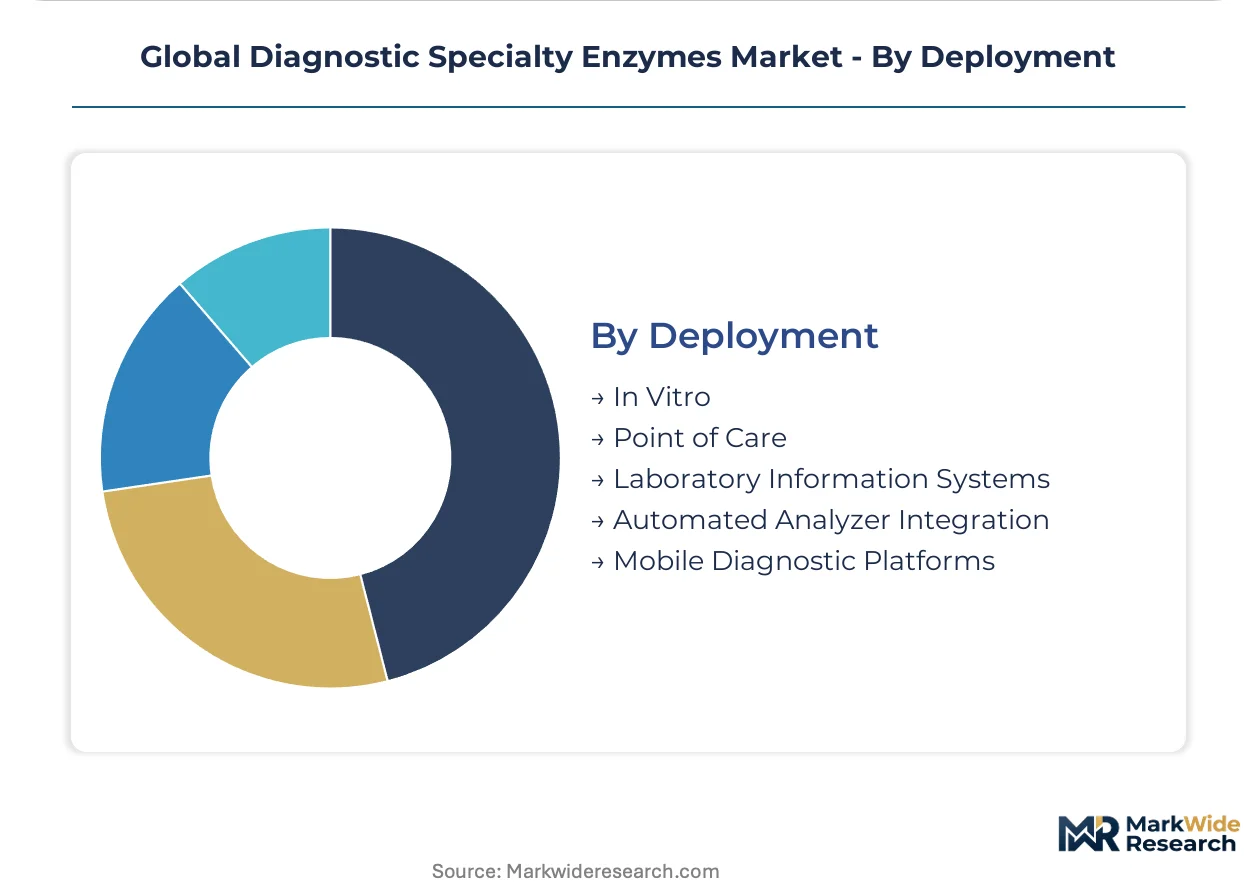
Deployment:
Deployment mode dictates formulation requirements around stability, integration complexity, and connectivity architecture.
- In Vitro:Central laboratory formats with controlled temperature storage and liquid-handling automation accommodate standard aqueous enzyme preparations with established shelf-life specifications.
- Point of Care:Lateral flow and microfluidic platforms in India and Brazil require lyophilized enzyme preparations with extended ambient stability, enabling regional toll-manufacturing arrangements.
- Laboratory Information Systems:Middleware-connected analyzers demand enzyme reagents with embedded consumption tracking and automated reorder triggers.
- Automated Analyzer Integration:High-throughput clinical chemistry and immunoassay platforms specify barcoded reagent cassettes with onboard stability monitoring.
- Mobile Diagnostic Platforms:Battery-powered field devices impose power and thermal constraints that favor solid-phase enzyme immobilization on magnetic beads and nanoparticle scaffolds.
In vitro retains the largest installed base. Point of care is expanding most quickly as decentralized testing infrastructure deploys across emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic specialty enzymes command price premiums in Germany and the United States that suppliers cannot replicate in China's Yangtze River Delta, where domestic manufacturers leverage local toll-manufacturing arrangements to compress procurement costs. This asymmetry redirects capacity investment toward ISO 13485-certified facilities in Basel and Copenhagen while mid-tier kit makers in Shanghai absorb margin pressure.
United States
FDA's streamlined 510(k) pathways for well-characterized biocatalysts compress registration timelines for polymerase and reverse transcriptase variants. The agency's classification reforms redirect regulatory investment toward novel enzyme engineering rather than documentation burden. Reference laboratories in Greater Boston consolidate supplier relationships around full-service contract manufacturers offering bundled fermentation, purification, and regulatory documentation services.
Germany
Automated immunoassay platform expansion in Bavaria and North Rhine-Westphalia elevates performance specifications for recombinant biocatalysts while compressing procurement cycles. The EU MDR framework enforces analytical performance documentation that elevates barriers for unvalidated enzyme suppliers. Precision fermentation expertise concentrates in the Basel-Copenhagen corridor, constraining regional capacity expansion for downstream purification operations.
China
NMPA's clinical evidence mandate for imported enzyme-containing kits extends registration timelines and redirects investment toward local partnership structures. Domestic diagnostic manufacturers in Shanghai's biotech corridor scale enzyme sourcing for NMPA-registered kits as test menu breadth expands across infectious disease and oncology panels. Yangtze River Delta producers prioritize single-source accountability over cost minimization in procurement decisions.
Japan
PMDA's quality management requirements for in vitro diagnostic reagents align with ISO 13485 baseline standards enforced by diagnostic OEMs. METI's industrial biotechnology programs support precision fermentation scale-up among domestic suppliers seeking to reduce import dependency. Osaka-based reference laboratories specify GMP-compliant fermentation records for contract qualification of thermostable biocatalysts.
India
Lateral flow and microfluidic platform deployment across Maharashtra and Karnataka creates demand for lyophilized enzyme preparations with extended ambient stability. CDSCO's evolving equivalency standards between reference methods and point-of-care formats compress product development timelines for regional kit developers. Mumbai-Pune biotech clusters enable toll-manufacturing arrangements that bypass capital intensity barriers for high-purity enzyme segments.
Global Diagnostic Specialty Enzymes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and purification. The vendor base separates into three tiers: global life science conglomerates bundling enzymes with analyzer platforms, mid-cap fermentation houses supplying bulk recombinant biocatalysts under long-term contracts, and regional toll-manufacturers serving point-of-care format developers. Consolidation pressure concentrates among precision purification operators as downstream chromatography capex excludes emerging suppliers. Dominant competitive moves include backward integration into captive fermentation capacity and strategic partnerships with diagnostic OEMs seeking single-source accountability.
Within the fermentation-scale tier, Novozymes A/S and Merck KGaA occupy positions anchored by large-scale bioprocessing infrastructure. Thermo Fisher Scientific exemplifies the platform-integrator archetype, bundling enzyme supply with analyzer systems and consumables workflows. These three entities represent contrasting strategic postures: bulk supply contracting, backward integration into precision fermentation, and full-service bundling respectively.
| Leading Market Players |
|---|
| Advanced Enzymes Technologies |
| Novozymes A/S |
| F. Hoffmann-La Roche Ltd |
| Merck KGaA |
| Codexis |
| Thermo Fisher Scientific |
| BBI Solutions |
| SEKISUI Diagnostics |
| Amano Enzymes |
| Others |
Supply & Pricing Matrix
Single-source dependency on Denmark and Germany-based precision fermentation operators determines both pricing tier spreads and supply chain shape across the diagnostic specialty enzymes market. This concentration elevates premiums for ISO 13485-certified GMP grades while compressing margins for mid-tier kit manufacturers lacking backward integration.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—FDA 510(k)-cleared and EU MDR-documented enzymes command substantial premiums over research-use-only preparations—and volume scale, where long-term offtake contracts secure favorable unit economics. Cost compression in the economy tier is intensifying because Shanghai-based domestic manufacturers leverage local toll-manufacturing arrangements. Academic research centers exhibit the highest price sensitivity, while pharmaceutical companion diagnostic programs demonstrate minimal elasticity due to regulatory validation requirements.
Supply Chain Analysis
Export-control restrictions on precision fermentation technology and specialized chromatography equipment limit capacity expansion outside established basins. Supply concentrates in Denmark, Germany, and Switzerland, where downstream purification infrastructure draws from recombinant cell banks and specialized resin media. Raw material dependencies include fermentation-grade yeast extracts, chromatography resins, and sterile filtration membranes. Single-source vulnerability pervades the bulk enzyme segment, as mid-tier diagnostic kit manufacturers lack alternative qualified suppliers. Distribution runs through full-service contract manufacturers offering bundled fermentation, purification, and regulatory documentation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates formidable barriers. Switching costs for diagnostic OEMs escalate once validation protocols lock in specific enzyme formulations and supplier quality systems.
For Market Incumbents: Insulate market position by deepening backward integration into captive fermentation capacity in the Basel-Copenhagen corridor, eliminating single-source exposure for critical hydrolase and polymerase inputs. Prioritize ISO 13485 certification investments to capture diagnostic OEM procurement consolidation toward full-service contract manufacturers. Emerging biotech firms in Shanghai represent the primary substitution threat through local partnership structures that bypass import registration timelines.
For New Entrants and Emerging Players: India's lateral flow and microfluidic platform deployment offers the most penetrable white-space target, where lyophilized enzyme preparations with extended ambient stability face limited qualified regional supply. Brazil's point-of-care infrastructure expansion presents a secondary entry vector. Pursue toll-manufacturing arrangements with established fermentation operators rather than capital-intensive greenfield capacity, enabling rapid qualification under CDSCO equivalency pathways.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision purification specialists with existing GMP-compliant downstream infrastructure. Long-term viability hinges on regulatory documentation depth and single-source accountability relationships with diagnostic OEMs. Acquisition targets should demonstrate established ISO 13485 quality systems and documented fermentation scale-up expertise. Watch for FDA classification reform implementation velocity as an inflection indicator for polymerase and reverse transcriptase variant clearance rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Fermentation | Captive supply of recombinant biocatalysts eliminates single-source dependency for diagnostic OEMs. |
| ISO 13485 Certification Investment | Quality management documentation opens contract qualification pathways with EU MDR-compliant kit manufacturers. |
| Regional Toll-Manufacturing Partnership | Local production in Shanghai corridor accelerates NMPA registration timelines for imported enzyme formulations. |
| Lyophilized Enzyme Formulation Development | Ambient-stable preparations enable point-of-care deployment across India and Brazil infrastructure. |
| Engineered Variant Pipeline Expansion | Modified thermostable polymerases capture isothermal amplification protocol demand from infectious disease panels. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, NMPA registration databases, and precision fermentation capacity disclosures preceded structured interviews with diagnostic kit procurement managers, contract manufacturing executives, regulatory affairs specialists, and bioprocess engineering directors. Primary fieldwork combined telephone and video interviews with secondary validation against GMP inspection records and ISO certification registries. Bottom-up enzyme consumption estimates triangulated against top-down diagnostic test volume projections across clinical chemistry, immunoassay, and molecular diagnostics applications.
Forecast assumptions held regulatory pathway timelines and fermentation scale-up economics fixed while varying test menu expansion rates and point-of-care adoption patterns across the projection horizon. The analytical framework modeled product type, application, end user, and deployment mode segments with regional regulatory cluster overlays. CAGRs derived from enzyme unit consumption intensity per test, test volume trajectories, and pricing tier migration patterns. Industry-specific inputs included PCR protocol multiplication rates and lateral flow platform deployment curves in emerging markets.
Practitioners should monitor FDA classification reform implementation, EU MDR equivalency standard evolution, and NMPA domestic clinical evidence requirement adjustments for early signals of forecast revision. Forecasts reflect assumptions regarding fermentation capacity expansion constraints and diagnostic OEM procurement consolidation patterns. Material shifts in export control enforcement on precision fermentation technology or sudden regulatory pathway accelerations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Ornithine Transcarbamylase (OTC) Deficiency Treatment Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
AI in Pharma and Biotech Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Hormone Sensitive Prostate Cancer Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Morgellons Disease Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Mecobalamin Injection Market