
 Nanomedicine Market | 2026-2036
Nanomedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomedicine Market Intelligence
The US FDA's framework for evaluating nanotechnology products is recalibrating the cost-of-entry and development timelines for new therapies. This regulatory scrutiny requires extensive characterization and safety data before market approval. Pfizer leverages its significant R&D infrastructure to advance a pipeline of nanoparticle-based therapeutics. Johnson & Johnson Services, Inc. specializes in drug delivery systems using novel nanomaterials, while Novartis International AG competes through its leadership in cell and gene therapies that incorporate nanomedical principles.
Nanomedicine involves the use of precisely engineered materials, typically between 1 and 100 nanometers in size, for medical intervention. These materials, such as lipid nanoparticles or nanoshells, are designed to interact with biological systems at a molecular level. The primary purpose is to enhance the efficacy and safety of diagnostics and therapeutics. Nanoparticles dominate the product landscape, driven by their central role in targeted drug delivery for oncology, while regenerative medicine applications represent a key frontier for future development.
Regulatory oversight from agencies like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA governs market access. These bodies mandate rigorous preclinical and clinical data to validate the safety and efficacy of nanotherapeutics, influencing trial design and manufacturing standards. Navigating the complex intellectual property rights for novel nanocarriers and scaling up GMP-compliant manufacturing remain critical decision points for all market participants.
Market Dynamics
The central dynamic in the nanomedicine market is the friction between rapid materials science innovation and the rigorous, data-intensive demands of regulatory bodies. Agencies such as the US FDA and EMA require extensive characterization, influencing development timelines and R&D investment strategies.
Growth Catalysts
- Targeted Oncology Therapies:The expanding application of nanocarriers for delivering cytotoxic agents directly to tumor cells, minimizing systemic toxicity, is a primary growth driver. This is particularly evident in treatments for solid tumors where conventional chemotherapy has limitations.
- Gene Therapy Platforms:Advances in lipid nanoparticles (LNPs) and viral vectors that incorporate nanoscale components are enabling the clinical progression of gene editing and mRNA-based therapeutics, creating significant demand for these delivery systems.
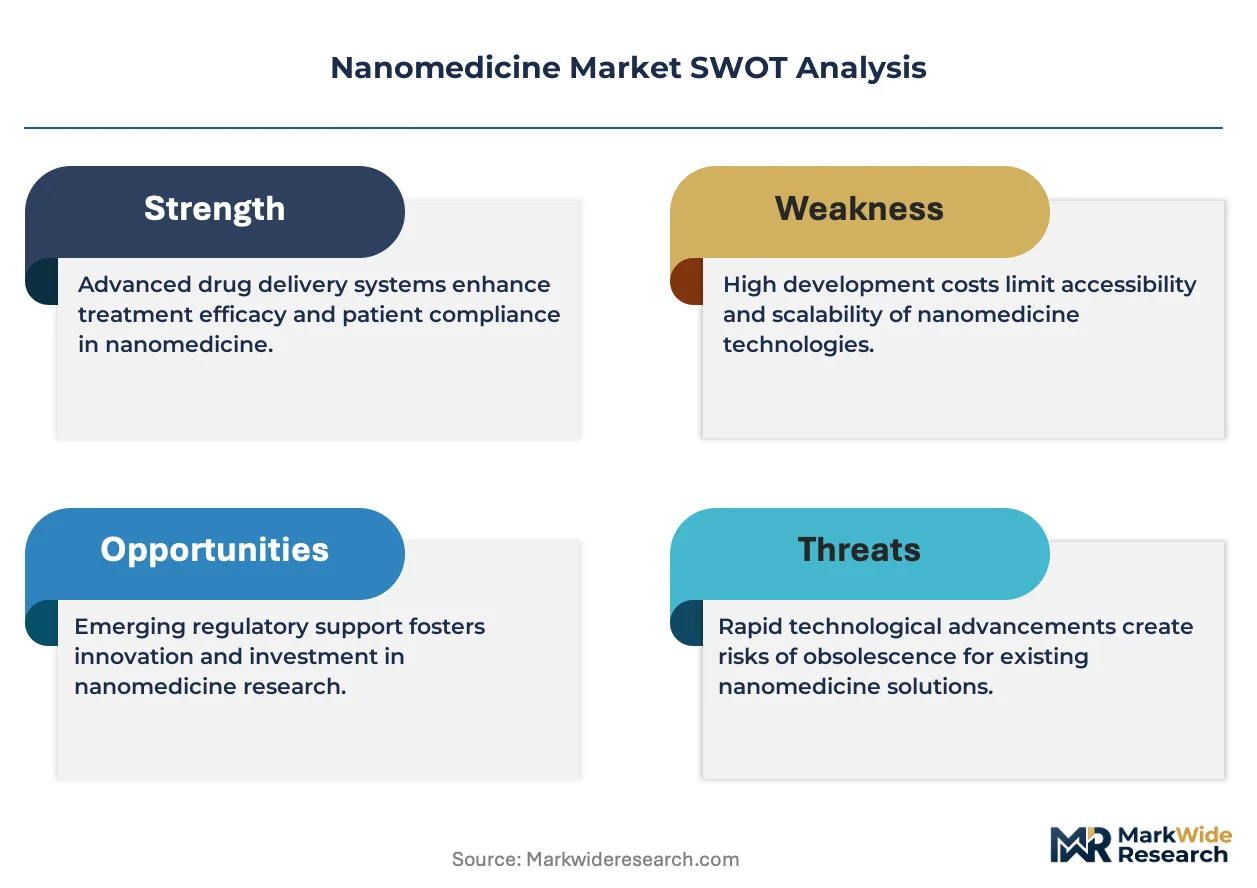
- Evolving Regulatory Frameworks:The establishment of specific guidance documents for nanotechnology-based products by regulators like the US FDA provides clearer development pathways, reducing ambiguity for market entrants with sufficient capital for extensive testing.
Market Restraints
- Manufacturing Complexity:The high cost and technical difficulty of scaling up GMP-compliant manufacturing for nanoparticles while maintaining consistent size, purity, and stability presents a significant barrier to commercialization for many developers.
- Immunogenicity and Biocompatibility:Unpredictable immune responses to novel nanomaterials remain a key technical hurdle, potentially causing adverse events and leading to late-stage clinical trial failures, which deters investment.
- Fragmented Global Standards:Divergent data requirements between the US FDA, the European Medicines Agency, and Japan's PMDA for preclinical characterization and clinical trial design complicate global product launches and increase compliance costs.
Strategic Opportunities
- Regenerative Medicine:The use of nanoscaffolds and nanoparticle-based systems to guide tissue regeneration and deliver growth factors presents a significant opportunity. This includes applications in orthopedics, wound healing, and cardiovascular repair.
- AI in Nanoparticle Design:Converging artificial intelligence with materials science allows for predictive modeling of a nanoparticle's behavior in biological systems. This accelerates the design and optimization of nanocarriers for specific therapeutic tasks.
- Expansion in Asian Markets:Government-led initiatives in South Korea and China to build domestic biotechnology and pharmaceutical R&D capabilities create opportunities for partnership and market entry, especially for platform technology licensors.
Industry Challenges
- Intellectual Property Thickets:The dense and often overlapping patent landscape for fundamental nanocarrier technologies, such as liposomes and LNPs, creates significant freedom-to-operate challenges and increases the risk of litigation.
- Characterization Standardization:A lack of universally accepted methods and standards for characterizing the physicochemical properties of nanomaterials complicates regulatory review and comparability studies between different products or manufacturing batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomedicine Market |
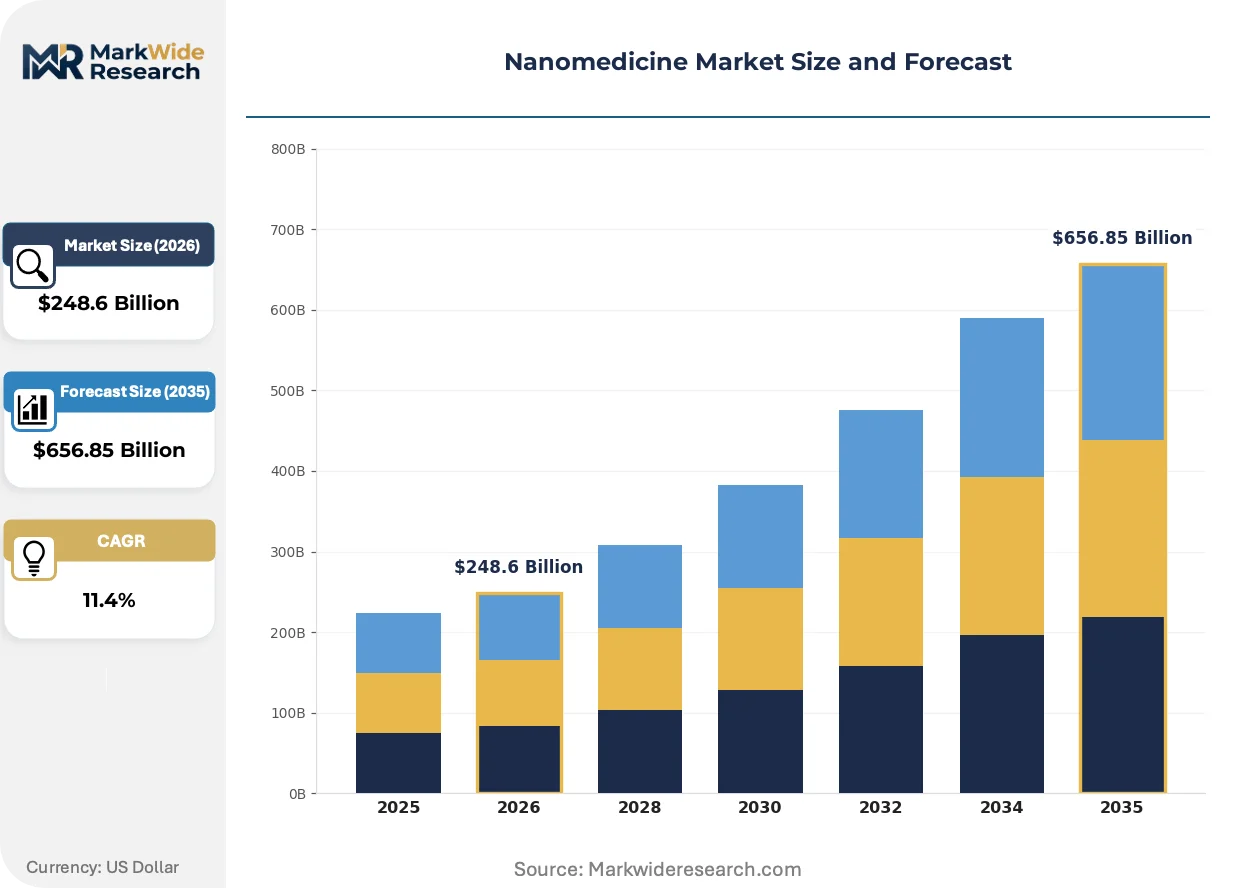
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $656.85 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoshells, Nanotubes, Nanoparticles, Quantum Dots, Dendrimers Application Area: Targeted Drug Delivery, Gene Therapy, Diagnostic Imaging, Regenerative Medicine, Vaccines End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Hospitals, Diagnostic Centers Delivery Mode: Oral, Intravenous, Transdermal, Inhalation, Implantable Devices |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., Bristol-Myers Squibb Company, Merck & Co., Inc., Abbott Laboratories, Novartis International AG, Sanofi SA, Teva Pharmaceutical Industries Ltd., Nanobiotix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomedicine Market Strategic Shifts & Innovations
The convergence of data science, automation, and materials science is transforming nanomedicine development from an empirical art into a more predictive engineering discipline. This shift enables the design of nanotherapeutics with greater precision for specific biological targets and patient populations.
High-throughput screening systems are using microfluidics to rapidly synthesize and test thousands of nanoparticle formulations in parallel. Pharmaceutical and biotech firms are adopting these platforms early in the drug discovery phase to identify lead candidates faster. This technology is automating the optimization of critical nanocarrier properties like size, charge, and drug-loading efficiency, compressing development timelines that traditionally took years.
Refined regulatory guidance from the European Medicines Agency (EMA) on follow-on versions of nanomedicines, known as nanosimilars, is creating a clearer pathway for market entry. This development introduces the prospect of generic competition for complex, non-biological drugs upon patent expiry. The oncology segment, which heavily relies on nanoparticle albumin-bound (nab) technology and liposomal formulations, is most affected by this evolving framework.
A shift from single-product in-licensing to broader platform-based collaborations is altering business development strategies. Large pharmaceutical companies increasingly seek to license entire nanoparticle delivery platforms from specialized biotechs, securing access to a pipeline-in-a-product and versatile delivery technology. This trend is most prominent within the United States and European Union, especially for developing next-generation mRNA vaccines and gene therapies.
Nanomedicine Market Segmentation
Understanding the Nanomedicine Market through segmentation reveals how diverse material sciences and therapeutic applications converge to address complex medical challenges. This granular view highlights areas of concentrated demand and emerging growth trajectories within the rapidly evolving landscape of molecular-level medical intervention.
Product Type:
Nanomedicine product types range from standalone materials designed for specific functions to those integrated into complex delivery systems for targeted biological interaction.
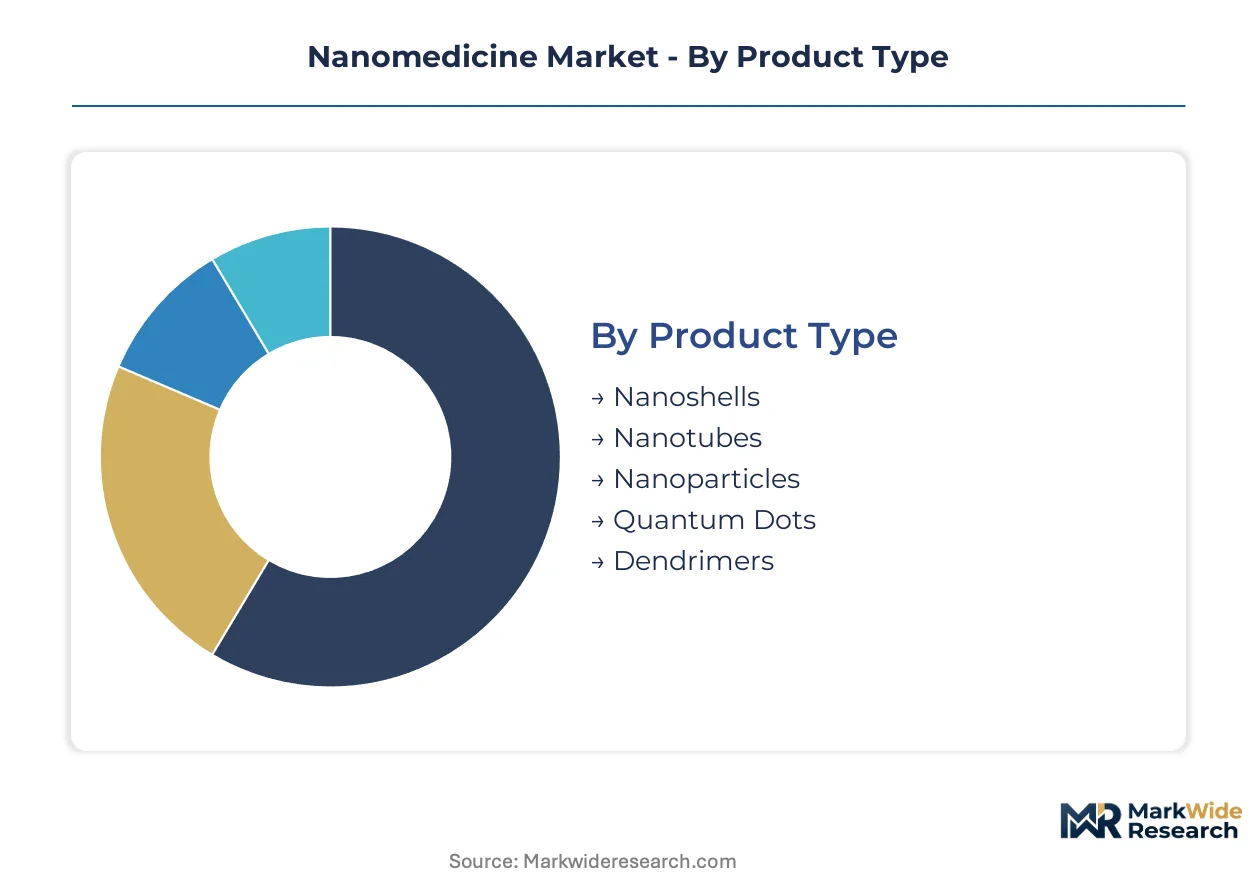
- Nanoparticles:These materials, typically between 1 and 100 nanometers, are engineered to interact with biological systems at a molecular level, enhancing drug efficacy and safety. Demand concentrates in targeted drug delivery for oncology and gene therapy platforms, driven by their ability to minimize systemic toxicity.
- Nanoshells:Comprising a dielectric core surrounded by a metallic shell, nanoshells are primarily used for their optical properties in diagnostic imaging and photothermal therapy. Demand is significant in advanced diagnostic imaging and oncology treatments, where precise targeting and localized energy delivery are critical.
- Nanotubes:Carbon-based cylindrical structures, these materials offer high strength and electrical conductivity, showing promise in biosensors and advanced drug delivery.
- Quantum Dots:Semiconductor nanocrystals exhibiting quantum mechanical properties, they are utilized in bioimaging, diagnostics, and light-emitting applications for their unique fluorescence.
- Dendrimers:Highly branched, synthetic macromolecules with precise molecular structures, useful for drug encapsulation, gene delivery, and contrast agents due to their tunable properties.
Volume placements concentrate in Nanoparticles; the faster expansion belongs to Quantum Dots.
Application Area:
The volume of nanomedicine applications reflects varying clinical needs and market maturity, from established oncology treatments to emerging regenerative therapies.
- Targeted Drug Delivery:This application leverages nanocarriers to transport therapeutic agents directly to diseased cells or tissues, minimizing exposure to healthy areas. Demand is highest in oncology, particularly for solid tumors, where it significantly reduces systemic toxicity and improves treatment outcomes.
- Gene Therapy:Nanoscale components, such as lipid nanoparticles and viral vectors, are crucial for delivering genetic material into cells to correct or modify gene expression. This segment sees substantial demand from mRNA-based therapeutics and gene editing technologies, driving clinical progression.
- Diagnostic Imaging:Nanomaterials enhance the resolution and sensitivity of various imaging techniques, improving disease detection and monitoring.
- Regenerative Medicine:This area uses nanoscaffolds and nanoparticle-based systems to guide tissue repair and deliver growth factors, particularly in orthopedics and cardiovascular repair.
- Vaccines:Nanomaterials improve antigen presentation, stability, and immunogenicity, leading to more effective and safer vaccine formulations.
Targeted Drug Delivery applications hold the largest share, while Regenerative Medicine applications show the steepest expansion trajectory.
End User:
End-user segments reflect the diverse institutional and commercial entities leveraging nanomedicine technologies, each with distinct needs and operational scales.
- Pharmaceutical Companies:These large entities possess significant R&D infrastructure and manufacturing capabilities, focusing on advancing pipelines of nanoparticle-based therapeutics. Their demand centers on platform licensing and strategic partnerships for drug development and commercialization.
- Biotechnology Firms:Specialized in innovative nanomaterials and advanced delivery systems, these firms often drive early-stage development and novel technology creation. They serve as key licensors of platform technologies, particularly for next-generation mRNA vaccines and gene therapies.
- Research Institutions:Academic and government-funded bodies conduct fundamental and translational research, contributing to the scientific understanding and initial development of nanomedicine concepts.
- Hospitals:Healthcare providers directly implement nanomedicine-based diagnostics and therapeutic interventions, particularly in specialized areas like oncology and advanced diagnostics.
- Diagnostic Centers:These facilities utilize advanced nanodiagnostics for precise patient screening, disease detection, and monitoring, leveraging enhanced sensitivity and specificity.
Pharmaceutical Companies represent the largest consumer base, with Biotechnology Firms demonstrating significant growth in innovation.
Delivery Mode:
The choice of nanomedicine delivery mode impacts patient compliance and therapeutic efficacy, influencing commercial viability and clinical adoption.
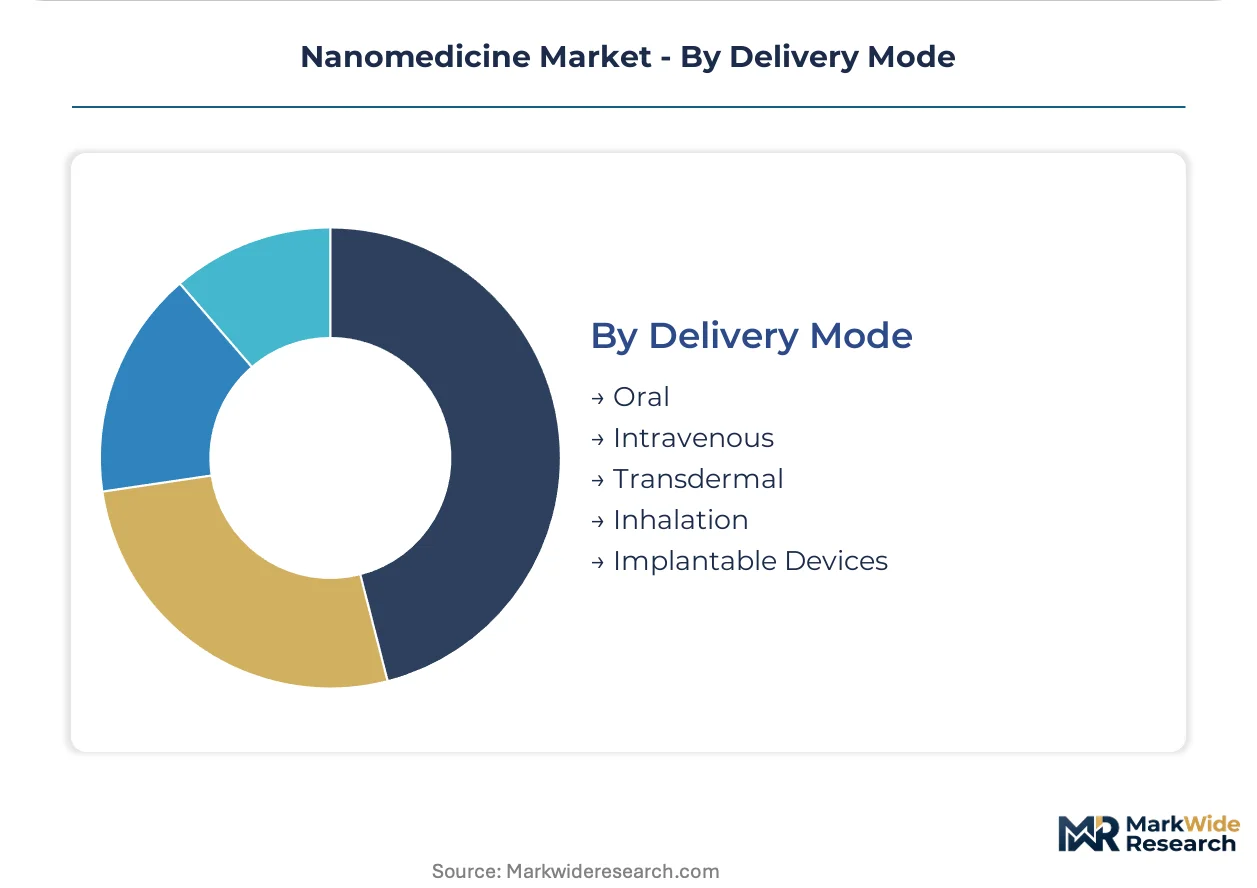
- Intravenous:This mode involves direct administration of nanomedicines into the bloodstream, ensuring rapid systemic distribution and precise dosing. It is a dominant delivery method for oncology and gene therapy, favored for its immediate therapeutic effect.
- Oral:Nanocarriers designed for oral delivery protect drugs from degradation in the gastrointestinal tract, aiming to improve bioavailability and patient convenience. This mode is sought after for chronic disease management, offering a non-invasive administration route.
- Transdermal:Non-invasive delivery through the skin avoids first-pass metabolism and offers sustained drug release, suitable for localized treatments or systemic absorption of certain compounds.
- Inhalation:This method targets respiratory conditions by delivering nanomedicines directly to the lungs, maximizing local drug concentration and minimizing systemic side effects.
- Implantable Devices:These devices provide sustained and controlled release of nanomedicines over extended periods, particularly beneficial for long-term therapies and localized drug delivery.
Intravenous delivery remains the most established method, while Implantable Devices exhibit expanding potential for long-term treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration is notable within research clusters, particularly for advanced diagnostic imaging and gene therapy platforms. This geographic clustering influences research and development, accelerating the translation of nanomedicine concepts into clinical applications. Regulatory frameworks also vary significantly across regions, shaping market entry strategies for pharmaceutical and biotechnology firms.
United States
Targeted drug delivery for oncology and gene therapy platforms drives significant demand in the United States. The US FDA's evolving guidance on nanotechnology-based products provides clearer development pathways for innovators. Research clusters in Boston and the San Francisco Bay Area are actively developing advanced diagnostic imaging and gene therapy platforms.
Germany
Regenerative medicine applications and novel drug delivery systems are key demand areas across Germany. The European Medicines Agency (EMA) mandates rigorous data for nanotherapeutics, influencing trial design. Biotechnology hubs in Munich and Berlin are fostering crucial collaborations for advanced nanomedicine development.
Japan
Advanced diagnostic imaging and personalized nanotherapeutics represent primary demand segments in Japan. The PMDA enforces rigorous preclinical and clinical data validation for novel nanomedicines. The Tokyo and Osaka regions are centers for significant research and development in quantum dots and biosensors.
China
Government-led initiatives to build domestic biotechnology R&D capabilities create substantial demand for platform technology licensing in China. The NMPA is actively working to streamline approval pathways for nanotechnology-based medical products. Shanghai and Beijing are critical centers for government-backed nanomaterials research and development.
Switzerland
High-value cell and gene therapies, alongside precision nanomedicine, generate strong demand in Switzerland. Swissmedic maintains strict oversight on novel therapeutic entities, ensuring patient safety and product efficacy. Basel's prominent pharmaceutical cluster contributes significantly to nanoparticle-based therapeutic advancements.
Nanomedicine Market Key Industry Players
United States producers anchor one tier, emphasizing large-scale R&D infrastructure and extensive clinical trial capabilities. European specialists hold another tier, focusing on novel nanomaterials and advanced delivery systems for niche applications. The market structure involves a mix of established pharmaceutical giants and agile biotechnology firms. Strategic partnerships and platform licensing agreements represent dominant competitive moves.
Large pharmaceutical entities like Pfizer Inc. and Johnson & Johnson Services, Inc. exemplify the significant R&D investment required for nanoparticle-based therapeutics. Novartis International AG occupies a position of leadership in cell and gene therapies that incorporate nanomedical principles. These companies leverage their extensive resources to navigate complex regulatory landscapes and scale manufacturing for global commercialization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Abbott Laboratories |
| Novartis International AG |
| Sanofi SA |
| Teva Pharmaceutical Industries Ltd. |
| Nanobiotix |
| Others |
Cost & Logistics Intelligence
Pharmaceutical companies' demand for advanced nanocarrier platforms shapes the market's value-based and licensing pricing structures. This concentration of purchasing power influences long-term contract negotiations and intellectual property valuations for novel nanomedicines.
Pricing Analysis
Premium pricing for rapid development cycles and validated nanocarrier platforms reflects the urgency in drug development pipelines. The dominant pricing model involves a hybrid of licensing fees for platform technologies and value-based pricing for approved therapeutics. Price differentiation stems from the level of customization for specific drug delivery targets, FDA/EMA certification tier, and the strength of underlying intellectual property. Pricing pressure stems from rigorous regulatory hurdles and the high cost of clinical trials for novel nanomaterials. Research institutions typically exhibit the most price-sensitive behavior, while large pharmaceutical companies show less sensitivity for critical platform technologies.
Supply Chain Analysis
Rigorous GMP certification and material qualification gate the nanomedicine supply chain, ensuring product consistency and regulatory compliance. Geographic supply concentrates in the United States, Germany, and Japan for specialized manufacturing and advanced R&D, with China contributing foundational raw materials. The market relies on high-purity lipids, polymers, and specialized inorganic precursors as critical raw material dependencies. A significant supply chain risk involves single-source vulnerability for GMP-compliant specialized nanomaterial manufacturers. Distribution runs through direct sales channels to pharmaceutical and biotechnology R&D departments, alongside specialized logistics for clinical trial materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nanomedicine market operates under significant supply constraints, where the specialized GMP manufacturing capacity for complex lipid nanoparticles props up pricing for platform technologies. This bottleneck limits rapid scale-up for new therapeutic candidates.
For Market Incumbents: Anchor market share by investing heavily in in-house GMP manufacturing expansion for critical nanocarriers. Strategic mergers and acquisitions targeting novel delivery platforms can mitigate threats from emerging biotech firms with specialized intellectual property. Reinforce competitive advantage through significant R&D investment in AI-driven nanoparticle design. Focus on navigating fragmented global regulatory standards to secure broader market access.
For New Entrants and Emerging Players: Capture white-space opportunities in regenerative medicine applications and AI-accelerated drug screening platforms. The most penetrable segments include niche diagnostic imaging agents and early-stage gene therapy delivery systems. A viable go-to-market angle involves platform licensing to large pharmaceutical companies, leveraging specialized intellectual property and agility. Develop robust preclinical data packages to attract strategic partnerships.
For Investors and Strategic Acquirers: The window for entry favors patient capital, given the long development timelines in nanomedicine. Long-term viability remains strong over a 5-10 year horizon, driven by unmet medical needs in oncology and gene therapy. Target acquisition profiles include specialized platform technology developers with robust intellectual property portfolios and promising early-stage clinical data. A key signal to watch as an inflection indicator is the establishment of clearer regulatory pathways for nanosimilars.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Expanding production capacity ensures consistent supply of high-quality nanocarriers for pharmaceutical companies. |
| AI-Driven Nanoparticle Design | Accelerating the discovery and optimization of novel nanomaterials streamlines drug development pipelines. |
| Platform Licensing Agreements | Securing access to versatile delivery technologies expands therapeutic pipelines for large pharmaceutical entities. |
| Clinical Trial Advancement in Gene Therapy | Progressing novel nanomedicines through trials unlocks significant market potential for genetic disorders. |
| Targeted M&A for Novel Nanomaterials | Acquiring specialized biotech firms enhances intellectual property portfolios and expands technological capabilities. |
Research Approach
Independent corroboration across industry reports, academic publications, and regulatory agency documents underwrites the qualitative findings within this nanomedicine analysis. Primary interviews with drug development executives, regulatory affairs leads, and materials scientists provided crucial insights. Secondary validation drew from FDA filings, EMA submissions, and patent databases. This approach ensures robust bottom-up and top-down triangulation for market sizing.
The forecast window was anchored to historical reference periods, establishing a baseline for nanomedicine market projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, application area, end user, and delivery mode. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included R&D investment trends and regulatory approval rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts and breakthrough material science discoveries. These forecasts reflect assumptions regarding clinical trial success rates and market access. A model refresh is warranted upon material change in major clinical trial outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Albendazole Drugs Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Amoxicillin Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market