
 Europe Stem Cell Therapy Market | 2026-2036
Europe Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stem Cell Therapy Market Foresight
The divergence between premium autologous therapies and commodity allogeneic platforms is realigning procurement patterns across European healthcare systems. Novartis AG anchors its position through sustained investment in CAR-T manufacturing infrastructure on the continent. Lonza Group AG leverages contract development capabilities to control supply chains for emerging cell therapy developers. Mesoblast Limited differentiates through specialized allogeneic mesenchymal stem cell platforms targeting graft-versus-host disease.
Stem cell therapy encompasses the isolation, expansion, and clinical delivery of undifferentiated or partially differentiated cells capable of self-renewal and tissue-specific differentiation, typically requiring cryopreservation at below -150°C and expansion in GMP-compliant cleanroom facilities to maintain viability and phenotypic stability. Its primary commercial purpose centers on regenerating damaged tissues, modulating immune responses, and replacing dysfunctional cell populations in conditions with limited therapeutic alternatives. Mesenchymal stem cells occupy the largest revenue pool due to established manufacturing protocols and broad immunomodulatory applicability across orthopedic and autoimmune indications. Hematopoietic stem cells represent the most mature segment, while neural stem cells command premium pricing amid scarcity of clinically validated sources for neurological disorder applications.
The European Medicines Agency (EMA) enforces centralized marketing authorization for advanced therapy medicinal products, while the EU Clinical Trials Regulation streamlines multi-national study protocols across member states. REACH and the EU Tissue and Cells Directive establish stringent donor traceability and quality benchmarks that shape manufacturing location decisions and market access timelines. Stakeholders must monitor evolving reimbursement negotiations between national health technology assessment bodies and manufacturers, as these determinations will dictate which therapy modalities achieve sustainable commercial scale.
Market Dynamics
Hospital procurement departments across Europe are consolidating vendor relationships for autologous stem cell therapies, compressing supplier margins while elevating quality assurance requirements for GMP-compliant manufacturing facilities.
Growth Catalysts
- EU Clinical Trials Regulation harmonization:Cross-border study protocols now activate simultaneously across member states, collapsing trial initiation timelines for multi-national sponsors. Germany's university medical centers leverage this framework to anchor Phase II and III cell therapy trials.
- Cryopreservation infrastructure expansion:Liquid nitrogen storage networks at below -150°C are proliferating through contract manufacturing organizations, enabling distributed cell banking without viability loss.
- Orthopedic regenerative medicine:Knee osteoarthritis and spinal disc degeneration patients are driving hospital-based procurement of mesenchymal stem cell interventions as surgical alternatives face reimbursement scrutiny.
Market Restraints
- Donor traceability compliance costs:The EU Tissue and Cells Directive mandates exhaustive chain-of-custody documentation, elevating per-batch quality assurance expenditure for allogeneic platforms.
- Cleanroom capacity concentration:GMP-compliant expansion facilities cluster in Switzerland and Germany, creating geographic supply bottlenecks for southern European therapy developers.
- Hematopoietic stem cell maturity ceiling:Established bone marrow transplant protocols leave limited pricing power for incremental autologous innovations in oncology indications.
Strategic Opportunities
- France's ATMP acceleration pathway:The country's national pharmaceutical regulator ANSM offers parallel scientific advice and marketing authorization procedures, compressing time-to-market for advanced therapy developers.
- Neurological disorder applications:Parkinson's disease and multiple sclerosis represent underpenetrated indications where neural stem cell scarcity commands premium positioning.
- Digital chain-of-custody systems:Blockchain-enabled temperature logging is converging with cryogenic logistics, enabling real-time viability verification for cross-border cell shipments.
Industry Challenges
- GMP cleanroom construction timelines:Facility qualification periods extend 18-24 months, delaying manufacturing scale-up for approved therapies and trapping capital in non-revenue-generating assets.
- Cell therapy-specific workforce scarcity:Qualified aseptic processing technicians and cryopreservation specialists command compensation premiums that inflate operating expenditure at expansion-stage facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stem Cell Therapy Market |
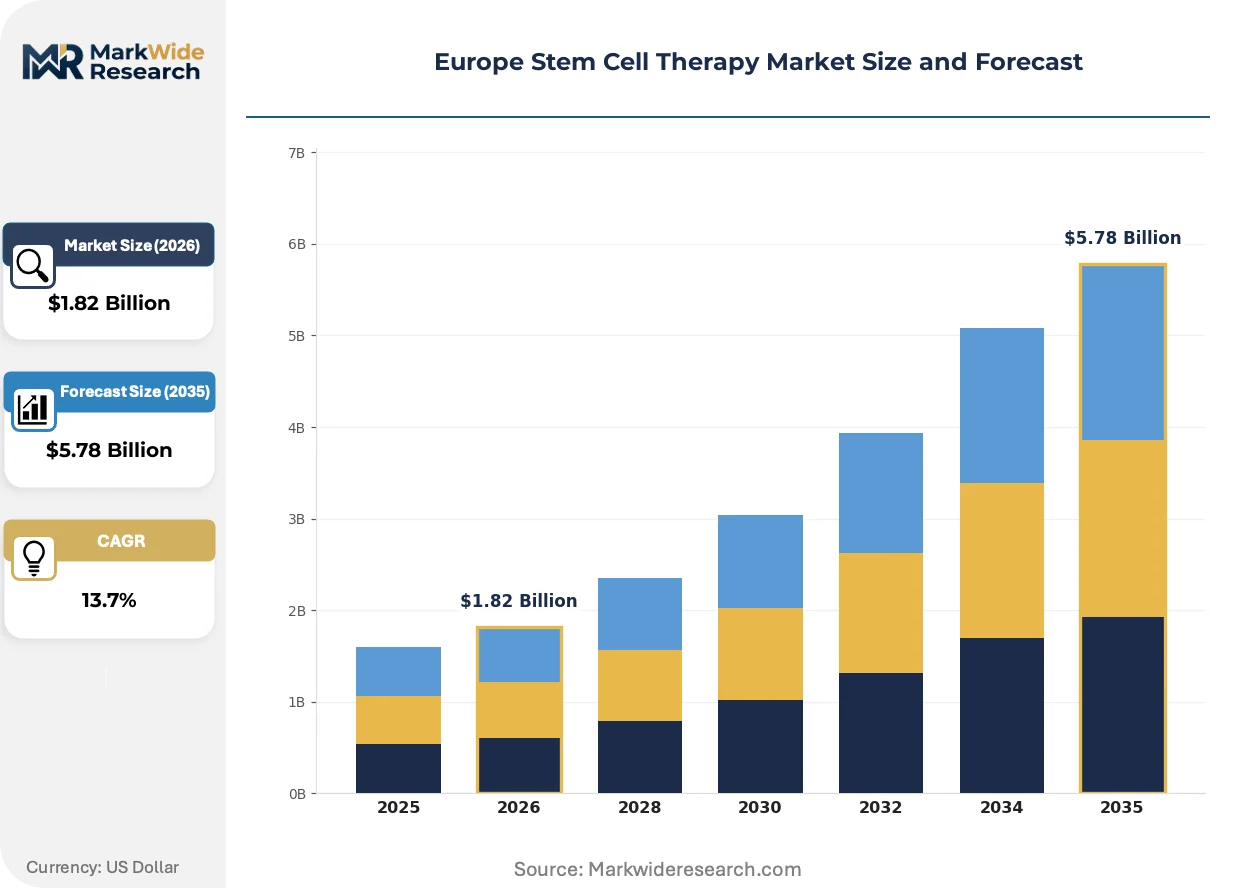
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal Stem Cells, Hematopoietic Stem Cells, Adipose Stem Cells, Neural Stem Cells Therapy Area: Cardiovascular Diseases, Neurological Disorders, Orthopedic Injuries, Autoimmune Diseases Delivery Mode: Intravenous Injection, Local Injection, Intra-articular Injection, Surgical Implantation End User: Hospitals, Research Institutions, Specialized Clinics, Regenerative Medicine Facilities |
| Companies Covered | Takeda Pharmaceutical Company Limited, Novartis AG, Gilead Sciences, Bristol-Myers Squibb, Lonza Group AG, STEMCELL Technologies, JCR Pharmaceuticals Co., Ltd, Mesoblast Limited, ReNeuron Group PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stem Cell Therapy Market Shifts & Advancements
Manufacturing automation and closed-system bioreactors are compressing cost structures for mesenchymal stem cell expansion, while regulatory science initiatives at EMA accelerate novel platform qualification pathways.
Closed-system bioreactor technology is converging with automated media exchange systems, eliminating open-manipulation contamination risks during mesenchymal stem cell expansion. German contract manufacturers are adopting these platforms at pace to reduce cleanroom footprint requirements. This convergence is enabling distributed manufacturing models that relocate production closer to hospital infusion sites.
EMA's regulatory science initiatives on cell therapy manufacturing comparability are clarifying acceptable process changes without full clinical re-validation. Sponsors gain flexibility to transfer production between facilities or upgrade equipment without triggering new trials. Early-phase developers in the Netherlands and Belgium are exploiting this guidance to accelerate technology transfer from academic labs to GMP facilities.
Hospital pharmacy departments are consolidating stem cell therapy procurement under centralized advanced therapy medicinal product committees, displacing individual clinician-driven purchasing. These committees mandate health technology assessment alignment before formulary inclusion. Spain's regional health systems exhibit this behavioral shift most visibly, with Andalusia and Catalonia pioneering consolidated tender mechanisms for CAR-T and stem cell products.
Europe Stem Cell Therapy Market Segmentation
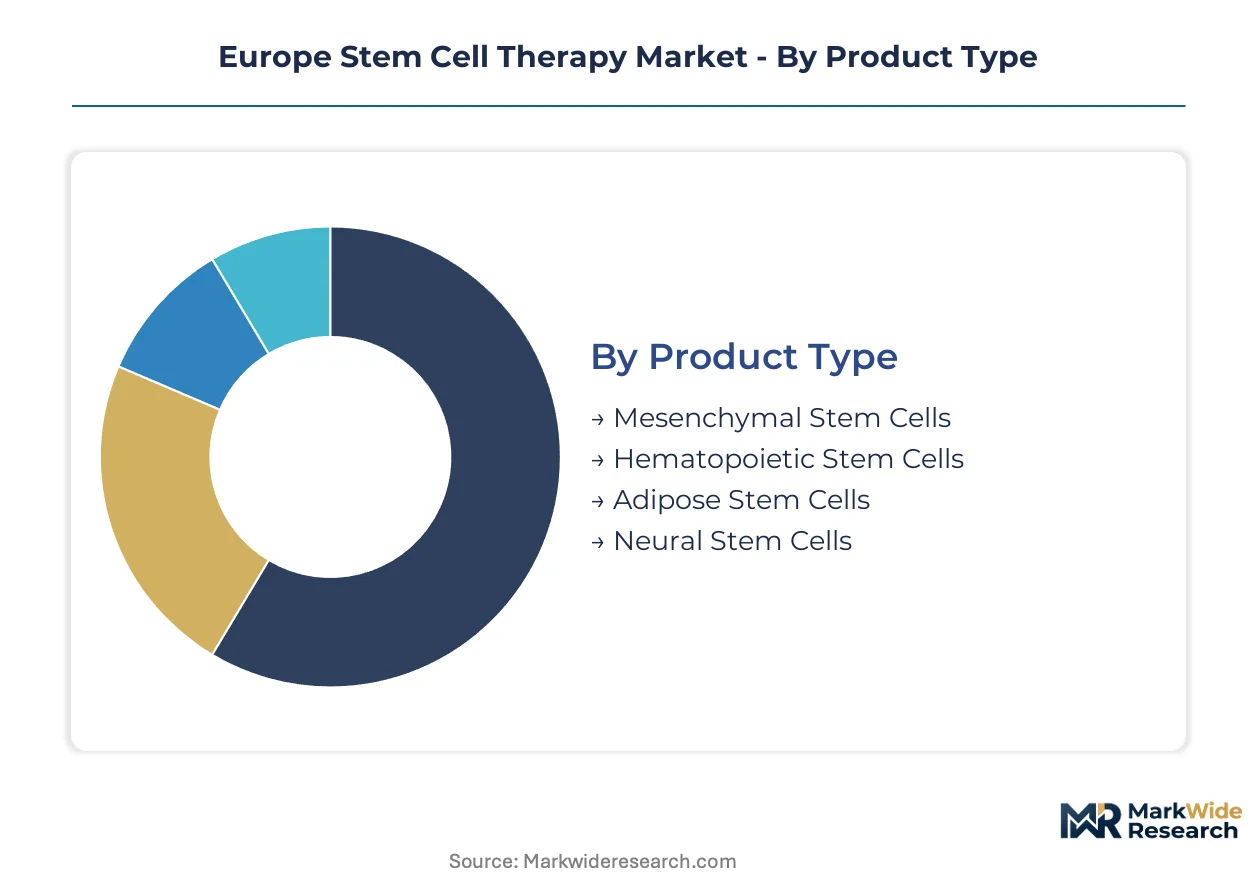
Segmentation in the Europe Stem Cell Therapy Market reveals how therapeutic platforms, clinical applications, and delivery infrastructure align with reimbursement pathways and manufacturing scale. Procurement committees at university medical centers use these categories to evaluate formulary inclusion against health technology assessment criteria.
Product Type:
Customization intensity varies sharply across this category, from standardized allogeneic platforms to patient-specific autologous manufacturing requiring dedicated cleanroom slots.
- Mesenchymal Stem Cells:These multipotent stromal cells derived from bone marrow, adipose tissue, or umbilical cord expand robustly in bioreactor systems. Demand concentrates in German orthopedic centers treating knee osteoarthritis, where hospital procurement committees prioritize established GMP protocols over novel platforms.
- Hematopoietic Stem Cells:CD34+ progenitor cells from bone marrow or mobilized peripheral blood constitute the most mature commercial segment. Spain's regional health systems drive volume through consolidated tender mechanisms for autologous transplant protocols, though pricing power remains constrained by treatment commoditization.
- Adipose Stem Cells:Lipoaspirate-derived stromal vascular fraction requires minimal expansion before clinical use.
- Neural Stem Cells:Scarcity of clinically validated sources limits supply to specialized French and UK neurological centers.
Most installed capacity flows through Mesenchymal Stem Cells. Expansion is steepest in Neural Stem Cells.
Therapy Area:
Reimbursement volatility distinguishes this category, with established oncology protocols contrasting against emerging neurological indications lacking health technology assessment precedent.
- Cardiovascular Diseases:Intramyocardial delivery of autologous bone marrow cells targets ischemic heart failure patients ineligible for revascularization. Italian cardiac centers anchor continental trial activity, though regulatory uncertainty around primary endpoint validation constrains procurement scale.
- Neurological Disorders:Parkinson's disease and multiple sclerosis applications command premium positioning amid donor cell scarcity and complex blood-brain barrier penetration requirements. Dutch academic medical centers pioneer intrathecal delivery protocols.
- Orthopedic Injuries:Intra-articular mesenchymal stem cell injections for cartilage repair face mixed reimbursement decisions across German sickness funds.
- Autoimmune Diseases:Systemic lupus erythematosus and Crohn's disease trials concentrate in French ATMP acceleration pathway cohorts.
Procurement volume concentrates in Orthopedic Injuries. Regulatory momentum is strongest in Neurological Disorders.
Delivery Mode:
Technical complexity and site-of-care requirements create distinct cost structures across this category, from ambulatory infusion to operating theater implantation.
- Intravenous Injection:Systemic administration enables outpatient delivery for immunomodulatory indications. Belgian contract manufacturing organizations optimize cryopreservation logistics for cross-border IV infusion networks.
- Local Injection:Targeted delivery to soft tissue or wound beds requires minimal imaging support.
- Intra-articular Injection:Image-guided knee and shoulder administration dominates Spanish specialized clinic procurement.
- Surgical Implantation:Open procedures for spinal disc or myocardial delivery require hospital operating theater allocation and extended recovery stays.
Ambulatory capacity concentrates in Intravenous Injection. Capital investment is shifting toward Intra-articular Injection suites.
End User:
Centralized versus distributed care models fragment procurement authority across this category, with hospital committees displacing individual clinician purchasing decisions.
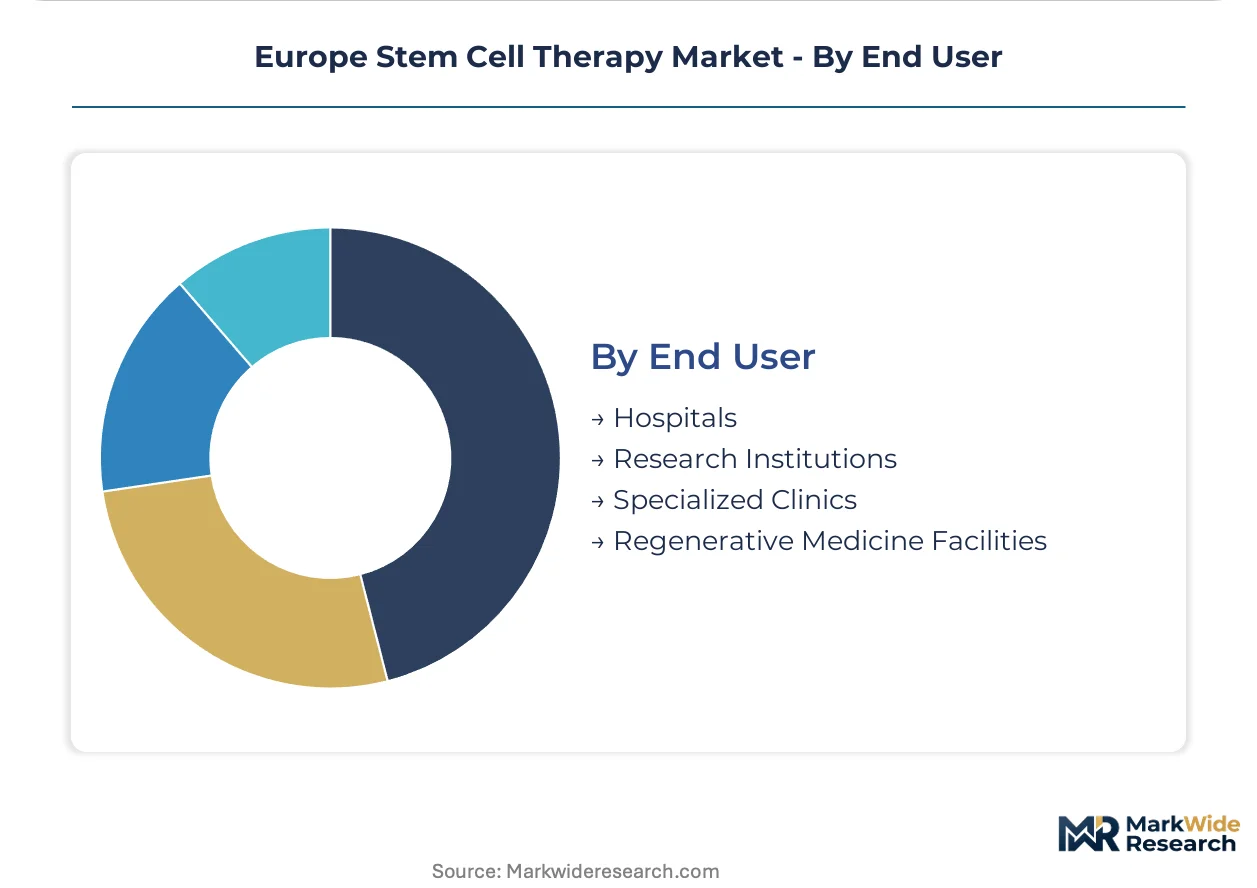
- Hospitals:University medical centers in Germany and Switzerland control the largest share of Phase II and III trial enrollment. Andalusia and Catalonia pioneer consolidated advanced therapy medicinal product committees that mandate health technology assessment alignment.
- Research Institutions:Academic GMP facilities in the Netherlands and Belgium accelerate technology transfer from discovery labs to clinical manufacturing.
- Specialized Clinics:Focused orthopedic and aesthetic practices drive out-of-pocket adipose stem cell procedures in regulatory gray zones.
- Regenerative Medicine Facilities:Dedicated cell therapy centers in France leverage ANSM parallel scientific advice to compress development timelines.
Manufacturing partnerships concentrate through Hospitals. New entrant growth is fastest in Regenerative Medicine Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryopreservation technicians and GMP-qualified aseptic processing staff concentrate in German and Swiss university medical centers, anchoring the continent's clinical trial infrastructure and manufacturing scale-up capacity.
Germany
University medical centers in Heidelberg and Berlin drive Phase II and III enrollment for autologous CAR-T protocols. The country's national pharmaceutical regulator, the Federal Institute for Drugs and Medical Devices (BfArM), enforces centralized ATMP compliance that shapes multi-site trial design. Bavaria's Munich cluster hosts the densest concentration of GMP cleanroom facilities serving southern European therapy developers.
France
Parisian neurological centers command premium positioning for neural stem cell scarcity applications in Parkinson's disease. ANSM's parallel scientific advice and marketing authorization procedures compress development timelines for advanced therapy developers. The Île-de-France region anchors continental trial activity for intrathecal delivery protocols developed at Dutch academic medical centers.
United Kingdom
London and Cambridge biotech corridors specialize in early-stage allogeneic platform discovery transitioning to GMP manufacturing. The Medicines and Healthcare products Regulatory Agency (MHRA) maintains alignment with EMA standards while preserving independent accelerated assessment pathways. Scottish cell therapy facilities exploit regulatory science guidance on manufacturing comparability to accelerate technology transfer.
Spain
Andalusia and Catalonia consolidate procurement authority under regional advanced therapy medicinal product committees mandating health technology assessment alignment. The Spanish Agency for Medicines and Health Products (AEMPS) oversees decentralized tender mechanisms for hematopoietic stem cell transplant protocols. Madrid's hospital pharmacy departments displace individual clinician purchasing for CAR-T and stem cell products.
Switzerland
Swissmedic's stringent donor traceability requirements elevate per-batch quality assurance expenditure for cross-border allogeneic supply. Basel and Zurich contract manufacturing organizations control cryogenic logistics networks enabling real-time viability verification. The country's cleanroom capacity concentration creates geographic supply bottlenecks for southern European therapy developers seeking expansion slots.
Europe Stem Cell Therapy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European stem cell therapy landscape, with integrated pharmaceutical conglomerates controlling manufacturing infrastructure while specialized biotech developers retain platform IP. The market structure tilts toward consolidation at the commercialization stage, where GMP facility ownership erects barriers to scale. Three archetypes dominate: integrated pharma with captive cell therapy divisions, contract development and manufacturing organizations with distributed cryopreservation networks, and pure-play allogeneic platform specialists. Competitive intensity centers on cleanroom capacity expansion and strategic partnerships bridging discovery-stage IP with late-stage manufacturing assets.
Among Swiss-integrated pharmaceutical conglomerates, Novartis AG and Lonza Group AG exemplify divergent strategic positioning—one anchoring CAR-T manufacturing infrastructure investment, the other leveraging contract development capabilities to control supply chains for emerging developers. Australian-listed Mesoblast Limited occupies a specialized position within the allogeneic mesenchymal stem cell archetype, differentiating through platform applications targeting immunomodulatory indications. These three entities collectively represent the capital deployment patterns reshaping vendor relationships with hospital procurement departments.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Novartis AG |
| Gilead Sciences |
| Bristol-Myers Squibb |
| Lonza Group AG |
| STEMCELL Technologies |
| JCR Pharmaceuticals Co., Ltd |
| Mesoblast Limited |
| ReNeuron Group PLC |
| Others |
Supply & Pricing Matrix
Autologous-versus-allogeneic manufacturing intensity bifurcation shapes procurement economics across European healthcare systems, with patient-specific therapies commanding premium positioning while standardized platforms compete on batch scale. Hospital formulary committees in Germany and Switzerland exploit this divergence to negotiate volume commitments against GMP facility access, compressing margins for contract manufacturers serving southern European developers lacking captive cleanroom capacity.
Pricing Analysis
Bundled cryopreservation-and-delivery contracts dominate autologous segments while unbundled cell-banking fees characterize allogeneic procurement. Three-tier pricing structure across premium, standard, and economy levels tracks GMP certification depth and donor traceability documentation completeness. Cost compression in allogeneic mesenchymal stem cell batches is intensifying because Spanish regional health systems consolidate tender mechanisms. Academic medical centers exhibit lowest price sensitivity due to trial enrollment imperatives, while specialized aesthetic clinics face acute margin pressure from out-of-pocket patient churn.
Supply Chain Analysis
Workforce scarcity for qualified aseptic processing technicians concentrates manufacturing gravity in Germany, Switzerland, and the Netherlands, where training pipelines feed GMP facility expansion. Cryogenic storage vessels, single-use bioreactor bags, and liquid nitrogen logistics networks constitute critical input dependencies. Single-source vulnerability runs through Swiss cleanroom capacity concentration for southern European therapy developers. Distribution runs through hospital pharmacy departments consolidating under advanced therapy medicinal product committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by hospital procurement committees shifting criteria toward health technology assessment alignment and documented clinical outcomes over novel platform claims.
For Market Incumbents: Acquire GMP cleanroom capacity in German and Swiss manufacturing clusters to preempt emerging entrant scale-up attempts. Defensive consolidation demands backward integration into cryogenic logistics networks controlling cross-border cell viability verification, while channel control through exclusive hospital pharmacy partnerships anchors formulary positioning against allogeneic platform commoditization. For New Entrants and Emerging Players: Capture neurological disorder applications in French ATMP acceleration pathway cohorts where neural stem cell scarcity limits incumbent response speed. White-space concentration in intrathecal delivery protocols for Parkinson's disease at Dutch academic medical centers offers penetrable entry points. Go-to-market execution hinges on ANSM parallel scientific advice engagement compressing regulatory timelines relative to centralized EMA routes. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play allogeneic mesenchymal stem cell platform specialists possessing validated immunomodulatory indications and transferable GMP protocols. Long-term viability across the analysis window favors developers with demonstrated manufacturing comparability guidance exploitation enabling facility transfer without clinical re-validation. Signal to watch: reimbursement determinations from German sickness funds establishing precedent for orthopedic regenerative medicine expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Cleanroom Capacity Expansion | Swiss and German facility ownership erects scale barriers trapping capital-constrained competitors. |
| ANSM Parallel Scientific Advice Engagement | French regulatory pathway compresses development timelines for advanced therapy developers. |
| Blockchain-Enabled Cryogenic Logistics | Real-time temperature verification enables cross-border cell shipments with viability guarantees. |
| Hospital Pharmacy Partnership Consolidation | Andalusia and Catalonia committee structures displace clinician-driven purchasing authority. |
| Neural Stem Cell Platform Validation | Parkinson's disease scarcity applications command premium positioning amid limited supply sources. |
Research Methodology
Coverage spans Western Europe and select Eastern European markets, with primary inputs from each regional cluster informing triangulation. Primary interviews with hospital procurement managers, GMP facility operations directors, regulatory affairs specialists at EMA and national agencies, and advanced therapy medicinal product committee chairs combined with secondary validation. Secondary sources encompass EMA centralized marketing authorization filings, EU Clinical Trials Regulation implementation reports, hospital formulary databases, and national health technology assessment body determinations. Bottom-up therapy-level demand modeling and top-down healthcare expenditure allocation checks anchored forecast integrity.
Granularity-level modeling tracked product type, therapy area, delivery mode, and end user dimensions at the country level across the projection horizon. CAGRs derived from therapy-specific enrollment trajectories, reimbursement pathway maturation timelines, and manufacturing capacity expansion announcements. Industry-specific forecast inputs incorporated GMP cleanroom construction pipeline tracking and cryopreservation infrastructure deployment rates.
Underlying measurement precision varies by segment; hematopoietic stem cell and mesenchymal stem cell categories carry tighter precision than neural stem cell applications given trial enrollment visibility. Forecasts reflect documented assumptions on regulatory harmonization progress and reimbursement negotiation outcomes. Material deviation in EMA manufacturing comparability guidance implementation or German sickness fund orthopedic regenerative medicine coverage determinations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market