
 Inherited Orphan Blood Disorders Therapeutics Market | 2026-2036
Inherited Orphan Blood Disorders Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Inherited Orphan Blood Disorders Therapeutics Market Outlook
European biologics manufacturing is shifting toward dedicated gene therapy capacity. Pfizer leverages its rare disease infrastructure to anchor production of novel hemophilia treatments. Novartis sustains leadership in sickle cell gene therapy through specialized manufacturing networks. Bristol Myers Squibb competes on hematopoietic stem cell platforms with differentiated cell processing capabilities.
Inherited orphan blood disorders therapeutics comprise pharmaceutical and biologic interventions targeting monogenic hematologic conditions including hemoglobinopathies, coagulation factor deficiencies, and bone marrow failure syndromes, administered through transfusion, cellular modification, or genetic correction to restore functional blood cell production or clotting cascade activity. Gene therapy dominates current pipeline investment while erythropoiesis stimulating agents retain established reimbursement in thalassemia management. Hematopoietic stem cell transplantation occupies the premium intervention tier for severe aplastic anemia. Intravenous delivery mode leads hospital-based administration though subcutaneous formulations are gaining traction in home healthcare settings.
FDA orphan drug exclusivity provisions and EMA's priority medicines scheme shape clinical development timelines and market access trajectories for novel therapeutics. The EU AI Act introduces algorithmic validation requirements for diagnostic tools used in patient stratification for gene therapy eligibility. Japan's PMDA sakigake designation accelerates review for innovative hematologic treatments. Stakeholders must monitor evolving manufacturing standards for autologous cell therapies and adaptive reimbursement models for one-time curative interventions.
Market Dynamics
Gene therapy manufacturing capacity constraints are forcing hematology centers to restructure patient intake protocols and treatment sequencing, creating bottlenecks that reshape competitive positioning across the value chain.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase III timelines for hemophilia gene therapies, enabling earlier commercial access. Pediatric treatment centers in the United States prioritize enrollment in these streamlined trials.
- EMA Priority Medicines Scheme:The framework grants scientific advice and accelerated assessment for sickle cell interventions, reducing regulatory uncertainty. European hematology networks align clinical development with these timelines.
- Japan's Sakigake Designation:PMDA's fast-track mechanism attracts orphan drug investment toward hematologic innovations. Japanese academic medical centers expand gene therapy infrastructure to capture these incentives.
Market Restraints
- Viral Vector Supply Concentration:Plasmid DNA and AAV manufacturing capacity clusters in select contract development organizations, creating single-source dependencies. Production delays cascade through autologous therapy pipelines.
- Reimbursement Complexity:Germany's G-BA assessment procedures for one-time curative therapies create payment uncertainty. Hospital pharmacists delay formulary adoption pending outcome-based contract frameworks.
- Allogeneic Stem Cell Substitution:Cord blood and haploidentical transplantation advances threaten gene therapy addressable populations in severe aplastic anemia. Transplant centers maintain dual capability.
Strategic Opportunities
- Home Healthcare Administration:Subcutaneous factor replacement formulations enable outpatient hemophilia management. Specialty pharmacies in the United States build infusion nursing networks to capture this shift.
- Diagnostic-Stratified Eligibility:Next-generation sequencing for genotype-phenotype correlation expands addressable populations. Molecular pathology laboratories partner with gene therapy developers on companion algorithms.
- EU AI Act Compliance:Algorithmic validation requirements for patient selection tools create service revenue streams. Diagnostic platform vendors integrate regulatory consulting into software offerings.
Industry Challenges
- Vector Manufacturing Workforce Gap:Cell culture and purification expertise for GMP-grade viral production remains scarce. Training programs at specialized manufacturing institutes cannot scale to demand.
- Autologous Supply Chain Complexity:Patient-specific cell collection, cryopreservation, and logistics coordination require bespoke infrastructure. Treatment centers struggle with cold chain integrity across multi-site networks.
- Intellectual Property Fragmentation:CRISPR licensing, viral vector patents, and cell processing methods create royalty stacking. Developers negotiate cross-licensing agreements that extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inherited Orphan Blood Disorders Therapeutics Market |
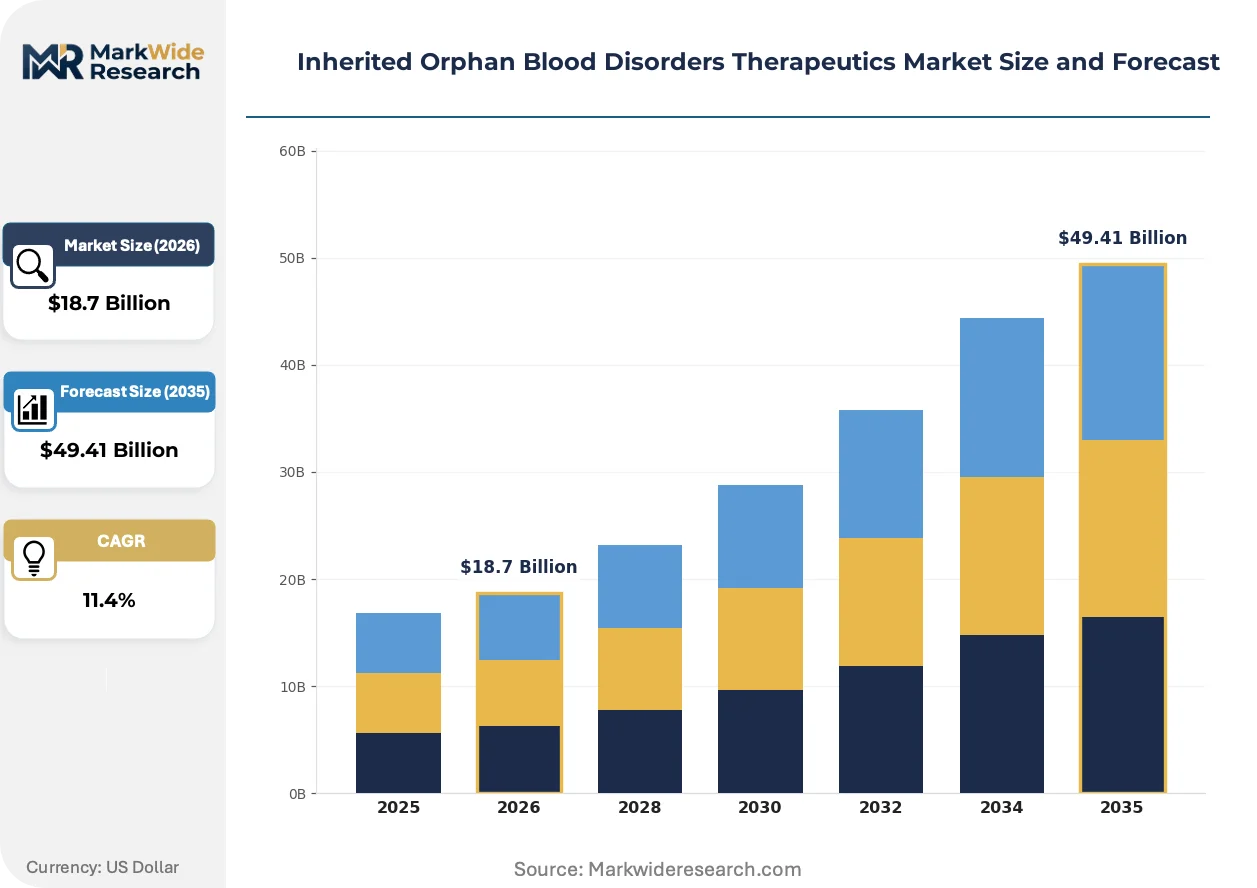
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusion, Gene Therapy, Hematopoietic Stem Cell Transplantation, Erythropoiesis Stimulating Agents Delivery Mode: Intravenous, Subcutaneous, Oral, Intraosseous End User: Hospitals, Specialty Clinics, Home Healthcare, Research Institutions Indication: Sickle Cell Disease, Hemophilia, Thalassemia, Aplastic Anemia |
| Companies Covered | AstraZeneca, Pfizer, Novartis, Bristol Myers Squibb, Bayer, F. Hoffmann-La Roche, Takeda Pharmaceutical Company, PTC Therapeutics, BioMarin Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inherited Orphan Blood Disorders Therapeutics Market Strategic Shifts
Lentiviral and AAV vector engineering is compressing treatment timelines while CRISPR-based editing expands addressable genotypes. These platform advances intersect with regulatory adaptation and care delivery restructuring.
Base-editing technologies are integrating precision cytosine and adenine modification to correct sickle cell mutations without double-strand breaks. Pediatric hematology centers in Boston and Philadelphia pilot these protocols for adolescent populations. The technology is integrating into existing CAR-T manufacturing infrastructure, reducing dedicated facility capex requirements.
EMA's adaptive pathways guidance for regenerative medicines enables rolling data submission for gene therapies. Manufacturers submit real-world evidence modules alongside controlled trial readouts. Hemophilia B programs in the Netherlands and Denmark leverage this framework to compress approval-to-reimbursement intervals.
Patient advocacy organizations now directly fund early-stage academic research and negotiate priority review vouchers. The Hemophilia Federation of America and European Haemophilia Consortium channel membership dues toward preclinical vector development. This philanthropic capital fills gaps left by retreating venture investment in rare disease platforms.
Inherited Orphan Blood Disorders Therapeutics Market Segmentation
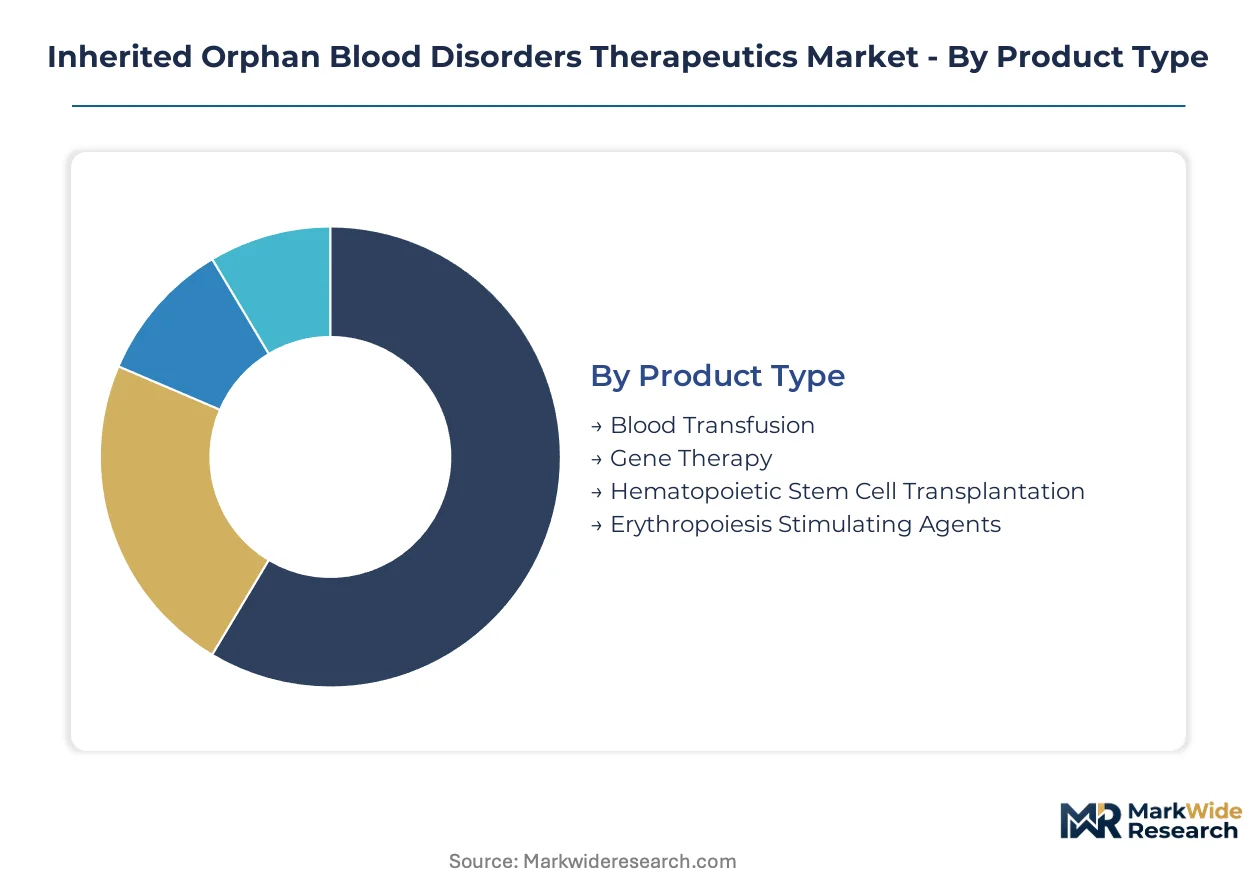
Patient stratification for gene therapy eligibility demands precise alignment between product classification and regulatory pathway. Segmentation reveals how manufacturing complexity, administration setting, and disease severity intersect to determine commercial access and reimbursement velocity.
Product Type:
FDA breakthrough therapy designation and EMA priority medicines eligibility vary sharply across these categories, with gene therapies commanding dedicated regulatory resources while transfusion products navigate established blood banking standards.
- Gene Therapy:Lentiviral and AAV vectors deliver functional genetic material to hematopoietic stem cells, requiring GMP-grade viral manufacturing and patient-specific cell processing. Demand concentrates in Boston, Philadelphia, and London pediatric hematology centers where specialized apheresis and cryopreservation infrastructure supports autologous workflows. Manufacturing bottlenecks at contract development organizations force treatment sequencing protocols that extend patient wait times.
- Hematopoietic Stem Cell Transplantation:Allogeneic donor cell infusion replaces defective marrow, demanding HLA-matching algorithms and conditioning regimen optimization. German university hospitals in Heidelberg and Hamburg anchor European volume, leveraging established donor registries and transplant coordination networks. Cord blood banking advances in Tokyo and Osaka expand haploidentical alternatives that compete with gene therapy addressable populations.
- Blood Transfusion:Red cell and platelet support manages chronic anemia and bleeding complications through standardized blood banking protocols.
- Erythropoiesis Stimulating Agents:Recombinant erythropoietin analogs reduce transfusion burden in thalassemia through subcutaneous administration.
Leading the category by volume: Blood Transfusion. Growing fastest: Gene Therapy.
Delivery Mode:
Administration route determines care setting economics, with hospital-based infusion requiring distinct reimbursement coding from home healthcare protocols that specialty pharmacies are assembling.
- Intravenous:Central venous access enables high-volume factor replacement and gene therapy vector infusion, tethering treatment to hospital pharmacy oversight. United States academic medical centers dominate this segment, with Cincinnati Children's and Children's Hospital of Philadelphia anchoring gene therapy administration volume. Reimbursement complexity around hospital outpatient prospective payment systems creates formulary adoption friction.
- Subcutaneous:Prophylactic factor concentrates and erythropoiesis stimulating agents enable outpatient hemophilia management, shifting care toward home infusion nursing networks. Japanese hemophilia treatment centers in Tokyo and Osaka pilot patient self-administration programs that reduce hospital dependency. Specialty pharmacies in the United States build regional nursing capacity to capture this migration.
- Oral:Small-molecule stabilizers and iron chelation support chronic thalassemia management through patient-directed dosing.
- Intraosseous:Emergency vascular access for acute bleeding episodes in hemophilia with inhibitor complications.
Dominating procedure volume: Intravenous. Expanding most quickly: Subcutaneous.
End User:
Site-of-care economics diverge sharply, with hospital outpatient departments capturing gene therapy technical fees while home healthcare platforms absorb factor replacement volume through pharmacy benefit management channels.
- Hospitals:Tertiary centers command gene therapy technical fees and transplant coordination, requiring specialized apheresis units and GMP-adjacent cell processing labs. United States children's hospitals in Boston, Houston, and San Francisco anchor national referral networks. EMA's advanced therapy medicinal products framework shapes European hospital accreditation requirements.
- Home Healthcare:Subcutaneous factor prophylaxis and oral chelation shift chronic disease management from institutional to domestic settings. German home care nursing networks in Bavaria and North Rhine-Westphalia specialize in hemophilia infusion protocols. United States specialty pharmacies build captive nursing capacity to secure payer contracts.
- Specialty Clinics:Dedicated hemophilia treatment centers and thalassemia programs concentrate expertise and clinical trial access.
- Research Institutions:Academic medical centers host early-phase gene therapy protocols and natural history studies.
Capturing majority volume: Hospitals. Gaining share fastest: Home Healthcare.
Indication:
Disease prevalence and severity stratification determine addressable population economics, with sickle cell disease commanding pipeline investment while hemophilia retains established replacement therapy markets.
- Sickle Cell Disease:CRISPR and lentiviral gene therapies target beta-globin mutations, with pediatric eligibility criteria expanding addressable cohorts. United States sickle cell centers in Atlanta, Baltimore, and Chicago anchor clinical trial enrollment. FDA accelerated approval pathways compress development timelines for adolescent populations.
- Hemophilia:Factor VIII and IX gene therapies promise functional cure, threatening established prophylaxis markets. German hemophilia treatment centers in Munich and Frankfurt coordinate real-world evidence collection for G-BA reimbursement assessments. Extended half-life recombinant factors retain market share pending gene therapy manufacturing scale.
- Thalassemia:Transfusion-dependent and non-transfusion-dependent subtypes stratify intervention intensity and chelation requirements.
- Aplastic Anemia:Severe forms demand immunosuppression or transplantation, with gene therapy trials emerging for telomere biology disorders.
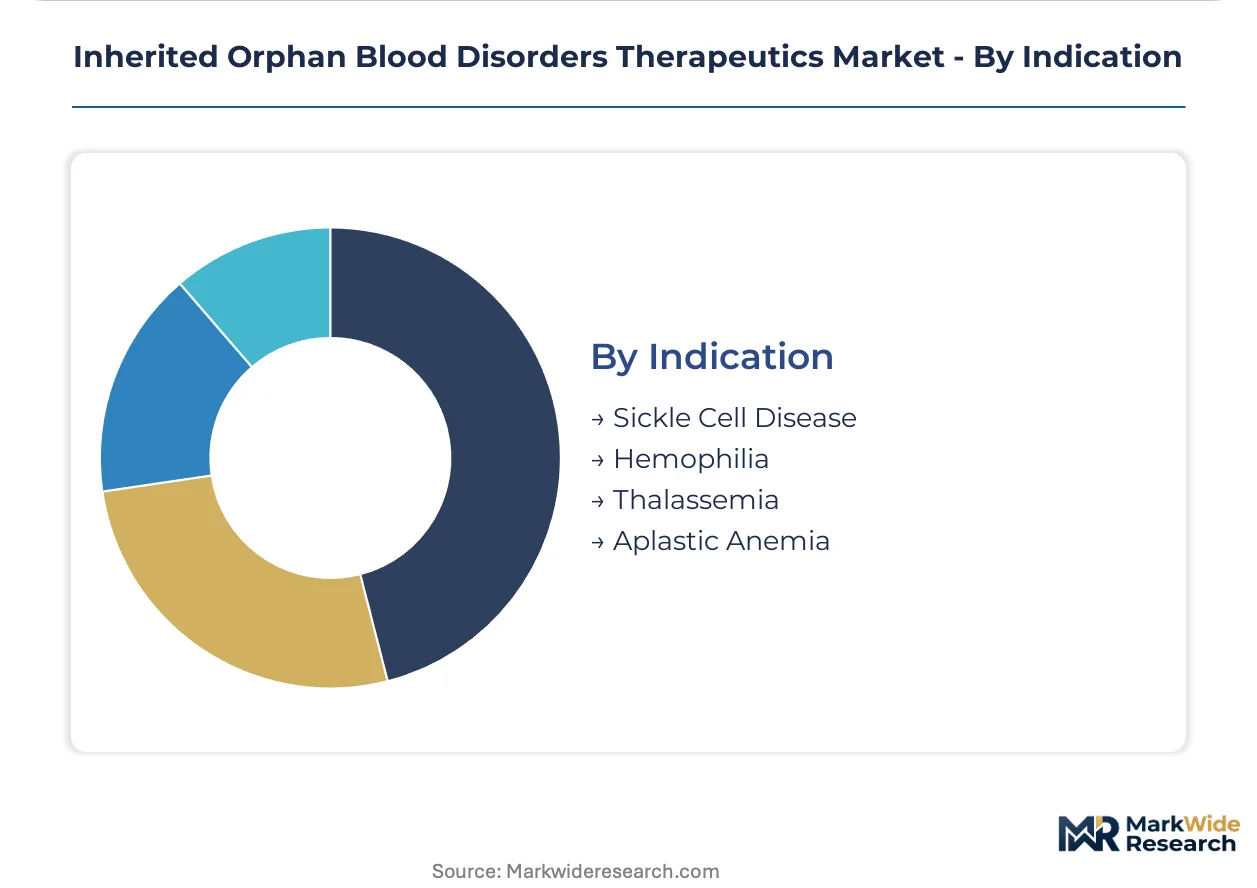
Holding largest patient population: Sickle Cell Disease. Steepest expansion trajectory: Hemophilia gene therapy addressable cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viral vector manufacturing clusters in Massachusetts, Basel, and Tokyo anchor therapeutic production capacity. Specialized hematology centers concentrate in cities with established apheresis infrastructure and GMP-adjacent cell processing capabilities.
United States
Pediatric gene therapy demand concentrates at academic medical centers in Boston, Philadelphia, and Houston. FDA accelerated approval pathways compress Phase III timelines for hemophilia and sickle cell interventions. Cincinnati Children's Hospital and Children's Hospital of Philadelphia anchor national referral networks for autologous cell collection and cryopreservation.
Germany
University hospitals in Heidelberg, Hamburg, and Munich coordinate European transplant volume through established donor registries. G-BA assessment procedures for one-time curative therapies create reimbursement negotiation frameworks. The EMA's advanced therapy medicinal products framework shapes hospital accreditation requirements across Bavaria and North Rhine-Westphalia.
Japan
PMDA sakigake designation attracts orphan drug investment toward hematologic innovations. Academic medical centers in Tokyo and Osaka expand gene therapy infrastructure to capture fast-track incentives. Cord blood banking advances in Kansai and Kanto regions expand haploidentical transplantation alternatives.
United Kingdom
NHS specialized commissioning for rare blood disorders concentrates treatment at designated hemophilia centers in London, Manchester, and Birmingham. MHRA rolling review mechanisms align with EMA adaptive pathways for regenerative medicines. Oxford and Cambridge research clusters anchor early-phase gene therapy protocols.
Switzerland
Swissmedic's streamlined assessment for advanced therapies complements EMA centralized procedures. Basel and Zurich host viral vector manufacturing capacity serving European clinical trial supply. The country's bilateral recognition agreements facilitate parallel submission strategies for gene therapy developers.
Inherited Orphan Blood Disorders Therapeutics Market Competitive Environment
Global majors compete with regional champions across vector manufacturing and cell processing capabilities. The market structure consolidates around three tiers: integrated pharmaceutical conglomerates with rare disease infrastructure, specialized biotech developers with platform technologies, and contract manufacturing organizations with GMP-grade viral production expertise. Strategic moves center on manufacturing capacity expansion and cross-licensing agreements to resolve intellectual property fragmentation.
Within the integrated pharmaceutical tier, Pfizer and Novartis occupy positions anchored by specialized manufacturing networks. Bristol Myers Squibb sits within the hematopoietic stem cell platform segment with differentiated cell processing capabilities. These three exemplify how established rare disease infrastructure determines competitive positioning in a market where autologous supply chain complexity creates high barriers to entry.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Novartis |
| Bristol Myers Squibb |
| Bayer |
| F. Hoffmann-La Roche |
| Takeda Pharmaceutical Company |
| PTC Therapeutics |
| BioMarin Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Curative versus chronic management paradigms split the market into divergent pricing architectures, with one-time gene therapy commanding premium reimbursement negotiations while transfusion-dependent regimens anchor value-based contracting. This bifurcation manifests in supply chain configurations where autologous cell processing demands patient-specific logistics, and standardized plasma products flow through established blood banking networks.
Pricing Analysis
Warranty and outcome guarantee bundling separates gene therapy pricing from conventional factor replacement, with manufacturers offering conditional rebates tied to durable clinical response. Three-tier pricing structure across premium curative interventions, extended half-life biologics, and standard replacement factors reflects manufacturing complexity and duration of benefit. Cost compression in chronic replacement segments is intensifying as biosimilar entry erodes originator margins. Hospital procurement committees exhibit highest price sensitivity for transfusion products, while specialized gene therapy centers accept premium pricing given limited therapeutic alternatives.
Supply Chain Analysis
Workforce scarcity for GMP-grade viral vector production concentrates manufacturing expertise in Massachusetts, Basel, and North Carolina research triangles. Plasmid DNA feedstock, specialized cell culture media, and cryopreservation solutions constitute critical input dependencies. Single-source vulnerability pervades contract manufacturing organization capacity, where patient-specific autologous workflows preclude inventory buffering. Distribution runs through hospital-based apheresis units coordinated with centralized cell processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing capacity constraints prop pricing power for incumbent developers, with treatment sequencing waitlists extending patient intake timelines. This supply bottleneck sustains premium positioning for qualified manufacturers.
For Market Incumbents: Hedge against allogeneic stem cell platform substitution by securing dual manufacturing capability in lentiviral and AAV modalities. Expand captive plasmid production capacity to reduce contract development organization dependency. Lock in long-term apheresis center partnerships to secure patient access nodes before competitor network buildout. For New Entrants and Emerging Players: Specialty pharmacies with home infusion nursing networks represent the most accessible channel for subcutaneous factor formulation entry. White space concentrates in thalassemia erythropoiesis stimulating agent substitution and oral iron chelation combination regimens. Target German and Japanese markets where orphan drug reimbursement frameworks offer faster commercial traction than United States hospital outpatient payment complexity. For Investors and Strategic Acquirers: Re-rating potential sits with platform technology developers possessing CRISPR base-editing intellectual property given FDA and EMA accelerated pathway utilization. Long-term viability hinges on manufacturing asset ownership rather than pure licensing plays. Watch for G-BA and NICE reimbursement determinations on one-time curative therapies as inflection signals for European market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP-grade viral vector capacity expansion in Basel and Massachusetts reduces patient waitlist bottlenecks. |
| Regulatory Approval Pathway | EMA adaptive pathways submission compresses approval-to-reimbursement intervals in Netherlands and Denmark. |
| Pipeline Diversification | Base-editing sickle cell programs broaden addressable genotype populations beyond lentiviral limitations. |
| Licensing Agreement | Cross-licensing CRISPR and viral vector patents resolves royalty stacking that delays commercialization. |
| Hospital System Partnership | Cincinnati Children's and CHOP referral network access secures technical fee capture for gene therapy administration. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this inherited orphan blood disorders therapeutics assessment. Primary interviews with gene therapy manufacturing executives, pediatric hematology center directors, hospital formulary pharmacists, and payer access specialists combined with FDA orphan drug designations, EMA advanced therapy medicinal products submissions, ClinicalTrials.gov protocols, and national health technology assessment determinations. Bottom-up patient population modeling and top-down manufacturer revenue triangulation validated segment-level outputs.
Granularity-level modeling distinguished gene therapy, stem cell transplantation, transfusion, and erythropoiesis stimulating agent product categories at the country-regulatory cluster intersection. Delivery mode segmentation captured intravenous, subcutaneous, oral, and intraosseous administration routes across hospital, home healthcare, specialty clinic, and research institution end users. CAGRs derived from patient incidence projections, treatment penetration curves, and pricing trajectory assumptions. Manufacturing capacity utilization rates and viral vector yield metrics informed supply-constrained market access timelines.
Caveats apply where G-BA reimbursement determinations, FDA manufacturing inspection outcomes, or AAV immunogenicity signal emergence could materially shift the outlook. Forecasts reflect assumptions regarding regulatory pathway efficiency and vector production scale-up execution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market