
 Fetal Valproate Syndrome Market | 2026-2036
Fetal Valproate Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Fetal Valproate Syndrome Market Analysis
The pool of pediatric neurologists trained in teratogenic pharmacovigilance is collapsing across multiple healthcare systems, constraining patient throughput at specialized centers. Novartis AG leverages its neurology franchise to sustain research into safer antiepileptic alternatives. Sanofi anchors European market presence through established sodium valproate portfolios and risk-minimization programs. Teva Pharmaceutical competes on generic divalproex sodium formulations across outpatient channels.
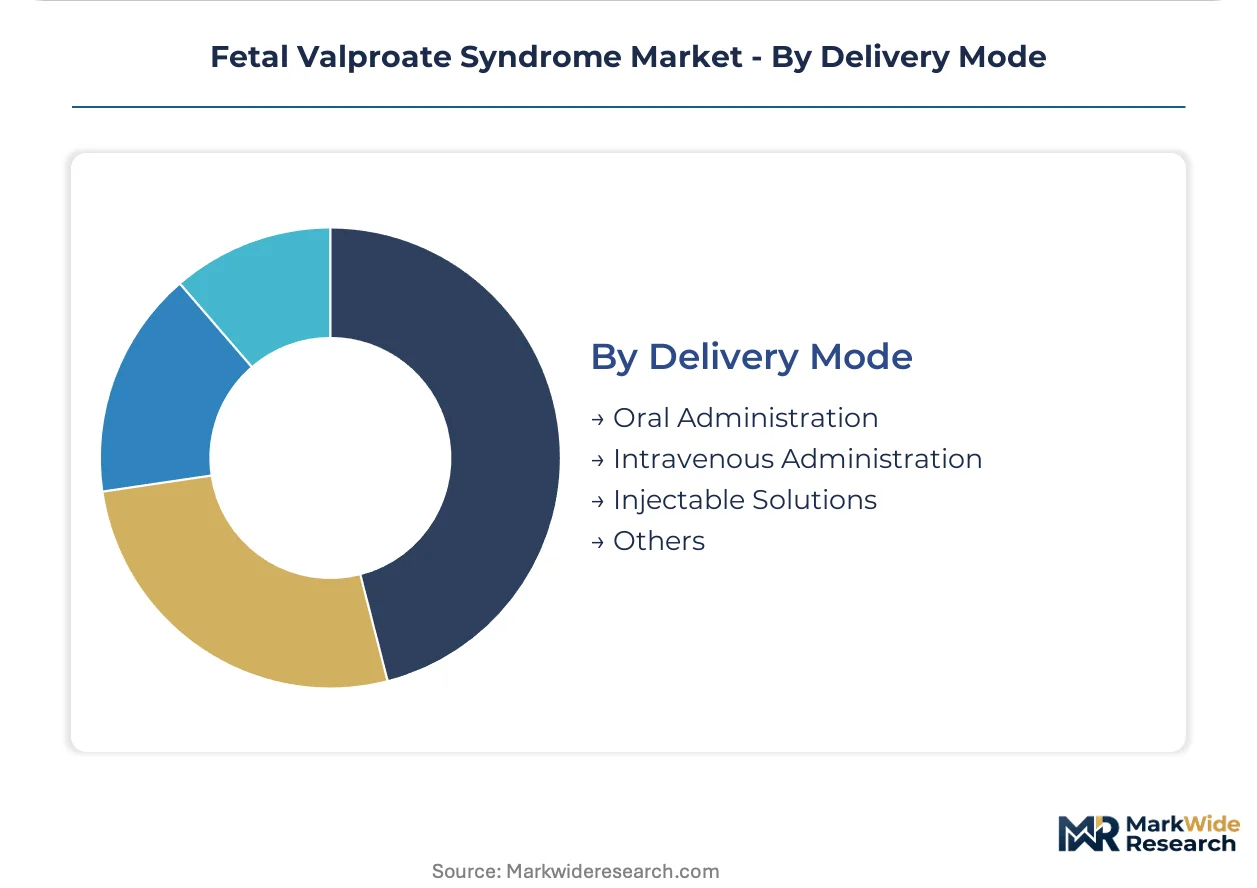
Fetal Valproate Syndrome encompasses a spectrum of congenital anomalies and neurodevelopmental deficits arising from in utero exposure to valproate compounds, characterized by neural tube defects, craniofacial dysmorphism, and cognitive impairment with documented gestational timing sensitivity. The condition's primary commercial purpose centers on diagnostic services, therapeutic interventions, and long-term management protocols for affected pediatric populations. Divalproex Sodium formulations command the largest product type share due to established bioequivalence profiles and payer familiarity, while Specialized Centers capture disproportionate margin pools through multidisciplinary care coordination. Oral Administration dominates delivery mode volumes, though Intravenous Administration protocols are expanding within hospital settings for acute seizure management in known exposure cases.
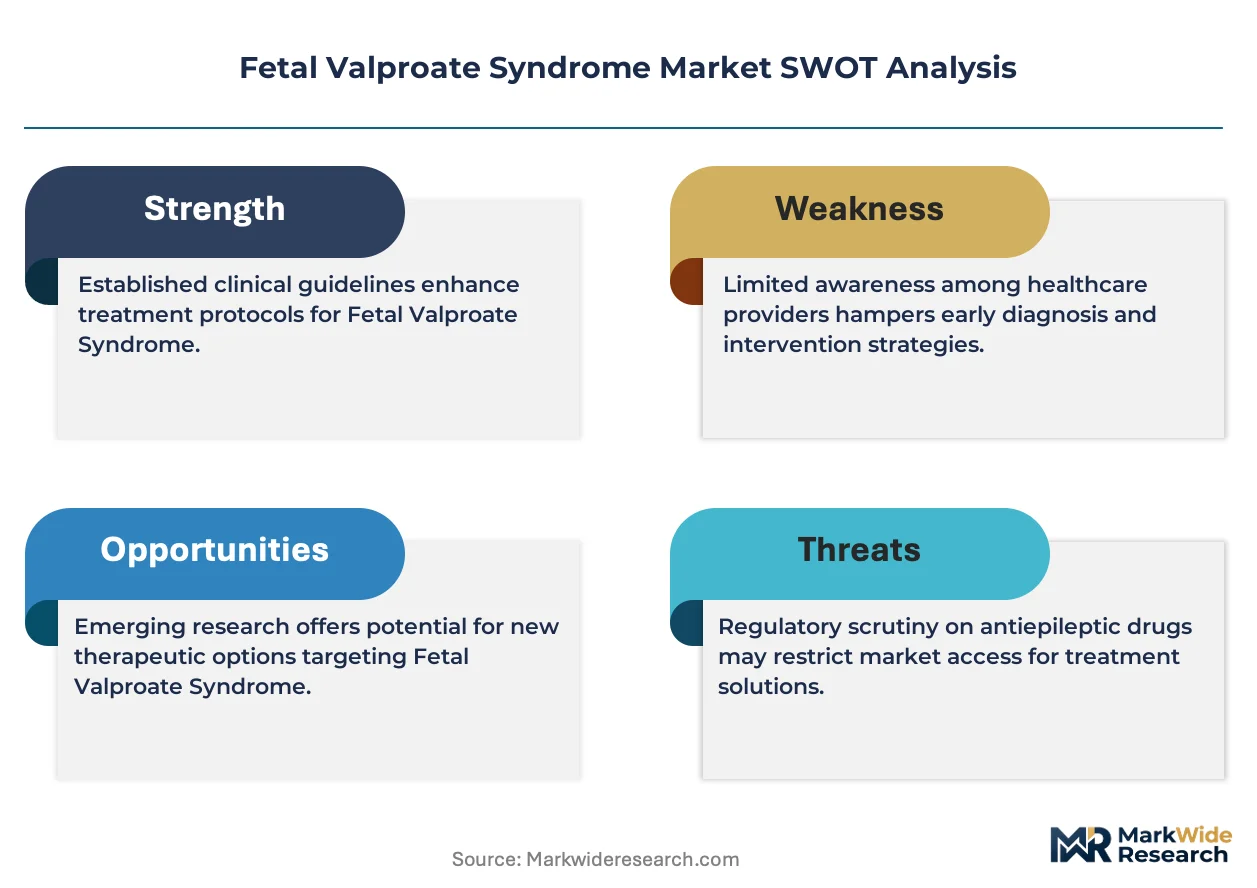
The FDA maintains strict pregnancy category labeling and Risk Evaluation and Mitigation Strategies for all valproate-containing products, directly shaping prescribing volumes and liability exposure for manufacturers. The EMA's strengthened contraindication protocols and patient registries across France, Germany, and Italy are redirecting demand toward alternative therapies and post-exposure diagnostic services. Stakeholders must monitor evolving teratogenicity litigation trends and regulatory shifts toward mandatory pre-prescription pregnancy testing as these forces reshape market access conditions and product liability frameworks.
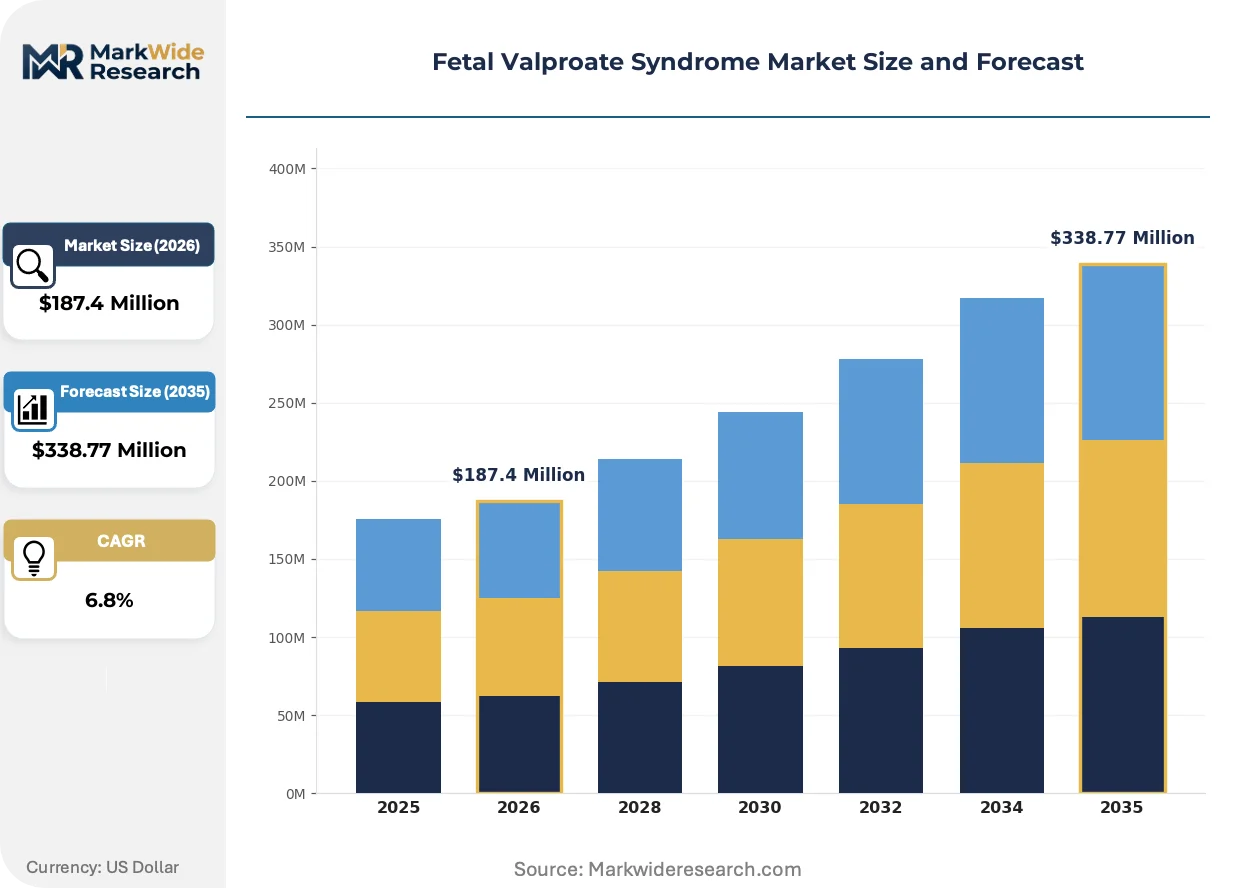
Market Dynamics
The EMA's strengthened pregnancy-prevention programs and the FDA's Risk Evaluation and Mitigation Strategies are structurally redirecting prescribing volumes toward post-exposure diagnostic services and long-term pediatric management protocols across hospital networks.
Growth Catalysts
- Teratogenic pharmacovigilance mandates:The FDA's Risk Evaluation and Mitigation Strategies compel specialized centers to expand diagnostic capacity for valproate-exposed cohorts.
- Pediatric neurology department expansion:Hospital networks across the United States are building multidisciplinary care coordination units for developmental disorder management.
- EMA pregnancy-prevention program enforcement:France, Germany, and Italy now require mandatory patient registries that generate sustained demand for post-exposure monitoring services.
Market Restraints
- Specialist workforce collapse:The shrinking pool of pediatric neurologists trained in teratogenic pharmacovigilance constrains patient throughput at specialized centers.
- Litigation liability exposure:Escalating teratogenicity lawsuits against valproate manufacturers create capital reservation pressures that limit R&D investment in adjacent therapeutic areas.
- Alternative therapy substitution:Levetiracetam and lamotrigine protocols are capturing antiepileptic prescriptions that previously defaulted to sodium valproate formulations.
Strategic Opportunities
- Underpenetrated diagnostic imaging integration:France's hospital networks lack systematic craniofacial dysmorphism screening protocols for second-trimester exposure cases.
- Intravenous administration protocol expansion:Hospital emergency departments in the United States require acute seizure management frameworks specifically designed for known in utero exposure.
- Neurodevelopmental rehabilitation service bundling:Cognitive impairment management programs represent an emerging white space beyond acute pharmacotherapy interventions.
Industry Challenges
- Multidisciplinary care coordination complexity:Integrating genetic counseling, pediatric neurology, and developmental psychology into unified patient pathways demands operational reconfiguration at specialized centers.
- Pre-prescription pregnancy testing standardization:The absence of uniform mandatory testing protocols across pharmacy chains and clinical settings creates compliance fragmentation.
- Longitudinal patient registry interoperability:EMA-mandated registries in France, Germany, and Italy operate on incompatible data standards that impede cross-border pharmacovigilance analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fetal Valproate Syndrome Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valproic Acid, Divalproex Sodium, Sodium Valproate, Other Medications Application: Pediatric Neurology, Mental Health, Developmental Disorders, Pharmacotherapy End User: Hospitals, Outpatient Clinics, Specialized Centers, Home Care Delivery Mode: Oral Administration, Intravenous Administration, Injectable Solutions, Others |
| Companies Covered | Novartis AG, Abbott Laboratories, Sanofi, Anjan Drug Pvt. Ltd., Teva Pharmaceutical, GSK plc, Roche Holding AG, Taj Pharmaceuticals Limited, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fetal Valproate Syndrome Market Emerging Trajectories
Diagnostic and therapeutic protocols for Fetal Valproate Syndrome are pivoting toward predictive risk stratification and non-pharmacological intervention models that reshape how exposed cohorts are managed across care continuums.
Pharmacogenomic screening for maternal metabolic enzyme variants is supplanting gestational timing as the primary exposure risk determinant. Specialized centers in the United States are adopting CYP2C9 and UGT1A6 genotyping panels to stratify neural tube defect probability. This molecular approach is compressing reliance on retrospective exposure documentation and redirecting resource allocation toward pre-conception counseling services.
REACH registration requirements for endocrine-disrupting substance classification are compelling European pharmaceutical manufacturers to reformulate valproate salt derivatives with enhanced purity profiles. The EMA's 2024 updated environmental risk assessment guidelines now mandate expanded aquatic toxicity testing for all antiepileptic active pharmaceutical ingredients. Generic divalproex sodium suppliers are responding by isolating manufacturing to dedicated batch facilities with closed-loop solvent recovery systems.
Hospital procurement departments are consolidating vendor relationships for teratogenic exposure management into single-source contracts with academic medical centers. The traditional fragmented purchasing of genetic testing, neuroimaging, and rehabilitation services through separate channels is yielding to bundled outcome guarantees. This concentration is most visible in the United States, where Medicaid managed care organizations in California and Texas now mandate exclusive provider network participation for valproate-exposed pediatric cases.
Fetal Valproate Syndrome Market Segmentation
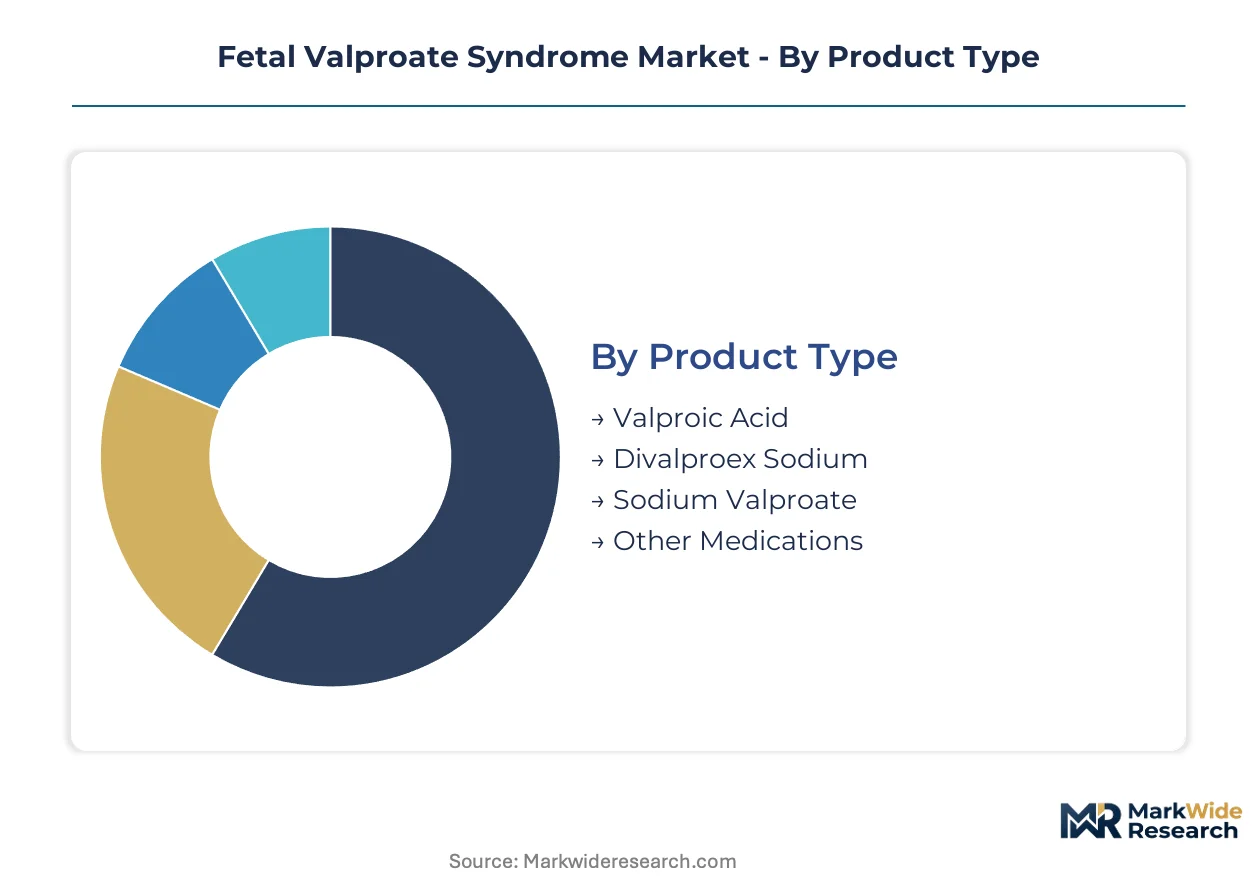
Channel configuration determines how Fetal Valproate Syndrome services reach affected populations. Hospital networks, specialized centers, and outpatient clinics each filter distinct product types and delivery modes through their procurement systems.
Product Type:
Hospital pharmacies and specialized centers channel distinct chemical formulations through their formularies based on bioequivalence profiles and teratogenic risk stratification protocols.
- Divalproex Sodium:This stable salt compound delivers controlled valproate release with established pharmacokinetic profiles. Demand concentrates in United States hospital networks where Medicaid managed care organizations mandate preferred formulary placement for pediatric neurology protocols.
- Sodium Valproate:The original antiepileptic formulation maintains presence across European hospital systems through EMA-mandated risk-minimization programs. France and Germany anchor volume through pregnancy-prevention registry requirements that sustain post-exposure monitoring demand.
- Valproic Acid:The unbuffered active pharmaceutical ingredient serves compounding pharmacies and research protocols.
- Other Medications:Extended-release and enteric-coated variants address specific absorption requirements in specialized centers.
Divalproex Sodium dominates installed base. Sodium Valproate is where expansion concentrates.
Application:
Cost tier stratification separates acute diagnostic services from longitudinal management programs across reimbursement categories.
- Pediatric Neurology:Multidisciplinary diagnostic protocols integrate genetic counseling, neuroimaging, and developmental assessment for exposed cohorts. United States academic medical centers capture disproportionate margin pools through bundled outcome guarantees with Medicaid managed care organizations.
- Developmental Disorders:Cognitive impairment management spans speech therapy, occupational therapy, and behavioral intervention over extended care continuums. California and Texas Medicaid programs now mandate exclusive provider network participation for these services.
- Mental Health:Psychiatric comorbidity management addresses anxiety and mood disorders in adolescent exposed populations.
- Pharmacotherapy:Antiepileptic alternative selection and dosing optimization supports transition from valproate-based regimens.
Pediatric Neurology commands premium reimbursement tiers. Developmental Disorders represents the fastest-growing trajectory as longitudinal care models mature.
End User:
Customer type fragmentation creates distinct procurement patterns across institutional and home-based settings.
- Specialized Centers:Academic medical centers with dedicated teratogenic pharmacovigilance units coordinate multidisciplinary care pathways. The United States concentrates these facilities in urban clusters where pediatric neurologist density supports complex case management.
- Hospitals:Emergency departments and inpatient units manage acute seizure presentations in known exposure cases. Intravenous administration protocols are expanding within these settings for rapid stabilization.
- Outpatient Clinics:Community-based neurology practices handle stable patients and routine monitoring.
- Home Care:Family-administered rehabilitation and behavioral support extends management beyond institutional boundaries.
Specialized Centers concentrate margin capture. Hospitals anchor volume throughput for acute interventions.
Delivery Mode:
Supply concentration in manufacturing shapes which formulations achieve formulary access across distribution channels.
- Oral Administration:Tablets, capsules, and liquid suspensions serve maintenance therapy and outpatient management. United States outpatient clinics and home care settings channel the majority of volume through retail pharmacy networks.
- Intravenous Administration:Hospital-compounded solutions address acute seizure emergencies in known exposure cases. Emergency departments in Texas and California health systems are adopting dedicated protocols for this administration route.
- Injectable Solutions:Intramuscular depot formulations support non-compliant patients in specialized center settings.
- Others:Rectal suppositories and nasogastric tube formulations serve specific pediatric populations.
Oral Administration dominates ambulatory volume. Intravenous Administration is where hospital-based expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States academic medical centers while European markets operate under tighter reimbursement ceilings. The United States captures premium margins through bundled outcome guarantees with Medicaid managed care organizations. European demand channels through EMA-mandated risk-minimization programs that sustain post-exposure diagnostic volumes.
United States
California and Texas Medicaid programs mandate exclusive provider network participation for valproate-exposed pediatric cases. FDA Risk Evaluation and Mitigation Strategies compel specialized centers to expand diagnostic capacity. Greater Boston and New York Metro clusters anchor multidisciplinary care coordination units with embedded genetic counseling services.
Germany
EMA pregnancy-prevention registry requirements sustain demand for post-exposure monitoring across hospital networks. The country's national pharmaceutical regulator enforces strengthened contraindication protocols that redirect prescribing toward alternative therapies. Bavaria and North Rhine-Westphalia concentrate specialized pediatric neurology capacity within academic medical center networks.
France
ANSM mandates systematic craniofacial dysmorphism screening protocols for second-trimester exposure cases that expand diagnostic service volumes. EMA-mandated patient registries generate sustained demand for longitudinal monitoring. Île-de-France anchors hospital network procurement consolidation into single-source contracts with academic medical centers.
United Kingdom
NHS England reimbursement frameworks favor bundled neurodevelopmental rehabilitation service models over fragmented purchasing. The MHRA maintains strict pregnancy category labeling alignment with FDA protocols. London/Southeast clusters concentrate pediatric neurologist density supporting complex case management pathways.
Italy
AIFA risk-minimization programs parallel EMA pregnancy-prevention enforcement across regional health systems. Mandatory pre-prescription pregnancy testing standardization remains fragmented across pharmacy chains. Lombardy and Emilia-Romagna anchor hospital network expansion of intravenous administration protocols for acute seizure management.
Fetal Valproate Syndrome Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Fetal Valproate Syndrome market. Swiss and German pharmaceutical conglomerates anchor research-intensive positions in antiepileptic alternative development, while Israeli and Indian generic manufacturers compete on divalproex sodium formulation cost. The market structure tiered between patented portfolio holders, established generic suppliers, and emerging market compounders. Dominant competitive moves include vertical integration into dedicated batch manufacturing with closed-loop solvent recovery, and strategic partnerships with academic medical centers for bundled outcome guarantees.
Among Swiss-based research-intensive conglomerates, Novartis AG and Roche Holding AG occupy positions exemplifying technology-forward archetypes focused on safer antiepileptic alternatives. Sanofi represents the established European incumbent with anchored presence through sodium valproate portfolios and risk-minimization program infrastructure. Teva Pharmaceutical sits within the scale-driven generic tier competing on divalproex sodium formulation cost across outpatient channels.
| Leading Market Players |
|---|
| Novartis AG |
| Abbott Laboratories |
| Sanofi |
| Anjan Drug Pvt. Ltd. |
| Teva Pharmaceutical |
| GSK plc |
| Roche Holding AG |
| Taj Pharmaceuticals Limited |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Batch-scale economies in divalproex sodium manufacturing anchor price floors across United States hospital networks, compressing margins for generic suppliers while concentrating premium capture among academic medical centers with bundled outcome guarantees. EMA-mandated environmental compliance costs in European production facilities are reshaping supplier tiering, as REACH registration requirements for endocrine-disrupting substance classification force smaller compounders toward contract manufacturing arrangements.
Pricing Analysis
The customization-premium spread separates standard divalproex sodium formulations from patient-stratified pharmacogenomic protocols. A three-tier pricing structure across premium, standard, and economy levels dominates, with price differentiation driven by CYP2C9/UGT1A6 genotyping bundling and FDA Risk Evaluation and Mitigation Strategies compliance certification. Cost compression in standard oral formulations is intensifying because Teva Pharmaceutical and Indian generic manufacturers are expanding outpatient channel volume. Medicaid managed care organizations in California and Texas exhibit highest price sensitivity, while specialized centers with exclusive provider network status command lowest sensitivity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among United States hospital networks for oral maintenance formulations, whereas strategic stockpiling of intravenous solutions concentrates in emergency departments managing acute seizure presentations. Active pharmaceutical ingredient production draws from India, China, and United States facilities, with sodium valproate raw material supply anchored in European chemical manufacturing hubs. Single-source vulnerability persists for CYP2C9 pharmacogenomic testing panels manufactured in specialized United States diagnostics facilities. Distribution runs through hospital pharmacy formularies and retail pharmacy networks for outpatient channels, with direct-to-specialist-center contracting expanding for bundled neurodevelopmental rehabilitation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as EMA pregnancy-prevention program enforcement generates sustained post-exposure diagnostic demand across European hospital networks, creating predictable revenue baselines for service providers.
For Market Incumbents: Consolidate diagnostic imaging integration capabilities within United States academic medical centers before underpenetrated craniofacial dysmorphism screening protocols in France achieve regulatory standardization. Deepen backward integration into dedicated batch manufacturing with closed-loop solvent recovery systems to deflect REACH compliance cost pressure from European regulatory shifts. Channel control through exclusive provider network participation with California and Texas Medicaid programs remains the critical defensive lever.
For New Entrants and Emerging Players: Differentiate on neurodevelopmental rehabilitation service bundling, the fastest-growing trajectory as longitudinal care models mature beyond acute pharmacotherapy interventions. Target developmental disorders management in United States Medicaid managed care territories where cognitive impairment programs remain fragmented. A go-to-market angle anchored to pharmacogenomic screening partnerships with pediatric neurology departments offers lowest competitive density.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized centers with embedded genetic counseling services and bundled outcome guarantees. Long-term viability across the projection horizon rests on exposure to EMA-mandated patient registry infrastructure rather than pharmaceutical formulation assets. Acquisition targets should display vertical integration into both diagnostic capacity and rehabilitation service delivery. The signal to watch is mandatory pre-prescription pregnancy testing standardization across United States pharmacy chains, which would trigger structural demand reallocation toward post-exposure service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Screening Partnership | CYP2C9 and UGT1A6 genotyping panels stratify neural tube defect probability at United States specialized centers. |
| Exclusive Provider Network Participation | California and Texas Medicaid programs mandate single-source contracting for valproate-exposed pediatric cases. |
| REACH-Compliant Manufacturing Transition | EMA's 2024 environmental risk assessment guidelines compel closed-loop solvent recovery in European batch facilities. |
| Intravenous Administration Protocol Expansion | Texas and California emergency departments adopt dedicated frameworks for acute seizure management in known exposure cases. |
| Neurodevelopmental Rehabilitation Service Bundling | NHS England reimbursement frameworks favor bundled cognitive impairment programs over fragmented purchasing patterns. |
Methodological Framework
Cross-validation between primary interviews with pediatric neurologists, genetic counselors, hospital procurement managers, and formulary directors anchors the qualitative findings against secondary validation from FDA Risk Evaluation and Mitigation Strategies filings, EMA pregnancy-prevention registry data, ClinicalTrials.gov antiepileptic protocols, and Medicaid managed care organization contract disclosures. Bottom-up patient cohort modeling and top-down pharmaceutical expenditure triangulation converge on segment-level demand estimates.
Sensitivity analysis across the modeling period tests variance in specialist workforce availability, litigation liability exposure thresholds, and alternative therapy substitution rates. Segmentation dimensions include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs derive from longitudinal patient registry growth trajectories and hospital network procurement consolidation patterns, with pharmacogenomic adoption curves and REACH compliance cost pass-through serving as key forecast inputs.
Decision-makers should treat outputs as directional under stable EMA enforcement and FDA labeling continuity assumptions; material deviation would warrant model refresh. Forecasts reflect documented assumptions regarding pediatric neurologist training pipeline recovery and generic manufacturer capacity expansion. Revision becomes warranted when mandatory pre-prescription pregnancy testing crosses jurisdictional adoption thresholds or teratogenicity litigation reserves trigger pharmaceutical manufacturer portfolio restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Middle East and Africa Bacteriophages Therapy Market
Medical Biotechnology
Gestational Trophoblastic Disease Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Neurotrophins Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Apoptosis Market
Medical Biotechnology
Global Diagnostic Specialty Enzymes Market
Medical Biotechnology
Glioblastoma Multiforme (GBM) Market
Medical Biotechnology
Cell Surface Markers Market
Medical Biotechnology
Insulinoma Market