
 Global Small Interfering RNA (Sirna) Therapeutics Market | 2026-2036
Global Small Interfering RNA (Sirna) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Interfering RNA (Sirna) Therapeutics Market Intelligence
Revenue from proprietary delivery technology licensing is rewriting the value chain for siRNA therapeutics. This shift prioritizes control over the mechanisms that get the drug to its target tissue safely and effectively. Alnylam Pharmaceuticals, Inc. leverages its pioneering work in lipid nanoparticle (LNP) platforms to maintain a strong market position. Novartis AG competes using its vast clinical development infrastructure and global commercialization capabilities. Arrowhead Pharmaceuticals, Inc. differentiates with its Targeted RNAi Molecule (TRiM) platform for tissues beyond the liver.
Small interfering RNA therapeutics are a class of drugs utilizing short, double-stranded RNA molecules, typically 20-25 base pairs long, to achieve post-transcriptional gene silencing. These molecules bind to and promote the degradation of specific messenger RNA (mRNA), preventing the synthesis of disease-causing proteins. Within therapy areas, applications for rare genetic disorders command premium pricing, while the oncology segment represents a major growth frontier. Lipid nanoparticles currently dominate the product type category, though innovation in conjugated siRNA is creating new opportunities for subcutaneous administration.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) govern market entry, often providing orphan drug designations and accelerated approval pathways for rare disease treatments. In parallel, China's National Medical Products Administration (NMPA) is creating faster review cycles for innovative biologics, including RNA-based therapies. Future success for developers hinges on securing intellectual property for novel delivery systems and generating robust long-term safety and efficacy data for regulators.
Market Dynamics
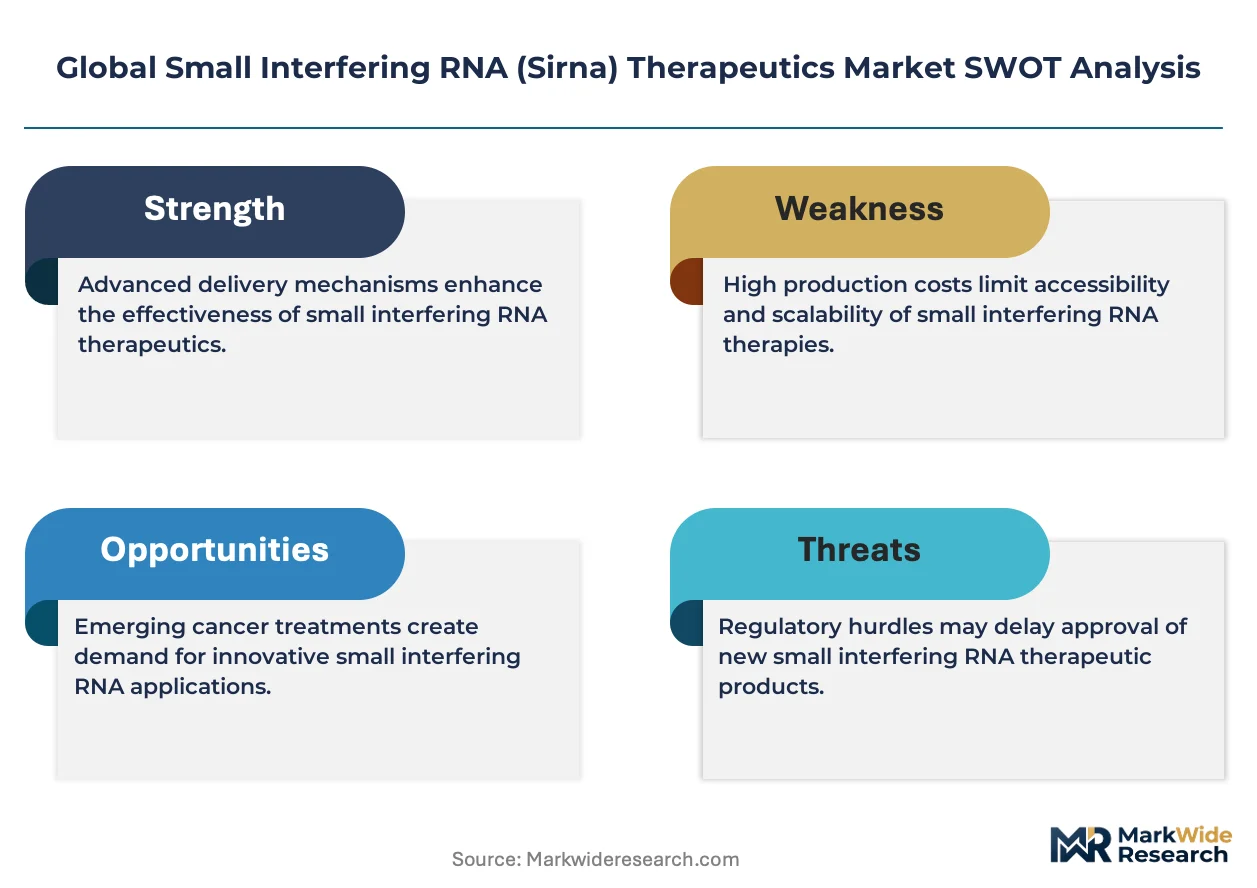
The market's structure is defined by the tension between proprietary delivery system innovation and the regulatory pathways that reward development for rare diseases. This dynamic concentrates value in intellectual property for platforms like lipid nanoparticles and targeted conjugates, shaping competitive strategies.
Growth Catalysts
- Orphan Drug Designations:Regulatory frameworks from the FDA and EMA provide market exclusivity and financial incentives, accelerating development for rare genetic conditions.
- Lipid Nanoparticle (LNP) Advances:Continuous improvements in LNP technology enhance the stability and targeted delivery of siRNA molecules, overcoming a primary historical barrier to efficacy.
- Expanded Genetic Sequencing:The increased use of next-generation sequencing in clinical diagnostics is identifying a larger patient population with actionable genetic targets for siRNA intervention.
Market Restraints
- High Manufacturing Costs:The synthesis of high-purity, chemically modified RNA oligonucleotides remains a complex and expensive process, limiting cost-effectiveness for non-premium indications.
- Off-Target Effects:Ensuring the high specificity of siRNA molecules to avoid unintended gene silencing is a persistent technical hurdle requiring extensive preclinical validation.
- Delivery to Extrahepatic Tissues:While liver-targeted delivery is well-established, achieving efficient and safe delivery to other tissues like the central nervous system or tumors remains a significant barrier.
Strategic Opportunities
- Oncology Applications:The vast heterogeneity of cancer genetics presents a major frontier for siRNA therapeutics designed to silence specific oncogenes or drug-resistance genes.
- China's Regulatory Streamlining:The NMPA's faster review cycles for innovative biologics create a significant opportunity for market entry and expansion into a large, underpenetrated patient population.
- AI-Driven Target Discovery:Integrating artificial intelligence with genomic data can rapidly identify and validate novel mRNA targets for new siRNA drug development programs.
Industry Challenges
- Delivery Platform IP Litigation:Intense competition over foundational intellectual property for lipid nanoparticle and conjugated delivery systems creates legal risks and licensing complexities for developers.
- Specialized Talent Scarcity:A shortage of scientists with expertise in RNA biology, oligonucleotide chemistry, and bio-nanotechnology constrains research and development capacity across the industry.
- Immunogenicity Risk Management:Managing the potential for innate immune responses to double-stranded RNA molecules requires sophisticated molecular design and rigorous long-term safety monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Interfering RNA (Sirna) Therapeutics Market |
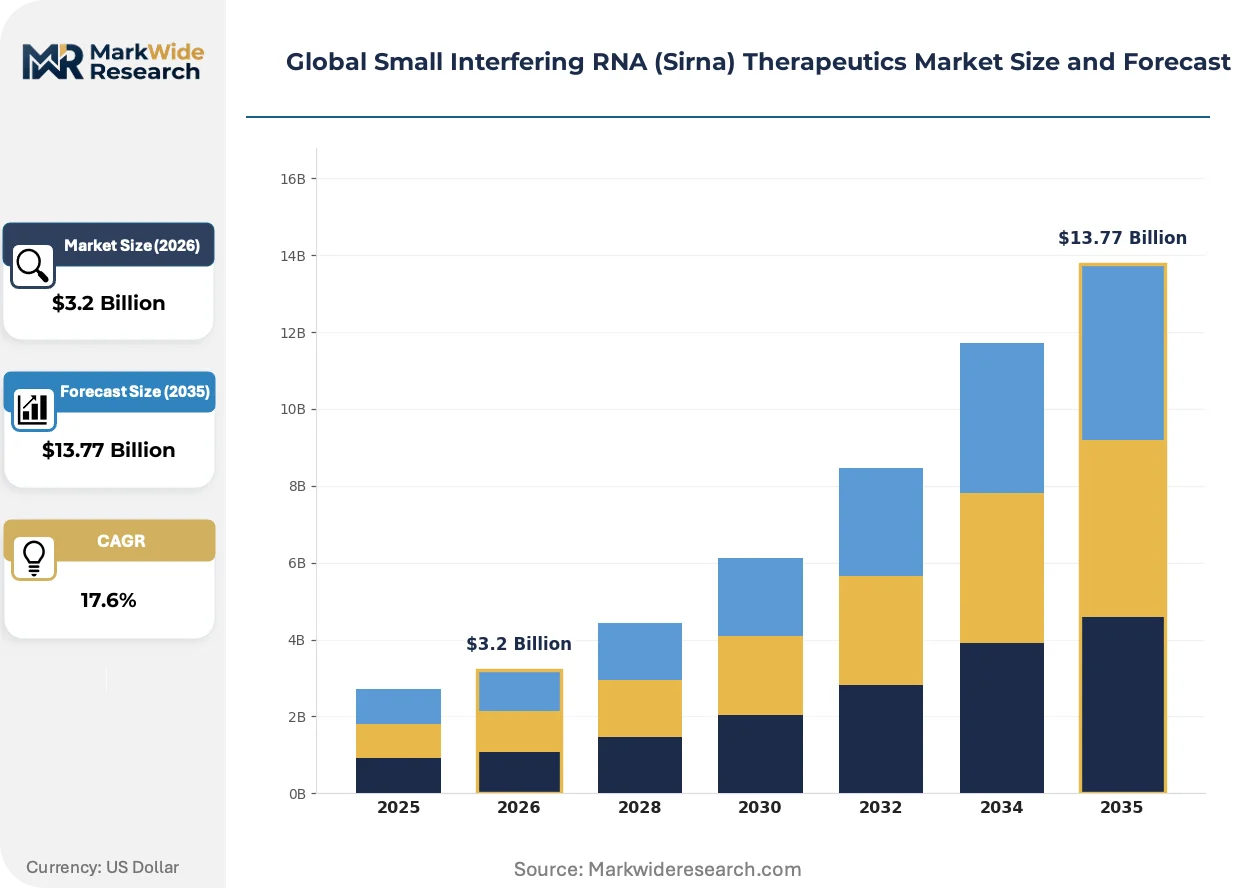
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $13.77 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipid Nanoparticles, Conjugated siRNA, Polymer-Based siRNA, Viral Vector siRNA, Others Therapy Area: Genetic Disorders, Infectious Diseases, Oncology, Neurological Disorders, Rare Diseases Delivery Technology: Intravenous Delivery, Subcutaneous Injection, Targeted Delivery Systems, Oral Delivery Platforms, Transdermal Patches End User: Research Laboratories, Biotechnology Companies, Pharmaceutical Firms, Clinical Institutions, Contract Research Organizations |
| Companies Covered | Alnylam Pharmaceuticals, Inc., Novartis AG, Novo Nordisk A/S, Arrowhead Pharmaceuticals, Inc., Sanofi Genzyme, Silence Therapeutics AG, Quark Pharmaceuticals, Dicerna Pharmaceuticals, Arbutus Biopharma Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Interfering RNA (Sirna) Therapeutics Market Strategic Shifts & Innovations
The industrialization of RNA interference is moving beyond niche applications, driven by platform standardization and a deepening understanding of its biological mechanisms. This evolution is expanding the therapeutic possibilities and reshaping clinical development strategies for genetic medicine.
Conjugated siRNA represents a significant evolution in delivery. These molecules attach a targeting ligand directly to the siRNA, facilitating uptake by specific cell types without a lipid shell. Clinical development programs are adopting this for subcutaneous administration, which is hybridizing delivery approaches away from exclusively intravenous infusions.
Priority review vouchers and accelerated approval pathways from regulators like the US FDA and EMA are critical policy instruments. These mechanisms shorten development timelines for therapies addressing serious conditions with unmet medical needs, such as rare genetic disorders. The rare disease segment is therefore the most direct beneficiary, attracting focused investment and research.
A shift toward collaborative development models is becoming standard practice for bringing new siRNA therapies to market. Small biotechnology firms with novel platform technologies increasingly partner with large pharmaceutical organizations to leverage their extensive clinical trial infrastructure and global commercial reach. This symbiotic relationship is most visible in the United States and European biotechnology clusters.
Global Small Interfering RNA (Sirna) Therapeutics Market Segmentation
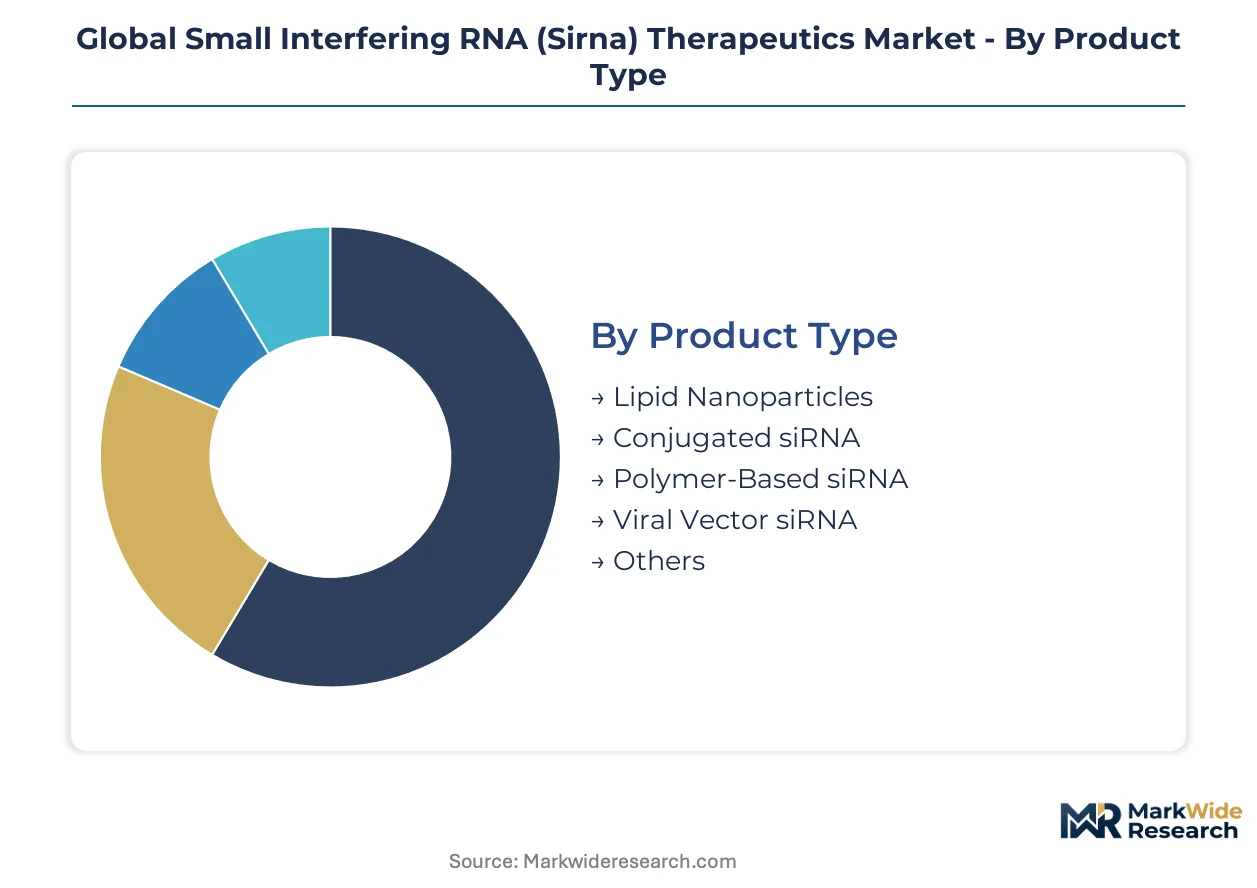
The Global Small Interfering RNA (siRNA) Therapeutics Market partitions across distinct categories, each reflecting specific technological capabilities, therapeutic applications, and operational structures. Understanding these segments helps developers align their innovation with market demand and regulatory pathways. This segmentation highlights the diverse approaches to leveraging gene-silencing technology for medical benefit.
Product Type:
The after-sales-service intensity for siRNA product types varies, with complex delivery systems often requiring more ongoing support and development. These product types define the fundamental molecular and formulation strategies employed for therapeutic effect. Each type offers distinct advantages in stability, targeting, and manufacturing scalability.
- Lipid Nanoparticles:These are sophisticated delivery vehicles encapsulating siRNA molecules, protecting them from degradation and facilitating cellular uptake. Demand concentrates in the United States, driven by their established safety profile and efficacy in liver-targeted therapies.
- Conjugated siRNA:These molecules feature a targeting ligand directly attached to the siRNA, enabling specific cell type delivery without a separate encapsulation vehicle. Their development focuses on subcutaneous administration, which simplifies patient dosing and expands therapeutic reach beyond intravenous routes.
- Polymer-Based siRNA:Synthetic or natural polymers form complexes with siRNA, enhancing stability and controlling release kinetics. This product type offers flexibility in tailoring delivery characteristics.
- Viral Vector siRNA:Modified viral vectors deliver the genetic material encoding shRNA (short hairpin RNA) or siRNA directly into cells for sustained gene silencing. This approach targets long-term expression in specific tissues.
- Others:This category encompasses emerging product types such as exosome-based delivery systems and novel chemical modifications. Innovation in these areas seeks to overcome current delivery limitations.
By volume, Lipid Nanoparticles lead. By growth pace, Conjugated siRNA is ahead.
Therapy Area:
The application focus of siRNA therapeutics spans a range of diseases, with varying patient populations and commercial potential. Each therapy area presents unique challenges and opportunities for drug development. Regulatory bodies often provide specific incentives for treatments addressing high unmet medical needs.
- Rare Diseases:These conditions affect a small percentage of the population but often command premium pricing due to the lack of alternative treatments and orphan drug designations. The US FDA and European Medicines Agency (EMA) provide accelerated approval pathways for these therapies.
- Oncology:Cancer represents a significant growth frontier for siRNA, targeting specific oncogenes or drug-resistance pathways. Research efforts in China are expanding rapidly within this segment.
- Genetic Disorders:siRNA offers highly specific gene-silencing capabilities for a wide array of inherited conditions. This area benefits from advances in genetic sequencing that identify actionable targets.
- Infectious Diseases:siRNA therapeutics can target viral or bacterial genes, disrupting pathogen replication or virulence. Development programs in this area aim to address emerging global health threats.
- Neurological Disorders:Delivering siRNA across the blood-brain barrier remains a technical challenge, but this area holds promise for treating conditions like Huntington's disease or Alzheimer's. Research institutions in Germany are exploring novel delivery methods.
Rare Diseases command the highest price points. Oncology is expanding most quickly.
Delivery Technology:
The volume of drug administered and the frequency of dosing are critical considerations for siRNA delivery technologies. These technologies define how the therapeutic molecules reach their intended cellular targets within the body. Advances in delivery systems are crucial for expanding the utility of siRNA beyond liver-targeted applications.
- Targeted Delivery Systems:These advanced platforms, including LNPs and conjugated siRNAs, direct the therapeutic agent specifically to disease-relevant cells or tissues. Innovation in this area is a primary driver of market growth.
- Subcutaneous Injection:This administration route offers patient convenience and is becoming increasingly viable with the development of stable and potent siRNA formulations. Many new therapies aim for this less invasive method.
- Intravenous Delivery:This traditional method ensures rapid systemic distribution of siRNA, often used for therapies targeting the liver or widespread systemic conditions. Clinical trials frequently employ this route.
- Oral Delivery Platforms:Developing oral siRNA formulations remains a significant challenge due to degradation in the gastrointestinal tract and poor absorption. Research laboratories are actively investigating protective coatings and absorption enhancers.
- Transdermal Patches:These non-invasive systems deliver siRNA through the skin, offering sustained release and avoiding first-pass metabolism. This technology is in earlier stages of development for siRNA.
Targeted Delivery Systems hold the largest share. Subcutaneous Injection is gaining share fastest.
End User:
The customer type for siRNA therapeutics and research tools ranges from academic institutions to large pharmaceutical corporations. Each end-user segment contributes uniquely to the market's innovation, development, and commercialization. Collaborations between these entities are common, particularly in early-stage research and clinical development.
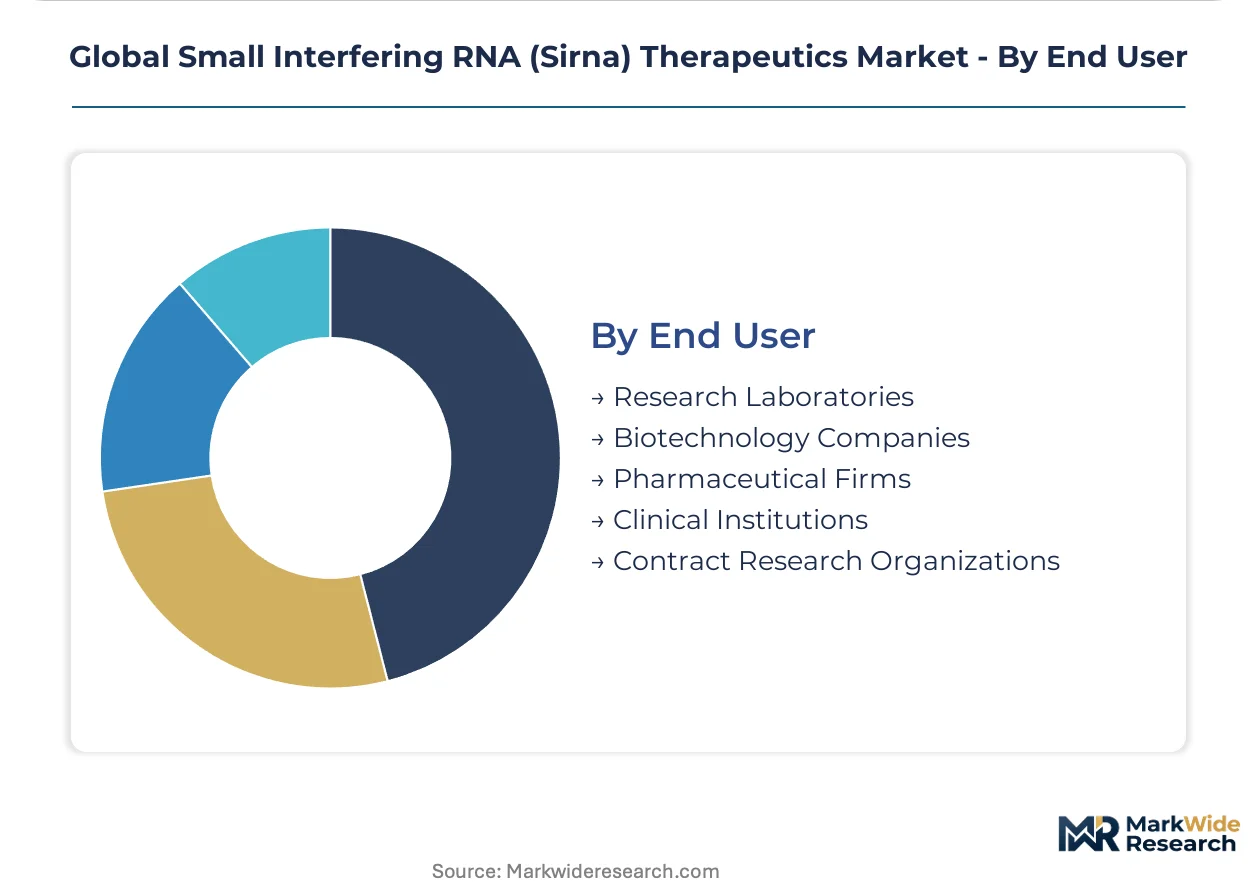
- Pharmaceutical Firms:These large corporations possess extensive clinical development infrastructure and global commercialization capabilities. They often partner with smaller biotech firms for novel platform technologies.
- Biotechnology Companies:These firms specialize in innovative drug discovery and platform development, frequently focusing on early-stage research and preclinical studies. Many are based in the United States and European biotechnology clusters.
- Research Laboratories:Academic and institutional research centers conduct foundational science, exploring new targets and mechanisms for siRNA. They contribute significantly to the scientific understanding of RNA interference.
- Clinical Institutions:Hospitals and medical centers are involved in clinical trials, patient recruitment, and the eventual administration of approved siRNA therapies. They provide critical data for regulatory submissions.
- Contract Research Organizations:CROs provide specialized services for drug development, including preclinical testing, clinical trial management, and regulatory support. They offer expertise to both biotech and pharma companies.
Pharmaceutical Firms represent the largest customer base. Biotechnology Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption-mix differential in siRNA therapeutics varies significantly by geography, reflecting diverse healthcare priorities and regulatory landscapes. The United States dominates early-stage clinical development, while China is rapidly expanding its oncology applications. European nations focus on rare disease treatments and neurological research, shaping regional market dynamics.
United States
Demand for siRNA therapeutics in the United States is driven by extensive clinical trials and a high concentration of leading biotechnology companies. The US Food and Drug Administration (FDA) provides critical orphan drug designations and accelerated approval pathways, fostering investment in rare disease treatments. Biotechnology clusters in Boston and San Francisco drive innovation in LNP and conjugated siRNA development.
China
China's market is rapidly expanding, propelled by significant growth in oncology applications and a large, underpenetrated patient population. The National Medical Products Administration (NMPA) facilitates market entry with faster review cycles for innovative biologics, including RNA-based therapies. Research efforts in Shanghai and Beijing focus on developing siRNA therapeutics for cancer treatment.
Germany
German demand centers on advanced research into neurological disorders, supported by robust academic institutions. The European Medicines Agency (EMA) provides accelerated approval pathways for therapies addressing high unmet medical needs, including rare genetic conditions. Research institutions in Munich and Heidelberg explore novel delivery methods to overcome the blood-brain barrier for siRNA treatments.
Japan
Japan exhibits strong demand for siRNA therapeutics targeting genetic disorders, supported by an aging population and robust pharmaceutical R&D. The Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approvals for innovative medicines, encouraging new drug development. Tokyo and Osaka host significant pharmaceutical R&D centers focusing on advanced gene therapy research.
Switzerland
Switzerland's market is characterized by a focus on high-value biopharmaceuticals and precision medicine. Swissmedic ensures rigorous approval processes for complex biopharmaceuticals, maintaining high safety and efficacy standards. Basel and Zurich are key biotechnology clusters, attracting specialized talent in RNA biology and oligonucleotide chemistry.
Global Small Interfering RNA (Sirna) Therapeutics Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the siRNA therapeutics market. The industry exhibits a tiered structure, with specialized biotechnology firms innovating delivery platforms. Larger pharmaceutical companies leverage their extensive clinical development infrastructure and global commercialization capabilities. Strategic partnerships and technology licensing are dominant competitive moves, enabling smaller innovators to access broader markets.
Within the innovative platform developer archetype, Alnylam Pharmaceuticals, Inc. and Arrowhead Pharmaceuticals, Inc. exemplify advancements in proprietary delivery systems for gene silencing. Alnylam Pharmaceuticals, Inc. leverages its pioneering work in lipid nanoparticle platforms, maintaining a strong market position through foundational intellectual property. Arrowhead Pharmaceuticals, Inc. differentiates with its Targeted RNAi Molecule (TRiM) platform, expanding delivery beyond liver-targeted applications. Novartis AG, representing the large pharmaceutical archetype, competes using its vast clinical development infrastructure and global commercialization capabilities, often through strategic collaborations.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals, Inc. |
| Novartis AG |
| Novo Nordisk A/S |
| Arrowhead Pharmaceuticals, Inc. |
| Sanofi Genzyme |
| Silence Therapeutics AG |
| Quark Pharmaceuticals |
| Dicerna Pharmaceuticals |
| Arbutus Biopharma Corp |
| Others |
Cost & Logistics Intelligence
Specialized cold chain logistics for RNA therapeutics, crucial for maintaining product integrity, significantly influence supply concentration and impact downstream premium pricing. This dynamic underscores the market's reliance on advanced infrastructure and expertise for product delivery.
Pricing Analysis
Long-term contract-based pricing structures dominate the siRNA therapeutics market, especially for rare genetic disorders where treatments command premium pricing. Value-based pricing models are common, reflecting the significant clinical benefit for patients with limited alternatives. Price differentiation stems from orphan drug designations and the complexity of proprietary delivery technologies like lipid nanoparticles. Pricing pressure arises from high manufacturing costs and the need for payer acceptance, though demand for rare disease therapies remains price-inelastic.
Supply Chain Analysis
Specialized raw materials like high-purity RNA oligonucleotides and proprietary lipids for nanoparticle formulation form the critical upstream feedstock for siRNA therapeutics. Supply concentration for these advanced components centers in the United States and specialized manufacturers in Europe. The supply chain relies on a limited number of expert suppliers, creating a single-source vulnerability for key ingredients. Distribution runs through specialized pharmaceutical logistics networks, ensuring temperature-controlled delivery to clinical institutions and pharmacies globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The siRNA therapeutics market requires a substitution defense strategy, as incumbents navigate the threat from emerging gene editing technologies like CRISPR. Maintaining market leadership necessitates continuous innovation in delivery systems and expanding therapeutic applications beyond rare diseases.
For Market Incumbents: Pre-empt competitive threats by aggressively investing in next-generation delivery platforms, including advanced conjugated siRNA and exosome-based systems. Secure foundational intellectual property for novel RNA modifications to mitigate the risk of off-target effects. Strategic partnerships with academic research laboratories can accelerate discovery of new therapeutic targets. This approach defends against emerging gene editing technologies and addresses the persistent challenge of high manufacturing costs.
For New Entrants and Emerging Players: China's underpenetrated oncology market offers significant white-space opportunities for siRNA therapeutics, benefiting from the NMPA's faster review cycles. Focus on developing novel delivery methods for neurological disorders, an area with high unmet medical need and technical challenges. Leverage AI-driven target discovery platforms to rapidly identify and validate new mRNA targets. This strategy allows for differentiation and market entry in high-growth segments.
For Investors and Strategic Acquirers: Specialized biotechnology firms with proprietary delivery platforms represent attractive acquisition targets for sustained growth over the next decade. These companies often hold critical intellectual property for lipid nanoparticles or conjugated siRNA technologies. Focus on entities demonstrating robust long-term safety and efficacy data for regulators. A key signal to watch is successful clinical trial readouts for efficient delivery to extrahepatic tissues, indicating expanded market potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate late-stage trials for oncology applications to expand market reach. |
| Licensing Agreement | Secure intellectual property for novel delivery systems from biotechnology companies. |
| Manufacturing Scale-Up | Optimize production of high-purity RNA oligonucleotides to reduce costs. |
| Pipeline Diversification | Explore new therapy areas like infectious diseases to broaden therapeutic scope. |
| Regulatory Approval Pathway | Utilize orphan drug designations for rare genetic disorders to expedite market entry. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, and clinical trial managers anchored the qualitative base for this analysis. Primary interviews combined with extensive secondary research, including FDA filings, EMA submissions, and scientific literature databases, informed market insights. This approach employed bottom-up data aggregation and top-down market validation, ensuring comprehensive coverage. Triangulation across diverse data points strengthened the analytical framework.
Scenario-bracketing across various market conditions informed the forecast framework, providing a robust projection across the analysis window. The model integrated segmentation by product type, therapy area, delivery technology, and end user. CAGRs were derived through a proprietary analytical model, incorporating historical growth patterns and future R&D investment trends. Clinical trial success rates for novel siRNA therapies served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or R&D investment would shift the trajectory of siRNA market growth. Forecasts reflect assumptions regarding regulatory changes and intellectual property litigation. Cross-checking against external pharmaceutical market benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
Fetal Valproate Syndrome Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Global Medical Enzyme Technology Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Cancer Antigens Market
Medical Biotechnology
Testicular Cancer Drugs Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Cancer RNA Expression Market