
 Cellular Epigenetics Market | 2026-2036
Cellular Epigenetics Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Epigenetics Market Outlook
Next-generation sequencing reagents are pivoting away from legacy fluorescent chemistries toward enzyme-based signal amplification systems. Thermo Fisher Scientific leverages its vertically integrated reagent manufacturing network to secure raw material access. Illumina sustains technology leadership through locked-in consumables economics. Merck KGaA anchors European supply chains with localized kit production facilities.
Cellular epigenetics encompasses the study of heritable changes in gene expression that occur without alterations to the underlying DNA sequence, typically involving DNA methylation, histone modification, and non-coding RNA regulation. These mechanisms functionally govern cell differentiation, X-chromosome inactivation, and genomic imprinting through enzymatic writers, erasers, and readers that modify chromatin architecture. The reagents segment captures the largest share of recurring revenue due to per-experiment consumption patterns. CRISPR-based epigenome editing tools represent the fastest-expanding technology category as programmable DNA-binding domains enable locus-specific chromatin remodeling. Academic research institutions remain the most price-sensitive end-user segment, while pharmaceutical companies generate the highest per-account revenue.
The FDA governs clinical epigenetic diagnostic assays through its in vitro diagnostic and companion test frameworks, while the EMA's IVDR transition in Europe imposes stricter conformity assessment requirements on kit manufacturers. ISO 13485 certification has become a baseline qualification for suppliers serving regulated clinical laboratories. Stakeholders must monitor how evolving payer coverage policies for methylation-based cancer screening tests reshape volume economics across health systems.
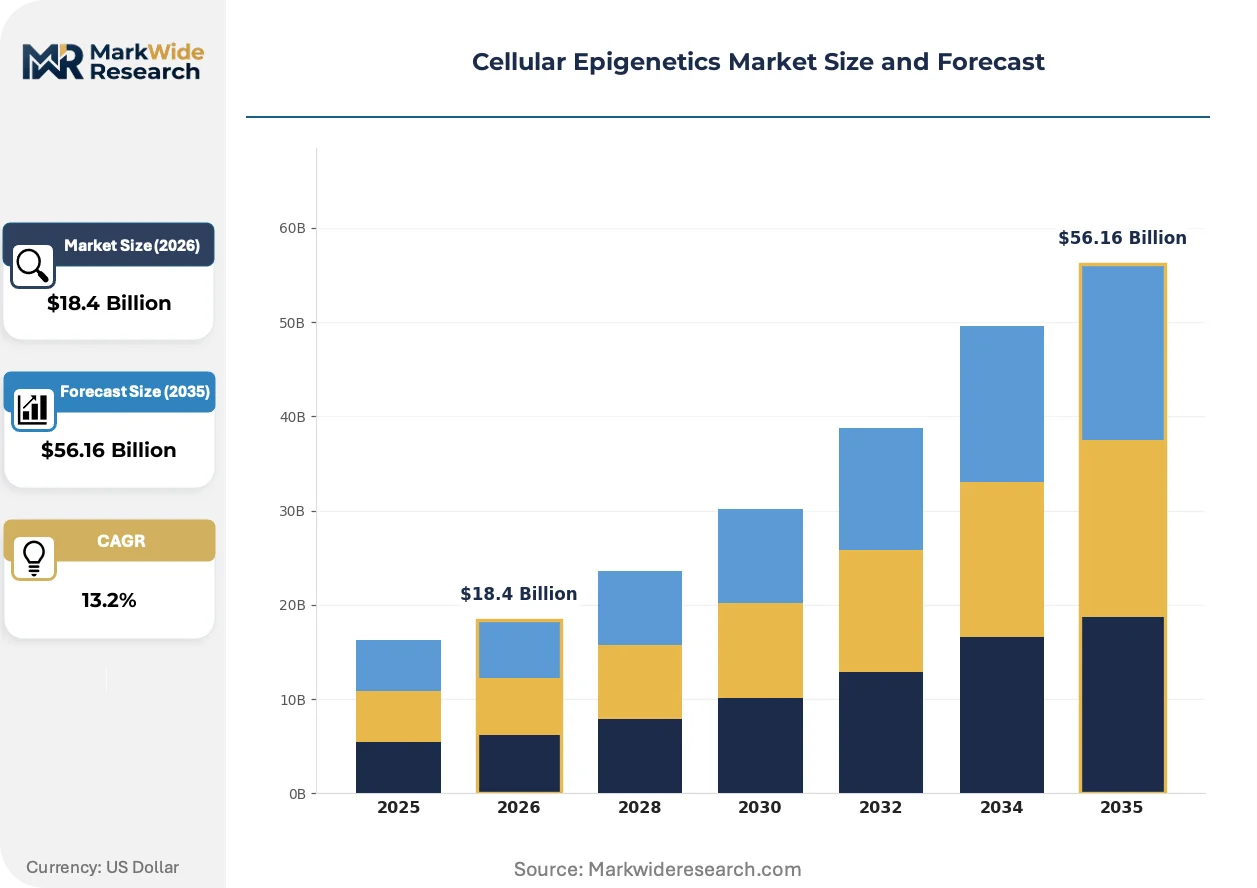
Market Dynamics
CRISPR-based epigenome editing platforms are compressing R&D timelines and redistributing value capture from centralized pharmaceutical pipelines toward distributed biotech development ecosystems.
Growth Catalysts
- NIH Epigenomics Funding Expansion:The National Institutes of Health has intensified grant allocations for chromatin modification research, directly expanding reagent consumption at academic medical centers.
- Enzyme-Based Signal Amplification:Next-generation sequencing workflows are migrating from fluorescent chemistries to enzymatic detection systems, reducing per-run costs and enabling higher-throughput screening.
- Companion Diagnostic Pathways:The FDA's accelerated approval frameworks for oncology therapeutics are embedding methylation-based biomarker tests into pivotal trial designs.
Market Restraints
- Consumables Lock-In Economics:Sequencing platform vendors enforce proprietary reagent contracts that inflate lifetime ownership costs and suppress switching flexibility.
- EMA IVDR Conformity Burden:Europe's In Vitro Diagnostic Regulation imposes extended certification timelines and notified body bottlenecks on kit manufacturers seeking CE marking.
- Specialized Talent Scarcity:The intersection of bioinformatics and chromatin biology requires hybrid skill sets that remain underdeveloped in standard molecular biology training programs.
Strategic Opportunities
- Liquid Biopsy Methylation Panels:Cell-free DNA epigenetic profiling for early cancer detection represents an underpenetrated clinical application with substantial reimbursement upside.
- CRISPR-dCas9 Convergence:Programmable DNA-binding domains fused to chromatin modifiers enable locus-specific therapeutic intervention without double-strand breaks.
- India's CDSCO Streamlining:The Central Drugs Standard Control Organization is harmonizing import licensing for research-use-only kits, reducing market entry friction for foreign suppliers.
Industry Challenges
- ISO 13485 Certification Timelines:Clinical laboratory suppliers face 12-18 month quality management system audits that delay product commercialization.
- Legacy Informatics Integration:Epigenetic data outputs require specialized analysis pipelines that clash with existing institutional sequencing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Epigenetics Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $56.16 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Technology: CRISPR, Bisulfite Sequencing, ChIP-Seq, Microarray End User: Academic Research, Pharmaceutical Companies, Contract Research Organizations, Biotechnology Firms Application: Cancer Research, Drug Development, Agricultural Biotechnology, Genetic Research |
| Companies Covered | Thermo Fisher Scientific, Illumina, Merck KGaA, QIAGEN, F. Hoffmann-La Roche Ltd, Revvity, Promega Corporation, Zymo Research Corporation, Diagenode, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Epigenetics Market Strategic Shifts
Epigenetic research instrumentation is fragmenting from centralized core facilities toward distributed benchtop deployment, while regulatory frameworks harden around clinical-grade assay validation standards.
Single-cell ATAC-seq and multi-omic profiling platforms are decentralizing chromatin accessibility analysis from national sequencing centers into individual principal investigator laboratories. Academic research groups now acquire compact droplet-based microfluidic systems that previously required institutional core facility access. This diffusion is compressing the publication cycle for developmental biology and immuno-oncology studies while expanding recurring reagent revenue streams.
The FDA's in vitro diagnostic and companion test frameworks are tightening evidentiary requirements for methylation-based cancer screening assays entering clinical use. Manufacturers must now submit analytical validation studies demonstrating reproducibility across multiple laboratory sites and operator conditions. High-complexity clinical laboratories in the United States are responding by consolidating purchasing authority under specialized molecular pathology directors who negotiate performance-based reagent contracts.
Pharmaceutical companies are unbundling epigenetic screening services from integrated CRO relationships and establishing direct procurement channels with specialized reagent vendors. This disintermediation enables just-in-time supply management for high-throughput target validation campaigns. The shift is most pronounced in Boston and San Diego biotech clusters where proximity to reagent manufacturing facilities supports rapid iteration cycles.
Cellular Epigenetics Market Segmentation
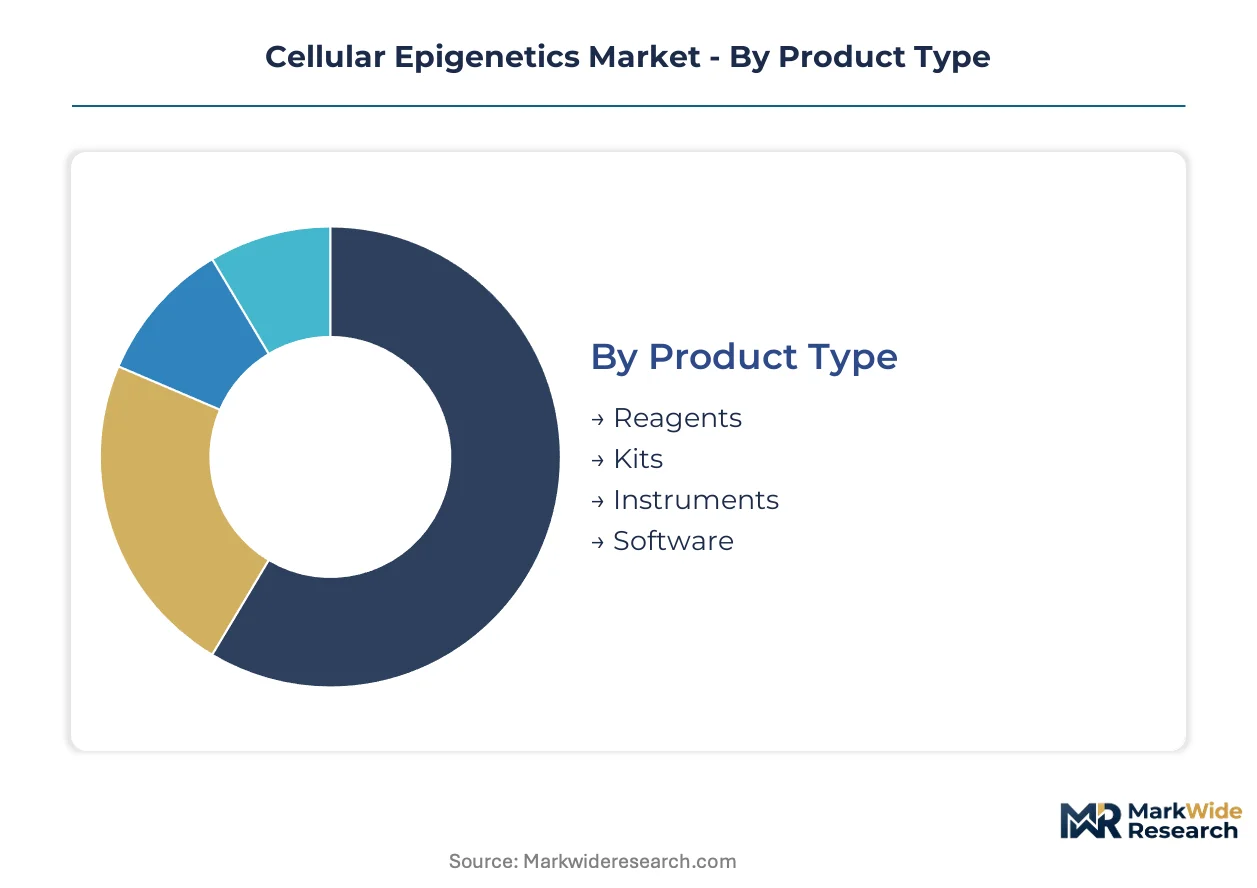
Segmentation in cellular epigenetics reveals distinct procurement patterns across reagent consumption, platform technologies, and institutional buyer types. Each dimension carries implications for pricing power, contract duration, and technical support requirements.
Product Type:
Reagents and kits function as embedded consumables within sequencing workflows, while instruments and software occupy standalone capital expenditure categories with divergent replacement cycles.
- Reagents:Enzyme-based signal amplification chemistries and nucleotide mixes constitute the highest-velocity purchase category. NIH-funded academic medical centers in the United States drive recurring bulk orders for chromatin immunoprecipitation buffers and methylation conversion reagents.
- Kits:Pre-formulated assay panels bundle reagents with validated protocols, reducing protocol development burden for laboratories lacking dedicated epigenetics expertise. Pharmaceutical companies in Boston and San Diego biotech clusters favor these for accelerated target validation timelines.
- Instruments:Capital equipment spans sequencers, microfluidic processors, and chromatin shearing systems with 5-7 year depreciation schedules.
- Software:Bioinformatics pipelines for peak calling, differential methylation analysis, and visualization require annual license renewals tied to core facility access tiers.
Volume placements concentrate in Reagents; the faster expansion belongs to Kits.
Technology:
Technology selection tracks the migration from hybridization-based detection toward programmable editing platforms with locus-specific precision.
- CRISPR:Programmable DNA-binding domains fused to chromatin modifiers enable therapeutic intervention without double-strand breaks. CRISPR-dCas9 convergence with epigenetic effector domains is climbing the fastest in pharmaceutical screening applications.
- Bisulfite Sequencing:Gold-standard DNA methylation detection relies on chemical conversion of unmethylated cytosines, demanding specialized library preparation expertise.
- ChIP-Seq:Chromatin immunoprecipitation coupled with sequencing maps histone modifications and transcription factor binding across the genome.
- Microarray:Hybridization-based methylation profiling retains cost advantages for high-sample retrospective studies with fixed content requirements.
Established laboratories favor Bisulfite Sequencing for regulatory submissions; CRISPR platforms are gaining share fastest among biotech entrants.
End User:
Buyer sophistication and procurement authority vary sharply between grant-dependent academic groups and revenue-generating commercial entities.
- Academic Research:Price-sensitive investigators rely on shared core facility access and compete for limited NIH epigenomics grant allocations.
- Pharmaceutical Companies:Generate the highest per-account revenue through direct reagent procurement channels bypassing traditional CRO intermediaries.
- Contract Research Organizations:Provide outsourced epigenetic screening services with equipment amortized across multiple sponsor contracts.
- Biotechnology Firms:Early-stage companies prioritize flexible kit configurations and rapid technical support response times.
Pharmaceutical Companies dominate absolute spending; Biotechnology Firms are expanding their vendor relationships most aggressively.
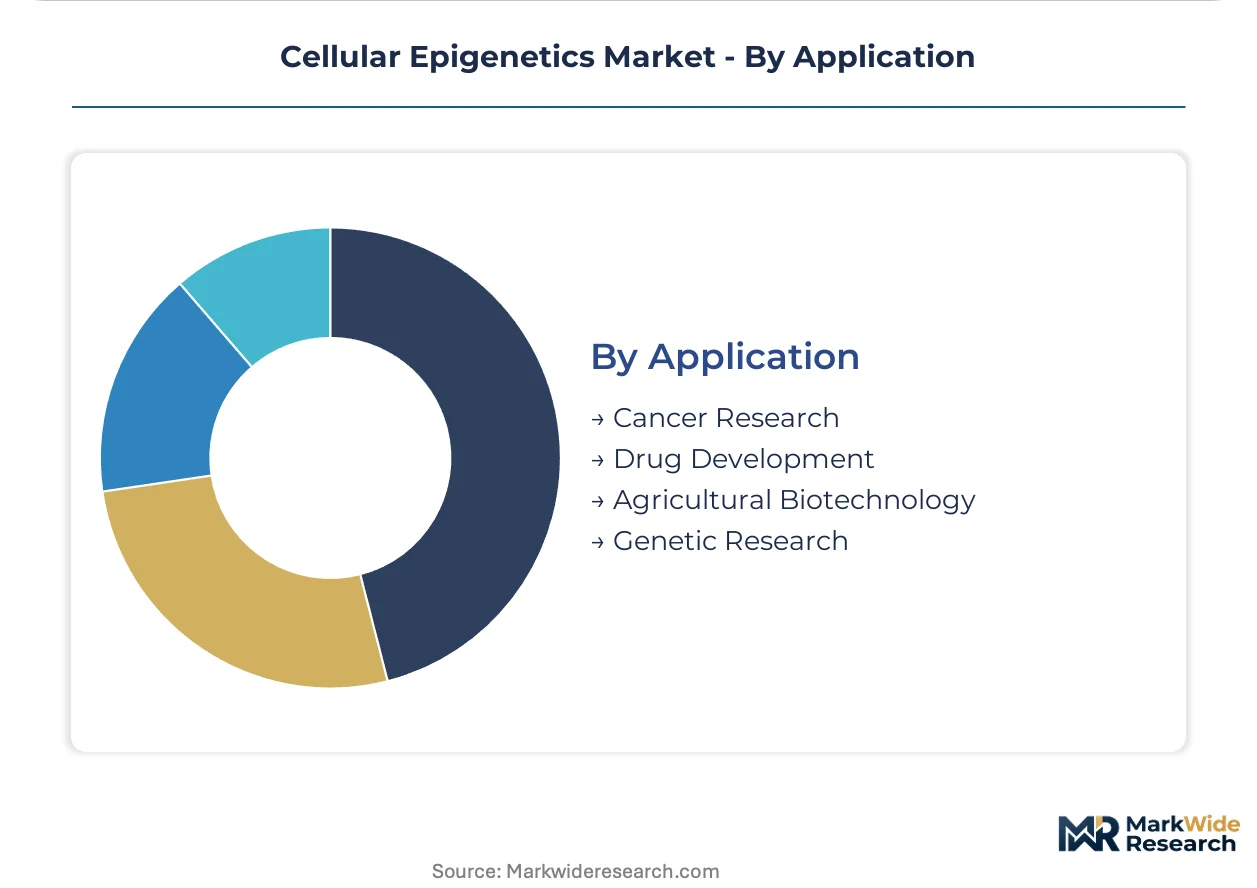
Application:
Clinical translation potential and regulatory pathway clarity differentiate therapeutic-focused applications from exploratory research.
- Cancer Research:Methylation-based liquid biopsy development and companion diagnostic qualification command the largest dedicated funding pools.
- Drug Development:Epigenetic target validation and mechanism-of-action studies integrate into FDA accelerated approval trial designs.
- Agricultural Biotechnology:Crop epigenome editing for stress tolerance and yield traits operates under distinct USDA regulatory frameworks.
- Genetic Research:Fundamental chromatin biology studies explore X-chromosome inactivation, genomic imprinting, and developmental programming.
Cancer Research anchors current procurement volumes; Drug Development applications are scaling fastest as regulatory pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Cambridge-Boston corridor concentrate epigenetics R&D through state-level tax credits and NIH proximity incentives. These zones anchor reagent procurement volumes and clinical trial activity for chromatin modification research.
United States
NIH epigenomics grant allocations at academic medical centers drive recurring bulk orders for methylation conversion reagents. The FDA's accelerated approval pathways for oncology therapeutics embed companion diagnostic requirements into trial designs. Boston and San Diego biotech clusters sustain direct procurement channels between pharmaceutical developers and specialized kit vendors.
Germany
EMA IVDR conformity assessments impose extended certification timelines on kit manufacturers seeking CE marking for clinical-grade assays. The country's national pharmaceutical regulator enforces stricter quality management audits under ISO 13485 baseline requirements. Heidelberg and Munich research institutes anchor European chromatin biology studies through Max Planck Society funding.
China
NMPA harmonization of import licensing for research-use-only kits reduces market entry friction for foreign reagent suppliers. The country's national pharmaceutical regulator streamlines clinical trial approvals for methylation-based cancer diagnostics. Shanghai and Beijing biotech parks concentrate CRISPR-dCas9 screening platforms through municipal innovation subsidies.
India
CDSCO streamlining of import licensing for research-use-only kits accelerates foreign supplier market entry. The Central Drugs Standard Control Organization harmonizes regulatory pathways for epigenetic diagnostic imports. Bangalore and Hyderabad biotech clusters expand contract research capacity for pharmaceutical epigenetic screening programs.
United Kingdom
UK Research and Innovation funding sustains academic chromatin immunoprecipitation studies at reduced per-experiment costs. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit diagnostic regulations with FDA evidentiary standards. Cambridge and Oxford life science parks concentrate single-cell ATAC-seq instrumentation deployment.
Cellular Epigenetics Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated reagent producers commanding pricing power in consumables while modular platform vendors compete on capital equipment financing. The vendor base organizes around three archetypes: diversified life science conglomerates with captive raw material networks, sequencing-platform specialists with locked-in consumables economics, and regional kit assemblers with localized production flexibility. Consolidation pressure concentrates among reagent suppliers seeking ISO 13485 certification for clinical laboratory access. Strategic moves center on backward integration into enzyme manufacturing and geographic expansion through distributor partnerships in Asia-Pacific markets.
Among diversified life science conglomerates, Thermo Fisher Scientific anchors the premium reagent tier through vertically integrated manufacturing networks, while Illumina occupies a position exemplifying platform-centric consumables lock-in. Merck KGaA represents the regional production archetype with European-localized kit assembly facilities. These three entities collectively illustrate how scale, technology control, and geographic proximity define competitive positioning in chromatin modification supply chains.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Merck KGaA |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Revvity |
| Promega Corporation |
| Zymo Research Corporation |
| Diagenode |
| Others |
Value Chain & Pricing Dynamics
Enzyme raw material indices cascade through cellular epigenetics supply chains into tiered pricing structures, where reagent manufacturers pass input volatility downstream through volume-discount contracts and ISO 13485 certification premiums. Academic medical centers absorb cost compression through NIH grant buffers, while pharmaceutical companies negotiate performance-based reagent agreements that shift price risk to suppliers.
Pricing Analysis
Lead-time premiums separate spot purchasers from contract-committed buyers, with 48-hour delivery guarantees commanding substantial markups over standard 14-day fulfillment cycles. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and technical support bundling, with ISO 13485-qualified clinical-grade reagents occupying the premium tier. Cost compression in economy-grade research-use-only kits is intensifying because Chinese manufacturers are scaling enzymatic detection chemistry production. Academic research institutions exhibit the highest price sensitivity, while pharmaceutical screening programs prioritize reliability over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework are reshaping sourcing patterns for CRISPR-dCas9 effector domains, compelling foreign suppliers to establish local enzyme fermentation partnerships. Manufacturing concentrates in the United States, Germany, and China, with reagent formulation drawing from specialized nucleotide chemistries, recombinant enzyme production, and microfluidic cartridge assembly. Single-source vulnerability pervades high-fidelity DNA polymerase supply, where patent-protected enzyme variants anchor kit performance claims. Distribution runs through authorized distributors in Asia-Pacific markets and direct procurement channels in Boston and San Diego biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellular epigenetics market sits in a technology-transition phase as CRISPR-dCas9 programmable editing platforms displace legacy hybridization-based methylation detection workflows. This substitution dynamic reconfigures vendor competitive positions and end-user procurement authority.
For Market Incumbents: Anticipate margin compression in fluorescent chemistry reagents as enzyme-based signal amplification systems capture sequencing workflow share. Defensive consolidation should prioritize backward integration into recombinant enzyme manufacturing to secure raw material access against supply disruption. Incumbents must also accelerate ISO 13485 certification investments to maintain clinical laboratory access as EMA IVDR conformity assessments harden evidentiary requirements. For New Entrants and Emerging Players: The premium-to-economy price gap in clinical-grade methylation panels creates white-space opportunity for mid-tier kit assemblers with regional production flexibility. Target India's CDSCO-streamlined import pathways and Bangalore contract research capacity expansion as the most penetrable geography-application intersection. A modular kit configuration strategy with rapid technical support response times addresses biotechnology firm procurement priorities. For Investors and Strategic Acquirers: Distressed-cycle entries favor European kit manufacturers facing EMA IVDR certification bottlenecks and extended notified body timelines. Long-term viability over the next decade hinges on CRISPR-dCas9 convergence with therapeutic applications beyond research tools. Watch FDA accelerated approval pathway expansion for methylation-based companion diagnostics as the inflection signal for clinical translation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Manufacturing | Captive supply of recombinant DNA polymerases insulates against single-source supplier concentration in fermentation capacity. |
| ISO 13485 Certification Investment | Clinical-grade quality management systems unlock high-complexity laboratory procurement channels under FDA and EMA frameworks. |
| CRISPR-dCas9 Platform Convergence | Programmable chromatin modifiers enable therapeutic pipelines without double-strand break liability, expanding addressable applications. |
| Liquid Biopsy Methylation Panel Development | Cell-free DNA epigenetic profiling addresses underpenetrated early cancer detection with substantial reimbursement upside potential. |
| Asia-Pacific Distributor Partnership Expansion | Localized kit assembly and technical support reduce import licensing friction in China and India regulatory environments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cellular epigenetics market analysis. Primary interviews with reagent procurement managers at pharmaceutical screening facilities, core facility directors at academic medical centers, regulatory affairs specialists navigating FDA companion diagnostic pathways, and kit manufacturing quality officers informed demand-side validation. Secondary sources encompassed NIH grant allocation databases, FDA in vitro diagnostic submission records, EMA IVDR notified body documentation, and ISO 13485 certification registries. Bottom-up reagent consumption modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Granularity-level modeling distinguished reagent, kit, instrument, and software product categories; CRISPR, bisulfite sequencing, ChIP-seq, and microarray technology platforms; and academic, pharmaceutical, CRO, and biotechnology end-user segments. CAGRs derived from fitted growth curves incorporating NIH funding trajectory, CRISPR platform adoption rates, and clinical diagnostic reimbursement expansion. Forecast inputs included pharmaceutical R&D pipeline counts for epigenetic targets, academic publication volume trends in chromatin biology, and regulatory approval velocity for methylation-based cancer screening assays.
Underlying measurement precision varies by segment; reagent and kit consumption carry tighter precision than instrument capital expenditure forecasting. Projections reflect assumptions regarding CRISPR therapeutic translation timelines, EMA IVDR implementation pacing, and payer coverage policy evolution for liquid biopsy applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market
Medical Biotechnology
RNA Interference (Rnai) Drug Delivery Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Mucormycosis Market
Medical Biotechnology
Humanized Liver Mice Model Market
Medical Biotechnology
Nerve Growth Factor (NGF) Market
Medical Biotechnology
Mycobacterium Tuberculosis Testing Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Apoptosis Market